
 Europe Variable Frequency Drive Market | 2026-2036
Europe Variable Frequency Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Variable Frequency Drive Market Insights
Software-defined energy optimization is decoupling hardware sales from recurring revenue streams across the Europe Variable Frequency Drive Market. ABB leverages its digital service platform to anchor long-term contracts in Nordic water utilities. Siemens sustains technology leadership through integrated drive-train architectures that span manufacturing and building automation segments. Danfoss differentiates via specialized HVAC drive portfolios that dominate refurbishment cycles in commercial real estate across France and the Netherlands.
A variable frequency drive modulates AC motor speed by varying input frequency and voltage, typically operating between 0.5 Hz and 400 Hz to match load demand and reduce energy consumption. Pulse Width Modulation technology leads installed capacity due to cost efficiency and broad compatibility with standard induction motors, while Direct Torque Control commands premium positioning in high-dynamic applications such as crane systems and extrusion lines. AC drives capture the dominant share of new installations across oil and gas and water treatment facilities, whereas servo drives concentrate margin pools in precision manufacturing where flux vector control enables positioning accuracy within 0.01 degrees.
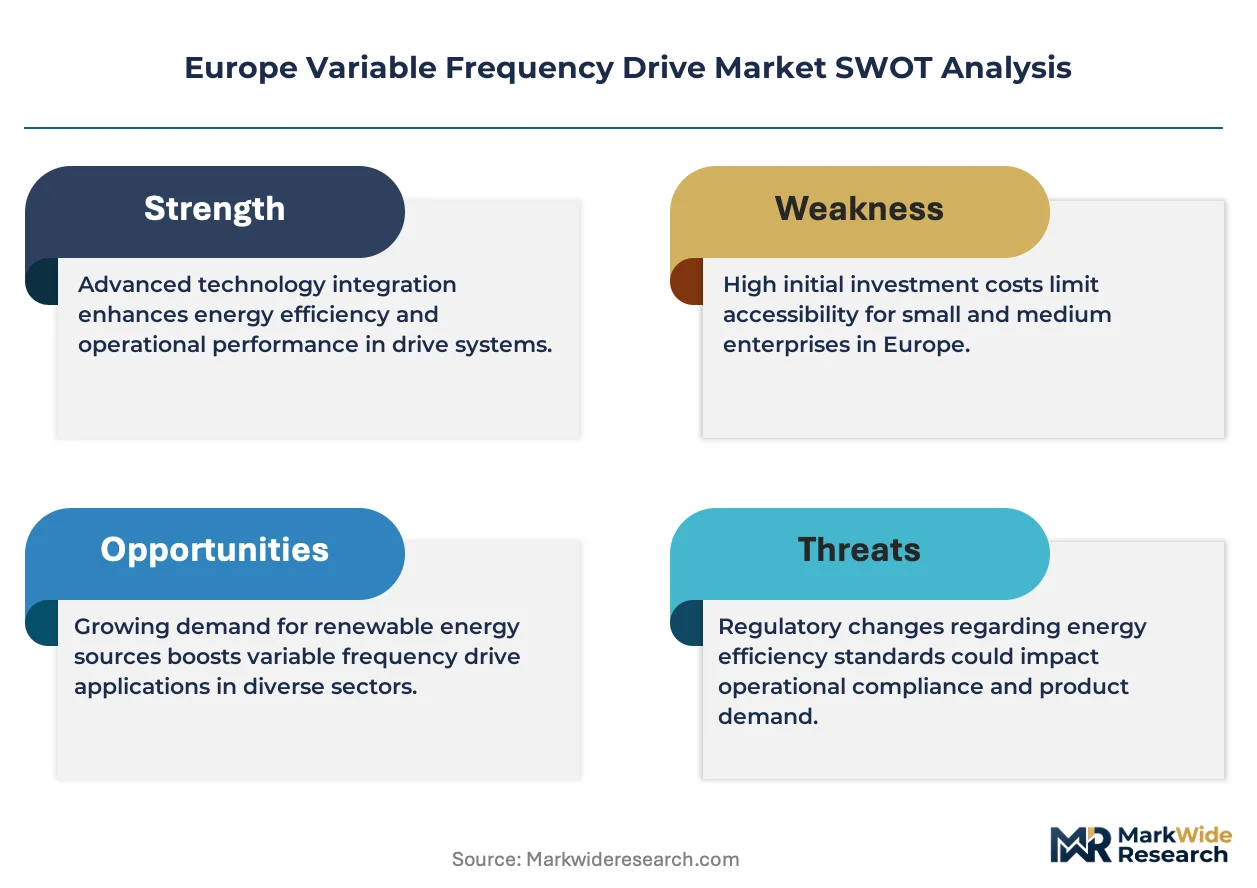
The EU Ecodesign Directive and ECHA chemical compliance frameworks mandate minimum efficiency tiers for motors and drives sold across member states, effectively phasing out non-compliant stock and redirecting procurement toward IE4-compatible variable frequency systems. CE marking requirements under the Machinery Directive enforce functional safety integration, compelling vendors to embed safe-torque-off circuitry as standard rather than optional configuration. Stakeholders must monitor how the F-Gas Regulation reshapes HVAC retrofit economics and whether national building codes in Germany and Italy accelerate mandatory VFD inclusion in public infrastructure tenders.
Market Dynamics
The EU Ecodesign Directive is compressing replacement cycles across Europe's motor-drive installed base, forcing industrial operators to retire IE2 systems ahead of depreciation schedules and redirect capital toward IE4-compatible variable frequency architectures.
Growth Catalysts
- Water utility modernization:German and Italian wastewater treatment operators are retrofitting aging pump stations with sensor-integrated VFD systems to meet tightening discharge standards under the EU Urban Wastewater Treatment Directive.
- F-Gas Regulation phase-down:HVAC contractors across France and the Netherlands face refrigerant cost spikes, accelerating building automation retrofits that pair low-GWP systems with precision motor control.
- Pulse Width Modulation cost curves:Semiconductor scaling has collapsed IGBT module pricing, enabling mid-tier manufacturers to embed vector control in standard induction motor drives previously limited to basic V/Hz operation.
Market Restraints
- Copper and rare earth magnet volatility:Permanent magnet motor supply chains remain exposed to Chinese export quotas on neodymium, compressing margins for high-efficiency drive-motor bundles.
- CE marking compliance costs:The Machinery Directive's functional safety requirements mandate third-party certification for STO circuitry, adding 12-18 week lead times for non-integrated safety modules.
- Direct-on-line motor persistence:Eastern European food processing and textile SMEs continue specifying DOL starters for sub-11kW applications, delaying VFD penetration in price-sensitive segments.
Strategic Opportunities
- Polish industrial corridor expansion:Automotive battery gigafactories near Wrocław and Poznań are specifying servo-grade VFD systems for electrode coating lines, creating premium positioning for flux vector architectures.
- EU Green Deal public procurement:Italian and Spanish infrastructure tenders now embed lifecycle cost scoring that rewards IE4 motor-drive packages with 15-year energy performance guarantees.
- Edge analytics convergence:Vendors bundling vibration monitoring and predictive maintenance algorithms with hardware are capturing multi-year service contracts that decouple revenue from unit shipments.
Industry Challenges
- Power electronics engineering scarcity:German and Austrian drive manufacturers report 18-month backlogs for field application engineers capable of tuning Direct Torque Control in extrusion and crane applications.
- Legacy SCADA integration friction:Brownfield manufacturing sites in Northern Italy operate 1990s-era Profibus networks, requiring protocol gateway investments that erode VFD retrofit project ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Variable Frequency Drive Market |
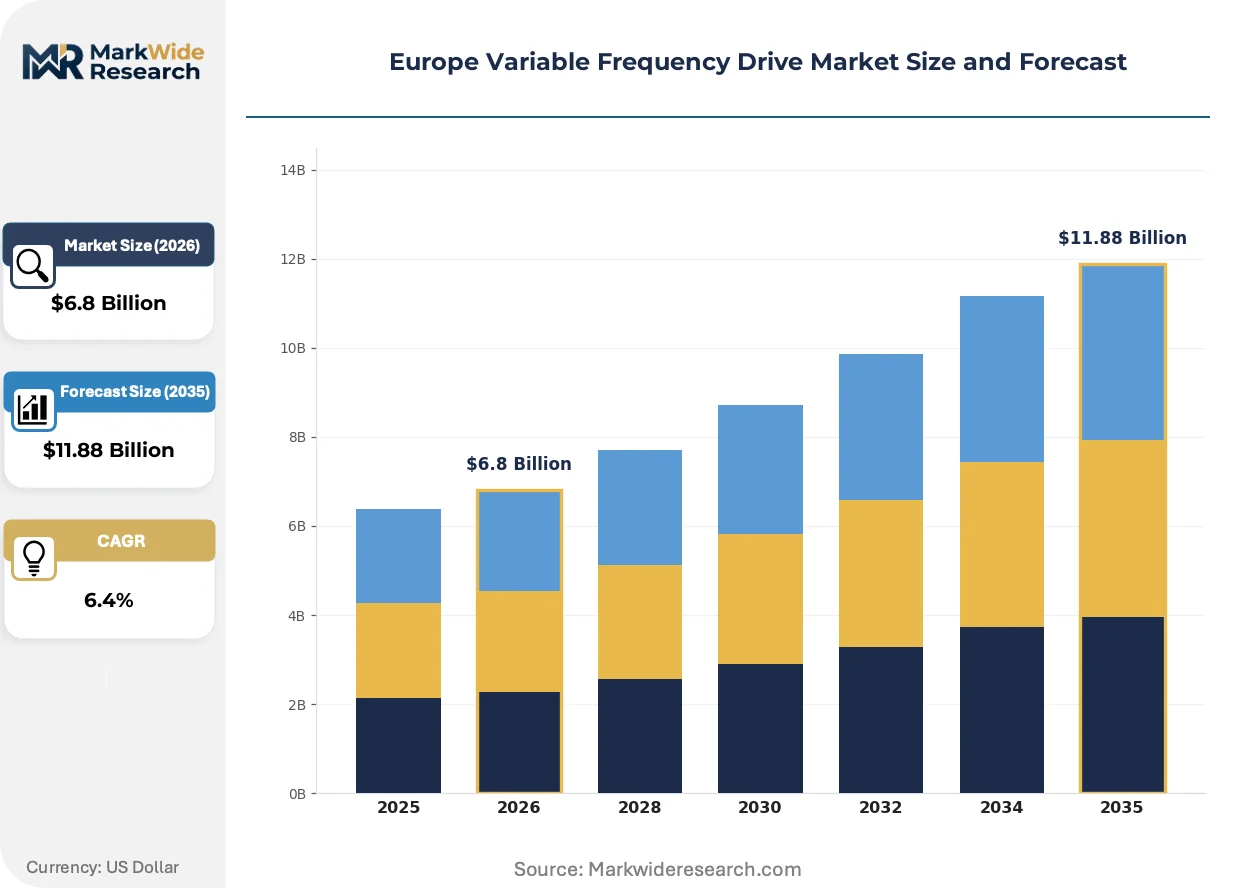
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Submersible Drives Technology: Pulse Width Modulation, Flux Vector Control, Direct Torque Control, Scalar Control End User: Oil & Gas, Water & Wastewater, Manufacturing, Building Automation Application: HVAC Systems, Conveyor Systems, Pump Control, Fan Control |
| Companies Covered | ABB, Schneider Electric, Siemens, Danfoss, Eaton, Bosch Rexroth, Emerson Electric, GE Vernova, Yaskawa Europe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Variable Frequency Drive Market Trends and Innovations
Digital service platforms are reconstituting how variable frequency drive value is captured and retained across European industrial automation, decoupling hardware margins from long-term customer relationships through subscription-based optimization tools.
Silicon carbide power semiconductors are absorbing switching losses in high-frequency VFD architectures that previously required liquid cooling. Oil and gas compressor stations in the North Sea are piloting SiC-based drives at 16 kHz carrier frequencies, enabling motor cable runs exceeding 500 meters without sinusoidal filters. This transition is absorbing the historical compromise between efficiency gains and electromagnetic compatibility costs.
The EU F-Gas Regulation is mandating refrigerant phase-downs that cascade into HVAC drive specification changes. Building automation contractors in France and Belgium must now document motor energy performance at part-load conditions to qualify for green lease certifications. Equipment manufacturers are responding by pre-loading drives with standardized efficiency curves that satisfy both Ecodesign and BREEAM compliance workflows.
Industrial buyers are consolidating vendor relationships around integrated drive-train suppliers capable of delivering motor-gearbox-drive packages with unified warranty terms. German automotive suppliers and Dutch logistics operators now specify single-source accountability for 10-year performance guarantees. This concentration is visible in tender documentation from Bavarian packaging machinery OEMs, where fragmented component sourcing no longer satisfies risk management protocols.
Europe Variable Frequency Drive Market Segmentation
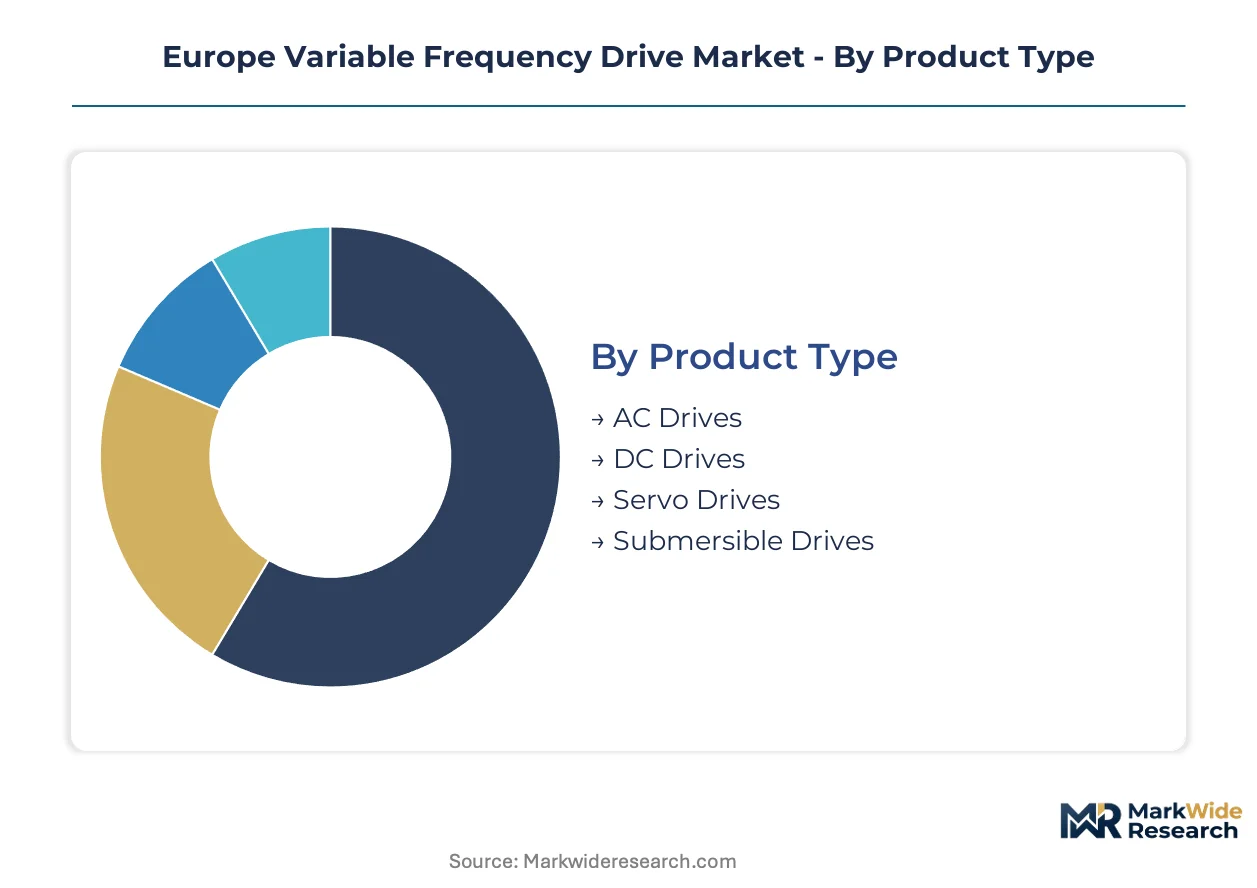
Variable frequency drive procurement across Europe fragments across four distinct segmentation axes, each carrying unique certification burdens and margin profiles. Understanding how product architecture, control methodology, end-use environment, and mechanical application intersect determines vendor positioning and pricing power.
Product Type:
AC Drives require CE marking under the Machinery Directive and IE4 compatibility certification under Ecodesign, while DC Drives face additional EMC compliance for legacy industrial networks. Servo Drives and Submersible Drives trigger specialized safety protocols—STO circuitry for precision motion, and IP68 ingress protection for submerged wastewater operations.
- AC Drives:Three-phase induction motor control dominates new installations across German automotive lines and Dutch logistics hubs. CE marking and Ecodesign IE4 tier compliance are mandatory for market access, compressing margins for non-integrated vendors.
- Servo Drives:Flux vector architectures deliver positioning accuracy within 0.01 degrees for Polish battery gigafactory electrode coating and Italian packaging machinery. Safe torque-off circuitry adds 12-18 week certification lead times per the Machinery Directive.
- DC Drives:Legacy mill applications in Northern England and Belgian steel corridors sustain residual demand, though Ecodesign phase-out schedules accelerate replacement toward AC alternatives.
- Submersible Drives:Hermetically sealed units withstand continuous immersion in German and Italian wastewater lift stations, where IP68 ratings and chemical resistance to hydrogen sulfide define specification thresholds.
AC Drives sits at the top of the volume ranking, with Servo Drives climbing the fastest.
Technology:
Control methodology determines semiconductor content, cooling requirements, and application bandwidth. Pulse Width Modulation leverages commodity IGBTs and scales across power ranges, while Direct Torque Control and Flux Vector Control absorb premium engineering talent and command price multiples in high-dynamic positioning.
- Pulse Width Modulation:Cost curves on IGBT modules have collapsed entry pricing, enabling vector-capable drives at standard V/Hz price points. French HVAC contractors and Spanish water utilities specify PWM for 90% of sub-75kW pump and fan applications.
- Direct Torque Control:Eliminates encoder feedback in crane and extrusion systems across Austrian steelworks and North Sea oil platforms. German and Austrian manufacturers report 18-month backlogs for field engineers capable of tuning these algorithms.
- Flux Vector Control:Closed-loop speed regulation serves precision manufacturing in Bavarian automotive supply chains and Dutch semiconductor fabrication. The technology commands 40-60% price premiums over open-loop alternatives.
- Scalar Control:Basic V/Hz operation persists in Eastern European food processing SMEs where DOL starter replacement cycles lag Western adoption curves by 5-7 years.
Pulse Width Modulation holds the installed base majority, though Direct Torque Control gains share fastest in premium positioning applications.
End User:
Vertical concentration shapes procurement sophistication—oil and gas majors demand unified 10-year warranties on integrated drive-trains, while water utilities optimize for lifecycle cost scoring under EU public procurement rules.
- Oil & Gas:North Sea compressor stations and Norwegian offshore platforms specify SiC-based drives at 16 kHz carrier frequencies for cable runs exceeding 500 meters. F-Gas Regulation compliance cascades into motor control specification changes.
- Water & Wastewater:German and Italian operators retrofit aging pump stations under the EU Urban Wastewater Treatment Directive. Sensor-integrated VFDs with predictive maintenance algorithms capture multi-year service contracts.
- Manufacturing:Automotive battery gigafactories near Wrocław and Poznań absorb servo-grade systems for electrode coating. Bavarian packaging machinery OEMs now mandate single-source accountability for drive-train packages.
- Building Automation:French and Dutch contractors face refrigerant cost spikes from F-Gas phase-downs, accelerating retrofits that pair low-GWP HVAC systems with precision motor control and BREEAM-compliant efficiency curves.
Manufacturing commands the highest average selling prices, with Water & Wastewater expanding most quickly under infrastructure modernization programs.
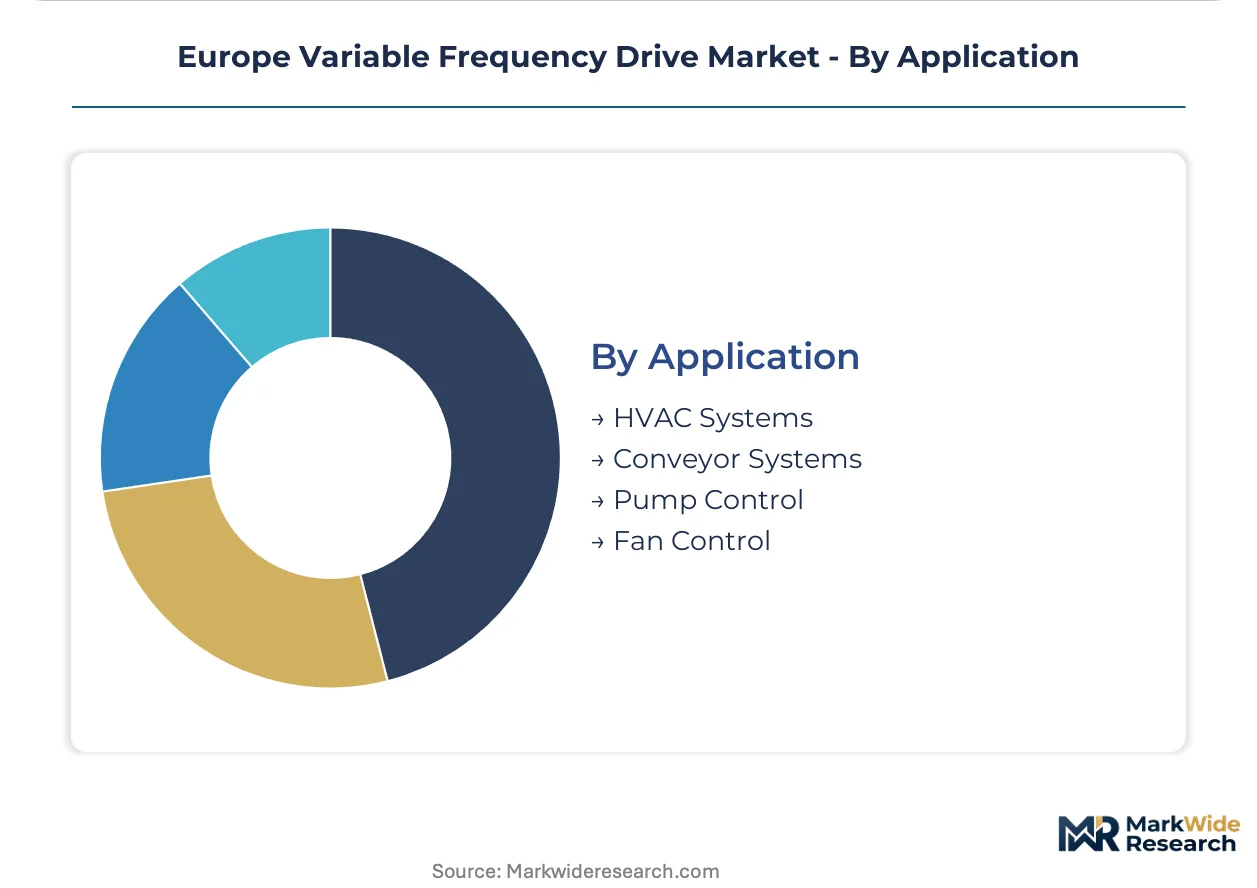
Application:
Mechanical load characteristics determine control bandwidth requirements—centrifugal pumps tolerate scalar control, while precision conveyors demand closed-loop vector performance.
- HVAC Systems:Part-load efficiency documentation is now mandatory for green lease certifications in Belgium and France. Pre-loaded standardized curves satisfy both Ecodesign and BREEAM workflows.
- Pump Control:German wastewater utilities specify sensor-integrated VFDs for discharge standard compliance. Energy optimization algorithms reduce consumption by 15-30% versus throttling valve control.
- Fan Control:Affinity laws reward variable speed operation in commercial real estate across the Netherlands and France. Refurbishment cycles concentrate margin pools for specialized HVAC drive portfolios.
- Conveyor Systems:Dutch logistics operators and German distribution centers demand coordinated multi-axis control with unified warranty terms. Fragmented component sourcing no longer satisfies risk protocols.
Pump Control leads by installed unit volume, with HVAC Systems showing the steepest expansion trajectory under F-Gas regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs premium AC drive volumes while Poland captures the fastest servo-grade expansion, reflecting divergent industrial maturities across the European VFD landscape.
Germany
Automotive battery gigafactories near Stuttgart and Munich specify flux vector servo systems for electrode coating precision. The EU Ecodesign Directive forces premature retirement of IE2 motor-drive combinations ahead of depreciation schedules. Bavarian packaging machinery OEMs now mandate single-source accountability for integrated drive-train packages with unified ten-year warranties.
France
Building automation contractors face F-Gas Regulation refrigerant cost spikes, accelerating HVAC retrofits that pair low-GWP systems with precision motor control. BREEAM compliance workflows now require part-load efficiency documentation for green lease certifications. Paris and Lyon commercial real estate markets concentrate refurbishment demand for specialized HVAC drive portfolios.
Italy
Wastewater treatment operators retrofit aging pump stations under the EU Urban Wastewater Treatment Directive discharge standards. Northern Italian brownfield manufacturing sites operate 1990s-era Profibus networks, creating protocol gateway friction that erodes VFD retrofit project returns. Emilia-Romagna packaging machinery clusters drive demand for closed-loop vector control systems.
Netherlands
Logistics operators and distribution centers demand coordinated multi-axis conveyor control with unified warranty terms. Rotterdam port infrastructure and Amsterdam Schiphol cargo facilities specify sensor-integrated drives with predictive maintenance algorithms. Dutch building automation markets absorb premium HVAC drive units under F-Gas regulatory pressure.
Poland
Automotive battery gigafactories near Wrocław and Poznań absorb servo-grade VFD systems for electrode coating lines. The country's industrial corridor expansion creates premium positioning opportunities for flux vector architectures. Manufacturing automation investments from German and Korean OEMs concentrate demand in Lower Silesian and Greater Poland voivodeships.
Europe Variable Frequency Drive Market Competitive Landscape
Top-tier vendors anchor integrated drive-train architectures, while mid-tier specialists compete on HVAC portfolio depth and regional service density. The vendor base stratifies across three functional tiers: diversified industrial conglomerates with unified warranty capabilities, power electronics specialists with semiconductor cost advantages, and application-focused HVAC contractors with refurbishment cycle expertise. Strategic moves concentrate on digital service platform bundling and silicon carbide power module integration for high-frequency architectures.
Within the diversified industrial tier, ABB and Siemens occupy positions exemplifying integrated drive-train supply, while Danfoss represents specialized HVAC portfolio concentration. These three anchors demonstrate how European VFD competition separates between unified warranty accountability and application-specific refurbishment expertise.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Siemens |
| Danfoss |
| Eaton |
| Bosch Rexroth |
| Emerson Electric |
| GE Vernova |
| Yaskawa Europe |
| Others |
Pricing and Supply Chain Analysis
The EU Ecodesign Directive gates qualified supply and premium-tier pricing access across the Europe Variable Frequency Drive Market, forcing vendors to absorb IE4 certification costs while IE2-compliant competitors face market exclusion. Procurement officers in German automotive corridors and Dutch logistics hubs now demand unified ten-year warranties that only integrated drive-train suppliers can underwrite, compressing margins for fragmented component vendors.
Pricing Analysis
Capacity additions in China's IGBT foundries are reshaping price floors for standard AC drives, enabling mid-tier European manufacturers to embed vector control at V/Hz price points. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling, with CE-marked IE4 systems commanding 25-40% premiums over basic configurations. Cost compression in the sub-11kW segment intensifies because Eastern European SMEs persist with direct-on-line starters. Water utilities exhibit lowest price sensitivity due to lifecycle cost scoring in EU public procurement, while food processing SMEs in Poland and Romania remain most cost-conscious.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium export quotas, which constrain permanent magnet motor supply chains for high-efficiency drive bundles. Manufacturing concentrates in Germany, China, and Japan, with semiconductor content drawing from Taiwanese foundries and Japanese substrate specialists. Raw material dependencies span copper windings, silicon carbide wafers, and rare earth magnets. Tariff exposure on Chinese magnet exports threatens margin stability for servo-grade architectures. Distribution runs through authorized industrial distributors and OEM direct channels, with aftermarket service contracts capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Variable Frequency Drive Market reads as a late-cycle quality story, with procurement gravity shifting toward IE4-compatible integrated drive-trains that satisfy Ecodesign mandates and unified warranty requirements.
For Market Incumbents: Anchor technology leadership through silicon carbide power module integration and predictive maintenance algorithm bundling. Threats from semiconductor-scaling mid-tier competitors intensify in standard AC drive segments. Prioritize backward integration into power electronics engineering talent pools to collapse 18-month field application engineer backlogs. Defensive consolidation around digital service platforms captures multi-year contracts that decouple revenue from unit shipments. For New Entrants and Emerging Players: Launch via HVAC refurbishment specialization targeting French and Dutch commercial real estate under F-Gas regulatory pressure. White-space targets include Polish battery gigafactory servo systems and Italian brownfield SCADA gateway integration. The most penetrable segment spans sub-75kW pump and fan applications where PWM cost curves have collapsed entry barriers. Go-to-market angle: pre-loaded efficiency curves that satisfy both Ecodesign and BREEAM compliance workflows without customization engineering. For Investors and Strategic Acquirers: Roll-up economics work for regional HVAC drive specialists because F-Gas phase-downs concentrate refurbishment demand in fragmented contractor networks. Long-term viability hinges on software-defined revenue streams and service contract annuities rather than hardware shipments. Acquisition target archetype: application-focused vendors with deep refurbishment cycle expertise in Benelux and French building automation. Signal to watch: national building code amendments in Germany and Italy that mandate VFD inclusion in public infrastructure tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Enables 16 kHz carrier frequencies for North Sea oil platform cable runs exceeding 500 meters. |
| Digital Service Platform Launch | ABB's predictive maintenance algorithms anchor ten-year contracts in Nordic water utilities. |
| Backward Integration into Magnet Supply | Reduces exposure to Chinese neodymium export quotas compressing servo-drive margins. |
| HVAC Refurbishment Specialization | Danfoss captures margin pools in French and Dutch commercial real estate under F-Gas pressure. |
| Unified Warranty Drive-Train Packaging | Bavarian packaging machinery OEMs now mandate single-source accountability for risk management. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic markets, with primary inputs from each region combined with secondary validation. Interviews incorporated plant engineers at German automotive suppliers, procurement leads at Dutch logistics operators, maintenance directors at Italian wastewater utilities, and aftermarket service heads at French HVAC contractors. Secondary sources included EU Ecodesign Directive implementation reports, ECHA chemical compliance frameworks, F-Gas Regulation impact assessments, and customs trade data on power semiconductor imports. Bottom-up unit shipment modeling triangulated against top-down energy efficiency investment forecasts.
Granularity-level modeling addressed product type, control technology, end-use vertical, and mechanical application dimensions across the projection horizon. Segment-level CAGRs derived from replacement cycle analysis under Ecodesign phase-out schedules and infrastructure modernization program commitments. Industry-specific forecast inputs incorporated battery gigafactory buildout timelines in Poland and F-Gas refrigerant phase-down curves affecting HVAC retrofit economics.
Several conditions sit outside the modeled scope, including potential delays in EU member state transposition of Ecodesign amendments and unanticipated rare earth magnet supply disruptions. Forecasts reflect assumptions about semiconductor cost curve trajectories and public procurement rule stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Embedded Power Generation Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Power Inverter Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Synchrophasors Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Grid Forming Inverters Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Synchronous Condenser Market
Power Systems
Shunt Reactor Market