
 Japan Indoor LED Lighting Market | 2026-2036
Japan Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Indoor LED Lighting Market Insights
Commercial office retrofits is realigning demand across Japan's indoor LED lighting sector. Endo Lighting Corporation leverages its deep channel presence in commercial fit-outs to sustain project flow. Panasonic Holdings Corporation anchors the residential segment through integrated home energy ecosystems. Nichia Corporation dominates upstream LED chip supply, giving it pricing leverage over downstream fixture assemblers.
Japan indoor LED lighting encompasses solid-state luminaires engineered with gallium nitride emitters, typically operating between 2700K and 6500K correlated color temperature, designed for enclosed interior environments requiring lumen maintenance above 70 percent over 50,000 hours. Panel lights lead volume in commercial retrofits where uniform glare reduction matters, while smart lighting commands margin premiums through sensor-integrated Building Energy Management System compatibility. Track lights occupy a specialized niche in hospitality and gallery applications where directional flexibility justifies higher fixture costs.
METI's Top Runner Program and JIS C 8152 standards jointly mandate efficiency thresholds that filter lower-performance imports from the Japanese market. PMDA guidelines intersect with healthcare facility lighting specifications, creating compliance layers for hospital and clinic segments. Stakeholders must monitor how METI's next efficiency tier revision interacts with local utility demand-response incentives to time product portfolio transitions.
Market Dynamics
METI's Top Runner Program creates a ratchet effect where efficiency thresholds escalate every three years, forcing fixture manufacturers to redesign thermal management systems and optical engines ahead of competitors in less regulated markets. This regulatory compression squeezes import-dependent assemblers while rewarding domestic players with captive chip supply.
Growth Catalysts
- Commercial building retrofits:Tokyo's 2020-2025 office stock renewal cycle replaces fluorescent troffers with edge-lit panels, concentrating procurement volumes in Greater Tokyo's five central wards.
- METI efficiency mandates:The Top Runner Program's 2024-2026 tier pushes luminous efficacy minimums to 150 lm/W for general illumination, disqualifying legacy imports from tender eligibility.
- Gallium nitride chip advances:Domestic foundries now produce mid-power flip-chip LEDs with 85 percent lumen maintenance at 105°C junction temperature, extending fixture warranty terms.
Market Restraints
- Upstream supply concentration:Nichia Corporation controls roughly 60 percent of domestic packaged LED supply, creating single-source vulnerability for mid-tier fixture assemblers.
- Phosphor cost volatility:Cerium-doped yttrium aluminum garnet phosphor prices fluctuate with rare earth export quotas from Chinese processors, compressing gross margins on warm-white SKUs.
- Technical substitution ceiling:OLED panel luminaires now achieve 120 lm/W efficacy in soft-task lighting, capturing niche share in high-end residential applications where color rendering index above 95 matters.
Strategic Opportunities
- Healthcare facility modernization:PMDA's 2023 circadian lighting guidelines for elderly care wards create specification pull for tunable-white systems in Hokkaido and Kyushu prefectures.
- Human-centric lighting convergence:Integration of melanopic flux sensors with Building Energy Management Systems opens premium positioning in Osaka's commercial redevelopment corridors.
- Utility demand-response programs:Tokyo Electric Power Company's interruptible load tariffs reward fixture-level dimming compliance, creating service revenue streams for system integrators.
Industry Challenges
- Thermal engineering talent scarcity:Fixture manufacturers struggle to recruit engineers capable of modeling junction-to-ambient thermal resistance for high-density COB arrays.
- JIS C 8152 certification timelines:Third-party testing for lumen maintenance claims now averages 14 months, delaying product launches past construction bidding windows.
- Legacy DALI protocol fragmentation:Mixed-vendor installations in 2015-2019 vintage smart buildings resist seamless upgrade to DALI-2 sensor integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Indoor LED Lighting Market |
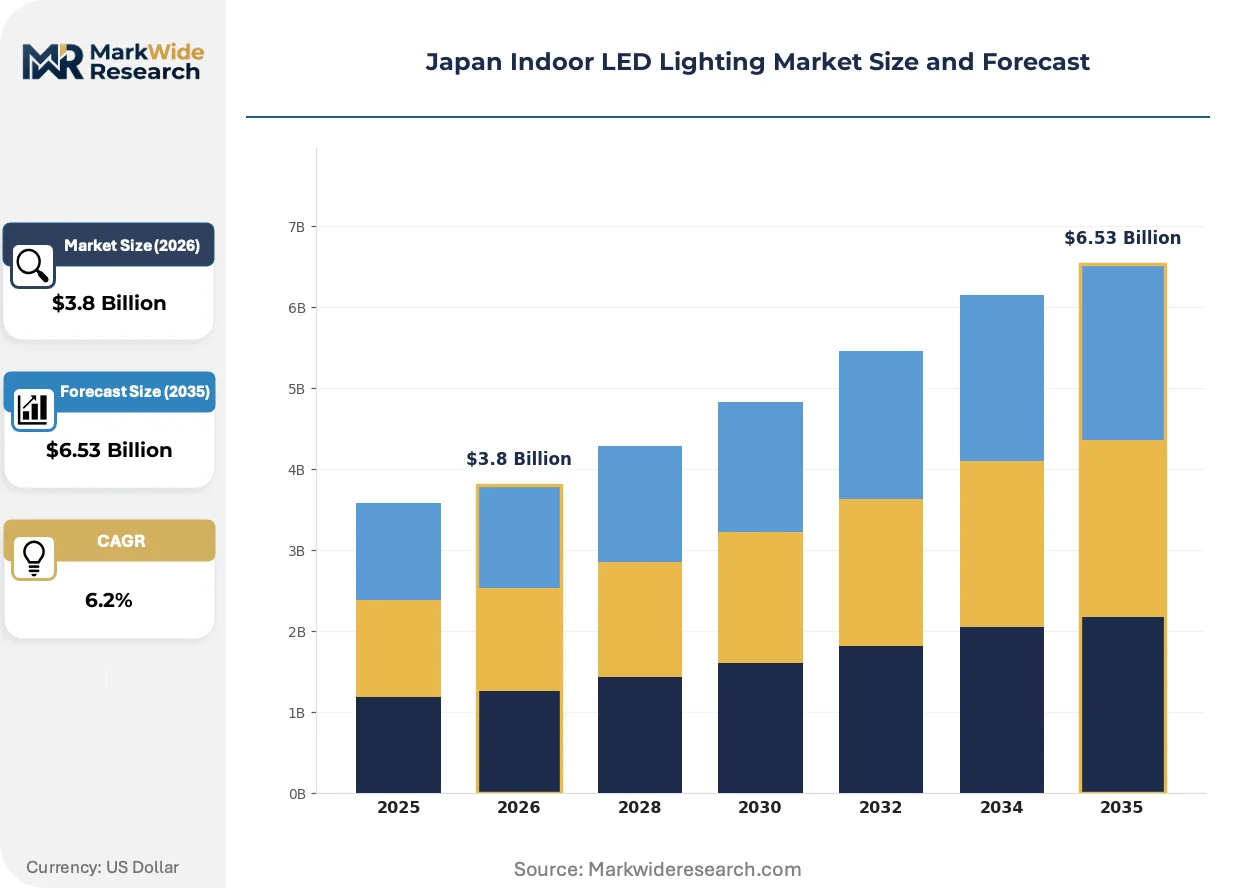
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recessed Lights, Track Lights, Panel Lights, Downlights Application: Residential, Commercial, Industrial, Hospitality Technology: Smart Lighting, Color Tuning, Dimmable, RGB End User: Homeowners, Businesses, Contractors, Designers |
| Companies Covered | Endo Lighting Corporation, Sharp Corporation, Panasonic Holdings Corporation, Mitsubishi Electric Corporation, Koizumi Lighting Technology Corp., Nichia Corporation, ams-OSRAM AG, Citizen Electronics Co., Ltd., Toshiba Lighting & Technology Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Indoor LED Lighting Market Trends and Innovations
Human-centric lighting specifications are displacing commodity lumen-per-watt procurement in Japan's premium commercial segments. Three convergent developments reshape competitive positioning: sensor-integrated spectral tuning, regulatory pressure on circadian efficacy claims, and compressed replacement cycles in high-occupancy buildings.
LiDAR occupancy sensors are integrating with tunable-white LED drivers to deliver real-time melanopic lux dosing in open-plan offices. Mitsui Fudosan's 2024-specification commercial towers in Toranomon require this capability as base build standard. The technology is integrating formerly separate lighting and building automation vendor ecosystems, forcing fixture manufacturers to certify interoperability with Siemens and Schneider Electric control platforms.
METI's 2024 amendment to the Act on Rationalizing Energy Use extends Top Runner coverage to standby power consumption in networked luminaires. Fixture assemblers must now document sub-0.5W idle draw to maintain compliance eligibility. Healthcare and education verticals face the tightest compliance windows, with prefectural procurement offices rejecting pre-amendment inventory from Q2 2025.
Building owners now specify outcome-based performance contracts where contractors guarantee maintained illuminance levels over 10-year terms. This displaces traditional unit-price procurement in Osaka and Nagoya municipal projects. Facility managers in Fukuoka's logistics hub corridor lead adoption, transferring lumen depreciation risk to vendors in exchange for higher upfront capital recovery.
Japan Indoor LED Lighting Market Segmentation
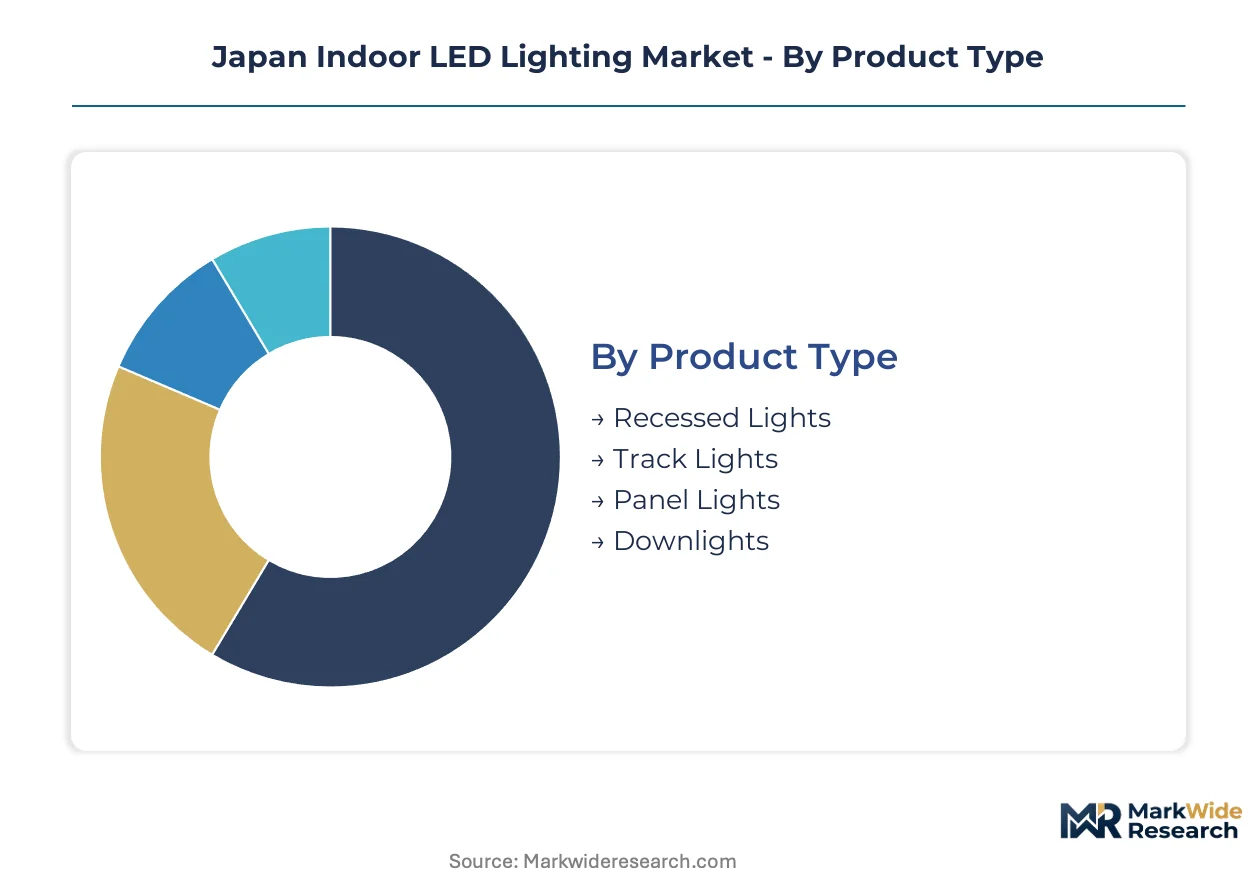
Segmentation in Japan's indoor LED lighting market reveals how METI's tiered efficiency mandates and JIS certification requirements create divergent compliance burdens across product categories. Procurement patterns in Greater Tokyo's commercial corridors concentrate demand in segments that satisfy both Top Runner standards and utility demand-response eligibility.
Product Type:
Certification intensity varies sharply across fixture formats, with edge-lit panels facing the most stringent lumen maintenance documentation under JIS C 8152 while track systems navigate shorter testing timelines for directional luminaires.
- Panel Lights:Edge-lit and back-lit flat-panel fixtures utilizing gallium nitride emitter arrays with prismatic diffusers to achieve uniform glare control below UGR 19. Procurement concentrates in Greater Tokyo's five central wards where Mitsui Fudosan's commercial tower specifications mandate melanopic flux compatibility as base build standard.
- Recessed Lights:COB and SMD downlight modules engineered for ceiling plenum integration with passive aluminum heat sinks managing junction temperatures below 85°C. Demand clusters in Osaka's municipal retrofit projects where outcome-based performance contracts now dominate specification language.
- Track Lights:Three-circuit and single-circuit directional systems with magnetic or mechanical locking adapters.
- Downlights:Compact ceiling-recessed modules for residential and light commercial applications.
Panel lights sit at the top of the volume ranking, with track lights climbing the fastest as hospitality and gallery segments prioritize directional flexibility over unit economics.
Application:
End-use verticals separate cleanly across cost tiers, with commercial retrofits absorbing premium smart-enabled systems while residential replacement cycles favor standardized efficacy tiers.
- Commercial:Open-plan offices, retail environments, and corporate headquarters requiring Building Energy Management System integration with DALI-2 protocol compliance. Tokyo Electric Power Company's interruptible load tariffs reward fixture-level dimming compliance, creating service revenue attachment opportunities for system integrators across the capital region.
- Residential:Single-family dwellings and multi-unit apartments where Panasonic Holdings Corporation anchors demand through integrated home energy ecosystems. Prefectural procurement offices in Hokkaido and Kyushu increasingly reject pre-amendment inventory lacking sub-0.5W standby power documentation.
- Industrial:Manufacturing floors, warehousing, and logistics facilities requiring high-bay and linear high-output configurations.
- Hospitality:Hotels, restaurants, and entertainment venues emphasizing aesthetic customization and scene-setting capabilities.
Commercial applications command the largest revenue share, with hospitality gaining share fastest as post-renovation property values in Fukuoka and Nagoya corridors justify premium fixture investments.
Technology:
Technology tiers stratify by margin structure, with sensor-integrated systems capturing service attach revenue while basic dimmable configurations compete on upfront capital recovery metrics.
- Smart Lighting:Networked luminaires with embedded occupancy sensors, daylight harvesting algorithms, and cloud-connected energy analytics. LiDAR occupancy sensors now integrate with tunable-white LED drivers to deliver real-time melanopic lux dosing, with Siemens and Schneider Electric control platform interoperability becoming mandatory for Toranomon district specifications.
- Color Tuning:Tunable-white and full-spectrum systems enabling circadian efficacy optimization.
- Dimmable:Phase-cut and 0-10V analog dimming modules for basic energy reduction.
- RGB:Multi-channel emitter configurations for ambient and decorative illumination.
Smart lighting leads on margin contribution, with color tuning expanding most quickly following PMDA's circadian lighting guidelines for elderly care ward modernization.
End User:
Buyer categories separate across procurement sophistication, with contractors managing specification risk in municipal projects while designers influence premium hospitality and gallery segments.
- Businesses:Corporate facility managers and property owners specifying outcome-based performance contracts with 10-year maintained illuminance guarantees. Fukuoka's logistics hub corridor leads this adoption, transferring lumen depreciation risk to vendors in exchange for higher upfront capital recovery.
- Contractors:Electrical and general construction firms bidding municipal and commercial retrofit projects where JIS C 8152 certification timelines averaging 14 months delay product launches past construction bidding windows.
- Homeowners:Individual consumers purchasing through retail and integrated homebuilder channels.
- Designers:Lighting design consultants and architects specifying for high-end residential and hospitality applications.
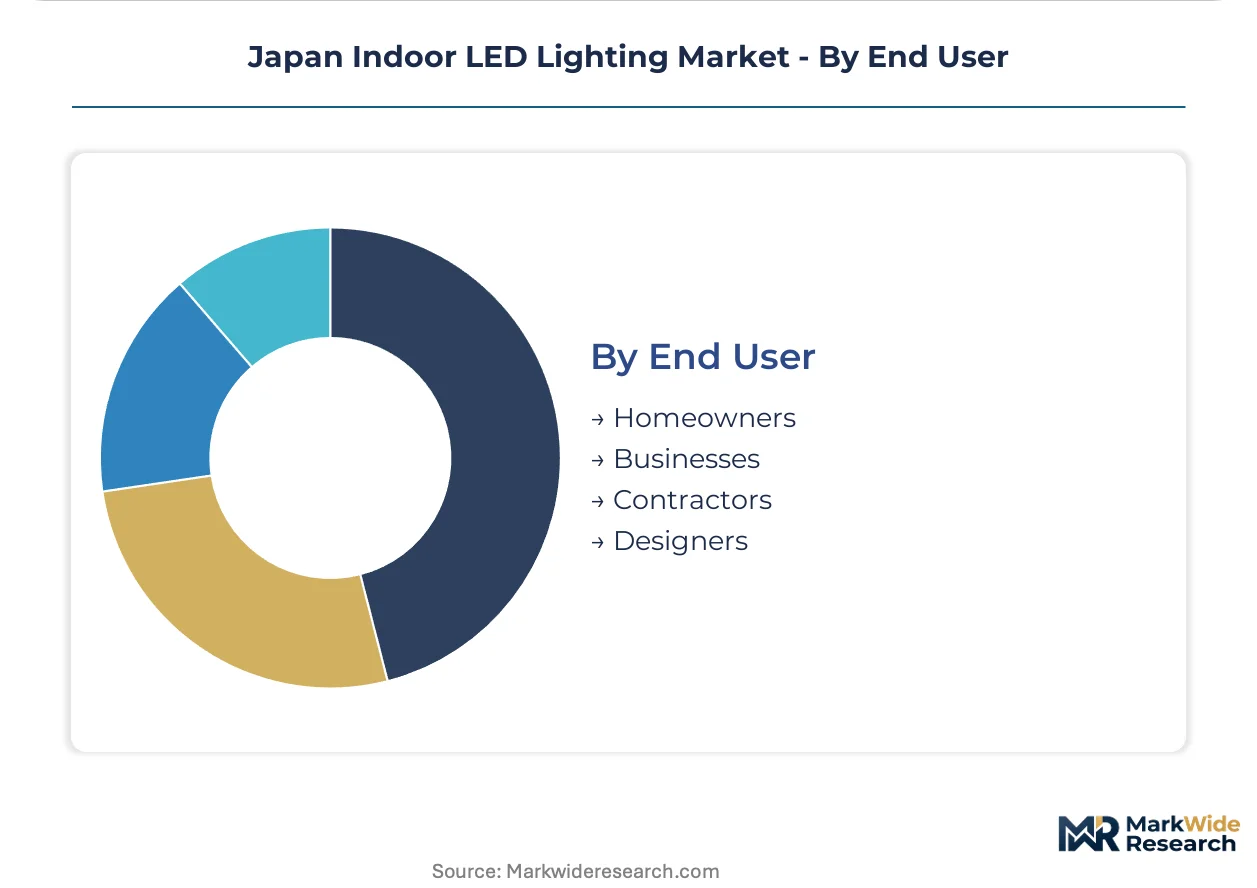
Businesses represent the largest addressable base, with contractors showing the steepest expansion trajectory as Tokyo's office stock renewal cycle concentrates procurement volumes through qualified installer networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Tokyo's five central wards concentrate Japan's indoor LED lighting procurement volumes through Mitsui Fudosan's commercial tower specifications and Tokyo Electric Power Company's demand-response incentive structures. METI's Top Runner Program efficiency mandates filter procurement toward domestic fixture assemblers with captive chip supply. Prefectural procurement offices in secondary metros increasingly reject pre-amendment inventory lacking sub-0.5W standby power documentation.
Kanto/Tokyo
Tokyo's 2020-2025 office stock renewal cycle replaces fluorescent troffers with edge-lit panels in Chiyoda, Chuo, Minato, Shinjuku, and Shibuya wards. METI's 2024-2026 Top Runner tier pushes luminous efficacy minimums to 150 lm/W for general illumination, disqualifying legacy imports from municipal tender eligibility. Toranomon district specifications now mandate LiDAR occupancy sensor integration with tunable-white LED drivers as base build standard.
Kansai/Osaka
Osaka's municipal retrofit projects favor outcome-based performance contracts where contractors guarantee maintained illuminance levels over 10-year terms. JIS C 8152 certification timelines averaging 14 months delay product launches past construction bidding windows for electrical contractors. The city's commercial redevelopment corridors drive specification pull for Building Energy Management System-compatible smart lighting with DALI-2 protocol compliance.
Chubu/Nagoya
Nagoya's automotive supplier ecosystem generates demand for high-bay and linear high-output configurations in manufacturing floors and logistics facilities. Local utility demand-response programs reward fixture-level dimming compliance, creating service revenue attachment opportunities for system integrators. Prefectural procurement offices prioritize domestic fixture assemblers with demonstrated thermal engineering capabilities for high-density COB arrays.
Kyushu
Kyushu's elderly care ward modernization follows PMDA's 2023 circadian lighting guidelines, creating specification pull for tunable-white systems in Fukuoka prefecture. The logistics hub corridor leads adoption of outcome-based performance contracts, transferring lumen depreciation risk to vendors in exchange for higher upfront capital recovery. Regional contractors face compressed compliance windows as prefectural offices reject pre-amendment inventory from Q2 2025.
Hokkaido
Hokkaido's healthcare facility segment absorbs premium smart-enabled systems for hospital and clinic modernization under intersecting PMDA and METI regulatory layers. Prefectural procurement offices enforce sub-0.5W standby power documentation requirements for networked luminaires ahead of national compliance deadlines. Sapporo's municipal projects concentrate demand through qualified installer networks bidding Tokyo-style specification packages.
Japan Indoor LED Lighting Market Competitive Landscape
Vertical integration into upstream LED chip production dominates the current landscape, with domestic foundries producing mid-power flip-chip LEDs extending fixture warranty terms. The vendor base stratifies across three tiers: integrated conglomerates with captive semiconductor supply, specialized lighting manufacturers with deep channel presence in commercial fit-outs, and import-dependent assemblers squeezed by regulatory compression. Strategic archetypes include chip-to-fixture integrators, project-flow specialists, and ecosystem platform builders. M&A activity concentrates on thermal engineering talent acquisition, while capacity expansion targets gallium nitride foundry output for next-generation efficacy tiers.
Among Japan-based integrated conglomerates, Panasonic Holdings Corporation anchors residential demand through home energy ecosystem integration, while Mitsubishi Electric Corporation occupies a position in industrial and infrastructure verticals. Endo Lighting Corporation exemplifies the project-flow specialist archetype with sustained commercial fit-out presence. Nichia Corporation represents the upstream supply concentration that creates single-source vulnerability for mid-tier fixture assemblers. These three anchors illustrate how regulatory ratchet effects reward domestic players with captive chip supply while filtering import-dependent competitors.
| Leading Market Players |
|---|
| Endo Lighting Corporation |
| Sharp Corporation |
| Panasonic Holdings Corporation |
| Mitsubishi Electric Corporation |
| Koizumi Lighting Technology Corp. |
| Nichia Corporation |
| ams-OSRAM AG |
| Citizen Electronics Co., Ltd. |
| Toshiba Lighting & Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
METI's 2024-2026 Top Runner tier mandating 150 lm/W efficacy minimums forces fixture assemblers to source premium gallium nitride emitters and advanced phosphor formulations, compressing margins on standardized SKUs while rewarding domestic players with captive chip supply.
Pricing Analysis
Phosphor cost pass-through from cerium-doped yttrium aluminum garnet price volatility runs directly into fixture pricing. Three-tier pricing structure across premium smart-enabled, standard dimmable, and economy basic efficacy levels separates procurement tiers. Cost compression in warm-white SKUs is intensifying because rare earth export quotas from Chinese processors constrain gross margins. Municipal contractors in Osaka and Fukuoka show highest price sensitivity, while Toranomon district commercial developers prioritize melanopic flux compatibility over unit economics.
Supply Chain Analysis
Engineering talent scarcity in thermal modeling for high-density COB arrays constrains domestic foundry expansion in Japan. Upstream LED chip production draws from Japan, Taiwan, and South Korea, with packaged emitter supply resting on gallium nitride wafer processing and phosphor deposition capabilities. Single-source vulnerability concentrates around Nichia Corporation's domestic packaged LED dominance. Distribution runs through qualified installer networks bidding municipal and commercial retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's indoor LED lighting market compounds steadily through regulatory ratchet effects that continuously reset efficiency baselines and force replacement cycles.
For Market Incumbents: Deepen backward integration into gallium nitride foundry capacity to secure chip supply against Nichia Corporation's pricing leverage. Fortify JIS C 8152 certification pipelines to compress 14-month testing timelines below construction bidding windows. OLED panel luminaires achieving 120 lm/W in soft-task lighting threaten niche residential share. For New Entrants and Emerging Players: Begin with Kyushu's elderly care ward modernization following PMDA circadian lighting guidelines, where tunable-white specification pull outpaces established vendor presence. Prefectural procurement offices rejecting pre-amendment inventory from Q2 2025 create compliance-driven replacement windows. Partner with regional electrical contractors holding qualified installer status in Fukuoka's logistics corridor. For Investors and Strategic Acquirers: Asymmetric upside sits with thermal engineering specialists capable of modeling junction-to-ambient resistance for next-generation COB arrays. Five-to-ten year viability hinges on METI efficiency tier transitions and utility demand-response program expansion. Watch for JIS C 8152 certification backlog clearance as inflection signal for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Expansion | Captive chip supply insulates margin pressure from Nichia Corporation's pricing power. |
| JIS C 8152 Certification Investment | Compressed testing timelines unlock municipal bidding windows in Osaka and Nagoya. |
| LiDAR Sensor Integration Partnership | Siemens and Schneider Electric platform interoperability satisfies Toranomon specifications. |
| Thermal Engineering Talent Acquisition | Modeling capability for high-density COB arrays differentiates next-generation efficacy tiers. |
| Utility Demand-Response Program Enrollment | Tokyo Electric Power Company interruptible load tariffs create service revenue attachment. |
Research Methodology
Multiple input streams — fixture manufacturer executives, electrical contractor procurement leads, prefectural procurement officers, and METI regulatory affairs specialists — were reconciled against customs trade data, JIS certification registries, utility demand-response program filings, and commercial real estate development databases. Bottom-up shipment estimates from gallium nitride emitter foundries and top-down construction spending projections were triangulated to validate volume assumptions.
Cross-referencing historical efficacy tier transitions with panel input from lighting design consultants and Building Energy Management System integrators anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application vertical, technology tier, and end-user procurement sophistication. CAGRs were derived from regression against METI mandate implementation schedules and commercial office stock renewal cycles.
Several conditions sit outside the modeled scope, including unannounced phosphor material substitutions, abrupt rare earth export policy shifts, and OLED efficacy breakthroughs exceeding 150 lm/W. Forecasts reflect documented assumptions regarding Top Runner tier adherence and certification timeline stability. Material deviation in METI efficiency tier revision timing or JIS testing capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Europe Outdoor LED Lighting Market
LED
Global Chip Scale Package (CSP) LED Market
LED
Thailand LED Market
LED
Japan LED Market
LED
7 Segment LED Displays Market
LED
United States Micro LED Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Germany Automotive LED Lighting Market
LED
Europe Indoor LED Lighting Market
LED
Europe LED Lighting Market
LED
Japan Outdoor LED Lighting Market
LED
Egypt LED Lighting Market
LED
South America Indoor LED Lighting Market
LED
Superluminescent Diodes Market
LED
GCC LED Lighting Market