
 LED Light Bar Market | 2026-2036
LED Light Bar Market Size, Share, and Industry Trends Forecast 2026-2036
LED Light Bar Market Outlook
The EU Green Deal is expanding the addressable market for LED light bars by accelerating halogen displacement across automotive and commercial vehicle lighting applications. Baja Designs leverages its specialized off-road engineering to capture premium positioning in the spot and flood beam categories. KC HiLiTES Inc. sustains brand loyalty through deep catalog breadth and dominant shelf presence in North American 4x4 retail channels. Federal Signal Corp. anchors its competitive stance through institutional relationships with emergency vehicle OEMs and municipal procurement frameworks.
An LED light bar is a linear solid-state lighting assembly comprising multiple diode packages mounted on a thermally conductive substrate, typically operating between 9 and 32 volts DC with luminous efficacy exceeding 100 lumens per watt, designed for high-intensity directional or area illumination in mobile and fixed outdoor applications. Work light bars command the largest installed base across commercial trucking and agricultural machinery due to their broad beam pattern and durability requirements. Spot light bars generate the fastest replacement-cycle velocity among off-road enthusiasts seeking maximum throw distance. LED technology dominates value contribution as laser and HID alternatives retreat to narrow performance-niche segments.
The U.S. Department of Transportation enforces FMVSS 108 compliance for automotive forward lighting, while the EPA Energy Star program and California Title 24 building standards shape efficiency benchmarks for auxiliary and commercial applications. The EU's RoHS and REACH frameworks restrict hazardous substances in semiconductor packaging and driver electronics, elevating compliance costs for non-European suppliers. Stakeholders must monitor evolving photobiological safety standards from IEC and regional variations in electromagnetic compatibility certification to preserve market access across jurisdictions.
Market Dynamics
The EU Green Deal's accelerated halogen phase-out mandates are compressing replacement cycles across commercial and consumer vehicle lighting, forcing rapid solid-state adoption while aftermarket channels scramble to capture displaced incandescent demand.
Growth Catalysts
- EU Green Deal mandates:Binding incandescent and halogen phase-out timelines under the European Commission's energy-efficiency framework are eliminating legacy technology options across member states, creating forced-upgrade demand pools.
- Off-road vehicle retrofitters:Consumer spending reallocation toward utility accessories in the United States is sustaining premium LED light bar attach rates across 4x4 and powersports segments.
- Fleet modernization programs:Municipal and commercial vehicle operators in North America are standardizing LED auxiliary lighting to reduce maintenance intervals and energy consumption.
Market Restraints
- Semiconductor substrate volatility:Aluminum nitride and silicon carbide thermal management substrates face concentrated supply from East Asian foundries, exposing cost structures to input price swings.
- REACH compliance friction:ECHA substance restrictions on driver electronics packaging elevate certification costs for non-European suppliers seeking EU market access.
- Photobiological safety certification:IEC 62471 testing requirements for high-intensity directional lighting extend product validation timelines and limit rapid iteration cycles.
Strategic Opportunities
- Agricultural machinery electrification:Autonomous tractor and harvester OEMs in the United States are specifying integrated LED work light bars for 24-hour operational visibility.
- Channel disintermediation:Direct-to-installer platforms are capturing share from traditional 4x4 retail distributors by offering configuration tools and same-day fulfillment.
- IRA clean vehicle incentives:U.S. commercial fleet tax credits for energy-efficient equipment are expanding addressable budgets for LED lighting retrofits.
Industry Challenges
- Thermal engineering talent scarcity:LED package-to-substrate bonding and junction temperature management expertise concentrates among semiconductor veterans, constraining product development velocity.
- Multi-jurisdiction certification backlog:Simultaneous FMVSS 108, ECE R10 EMC, and IEC photobiological approvals create sequential testing dependencies that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Light Bar Market |
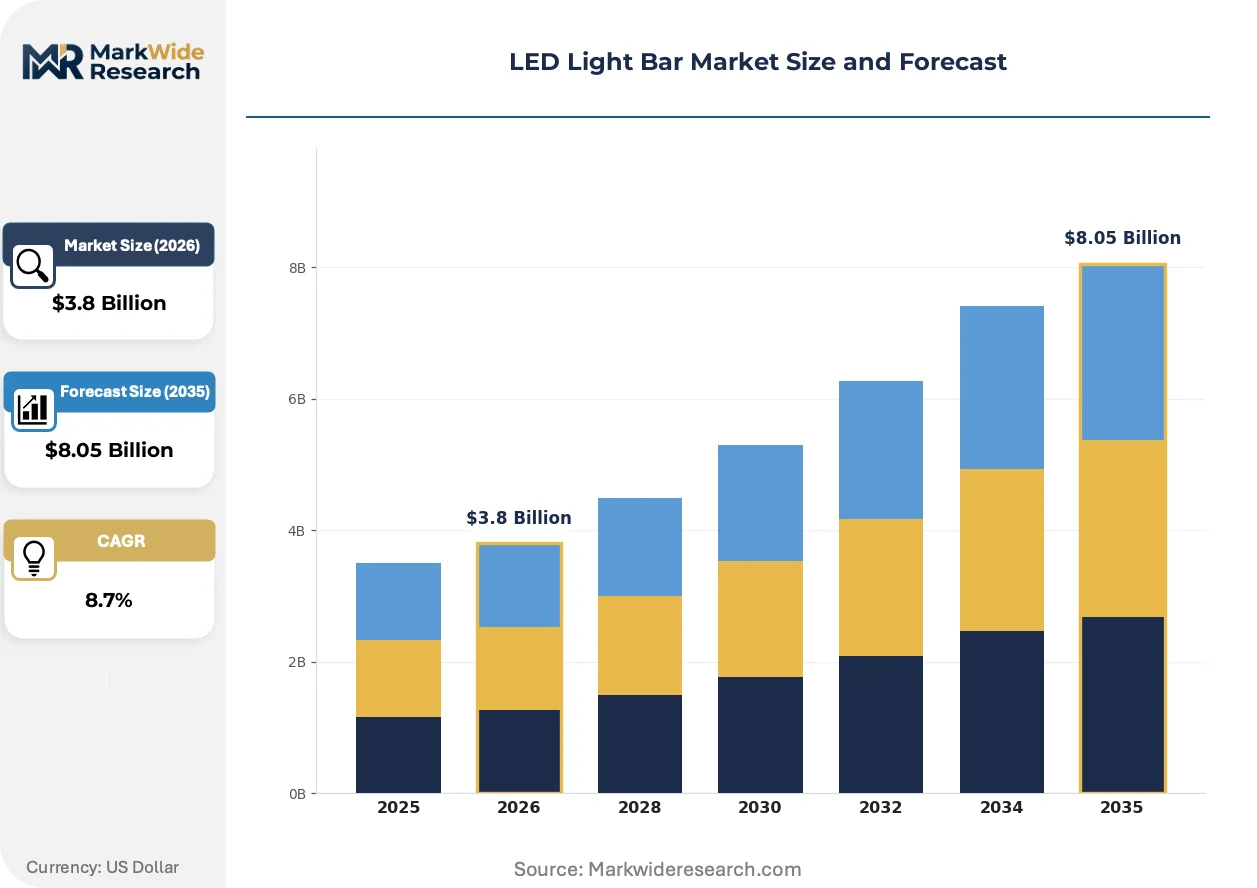
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flood Light Bars, Spot Light Bars, Work Light Bars, Accent Light Bars Technology: Halogen, HID, LED, Laser Application: Off-Road Vehicles, Emergency Vehicles, Commercial Trucks, Recreational Vehicles Installation Type: Permanent Mount, Temporary Mount, Magnetic Mount, Clamp Mount |
| Companies Covered | KC HiLiTES Inc., Baja Designs, Federal Signal Corp., Whelen Engineering Inc., Grote Industries LLC, Nilight Led Light, PIAA Corp., Putco Inc., Clarience Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Light Bar Market Strategic Shifts
Chip-on-board LED architectures and intelligent thermal feedback systems are compressing form factors while extending operational lifespans, fundamentally altering how auxiliary lighting integrates with vehicle electrical systems.
Chip-on-board LED packaging is rewriting thermal dissipation economics by eliminating wire bonds and reducing junction-to-case resistance. Off-road enthusiasts and commercial fleet managers are specifying these modules for their lumen density and shock resistance. The technology is compressing premium-mid-tier performance gaps and forcing incumbent suppliers to retool substrate bonding lines.
EPA Energy Star efficiency benchmarks and California Title 24 building standards are tightening luminous efficacy minimums for commercial auxiliary lighting. Manufacturers serving construction and agricultural segments must now document wattage-per-lumen performance across operating temperature ranges. The U.S. West Coast and Northeast corridor markets are responding with specification sheets that prioritize efficacy over raw output claims.
Installer-direct procurement patterns are fragmenting traditional aftermarket distribution hierarchies. Specialty vehicle upfitters and municipal fleet garages are bypassing regional distributors to source LED light bars through manufacturer portals with VIN-specific mounting compatibility. This behavioral shift is most pronounced in Texas and Florida, where large fleet concentrations negotiate volume pricing outside established retail channels.
LED Light Bar Market Segmentation
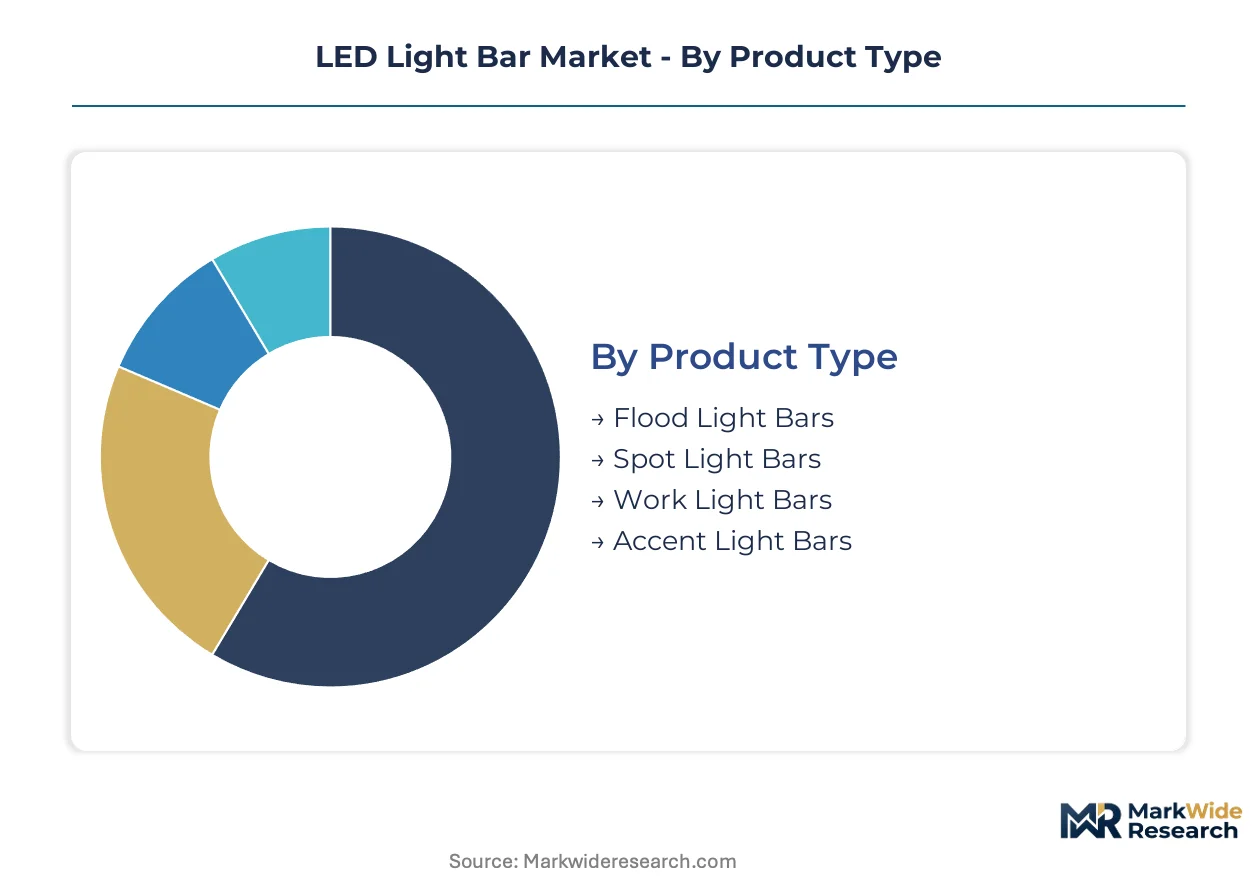
LED light bar segmentation reveals how thermal engineering capabilities and beam optics specialization concentrate margin capture across distinct product architectures. Procurement patterns diverge sharply between fleet operators prioritizing durability specifications and enthusiast segments demanding configurable illumination profiles.
Product Type:
Supply concentration in thermal substrate bonding favors manufacturers with captive semiconductor packaging lines, compressing margins for outsourced assemblers across all beam pattern categories.
- Work Light Bars:Broad beam patterns with 120-degree spread dominate agricultural machinery and commercial trucking installations. John Deere and Caterpillar specify these modules for 24-hour harvesting operations across the US Midwest, where dust ingress resistance determines warranty claim rates.
- Spot Light Bars:Tight 10-degree throw distances serve off-road enthusiasts seeking maximum beam penetration. The Mojave Desert racing circuit and Baja California competition trails sustain replacement-cycle velocity for premium diode packages.
- Flood Light Bars:Medium spread patterns illuminate construction site perimeters and mining equipment. Australian iron ore operations specify IP69K-rated housings for pressure-wash compatibility.
- Accent Light Bars:Low-output decorative strips attach to powersports chassis and marine vessels. California coastal marinas represent concentrated demand for corrosion-resistant anodized finishes.
Today's leader: Work Light Bars. Tomorrow's challenger: Spot Light Bars.
Technology:
Cost tier stratification separates legacy arc-discharge systems from solid-state architectures, with diode efficacy gains forcing rapid technology transitions across price-sensitive fleet segments.
- LED:Chip-on-board packaging eliminates wire bonds and reduces junction-to-case thermal resistance below 2°C per watt. EPA Energy Star benchmarks now mandate 100 lumens per watt minimums for California Title 24 compliance, locking in LED dominance across commercial auxiliary lighting.
- Halogen:Tungsten-halogen filaments persist in price-sensitive emerging markets where regulatory phase-out timelines lag EU Green Deal mandates. Brazilian agricultural equipment still specifies these for cost-constrained harvester retrofits.
- HID:High-intensity discharge arc lamps retreat to narrow performance niches requiring extreme lumen density in compact form factors. German emergency vehicle OEMs specify these for narrow grille integrations where thermal envelope constraints limit diode counts.
- Laser:Phosphor-converted laser diodes enable kilometer-class throw distances in military and search-rescue applications. US Border Patrol night vision operations represent the primary addressable volume for this architecture.
LED commands current volume leadership. Laser phosphor conversion climbs the fastest as defense procurement expands.
Application:
Volume concentration in aftermarket automotive channels creates divergent margin structures between standardized fleet specifications and customized enthusiast configurations.
- Commercial Trucks:Class 8 long-haul operators specify roof-mounted work bars for loading bay illumination. US Department of Transportation FMVSS 108 compliance mandates photometric pattern certification, elevating supplier qualification barriers.
- Off-Road Vehicles:Jeep Wrangler and Ford Bronco owners drive premium attach rates for multi-bar configurations. Texas and Florida 4x4 retail channels sustain the highest per-vehicle lighting expenditure in North America.
- Emergency Vehicles:Fire apparatus and ambulance OEMs integrate warning and scene lighting on common electrical architectures. Federal Signal and Whelen dominate municipal procurement frameworks through pre-approved vendor lists.
- Recreational Vehicles:Overland trailer and camper van builders specify low-draw accent lighting for boondocking operations. Colorado and Utah outdoor recreation corridors concentrate demand for solar-compatible 12-volt systems.
Commercial Trucks anchor present revenue. Off-Road Vehicles are expanding most quickly as consumer accessory spending reallocates.
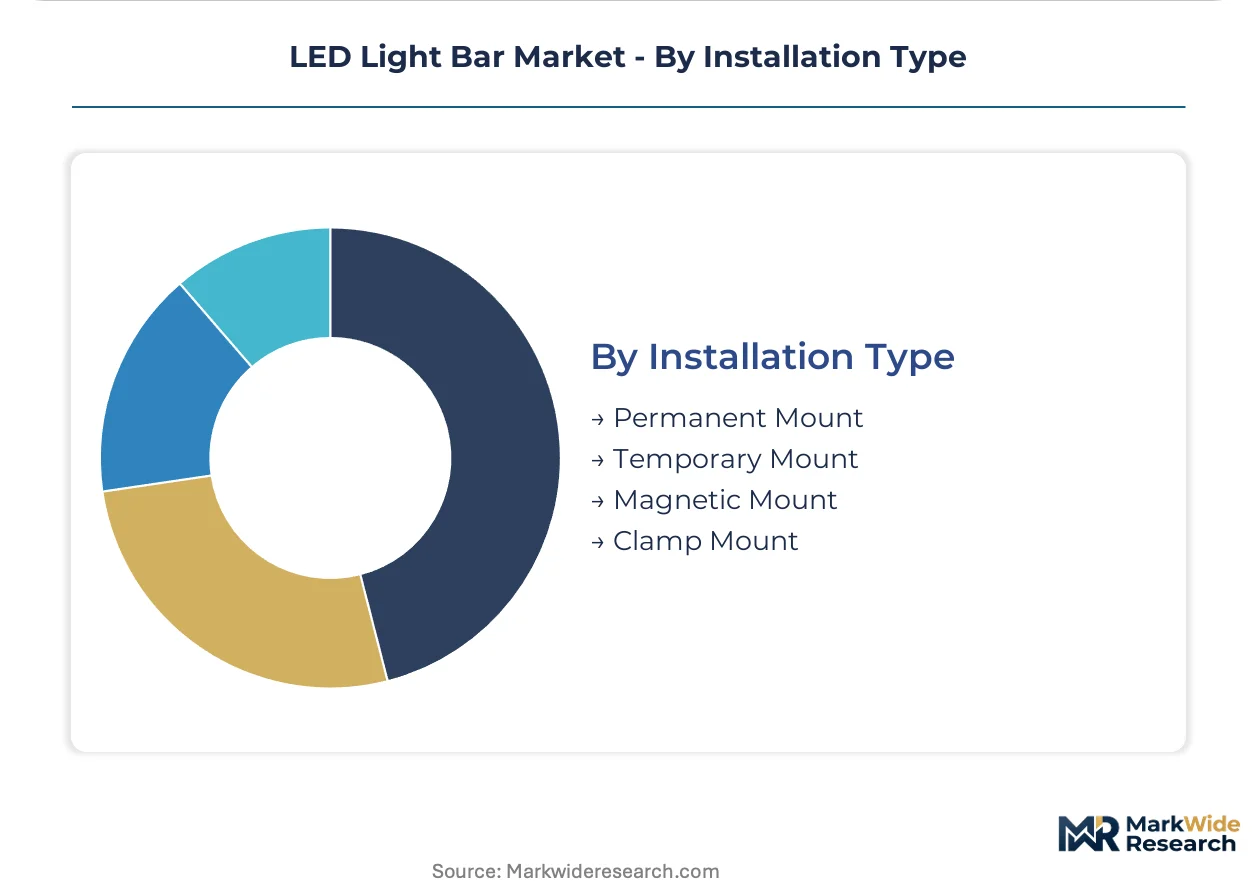
Installation Type:
Customer type stratification separates permanent fleet integrations from temporary enthusiast configurations, with mounting hardware durability becoming a discrete competitive battleground.
- Permanent Mount:Drilled bracket installations with sealed wiring penetrations dominate municipal fleet specifications. Chicago and Los Angeles public works departments mandate stainless steel hardware for salt corrosion resistance.
- Temporary Mount:Quick-disconnect harnesses serve rental equipment and seasonal agricultural machinery. Ukrainian grain harvester operators deploy these for rapid field-season deployment.
- Magnetic Mount:Rare-earth magnet bases enable rapid repositioning on steel body panels. Canadian oil field service trucks specify these for wellhead illumination in remote Alberta operations.
- Clamp Mount:Roll bar and bull bar attachments dominate powersports applications. Arizona and Nevada UTV rental fleets standardize these for damage-resistant deployment.
Permanent Mount holds current specification dominance. Magnetic Mount gains share fastest as mobile service applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Off-road vehicle engineering talent concentrates in California and Arizona desert racing corridors, anchoring aftermarket LED innovation cycles. Municipal fleet procurement expertise clusters in Midwest manufacturing belts and Texas energy corridors.
United States
Aftermarket 4x4 retail channels in Texas and Florida sustain the highest per-vehicle lighting expenditure globally. The U.S. Department of Transportation enforces FMVSS 108 photometric compliance for forward lighting, elevating supplier qualification barriers. California Title 24 building standards and EPA Energy Star benchmarks tighten luminous efficacy minimums for commercial auxiliary lighting across the West Coast.
Germany
Emergency vehicle OEMs and municipal procurement frameworks concentrate demand for high-reliability LED architectures. The EU Green Deal's binding halogen phase-out timelines under European Commission energy-efficiency frameworks eliminate legacy technology options. KBA vehicle type approval requirements and ECE R10 EMC certification anchor supplier compliance investments in Baden-Württemberg automotive clusters.
China
Thermal substrate bonding and semiconductor packaging capabilities concentrate in Yangtze River Delta foundry complexes. MIIT industrial standards and GB certification frameworks shape electromagnetic compatibility requirements for export-bound lighting assemblies. Shenzhen and Dongguan electronics manufacturing corridors host the dominant share of COB LED module assembly capacity serving aftermarket channels.
Australia
Mining equipment and agricultural machinery fleets drive IP69K-rated housing demand for pressure-wash compatibility. The country's national building code and state-level energy efficiency programs shape commercial auxiliary lighting specifications. Western Australia iron ore operations and Queensland agricultural belts represent concentrated demand for durable work light bar installations.
Brazil
Agricultural equipment retrofits in Mato Grosso and Goiás soybean belts sustain halogen persistence in price-constrained harvester segments. ANVISA and national automotive regulator frameworks lag EU Green Deal phase-out timelines, extending legacy technology windows. São Paulo state industrial corridors host the dominant share of South American LED lighting assembly and distribution infrastructure.
LED Light Bar Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the LED light bar landscape, with thermal engineering capabilities separating premium positioning from commodity assembly. The market structure fragments across three tiers: integrated semiconductor packagers with captive substrate bonding lines, specialized off-road lighting engineers with deep optic catalogs, and volume assemblers sourcing standardized diode modules. Strategic moves concentrate on M&A to secure thermal management IP and geographic expansion to capture fleet procurement frameworks.
Among North American specialists, KC HiLiTES Inc., Baja Designs, and Federal Signal Corp. exemplify distinct competitive archetypes. KC HiLiTES Inc. occupies a position within the catalog-breadth tier, anchoring shelf presence across 4x4 retail channels. Baja Designs represents the engineering-specialist vector, with concentrated expertise in desert racing and off-road beam pattern optimization. Federal Signal Corp. sits within the institutional-procurement tier, securing municipal and emergency vehicle OEM relationships through pre-approved vendor list positioning. These three structures illustrate how thermal engineering depth, distribution reach, and procurement access separate margin capture across the competitive landscape.
| Leading Market Players |
|---|
| KC HiLiTES Inc. |
| Baja Designs |
| Federal Signal Corp. |
| Whelen Engineering Inc. |
| Grote Industries LLC |
| Nilight Led Light |
| PIAA Corp. |
| Putco Inc. |
| Clarience Technologies |
| Others |
Value Chain & Pricing Dynamics
Thermal engineering talent scarcity in Yangtze River Delta foundry complexes compresses labor-cost differentials into premium-mid-economy pricing spreads, with diode packaging specialists commanding wage premiums that propagate through tiered product positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates chip-on-board LED architectures with sub-2°C thermal resistance from wire-bond legacy modules and halogen substitutes. Price differentiation rests on certification grade—FMVSS 108 compliance for automotive forward lighting versus uncertified auxiliary tiers—and volume scale for fleet procurement frameworks. Cost compression in the standard tier is intensifying because aluminum nitride substrate spot markets feed through to module assembly costs. Municipal fleet operators exhibit the least price sensitivity due to total-cost-of-ownership procurement mandates, while Brazilian agricultural retrofitters remain most exposed to economy-tier volatility.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 automotive OEMs and municipal procurement frameworks mandate multi-supplier qualification for thermal substrate bonding and COB LED module assembly. Geographic supply concentration centers on China for semiconductor packaging, Taiwan for driver electronics foundry capacity, and Germany for automotive-grade optic design. Raw material dependencies draw from aluminum nitride ceramic substrates, rare-earth phosphor compounds, and copper-clad thermal management laminates. Single-source vulnerability in East Asian foundry networks elevates disruption exposure for non-integrated assemblers. Distribution runs through manufacturer-direct portals for fleet installers and 4x4 retail distributors for enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chip-on-board packaging yield improvements and premium-tier attach rate expansion in off-road vehicle configurations frame this market as a margin-expansion story, with thermal engineering capabilities separating sustainable positioning from commodity compression.
For Market Incumbents: Anchor competitive position through captive substrate bonding lines that eliminate foundry dependency, while deepening FMVSS 108 and ECE R10 EMC certification portfolios to raise qualification barriers against emerging Asian assemblers. Threat from direct-to-installer platform disintermediation demands channel control investments in VIN-specific configuration tools. For New Entrants and Emerging Players: Direct-to-installer digital platforms offer the lowest friction route for white-space penetration, targeting Texas and Florida 4x4 fleet concentrations with same-day fulfillment capabilities. Agricultural machinery electrification in US Midwest autonomous tractor programs represents the most penetrable application segment, with specification-in timing at OEM design gates as the critical go-to-market angle. For Investors and Strategic Acquirers: Automotive Tier 1 lighting suppliers and powersports OEMs are the most active acquirer categories in this space, pursuing thermal management IP and beam optic design houses to secure auxiliary lighting integration mandates. Long-term viability hinges on semiconductor packaging capabilities migrating in-house. The signal to monitor is municipal procurement framework consolidation around pre-approved vendor lists, which would accelerate captive-supply M&A velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Substrates | Captive aluminum nitride bonding lines eliminate foundry margin extraction and supply disruption exposure. |
| FMVSS 108 Certification Investment | DOT photometric compliance unlocks Class 8 commercial truck roof-mount specifications and fleet procurement frameworks. |
| Direct-to-Installer Platform Launch | VIN-specific mounting compatibility tools bypass 4x4 retail distributor markups in Texas and Florida fleet corridors. |
| Chip-on-Board Packaging Retool | Eliminating wire bonds reduces junction-to-case resistance below 2°C per watt for premium-tier lumen density positioning. |
| Emergency Vehicle OEM Partnership | Pre-approved vendor list positioning with Federal Signal and Whelen anchors municipal procurement access. |
Study Parameters
Multiple input streams—primary interviews with thermal engineering directors, aftermarket distribution channel managers, and municipal fleet procurement officers, alongside secondary validation through SEC filings of lighting component suppliers, EPA Energy Star certification databases, and FMVSS 108 compliance registries—were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel inputs across beam pattern categories, installation types, and regional regulatory clusters to derive growth parameters over the projection horizon. Segmentation dimensions modeled include product architecture, thermal management technology tier, end-use application intensity, and procurement channel structure. CAGRs were synthesized from replacement-cycle velocity patterns in off-road enthusiast segments and fleet modernization program cadences.
Semiconductor substrate price volatility, EU Green Deal mandate acceleration timelines, and photobiological safety certification backlog durations are the dominant revision risks to modeled outputs. Deviation in aluminum nitride foundry capacity utilization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Downlight Market
LED
GCC LED Lighting Market
LED
China LED Lighting Market
LED
UAE LED Lights Market
LED
LED Lighting Solution Market
LED
LED Panel Market
LED
Europe LED Lighting Market
LED
Outdoor LED Display Market
LED
LED Street Light Drivers Market
LED
Asia Pacific LED Lighting Market
LED
Europe LED Packaging Market
LED
Middle East LED Lights Market
LED
LED Display Control Card Market
LED
Small Pitch LED Display Market
LED
Japan LED Lighting Market
LED
LED Panel Light Drivers Market