
 Americas Integrated Circuit (IC) Market | 2026-2036
Americas Integrated Circuit (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Integrated Circuit (IC) Market Insights
Modular system-in-package configurations is rebalancing procurement strategies for complex semiconductor assemblies. Intel Corporation leverages captive foundry investments to anchor domestic wafer supply. Texas Instruments sustains broad analog portfolios that dominate industrial and automotive sockets. NXP Semiconductors specializes in automotive-qualified mixed-signal architectures that secure Tier-1 supplier relationships.
Integrated circuits are miniaturized electronic assemblies of transistors, resistors, and capacitors fabricated on semiconductor substrates, typically silicon wafers with feature nodes measured in nanometers, designed to process, store, or transmit electrical signals for computational and control functions. Analog IC segments occupy mature margin pools in power management and signal conditioning where process expertise outweighs scale economics. Digital IC categories concentrate value in advanced logic and memory architectures driven by CMOS technology scaling. Automotive electronics applications represent the fastest-growing demand vector as electrification and advanced driver-assistance systems proliferate across OEM platforms.
The CHIPS and Science Act directs federal incentives through the Department of Commerce to reshape domestic fabrication capacity, while EPA emissions standards and NHTSA safety regulations mandate chip-intensive vehicle architectures. BIS export controls on advanced manufacturing equipment constrain technology transfer pathways and redirect supply chain investments toward sovereign capabilities. Stakeholders must monitor regulatory calibration between industrial policy objectives and equipment access restrictions to anticipate capacity allocation decisions.
Market Dynamics
The CHIPS and Science Act redirects capital toward domestic fabrication clusters while EPA tailpipe rules and NHTSA safety mandates force chip density into vehicle platforms. This dual policy pressure compresses design cycles and concentrates procurement around qualified suppliers.
Growth Catalysts
- Automotive electrification mandates:NHTSA advanced driver-assistance system requirements and EPA emissions standards embed silicon content into powertrain and chassis controllers. OEMs in Michigan and Ontario are qualifying multi-die packages for battery management systems.
- CHIPS Act fabrication incentives:Department of Commerce subsidies for Arizona and Texas fab construction accelerate 300mm wafer capacity. Equipment installation timelines compress as Treasury tax credits reduce project hurdle rates.
- Advanced packaging migration:Chiplet architectures and 2.5D interposers displace monolithic dies in high-performance computing. Foundries in the southwestern United States are adding fan-out panel-level capacity to capture assembly value.
Market Restraints
- Equipment access restrictions:BIS export controls on extreme ultraviolet lithography systems constrain node advancement for logic fabs. Domestic manufacturers face yield gaps at sub-7nm geometries without access to Dutch and Japanese tooling.
- Substrate material concentration:Ajinomoto build-up film and bismaleimide-triazine resin supply concentrates in East Asian chemical processors. Americas-based substrate fabricators face 18-24 month qualification cycles for automotive-grade laminates.
- Neon and noble gas dependency:Ukraine and Russian-sourced neon purification for excimer lasers creates input volatility. Semiconductor-grade noble gas recycling infrastructure in the Americas remains underdeveloped relative to East Asian recovery rates.
Strategic Opportunities
- Mexico border assembly expansion:Nuevo León and Chihuahua industrial parks attract back-end test and packaging investment. Nearshoring from Asian OSATs accelerates as USMCA rules of origin clarify semiconductor content requirements.
- GaN-on-silicon power integration:Gallium nitride epitaxy on standard silicon substrates merges RF and power management functions. Electric vehicle onboard chargers and solar inverters in California and Texas are adopting these merged process flows.
- Defense Trusted Foundry accreditation:Department of Defense DMEA certification creates a captive demand pool for radiation-hardened and secure microelectronics. Arizona and New York fabs with accredited status command premium pricing for aerospace and satellite applications.
Industry Challenges
- Process engineer scarcity:Plasma etch and chemical mechanical planarization expertise concentrates among retiring veterans from Intel and GlobalFoundries. Community college partnerships in Arizona and Oregon struggle to replace experiential knowledge with two-year credentials.
- Automotive qualification timelines:AEC-Q100 stress testing and PPAP documentation extend design-in cycles to 36-48 months. Fabless designers face working capital strain while waiting for Tier-1 supplier gate approvals.
- Legacy node equipment obsolescence:200mm tool refurbishment for analog and power ICs depends on secondary market brokers. Depreciation schedules mismatch with 20-year automotive production commitments for mature geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Integrated Circuit (IC) Market |
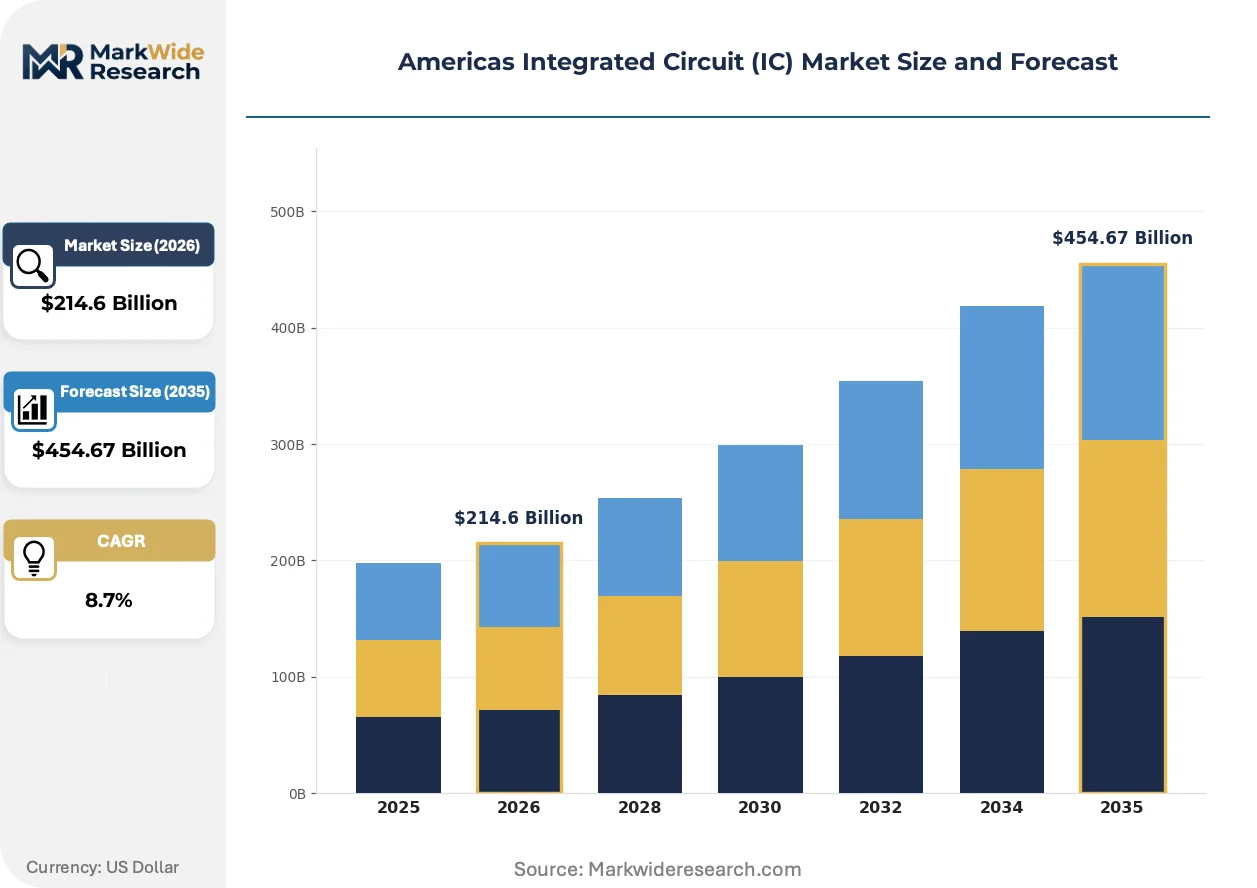
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $454.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog IC, Digital IC, Mixed-Signal IC, Power IC Technology: CMOS, BiCMOS, Bipolar, GaN Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications End User: OEMs, Tier-1 Suppliers, Contract Manufacturers, Aftermarket Providers |
| Companies Covered | Intel Corporation, Texas Instruments, Analog Devices, Infineon Technologies AG, STMicroelectronics, NXP Semiconductors, On Semiconductor Corporation, Microchip Technology, Renesas Electronics Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Integrated Circuit (IC) Market Trends and Innovations
Silicon carbide substrates and chiplets are compressing traditional power semiconductor architectures while federal industrial policy accelerates capital deployment into domestic manufacturing nodes.
Silicon carbide MOSFETs and Schottky diodes handle higher breakdown voltages and switching frequencies than silicon IGBTs. Automotive traction inverters in Detroit and Stuttgart are adopting 6-inch and 8-inch SiC wafers for 800-volt battery platforms. This wide-bandgap material is expanding into onboard charging and DC-DC conversion, displacing silicon superjunction devices in 200-kW+ applications.
The CHIPS and Science Act directs NIST standards development and DOC subsidy allocation toward onshore logic and memory capacity. Equipment depreciation allowances and domestic content bonuses reshape foundry investment math. Arizona and Texas project sites absorb the bulk of initial awards, with New York and Ohio trailing in fab construction permits.
Automotive OEMs are consolidating semiconductor procurement around direct foundry relationships and away from tiered distribution. Tier-1 suppliers in Michigan and Ontario face margin compression as Ford and GM negotiate wafer-start commitments directly with Texas Instruments and NXP. This disintermediation concentrates in electrified powertrain controllers where chip shortages disrupted 2021-2022 production schedules.
Americas Integrated Circuit (IC) Market Segmentation
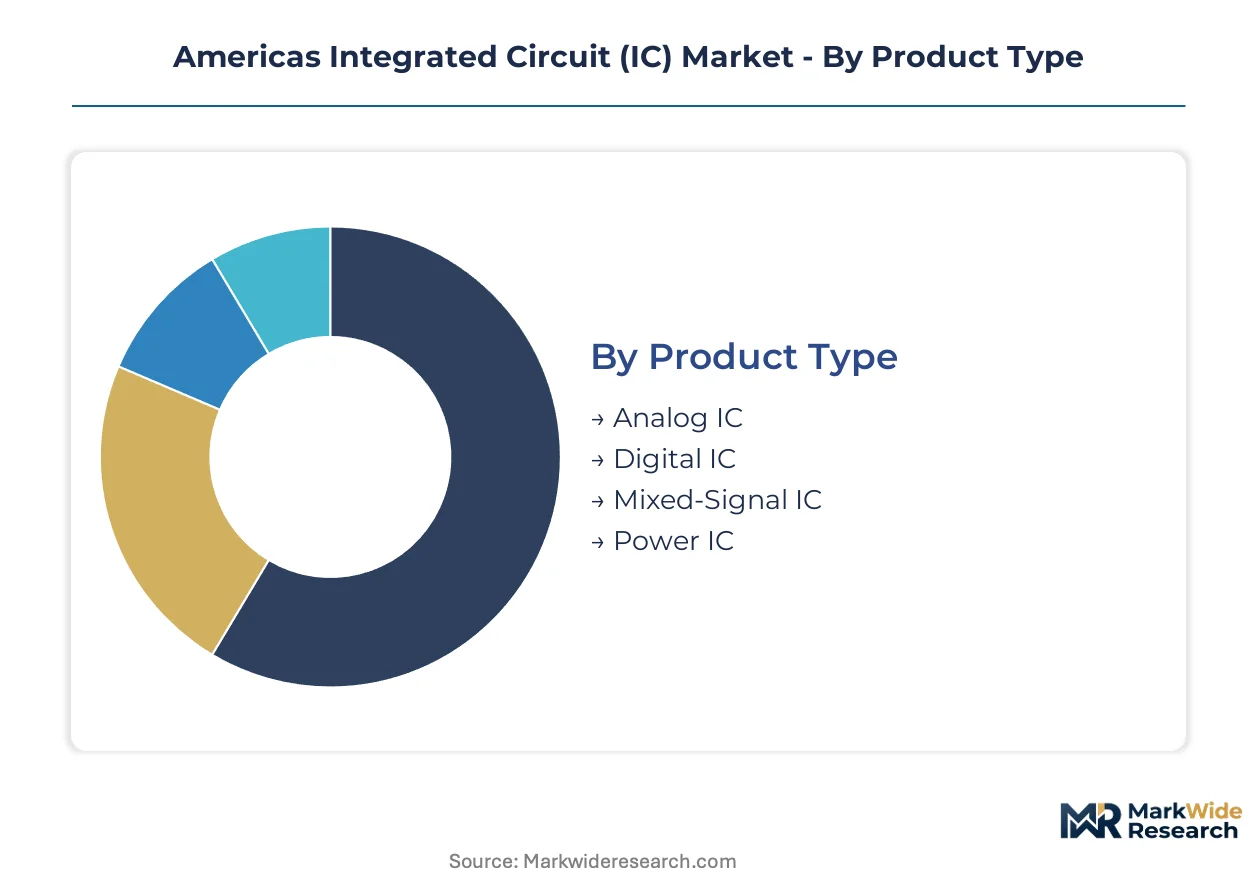
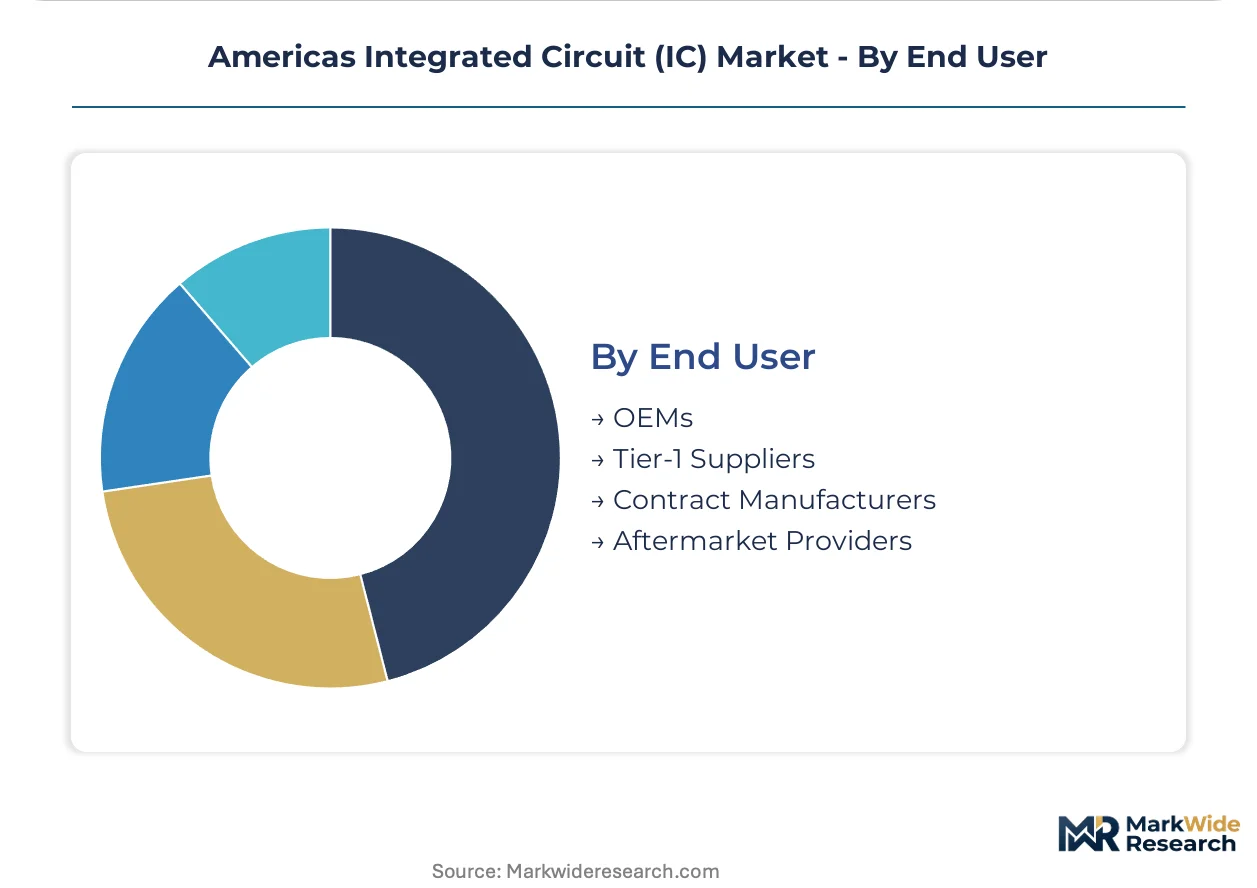
Integrated circuit segmentation in the Americas reflects divergent technology lifecycles and procurement patterns across automotive, industrial, and consumer verticals. Upgrade cycles vary from 3-year smartphone refreshes to 15-year automotive platform commitments, forcing suppliers to maintain multi-generational process nodes simultaneously.
Product Type:
Replacement intensity differs sharply across IC categories, with power management devices refreshing fastest due to efficiency mandates while analog architectures persist for decades in industrial sockets.
- Analog IC:Continuous-time signal processing circuits operate on mature 180nm to 350nm geometries. Industrial sensor interfaces in Texas and Ohio chemical plants demand 20-year supply guarantees, locking foundries into legacy node maintenance.
- Digital IC:Logic and memory devices scale through CMOS advancement, with Arizona fabs pushing toward sub-5nm geometries. Cloud infrastructure buildouts in Northern Virginia and Oregon concentrate demand for high-performance compute dies.
- Mixed-Signal IC:Data converters and RF transceivers merge precision analog with digital signal processing. Automotive radar modules in Michigan qualify these devices through AEC-Q100 Grade 1 stress protocols.
- Power IC:Voltage regulators and motor drivers handle load switching across electrification platforms. Texas and California EV charging infrastructure deployments are absorbing silicon carbide-enhanced power modules.
Digital IC sits at the top of the volume ranking, with Power IC climbing the fastest as electrification mandates proliferate across federal and state regulatory frameworks.
Technology:
Process selection hinges on cost-per-function thresholds, with mature nodes dominating high-volume analog production while advanced lithography captures premium logic sockets.
- CMOS:Complementary metal-oxide-semiconductor dominates digital logic and memory fabrication through aggressive scaling. Intel and Samsung fabs in Arizona and Texas compete on transistor density metrics for hyperscaler processor orders.
- BiCMOS:Bipolar-CMOS integration merges high-speed analog with dense digital on single substrates. Satellite communication payloads in Colorado and Florida leverage these processes for RF front-end integration.
- Bipolar:Junction transistor architectures persist in precision voltage references and high-current switching. Legacy military programs in California and Arizona sustain demand through DMEA-certified foundry networks.
- GaN:Gallium nitride epitaxy enables high-frequency power conversion beyond silicon physical limits. Onboard chargers for Detroit OEM platforms are migrating to GaN-on-silicon architectures for 800-volt battery systems.
CMOS commands the largest installed capacity base, though GaN is expanding most quickly as wide-bandgap materials penetrate automotive and renewable energy conversion applications.
Application:
End-use concentration shapes foundry allocation, with automotive qualification timelines stretching procurement cycles while consumer electronics demands rapid volume ramps.
- Consumer Electronics:Smartphones, tablets, and wearables drive annual refresh cycles with compressed design windows. California and Washington state design centers source advanced node wafers for mobile application processors.
- Automotive Electronics:Powertrain controllers, ADAS modules, and infotainment systems embed silicon across vehicle architectures. Michigan and Ontario OEMs are qualifying multi-die packages for battery management and domain controller integration.
- Industrial Automation:Programmable logic controllers and motor drives operate in extended temperature ranges with decade-long availability requirements. Ohio and Pennsylvania manufacturing corridors sustain demand for ruggedized analog and power devices.
- Telecommunications:Baseband processors and RF transceivers enable 5G infrastructure deployment. Texas and Illinois network equipment manufacturers are absorbing mmWave-capable beamforming ICs for urban densification projects.
Consumer Electronics maintains volume leadership, while Automotive Electronics is gaining share fastest as EPA tailpipe regulations and NHTSA safety mandates force chip density into vehicle platforms.
End User:
Procurement authority is shifting upstream, with OEMs disintermediating traditional distribution channels to secure direct foundry commitments during supply-constrained periods.
- OEMs:Original equipment manufacturers in automotive and electronics verticals negotiate wafer-start agreements directly with foundries. Ford and GM procurement teams in Michigan now contract Texas Instruments and NXP for powertrain controller supply.
- Tier-1 Suppliers:Delphi and Bosch subsidiaries in Mexico and the US Midwest assemble module-level products for OEM platforms. These intermediaries face margin compression as direct OEM-foundry relationships proliferate.
- Contract Manufacturers:Foxconn and Jabil facilities in Mexico and the southern United States provide assembly and test services. USMCA rules of origin calculations determine semiconductor content eligibility for tariff preferences.
- Aftermarket Providers:Replacement part distributors serve extended vehicle lifecycles and industrial equipment refurbishment. California and Florida electronics recyclers recover legacy ICs for obsolete system maintenance.
OEMs dominate procurement value, with Contract Manufacturers expanding most quickly as nearshoring accelerates test and assembly migration to Mexico border industrial parks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Americas IC industry traces its commercial scale to Fairchild Semiconductor's 1957 founding in Mountain View, California, establishing the planar process that diffused fabrication expertise across subsequent spin-offs and regional clusters.
United States
Arizona and Texas absorb the bulk of CHIPS Act subsidies for 300mm wafer capacity expansion. EPA tailpipe regulations and NHTSA safety mandates embed silicon density into Detroit and California automotive platforms. Intel's Arizona fabs and Samsung's Taylor, Texas complex anchor domestic logic production.
Canada
Ontario's automotive corridor in Windsor and Waterloo sustains demand for mixed-signal and power management devices. Health Canada coordinates with EPA on emissions-aligned vehicle electrification timelines. Ottawa and Toronto design centers qualify AEC-Q100 components for Tier-1 supplier integration.
Mexico
Nuevo León and Chihuahua industrial parks attract back-end test and packaging investment from Asian OSATs. USMCA rules of origin clarify semiconductor content requirements for tariff preferences. Monterrey clusters concentrate assembly capacity for automotive module integration.
Brazil
São Paulo's industrial automation sector sustains demand for ruggedized analog and power ICs in extended temperature ranges. ANVISA medical device regulations indirectly drive precision mixed-signal requirements. Campinas and São José dos Campos host design centers for industrial controller development.
Americas Integrated Circuit (IC) Market Competitive Landscape
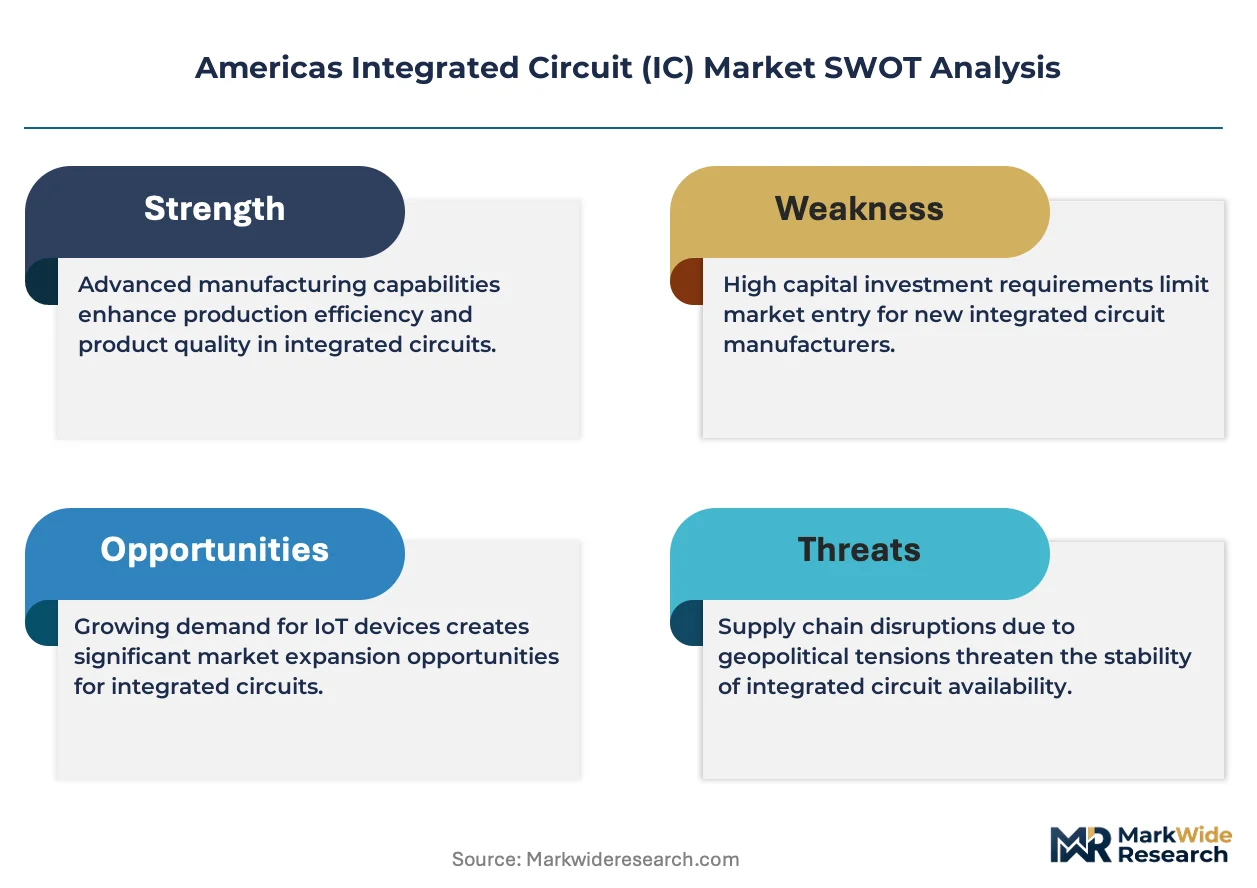
The competitive structure tilts toward integrated IDMs with captive fabrication and long-term automotive qualification relationships. Market concentration remains high among established players with multi-decade process expertise and DMEA-certified facilities for defense applications. Three archetypes dominate: vertically integrated analog specialists, advanced logic foundries with federal subsidy access, and automotive-qualified mixed-signal providers. Capacity expansion and direct OEM procurement relationships constitute the primary competitive vectors as supply constraints persist.
Among established integrated device manufacturers, Intel Corporation, Texas Instruments, and NXP Semiconductors represent distinct strategic positions. Intel anchors domestic logic fabrication through Arizona-based captive capacity. Texas Instruments exemplifies the broad analog portfolio archetype with sustained industrial and automotive socket dominance. NXP occupies the automotive-qualified mixed-signal specialization, securing Tier-1 supplier relationships through domain controller expertise.
| Leading Market Players |
|---|
| Intel Corporation |
| Texas Instruments |
| Analog Devices |
| Infineon Technologies AG |
| STMicroelectronics |
| NXP Semiconductors |
| On Semiconductor Corporation |
| Microchip Technology |
| Renesas Electronics Corporation |
| Others |
Pricing and Supply Chain Analysis
Federally subsidized fab construction in Arizona and Texas concentrates capital deployment among sovereign-backed producers, compressing procurement timelines while embedding long-term contract structures that insulate domestic wafer pricing from spot volatility in East Asian foundry markets.
Pricing Analysis
Contract-based long-term offtake dominates procurement between automotive OEMs and qualified foundries, with price differentiation hinging on AEC-Q100 certification grade and volume scale commitments. Cost compression in mature analog nodes is intensifying because secondary equipment brokers face depreciation mismatches against 20-year automotive production schedules. Tier-1 suppliers exhibit highest price sensitivity due to margin compression from direct OEM-foundry disintermediation, while defense contractors accept premium pricing for DMEA-accredited radiation-hardened supply.
Supply Chain Analysis
Single-source vulnerability sits with Dutch and Japanese lithography equipment suppliers, constraining sub-7nm node advancement for domestic logic fabs. Geographic supply concentration centers on Taiwan, South Korea, and the United States for advanced wafer fabrication, while East Asian chemical processors dominate Ajinomoto build-up film and bismaleimide-triazine resin inputs. Tariff exposure through USMCA rules of origin calculations creates compliance complexity for Mexico-based assembly operations. Distribution runs through direct foundry relationships with automotive OEMs, bypassing traditional tiered component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas IC market functions as a regulatory compounder, with EPA tailpipe mandates and NHTSA safety requirements embedding silicon density into vehicle platforms faster than supply elasticity can respond.
For Market Incumbents: To counter process engineer scarcity as retiring Intel and GlobalFoundries veterans deplete experiential knowledge pools, anchor capacity addition in Arizona community college partnership pipelines while securing DMEA certification investment for defense premium capture.
For New Entrants and Emerging Players: Capture white-space in GaN-on-silicon power integration for 800-volt EV onboard chargers, targeting California and Texas renewable energy conversion applications with merged RF-power process flows as the go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among legacy node analog specialists with 20-year automotive supply guarantees, framing long-term viability around industrial automation socket persistence; monitor BIS equipment access calibration as the inflection signal for advanced logic capacity feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| CHIPS Act Fab Construction | Department of Commerce subsidies compress project hurdle rates for 300mm Arizona and Texas capacity. |
| Automotive Qualification Investment | AEC-Q100 Grade 1 stress protocols secure 36-48 month design-in cycles with Detroit OEM platforms. |
| Advanced Packaging Migration | 2.5D interposer and fan-out panel-level capacity captures assembly value from monolithic die displacement. |
| Defense Trusted Foundry Accreditation | DMEA certification creates captive demand pools for radiation-hardened aerospace and satellite applications. |
| Mexico Border Assembly Expansion | Nuevo León industrial parks attract nearshored OSAT investment under clarified USMCA content rules. |
Research Methodology
Direct dialogue with foundry operations executives, Tier-1 supplier procurement directors, automotive platform engineers, and semiconductor equipment specialists grounded qualitative assessment, cross-referenced against SEC 10-K filings, Department of Commerce CHIPS Act award disclosures, EPA regulatory dockets, and IHS Markit vehicle production databases. Bottom-up wafer demand modeling and top-down federal incentive allocation analysis provided triangulation anchors.
Segment-level value outputs across the projection horizon reflect CMOS node scaling economics, automotive electrification content-per-vehicle trajectories, and foundry utilization rate assumptions. CAGRs derive from equipment installation timeline compression under Treasury tax credit schedules and analog versus digital IC replacement intensity differentials.
Equipment access restriction escalation, automotive qualification timeline extension, and noble gas supply disruption are the dominant revision risks to modeled capacity expansion assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Integrated CMOS Tri-Gate Transistor Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
LED Driver IC Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
PFC Control IC Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Rugged IC Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market