
 Global LED Phosphor Market | 2026-2036
Global LED Phosphor Market Size, Share, and Industry Trends Forecast 2026-2036
Global LED Phosphor Market Foresight
China's Jiangsu and Fujian provinces are rewriting regional supply dynamics through integrated phosphor-to-package manufacturing corridors. Nichia Corporation anchors high-performance nitride phosphor output through captive crystal growth operations in Japan. Intematix Corporation specializes in remote phosphor architectures that decouple thermal management from LED die design. OSRAM GmbH extends its European footprint via oxide-based formulations tailored to automotive forward-lighting specifications.
LED phosphors are inorganic luminescent materials, typically rare-earth doped silicates, nitrides, or oxides, that absorb blue or UV chip emission and down-convert it to broader visible spectra with quantum efficiencies exceeding 90%. These materials determine color temperature, color rendering index, and luminous efficacy in solid-state lighting systems. Nitride technology leads in high-power applications where thermal quenching resistance commands premium positioning, while quantum dot formulations represent the fastest-growing segment as display manufacturers pursue Rec. 2020 color gamut coverage. Silicate phosphors occupy the volume tier in general lighting, where cost-per-lumen dominates procurement criteria.
REACH and RoHS frameworks in Europe restrict cadmium and mercury content in phosphor precursors, forcing reformulation of legacy sulfide systems. China's MEE enforces emission controls on rare-earth roasting operations that feed phosphor supply chains. Japan's METI sets efficacy benchmarks through Top Runner standards that cascade into phosphor performance requirements. Stakeholders must monitor how evolving MEPS tiers across multiple jurisdictions redefine the minimum acceptable conversion efficiency for phosphor-coated packages.
Market Dynamics
Automotive OEMs are consolidating phosphor specifications around nitride and quantum dot systems as cabin lighting and headlamp architectures converge on higher color rendering indices. This specification tightening is compressing formulation diversity and elevating thermal stability requirements across the supply base.
Growth Catalysts
- China's dual carbon goals:MEPS tier upgrades are mandating mercury-free, high-efficiency phosphor architectures in domestic LED packaging operations.
- Automotive forward-lighting:Nitride phosphor absorption is accelerating as OEMs chase 90+ CRI targets for adaptive driving beam systems.
- East Asian manufacturing clusters:Proximity between phosphor synthesis facilities and LED packaging houses in Japan, South Korea, and China is compressing logistics costs and lead times.
Market Restraints
- Rare-earth price volatility:Cerium and europium oxide feedstock costs fluctuate with Chinese export quota adjustments, squeezing silicate phosphor margins.
- Supply concentration risk:High-purity nitride phosphor precursor production concentrates in Japanese crystal growth operations, creating single-source vulnerability.
- Technical limitation:Quantum dot thermal degradation above 85°C restricts deployment in high-power automotive engine-bay applications.
Strategic Opportunities
- India's lighting infrastructure:UJALA program scale-up is creating demand for cost-optimized silicate phosphors in street and residential retrofit markets.
- Regulatory tailwind:EU RoHS cadmium exemptions for quantum dots are scheduled to expire, positioning indium phosphide alternatives for premium display capture.
- Technology convergence:Mini-LED backlighting architectures are fusing remote phosphor films with quantum dot enhancement layers, opening hybrid formulation demand.
Industry Challenges
- Rare-earth roasting emission compliance:China's MEE enforcement is forcing phosphor precursor suppliers to retool pyrometallurgical operations, extending qualification timelines.
- IP licensing complexity:Nitride phosphor composition patents held by Japanese and European entities create royalty stacking for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LED Phosphor Market |
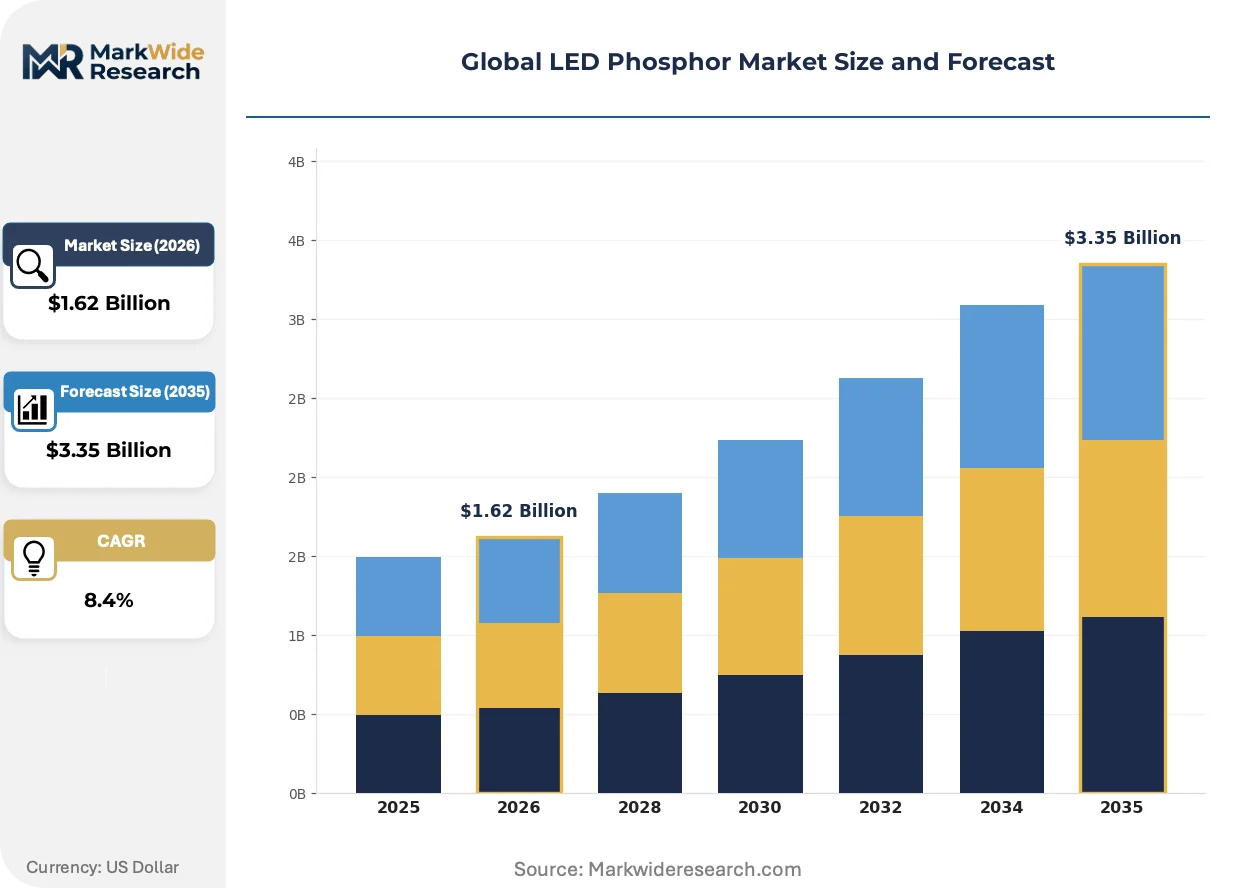
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $3.35 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Phosphor, Green Phosphor, Red Phosphor, Blue Phosphor, White Phosphor Technology: Quantum Dots, Silicate, Nitride, Oxide, Sulfide Application: Backlighting, General Lighting, Automotive Lighting, Display, Signage End User Industry: Consumer Electronics, Transportation, Hospitality, Education, Entertainment |
| Companies Covered | Nichia Corporation, Intematix Corporation, OSRAM GmbH, Lumileds Holding B.V., Denka Co. Ltd., Mitsubishi Chemical Corporation, Merck KGaA, Seoul Semiconductor Co. Ltd., Yuji International Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LED Phosphor Market Shifts & Advancements
Formulation chemistry and thermal management architectures are diverging as display and automotive applications impose incompatible performance envelopes. This bifurcation is fragmenting R&D investment and reshaping supplier specialization.
Perovskite quantum dot emitters are achieving 95% quantum efficiency with narrower full-width half-maximum than traditional cadmium selenide systems. Display manufacturers in South Korea and China are integrating these materials into quantum dot enhancement films for Rec. 2020 gamut coverage. Conventional cadmium-based quantum dot formulations are rendering obsolete in premium television and monitor segments.
REACH authorization requirements for cadmium and lead compounds are forcing reformulation of legacy sulfide phosphor systems across European lighting manufacturing. ECHA sunset date pressures are cascading into supply chain audits and substitution timelines for phosphor-coated LED packages. Oxide-based alternatives are absorbing R&D priority in general lighting applications subject to EU market access.
Automotive Tier 1 suppliers are unbundling phosphor specification authority from LED package vendors and asserting direct relationships with phosphor synthesis houses. This disintermediation compresses formulation feedback loops but fragments volume commitments across smaller supplier bases. German and Japanese automotive lighting programs are most advanced in this procurement model transition.
Global LED Phosphor Market Segmentation
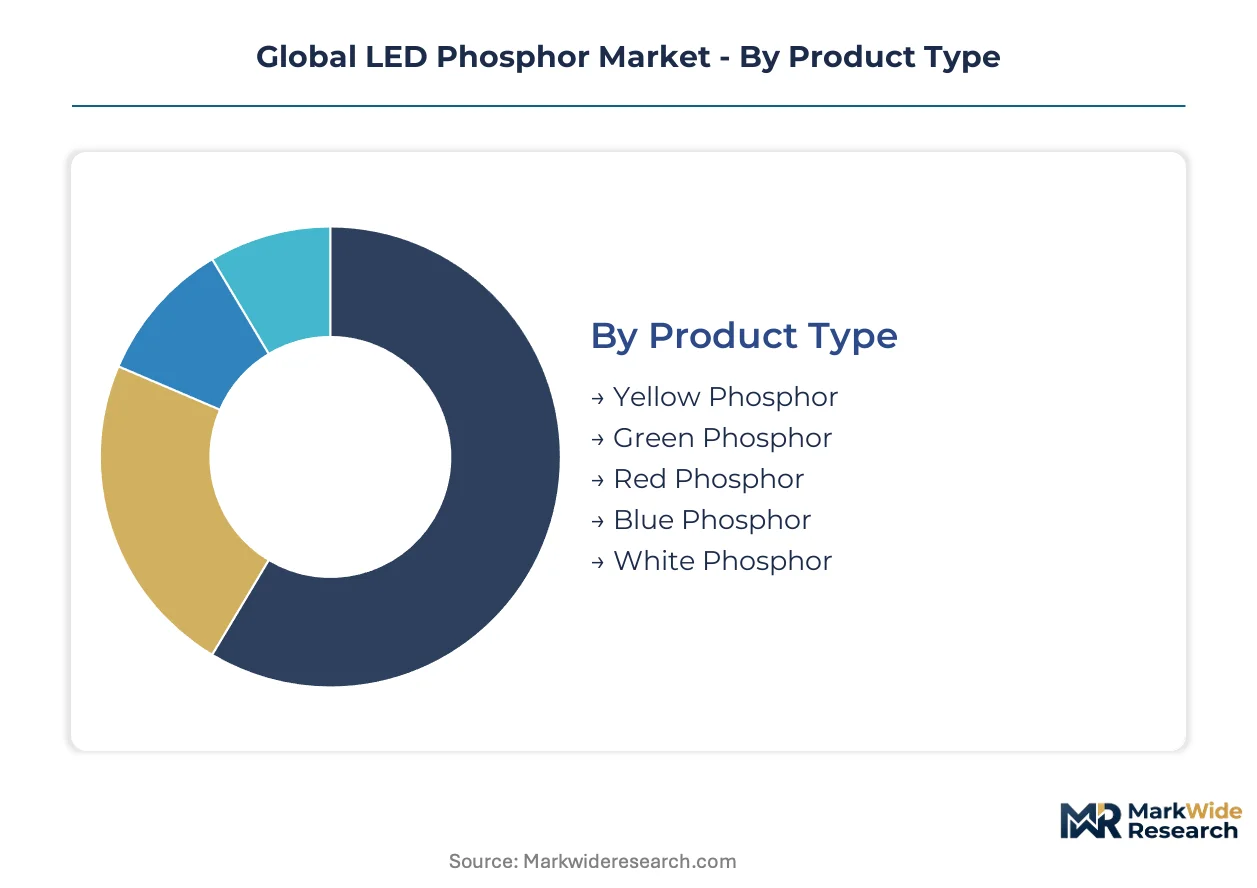
Phosphor segmentation determines procurement economics and thermal architecture decisions across LED packaging operations. Formulation chemistry, application requirements, and end-use specifications create distinct performance tiers that reshape supplier positioning and margin structures.
Product Type:
Color emission characteristics define cost structures and efficacy trade-offs across LED package designs.
- Yellow Phosphor:Cerium-doped yttrium aluminum garnet formulations dominate general lighting volume. Chinese packaging houses in Jiangsu province absorb the majority of yellow phosphor output for residential retrofit programs.
- Green Phosphor:Eu²⁺-activated silicates and β-SiAlON nitrides enable high-lumen efficacy in commercial downlighting. Automotive interior applications in Germany and Japan are specifying narrow-band green phosphors for 90+ CRI cabin environments.
- Red Phosphor:Nitride-based CaAlSiN₃:Eu²⁺ systems command premium positioning in high-power applications. Display backlighting in South Korea is absorbing increasing volumes of narrow red phosphors for wide-gamut coverage.
- Blue Phosphor:Eu²⁺-activated aluminate and halophosphate formulations serve specialty medical and horticultural applications. Limited deployment relative to other color categories due to direct blue LED chip availability.
- White Phosphor:Blended multi-phosphor systems or single-source white emitters simplify package assembly. Hospitality retrofit projects in India specify white phosphor packages for color consistency across large installations.
Yellow phosphor holds installed capacity. Red phosphor is rotating up the share rankings.
Technology:
Thermal stability and quantum efficiency specifications fragment R&D investment across competing material platforms.
- Quantum Dots:Colloidal semiconductor nanocrystals achieve 95% quantum efficiency with narrow emission bandwidth. South Korean display manufacturers are integrating perovskite quantum dots into quantum dot enhancement films for Rec. 2020 gamut coverage.
- Silicate:(Sr,Ba)₂SiO₄:Eu²⁺ and related orthosilicates balance cost and performance for general lighting. China's UJALA street lighting program is specifying silicate phosphors for lumen-per-rupee optimization.
- Nitride:MAlSiN₃:Eu²⁺ systems resist thermal quenching above 150°C. Japanese crystal growth operations in Anan and Tokushima supply high-purity nitride precursors for automotive forward-lighting specifications.
- Oxide:Garnet and aluminate hosts serve mid-power applications where thermal loading remains moderate. European REACH compliance is redirecting formulation toward mercury-free oxide alternatives.
- Sulfide:SrGa₂S₄:Eu²⁺ and CaS:Eu²⁺ systems face regulatory pressure from cadmium and mercury content restrictions. Legacy sulfide production is contracting as ECHA sunset dates approach for hazardous precursor authorization.
Nitride technology commands premium positioning. Quantum dot formulations are gaining share fastest.
Application:
End-use thermal environments and color performance requirements create incompatible specification envelopes.
- Backlighting:Narrow-band red and green phosphors enable wide-color-gamut LCD displays. Chinese panel manufacturers in Shenzhen and Hefei specify nitride-silicate hybrid systems for mini-LED backlighting architectures.
- General Lighting:High-efficacy warm white phosphors dominate residential and commercial retrofit demand. India's Bureau of Energy Efficiency mandates are accelerating silicate phosphor absorption in street lighting tenders.
- Automotive Lighting:Nitride phosphors withstand engine-bay thermal cycling for headlamp applications. German Tier 1 suppliers are unbundling phosphor specification authority from LED package vendors.
- Display:Quantum dot enhancement films and on-chip phosphor coatings compete for color gamut performance. South Korean television manufacturers specify cadmium-free indium phosphide quantum dots for premium segment positioning.
- Signage:High-brightness saturated colors serve outdoor advertising and traffic signal applications. Japanese traffic infrastructure standards specify nitride-based red phosphors for visibility under direct sunlight.
General lighting holds installed capacity. Automotive lighting is rotating up the share rankings.
End User Industry:
Customer procurement sophistication and volume concentration reshape supplier relationship models.
- Consumer Electronics:Smartphone and tablet manufacturers specify ultra-thin phosphor films for compact backlighting. Chinese OEMs in Dongguan and Chongqing negotiate direct phosphor supply agreements bypassing traditional LED package vendors.
- Transportation:Automotive and aerospace lighting programs impose stringent thermal and reliability qualifications. Japan's METI Top Runner standards cascade into phosphor performance requirements for domestic vehicle production.
- Hospitality:Hotel and restaurant chains prioritize color consistency and dimming performance across property portfolios. Marriott and Hilton specification programs in the United States are standardizing phosphor-coated LED packages for renovation cycles.
- Education:School districts and universities specify flicker-free, high-CRI lighting for classroom environments. India's K-12 infrastructure expansion is creating demand for cost-optimized silicate phosphor packages.
- Entertainment:Cinema and broadcast applications demand precise color temperature control and dimming linearity. Dolby Cinema specifications in the United States require phosphor systems meeting DCI-P3 color gamut with minimal metameric failure.
Consumer electronics holds installed capacity. Transportation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity nitride phosphor precursor production concentrates in Japanese crystal growth operations, while Chinese rare-earth roasting facilities feed silicate phosphor supply chains. East Asian manufacturing clusters in Japan, South Korea, and China compress logistics costs between phosphor synthesis and LED packaging operations.
China
Jiangsu and Fujian provinces host integrated phosphor-to-package manufacturing corridors serving domestic LED packaging houses. The Ministry of Ecology and Environment enforces emission controls on rare-earth roasting operations that feed phosphor supply chains. Xiamen and Suzhou industrial zones concentrate silicate phosphor production for the UJALA street lighting program.
Japan
Anan and Tokushima host captive crystal growth operations supplying high-purity nitride precursors for automotive forward-lighting specifications. METI Top Runner standards cascade into phosphor performance requirements for domestic vehicle production. Nichia Corporation anchors nitride phosphor output through proprietary synthesis operations in Tokushima Prefecture.
Germany
Automotive Tier 1 suppliers assert direct phosphor specification authority unbundled from LED package vendors. ECHA REACH authorization requirements force reformulation of legacy sulfide phosphor systems across European lighting manufacturing. Bavaria-based automotive lighting programs lead procurement model transitions toward direct phosphor supplier relationships.
South Korea
Display manufacturers integrate perovskite quantum dots into enhancement films for Rec. 2020 gamut coverage. Seoul Semiconductor Co. Ltd. and domestic panel makers in Suwon and Paju specify nitride-silicate hybrid systems for mini-LED backlighting architectures. The MFDS regulates precursor chemicals in quantum dot manufacturing processes.
India
The Bureau of Energy Efficiency mandates accelerate silicate phosphor absorption in street lighting tenders under UJALA program scale-up. Cost-optimized formulations dominate procurement criteria for residential retrofit markets. Gujarat and Maharashtra industrial corridors concentrate LED package assembly operations importing phosphor materials from East Asian suppliers.
Global LED Phosphor Market Competitive Landscape
Captive synthesis specialists and independent formulation houses split the market between vertically integrated LED package vendors and external phosphor suppliers. Japanese and European entities hold composition patents for nitride systems, creating royalty stacking for new market entrants. Three archetypes dominate: crystal growth operators with captive precursor supply, remote phosphor architecture specialists, and oxide-based formulation houses serving automotive specifications. Competitive moves center on backward integration into rare-earth precursor refining and strategic patent licensing to secure automotive qualification pathways.
Among Japanese crystal growth operators, Nichia Corporation exemplifies the captive synthesis archetype through Tokushima-based nitride phosphor operations. Intematix Corporation occupies a position within the remote phosphor specialist tier, decoupling thermal management from LED die design. OSRAM GmbH anchors the European oxide-based formulation segment, with German automotive forward-lighting specifications driving qualification priorities.
| Leading Market Players |
|---|
| Nichia Corporation |
| Intematix Corporation |
| OSRAM GmbH |
| Lumileds Holding B.V. |
| Denka Co. Ltd. |
| Mitsubishi Chemical Corporation |
| Merck KGaA |
| Seoul Semiconductor Co. Ltd. |
| Yuji International Co. Ltd. |
| Others |
Supply & Pricing Matrix
Japanese crystal growth operations in Tokushima and Anan prefectures anchor high-purity nitride phosphor precursor output, concentrating margin capture upstream while downstream LED packaging houses in Jiangsu province compete on volume throughput. This upstream-downstream asymmetry funnels pricing power toward nitride formulation specialists and compresses silicate phosphor margins in commoditized general lighting tiers.
Pricing Analysis
REACH and RoHS frameworks dictate the pricing tier structure across European phosphor procurement, separating mercury-free oxide formulations at premium positioning from legacy sulfide systems facing sunset compliance costs. Three-tier pricing structure across premium, standard, and economy levels reflects thermal stability grades, with nitride systems commanding top tier for automotive specifications. Cost compression in silicate phosphors intensifies because Chinese packaging houses negotiate aggregate volume contracts for UJALA program deployment. Street lighting tenders in India exhibit highest price sensitivity, while German Tier 1 automotive suppliers absorb premium nitride pricing for adaptive driving beam qualification.
Supply Chain Analysis
Extended payment terms from Japanese crystal growth operators to Korean display manufacturers illustrate supply-chain finance facilities penetrating phosphor precursor trade flows. Production gravity centers on Japan, China, and South Korea, with rare-earth roasting in Jiangsu feeding silicate synthesis and nitride crystal growth anchored in Tokushima. The supply chain draws from cerium oxide, europium oxide, and high-purity nitrogen feedstocks. Single-source vulnerability concentrates in Japanese nitride precursor operations. Distribution runs through integrated phosphor-to-package manufacturing corridors in Fujian province serving domestic LED assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum dot thermal degradation thresholds and cadmium exemption expiries are disrupting established formulation hierarchies, creating entry windows for indium phosphide alternatives and perovskite architectures.
For Market Incumbents: Entrench nitride phosphor positioning through captive crystal growth capacity expansion in Tokushima and strategic patent licensing to block royalty-stacking competitors. Secure automotive qualification pathways before German Tier 1 suppliers complete procurement model transitions. Backward integration into rare-earth precursor refining in Jiangsu province defends margin position against export quota volatility. For New Entrants and Emerging Players: India's UJALA street lighting retrofit represents the most penetrable entry point for cost-optimized silicate phosphor specialists, with Gujarat and Maharashtra industrial corridors absorbing import volumes from East Asian suppliers. Perovskite quantum dot enhancement films for Rec. 2020 display applications offer technology-led positioning against cadmium-based incumbents. Direct supply agreements with Chinese panel manufacturers in Shenzhen bypass established LED package vendor intermediation. For Investors and Strategic Acquirers: Capital is best deployed toward remote phosphor architecture specialists with decoupled thermal management IP and oxide-based formulation houses serving REACH-compliant European automotive specifications. Long-term viability hinges on mercury-free formulation portfolios and cadmium-free quantum dot pipelines. Watch ECHA sunset date enforcement cadence as inflection indicator for sulfide system substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Jiangsu province operations secure cerium and europium oxide supply against Chinese export quota adjustments. |
| Patent Licensing for Nitride Compositions | Japanese and European IP holders extract royalties while constraining new entrant formulation freedom. |
| Perovskite Quantum Dot Scale-Up | South Korean display manufacturers achieve Rec. 2020 gamut without cadmium regulatory exposure. |
| Direct Phosphor Specification Authority | German automotive Tier 1 suppliers disintermediate LED package vendors for formulation feedback control. |
| Mercury-Free Oxide Formulation Transition | European REACH compliance redirects R&D priority away from legacy sulfide systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with phosphor synthesis specialists, LED package procurement leads, automotive Tier 1 lighting engineers, and display panel manufacturing directors; alongside secondary validation through customs trade data, SEC filings of listed LED component suppliers, METI Top Runner standard documentation, and ECHA REACH authorization records. Bottom-up triangulation across phosphor formulation chemistries and top-down cross-check against LED packaging volume aggregates ensured consistency.
Forecast inputs span nitride, silicate, oxide, sulfide, and quantum dot technology platforms across general lighting, automotive, display backlighting, and signage applications, with end-user industry segmentation modeling consumer electronics, transportation, hospitality, education, and entertainment demand patterns. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit erosion curves. Rare-earth price volatility indices and MEPS tier upgrade schedules fed sensitivity testing.
Practitioners should monitor Chinese MEE enforcement intensity on rare-earth roasting operations and EU RoHS cadmium exemption renewal decisions for early signals of supply constraint or formulation substitution acceleration. Forecasts reflect assumptions around thermal stability thresholds and regulatory sunset timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Mini LED Display Market
LED
India LED Lighting Market
LED
Middle East LED Lighting Market
LED
South America LED Lighting Market
LED
Smart LED Indoor Signage Market
LED
Philippines LED Market
LED
Europe LED Packaging Market
LED
North America LED Packaging Market
LED
France LED Lighting Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Architectural LED Products Market
LED
LED Lighting Controllers Market
LED
UK Outdoor LED Lighting Market
LED
Arrow LED Displays Market
LED
LED Display Control Card Market
LED
Japan LED Lighting Market