
 Japan LED Lighting Market | 2026-2036
Japan LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Japan LED Lighting Market Insights
Japan's shrinking pool of licensed electrical contractors is reorganizing how LED manufacturers structure their distribution and installation support networks. Panasonic Holdings Corporation leverages its captive contractor training academies to sustain channel loyalty across prefectural markets. Nichia Corporation anchors upstream supply through in-house epitaxial wafer production, while Koito Manufacturing Co., Ltd. dominates automotive-grade LED modules for domestic vehicle assembly lines.
Japan LED Lighting refers to solid-state illumination systems employing semiconductor diodes that emit visible light when electrical current passes through a p-n junction, typically operating at 2-4 volts DC with luminous efficacy exceeding 150 lumens per watt in premium configurations. These systems serve commercial, industrial, and residential applications by converting electrical energy directly to photonic output with minimal thermal dissipation compared to legacy incandescent or fluorescent technologies. Residential end users represent a mature volume base where replacement cycles drive steady turnover, while smart lighting technology captures expanding margin pools as building automation systems penetrate commercial real estate. The fixtures product category leads installed value due to integrated luminaire designs that command higher unit economics than standalone bulb replacements.
METI's Top Runner Program, JIS C 8156 standards, and the Act on Rationalizing Energy Use collectively mandate minimum luminous efficacy thresholds and labeling requirements that filter lower-performance imports from Japanese distribution channels. PMDA oversight of medical-grade illumination and local prefectural building codes further segment compliance obligations across application verticals. Stakeholders must monitor how amendments to the Energy Conservation Act reshape qualification criteria for subsidy-eligible LED products in public procurement channels.
Market Dynamics
The Japan LED Lighting Market is compressing around METI's tightening Top Runner efficiency mandates, which filter substandard imports while forcing domestic manufacturers toward higher-lumen-per-watt architectures. This regulatory pressure is restructuring competitive positioning around captive supply chains and prefecture-level installation networks.
Growth Catalysts
- METI Top Runner Program:Successive efficiency benchmarks accelerate replacement cycles in commercial buildings across Tokyo and Osaka, locking out lower-performance imports.
- Smart city infrastructure:Municipal retrofit programs in Kanto and Kansai corridors bundle LED deployment with building automation systems, expanding fixture value per installation.
- Aging infrastructure replacement:Commercial real estate in Japan's major urban centers faces synchronized end-of-life cycles for legacy fluorescent systems, creating concentrated demand windows.
Market Restraints
- Licensed contractor scarcity:Japan's shrinking pool of certified electrical installers constrains installation velocity and inflates labor costs for retrofit projects.
- Epitaxial wafer supply concentration:Upstream dependence on limited domestic III-V semiconductor production creates vulnerability in high-efficacy chip availability.
- JIS C 8156 compliance friction:Stringent testing and labeling requirements extend product qualification timelines for new market entrants.
Strategic Opportunities
- Human-centric lighting:Circadian rhythm-tuned systems are penetrating healthcare and educational facilities as PMDA guidelines evolve for medical-grade illumination.
- Predictive maintenance integration:IoT-enabled luminaires with embedded sensors are creating recurring revenue streams through lighting-as-a-service models in commercial portfolios.
- Prefectural building code harmonization:Local subsidy programs in Aichi and Fukuoka are lowering adoption barriers for residential smart lighting retrofits.
Industry Challenges
- Cross-functional talent gaps:Shortages in firmware engineering and optical design are bottlenecking smart fixture development timelines.
- Legacy system integration complexity:Retrofit projects face interoperability failures when connecting DC-native LED drivers to existing AC building management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan LED Lighting Market |
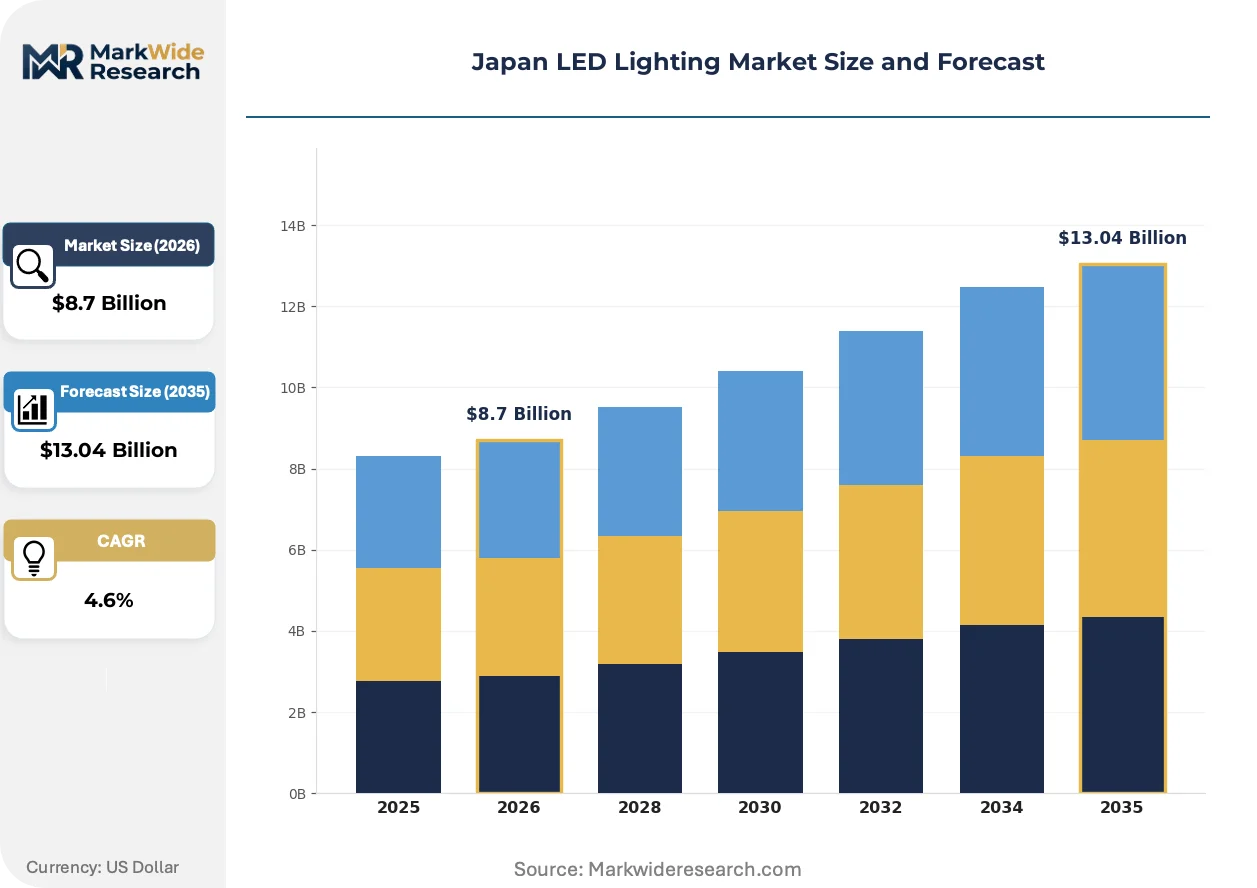
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Downlights End User: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Tunable White, RGB, Organic LED Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Panasonic Holdings Corporation, Toshiba Lighting & Technology, Nichia Corporation, Maruwa Shomei, ODELIC, ENDO Lighting Corporation, Stanley Electric Co., Ltd., Mitsubishi Electric Corporation, Koito Manufacturing Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan LED Lighting Market Trends and Innovations
Technological convergence between solid-state illumination and building automation is reshaping how value is captured across the Japan LED Lighting Market. Three forces are restructuring competitive dynamics.
Mini-LED backlighting architectures are supplanting conventional edge-lit designs in premium commercial and automotive applications. Domestic vehicle assembly lines are adopting these configurations for interior ambient systems. The shift is compressing margins for mid-tier COB package suppliers while rewarding epitaxial specialists with captive wafer capacity.
METI's amendments to the Energy Conservation Act are tightening subsidy eligibility criteria for public procurement channels. Municipal purchasers must now demonstrate lifecycle cost calculations that favor integrated luminaire designs over standalone bulb replacements. Prefectural governments in Kanto are accelerating compliance timelines ahead of national deadlines.
Building operators are unbundling lighting specification from general electrical contracting, creating direct procurement relationships with fixture manufacturers. This disintermediation is fragmenting traditional distribution channels in Tokyo's commercial real estate sector. Facility managers are prioritizing vendors with in-house installation training academies to mitigate contractor scarcity risks.
Japan LED Lighting Market Segmentation
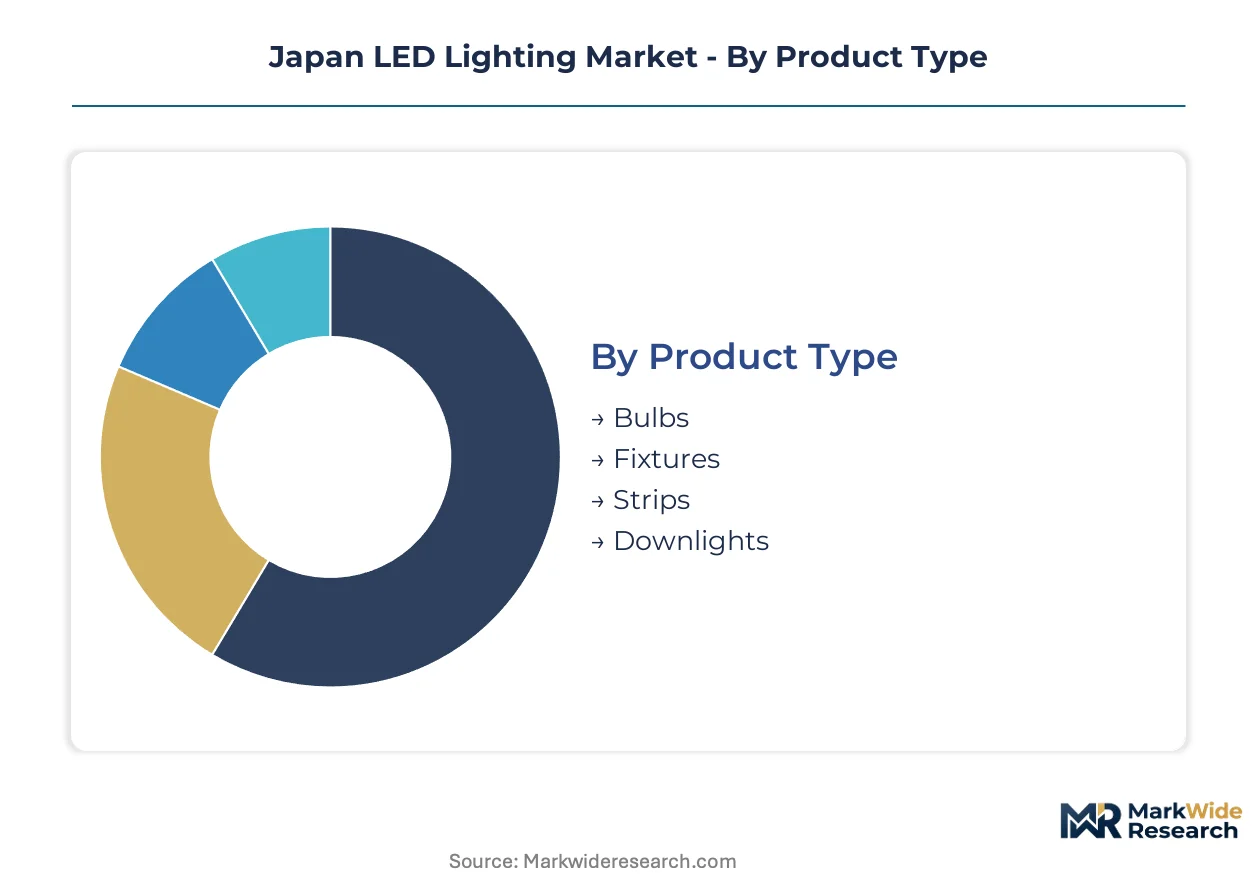
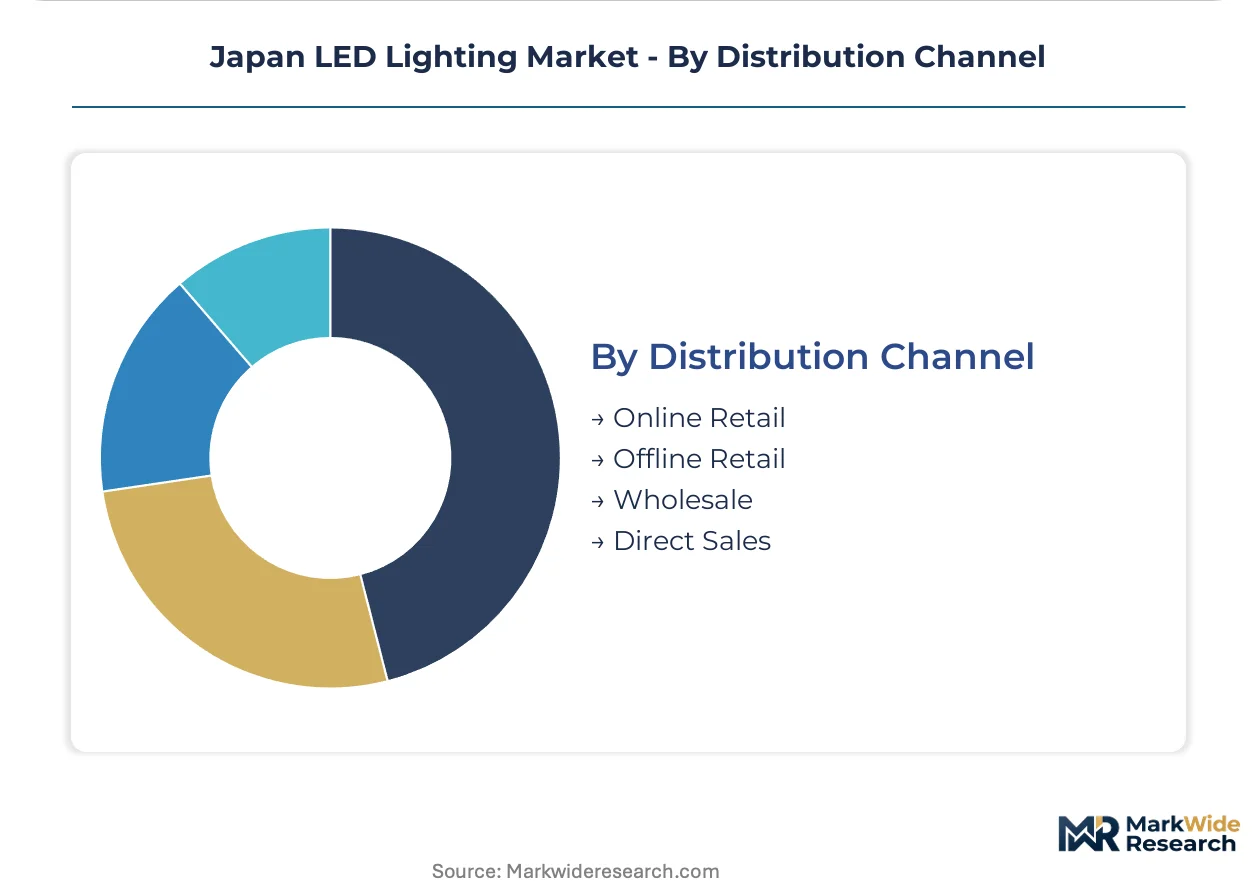
Segmentation in the Japan LED Lighting Market reveals how METI efficiency mandates and smart city procurement reshape profit pools across product tiers and channel structures. Manufacturers configure their portfolios differently depending on whether they target municipal retrofit programs, commercial building automation, or residential replacement cycles.
Product Type:
Margin pools concentrate in integrated luminaire designs that bundle optical engineering with thermal management, commanding premium positioning over commoditized bulb replacements.
- Fixtures:Integrated luminaire assemblies combine LED modules with heat sinks, drivers, and optical lenses in sealed enclosures. Demand clusters in Tokyo and Osaka commercial retrofits where METI subsidy programs favor lifecycle cost calculations for complete fixture replacements over bulb swaps.
- Bulbs:Standalone retrofit lamps with Edison or pin-base connectors serve residential replacement cycles and legacy fluorescent conversions. Volume concentrates in Kanto prefectures where aging infrastructure replacement coincides with prefectural energy rebate programs.
- Downlights:Recessed ceiling luminaires for commercial and residential ambient illumination.
- Strips:Flexible linear LED arrays for accent and cove lighting applications.
The dominant share belongs to Fixtures, while Downlights is closing the gap fastest.
End User:
Application concentration follows Japan's urban infrastructure geography, with commercial building stock in major metropolitan areas driving the highest-value procurement.
- Commercial:Office towers, retail spaces, and hospitality venues deploy integrated luminaire systems with building automation compatibility. Procurement concentrates in Tokyo's 23 wards and Osaka's central business district where municipal retrofit programs bundle LED deployment with smart city infrastructure.
- Residential:Single-family homes and multi-unit dwellings generate steady replacement demand for standard retrofit bulbs and downlights. Demand concentrates in Kansai corridor prefectures where local subsidy programs in Aichi and Fukuoka lower adoption barriers for smart lighting upgrades.
- Industrial:Manufacturing facilities and warehouses require high-bay and task-optimized illumination systems.
- Outdoor:Street lighting, parking structures, and architectural facade applications.
Commercial commands the largest revenue pool, though Residential is expanding most quickly through prefectural smart home incentive programs.
Technology:
Technology tiering separates premium systems with embedded connectivity and circadian tuning from basic illumination commodities.
- Smart Lighting:Network-connected luminaires with embedded sensors, wireless protocols, and cloud-based control platforms enable lighting-as-a-service business models. Adoption concentrates in Tokyo commercial real estate where facility managers disintermediate traditional electrical contractors and procure directly from manufacturers with installation training academies.
- Tunable White:Color temperature-adjustable systems supporting circadian rhythm applications in healthcare and educational facilities. Demand drivers include evolving PMDA guidelines for medical-grade illumination and prefectural school modernization programs.
- RGB:Multi-color systems for architectural accent and entertainment applications.
- Organic LED:Thin-film electroluminescent panels for specialized display and ambient lighting.
Smart Lighting holds the dominant position, while Tunable White is gaining share fastest through healthcare facility specifications.
Distribution Channel:
Channel structure reflects the contractor scarcity crisis reshaping how products reach installation sites across Japanese prefectures.
- Direct Sales:Manufacturer-to-facility-manager relationships bypass traditional electrical wholesalers in Tokyo's commercial real estate sector. Panasonic Holdings Corporation leverages captive contractor training academies to sustain channel loyalty and mitigate installation velocity constraints.
- Offline Retail:Home improvement centers and electrical supply houses serve residential and small commercial contractors. Geographic concentration follows prefectural population density with strongest presence in Kanto and Kansai corridors.
- Wholesale:Electrical distributors stock bulk quantities for contractor procurement.
- Online Retail:E-commerce platforms serve DIY residential replacements and specification research.
Direct Sales captures the highest margin transactions, while Online Retail is climbing the fastest as procurement research digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's Top Runner Program anchors demand concentration in Japan's major metropolitan corridors, with prefectural retrofit programs creating synchronized replacement cycles across Kanto and Kansai.
Kanto/Tokyo
Commercial building stock in Tokyo's 23 wards drives premium fixture demand through municipal smart city bundles. The Tokyo Metropolitan Government's Green Building Program mandates LED retrofits for public facilities. Facility managers in Marunouchi and Otemachi financial districts procure directly from manufacturers with captive installation networks.
Kansai/Osaka
Osaka's central business district concentrates hospitality and retail retrofit activity alongside aging infrastructure replacement. Osaka Prefecture's energy rebate programs accelerate residential smart lighting adoption. The Osaka-Kobe industrial corridor sustains demand for high-bay industrial luminaires in manufacturing facilities.
Chubu/Nagoya
Automotive supply chain proximity in Aichi Prefecture generates specialized demand for automotive-grade LED modules. Local subsidy programs in Nagoya lower adoption barriers for residential efficiency upgrades. Toyota City and surrounding industrial zones deploy task-optimized illumination in precision manufacturing environments.
Kyushu
Fukuoka Prefecture's regional subsidy programs expand residential smart lighting penetration in southwestern markets. Semiconductor fabrication facilities in Kumamoto and Kagoshima require cleanroom-grade illumination systems. The Kyushu Economic Federation coordinates prefectural procurement standards for public building retrofits.
Hokkaido
Sapporo's municipal infrastructure faces accelerated replacement cycles due to extreme climate stress on legacy lighting systems. Hokkaido Prefecture's energy independence targets prioritize high-efficacy LED deployment in remote municipal facilities. Cold-weather performance specifications filter product eligibility for northern installations.
Japan LED Lighting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Japan LED Lighting Market. The vendor base organizes around three strategic tiers: diversified electronics conglomerates with captive distribution networks, specialized epitaxial wafer producers controlling upstream supply, and automotive-focused module suppliers integrated with domestic vehicle assembly lines. Competitive dynamics center on backward integration into III-V semiconductor production and the construction of prefecture-level contractor training academies to mitigate installation velocity constraints.
Among diversified conglomerates, Panasonic Holdings Corporation exemplifies the integrated manufacturer archetype with captive contractor development infrastructure. Nichia Corporation anchors the upstream specialist tier through in-house epitaxial wafer production. Koito Manufacturing Co., Ltd. occupies a position within the automotive module segment, serving domestic vehicle assembly requirements.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Toshiba Lighting & Technology |
| Nichia Corporation |
| Maruwa Shomei |
| ODELIC |
| ENDO Lighting Corporation |
| Stanley Electric Co., Ltd. |
| Mitsubishi Electric Corporation |
| Koito Manufacturing Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Wafer-scale economies at Nichia Corporation's Anan facilities set price floors for high-efficacy LED modules, concentrating margin capture among epitaxial specialists while forcing mid-tier packagers toward commoditized bulb segments. This scale dynamic tightens procurement leverage for Tokyo facility managers bundling smart city retrofits with building automation systems.
Pricing Analysis
Price spreads between Kanto commercial retrofits and Kyushu residential replacements reflect METI subsidy tiering rather than pure manufacturing cost. Three-tier pricing structure across premium smart fixtures, standard integrated luminaires, and economy retrofit bulbs dominates procurement channels. Cost compression in economy bulbs intensifies because Chinese import competition exploits JIS C 8156 compliance gaps. Municipal purchasers in Tokyo's 23 wards show least price sensitivity, while Fukuoka residential buyers prioritize rebate-eligible entry points.
Supply Chain Analysis
Inventory cycles for epitaxial wafers stretch 16-20 weeks, constraining fixture manufacturers' ability to respond to synchronized replacement windows in Osaka and Nagoya. Upstream supply draws from Japan's domestic III-V semiconductor fabrication, South Korean chip packaging specialists, and Taiwanese driver IC foundries. Gallium nitride substrates and phosphor conversion materials feed from concentrated specialty chemical suppliers. Single-source vulnerability in high-purity sapphire wafer supply threatens high-bay industrial luminaire availability. Distribution runs through captive contractor networks in Tokyo, electrical wholesalers in Kansai, and direct e-commerce for residential replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefectural subsidy fragmentation creates service-layer niches where national manufacturers lack localized installation support, rewarding regional specialists with contractor academy infrastructure.
For Market Incumbents: Secure backward integration into epitaxial wafer capacity to defend margin position against Nichia Corporation's captive supply advantage. Expand contractor training academies in Aichi and Fukuoka to preempt new entrant channel capture as prefectural building codes harmonize around smart lighting specifications. For New Entrants and Emerging Players: Predictive maintenance software integration for commercial portfolios represents the most penetrable white-space where Panasonic Holdings Corporation's hardware-centric model under-serves facility managers seeking lighting-as-a-service revenue streams. Target Nagoya automotive supplier campuses with tunable white systems for precision manufacturing environments, leveraging direct sales relationships that bypass electrical wholesaler markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors epitaxial specialists with captive wafer capacity and firmware-enabled fixture developers over pure-play bulb assemblers. Long-term viability hinges on METI efficiency mandate compliance trajectory rather than volume scale. Acquisition target archetype: regional contractors with prefectural installation licenses and smart city procurement relationships. Watch for PMDA medical-grade illumination guideline amendments as inflection signal for healthcare facility specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Production | Captive gallium nitride supply insulates margins from Nichia Corporation's pricing power in high-efficacy segments. |
| Contractor Training Academy Expansion | Licensed installer scarcity in Kanto and Kansai corridors creates channel loyalty through captive workforce development. |
| Predictive Maintenance Platform Launch | IoT-enabled luminaires unlock recurring revenue from Tokyo commercial real estate portfolios seeking operational expenditure models. |
| Prefectural Subsidy Compliance Certification | Aichi and Fukuoka rebate program eligibility accelerates residential smart lighting penetration in underpenetrated corridors. |
| Automotive-Grade Module Supply Agreement | Toyota City proximity and domestic vehicle assembly integration secure volume commitments from Tier 1 suppliers. |
Research Methodology
A standing panel of LED fixture procurement managers, electrical contractor association directors, METI efficiency standard committee members, and prefectural building code administrators provided ongoing calibration across primary interview cycles. Secondary validation drew from JIS C 8156 certification databases, METI Top Runner Program compliance filings, Tokyo Metropolitan Government procurement records, and Osaka Prefecture energy rebate program disclosures. Bottom-up unit economics from fixture manufacturers triangulated against top-down municipal retrofit budget allocations.
Consistency checks against METI energy conservation act amendment timelines and smart city infrastructure deployment schedules anchored projection outputs across the analysis window. Segmentation modeling incorporated product type tiering, end-user application concentration, technology sophistication levels, and distribution channel structure. CAGRs derived from replacement cycle synchronization patterns in aging commercial building stock and prefectural subsidy program ramp schedules.
Underlying assumptions cover METI efficiency mandate enforcement continuity and epitaxial wafer supply stability, with deviation risk concentrated in licensed contractor availability shocks and JIS standard revision timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Small Pitch LED Display Market
LED
UK LED Lighting Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Japan Outdoor LED Lighting Market
LED
Global Waterproof LED Module Market
LED
Led Video Walls Market
LED
Thailand LED Market
LED
South America Indoor LED Lighting Market
LED
GCC LED Lighting Market
LED
India LED Outdoor Lighting Market
LED
Middle East LED Lighting Market
LED
Four-Digit 7 Segment LED Displays Market
LED
China Indoor LED Lighting Market
LED
Superluminescent Diodes Market
LED
UAE LED Lights Market