
 Street Lighting Market | 2026-2036
Street Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Street Lighting Market Intelligence
Platform-based smart lighting management is reconfiguring the value chain from one-time hardware sales to recurring service revenue. Signify Holding leverages its extensive portfolio in connected lighting systems to capture this shift. Acuity Brands competes through its integrated controls and software solutions for municipal clients. Cree Lighting differentiates with its focus on high-efficacy LED luminaires for new installations.
Street lighting comprises public illumination systems designed for roadways, pathways, and urban spaces to ensure safety and security. Modern systems utilize LED sources with specific correlated color temperature (CCT) values, typically between 2700K and 4000K, for optimal visual comfort. Within product types, LED technology has almost entirely displaced legacy HID and fluorescent options. The retrofit installation segment is expanding rapidly as municipalities upgrade existing infrastructure to connected lighting for enhanced operational efficiency.
Regulatory frameworks like the EU Green Deal and China's dual carbon goals mandate energy efficiency, accelerating the phase-out of older lighting technologies. In the United States, the EPA's ENERGY STAR program provides certification standards that guide procurement decisions for municipal buyers. Stakeholders must now decide whether to prioritize basic energy savings or invest in comprehensive smart city platforms with advanced data capabilities.
Market Dynamics
The central structural force is the transition from one-time hardware sales to recurring revenue models. This shift is driven by the adoption of platform-based smart lighting management systems that redefine the value chain for municipal end-users.
Growth Catalysts
- Energy Efficiency Mandates:Regulations like the EU Green Deal compel the replacement of legacy systems, creating consistent demand for energy-saving LED technology.
- Smart City Projects:Large-scale infrastructure programs in India drive concentrated procurement of connected street lighting systems for urban renewal.
- LED Cost-Effectiveness:The falling cost of LED luminaires makes retrofit projects financially viable for budget-constrained municipalities, speeding up replacement cycles.
Market Restraints
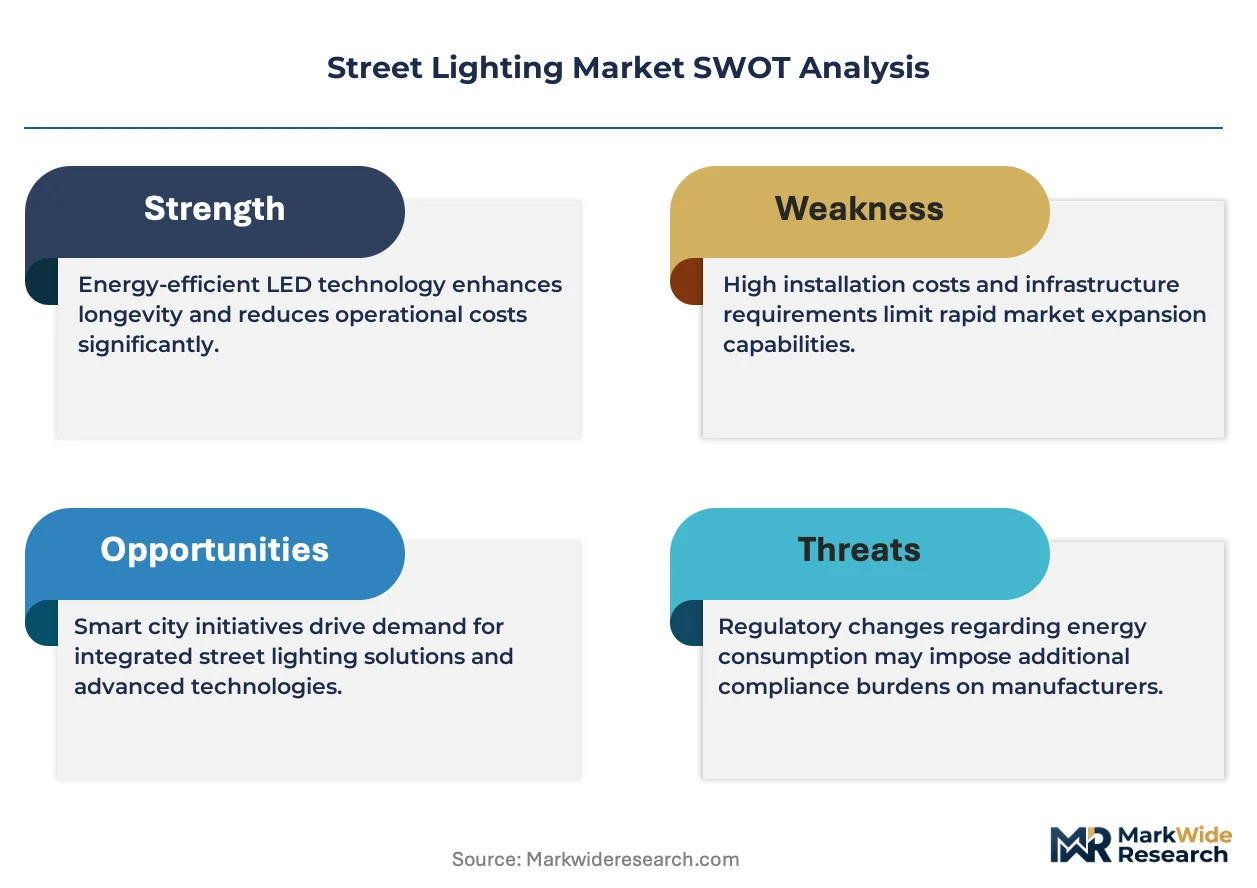
- High Initial Capex:Significant upfront investment for city-wide smart conversions remains a primary barrier for municipalities with constrained budgets.
- Platform Interoperability:A lack of universal standards for control systems creates vendor lock-in risks and complicates long-term infrastructure planning.
- Component Volatility:Reliance on a concentrated supply chain for critical semiconductors creates risks of price instability and procurement delays.
Strategic Opportunities
- Lighting-as-a-Service (LaaS):Subscription models allow municipalities to bypass high upfront costs, converting capital expenditures into predictable operational expenses.
- Integrated Pole Infrastructure:Embedding environmental, traffic, or acoustic sensors into light poles creates new data-driven services beyond simple illumination.
- Secondary City Expansion:Urbanization in Southeast Asian and African secondary cities presents an underpenetrated market for foundational smart lighting infrastructure.
Industry Challenges
- Legacy System Integration:Connecting new smart systems with outdated municipal IT and utility billing platforms presents significant technical and operational hurdles.
- Cybersecurity Vulnerabilities:Securing vast networks of connected devices from cyberattacks demands specialized expertise that is often lacking in public works departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Street Lighting Market |
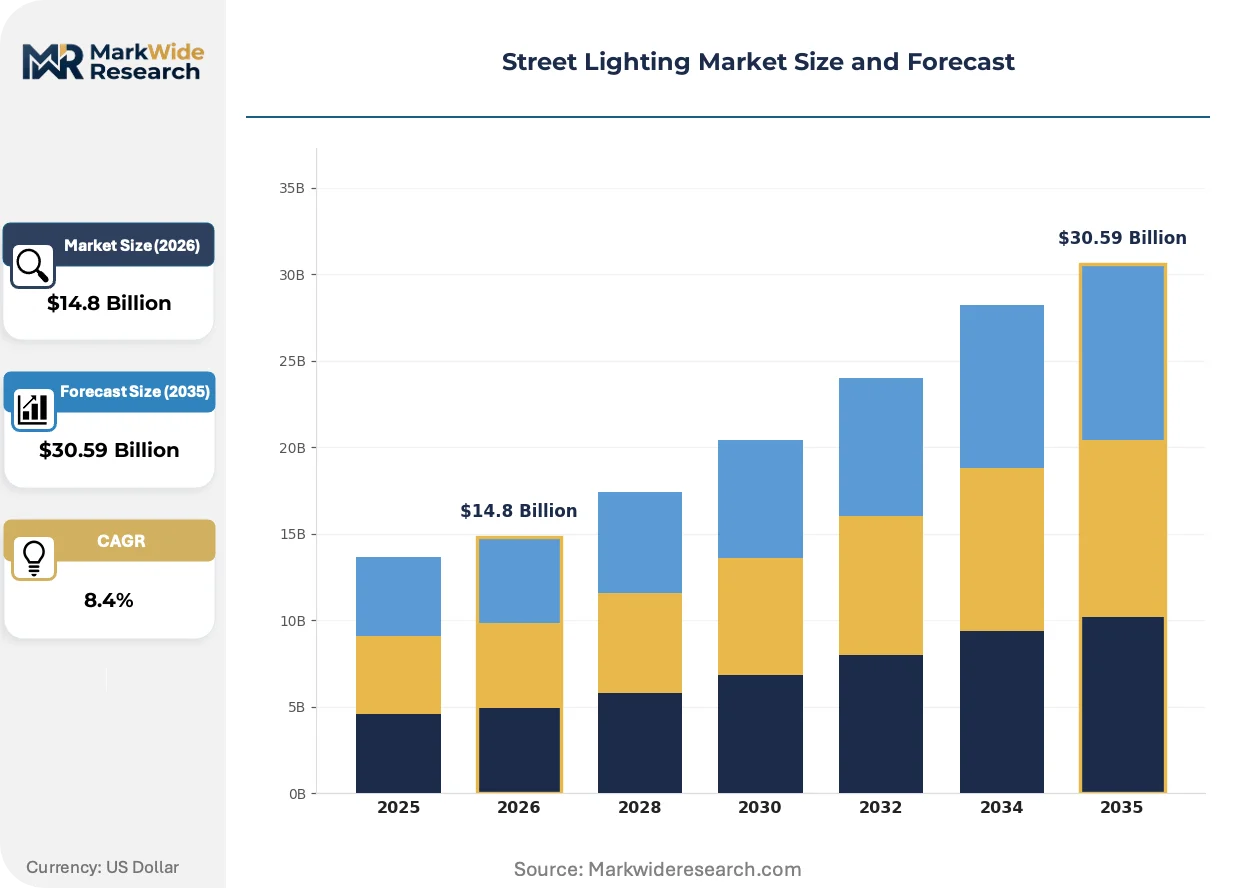
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Solar, HID, Fluorescent Technology: Smart Lighting, Conventional, Hybrid, Connected Lighting End User: Municipal, Institutional, Commercial, Residential Installation Type: New Installation, Retrofit, Replacement, Upgradation |
| Companies Covered | Acuity Brands, Signify Holding, ams-OSRAM AG, Cree Lighting, Zumtobel Group, Cooper Lighting, Hubbell, Schréder, Thorn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Street Lighting Market Strategic Shifts & Innovations
The function of street lighting is transforming from a basic municipal utility into an intelligent urban data platform. This evolution is driven by the convergence of energy-efficient hardware, ubiquitous connectivity, and new service-oriented business models.
Adaptive lighting control systems use real-time sensor data from motion or ambient light detectors to adjust illumination levels dynamically. Municipalities and campus facility managers are adopting these systems to maximize energy savings beyond simple LED conversion. The market is migrating from static, scheduled dimming profiles to dynamic, responsive illumination, enabling deeper operational efficiency and improved public safety.
China's dual carbon goals establish a national strategy that compels provincial governments to invest in energy-efficient infrastructure. This policy directly impacts the legacy High-Intensity Discharge (HID) luminaire segment by accelerating its mandated phase-out. Consequently, procurement now prioritizes LED products with the highest lumens-per-watt efficacy to meet stringent new energy targets.
Municipal buying is evolving from discrete hardware purchases toward acquiring integrated systems via long-term public-private partnerships (PPPs). This model transfers financial and operational risk to private sector partners who manage installation, maintenance, and network operations. This approach is most visible in large-scale smart city projects across North America and Europe.
Street Lighting Market Segmentation
Street lighting market segmentation provides a granular understanding of diverse customer needs and technological preferences. This detailed analysis helps stakeholders identify specific growth pockets and tailor solutions for different operational contexts, moving beyond basic illumination to integrated urban platforms.
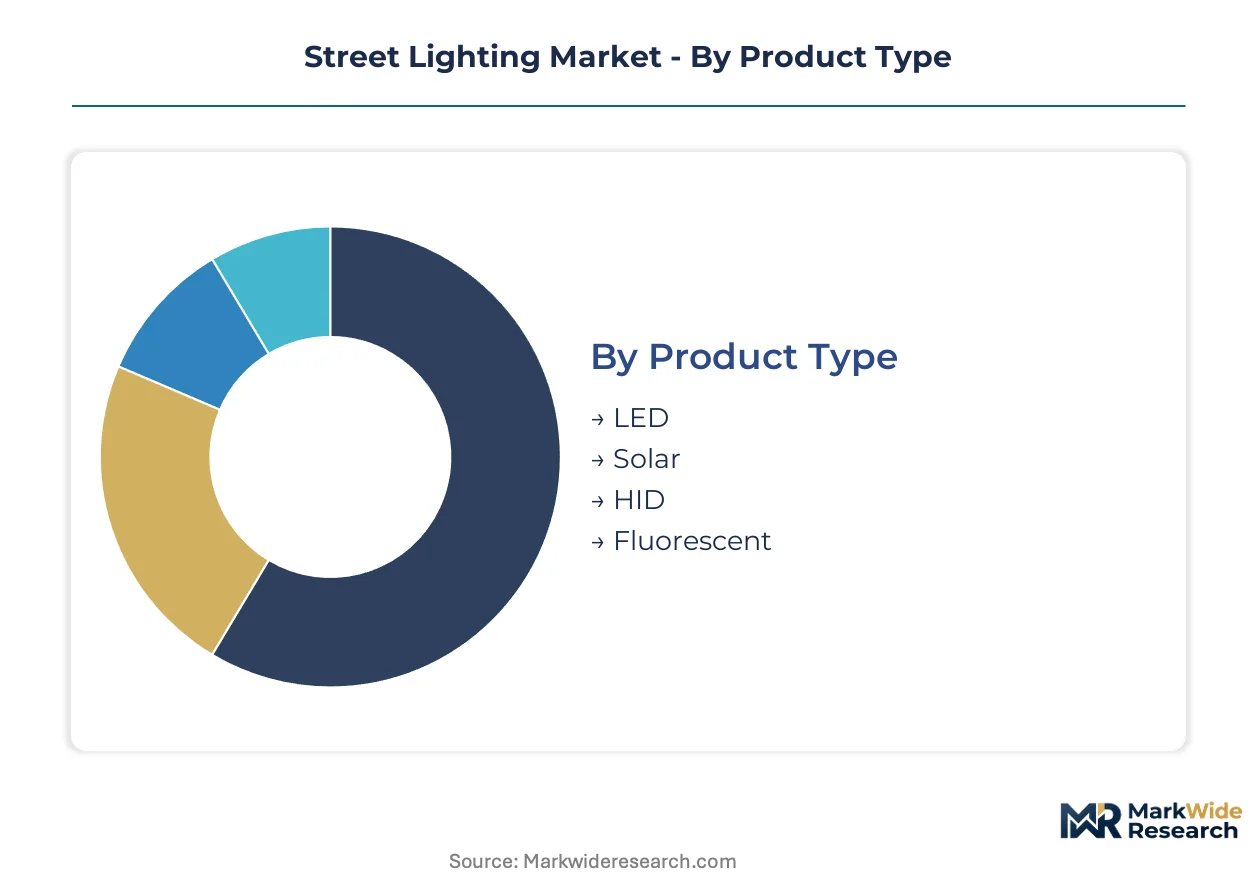
Product Type:
The diverse product types in street lighting dictate varying after-sales service requirements, influencing long-term operational costs and maintenance strategies for municipal authorities.
- LED:These highly energy-efficient diodes emit light in a narrow spectrum; integrated control systems are common. Demand concentrates in developed economies like Germany and the United States due to strong energy efficiency mandates and smart city initiatives.
- Solar:These self-contained units integrate photovoltaic panels, battery storage, and LED luminaires. Demand concentrates in remote or off-grid areas in countries like India and South Africa, driven by infrastructure gaps and sustainability goals.
- HID:High-intensity discharge lamps provide powerful illumination but consume significant energy for their output.
- Fluorescent:These gas-discharge lamps offer diffuse light, largely phased out in modern street lighting applications.
LED holds the largest share; momentum sits with Solar.
Technology:
Street lighting technologies differentiate significantly by their application scope, ranging from basic illumination to comprehensive urban data collection.
- Smart Lighting:These systems integrate sensors, communication modules, and central management platforms for dynamic control. Demand is strong in large urban centers such as London and Singapore, where advanced city management platforms are being deployed.
- Connected Lighting:These luminaires are equipped with communication capabilities, often wirelessly, allowing remote monitoring and control. Municipalities in countries like Canada and Australia are adopting these systems to optimize energy consumption and maintenance schedules.
- Conventional:These basic lighting fixtures operate independently without advanced control or networking features.
- Hybrid:These solutions combine elements of different technologies, often pairing solar power with smart control features.
Smart Lighting and Connected Lighting are expanding most quickly due to their operational efficiency benefits.
End User:
Different end-user segments exhibit distinct procurement processes and demand profiles for street lighting solutions.
- Municipal:These government bodies are responsible for public infrastructure, typically procuring large-scale systems for urban and suburban areas. Demand is concentrated in regions undertaking significant infrastructure upgrades, such as India's smart city initiatives and the EU Green Deal projects.
- Institutional:Entities like universities, hospitals, and corporate campuses require specialized lighting for safety and aesthetics. Organizations in the United States and Japan are investing in integrated campus-wide lighting systems for enhanced security and energy management.
- Commercial:Businesses and private developers install lighting for retail spaces, parking lots, and industrial facilities.
- Residential:These lighting solutions serve private residential communities and individual properties, often focused on aesthetic integration and security.
Municipal end-users account for the largest volume of street lighting deployments.
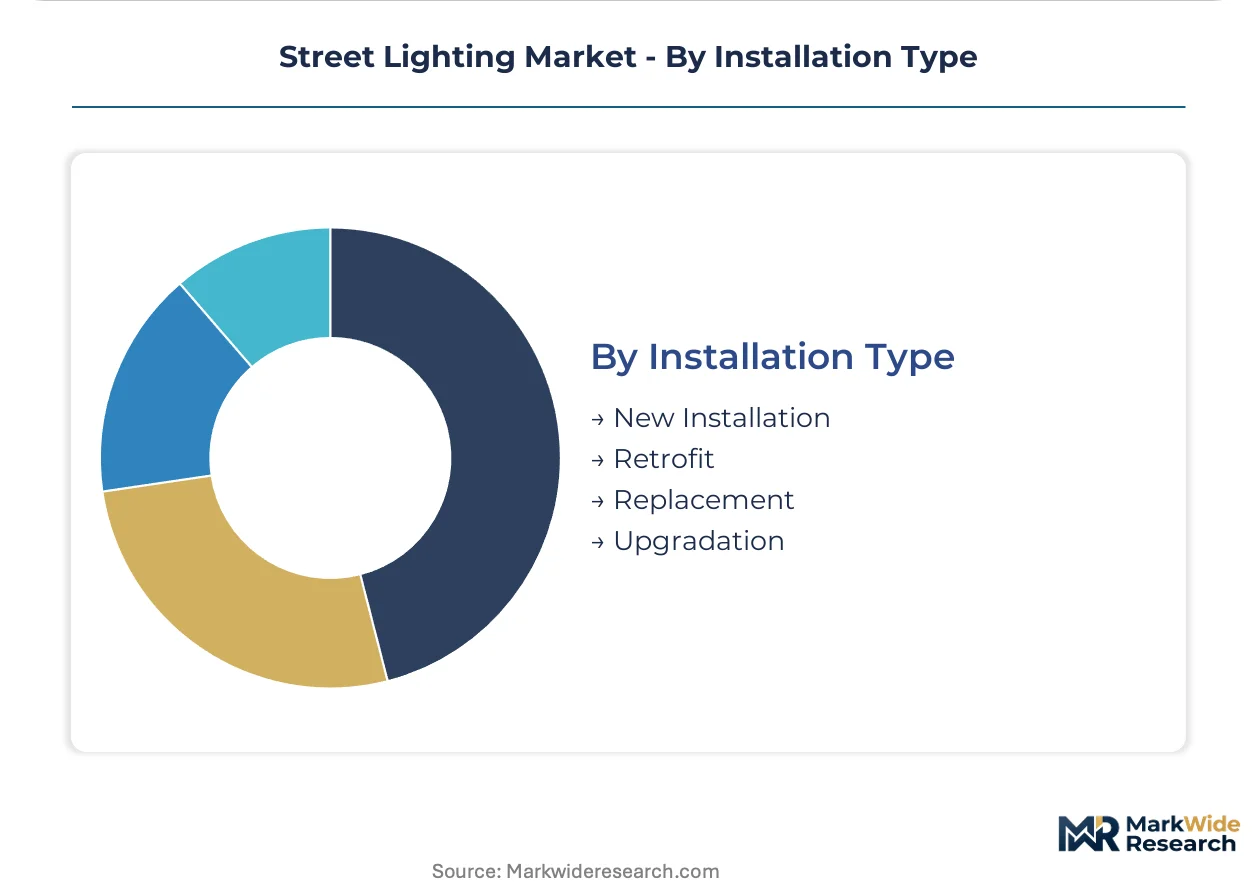
Installation Type:
The maturity curve of street lighting projects varies significantly across different installation types, impacting project complexity and investment cycles.
- Retrofit:This involves replacing existing, older lighting fixtures with newer, more efficient technologies, often LEDs. Demand for retrofits is high in mature economies across Europe and North America, where aging infrastructure requires modernization.
- New Installation:This entails deploying entirely new lighting systems in undeveloped areas or new construction projects. Developing economies like Vietnam and Brazil show strong demand for new installations as urbanization expands.
- Replacement:This is a direct one-for-one exchange of a faulty or end-of-life lighting unit with a similar or upgraded model.
- Upgradation:This involves enhancing existing lighting systems with advanced features like smart controls or higher efficacy luminaires.
Retrofit projects currently exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for street lighting solutions varies significantly across global markets. Developed economies often prioritize advanced smart features and comprehensive platforms, exhibiting lower price sensitivity for higher initial investments. Conversely, developing nations frequently focus on fundamental energy savings and cost-effective LED conversions, where budget constraints drive procurement decisions.
India
Extensive smart city initiatives drive significant demand for connected street lighting systems across urban areas. The Indian government's Smart Cities Mission mandates energy-efficient infrastructure upgrades nationwide. Urban centers like Mumbai and Delhi are implementing large-scale LED deployments, integrating smart controls for enhanced public services.
United States
Retrofit projects dominate the street lighting market, driven by aging infrastructure and strong energy efficiency goals. The EPA's ENERGY STAR program guides procurement decisions for municipalities seeking certified products. Cities such as Los Angeles are converting entire street networks to smart LED systems, improving operational efficiency and safety.
China
Rapid urbanization and stringent environmental policies fuel the adoption of high-efficacy LED luminaires in public spaces. China's dual carbon goals accelerate the mandated phase-out of legacy High-Intensity Discharge (HID) lighting technologies. Major urban clusters in the Yangtze River Delta are prioritizing smart lighting systems for comprehensive city management and data collection.
Germany
European Union Green Deal mandates compel municipalities to transition towards sustainable and energy-efficient lighting solutions. German cities emphasize advanced control systems and data integration for urban planning. Berlin's public works departments are deploying connected lighting networks, optimizing energy consumption and maintenance schedules across its infrastructure.
Brazil
Urban expansion and infrastructure development create strong demand for new street lighting installations in rapidly growing cities. Brazil's national energy efficiency programs encourage the adoption of modern LED technology in public procurement. Cities like São Paulo are investing in foundational smart lighting infrastructure to support growing urban populations and enhance public security.
Street Lighting Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the street lighting market. The industry exhibits a tiered structure, with specialized technology providers and large-scale hardware manufacturers. Strategic archetypes include integrated platform developers, high-efficacy luminaire specialists, and service-oriented solution providers. Key competitive moves involve strategic partnerships to expand service offerings and portfolio diversification into smart city platforms, alongside targeted mergers and acquisitions for technology access.
Specialists in integrated lighting solutions exemplify the market's shift towards recurring revenue models. Signify Holding, with its extensive portfolio in connected lighting systems, anchors the platform-based service archetype, offering comprehensive smart city capabilities. Acuity Brands competes through its integrated controls and software solutions for municipal clients, representing a comprehensive smart city approach focused on operational efficiency. Cree Lighting differentiates with its focus on high-efficacy LED luminaires for new installations, emphasizing hardware performance and energy savings for foundational infrastructure.
| Leading Market Players |
|---|
| Acuity Brands |
| Signify Holding |
| ams-OSRAM AG |
| Cree Lighting |
| Zumtobel Group |
| Cooper Lighting |
| Hubbell |
| Schréder |
| Thorn |
| Others |
Cost & Logistics Intelligence
Shanghai's advanced semiconductor manufacturing capacity directly influences the cost structure of LED luminaires, creating pricing pressure across the entire street lighting value chain. This supply concentration in key components dictates the final product pricing for municipalities.
Pricing Analysis
Project-based contracting dominates procurement for large-scale street lighting deployments, with municipalities often seeking long-term service agreements. Price differentiation stems from luminaire efficacy ratings and the sophistication of integrated smart controls, reflecting varying performance tiers. Pricing softness stems from the increasing commoditization of basic LED modules, particularly for standard retrofit projects. Institutional buyers generally exhibit lower price sensitivity than budget-constrained municipal clients, who prioritize initial capital expenditure.
Supply Chain Analysis
Upstream polysilicon and rare earth element extraction primarily occurs in China, anchoring the global supply chain for LED components. Key raw material dependencies include gallium nitride for LED chips and various plastics for luminaire housings. A significant structural risk is component volatility, driven by a concentrated semiconductor supply chain. Downstream distribution runs through a mix of direct sales to large municipal clients and regional electrical distributors for smaller projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This street lighting market sits as a defensive-moat story because high switching costs for integrated smart city platforms create vendor stickiness. Municipalities face significant operational disruption and data migration challenges when changing core infrastructure providers.
For Market Incumbents:Harden core platform offerings by integrating advanced cybersecurity protocols against evolving threats to urban data networks. Consolidate market share through strategic partnerships with specialized sensor manufacturers, expanding integrated pole infrastructure capabilities. Invest in localized manufacturing capacity in emerging markets to mitigate component volatility risks and meet regional procurement mandates. Focus on expanding recurring Lighting-as-a-Service (LaaS) contracts to secure predictable revenue streams against hardware commoditization.
For New Entrants and Emerging Players:Establish a beachhead in secondary cities across Southeast Asia and Africa, where foundational smart lighting infrastructure is underpenetrated. Target institutional end-users like university campuses or corporate parks with specialized, vertically integrated solutions for easier entry. A go-to-market angle could involve offering flexible, subscription-based models that bypass high initial capital expenditure for budget-constrained clients. Focus on open-standard interoperability to differentiate from proprietary vendor lock-in risks.
For Investors and Strategic Acquirers:Long-term, this sits as a utility-like infrastructure play because consistent public sector demand and regulatory mandates ensure stable growth. Acquisition target archetypes include specialized software providers for smart city platforms or regional integrators with strong municipal relationships. A key signal to watch is the increasing share of recurring service revenue in leading players' financial reports, indicating successful business model transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Lighting-as-a-Service (LaaS) Offerings | Secures predictable recurring revenue streams from municipal end-users, shifting from one-time hardware sales. |
| Integrate Advanced Sensor Technologies | Creates new data-driven services beyond illumination, enhancing smart city platform value for urban centers. |
| Invest in Cybersecurity Solutions | Protects vast networks of connected devices from cyberattacks, building trust with public works departments. |
| Form Public-Private Partnerships (PPPs) | Transfers financial and operational risks to private sector partners, facilitating large-scale infrastructure deployment. |
| Develop Open-Standard Interoperability | Reduces vendor lock-in risks for municipalities, potentially expanding market access for compatible solutions. |
Research Approach
Findings reconcile primary fieldwork against secondary review of government reports, industry association publications, and company financial disclosures. This involved interviews with municipal procurement officers, smart city project managers, luminaire design engineers, and urban planners. The analysis triangulates bottom-up market sizing from individual projects with top-down validation against macroeconomic indicators and regional infrastructure spending.
Forecast inputs considered include urbanization rates, regulatory mandates, and technological advancements across the analysis window. The market is segmented by product type, technology, end-user, and installation type, alongside regional economic development stages. Compound annual growth rates were derived from historical data trends, projected infrastructure investments, and expert consensus on technology adoption curves. Key forecast inputs include LED efficacy improvements and smart city project pipelines.
Sensitivities concentrate around shifts in government infrastructure spending priorities, unforeseen component supply disruptions, or rapid changes in energy policy. Forecasts reflect assumptions documented from current market conditions and known development plans. Cross-checking against national infrastructure development plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Fluorescent Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
North America Street Lighting Market
Lighting
Industrial Lighting Market
Lighting
Photography Light Box Market
Lighting
Solid-State Lighting Source Market
Lighting
Ring Lights Market
Lighting
Lamps and Lighting Market
Lighting
Xenon Lights Market
Lighting
Inspection Lighting Fixture Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Solid State Lighting System Market
Lighting
UAE Smart Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Portable Lamps Market
Lighting
Asia-Pacific Lighting Control Market