
 Led Video Walls Market | 2026-2036
Led Video Walls Market Size, Share, and Industry Trends Forecast 2026-2036
Led Video Walls Market Intelligence
Corporate command centers and broadcast studios are redrawing procurement priorities for LED video walls, shifting budget share from traditional static signage toward real-time data visualization systems. Daktronics leverages its sports venue dominance to extend into esports arenas and training facilities. Unilumin anchors high-volume production through its Shenzhen manufacturing base, competing aggressively on module cost for outdoor stadium installations. Samsung Electronics differentiates through proprietary semiconductor packaging that reduces thermal load in fine-pitch indoor configurations.
LED video walls consist of tiled arrays of light-emitting diode modules, typically measured by pixel pitch ranging from sub-1mm for indoor close-viewing applications to 10mm and above for outdoor long-distance visibility, assembled through surface-mount device bonding onto printed circuit boards to create seamless scalable displays for commercial and industrial visualization. Indoor LED installations occupy the largest revenue pool due to enterprise boardroom and retail flagship deployments, while transparent LED competes for architectural integration where glass facades require unobstructed sightlines. Rental LED sustains the fastest replacement cycle as event production companies prioritize rapid deployment frames and front-serviceable modules.
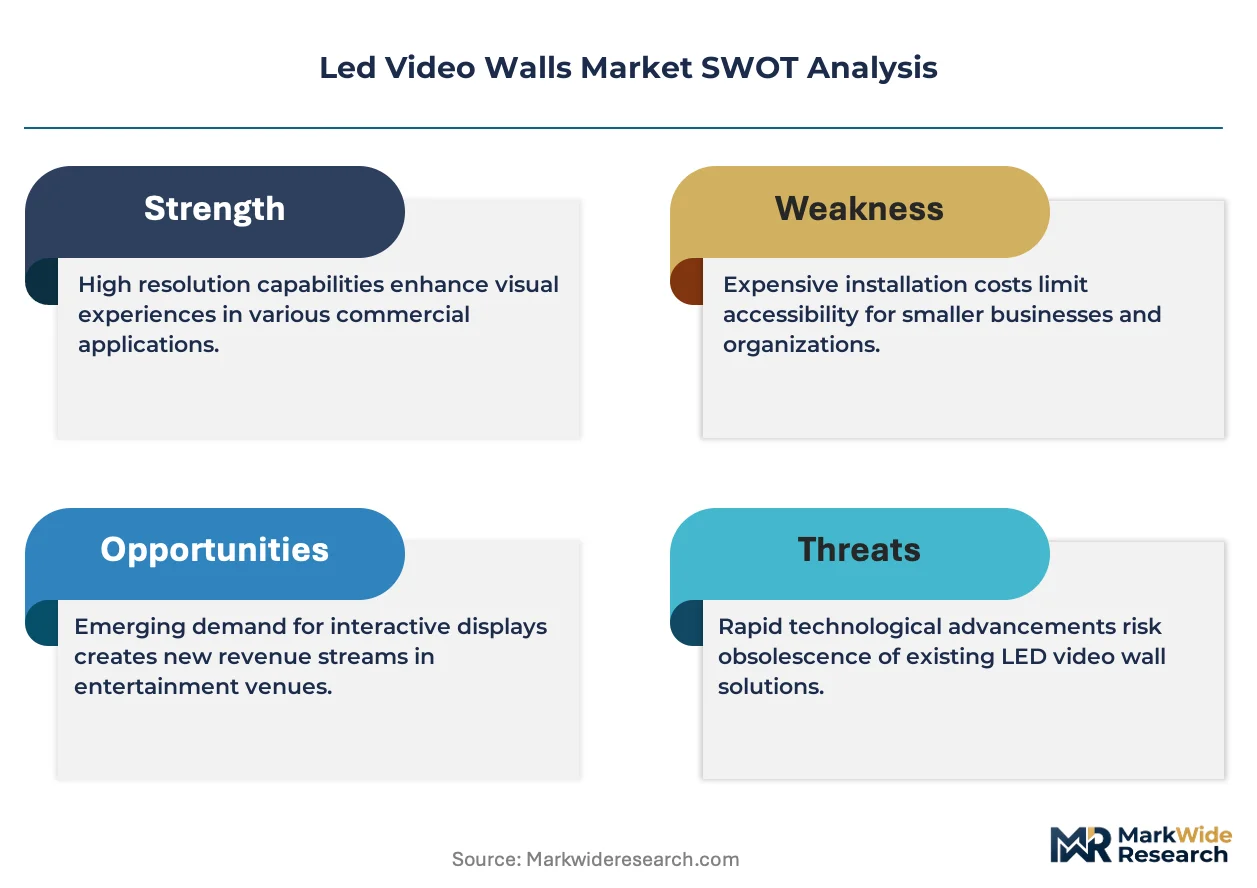
FCC Part 15 emissions standards constrain driver electronics for US-bound products, while the EU RoHS Directive and REACH framework restrict hazardous substances in solder and phosphor coatings, shaping supplier qualification requirements for European market access. China's GB standards for electronic display energy consumption, administered by MIIT, create domestic preference for locally certified manufacturers. Stakeholders must monitor divergence between regional efficiency certifications and emerging sustainability disclosure rules that will reshape component sourcing decisions.
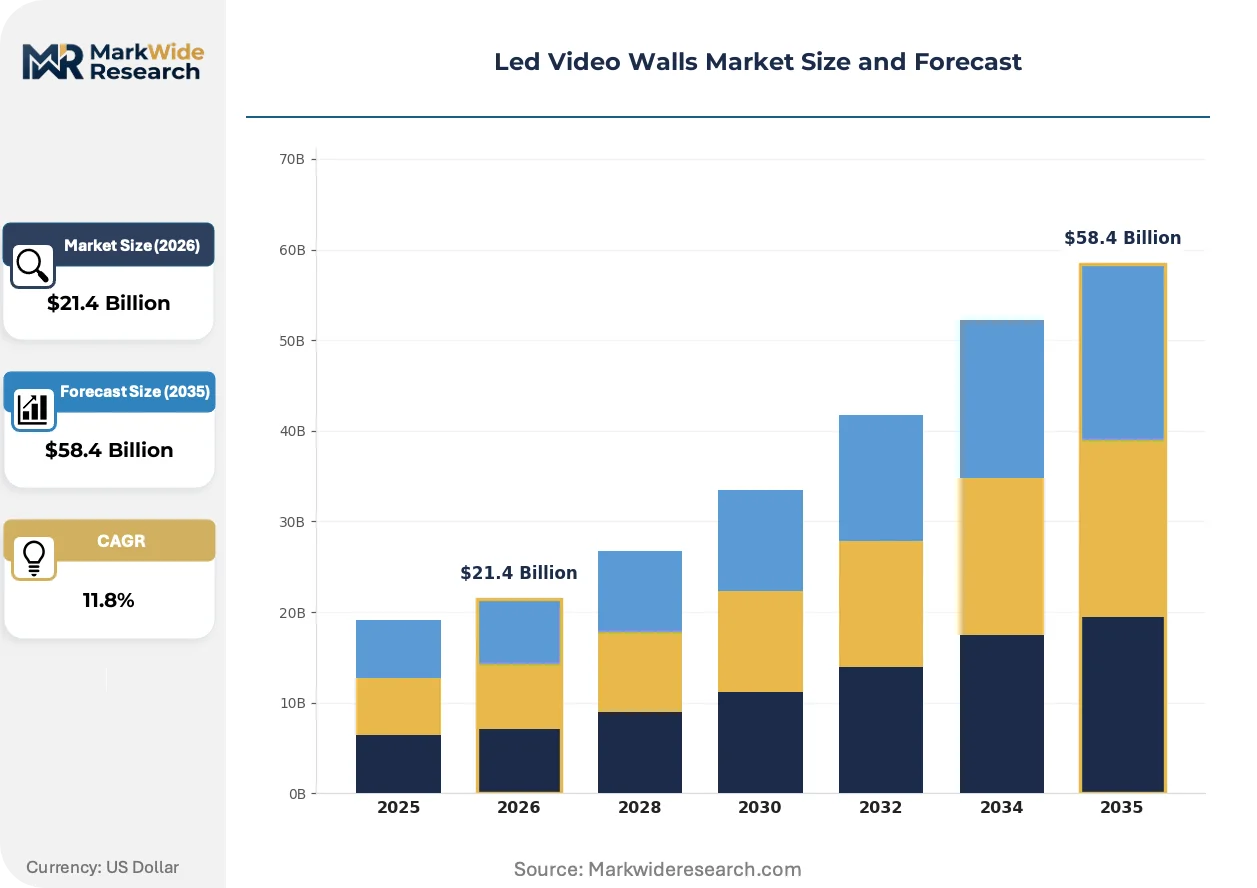
Market Dynamics
Fine-pitch indoor LED technology is compressing replacement cycles for legacy projection and LCD videowall installations across corporate, broadcast, and command-center environments. Shenzhen's manufacturing cluster concentration is reshaping procurement economics and supplier qualification protocols for international buyers.
Growth Catalysts
- EU Ecodesign Directive:Energy efficiency mandates are accelerating manufacturer migration toward lower-wattage chip architectures and advanced thermal management systems.
- Esports and live events:Broadcast studios and competitive gaming venues are expanding real-time data visualization budgets, displacing static signage with scalable LED arrays.
- Surface-mount device bonding:Advanced PCB assembly techniques are reducing pixel pitch thresholds below 1mm, enabling close-viewing indoor applications previously served by projection.
Market Restraints
- Phosphor and solder input costs:REACH and RoHS restrictions on hazardous substances are constraining supplier pools and raising qualified material costs for European-bound production.
- Shenzhen cluster dependency:Overreliance on a single manufacturing geography creates geopolitical and logistics vulnerability for global module supply.
- Driver electronics thermal limits:FCC Part 15 emissions standards constrain power density in US-market products, capping brightness performance relative to unregulated alternatives.
Strategic Opportunities
- Transparent LED architectural integration:Glass facade applications in commercial real estate present unobstructed sightline solutions competing with traditional curtain wall systems.
- Rental LED service models:Event production companies are prioritizing rapid-deployment frames and front-serviceable modules, creating recurring revenue streams beyond equipment sales.
- China GB standards alignment:MIIT energy consumption certifications favor locally certified manufacturers, creating domestic preference tailwinds for compliant suppliers.
Industry Challenges
- Pixel pitch engineering talent scarcity:Fine-pitch indoor design requires specialized thermal and signal-integrity expertise that outpaces current workforce development pipelines.
- Multi-jurisdiction certification timelines:Divergent FCC, CE marking, and GB standard testing protocols extend product launch cycles and fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Led Video Walls Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $58.4 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor LED, Outdoor LED, Rental LED, Transparent LED Technology: OLED, Mini LED, Micro LED, SMD End User: Advertising, Education, Entertainment, Corporate Installation: Wall-Mounted, Freestanding, Ceiling-Mounted, Custom |
| Companies Covered | Daktronics, Unilumin, Samsung Electronics, Liantronics, Absen, Leyard, Barco, Planar Systems, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Led Video Walls Market Strategic Shifts & Innovations
Active matrix driving architectures and miniaturized LED packaging are compressing the performance gap between indoor and outdoor display specifications. Regulatory divergence between efficiency frameworks is forcing modular product architectures that can be regionally configured without full redesigns.
Chip-on-board LED packaging is fragmenting the traditional discrete SMD module supply chain by integrating driver logic directly onto the substrate. Broadcast studios and high-end corporate installations are adopting these denser configurations for sub-1mm pitch requirements. The technology is fragmenting procurement patterns as buyers separate premium indoor specifications from commoditized outdoor standards.
REACH substance restrictions and evolving RoHS exemptions are reshaping phosphor chemistry and solder alloy selection for European market access. Manufacturers are reformulating coatings and joint materials to maintain luminance performance under tightened hazardous substance thresholds. Driver electronics suppliers serving EU-bound products face accelerated qualification cycles as ECHA reviews additional candidate list substances.
Event production companies are unbundling after-sales service from capital purchase contracts, favoring operational lease structures with bundled maintenance and rapid replacement guarantees. Rental LED fleet operators are consolidating around standardized frame geometries and hot-swappable module designs. This behavioral shift is most pronounced in North American and Western European live entertainment markets where utilization rates justify service-heavy commercial terms.
Led Video Walls Market Segmentation
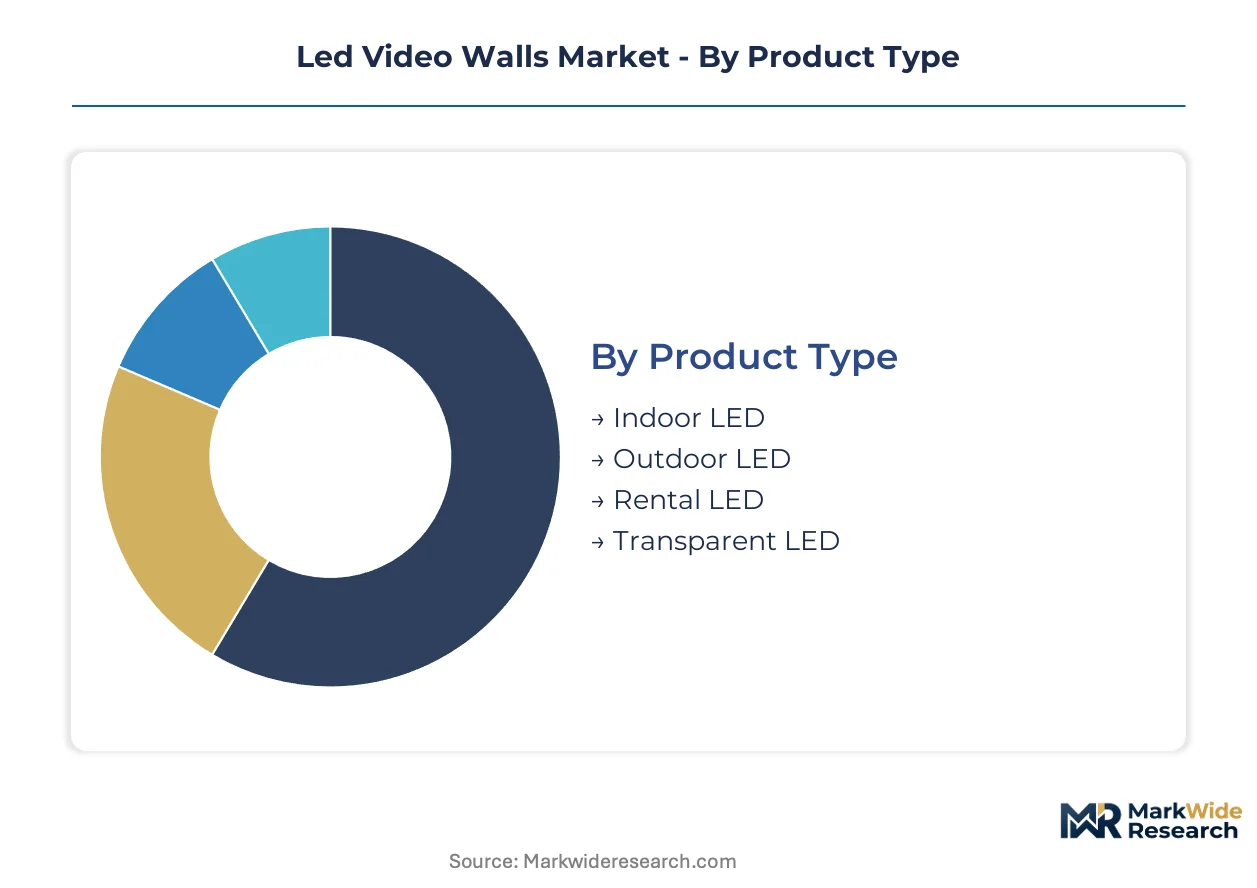
LED video wall procurement patterns diverge sharply across application environments, with pixel pitch requirements and thermal specifications driving fundamentally different product architectures. Understanding these segment boundaries clarifies why manufacturers maintain parallel development tracks rather than unified platforms.
Product Type:
Domestic demand in China absorbs the majority of outdoor and rental LED production from Shenzhen-based manufacturers, while indoor and transparent LED shipments skew toward export markets in Europe and North America.
- Indoor LED:Sub-2mm pixel pitch configurations dominate corporate boardroom and broadcast studio deployments. European buyers under EU Ecodesign Directive mandates prioritize lower-wattage chip architectures for these installations. Fine-pitch engineering talent scarcity constrains expansion of qualified supplier pools.
- Outdoor LED:Coarse pitch arrays from 6mm to 10mm serve stadium and highway billboard applications where viewing distances exceed 50 meters. Chinese domestic procurement absorbs the majority of volume, with MIIT GB standards creating preference for locally certified manufacturers. Weatherproofing requirements and thermal cycling durability differentiate competitive offerings.
- Rental LED:Rapid-deployment frames and front-serviceable modules dominate event production procurement in North America and Western Europe. Operational lease structures with bundled maintenance are displacing capital purchase contracts.
- Transparent LED:Glass facade integration competes with traditional curtain wall systems in commercial real estate developments across Germany, France, and the United Kingdom. Architectural specifications demand unobstructed sightlines with 70% transparency ratings.
Indoor LED commands the established base. The steepest expansion runs through rental LED.
Technology:
Cost tiers separate mature surface-mount device packaging from emerging micro-scale alternatives, with premium configurations commanding five-to-ten-fold price multiples over commodity options.
- OLED:Self-emissive organic compounds enable true black levels and infinite contrast ratios for high-end broadcast color grading suites. South Korean and Japanese display fabs control critical material supply chains.
- Mini LED:Chip-on-board architectures integrate driver logic directly onto substrates, fragmenting traditional discrete module supply chains. Sub-1mm pitch requirements in corporate flagship installations drive qualification cycles.
- Micro LED:Monolithic integration of microscopic emitters promises brightness and efficiency advantages for next-generation command centers. Mass transfer yield challenges limit commercial availability to pilot installations.
- SMD:Conventional surface-mount device bonding remains the workhorse for outdoor stadium and rental applications where cost sensitivity outweighs pitch compression. Shenzhen manufacturing clusters optimize throughput for this segment.
SMD retains volume leadership. Mini LED climbs the fastest as broadcast studios accelerate refresh cycles.
End User:
Customer type determines service model preferences, with advertising and entertainment buyers favoring operational leases while education and corporate procurement emphasizes capital ownership and extended warranties.
- Advertising:Digital out-of-home networks prioritize brightness uniformity and remote diagnostics for 24/7 roadside deployments. FCC Part 15 emissions standards constrain driver electronics for US-bound products.
- Education:K-12 and university installations balance upfront cost against 10-year replacement horizons. E-rate funding eligibility shapes procurement specifications for US public institutions.
- Entertainment:Esports arenas and live event venues demand sub-3ms latency for real-time data visualization. Front-serviceable modules minimize downtime during tournament schedules.
- Corporate:Enterprise command centers and executive briefing facilities drive fine-pitch indoor specifications below 1.5mm. REACH and RoHS restrictions constrain qualified supplier pools for European deployments.
Advertising commands the installed base. Entertainment gains share fastest as esports venue construction accelerates.
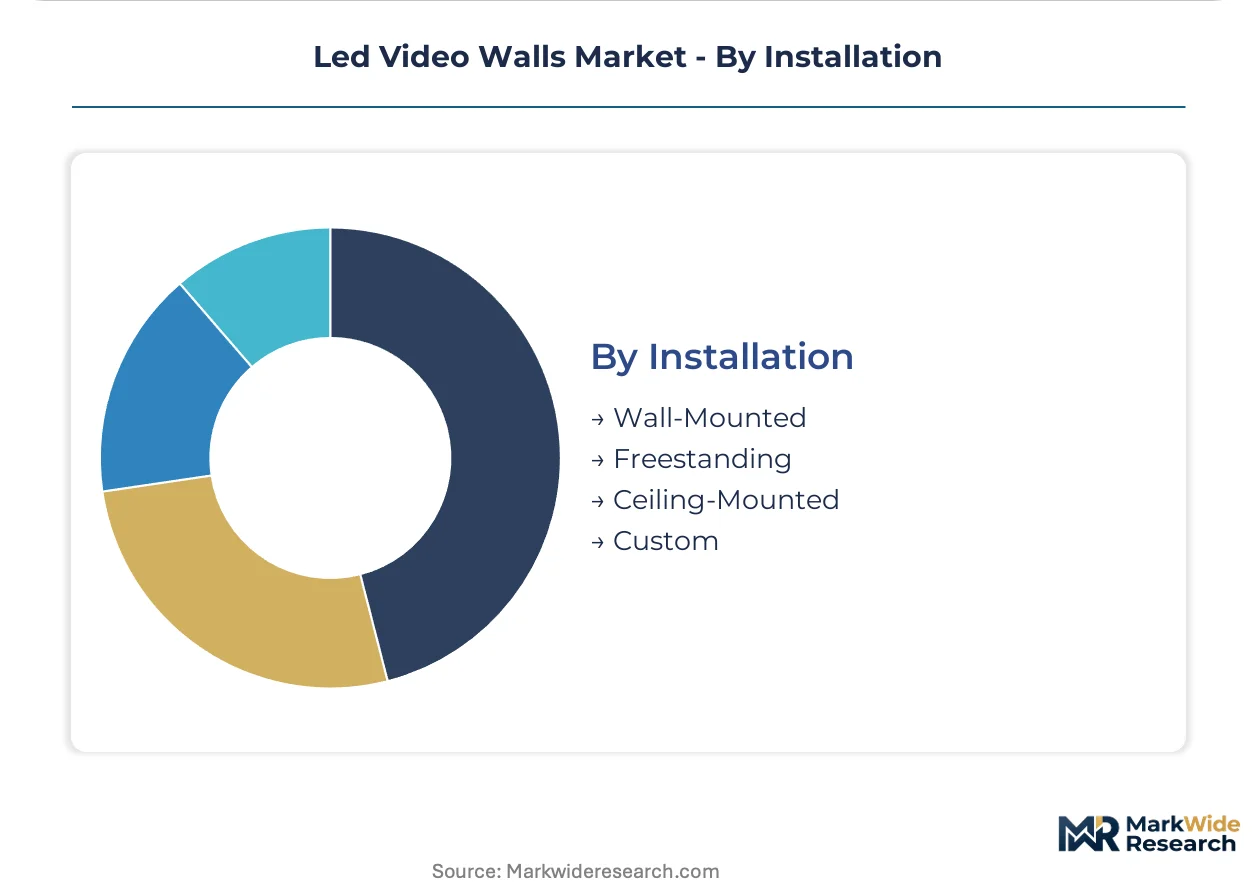
Installation:
Mounting geometry influences module selection, with wall-mounted and freestanding configurations representing volume categories while ceiling and custom installations capture premium margins through engineering services.
- Wall-Mounted:Permanent installations dominate corporate lobby and retail flagship applications. Structural load calculations and thermal management integration require project-specific engineering.
- Freestanding:Self-supporting structures serve temporary exhibitions and tradeshow environments where lease terms preclude building modifications. Standardized frame geometries enable rapid reconfiguration.
- Ceiling-Mounted:Suspended arrays in broadcast studios and control rooms demand redundant rigging and front-service access for maintenance safety.
- Custom:Curved, cylindrical, and irregular geometries command engineering premiums for architectural integration projects. Glass facade transparent LED deployments typically require custom structural adaptation.
Wall-mounted retains volume dominance. Custom installations expand most quickly as architectural LED integration proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's display manufacturing cluster exports the majority of global LED module capacity to European broadcast studios and North American esports venues. Trade corridors connect Chinese production bases with German architectural integrators and US rental fleet operators. Regional regulatory divergence shapes procurement qualification protocols.
United States
Esports arena construction and broadcast studio modernization drive procurement of sub-2mm fine-pitch installations. FCC Part 15 emissions standards constrain driver electronics power density for domestically deployed products. Daktronics leverages its South Dakota engineering base to supply sports venue and training facility installations across the Midwest and Southeast.
Germany
Commercial real estate developers integrate transparent LED into glass facades for flagship retail and corporate headquarters projects. EU Ecodesign Directive mandates accelerate manufacturer migration toward lower-wattage chip architectures. Munich and Frankfurt architectural practices specify 70% transparency ratings for curtain wall competitions.
China
Domestic demand absorbs the majority of outdoor and rental LED production from Shenzhen-based manufacturers. MIIT GB standards for electronic display energy consumption create preference for locally certified suppliers. The Pearl River Delta manufacturing cluster optimizes throughput for surface-mount device bonding at sub-1mm pitch thresholds.
United Kingdom
London broadcast studios and corporate command centers displace legacy projection with real-time data visualization arrays. REACH and RoHS restrictions on hazardous substances constrain qualified supplier pools for European-bound production. Post-production facilities in Soho and White City drive premium-tier indoor specifications.
Japan
High-end broadcast color grading suites demand self-emissive display technologies for infinite contrast ratios. METI efficiency guidelines shape domestic procurement specifications for command center installations. Tokyo and Osaka display fabs control critical material supply chains for organic compound substrates.
Led Video Walls Market Key Industry Players
Player mix skews toward integrated display manufacturers with captive semiconductor packaging capabilities and specialized rental fleet operators with rapid-deployment service models. Market structure concentrates around three strategic archetypes: Shenzhen-based volume producers optimizing module cost, South Korean and Japanese semiconductor specialists controlling premium chip architectures, and Western systems integrators bundling installation engineering with hardware procurement. Dominant competitive moves include backward integration into driver IC design and geographic expansion through regional certification partnerships.
Among Shenzhen-based volume producers, Unilumin and Liantronics exemplify the manufacturing cluster's cost-optimization archetype. Samsung Electronics occupies a position within the semiconductor-specialist tier, leveraging proprietary packaging expertise for thermal management in fine-pitch configurations. Daktronics represents the Western systems integrator model, extending from sports venue dominance into adjacent esports and training facility verticals.
| Leading Market Players |
|---|
| Daktronics |
| Unilumin |
| Samsung Electronics |
| Liantronics |
| Absen |
| Leyard |
| Barco |
| Planar Systems |
| LG Electronics |
| Others |
Cost & Logistics Intelligence
EU Ecodesign Directive energy efficiency mandates simultaneously gate supplier qualification and stratify price tiers by certification burden, compressing margins for non-compliant manufacturers while rewarding lower-wattage chip architectures with premium positioning. Shenzhen's manufacturing cluster concentration amplifies this dynamic, as GB standards alignment creates domestic procurement preference that feeds back into export pricing power.
Pricing Analysis
Technology-generation pricing gaps separate commodity SMD outdoor installations from premium Mini LED sub-1mm configurations, with five-to-ten-fold multiples between legacy and emerging chip-on-board architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal management sophistication, with European-bound products commanding tier premiums due to REACH compliance costs. Cost compression in outdoor stadium segments intensifies as Shenzhen volume producers optimize throughput, while broadcast studios exhibit lowest price sensitivity for fine-pitch indoor specifications.
Supply Chain Analysis
Inventory lead times for driver ICs and phosphor coatings extend qualification cycles for European-bound production, constraining rapid response to demand spikes. Supply concentrates in China, South Korea, and Japan, with Shenzhen module assembly feeding from Taiwanese semiconductor foundries and Japanese phosphor suppliers. Raw material dependencies span gallium nitride substrates, rare-earth phosphors, and RoHS-compliant solder alloys. Single-source vulnerability around Mini LED mass transfer equipment fragments procurement timelines. Distribution runs through systems integrators in Germany and the United States, with rental fleet operators in North America bypassing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fine-pitch thermal engineering and signal-integrity expertise outpaces workforce development pipelines, creating sustained scarcity premiums for qualified suppliers across corporate and broadcast verticals.
For Market Incumbents: Consolidate backward integration into driver IC design to escape commodity margin compression in outdoor stadium segments, while deepening certification partnerships for EU Ecodesign Directive compliance to defend positioning against emerging chip-on-board specialists. Capacity addition in Southeast Asian assembly locations mitigates Shenzhen cluster dependency risks. For New Entrants and Emerging Players: After-sales service unbundling from capital contracts presents white-space opportunity in North American rental LED markets, where event production companies prioritize operational lease structures with rapid replacement guarantees. Front-serviceable module design expertise offers the most penetrable entry point against established Shenzhen volume producers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Mini LED micro-scale packaging lines, favoring acquisition targets with captive semiconductor bonding capabilities and existing FCC Part 15 qualification portfolios. Monitor divergence between regional efficiency certifications as the inflection signal for component sourcing reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | Captive semiconductor logic reduces thermal constraints and accelerates FCC Part 15 compliance cycles. |
| Regional Certification Partnership Expansion | EU Ecodesign and MIIT GB alignment unlocks procurement preference in parallel regulatory regimes. |
| Front-Serviceable Module Platform Standardization | Rapid-deployment frames capture recurring revenue from North American event production operators. |
| Phosphor Chemistry Reformulation Investment | REACH-compliant coatings maintain luminance performance under tightening ECHA substance thresholds. |
| Transparent LED Architectural Integration Capability | Glass facade specifications in German commercial real estate command engineering service premiums. |
Research Approach
A spread of perspectives from display manufacturing executives, broadcast studio technical directors, rental fleet procurement managers, and architectural specification consultants converged on the working assumptions. Primary fieldwork combined with secondary validation from MIIT GB standard filings, FCC equipment authorization databases, EU Ecodesign implementing measure texts, and Shenzhen customs export records. Bottom-up module shipment aggregation triangulated against top-down display systems revenue estimates.
Segmentation dimensions modeled span pixel pitch tier, installation environment, technology packaging architecture, end-user vertical, and regional regulatory cluster across the projection horizon. CAGRs derived from fitted growth curves incorporating replacement cycle compression in legacy projection displacement and esports venue construction acceleration. Forecast inputs include Shenzhen manufacturing capacity utilization rates and phosphor coating material cost trajectories under REACH substance review timelines.
Forecasts assume regulatory continuity in EU Ecodesign, FCC Part 15, and MIIT GB regimes; material policy shifts would require re-modeling. Specific risk factors include geopolitical disruption to Taiwan semiconductor foundry access and ECHA candidate list expansion affecting solder alloy availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Driver Market
LED
Biometrics Infrared LED Market
LED
LED Modular Display Market
LED
LED Display Control Card Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
LED Lighting Solution Market
LED
Architectural LED Products Market
LED
7 Segment LED Displays Market
LED
Vietnam LED Lighting Market
LED
Middle East LED Lighting Market
LED
Xenon Market
LED
China LED Lighting Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Outdoor LED Display Market
LED
LED Panel Light Drivers Market
LED
Infrared (IR) LED Market