
 Latin America Hypodermic Syringes and Needles Market | 2026-2036
Latin America Hypodermic Syringes and Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Hypodermic Syringes and Needles Market Intelligence
Home care providers are reorganizing procurement priorities across Latin America, shifting volume toward safety-engineered and pre-filled formats that reduce clinician handling steps. Becton Dickinson leverages its regional distribution infrastructure to sustain contract renewals with Brazilian federal health networks. B. Braun Melsungen AG anchors its position through specialized safety syringe manufacturing capabilities serving Mexican public hospitals. Terumo Corporation competes on cost-optimized conventional syringe lines that dominate tender-based purchasing in Argentina and Colombia.
Hypodermic syringes and needles consist of cylindrical barrels manufactured from medical-grade polypropylene or borosilicate glass, paired with stainless steel cannulas ground to precise bevel angles for minimally traumatic tissue penetration; these devices deliver parenteral medications, extract biological specimens, and administer vaccines under aseptic conditions. Safety syringes command premium positioning due to retractable needle mechanisms that satisfy occupational safety mandates, while insulin syringes occupy a dedicated growth corridor driven by expanding diabetes care protocols across the region. Conventional syringes retain volume leadership in price-sensitive public tenders, though margin pools concentrate in pre-filled formats where pharmaceutical companies seek integrated delivery partnerships.
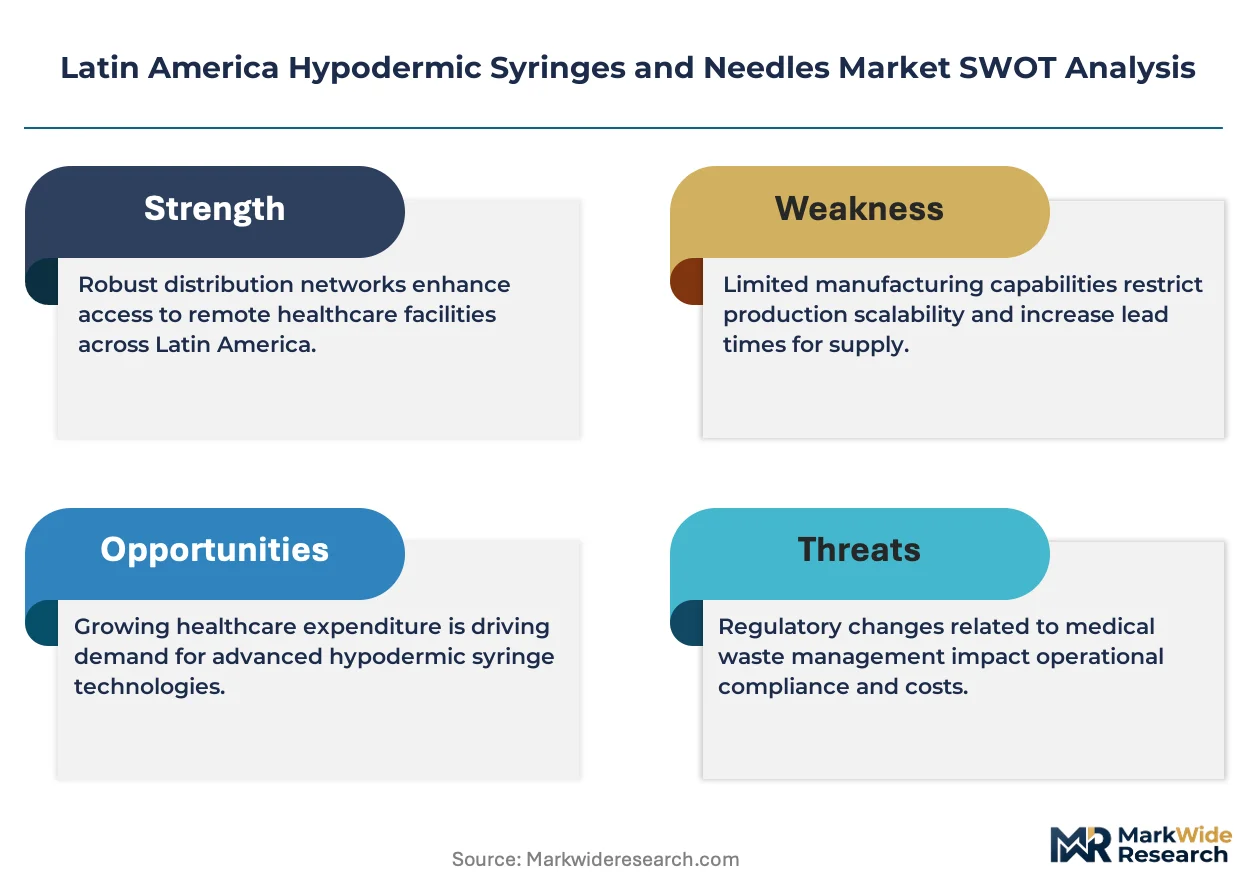
ANVISA in Brazil enforces medical device vigilance reporting for needlestick incidents, while COFEPRIS in Mexico classifies safety syringes under higher-risk registration tiers that extend approval timelines but elevate barrier to entry. ISO 7864 and ISO 9626 standards govern cannula dimensions and material specifications, directly influencing manufacturer qualification for regional hospital tenders. Stakeholders must monitor evolving national health technology assessments that increasingly weight total cost of needlestick prevention against acquisition price in multi-year procurement decisions.
Market Dynamics
ANVISA's needlestick injury reporting mandates and COFEPRIS's elevated safety-device registration tiers are compressing approval timelines while redirecting procurement budgets toward retractable-needle formats across Brazilian and Mexican hospital networks.
Growth Catalysts
- ANVISA Vigilance Mandates:Brazil's medical device regulator requires systematic reporting of occupational needlestick incidents, compelling state hospital networks to prioritize safety-engineered syringes in multi-year tenders.
- Diabetes Protocol Expansion:Public health institutes across Mexico are integrating insulin syringe distribution into primary care pathways, creating dedicated procurement corridors for ultra-fine cannula formats.
- Pre-filled Partnership Models:Pharmaceutical manufacturers are seeking integrated delivery alliances that bundle drug and device, locking in volume commitments from regional vaccine programs.
Market Restraints
- Medical-Grade Polypropylene Cost Volatility:Resin feedstock fluctuations squeeze margins on conventional syringe lines that dominate price-sensitive Argentine and Colombian tenders.
- COFEPRIS Tiered Registration Friction:Mexico's classification of safety syringes under higher-risk categories extends approval timelines by 8-14 months, elevating capital requirements for market entry.
- Conventional Format Lock-in:Legacy tender specifications in several Latin American markets still prioritize unit cost over total cost of needlestick prevention, slowing safety-device conversion.
Strategic Opportunities
- Colombian Regional Hospital Networks:Decentralized procurement in secondary cities remains underpenetrated by safety-engineered suppliers, offering first-mover positioning ahead of regulatory harmonization.
- Home Care Channel Expansion:Direct-to-patient distribution models for insulin and biologic delivery are bypassing traditional hospital procurement, creating new margin pools for specialized formats.
- ISO 80369-7 Convergence:The small-bore connector standard for enteral and neuraxial applications is opening adjacent device categories for manufacturers with existing Luer-lock expertise.
Industry Challenges
- Retractable Mechanism Engineering Talent:The specialized skill set for safety-spring design and polymer fatigue testing remains concentrated among a limited pool of device engineers, constraining R&D velocity.
- Multi-Jurisdictional Certification Burden:Manufacturers serving both ANVISA and COFEPRIS markets face divergent biocompatibility testing protocols, duplicating validation costs without mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Hypodermic Syringes and Needles Market |
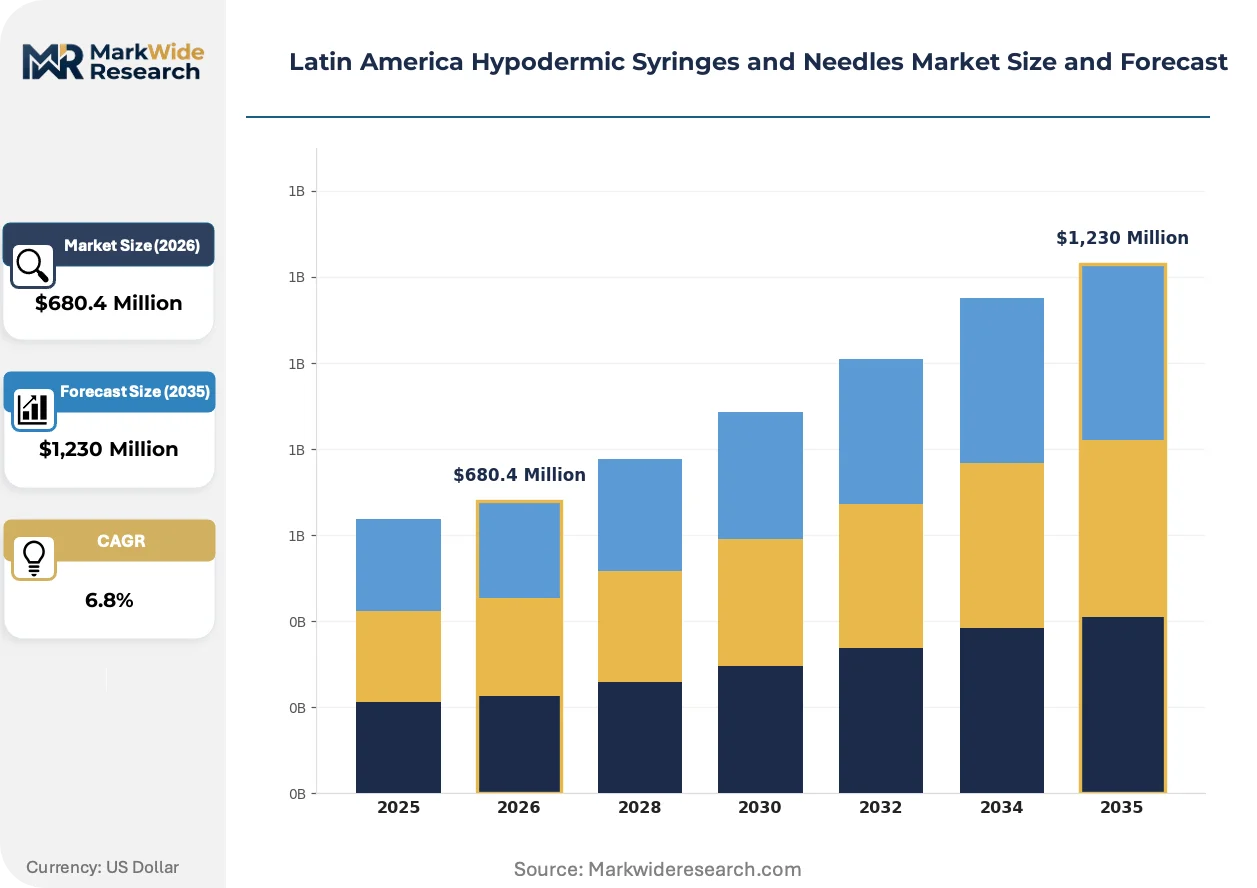
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $1,230 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Syringes, Conventional Syringes, Pre-filled Syringes, Insulin Syringes End User: Hospitals, Clinics, Home Care, Pharmaceutical Companies Material: Plastic, Glass, Rubber, Stainless Steel Application: Immunization, Pain Management, Diabetes Care, Blood Sampling |
| Companies Covered | Becton Dickinson, B. Braun Melsungen AG, Terumo Corporation, Nipro Corporation, Cardinal Health, Smiths Medical, Medline Industries, Retractable Technologies, Vitrex Medical A/S, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Hypodermic Syringes and Needles Market Strategic Shifts & Innovations
Device architectures are fragmenting across distinct performance tiers as regulators and end-users impose divergent requirements on the same underlying delivery platform.
Retractable needle systems are bifurcating the safety-syringe category into premium spring-loaded formats for Brazilian federal networks and cost-optimized passive-sheath designs for Colombian state tenders. Hospital procurement committees in Mexico City and São Paulo are piloting the premium tier, while secondary markets delay conversion pending budget cycles. This technological split is compressing mid-tier positioning and forcing manufacturers to commit to single-architecture specialization.
COFEPRIS has introduced mandatory human-factors documentation for safety-device submissions, requiring manufacturers to demonstrate clinician activation success rates under simulated stress conditions. This regulatory evolution is disqualifying legacy designs that lack ergonomic validation data. Mexican public health institutes are now embedding these requirements into technical specifications, effectively filtering tender participation to suppliers with dedicated usability engineering capabilities.
Home care providers are consolidating purchasing through specialized distributors that bundle device training with product supply, displacing traditional wholesale channels. This channel restructuring concentrates volume among logistics platforms with clinical education infrastructure. The shift is most visible in Brazilian diabetes management programs, where state contracts now specify distributor accreditation requirements alongside product specifications.
Latin America Hypodermic Syringes and Needles Market Segmentation
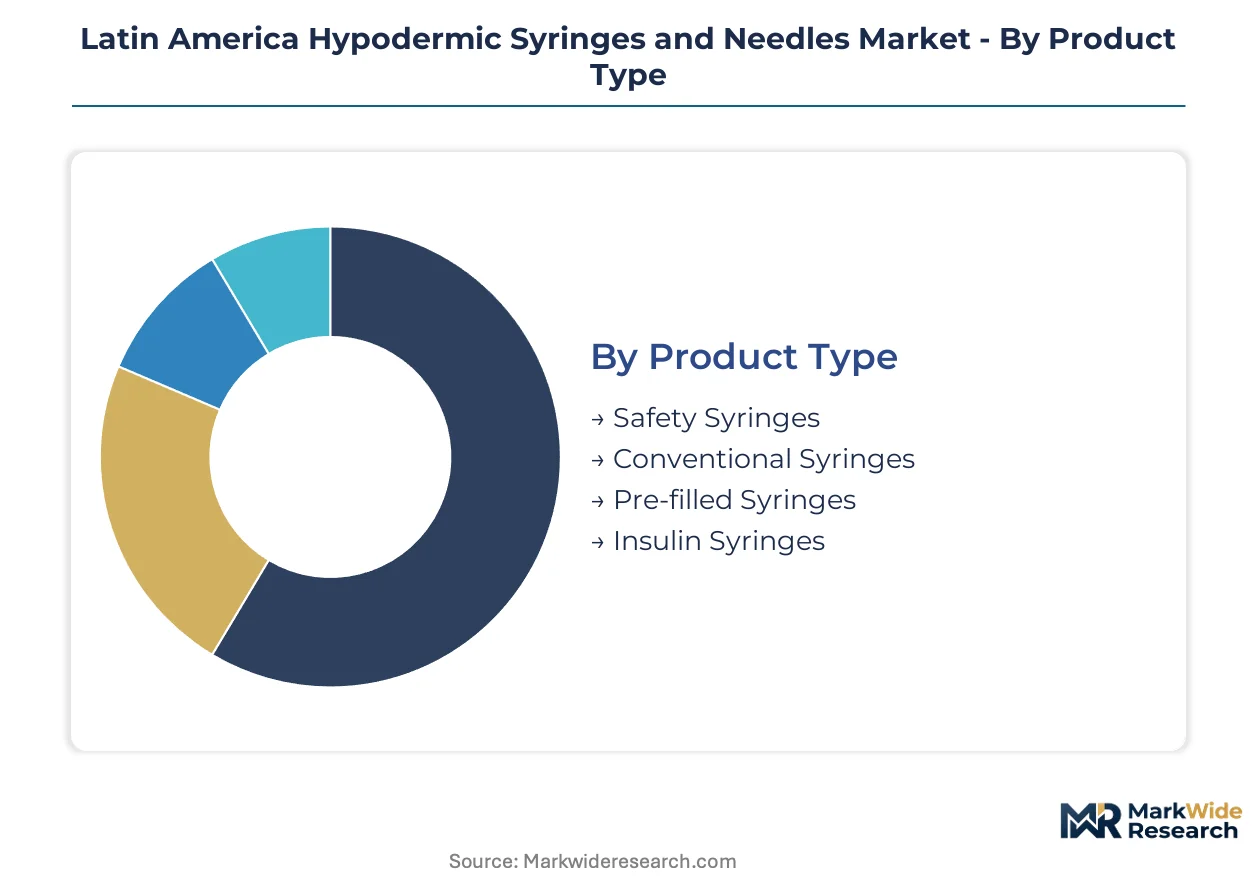
Segmentation in Latin America reflects divergent regulatory pressures across ANVISA and COFEPRIS jurisdictions, with procurement specifications increasingly dictating product selection rather than clinician preference alone. Manufacturers must align portfolio architecture to distinct approval tiers, tender formats, and end-user capabilities spanning Brazilian federal networks to Colombian decentralized purchasing.
Product Type:
ANVISA's needlestick injury reporting mandates and COFEPRIS's elevated risk-classification for safety devices create a bifurcated approval landscape where retractable mechanisms command premium positioning against conventional alternatives.
- Safety Syringes:Spring-loaded or passive-sheath designs with integrated needlestick prevention mechanisms satisfy Brazilian federal hospital network requirements. São Paulo state procurement committees now mandate retractable formats in multi-year tenders, though Colombian secondary cities lag in budget allocation for conversion.
- Conventional Syringes:Standard Luer-lock polypropylene barrels with detachable stainless steel cannulas dominate Argentine and Colombian price-sensitive tenders where unit cost outweighs total cost of prevention calculations. These formats retain volume leadership in legacy public health contracts.
- Pre-filled Syringes:Pharmaceutical-integrated delivery systems combining drug and device in sterile, ready-to-administer formats.
- Insulin Syringes:Ultra-fine 31-gauge cannulas with unit-dose calibration for diabetes management protocols.
Established volume favors Conventional Syringes; emerging adoption favors Safety Syringes.
End User:
Procurement authority concentration varies sharply across the region, with Brazilian state purchasing consortia wielding contract-scale leverage unavailable to fragmented Colombian clinic networks.
- Hospitals:Brazilian SUS-affiliated institutions and Mexican IMSS facilities drive safety-device conversion through centralized tender specifications. ANVISA vigilance reporting requirements filter supplier participation to manufacturers with dedicated Brazilian regulatory affairs capabilities.
- Home Care:Direct-to-patient distribution for insulin and biologic delivery is bypassing traditional wholesale channels in Brazil's state diabetes programs. Distributor accreditation requirements now accompany product specifications in Minas Gerais and Rio Grande do Sul contracts.
- Clinics:Private diagnostic chains and outpatient surgical centers with mixed procurement autonomy.
- Pharmaceutical Companies:Vaccine and biologic manufacturers seeking integrated delivery partnerships.
Hospital procurement concentrates contract value; Home Care channels are climbing the fastest in margin contribution.
Material:
Feedstock cost volatility and sterilization compatibility requirements shape material selection across distinct performance tiers.
- Plastic:Medical-grade polypropylene barrels dominate disposable syringe production, though resin price fluctuations squeeze margins on conventional lines serving Argentine tenders. Gamma-irradiation stability distinguishes qualified suppliers from commodity converters.
- Stainless Steel:304-grade cannulas with precision-ground bevel angles for minimally traumatic penetration. Mexican public hospitals specify ISO 9626-compliant dimensions in technical requirements, elevating barrier to entry for unqualified manufacturers.
- Glass:Borosilicate barrels for heat-stable pharmaceutical applications and pre-filled formats.
- Rubber:Chlorobutyl or bromobutyl plunger stoppers for seal integrity and drug compatibility.
Plastic retains cost-driven volume dominance; Stainless Steel specifications are expanding most quickly in safety-device qualification requirements.
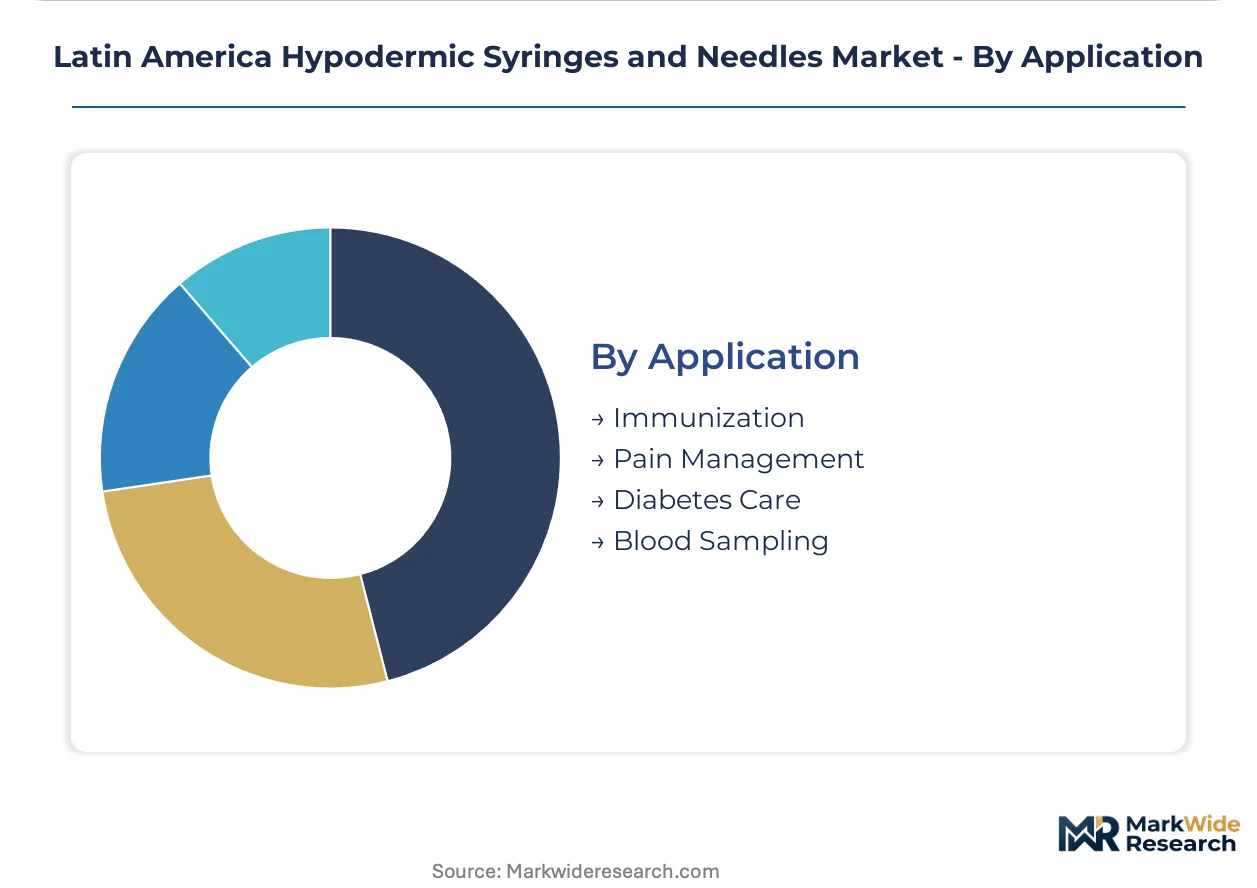
Application:
Protocol standardization across national immunization programs and diabetes management initiatives is creating dedicated procurement corridors with distinct device specifications.
- Diabetes Care:Insulin delivery protocols in Mexican public health institutes and Brazilian state programs are integrating ultra-fine syringe distribution into primary care pathways. COFEPRIS registration requirements for home-use devices incorporate human-factors documentation that disqualifies legacy designs.
- Immunization:Mass vaccination campaigns and routine pediatric schedules drive high-volume, low-margin procurement. Brazilian federal purchases specify auto-disable formats for certain vaccine categories, though conventional syringes persist in routine adult immunization.
- Pain Management:Neuraxial and parenteral analgesic delivery in hospital settings.
- Blood Sampling:Diagnostic specimen collection with vacuum tube compatibility requirements.
Immunization anchors procurement volume; Diabetes Care is gaining share fastest in specialized format development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminal underwrites Brazil's dominance in medical device import logistics, handling the bulk of polypropylene resin and finished syringe shipments that feed São Paulo's manufacturing corridor.
Brazil
ANVISA's needlestick injury reporting mandates compel state hospital networks to prioritize safety-engineered syringes in multi-year tenders. São Paulo state procurement committees now mandate retractable formats, while Minas Gerais and Rio Grande do Sul contracts specify distributor accreditation requirements alongside product specifications.
Mexico
COFEPRIS classifies safety syringes under higher-risk registration tiers that extend approval timelines by 8-14 months. Mexico City and Monterrey hospital procurement committees pilot premium spring-loaded formats, while the Bajío Region's pharmaceutical manufacturing clusters drive pre-filled syringe partnership demand.
Argentina
Price-sensitive public tenders dominate procurement, with conventional syringes retaining volume leadership. Buenos Aires province hospital networks balance budget constraints against emerging occupational safety guidelines, while Córdoba's decentralized purchasing maintains legacy unit-cost prioritization.
Colombia
Decentralized procurement in secondary cities remains underpenetrated by safety-engineered suppliers. Bogotá's central hospital networks lag São Paulo and Mexico City in safety-device conversion, creating first-mover positioning opportunities ahead of anticipated regulatory harmonization.
Chile
Santiago's public health institutes integrate diabetes care protocols into primary care pathways, generating demand for ultra-fine insulin syringes. The country's medical device regulator enforces ISO 7864 compliance in technical specifications, elevating qualification barriers for unqualified manufacturers.
Latin America Hypodermic Syringes and Needles Market Key Industry Players
Listed leaders compete with private specialists across regulatory affairs capabilities and distribution infrastructure. The market exhibits consolidated tiering among multinational device manufacturers with dedicated Latin American regulatory teams, while mid-scale specialists concentrate on cost-optimized conventional lines for price-sensitive tenders. Three archetypes dominate: integrated safety-device specialists with retractable mechanism expertise, volume-scale conventional syringe suppliers, and pharmaceutical-integrated pre-filled format partners. Capacity expansion and strategic distributor partnerships constitute the dominant competitive moves.
Within the integrated safety-device tier, Becton Dickinson and B. Braun Melsungen AG exemplify multinational positioning through regional distribution infrastructure and specialized manufacturing capabilities respectively. Terumo Corporation occupies a position among volume-scale suppliers competing on cost-optimized conventional lines. These three anchors represent divergent strategic commitments: federal network contract renewal through regulatory depth, public hospital manufacturing specialization, and tender-based cost leadership.
| Leading Market Players |
|---|
| Becton Dickinson |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Nipro Corporation |
| Cardinal Health |
| Smiths Medical |
| Medline Industries |
| Retractable Technologies |
| Vitrex Medical A/S |
| Others |
Cost & Logistics Intelligence
Multi-year tender contracts with Brazilian federal health networks lock in supply access for safety-engineered syringes while providing price visibility against volatile medical-grade polypropylene feedstock costs. These contractual structures concentrate procurement leverage within state purchasing consortia, compressing margin pools for manufacturers serving price-sensitive Argentine and Colombian markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates retractable safety syringes from conventional Luer-lock formats and commodity insulin lines. Premium tier pricing draws from ANVISA-mandated needlestick prevention compliance in São Paulo state tenders, while economy tiers serve Colombian decentralized purchasing where unit cost dominates total cost calculations. Cost compression in conventional polypropylene lines intensifies because resin price volatility squeezes converter margins without corresponding tender price adjustments. Argentine public health institutes exhibit highest price sensitivity; Brazilian SUS-affiliated networks demonstrate lowest sensitivity due to federal safety-device mandates.
Supply Chain Analysis
Safety-spring inventory cycles and extended COFEPRIS approval lead times strain working capital for manufacturers qualifying retractable mechanisms under Mexican higher-risk registration tiers. Finished device production concentrates in Brazil, Mexico, and Costa Rica, drawing from Chinese and South Korean medical-grade polypropylene resin suppliers. Single-source vulnerability sits with precision cannula grinding equipment anchored in German and Japanese manufacturing bases. Distribution runs through specialized hospital supply distributors in São Paulo and Mexico City, bypassing traditional wholesale channels for home care insulin delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's hypodermic syringe market represents an early-cycle expansion story as ANVISA and COFEPRIS needlestick prevention mandates accelerate safety-device conversion ahead of full regional regulatory harmonization. Penetration gaps in Colombian secondary cities and Argentine decentralized procurement create runway for specialized suppliers.
For Market Incumbents: Secure multi-year contract renewals with Brazilian state hospital networks by embedding distributor accreditation requirements into technical specifications, blocking emerging entrants from qualification. Backward integration into medical-grade polypropylene compounding mitigates resin cost volatility threatening conventional syringe margins in Argentine tenders. Prioritize ISO 80369-7 small-bore connector certification to capture adjacent enteral and neuraxial device categories. For New Entrants and Emerging Players: Regulatory affairs service-layer gaps in Colombian decentralized procurement present first-mover positioning ahead of anticipated safety-device harmonization. Target secondary city hospital networks in Medellín and Cali with cost-optimized passive-sheath designs that bridge conventional pricing with basic needlestick prevention. Partner with Brazilian state diabetes program distributors to bypass São Paulo procurement concentration. For Investors and Strategic Acquirers: Capital is best deployed toward retractable mechanism engineering specialists with dedicated polymer fatigue testing capabilities and existing ANVISA regulatory dossiers. Long-term viability across the projection horizon rests on manufacturers qualifying under both Brazilian vigilance mandates and Mexican human-factors documentation requirements. Watch COFEPRIS mutual recognition negotiations with Chilean and Colombian regulators as inflection signal for regional approval timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Safety-Device Registration Pathway | Accelerates federal hospital network qualification ahead of state-level mandate expansion. |
| COFEPRIS Human-Factors Documentation Investment | Elevates barrier to entry for legacy designs lacking ergonomic validation data. |
| Brazilian Distributor Accreditation Partnership | Locks in Minas Gerais and Rio Grande do Sul state diabetes program volume. |
| Medical-Grade Polypropylene Backward Integration | Captures resin margin and insulates against Argentine tender price compression. |
| ISO 80369-7 Small-Bore Connector Certification | Opens adjacent enteral and neuraxial categories for Luer-lock expertise extension. |
Research Approach
Operator-level perspectives from hospital procurement managers, biomedical engineers, GPO contracts specialists, and home care distributor operations heads anchored the qualitative base for this study. Primary interview insights combined with secondary validation from ANVISA vigilance incident databases, COFEPRIS medical device registration filings, Brazilian SUS procurement bulletins, and ISO standard revision documentation. Bottom-up tender volume aggregation and top-down manufacturer capacity assessment provided cross-verification across the analysis window.
Sensitivity analysis around resin price volatility scenarios and regulatory approval timeline variations shaped the analytical framework. Segmentation dimensions modeled include product type, end-user procurement authority concentration, material sterilization compatibility, and application protocol standardization. CAGRs derived from installed base replacement cycles, safety-device conversion penetration curves, and pharmaceutical partnership formation rates.
Underlying assumptions cover ANVISA mandate enforcement consistency and COFEPRIS registration tier stability, with deviation risk concentrated in Argentine fiscal constraints delaying occupational safety guideline adoption and Colombian regulatory harmonization timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Medical Gloves Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Medical Shoe Covers Market