
 Medical Shoe Covers Market | 2026-2036
Medical Shoe Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Shoe Covers Market Foresight
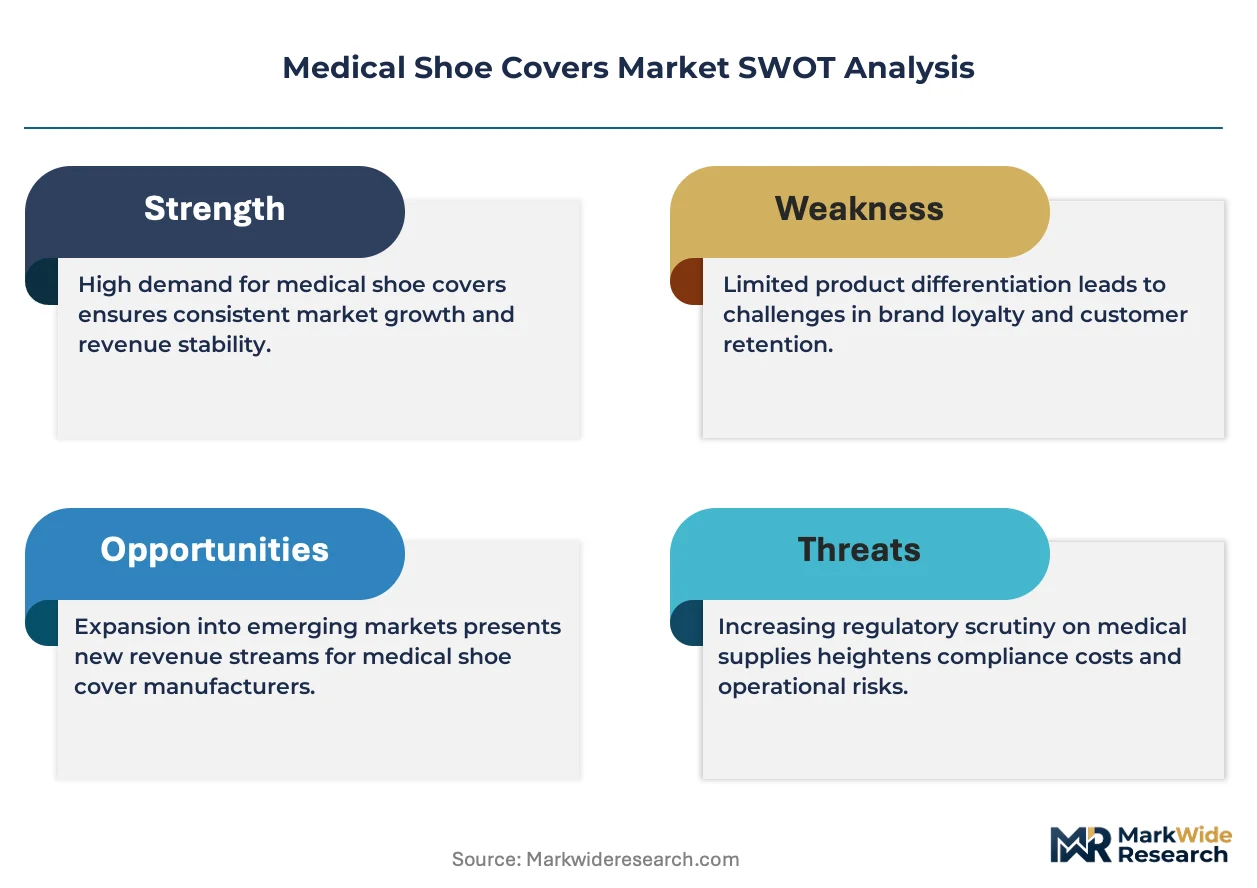
The EU Medical Device Regulation is decoupling low-grade imports from compliant supply chains across European healthcare procurement. Kimberly-Clark Corporation leverages its non-woven manufacturing scale to sustain contract positions with major hospital networks. Cardinal Health anchors its distribution through direct sales channels that span integrated delivery networks in North America. Medline Industries differentiates via vertical control over polypropylene sourcing and converted product output.
Medical shoe covers are disposable or reusable protective garments worn over footwear to maintain sterile environments and prevent cross-contamination in healthcare and laboratory settings; polypropylene spunbond meltblown composites deliver particulate filtration with breathability, while chlorinated polyethylene formulations provide fluid resistance for wet procedure areas. The disposable segment dominates volume due to single-use mandates in operating theaters, though biodegradable alternatives are gaining traction as procurement teams evaluate life-cycle environmental impact alongside unit cost. Hospitals represent the largest end-user category, with demand amplified by Joint Commission accreditation requirements and expansion of ambulatory surgical centers.
FDA 510(k) clearance pathways govern barrier claim substantiation for medical shoe covers distributed in the United States, while the EU MDR requires notified body certification for products claiming microbial protection. OSHA bloodborne pathogen standards and CDC isolation precaution guidelines further institutionalize purchase requirements across American acute care facilities. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union reshape material specifications and end-of-life obligations for single-use protective apparel.
Market Dynamics
The EU Medical Device Regulation is decoupling low-grade imports from compliant supply chains across European healthcare procurement. This regulatory tightening forces converters to revalidate barrier performance claims and resubmit technical documentation under stricter notified body oversight.
Growth Catalysts
- Joint Commission accreditation mandates:US hospital systems must maintain sterile corridors and operating theaters, institutionalizing bulk purchasing of disposable shoe covers through group purchasing organizations.
- Polypropylene spunbond meltblown composites:These materials deliver particulate filtration with breathability, enabling extended wear duration in cleanroom environments without moisture buildup.
- Germany:Expansion of ambulatory surgical centers and biosafety laboratories drives consistent demand for fluid-resistant protective footwear.
Market Restraints
- Petrochemical input volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing converter margins on fixed-price hospital contracts.
- Single-use plastic directives:Extended producer responsibility frameworks in the European Union impose end-of-life collection obligations on manufacturers and distributors.
- Reusable silicone boot covers:These alternatives threaten volume in pharmaceutical cleanrooms where laundering infrastructure exists.
Strategic Opportunities
- Biodegradable PLA formulations:Polylactic acid variants decompose in industrial composting facilities, addressing procurement teams' life-cycle environmental impact evaluations.
- China:Provincial hospital tier upgrades and biosafety level-3 laboratory construction create demand for imported barrier-certified products.
- Direct e-commerce channels:Smaller dental clinics and veterinary practices bypass traditional distribution, purchasing through specialized medical supply platforms.
Industry Challenges
- FDA 510(k) clearance timelines:Barrier claim substantiation requires fluid resistance testing and biocompatibility documentation, delaying product launches by 12-18 months.
- Polypropylene supply concentration:Converter reliance on Asian resin suppliers exposes production schedules to shipping disruptions and customs delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Shoe Covers Market |
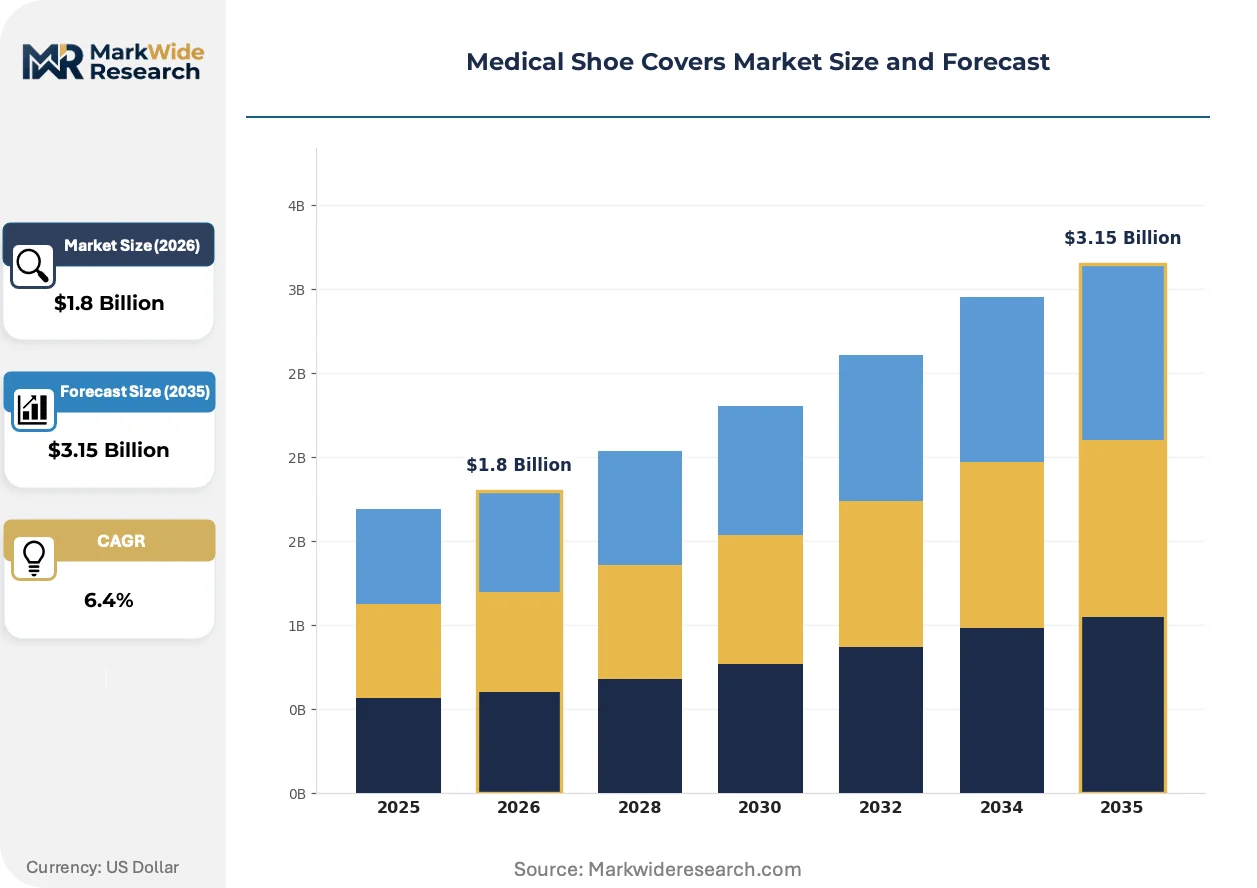
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Waterproof Material: Polypropylene, CPE, PVC, Non-woven End User: Hospitals, Laboratories, Clinics, Research Facilities Distribution Channel: Online, Retail, Direct Sales, Medical Supply Stores |
| Companies Covered | 3M Company, Kimberly-Clark Corporation, Cardinal Health, Medline Industries, DuPont de Nemours, Alpha Pro Tech, Dynarex Corporation, Molnlycke Health Care AB, Ansell Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Shoe Covers Market Shifts & Advancements
Material science advances and procurement digitization are compressing product lifecycles while elevating performance benchmarks. Three converging developments reshape competitive positioning.
Chlorinated polyethylene formulations are overtaking standard polypropylene in wet procedure areas. These materials provide superior fluid resistance during orthopedic and trauma surgeries. Operating theater managers in Germany and the United States specify CPE for high-splash procedures. The technology is overtaking commodity spunbond in premium contract tiers, compressing price premiums for basic polypropylene alternatives.
REACH chemical substance restrictions are tightening phthalate and heavy metal limits in plasticized footwear barriers. The European Chemicals Agency evaluates new candidate substances annually, forcing compound reformulation. Manufacturers serving EU hospital networks must maintain dual formulation portfolios or abandon the European market entirely.
Hospital group purchasing organizations now bundle shoe covers with broader personal protective equipment categories. This consolidation reduces supplier count from dozens to preferred panels of three to five converters. The shift is most visible in integrated delivery networks across the United States, where standardization committees mandate single-source contracts for infection control apparel.
Medical Shoe Covers Market Segmentation
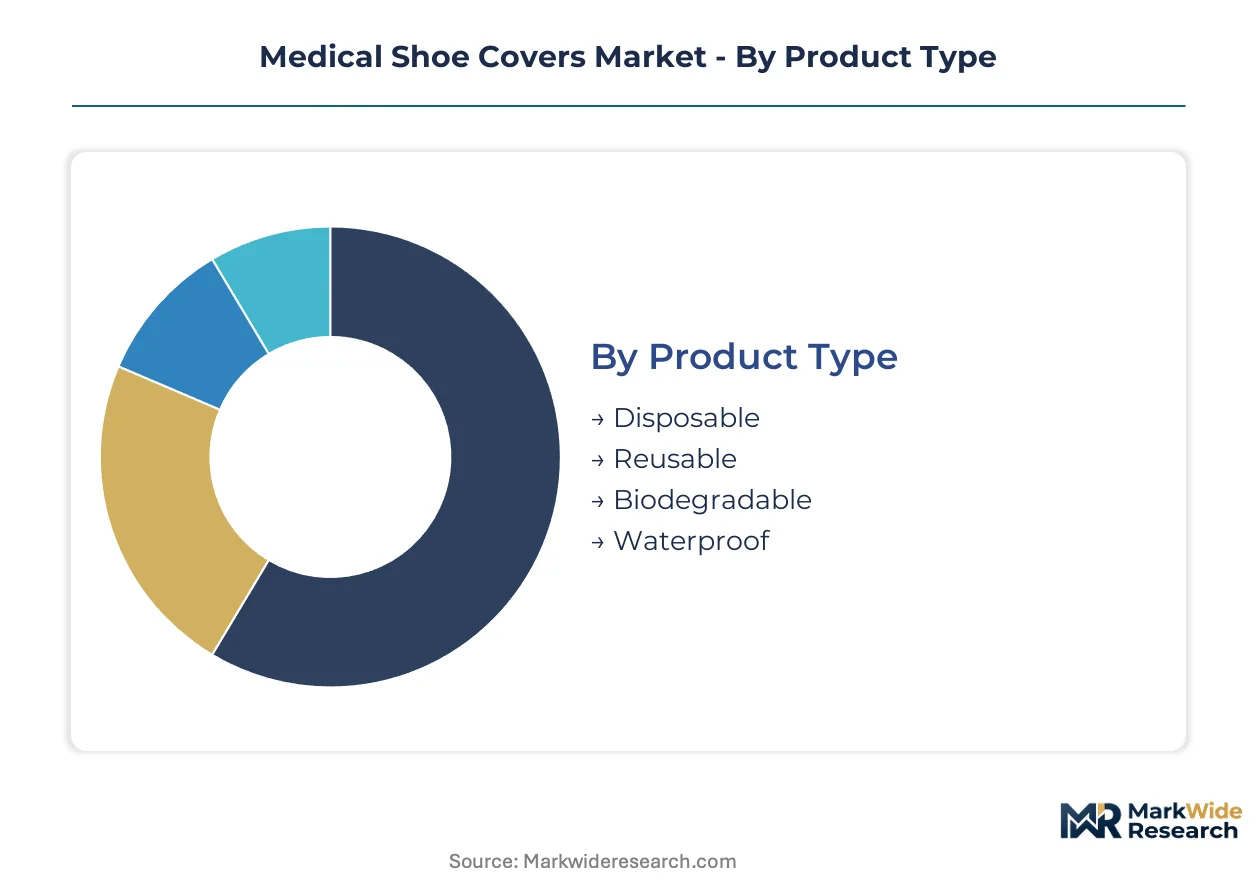
Material specifications and sterility protocols create divergent procurement patterns across healthcare settings. Buyers prioritize barrier performance, disposal economics, or sustainability credentials depending on facility type and regulatory exposure.
Product Type:
Cost tier dominates buyer calculus, with single-use mandates in surgical theaters clashing against waste reduction targets in administrative zones.
- Disposable:Polypropylene spunbond meltblown composites deliver particulate filtration with breathability. Operating theater managers in Germany and the United States specify these for Joint Commission compliance, locking in high-volume contracts through group purchasing organizations.
- Reusable:Silicone and chlorinated polyethylene formulations withstand industrial laundering cycles. Pharmaceutical cleanrooms with captive sterilization infrastructure favor these for total cost of ownership reduction, though upfront capital requirements limit adoption to tier-one facilities.
- Biodegradable:Polylactic acid variants decompose in industrial composting facilities, addressing EU extended producer responsibility frameworks.
- Waterproof:Fluid-resistant barriers for orthopedic and trauma surgery suites where splash exposure is routine.
Volume sits with Disposable; growth tilts toward Biodegradable.
Material:
Supply concentration in Asian resin markets shapes converter sourcing strategies and margin exposure.
- Polypropylene:Dominates commodity production through spunbond meltblown fabrication. Hospital networks standardize on this material for corridor and general ward applications where fluid exposure is minimal.
- CPE:Chlorinated polyethylene provides superior fluid resistance during wet procedures. Operating theater managers in Germany specify CPE for high-splash orthopedic surgeries, compressing price premiums for basic polypropylene alternatives in premium contract tiers.
- PVC:Plasticized formulations face REACH chemical restrictions on phthalate content, forcing dual-formulation portfolios for EU market access.
- Non-woven:Composite structures blend filtration efficiency with manufacturing throughput for high-volume converters.
Procurement volume clusters in Polypropylene; specification intensity concentrates in CPE.
End User:
Application environment dictates performance tier, with accreditation requirements institutionalizing purchase mandates.
- Hospitals:Joint Commission accreditation mandates and CDC isolation precaution guidelines institutionalize bulk purchasing through group purchasing organizations. Ambulatory surgical center expansion amplifies demand for fluid-resistant variants.
- Laboratories:Biosafety level-3 construction and cleanroom certification requirements drive demand for barrier-certified products with documented particulate filtration.
- Clinics:Smaller dental and veterinary practices bypass traditional distribution, purchasing through specialized medical supply platforms.
- Research Facilities:Academic and government laboratories with grant-funded procurement cycles prioritize unit cost over performance specifications.
Revenue concentration favors Hospitals; specification complexity peaks in Laboratories.
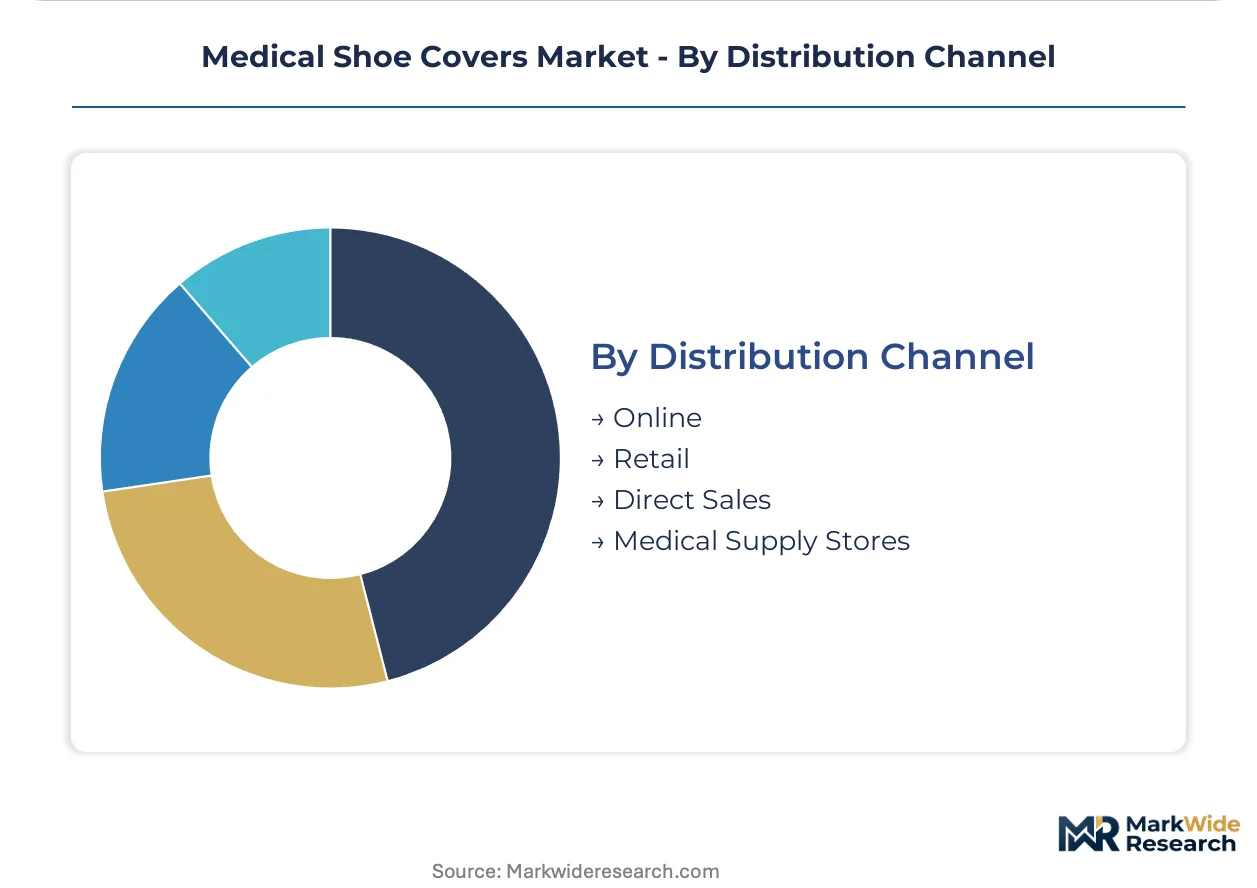
Distribution Channel:
Customer scale determines channel preference, with procurement digitization fragmenting traditional distributor relationships.
- Direct Sales:Integrated delivery networks in North America mandate single-source contracts for infection control apparel, consolidating supplier panels to three-to-five preferred converters.
- Online:E-commerce platforms capture smaller independent clinics and veterinary practices with transparent pricing and rapid fulfillment.
- Retail:Pharmacy chains and medical supply wholesalers serve walk-in professional buyers with immediate inventory needs.
- Medical Supply Stores:Regional distributors maintain local stock positions for emergency replenishment and same-day delivery commitments.
Contract value aggregates in Direct Sales; channel expansion runs through Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asian resin suppliers dominate upstream polypropylene feedstock, while North American and European healthcare systems absorb the bulk of finished medical shoe cover consumption through institutional procurement channels.
United States
Joint Commission accreditation mandates and CDC isolation precaution guidelines institutionalize bulk purchasing through group purchasing organizations. FDA 510(k) clearance pathways govern barrier claim substantiation for products distributed nationwide. The Midwest manufacturing corridor around Chicago anchors domestic converter operations serving integrated delivery networks.
Germany
Expansion of ambulatory surgical centers and biosafety level-3 laboratories drives consistent demand for fluid-resistant protective footwear. EU MDR notified body certification requirements force revalidation of barrier performance claims under stricter oversight. The Baden-Württemberg industrial cluster hosts specialized non-woven converters supplying university hospital networks.
China
Provincial hospital tier upgrades and biosafety level-3 laboratory construction create demand for imported barrier-certified products. NMPA registration requirements for Class II medical devices filter import eligibility. The Yangtze River Delta concentration of spunbond meltblown fabricators supplies both domestic converters and export markets.
India
Central government health mission procurement scales and private hospital chain expansion amplify disposable protective apparel requirements. CDSCO medical device rules classify shoe covers as notified devices requiring manufacturing licenses. The Gujarat pharmaceutical manufacturing belt generates concentrated demand from FDA-inspected export-oriented facilities.
Japan
Metropolitan hospital system standardization and eldercare facility infection control protocols sustain steady procurement volumes. PMDA quality management system requirements align with MHLW ministerial ordinances for protective equipment. The Osaka-Kobe industrial zone maintains specialized chlorinated polyethylene compounding capacity for premium surgical applications.
Medical Shoe Covers Market Competitive Landscape
The competitive structure tilts toward diversified health conglomerates with captive non-woven manufacturing assets. Tier-one positions cluster around entities controlling upstream polypropylene resin relationships and downstream hospital contracting channels. Two strategic archetypes dominate: integrated health supply conglomerates with direct sales infrastructure, and specialized infection control apparel converters with vertical material control. Capacity expansion and portfolio diversification represent the dominant competitive moves, as players extend protective apparel lines into adjacent barrier product categories.
Among North American health supply conglomerates, 3M Company and Kimberly-Clark Corporation exemplify the integrated archetype through their non-woven manufacturing scale and established hospital network relationships. Cardinal Health anchors the distribution-intensive tier with direct sales channels spanning integrated delivery networks. These three entities represent contrasting strategic positions: manufacturing-led versus logistics-led market access.
| Leading Market Players |
|---|
| 3M Company |
| Kimberly-Clark Corporation |
| Cardinal Health |
| Medline Industries |
| DuPont de Nemours |
| Alpha Pro Tech |
| Dynarex Corporation |
| Molnlycke Health Care AB |
| Ansell Limited |
| Others |
Supply & Pricing Matrix
Barrier certification tier divergence separates FDA 510(k) cleared products from unregistered commodity imports, manifesting in both hospital contract premiums and supply chain segregation between notified body audited facilities and unverified Asian converters. This bifurcation concentrates pricing power with converters maintaining dual EU MDR and FDA documentation portfolios while squeezing margin for undifferentiated polypropylene suppliers.
Pricing Analysis
Margin tightening in standard polypropylene tiers reflects resin price volatility and fixed-price GPO contract structures. Three-tier pricing structure across premium CPE, standard polypropylene, and economy non-woven levels differentiates on fluid resistance certification and breathability metrics. Pricing pressure stems from biodegradable PLA alternatives capturing sustainability-driven procurement mandates. Ambulatory surgical centers exhibit highest price sensitivity; biosafety level-3 laboratories show least.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta spunbond facilities and Gujarat pharmaceutical manufacturing belts shape converter sourcing strategies. Supply concentrates in China, India, and Germany for polypropylene resin, meltblown fabrication, and chlorinated polyethylene compounding respectively. Raw material dependencies span petrochemical feedstocks, plasticizer additives, and industrial composting infrastructure. Single-source vulnerability sits with Asian resin suppliers exposed to shipping disruptions. Distribution runs through integrated delivery network direct contracts and specialized medical supply platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical shoe covers market functions as a cost-of-compliance story where EU MDR notified body certification requirements erect barrier-to-entry moats favoring incumbents with validated technical documentation and audited manufacturing footprints.
For Market Incumbents: To counter biodegradable PLA entrants capturing sustainability procurement mandates, incumbents should deepen backward integration into polylactic acid resin sourcing and expand CPE compounding capacity in Baden-Württemberg to serve German university hospital networks with premium fluid-resistant specifications. For New Entrants and Emerging Players: Smaller dental and veterinary clinics purchasing through specialized medical supply platforms represent the most penetrable buyer archetype. These independent practices bypass GPO consolidation, enabling direct e-commerce access with rapid fulfillment value propositions and transparent unit pricing unencumbered by contract tier complexity. For Investors and Strategic Acquirers: Re-rating potential sits with converters possessing captive non-woven manufacturing and dual FDA-EU MDR certification portfolios given regulatory tightening decoupling low-grade imports from compliant supply chains. Acquisition targets should demonstrate hospital GPO panel positioning and vertical polypropylene sourcing control. The signal to watch is extended producer responsibility framework implementation accelerating biodegradable material substitution curves.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Technical documentation revalidation under stricter oversight locks in premium contract tiers with German hospital networks. |
| Biodegradable PLA Formulation Development | Polylactic acid variants address EU extended producer responsibility frameworks and procurement life-cycle evaluations. |
| Direct E-Commerce Channel Establishment | Specialized medical supply platforms capture smaller dental and veterinary practices bypassing traditional distribution. |
| CPE Compounding Capacity Expansion | Chlorinated polyethylene production in Osaka-Kobe industrial zone serves premium orthopedic surgery specifications. |
| Backward Polypropylene Integration | Captive resin sourcing mitigates petrochemical input volatility and shipping disruption exposure. |
Research Methodology
Independent corroboration across hospital procurement managers, GPO contracts specialists, biomedical engineers, and non-woven converter operations directors underwrites the qualitative findings. Primary fieldwork with infection control apparel manufacturers and cleanroom certification auditors combined with secondary validation from FDA 510(k) filings, EU MDR notified body registries, hospital procurement databases, and polypropylene trade flow records. Bottom-up volume estimates triangulate against top-down healthcare expenditure allocations.
Comparable-period anchoring to historical Joint Commission accreditation mandate implementation and EU MDR transition timelines structured the forecast window across the analysis window. Segmentation modeling incorporated material type, sterility protocol, end-user facility tier, and distribution channel complexity. CAGRs derived from regression against healthcare infrastructure expansion rates and biosafety laboratory construction permits. Industry-specific inputs included polypropylene resin price indices and extended producer responsibility framework adoption curves.
Revisions become necessary when EU MDR enforcement intensity exceeds notified body capacity constraints or when biodegradable material industrial composting infrastructure deployment lags procurement mandate timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Physiological Saline Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Skin Tac Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
GCC Medical Gloves Market
Medical Supplies
Latin America Incontinence Pads Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Swab Cups Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Europe Ultrasound Gels Market