
 Smart Face Masks Market | 2026-2036
Smart Face Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Face Masks Market Insights
Healthcare procurement departments are rotating toward smart mask portfolios as institutional buyers replace commodity PPE with connected respiratory systems. 3M Company leverages its filtration science heritage to dominate N95-class smart mask development. Xiaomi Corporation competes through aggressive cost engineering in health monitoring variants for Asian consumer markets. LG Electronics anchors its position via air purification technology transferred from its home appliance division.
Smart face masks integrate sensors, microfans, filtration media, and wireless connectivity into wearable respiratory devices that monitor biometric signals, filter particulates, or amplify speech. Manufacturing employs multilayer melt-blown polypropylene for filtration matrices paired with flexible PCB assemblies for sensor integration, producing devices rated for particulate filtration efficiency alongside real-time health data transmission. Reusable masks with embedded electronics capture expanding margin pools as replacement filter subscriptions generate recurring revenue, while health monitoring technology leads growth by embedding SpO2 and respiratory rate sensors. Air purification technology sustains premium positioning in industrial and healthcare settings where active ventilation addresses high-exposure environments.
FDA regulates smart masks with health claims as Class II medical devices in the United States, requiring 510(k) premarket notification and driving development costs upward for new entrants. ISO 13485 quality management standards and EU MDR conformity assessment in Europe create parallel compliance burdens that favor established manufacturers with regulatory affairs infrastructure. Stakeholders must monitor how FDA guidance on software-as-medical-device classification reshapes liability and approval timelines for mask-integrated health monitoring algorithms.
Market Dynamics
Hospital procurement departments are mandating connected respiratory protection as standard PPE, forcing manufacturers to integrate biometric sensors and wireless telemetry into mask architectures previously designed for passive filtration alone.
Growth Catalysts
- ISO 13485 certification mandates:European healthcare systems now require quality management documentation for all connected medical wearables, accelerating vendor consolidation toward compliant suppliers.
- Active ventilation modules:Industrial facilities in Japan are retrofitting worker protection protocols with battery-powered microfan systems that reduce breathing resistance during extended shifts.
- SpO2 monitoring integration:Post-acute care facilities embed pulse oximetry sensors directly into mask substrates, capturing respiratory data without separate finger-clip devices.
Market Restraints
- Flexible PCB supply concentration:Substrate fabrication for curved sensor arrays depends heavily on Taiwanese contract manufacturers, creating single-source vulnerability.
- EU MDR conformity timelines:Extended assessment periods for software-as-medical-device classification delay product launches by 14-22 months for algorithm-embedded masks.
- Lithium-polymer cell volatility:Battery chemistry price swings and shipping restrictions compress margins on rechargeable smart mask variants.
Strategic Opportunities
- Rural India penetration gap:Unconnected healthcare facilities present first-mover advantage for low-cost health monitoring masks with offline data storage.
- Speech amplification convergence:Combining bone-conduction microphones with noise-canceling algorithms opens classroom and hospitality applications beyond medical settings.
- Japan METI clean-air subsidies:Municipal rebate programs for personal air purification devices subsidize 30-40% of retail cost for aging populations in Tokyo and Osaka prefectures.
Industry Challenges
- Firmware validation bottlenecks:FDA 510(k) submissions for over-the-air update capabilities require documented cybersecurity frameworks that extend engineering cycles.
- Biocompatibility testing backlogs:ISO 10993 skin-sensitivity protocols for new elastomeric mask materials queue 8-12 months at accredited laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Face Masks Market |
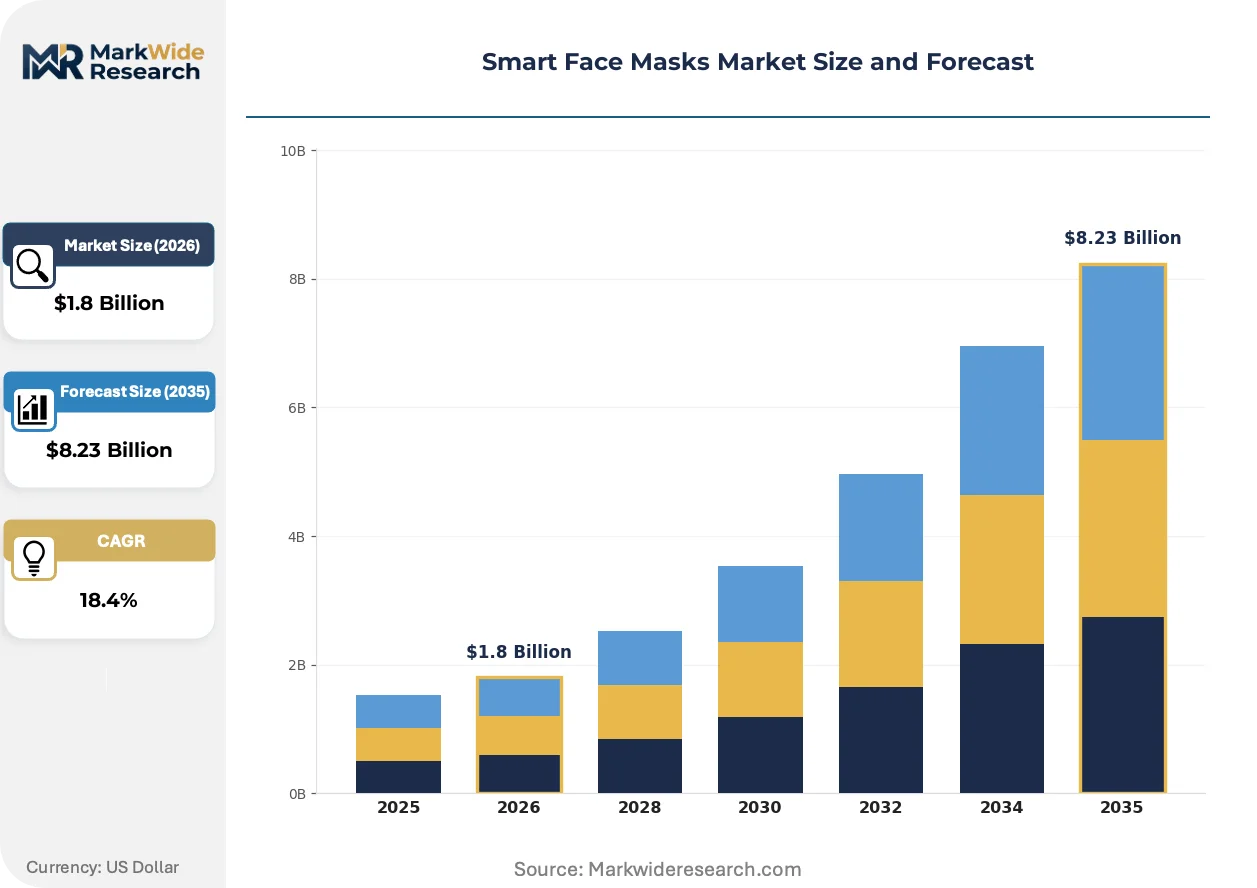
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Masks, Reusable Masks, Surgical Masks, N95 Masks Technology: Health Monitoring, Air Purification, Communication, Filtration End User: Healthcare Workers, General Public, Industrial Workers, Athletes Application: Infection Control, Air Quality Improvement, Personal Safety, Communication Enhancement |
| Companies Covered | 3M Company, Honeywell International Inc., LG Electronics, Xiaomi Corporation, Razer Inc., AirPop Health, RespoKare, Ao Air, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Face Masks Market Trends and Innovations
Material science breakthroughs and algorithmic miniaturization are compressing sensor-to-surface distances, enabling masks that capture clinical-grade respiratory data without compromising breathability or speech clarity.
Printed graphene electrodes are supplanting rigid silicon-based SpO2 sensors in next-generation mask designs. Post-operative wards at tertiary hospitals in Germany and South Korea are piloting these flexible arrays for continuous overnight monitoring. The technology is supplanting conventional fingertip oximeters by embedding photoplethysmography directly into mask nose-bridge assemblies, collapsing device count and patient discomfort while expanding reimbursable monitoring windows.
EU MDR software classification guidance issued in 2023 now treats respiratory rate algorithms as active medical devices requiring notified body review. Development teams must submit clinical validation studies for machine learning models that filter motion artifacts from breathing patterns. Wearable manufacturers with existing MDR infrastructure capture regulatory velocity advantages over consumer electronics entrants unfamiliar with European conformity assessment pathways.
Institutional buyers are consolidating vendor relationships around full-service respiratory protection contracts that bundle mask hardware, filter subscription logistics, and cloud-based exposure analytics. Industrial hygiene departments at manufacturing conglomerates negotiate multi-year agreements with single-source suppliers rather than maintaining fragmented PPE procurement across facility networks. This concentration is most visible in Japanese automotive supply chains, where tier-one component makers mandate unified smart mask deployments across stamping, welding, and painting operations.
Smart Face Masks Market Segmentation
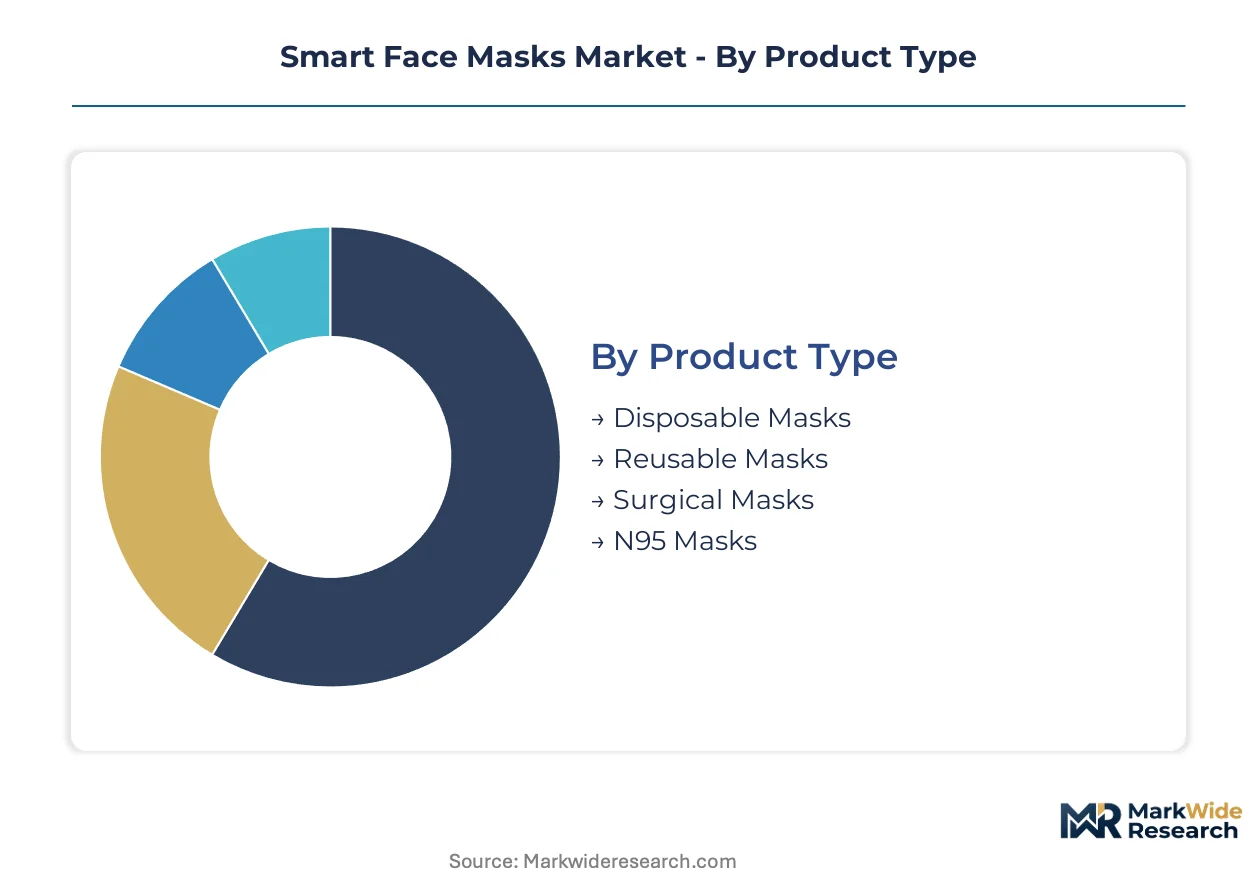
Smart face mask segmentation reveals how sensor integration and connectivity reshape purchasing decisions across institutional and consumer channels. Product durability, embedded technology sophistication, and end-user risk exposure determine margin structures and regulatory pathways for manufacturers.
Product Type:
Reusable variants face intensifying substitution pressure from disposable alternatives in high-turnover clinical environments where contamination protocols prioritize single-use economics.
- Reusable Masks:Embedded electronics and washable filtration substrates support multi-cycle deployment in industrial and consumer settings. Japanese automotive suppliers mandate these for welding floor workers under METI-backed clean-air protocols, with battery-powered microfans reducing breathing resistance across extended shifts.
- N95 Masks:NIOSH-certified filtration efficiency combines with biometric sensor arrays in hospital respiratory protection programs. Post-acute care facilities in Germany embed SpO2 monitoring directly into mask substrates, collapsing device count while expanding reimbursable monitoring windows.
- Disposable Masks:Single-use designs with limited sensor integration dominate high-turnover surgical suites where contamination protocols override durability requirements.
- Surgical Masks:Fluid-resistant barriers with basic filtration meet operating room standards without active ventilation or health monitoring capabilities.
Reusable masks retain volume leadership; health monitoring-enabled N95 variants hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensor-embedded systems from basic filtration, with health monitoring commanding the highest development overhead and regulatory burden.
- Health Monitoring:Printed graphene electrodes supplant rigid silicon-based SpO2 sensors in next-generation designs. Tertiary hospitals in South Korea pilot flexible photoplethysmography arrays for continuous overnight post-operative monitoring, eliminating patient discomfort from fingertip oximeters.
- Air Purification:Battery-powered microfan modules with HEPA-grade filtration target high-exposure industrial environments. Japanese municipal rebate programs subsidize retail costs for aging populations in Tokyo and Osaka prefectures.
- Filtration:Passive multilayer melt-blown polypropylene matrices meet baseline particulate efficiency without active components or wireless connectivity.
- Communication:Bone-conduction microphones with noise-canceling algorithms enable speech clarity in classroom and hospitality applications beyond medical settings.
Filtration technology anchors baseline volume; health monitoring climbs the fastest as FDA 510(k) pathways mature for algorithm-embedded masks.
End User:
Application maturity varies sharply across user categories, with healthcare procurement departments consolidating vendor relationships around full-service respiratory protection contracts.
- Healthcare Workers:Institutional buyers replace commodity PPE with connected respiratory systems integrating biometric sensors and wireless telemetry. Hospital procurement departments mandate these upgrades as standard protective equipment across infection control protocols.
- Industrial Workers:Manufacturing conglomerates negotiate multi-year agreements with single-source suppliers for unified deployments across stamping, welding, and painting operations.
- General Public:Consumer demand concentrates in aging demographics seeking personal air purification with health monitoring capabilities.
- Athletes:Performance-oriented variants capture respiratory rate data during training with motion artifact filtering for high-exertion environments.
Healthcare workers dominate procurement volume; industrial applications gain share fastest as Japanese automotive supply chains mandate facility-wide adoption.
Application:
Geographic concentration in developed Asian and European markets drives premium positioning for multi-function masks serving aging populations with reimbursable monitoring capabilities.
- Infection Control:Hospital-grade filtration with real-time exposure analytics supports institutional procurement consolidation. EU MDR software classification now treats respiratory rate algorithms as active medical devices requiring notified body review.
- Air Quality Improvement:Personal ventilation systems address urban particulate exposure in dense metropolitan environments with government subsidy support.
- Personal Safety:Industrial protocols prioritize breathing resistance reduction through active ventilation during extended shift work.
- Communication Enhancement:Speech amplification converges with noise-canceling algorithms for classroom and hospitality deployment beyond clinical settings.
Infection control maintains revenue concentration; air quality improvement expands most quickly as METI subsidies accelerate consumer uptake in Japan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturers export smart mask components to German healthcare systems upgrading respiratory protection protocols. South Korean fabricators supply sensor arrays to US hospital networks consolidating vendor relationships. Taiwanese contract manufacturers dominate flexible PCB substrate production for curved sensor arrays across all major buyer geographies.
United States
FDA 510(k) clearance pathways for health monitoring algorithms drive development costs upward for new market entrants. Hospital procurement departments in Massachusetts and California mandate connected respiratory protection with biometric telemetry as standard PPE. OSHA workplace exposure limits accelerate industrial adoption of active ventilation masks in Michigan automotive stamping facilities.
Japan
METI-backed clean-air initiatives subsidize personal air purification devices for aging populations in Tokyo and Osaka prefectures. PMDA quality management standards tighten product requirements for algorithm-embedded masks entering clinical settings. Automotive supply chains in Aichi Prefecture mandate unified smart mask deployments across welding and painting operations.
Germany
EU MDR software classification treats respiratory rate algorithms as active medical devices requiring notified body review. Post-operative wards at tertiary hospitals in Bavaria pilot printed graphene electrodes for continuous overnight monitoring. North Rhine-Westphalia industrial hygiene departments negotiate multi-year respiratory protection contracts bundling hardware with cloud-based exposure analytics.
South Korea
MFDS regulatory frameworks accelerate approval timelines for mask-integrated health monitoring systems. Tertiary hospitals in Seoul deploy flexible photoplethysmography arrays eliminating patient discomfort from fingertip oximeters. Daegu-Gyeongbuk manufacturing clusters source rechargeable mask variants with embedded SpO2 sensors for worker protection protocols.
India
CDSCO medical device regulations create compliance burdens favoring established manufacturers with regulatory affairs infrastructure. Unconnected healthcare facilities in Maharashtra and Karnataka present first-mover advantage for low-cost health monitoring masks with offline data storage. Tamil Nadu electronics manufacturing zones fabricate basic filtration substrates for regional distribution networks.
Smart Face Masks Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and manufacturing scale. The vendor base concentrates around three strategic archetypes: diversified conglomerates leveraging cross-division technology transfer, dedicated respiratory protection specialists with FDA infrastructure, and consumer electronics entrants competing on cost engineering. Dominant competitive moves include portfolio diversification into health monitoring variants and strategic partnerships for flexible PCB substrate supply security.
Within the diversified conglomerate tier, 3M Company and LG Electronics exemplify players transferring filtration science and home appliance air purification technology into wearable respiratory systems. Xiaomi Corporation occupies a position among cost-engineered consumer electronics specialists targeting Asian markets. Honeywell International Inc. anchors the industrial safety archetype with established regulatory affairs infrastructure spanning multiple geographies.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| LG Electronics |
| Xiaomi Corporation |
| Razer Inc. |
| AirPop Health |
| RespoKare |
| Ao Air |
| Kimberly-Clark Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term filter subscription contracts lock in recurring revenue visibility for reusable mask vendors while insulating buyers from lithium-polymer cell volatility. Japanese automotive suppliers and German hospital systems negotiate multi-year agreements that bundle hardware replacement cycles with cloud analytics access, compressing procurement friction into predictable per-worker costs.
Pricing Analysis
Next-generation health monitoring masks command substantial premiums over basic filtration variants, with printed graphene electrode integration driving the steepest tier separation. Three-tier pricing structure across premium health monitoring, standard air purification, and economy passive filtration reflects FDA 510(k) certification overhead and ISO 13485 compliance investment. Cost compression in the economy tier intensifies as Chinese consumer electronics entrants flood Asian markets with unconnected disposable alternatives. Industrial buyers in Japan exhibit lowest price sensitivity due to METI subsidy absorption, while rural Indian healthcare facilities remain acutely cost-constrained.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates flexible PCB substrate fabrication for curved sensor arrays in the hands of contract manufacturers near Kaohsiung. Manufacturing draws from South Korean battery cell suppliers, Japanese filtration media specialists, and German precision molding operations for elastomeric components. Single-source dependency on Taiwanese substrate producers creates acute disruption exposure from geopolitical friction or shipping lane congestion. Distribution runs through hospital GPOs in North America, industrial safety distributors in Europe, and direct-to-consumer channels in Asian consumer markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device reclassification transforms smart masks from consumer electronics into regulated clinical instruments, collapsing approval timelines for unprepared entrants while rewarding established regulatory affairs infrastructure.
For Market Incumbents: Secure flexible PCB supply through capacity reservations or minority stakes in Taiwanese substrate fabricators, insulating against single-source disruption as sensor-embedded mask volumes accelerate. Deepen ISO 13485 certification moats by pre-validating firmware update frameworks for 510(k) submissions, blocking consumer electronics rivals from algorithm-embedded health monitoring segments. For New Entrants and Emerging Players: Offline data storage architectures for unconnected rural healthcare facilities in Maharashtra and Karnataka present white-space penetration opportunities where cloud-dependent incumbents cannot compete. Target speech amplification convergence for classroom and hospitality applications beyond medical settings, leveraging bone-conduction microphone supply chain maturity from consumer audio markets. For Investors and Strategic Acquirers: Regulatory affairs boutiques with existing FDA 510(k) infrastructure and EU MDR notified body relationships represent priority acquisition targets as software classification burdens intensify. Monitor FDA guidance publication velocity on algorithm validation requirements as the inflection signal separating viable health monitoring plays from stranded consumer electronics pivots.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-submission | Early engagement with FDA CDRH compresses approval timelines for algorithm-embedded masks. |
| Flexible PCB Supply Partnership | Taiwanese substrate capacity reservations secure sensor array fabrication for health monitoring variants. |
| Hospital GPO Contract Negotiation | Multi-year agreements with Premier or Vizient consolidate procurement volume against fragmented competitors. |
| Software Companion Development | Cloud-based exposure analytics platforms generate recurring revenue beyond hardware replacement cycles. |
| EU MDR Notified Body Engagement | BSI or TÜV SÜD conformity assessment pre-empts software classification delays for European market entry. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers, industrial hygiene directors, and regulatory affairs leads, then refined through secondary validation against FDA 510(k) filings, EU MDR notified body databases, and Japanese METI clean-air subsidy records. Bottom-up triangulation across component supplier interviews and top-down reconciliation against hospital GPO contract values anchored volume estimates.
Variance decomposition across product type, technology tier, end-user segment, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs emerged from segmented growth rate reconciliation against macro healthcare expenditure trends and industrial PPE upgrade cycles. Forecast inputs incorporated lithium-polymer cell price trajectory assumptions and ISO 13485 certification penetration rates by manufacturer tier.
Underlying assumptions cover FDA software guidance stability and Taiwan Strait shipping lane continuity, with deviation risk concentrated in EU MDR timeline extensions and battery chemistry shipping restriction escalations. Practitioners should keep alternative scenarios live as regulatory classification boundaries and geopolitical supply chain conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Compression Socks Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Medical Plastics Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Gingival Retraction Kits Market
Medical Supplies
Super Absorbent Dressings Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Intravenous (IV) Fluid Bags Market