
 Global IV Tubing Sets and Accessories Market | 2026-2036
Global IV Tubing Sets and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global IV Tubing Sets and Accessories Market Foresight
Hospital procurement channels is tilting toward consolidated purchasing through group purchasing organizations and direct manufacturer contracts. B. Braun Medical Inc. leverages its integrated manufacturing footprint across European and North American production sites to secure long-term supply agreements with major health systems. Baxter anchors its position through deep relationships with integrated delivery networks, while BD competes aggressively on standardized product lines that reduce clinical training burdens.
IV tubing sets and accessories comprise sterile, single-use conduits manufactured from medical-grade PVC, polyurethane, or silicone, typically featuring Luer-lock connectors, roller clamps, and needle-free injection ports designed to deliver fluids, medications, or blood products directly into a patient's vascular system. Standard IV tubing and extension sets represent mature, high-volume categories where margin compression is most severe, while filtered sets and pressure monitoring sets command premium positioning due to specialized clinical applications and stricter performance requirements. The application split shows intravenous therapy and chemotherapy generating the most consistent demand, with parenteral nutrition emerging as a faster-growing segment driven by home healthcare expansion.
FDA device regulations, EU MDR requirements, and ISO 80369 small-bore connector standards collectively govern material biocompatibility, sterility assurance, and interoperability across the installed base of infusion devices. These frameworks elevate barriers for new entrants while forcing incumbent manufacturers to absorb recurring compliance and validation costs. Stakeholders must track evolving connector standards and regional notification requirements to anticipate redesign cycles and certification timelines that determine competitive access.
Market Dynamics
Hospital procurement consolidation through group purchasing organizations is compressing distributor margins while elevating volume commitments for direct manufacturer contracts, fundamentally restructuring how IV tubing flows from production lines to patient bedsides.
Growth Catalysts
- EU MDR compliance deadlines:Stricter sterility assurance requirements are accelerating replacement cycles for legacy tubing sets across European acute care facilities.
- Home infusion therapy expansion:Parenteral nutrition and chemotherapy administration outside hospital walls is generating pull for specialized ambulatory tubing configurations.
- Polyurethane material substitution:Superior biocompatibility and kink resistance versus PVC is driving specification upgrades in pediatric and oncology segments.
Market Restraints
- Medical-grade PVC feedstock volatility:Petrochemical input cost swings compress margin predictability for standard tubing manufacturers.
- Single-source sterilization dependency:Ethylene oxide and gamma sterilization capacity concentrates in the United States and Germany, creating geographic supply risk.
- ISO 80369 redesign cycles:Mandatory small-bore connector standardization forces recurring engineering validation costs without volume expansion.
Strategic Opportunities
- India hospital infrastructure buildout:Government tertiary care expansion and medical device PLI incentives create white space for premium tubing localization.
- Closed-system transfer device convergence:Integration of IV tubing with hazardous drug containment technology opens oncology pharmacy automation.
- Amazon Business and direct-to-facility e-procurement:Digital procurement platforms are disintermediating traditional medical-surgical distributors for non-critical SKUs.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization validation timelines stretch 12-18 months for novel material formulations.
- Legacy pump interoperability:Retrofitting new connector standards onto installed infusion device bases requires hospital IT and clinical engineering coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IV Tubing Sets and Accessories Market |
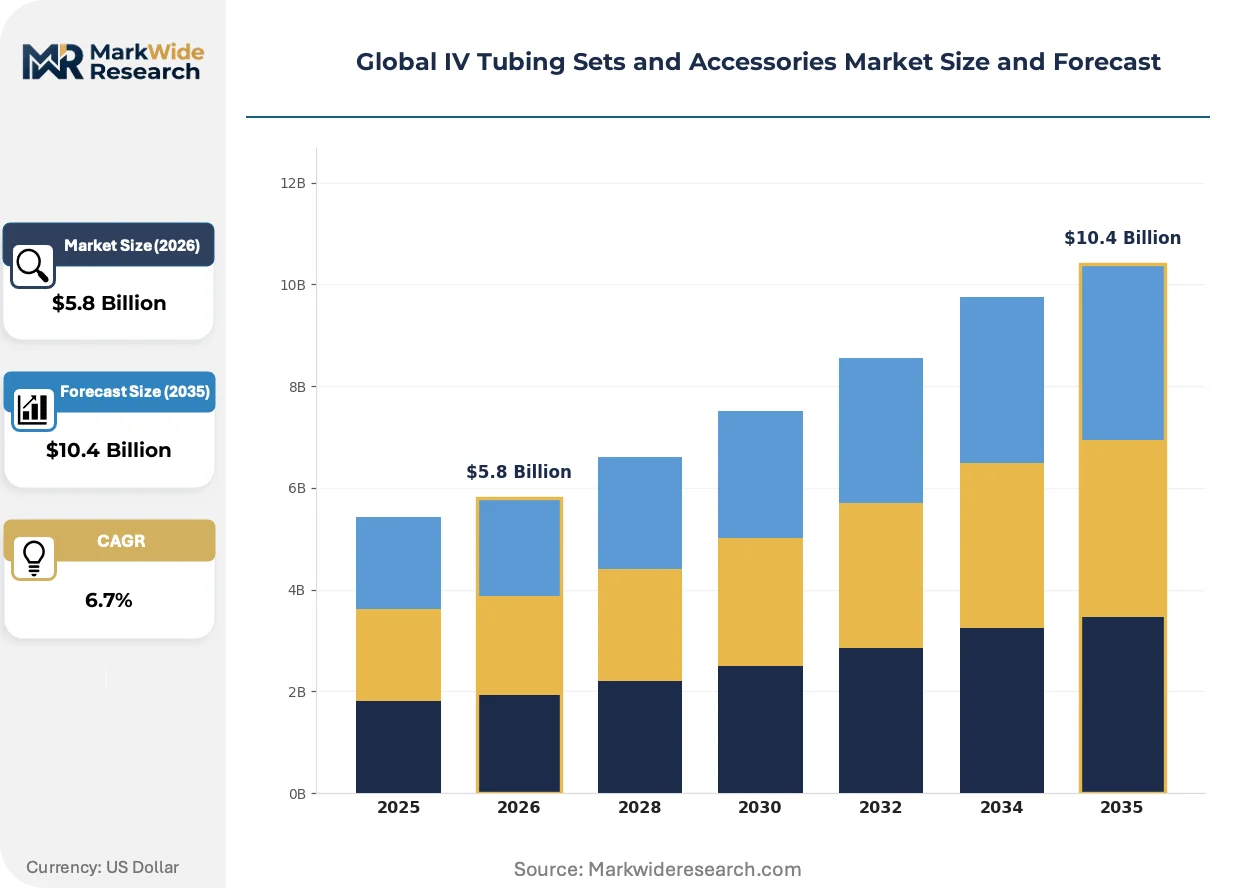
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard IV Tubing, Blood Transfusion Sets, Extension Sets, Pressure Monitoring Sets, Filtered Sets Application: Intravenous Therapy, Parenteral Nutrition, Chemotherapy, Anesthesia, Fluid Replacement End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Healthcare Agencies, Dialysis Centers Distribution Channel: Direct Sales, Online Platforms, Medical Distributors, Group Purchasing Organizations, Retail Pharmacies |
| Companies Covered | B. Braun Medical Inc., Nipro Medical Corporation, Baxter, Zyno Medical LLC, Polymedicure, BD, Fresenius Kabi AG, Romsons, ICU Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IV Tubing Sets and Accessories Market Shifts & Advancements
Active material science advancement and regulatory harmonization pressures are converging to reshape product architectures, with manufacturers racing to embed connectivity and sustainability credentials ahead of compliance deadlines.
Smart infusion tubing with embedded pressure sensors and flow verification chips is hybridizing traditional fluid conduits with real-time monitoring infrastructure. Academic medical centers in the United States are piloting these systems for high-risk medication administration. This convergence is compressing the boundary between disposable sets and capital equipment, forcing tubing manufacturers to develop firmware competencies or partner with pump OEMs.
REACH restrictions on phthalate plasticizers are compelling PVC formulation changes across European supply chains. Manufacturers face reformulation costs for DEHP-free alternatives while maintaining equivalent flexibility and sterilization tolerance. Pediatric and neonatal segments in Germany and France are experiencing the fastest specification migration as hospitals preempt stricter national bans.
Standardized product catalogs are displacing custom-configured tubing sets as health system formularies consolidate SKUs. Integrated delivery networks in the United States are mandating universal connectors and clamp designs across their facilities to reduce nursing training burden and error rates. This rationalization is most visible in multi-state hospital systems where supply chain centralization has eliminated regional product variation.
Global IV Tubing Sets and Accessories Market Segmentation
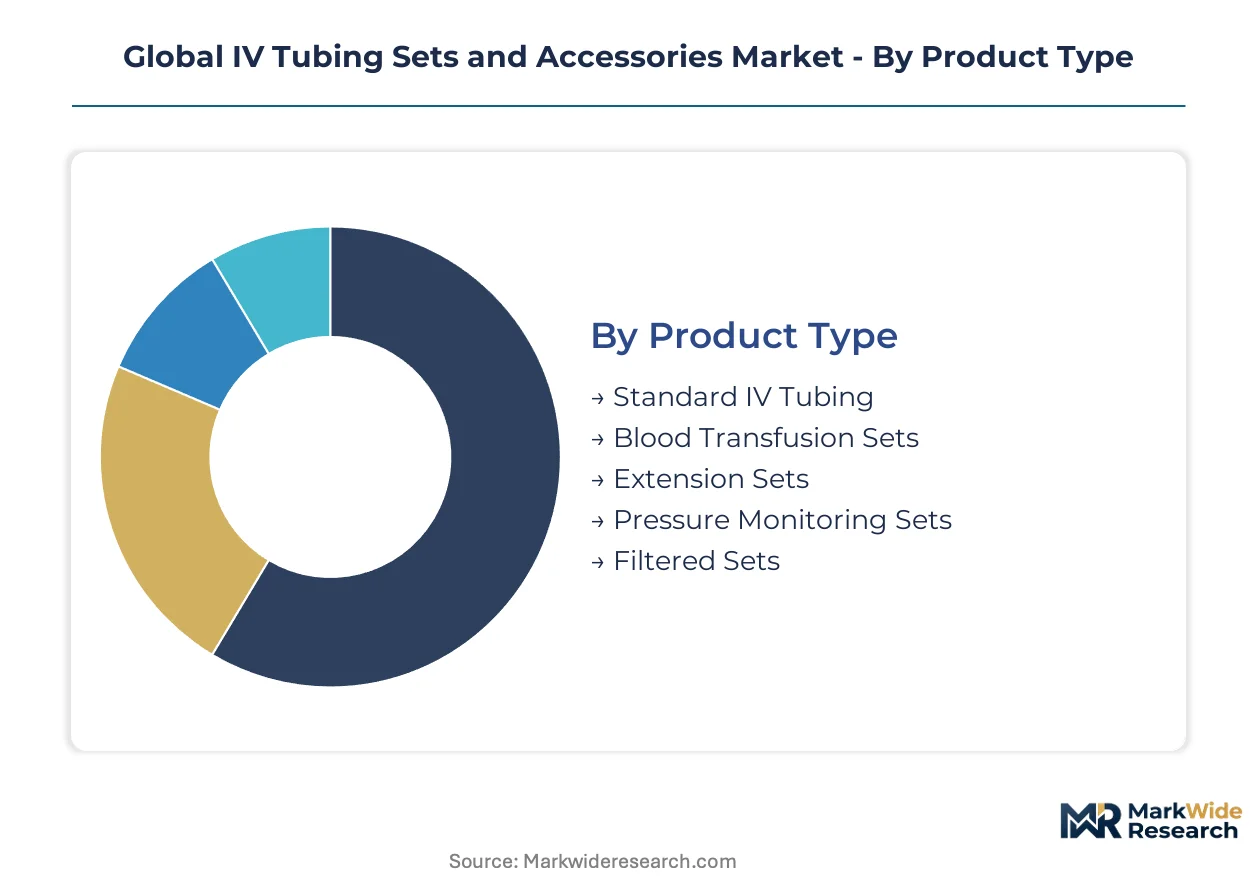
IV tubing segmentation determines service intensity, inventory velocity, and compliance burden across the supply chain. Product architecture, clinical application, and procurement channel each create distinct margin profiles and renewal cycles.
Product Type:
After-sales service intensity varies sharply by complexity — pressure monitoring and filtered sets demand calibration support and field engineering, while standard tubing requires minimal technical intervention.
- Standard IV Tubing:Manufactured from medical-grade PVC with Luer-lock connectors and roller clamps, these high-volume conduits face severe margin compression. Demand concentrates in United States acute care hospitals where GPO contracts drive specification standardization and price-down cycles.
- Filtered Sets:Integrating hydrophobic or depth filters for particulate and air removal, these sets command premium positioning. German and French pediatric oncology units specify these for high-risk medication delivery, with ISO 80369 connector mandates accelerating replacement timelines.
- Blood Transfusion Sets:Feature specialized drip chambers and inline filters for hemocompatibility.
- Extension Sets:Provide modular connectivity between primary lines and access points.
- Pressure Monitoring Sets:Incorporate transducer interfaces for hemodynamic measurement in critical care.
Standard IV tubing holds the largest share; momentum sits with filtered sets.
Application:
Clinical risk tier determines material specification and regulatory scrutiny — oncology and parenteral nutrition applications carry the highest biocompatibility validation burdens.
- Intravenous Therapy:The foundational application encompassing fluid resuscitation, electrolyte correction, and medication delivery through peripheral or central lines. United States hospital systems generate the highest procurement volumes as surgical caseloads expand and length-of-stay compression drives ambulatory conversion.
- Parenteral Nutrition:Requires lipid-compatible tubing formulations with minimal extractables for long-term vascular access. Home healthcare expansion in Germany and Japan is pulling specialized ambulatory configurations with integrated pump interfaces.
- Chemotherapy:Demands closed-system transfer device compatibility and hazardous drug containment.
- Anesthesia:Utilizes high-flow, low-compliance tubing for rapid volume administration.
- Fluid Replacement:Encompasses crystalloid and colloid resuscitation in emergency and perioperative settings.
Intravenous therapy dominates volume; parenteral nutrition is expanding most quickly.
End User:
Customer scale and purchasing sophistication fragment procurement patterns — integrated delivery networks negotiate multi-year commitments while home healthcare agencies prioritize disposability and ease of use.
- Hospitals:The dominant channel with centralized supply chain operations and formulary control. United States multi-state systems mandate universal connector standards across their facilities, eliminating SKU variation and reducing nursing training burden.
- Home Healthcare Agencies:Represent the steepest expansion trajectory as infusion therapy migrates outside institutional walls. Japanese and German reimbursement frameworks now cover parenteral nutrition and chemotherapy administration in residential settings.
- Ambulatory Surgical Centers:Focus on high-turnover, standardized procedure packs.
- Specialty Clinics:Require procedure-specific configurations for dermatology, rheumatology, and gastroenterology.
- Dialysis Centers:Utilize specialized bloodlines with heparin coating and ultrafiltration monitoring.
Hospitals retain the largest share; home healthcare agencies are gaining share fastest.
Distribution Channel:
Channel economics reflect buyer scale and product criticality — direct contracts capture high-volume predictable demand while digital platforms disintermediate non-critical replenishment.
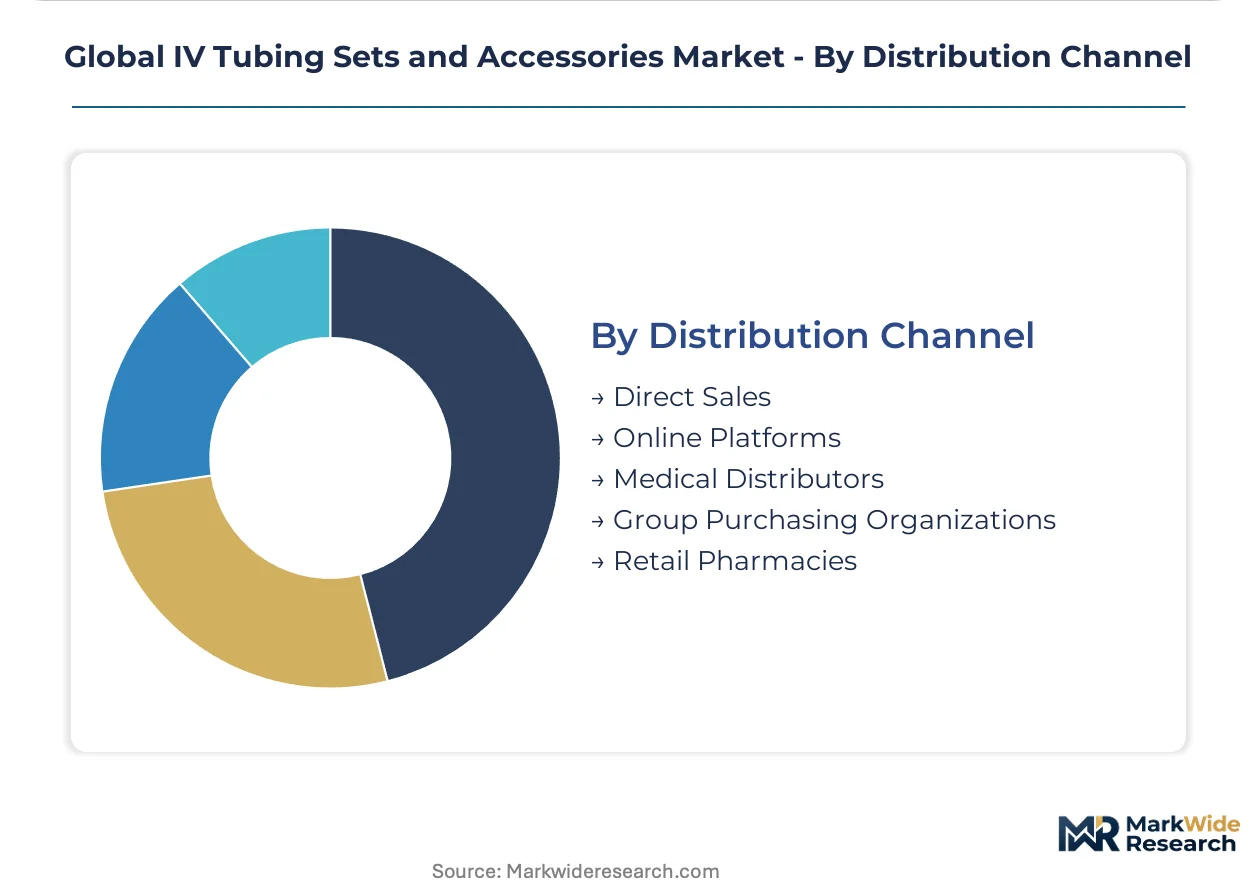
- Direct Sales:Manufacturer relationships with integrated delivery networks and major health systems lock in multi-year volume commitments. B. Braun and Baxter leverage direct channels for customized tubing configurations with embedded pump compatibility.
- Group Purchasing Organizations:Consolidate procurement across hundreds of United States hospitals, compressing distributor margins and elevating standardization mandates. Premier and Vizient contracts specify DEHP-free formulations and ISO 80369 compliance.
- Medical Distributors:McKesson and Cardinal Health maintain regional stocking for emergency replenishment.
- Online Platforms:Amazon Business and specialized medical marketplaces serve smaller clinics and ASCs.
- Retail Pharmacies:Capture limited home infusion accessory demand.
Direct sales holds the largest share; momentum sits with group purchasing organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites Europe's distribution supremacy for sterile medical devices, while Singapore's Changi air freight hub anchors Asia-Pacific supply chain velocity for temperature-sensitive infusion components.
United States
Surgical procedure volumes and aging demographics sustain procurement intensity for advanced IV delivery systems. FDA device classification updates for infusion pumps reshape compliance timelines and validation costs for domestic manufacturers. The Minneapolis-Saint Paul corridor hosts concentrated sterilization infrastructure serving upper Midwest health systems.
Germany
EU MDR sterility assurance deadlines accelerate replacement cycles for legacy tubing across acute care networks. REACH restrictions on phthalate plasticizers compel DEHP-free formulation shifts in pediatric and neonatal segments. The Baden-Württemberg medical technology cluster drives specification upgrades for oncology pharmacy automation.
China
Hospital infrastructure expansion and domestic production incentives elevate local manufacturing capacity for standard IV configurations. NMPA medical device registration reforms streamline pathway timelines for imported premium sets. The Yangtze River Delta concentration of polymer processing facilities supplies medical-grade PVC feedstock to regional fabricators.
India
Government tertiary care expansion and medical device PLI incentives create procurement white space for premium tubing localization. CDSCO quality control orders tighten import inspection protocols for sterile single-use devices. The Maharashtra pharmaceutical manufacturing belt attracts contract sterilization investments serving domestic and export markets.
Japan
Reimbursement framework expansion for home parenteral nutrition pulls specialized ambulatory tubing configurations into residential settings. PMDA biocompatibility validation requirements extend certification timelines for novel polyurethane formulations. The Kansai region's precision polymer processing base supplies lipid-compatible tubing for long-term vascular access applications.
Global IV Tubing Sets and Accessories Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material science and connector engineering. The vendor base stratifies across three tiers: diversified medical device conglomerates with captive sterilization assets, mid-scale specialists with regional GPO anchoring, and emerging fabricators competing on cost-advantaged standard configurations. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with infusion pump OEMs for interoperability certification.
Within the diversified conglomerate tier, B. Braun Medical Inc., Baxter, and BD exemplify scale-driven platform positioning. B. Braun leverages integrated European and North American manufacturing footprints to secure long-term supply agreements. Baxter anchors relationships with integrated delivery networks through direct contracting structures. BD competes on standardized product lines that reduce clinical training burdens across multi-state health systems.
| Leading Market Players |
|---|
| B. Braun Medical Inc. |
| Nipro Medical Corporation |
| Baxter |
| Zyno Medical LLC |
| Polymedicure |
| BD |
| Fresenius Kabi AG |
| Romsons |
| ICU Medical, Inc. |
| Others |
Supply & Pricing Matrix
Medical-grade PVC compounding capacity concentrates in the Yangtze River Delta and the US Gulf Coast, tethering margin pools to polymer feedstock procurement scale and sterilization asset ownership. GPO-negotiated volume tiers compress unit economics for standard tubing while filtered sets and pressure monitoring configurations retain pricing power through clinical differentiation.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating premium filtered sets from standard IV configurations from economy extension sets. Price differentiation hinges on ISO 80369 connector certification and DEHP-free material validation, with pediatric oncology segments showing lowest price sensitivity due to liability exposure. Cost compression in standard tubing intensifies as Chinese manufacturers expand capacity for non-critical SKUs. Ambulatory surgical centers exhibit highest price sensitivity, prioritizing procedure-pack standardization over performance specifications.
Supply Chain Analysis
Contract manufacturing concentrates with B. Braun's captive European facilities, Baxter's integrated North American footprint, and Nipro's Japanese polymer processing centers. Raw material dependencies span medical-grade PVC resin, polyurethane formulations, and Luer-lock connector moldings. Single-source sterilization vulnerability runs through ethylene oxide capacity in the United States and Germany. Distribution runs through GPO-mediated direct contracts for high-volume hospital systems, with medical distributors handling emergency replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global IV Tubing Sets and Accessories Market is entering a cyclical recovery phase as EU MDR compliance deadlines force replacement cycles across European acute care networks. Hospital procurement consolidation and home infusion expansion create divergent demand patterns requiring distinct strategic responses.
For Market Incumbents: Build regulatory certification moats by accelerating ISO 80369 validation pipelines and securing DEHP-free material equivalency documentation ahead of REACH enforcement waves. Incumbents should anchor backward integration into polymer compounding to defend margin position against feedstock volatility, while deepening pump OEM partnerships to lock in interoperability certification for smart tubing configurations. For New Entrants and Emerging Players: Build out contract sterilization partnerships in India and Southeast Asia to bypass capacity bottlenecks in the United States and Germany. Target home healthcare agencies with ambulatory-optimized tubing configurations featuring integrated pump interfaces and simplified training protocols. Penetrate through digital procurement platforms serving smaller clinics and specialty practices outside GPO coverage. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-system transfer device convergence plays as oncology pharmacy automation demands hazardous drug containment integration. The 5-10 year viability window favors platform integrators with captive sterilization assets over pure-play component fabricators. Watch for FDA device classification updates as inflection signals determining compliance cost trajectories and competitive access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80369 Connector Certification | Ensures interoperability with Baxter and B. Braun infusion pumps across hospital formularies. |
| DEHP-Free Material Transition | Aligns with REACH restrictions and preempts pediatric segment bans in Germany and France. |
| Closed-System Transfer Device Integration | Captures oncology pharmacy automation demand for hazardous drug containment protocols. |
| Home Healthcare Configuration Development | Addresses Japanese and German reimbursement expansion for residential parenteral nutrition. |
| Direct-to-Facility E-Procurement Partnership | Disintermediates traditional distributors for non-critical SKU replenishment through Amazon Business. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committees, GPO contracts managers, biomedical engineers, and regulatory affairs leads at sterilization facilities; and secondary validation through FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and polymer trade flow records. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against health system consumption patterns.
Forecast inputs considered product type segmentation by clinical application, material specification tiers, and end-user procurement sophistication across the projection horizon. Modeled dimensions spanned standard versus filtered versus pressure monitoring configurations, PVC versus polyurethane material splits, and hospital versus home healthcare delivery settings. CAGRs derived from regression analysis of historical replacement cycles, regulatory deadline impacts, and reimbursement framework expansions.
Stress conditions across ethylene oxide sterilization capacity, medical-grade PVC feedstock pricing, and EU MDR enforcement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance cost absorption and home infusion therapy migration rates. Quarterly review of GPO contract renewal patterns and CDSCO import inspection protocols is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Microcarrier Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
South America Syringe Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Global Swab Market
Medical Supplies
Breast Shells Market