
 United States Hospital Supplies Market | 2026-2036
United States Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hospital Supplies Market Analytics
Software-defined inventory management is decoupling capital equipment sales from recurring revenue streams in the hospital supplies sector. Cardinal Health leverages its distribution network to sustain national coverage for disposable surgical products. Medtronic anchors its position through specialized cardiac catheterization supplies. Becton Dickinson differentiates via vertically integrated needle and syringe manufacturing.
United States hospital supplies encompass instruments, apparatus, and consumables manufactured from medical-grade polymers, stainless steel alloys, and sterilizable composites designed to support diagnostic, therapeutic, and surgical interventions in acute care settings. FDA 510(k) clearance pathways and ISO 13485 quality management systems govern material biocompatibility and sterility assurance levels for patient-contact devices. Surgical instruments and IV supplies capture dominant volume positions, while diagnostic equipment commands premium margin pools due to embedded sensor technologies and software validation requirements. Private hospitals drive procurement velocity through centralized purchasing consortia, whereas outpatient clinics represent the fastest-expanding end-user channel as procedural migration accelerates.
FDA device classification rules, CMS reimbursement coding, and Joint Commission accreditation standards collectively shape product development priorities and market access conditions for domestic manufacturers. OSHA bloodborne pathogen regulations and EPA medical waste disposal mandates further constrain material selection and end-of-life handling protocols across the supply chain. Stakeholders must monitor evolving FDA guidance on cybersecurity for connected diagnostic devices and anticipate CMS bundled payment expansions that will reconfigure procurement economics for integrated supply categories.
Market Dynamics
Software-defined inventory management is decoupling capital equipment sales from recurring revenue streams, forcing distributors to restructure contract economics around consumption-based replenishment rather than upfront purchase volumes.
Growth Catalysts
- Academic medical center expansion:Tier-one teaching hospitals are accelerating procurement of advanced surgical consumables to support robotic-assisted procedure volumes. This channel now drives premium product mix shifts across cardiovascular and orthopedic categories.
- FDA 510(k) pathway refinement:Streamlined premarket notification for moderate-risk devices is compressing time-to-market for polymer-based single-use instruments. Domestic manufacturers are redirecting R&D budgets toward iterative device improvements rather than novel predicate searches.
- Texas hospital construction pipeline:Active greenfield development in Dallas-Fort Worth and Houston metro corridors is generating concentrated demand for turnkey supply packages. Regional health systems are pre-negotiating multi-year consumable commitments before facility commissioning.
Market Restraints
- Medical-grade polymer cost volatility:Polypropylene and polycarbonate feedstock prices fluctuate with petrochemical indices, squeezing margin predictability for disposable instrument manufacturers. Contract manufacturers lack pricing power to pass through raw material swings.
- Chinese stainless steel alloy concentration:Surgical instrument forging relies on specialized 400-series stainless sourced from Zhejiang and Jiangsu provinces. Geopolitical friction elevates supply interruption risk for precision-cut instrument blanks.
- EPA medical waste disposal mandates:Stricter sterilization byproduct handling rules are elevating end-of-life compliance costs for single-use device categories. Rural hospitals face disproportionate burden from limited licensed disposal infrastructure.
Strategic Opportunities
- Outpatient clinic channel expansion:Ambulatory surgical centers in Florida and Arizona are migrating historically inpatient procedures, creating demand for compact, procedure-specific supply kits. Distributors can capture wallet share through consignment inventory models.
- CMS bundled payment expansion:Episode-based reimbursement for cardiac and orthopedic interventions incentivizes supply cost consolidation. Manufacturers offering integrated procedure packs gain preference in value-based contracting discussions.
- AI-enabled demand forecasting convergence:Machine learning algorithms layered atop ERP systems are reducing safety stock requirements for high-velocity consumables. Early adopters in California health systems report working capital improvements.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, extending product launch timelines for novel polymer formulations. Third-party testing providers command premium pricing for expedited slots.
- Legacy EHR integration friction:Supply chain modules from incumbent software vendors resist seamless data exchange with emerging inventory optimization platforms. Health system IT departments must maintain parallel workflows during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hospital Supplies Market |
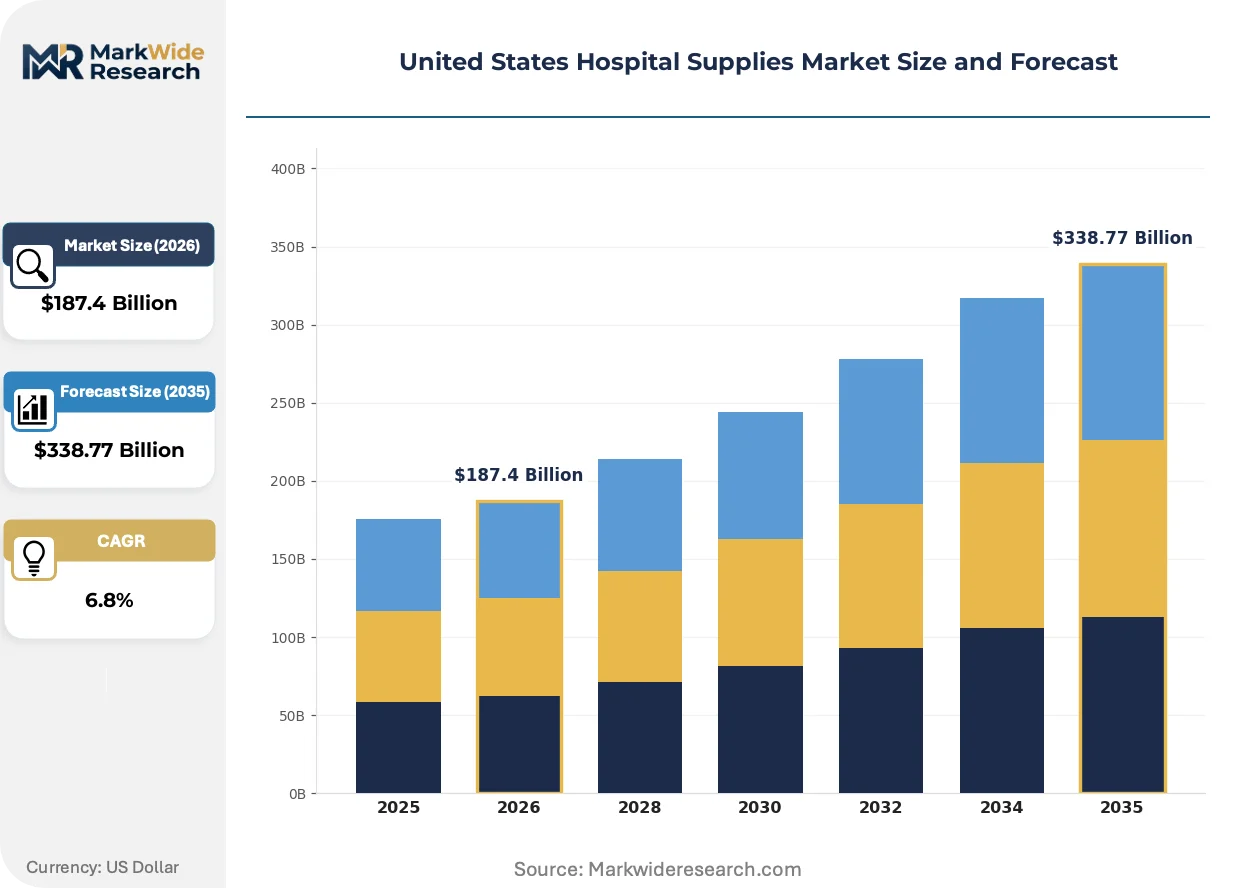
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, IV Supplies, Hospital Furniture End User: Private Hospitals, Public Hospitals, Outpatient Clinics, Rehabilitation Centers Material: Plastic, Metal, Glass, Fabric Form: Disposable, Reusable, Sterilized, Non-Sterilized |
| Companies Covered | Cardinal Health, Boston Scientific Corporation, Medtronic, 3M, Abbott Laboratories, Becton Dickinson, Thermo Fisher Scientific, B. Braun, Baxter International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hospital Supplies Market Evolving Landscape
Connected device architectures and predictive analytics are restructuring how acute care facilities acquire, deploy, and replenish clinical supplies. Three developments are compressing traditional procurement cycles and redefining supplier relationships.
Smart sensor-embedded surgical instruments are integrating real-time usage data into cloud-based inventory platforms. Academic medical centers in Massachusetts and Pennsylvania are piloting instrument trays that auto-report sterilization cycles and wear indicators. This telemetry is integrating predictive maintenance alerts with automated reorder triggers, collapsing the gap between consumption detection and replenishment fulfillment.
FDA guidance on cybersecurity for connected diagnostic devices is mandating software bill of materials and vulnerability disclosure protocols. Device manufacturers must now embed update mechanisms and encryption standards into IV pumps and patient monitoring systems. The cardiac catheterization supply segment faces the steepest compliance burden given the density of network-connected hemodynamic monitors.
Centralized purchasing consortia are consolidating vendor panels and compressing contract renegotiation cycles. Private hospital systems in Texas and Florida are displacing individual facility procurement autonomy with enterprise-wide formulary standardization. This concentration is most visible in disposable surgical product categories where volume aggregation yields double-digit unit cost reductions.
United States Hospital Supplies Market Segmentation
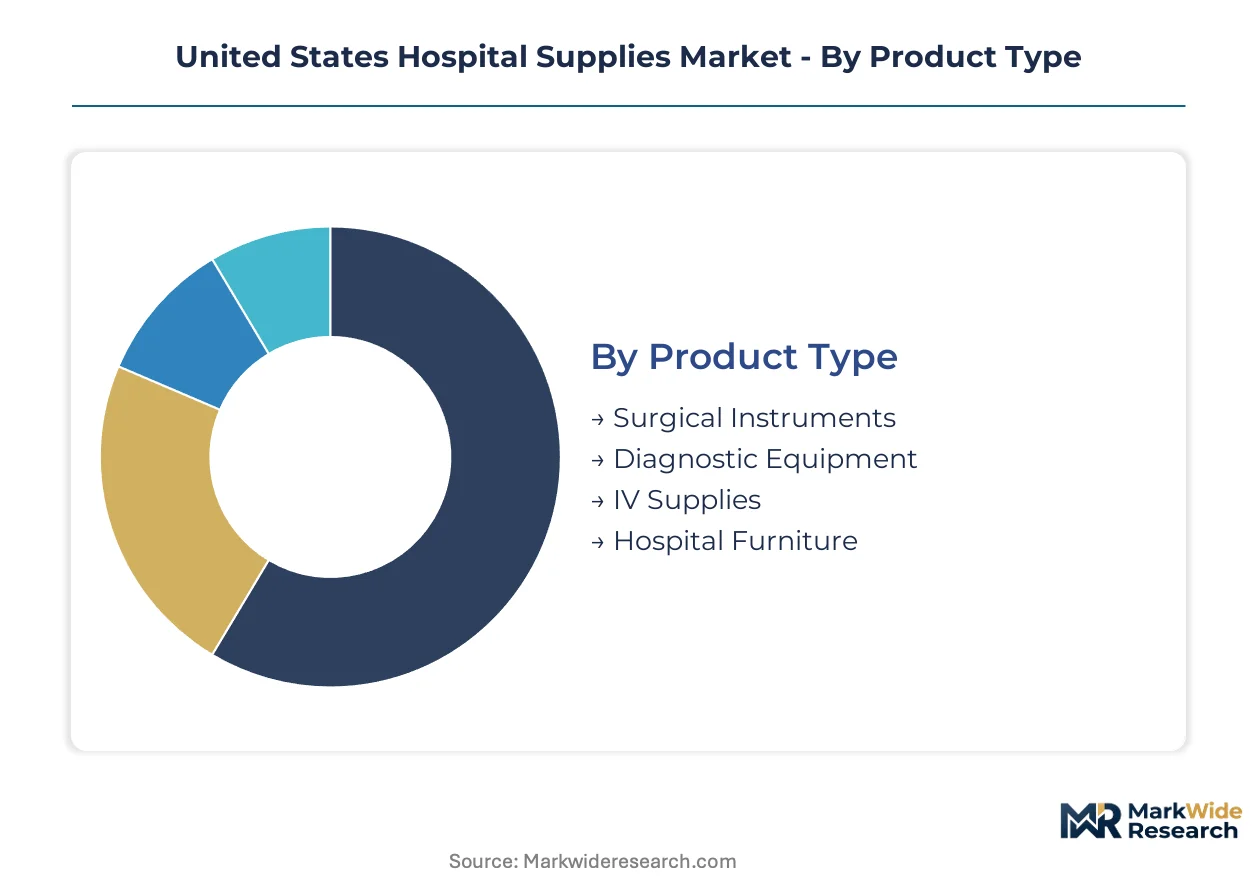
Hospital supplies segmentation reveals divergent margin architectures across product categories. Material composition and sterility requirements create distinct procurement workflows that distributors must navigate simultaneously.
Product Type:
Volume concentration clusters in consumable categories while premium margins concentrate in capital-intensive diagnostic platforms.
- Surgical Instruments:Forged from 400-series stainless steel alloys and medical-grade titanium, these instruments span precision-cut scalpels to robotic-assisted laparoscopic toolsets. Demand concentrates in academic medical centers across Texas and Massachusetts where robotic procedure volumes are climbing fastest. FDA 510(k) clearance timelines constrain iterative product launches for specialized electrosurgical devices.
- Diagnostic Equipment:Embedded sensor arrays and software-validated algorithms define this premium tier, spanning MRI-compatible patient monitors to AI-enhanced imaging workstations. Procurement is shifting toward integrated platform purchases in California health systems pursuing enterprise standardization. CMS reimbursement coding complexity elevates total cost of ownership calculations during vendor selection.
- IV Supplies:Polymer-based infusion sets and closed-system transfer devices manufactured under ISO 13485 protocols.
- Hospital Furniture:Electric patient beds and procedure chairs with antimicrobial surface coatings.
Mature deployment sits with Surgical Instruments. Newer deployment is concentrated in Diagnostic Equipment.
End User:
Procurement autonomy varies sharply by ownership structure and reimbursement exposure.
- Private Hospitals:Centralized purchasing consortia dominate procurement, with multi-hospital systems in Florida and Texas negotiating enterprise-wide formulary contracts. These entities prioritize consignment inventory models that transfer working capital burden to distributors while demanding real-time usage telemetry.
- Outpatient Clinics:Ambulatory surgical centers in Arizona and Nevada are migrating historically inpatient procedures, creating demand for compact, procedure-specific supply kits. This channel is expanding most quickly as CMS bundled payment incentives accelerate site-of-care migration.
- Public Hospitals:County and municipal facilities operating under constrained capital budgets.
- Rehabilitation Centers:Post-acute facilities with specialized durable medical equipment requirements.
Established infrastructure sits with Private Hospitals. Capacity expansion is concentrated in Outpatient Clinics.
Material:
Supply chain geography and sterilization compatibility drive material selection tradeoffs.
- Plastic:Medical-grade polypropylene and polycarbonate dominate single-use instrument categories, with polymer feedstock prices tracking petrochemical indices. Texas and Louisiana petrochemical corridors anchor domestic resin supply.
- Metal:Surgical instrument forging relies on specialized stainless alloys, with Zhejiang and Jiangsu provinces in China supplying precision-cut blanks. Geopolitical friction elevates supply interruption risk for domestic manufacturers lacking captive forging capacity.
- Glass:Borosilicate and soda-lime formulations for diagnostic containers and ampoules.
- Fabric:Non-woven polypropylene for surgical drapes and sterilization wraps.
Conventional supply sits with Metal. Substitution momentum is concentrated in Plastic.
Form:
Sterility assurance levels and reprocessing economics create distinct regulatory pathways.
- Disposable:Single-use polymer instruments eliminate reprocessing costs but elevate EPA medical waste disposal compliance burdens. Rural hospitals face disproportionate burden from limited licensed disposal infrastructure in Montana and Wyoming.
- Reusable:Stainless steel instrument sets requiring centralized sterilization facilities. Academic medical centers in Pennsylvania and Ohio maintain captive reprocessing departments with automated washer-disinfector tunnels.
- Sterilized:Pre-validated packaging with ISO 11135 ethylene oxide or gamma irradiation documentation.
- Non-Sterilized:Bulk-packaged components requiring terminal sterilization at point of use.
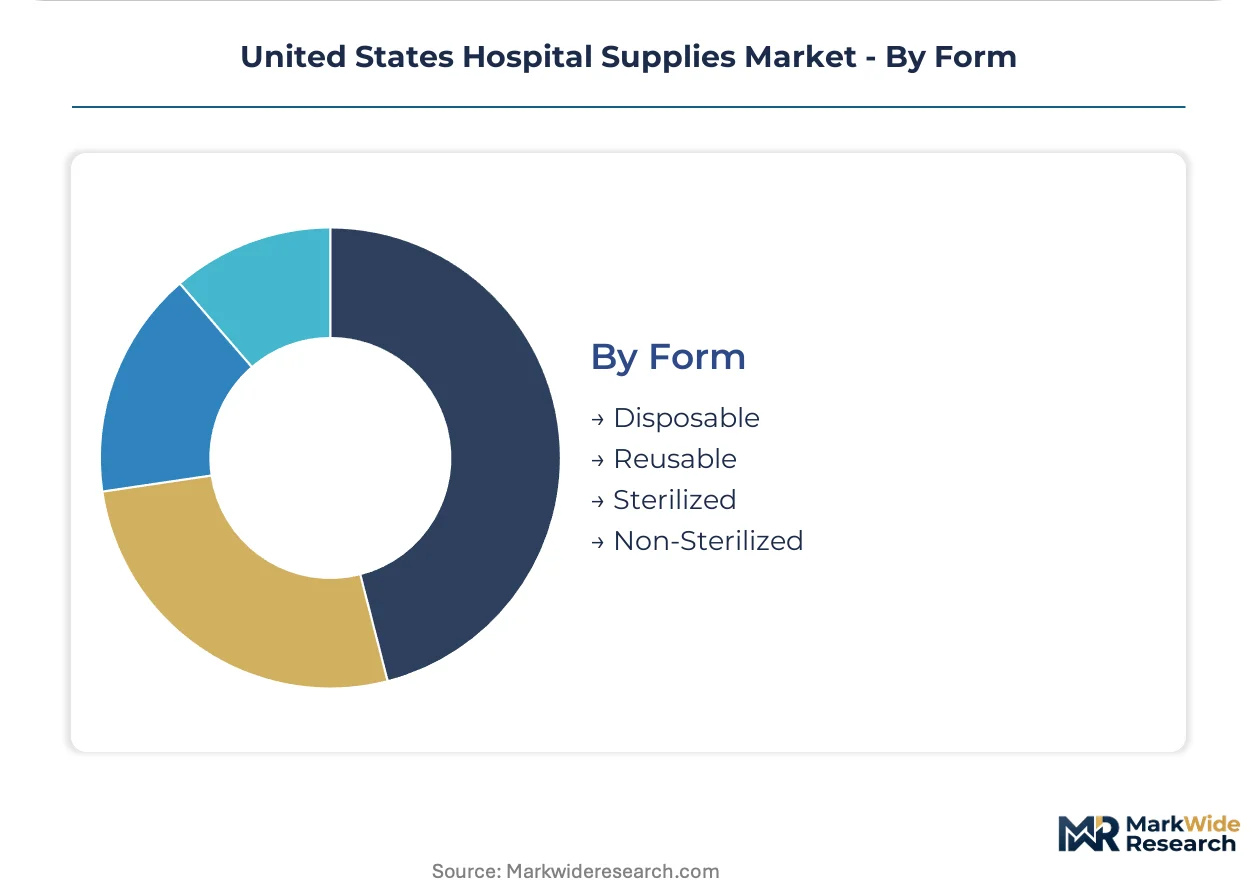
Regulatory complexity sits with Disposable. Cost optimization is concentrated in Reusable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth and Houston metro corridors anchor domestic hospital supply procurement velocity, with Texas health systems pre-negotiating multi-year consumable commitments before facility commissioning drives concentrated demand patterns.
Texas
Greenfield hospital development in Dallas-Fort Worth and Houston generates turnkey supply package demand. OSHA bloodborne pathogen regulations constrain material selection for single-use devices. The Texas Medical Center in Houston anchors procurement concentration for cardiovascular and orthopedic consumables.
California
Health systems in Los Angeles and San Francisco pursue enterprise standardization for diagnostic platforms. FDA cybersecurity guidance for connected devices elevates compliance burdens for IV pump manufacturers. The Bay Area corridor concentrates AI-enabled demand forecasting adoption.
Florida
Ambulatory surgical centers in Miami and Tampa migrate historically inpatient procedures, creating demand for compact supply kits. CMS bundled payment incentives accelerate site-of-care migration. The I-4 corridor between Orlando and Tampa anchors outpatient clinic expansion.
Massachusetts
Academic medical centers in Boston accelerate procurement of robotic-assisted surgical consumables. Joint Commission accreditation standards shape product development priorities for teaching hospitals. The Longwood Medical Area concentrates pilot programs for smart sensor-embedded instrument trays.
Pennsylvania
Health systems in Philadelphia and Pittsburgh maintain captive sterilization facilities for reusable instrument sets. EPA medical waste disposal mandates elevate compliance costs for rural facilities. The Pittsburgh corridor anchors automated washer-disinfector tunnel deployment.
United States Hospital Supplies Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the hospital supplies sector, with integrated manufacturers maintaining captive forging capacity while contract specialists rely on third-party resin supply. The vendor base clusters around three strategic archetypes: diversified distributors with national logistics networks, specialized manufacturers of cardiac and orthopedic consumables, and vertically integrated needle and syringe producers. Consolidation pressure intensifies as health system purchasing consortia compress vendor panels and demand real-time inventory telemetry.
Within the diversified distribution tier, Cardinal Health exemplifies network-scale competitive positioning. Among device specialists, Medtronic and Boston Scientific Corporation occupy positions anchored to procedure-specific consumable categories. Becton Dickinson represents vertical integration archetypes with in-house manufacturing of polymer-based single-use instruments.
| Leading Market Players |
|---|
| Cardinal Health |
| Boston Scientific Corporation |
| Medtronic |
| 3M |
| Abbott Laboratories |
| Becton Dickinson |
| Thermo Fisher Scientific |
| B. Braun |
| Baxter International |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up distributors now dominate the middle tier of hospital supply distribution, compressing working capital cycles and enforcing rigid price discipline on contract manufacturers who lack alternative channel access.
Pricing Analysis
Value-based pricing anchors on CMS reimbursement benchmarks and episode-based cost targets rather than unit list prices. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated devices from 510(k)-exempt alternatives and private-label imports. Pricing pressure stems from GPO volume aggregation in Texas and Florida health systems. Outpatient clinics exhibit highest price sensitivity due to thin procedure margins, while academic medical centers prioritize clinical outcome guarantees over per-unit cost.
Supply Chain Analysis
Workforce availability constraints in Zhejiang and Jiangsu provinces limit precision forging capacity for 400-series stainless surgical instruments. Supply draws from Chinese alloy mills, Texas petrochemical corridors for polypropylene resin, and domestic ISO 13485-certified cleanrooms for final assembly. Single-source vulnerability concentrates in Zhejiang forging houses subject to geopolitical friction. Distribution runs through Cardinal Health and regional GPO networks to hospital loading docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital supply distribution is consolidating into a winner-take-most structure where health system purchasing consortia are systematically eliminating subscale vendors unable to deliver real-time inventory telemetry.
For Market Incumbents: Deploy consignment inventory models to lock out challengers. Cardinal Health and McKesson have already captured Texas and Florida GPO contracts through working capital absorption. Biocompatibility testing backlog at ISO 10993 laboratories now bars mid-tier entrants from timely product launches. Incumbents should deepen backward integration into polymer compounding to offset resin price volatility. For New Entrants and Emerging Players: Ambulatory surgical centers in Arizona and Nevada represent the most penetrable channel. These facilities lack procurement sophistication of academic medical centers and tolerate shorter track records for procedure-specific supply kits. A direct sales force targeting ASC administrators bypasses GPO gatekeepers entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract manufacturers with captive ISO 13485 cleanrooms in the Southeast. Long-term viability hinges on FDA cybersecurity compliance infrastructure for connected devices. Watch for EPA medical waste disposal mandate enforcement as the inflection signal—rural hospital distress will force asset sales.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined premarket notification compresses time-to-market for polymer-based single-use instruments. |
| Hospital System Partnership | Enterprise-wide formulary standardization in Texas and Florida locks in multi-year consumable commitments. |
| Software Companion Development | AI-enabled demand forecasting modules reduce safety stock requirements for high-velocity IV supplies. |
| Reimbursement Strategy | CMS bundled payment alignment for cardiac and orthopedic procedures favors integrated supply pack vendors. |
| CE Marking Pathway | Dual-track FDA-EMA submissions open European academic medical center procurement channels. |
Research Methodology
FDA 510(k) databases, CMS Medicare cost reports, and GPO contract disclosure filings formed the secondary backbone of this analysis. Primary interviews with hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and sterile processing directors validated demand assumptions. Bottom-up product category sizing triangulated against top-down health system expenditure data.
Historical trendline analysis tracked surgical procedure volumes, hospital construction permitting, and polymer feedstock pricing across the projection horizon. Segmentation modeling spanned product type, end-user channel, material composition, and sterility assurance level. CAGRs derived from regression analysis of correlated drivers including CMS reimbursement rulemaking and FDA premarket review timelines.
Caveats apply where FDA cybersecurity guidance enforcement, EPA medical waste disposal mandate expansion, or Chinese alloy export restrictions could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Micro Vials Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Autoclaving Trays Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
North America Insulin Syringe Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Intraosseous Infusion Kits Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Medical and Industrial Gloves Market