
 Latin America Insulin Syringes Market | 2026-2036
Latin America Insulin Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Insulin Syringes Market Foresight
Preventive maintenance contracts and calibration service subscriptions for smart insulin delivery systems is decoupling hardware margins from recurring revenue streams across the Latin America insulin syringes landscape. Becton, Dickinson and Company leverages its regional distribution infrastructure to sustain institutional channel dominance in Brazilian teaching hospitals. Terumo Corporation anchors its competitive stance through specialized safety-engineered syringe manufacturing for Latin American ministries of health. B. Braun Melsungen AG differentiates via integrated diabetes management training programs bundled with device procurement.
Insulin syringes are precision medical instruments comprising a graduated barrel, plunger, and hypodermic needle, typically constructed from medical-grade polypropylene and stainless steel, designed for subcutaneous insulin administration with dose accuracy measured in international units. Safety-engineered syringes lead Latin American hospital procurement due to needlestick prevention mandates, while disposable syringes occupy the volume-dominant position in homecare channels across Mexico and Colombia. Smart insulin syringe technology represents the fastest-growing segment as connected dose-logging capabilities expand reimbursement eligibility in Brazil's public health system.
ANVISA in Brazil and COFEPRIS in Mexico enforce medical device registration and post-market surveillance protocols that directly determine syringe market access timelines and safety-feature requirements across Latin America. The Pan American Health Organization coordinates regional harmonization initiatives that reduce regulatory fragmentation for manufacturers seeking multi-country distribution. Stakeholders must monitor evolving reimbursement criteria for connected delivery devices as public health budgets recalibrate chronic disease spending priorities.
Market Dynamics
ANVISA's updated medical device vigilance rules are compressing product registration timelines while mandating safety-engineered features, forcing manufacturers to reconfigure supply chains around São Paulo's regulatory compliance infrastructure.
Growth Catalysts
- Homecare channel expansion:Brazil's Sistema Único de Saúde reimbursement expansion for ambulatory diabetes management is redirecting volume from hospital procurement networks toward retail pharmacy and direct-to-patient distribution.
- COFEPRIS fast-track registration:Mexico's streamlined equivalency pathway for devices already approved by FDA or Health Canada is accelerating market entry for safety-engineered syringe portfolios.
- Smart dose-logging integration:Bluetooth-enabled insulin delivery systems are capturing patient adherence data that qualifies for enhanced reimbursement tiers in Brazilian public health tenders.
Market Restraints
- Polypropylene resin import dependency:Medical-grade polymer supply concentrates through Port of Santos distributors, exposing margins to petrochemical price volatility and foreign exchange fluctuation.
- Needlestick prevention mandate compliance costs:ANVISA's safety-engineered syringe requirements impose retooling capital burdens on domestic manufacturers lacking integrated safety mechanism production lines.
- Reusable pen injector substitution:Insulin pen systems are capturing Type 2 diabetes volume in Colombian and Argentine private insurance channels, compressing disposable syringe growth ceilings.
Strategic Opportunities
- Central American corridor penetration:Guatemala and Panama's underdeveloped diabetes device distribution infrastructure presents first-mover consolidation potential for integrated logistics operators.
- Pan American Health Organization harmonization:Regional regulatory convergence initiatives are reducing multi-country registration duplication costs for manufacturers with Brazilian ANVISA approval.
- Subscription calibration services:Connected insulin delivery platforms enable recurring revenue capture through remote device monitoring and preventive maintenance contracts decoupled from hardware sales cycles.
Industry Challenges
- Biomedical engineering talent scarcity:Safety mechanism design and connected device firmware development capabilities concentrate in São Paulo and Mexico City, constraining regional manufacturing scale-up.
- Legacy hospital procurement system integration:Smart syringe data platforms face interoperability friction with existing electronic health record architectures in Brazilian public hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Insulin Syringes Market |
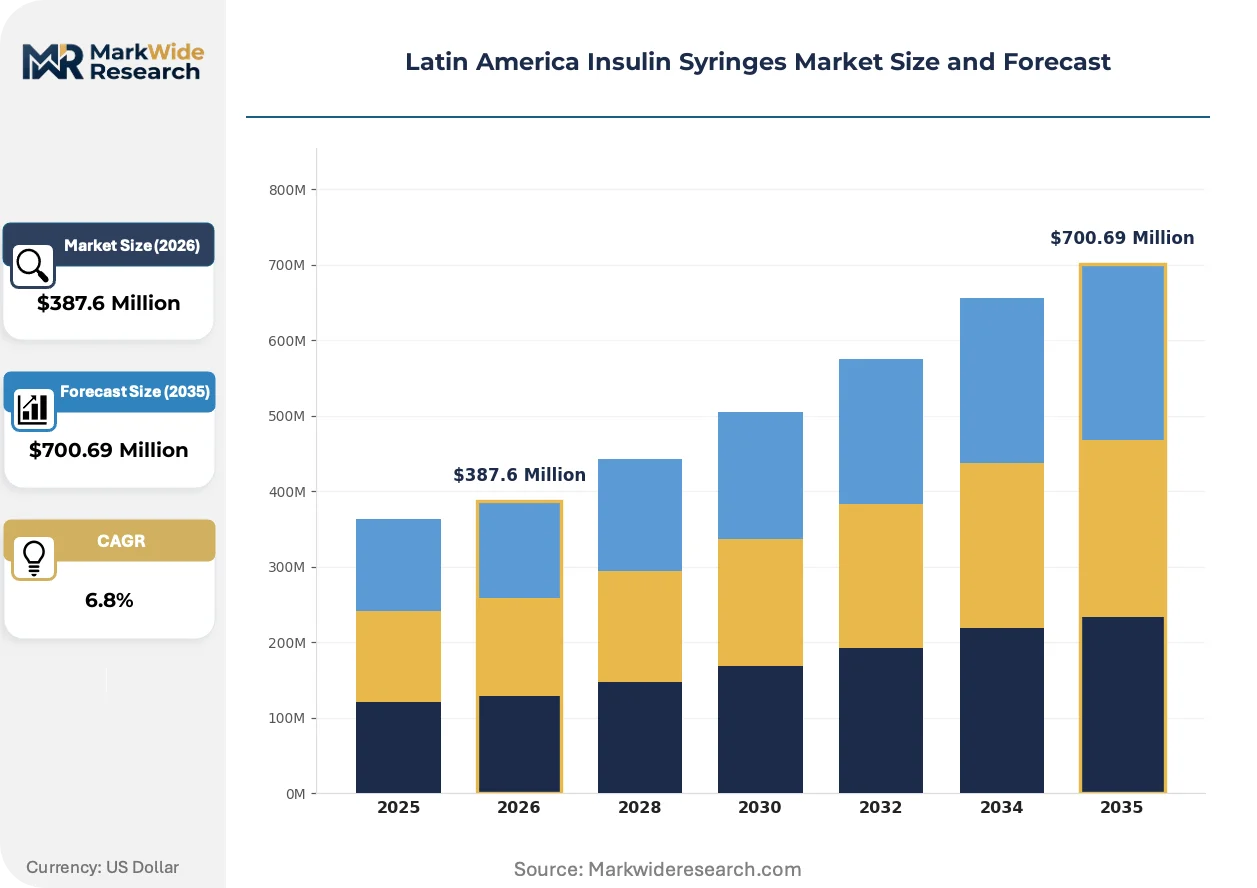
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Safety-engineered, Prefilled End User: Hospitals, Clinics, Homecare, Pharmacies Technology: Conventional, Smart Insulin, Auto-disable, Manual Distribution Channel: Online, Retail, Wholesale, Hospital Supply |
| Companies Covered | Becton, Dickinson and Company, B. Braun Melsungen AG, Hindustan Syringes & Medical Devices, Terumo Corporation, Nipro Corporation, Cardinal Health, Smiths Medical, Schott AG, Baxter International, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Insulin Syringes Market Shifts & Advancements
Connected dose-logging capabilities are absorbing capital allocation from traditional safety-engineered hardware, while regulatory data requirements and procurement digitization reshape competitive positioning across Latin American distribution channels.
Safety-engineered syringes with integrated needle retraction mechanisms are absorbing manufacturing investment as ANVISA's needlestick prevention mandates harden compliance deadlines. Brazilian teaching hospitals in São Paulo and Rio de Janeiro metropolitan corridors are adopting these devices at accelerated procurement cycles. The technology is absorbing margin pressure from commodity disposable syringes while enabling premium positioning in institutional tenders.
ANVISA's updated medical device vigilance rules now require real-time adverse event reporting through digital platforms, compressing post-market surveillance response windows. Manufacturers must maintain localized quality management systems with Portuguese-language documentation and domestic legal representation. Safety-engineered syringe portfolios face the steepest compliance adaptation costs as needlestick incident reporting thresholds tighten.
Hospital procurement consortia in southeastern Brazil are consolidating purchasing authority through São Paulo state tender platforms, reducing supplier fragmentation. Traditional distributor networks serving individual municipal hospitals face disintermediation as volume concentrates through centralized procurement. This pattern is most visible in Minas Gerais and Paraná state health systems, where regional purchasing cooperatives now dominate insulin delivery device acquisition.
Latin America Insulin Syringes Market Segmentation
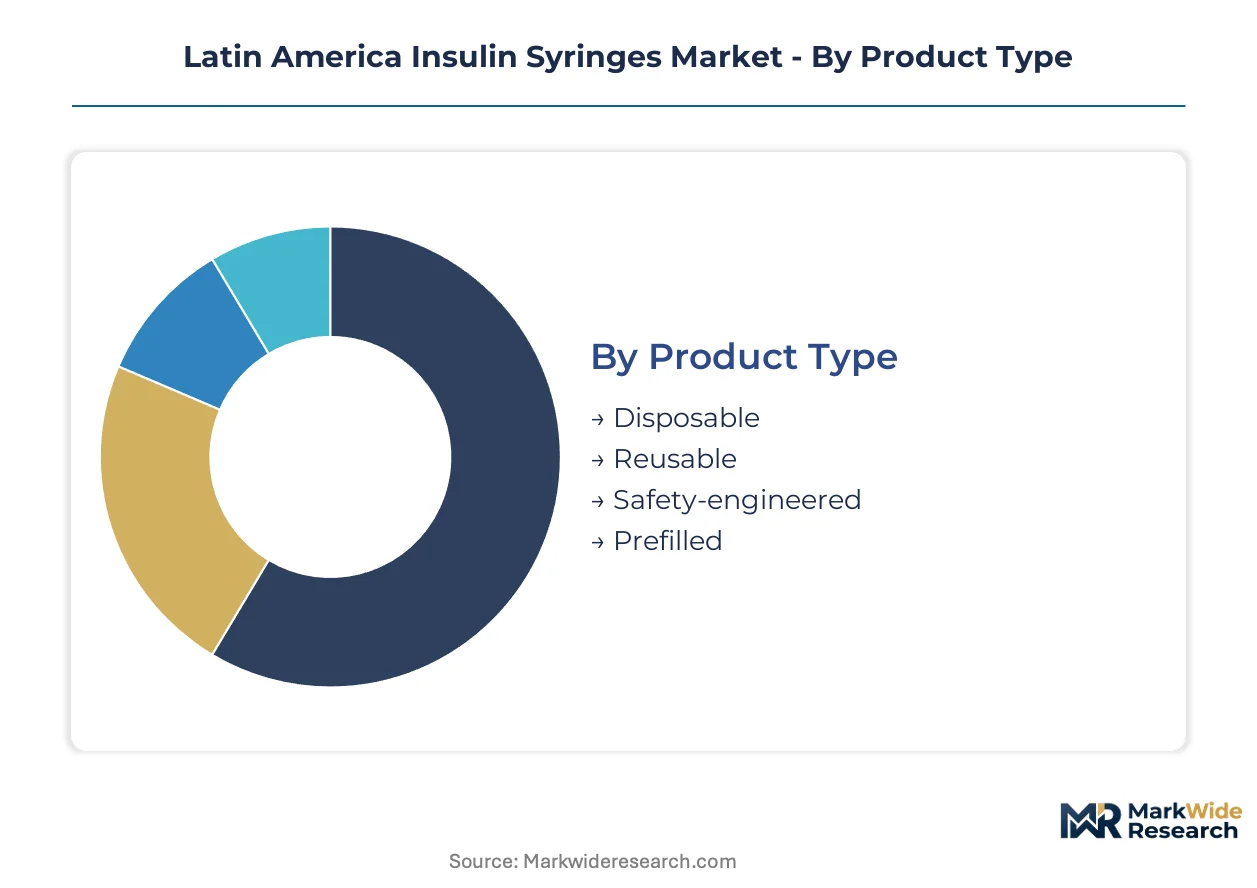
Insulin syringe segmentation in Latin America tracks divergent procurement logics across public health systems, private insurance networks, and direct-to-patient retail channels. Category boundaries are hardening as ANVISA's safety mandates and SUS reimbursement tiers reshape volume flows between institutional and homecare settings.
Product Type:
Standardization pressure from needlestick prevention regulations collides with customization demand for dose-precision features across this category.
- Safety-engineered:Integrated needle retraction mechanisms and shielding systems meet ANVISA's compulsory adverse event reporting thresholds. Brazilian teaching hospitals in São Paulo's metropolitan corridor are consolidating procurement around these devices as municipal tender platforms harden compliance deadlines.
- Disposable:Polypropylene barrel construction with fixed stainless steel needles dominates volume in Mexican retail pharmacy channels and Colombian homecare distribution. SUS reimbursement expansion for ambulatory diabetes management is redirecting hospital procurement toward patient-direct models.
- Reusable:Glass barrel syringes with detachable needles persist in specialized endocrinology clinics requiring dose calibration flexibility. Metal plunger construction enables sterilization cycles that appeal to cost-conscious private practice networks.
- Prefilled:Manufacturer-loaded insulin cartridges reduce dosing error rates in elderly patient populations. These devices are gaining traction in Brazilian private insurance channels where adherence monitoring justifies premium positioning.
Most installed capacity flows through Disposable. Expansion is steepest in Safety-engineered.
End User:
Procurement authority is migrating from individual facilities toward consolidated purchasing cooperatives across this category.
- Homecare:Patient-direct administration models are capturing volume as SUS expands reimbursement for ambulatory diabetes management. Retail pharmacy networks in Mexico and Brazil are building cold-chain logistics to serve this channel.
- Hospitals:Tertiary care institutions in Rio de Janeiro and Minas Gerais state systems are centralizing insulin delivery device acquisition through São Paulo-based tender platforms. ANVISA's digital adverse event reporting requirements are accelerating safety-engineered adoption.
- Clinics:Specialized endocrinology practices in Buenos Aires and Santiago maintain preference for reusable syringe systems enabling dose customization. These facilities operate outside consolidated procurement networks.
- Pharmacies:Community dispensaries serve as the primary touchpoint for Type 2 diabetes patients in Colombian and Peruvian markets. Counter staff counseling requirements are shaping packaging and instruction design.
Volume concentrates in Homecare. Margin capture is strongest in Hospitals.
Technology:
Connected device architectures are absorbing R&D investment while conventional manufacturing lines defend commodity volume positions.
- Smart Insulin:Bluetooth-enabled dose-logging systems transmit adherence data to Brazilian public health electronic records. These platforms qualify for enhanced reimbursement tiers in SUS tenders.
- Conventional:Graduated barrel designs without electronic components maintain cost advantages in price-sensitive Central American markets. Polypropylene resin sourcing through Port of Santos distributors shapes margin stability.
- Auto-disable:Single-use mechanisms prevent needle reuse in harm-reduction programs and resource-constrained settings. Pan American Health Organization procurement specifications favor these devices.
- Manual:Unassisted plunger operation persists in legacy hospital inventory systems and elderly patient populations resistant to digital interfaces.
Capital deployment favors Smart Insulin. Conventional retains the largest installed base.
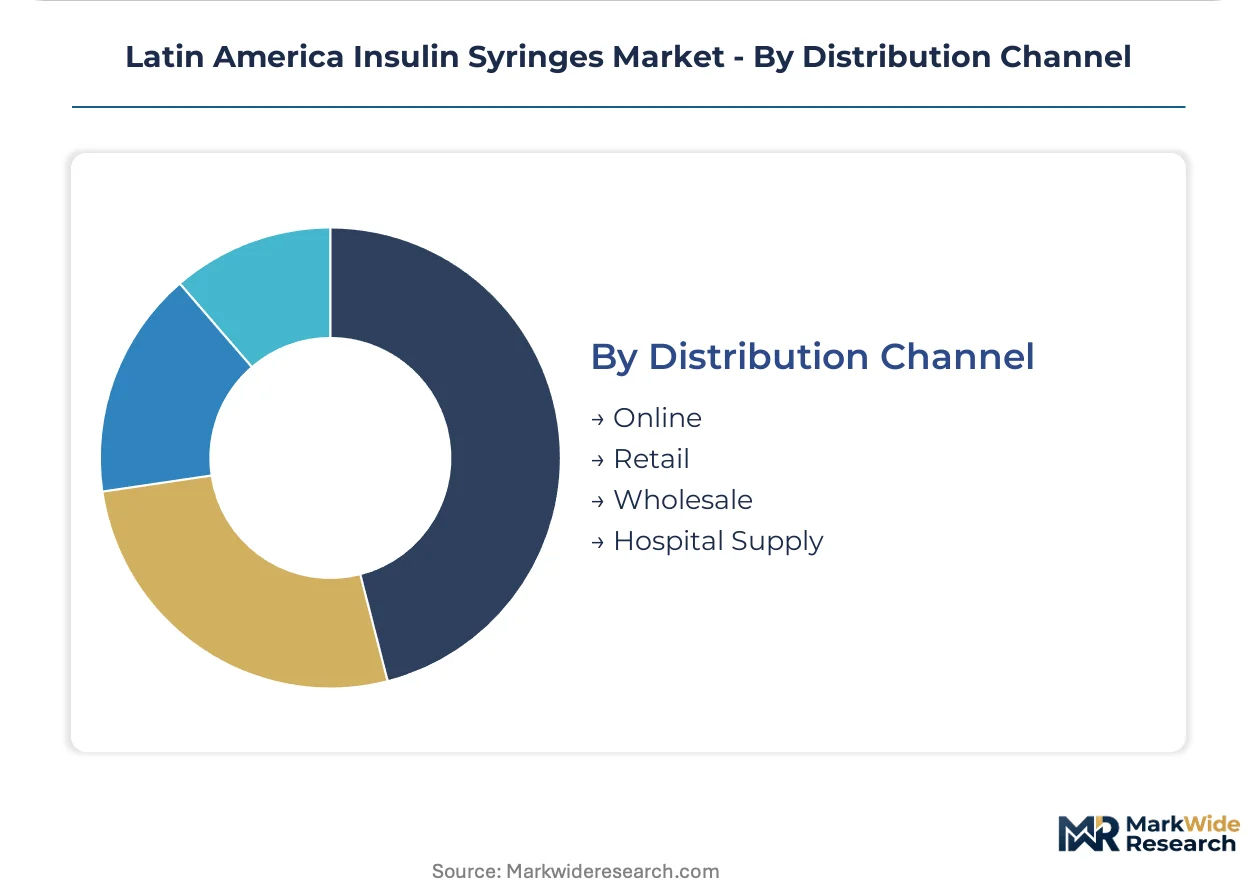
Distribution Channel:
Channel strategy bifurcates between centralized institutional procurement and fragmented last-mile patient access.
- Hospital Supply:Dedicated medical device distributors serving southeastern Brazilian state health systems are consolidating as purchasing cooperatives gain scale. These intermediaries manage ANVISA compliance documentation.
- Retail:Pharmacy chains in Mexico and Colombia are building diabetes device sections with cold-chain storage capacity. COFEPRIS fast-track registration accelerates product rotation.
- Wholesale:Regional distributors serving municipal hospital networks face disintermediation as volume concentrates through state-level tender platforms.
- Online:Direct-to-patient platforms are emerging in Brazilian metropolitan markets, though reimbursement complexity limits SUS patient participation.
Transaction volume concentrates in Hospital Supply. Growth velocity is highest in Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined medical device registration pathways. Brazil's ANVISA compliance infrastructure imposes higher fixed costs than Mexico's COFEPRIS equivalency route, creating divergent production location incentives across the regional landscape.
Brazil
Homecare channel expansion and Sistema Único de Saúde reimbursement reform are redirecting volume from hospital networks toward patient-direct distribution. ANVISA's updated vigilance rules mandate real-time adverse event reporting through digital platforms, compressing compliance response windows. São Paulo's metropolitan corridor anchors procurement consolidation through state-level tender platforms serving Minas Gerais and Paraná health systems.
Mexico
Retail pharmacy networks are building cold-chain logistics capacity to capture Type 2 diabetes patient volume in community settings. COFEPRIS fast-track registration for FDA- or Health Canada-approved devices accelerates safety-engineered syringe market entry timelines. Mexico City Metro and Nuevo León industrial clusters concentrate distribution infrastructure serving northern border states and Central American export channels.
Argentina
Private insurance channels are absorbing insulin pen system substitution, compressing disposable syringe growth ceilings in Buenos Aires metropolitan endocrinology practices. The national pharmaceutical regulator maintains distinct registration requirements from MERCOSUR harmonization initiatives. Córdoba and Rosario procurement networks operate outside consolidated purchasing cooperatives, preserving distributor fragmentation.
Colombia
Community pharmacy counter staff counseling requirements are shaping packaging and instruction design for Type 2 diabetes patient populations. The national health regulator enforces post-market surveillance protocols that determine syringe market access timelines. Bogotá and Medellín distribution networks serve as primary touchpoints for homecare channel expansion in Andean corridor markets.
Chile
Specialized endocrinology clinics in Santiago maintain preference for reusable syringe systems enabling dose calibration flexibility. The national medical device regulator coordinates with Pan American Health Organization harmonization initiatives to reduce registration duplication costs. Valparaíso port infrastructure supports polymer resin import dependency for domestic manufacturing operations.
Latin America Insulin Syringes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement favoring integrated safety-engineered portfolios while retail channels absorb commodity disposable volume. The vendor base concentrates around three strategic archetypes: multinational medical device conglomerates with regional distribution infrastructure, specialized safety-mechanism manufacturers serving ministry of health tenders, and integrated diabetes management providers bundling training with device procurement. Dominant competitive moves include strategic partnerships with state-level purchasing cooperatives and geographic expansion through Central American corridor penetration.
Within the multinational conglomerate tier, Becton, Dickinson and Company and Terumo Corporation exemplify divergent positioning archetypes, with the former anchoring institutional channel dominance and the latter specializing in ministry of health safety-engineered manufacturing requirements. B. Braun Melsungen AG occupies a position within the integrated services tier, representing the bundled diabetes management training model. These three entities collectively illustrate the competitive spectrum spanning hardware-centric, safety-specialized, and service-integrated market approaches.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Hindustan Syringes & Medical Devices |
| Terumo Corporation |
| Nipro Corporation |
| Cardinal Health |
| Smiths Medical |
| Schott AG |
| Baxter International |
| Others |
Supply & Pricing Matrix
Medical-grade polypropylene resin pricing volatility transmits directly through three-tier pricing structures across premium, standard, and economy levels of Latin American insulin syringe procurement. Port of Santos distributors anchor upstream cost exposure for Brazilian manufacturers while Mexican COFEPRIS equivalency pathways enable faster margin recovery for importers bypassing lengthy registration timelines.
Pricing Analysis
Distributor margins compress as hospital supply consortia in São Paulo and Rio de Janeiro consolidate purchasing authority through state-level tender platforms. Three-tier pricing separates safety-engineered devices with integrated needle retraction from conventional disposable syringes and commodity manual units. Pricing pressure stems from ANVISA's retooling mandates for domestic manufacturers lacking integrated safety mechanism production lines. Retail pharmacy channels in Mexico exhibit highest price sensitivity as patient-direct models expand, while Brazilian teaching hospitals demonstrate lowest sensitivity due to bundled training and compliance documentation requirements.
Supply Chain Analysis
Dual-sourcing requirements from Brazilian state health systems mandate multi-supplier qualification for polypropylene resin and stainless steel needle components. Manufacturing concentration centers on China, South Korea, and domestic Brazilian operations for medical-grade polymer conversion. Raw material dependencies include polypropylene resin, 304-grade stainless steel, and medical-grade silicone lubricants. Single-source vulnerability concentrates through Port of Santos petrochemical distributors exposed to foreign exchange fluctuation. Distribution runs through dedicated medical device distributors managing ANVISA compliance documentation for southeastern Brazilian hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's needlestick prevention mandate functions as a regulatory compounder, accelerating safety-engineered syringe demand while compressing registration timelines for compliant manufacturers.
For Market Incumbents: Anchor institutional channel dominance through exclusive partnerships with São Paulo and Minas Gerais state purchasing cooperatives. Deepen backward integration into safety mechanism production to deflect retooling capital burdens from domestic contract manufacturers. Secure long-term polypropylene supply agreements with Port of Santos distributors to stabilize margin exposure against petrochemical volatility. For New Entrants and Emerging Players: Begin with Guatemala and Panama's underdeveloped diabetes device distribution infrastructure where first-mover logistics consolidation remains achievable. Target Central American corridor penetration through COFEPRIS equivalency pathways already validated for Mexican market entry. Deploy direct-to-patient online platforms in Brazilian metropolitan markets, navigating SUS reimbursement complexity through private insurance channel partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where biomedical engineering talent scarcity constrains regional manufacturing scale-up for connected device firmware development. Long-term viability favors acquisition targets with integrated safety-engineered manufacturing capabilities and existing ANVISA quality management systems. Monitor Pan American Health Organization harmonization progress as inflection indicator for multi-country registration cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Safety-Engineered Compliance Investment | Accelerates hospital procurement eligibility in São Paulo metropolitan tender platforms. |
| COFEPRIS Fast-Track Registration Pathway | Reduces market entry timelines for FDA-approved safety syringe portfolios in Mexico. |
| State Purchasing Cooperative Partnership | Secures volume allocation through Minas Gerais and Paraná centralized procurement networks. |
| Connected Dose-Logging Platform Development | Qualifies for enhanced SUS reimbursement tiers in Brazilian public health tenders. |
| Central American Distribution Infrastructure Buildout | Captures first-mover consolidation potential in Guatemala and Panama underdeveloped channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and ANVISA regulatory affairs specialists with secondary validation. Secondary sources included ANVISA medical device registration databases, COFEPRIS equivalency pathway filings, Pan American Health Organization procurement specifications, and Brazilian SUS reimbursement tier documentation. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, technology, and distribution channel dimensions.
Segment-weighting approaches distributed volume and value projections across safety-engineered, disposable, reusable, and prefilled product categories, with technology tiers modeled separately for smart insulin, conventional, auto-disable, and manual systems. CAGRs were derived from regression analysis of historical procurement data and forward-looking reimbursement policy trajectories. Forecast inputs incorporated ANVISA vigilance rule implementation schedules and COFEPRIS registration velocity metrics.
Several conditions sit outside the modeled scope, including specific polymer resin price trajectories, foreign exchange rate assumptions, and unannounced regulatory harmonization accelerations. Deviation in ANVISA adverse event reporting threshold tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Ablation Devices Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Oxygenator Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Bathroom and Toilet Assist Devices Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Cardiac Pacemakers Market
Medical Devices
Global Amniocentesis Needle Market
Medical Devices
Infant Incubator Market
Medical Devices
Cyclotron Market
Medical Devices
Europe Otoscope Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Global Monopolar Electrosurgery Market