
 Global Veress Needle Market | 2026-2036
Global Veress Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veress Needle Market Foresight
Disposable needle subscription programs for high-volume surgical centers is hardening as a recurring revenue layer. Medtronic leverages its hospital GPO contracts to anchor this service model. Johnson & Johnson competes through bundled laparoscopy kits that incorporate Veress needle replenishment. B. Braun Melsungen AG differentiates by offering sterilization logistics alongside disposable supply agreements.
A Veress needle is a spring-loaded or shielded puncture instrument designed to establish pneumoperitoneum through controlled fascial entry, typically constructed from surgical stainless steel with a hollow bore and blunt-tipped safety obturator that retracts upon tissue resistance. The device serves to insufflate the abdominal cavity with carbon dioxide prior to minimally invasive laparoscopic intervention. Disposable product types command premium pricing in North American and Western European procurement channels where single-use mandates dominate infection control protocols. Safety mechanism technology absorbs disproportionate R&D investment as FDA and MDR compliance costs escalate for mechanical fail-safe designs. Reusable segments retain footholds in cost-constrained hospital systems across India and Brazil despite accelerating disposable conversion in tertiary settings.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and market access barriers for manufacturers seeking commercial distribution in the United States and European Economic Area. ISO 13485 quality management standards govern manufacturing audits that determine supplier eligibility for Japanese PMDA registration and South Korean MFDS approval. Stakeholders must monitor evolving sterilization validation protocols and biocompatibility testing benchmarks that determine which needle designs achieve regulatory authorization across multiple jurisdictions.
Market Dynamics
The Veress needle market pivots on the tension between disposable single-use mandates and sterilization infrastructure economics, with tertiary hospital procurement committees now weighting total cost of ownership over unit price in vendor selection.
Growth Catalysts
- Laparoscopic surgery volume:Minimally invasive procedures in Germany, Japan, and the United States generate consistent demand for pneumoperitoneum establishment tools.
- EU MDR Class IIa certification:Stricter biocompatibility and mechanical fail-safe requirements accelerate replacement cycles for legacy needle inventories.
- Carbon dioxide insufflation protocols:Standardized pressure-controlled abdominal cavity preparation in tertiary surgical suites drives instrument standardization.
Market Restraints
- Surgical stainless steel price volatility:Raw material cost swings compress margin buffers for manufacturers of reusable needle variants.
- Supply concentration in Western Europe:German and Swiss sterilization equipment vendors create single-source dependencies for reusable segment logistics.
- Mechanical safety obturator complexity:Spring-loaded shield mechanisms require precision manufacturing that limits qualified supplier pools.
Strategic Opportunities
- Brazilian tertiary hospital conversion:Disposable penetration remains below Western European benchmarks, creating whitespace for infection control protocol upgrades.
- Subscription replenishment models:High-volume surgical centers in the United States are piloting automated reorder systems tied to case volume forecasting.
- ISO 13485 harmonization:Unified quality management standards streamline multi-jurisdiction registration for Japanese PMDA and South Korean MFDS pathways.
Industry Challenges
- EU MDR technical documentation:Clinical evaluation report requirements extend certification timelines by 12-18 months for mechanical safety designs.
- Legacy sterilization asset stranding:Hospital systems with sunk capital in autoclave infrastructure resist full conversion to disposable workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veress Needle Market |
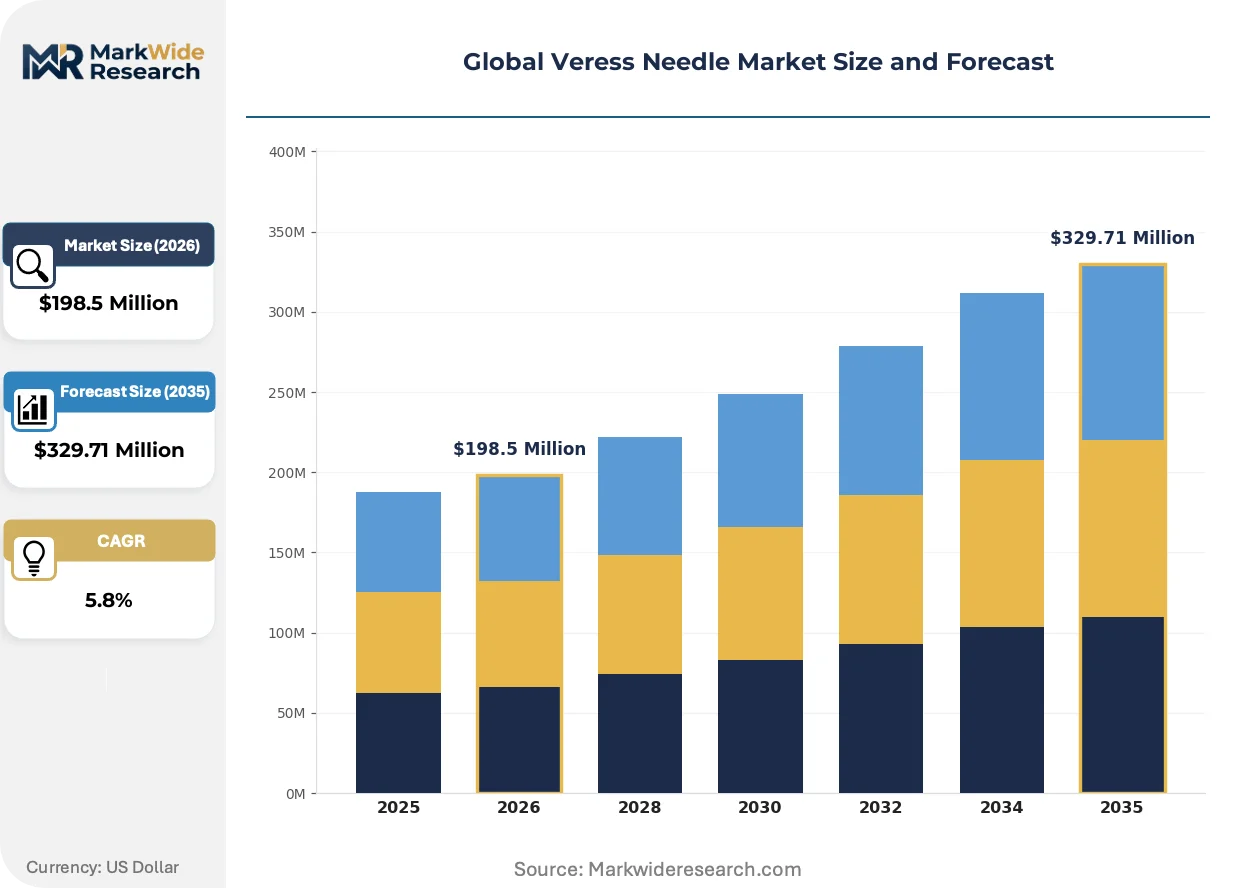
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $329.71 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
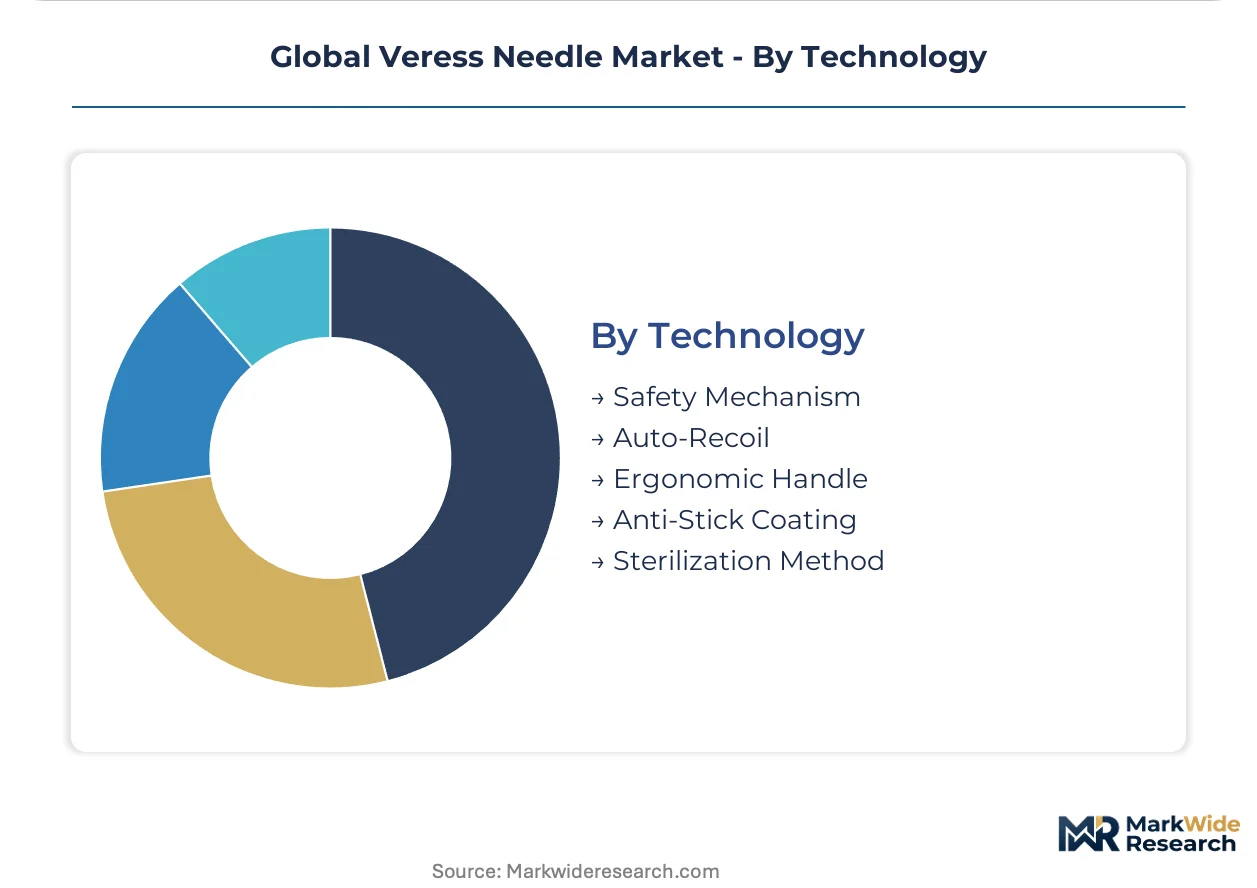
| Segmentation | Product Type: Spring-Loaded, Non-Spring, Shielded, Disposable, Reusable Application: Laparoscopy, Gynecology, Urology, General Surgery, Thoracic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Centers Technology: Safety Mechanism, Auto-Recoil, Ergonomic Handle, Anti-Stick Coating, Sterilization Method |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun Melsungen AG, CONMED Corporation, Teleflex Incorporated, Olympus Corporation, Stryker Corporation, Applied Medical Resources Corporation, Karl Storz SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veress Needle Market Shifts & Advancements
Shielded-tip safety mechanisms are absorbing disproportionate engineering investment as regulators on three continents tighten mechanical fail-safe standards. Manufacturers now compete on obturator reliability rather than price alone.
Blunt-tipped safety obturators with pressure-sensitive retraction are expanding into outpatient surgical centers previously served by reusable instruments. Ambulatory facilities in the United States and Germany adopt these devices to eliminate sterilization overhead. The technology is expanding into cost-sensitive settings by reducing per-procedure labor and capital requirements.
EU MDR Class IIa designation now mandates clinical evidence for Veress needle mechanical safety features, not just biocompatibility. Manufacturers must submit post-market surveillance data on obturator failure rates. German notified bodies enforce this most stringently, delaying market access for designs lacking sufficient clinical follow-up.
Hospital procurement committees now bundle Veress needle replenishment into broader laparoscopy kit contracts rather than sourcing standalone. United States GPOs consolidate vendor relationships through multi-instrument agreements. Tertiary systems in Japan and Germany replicate this model to reduce administrative burden and secure volume pricing.
Global Veress Needle Market Segmentation
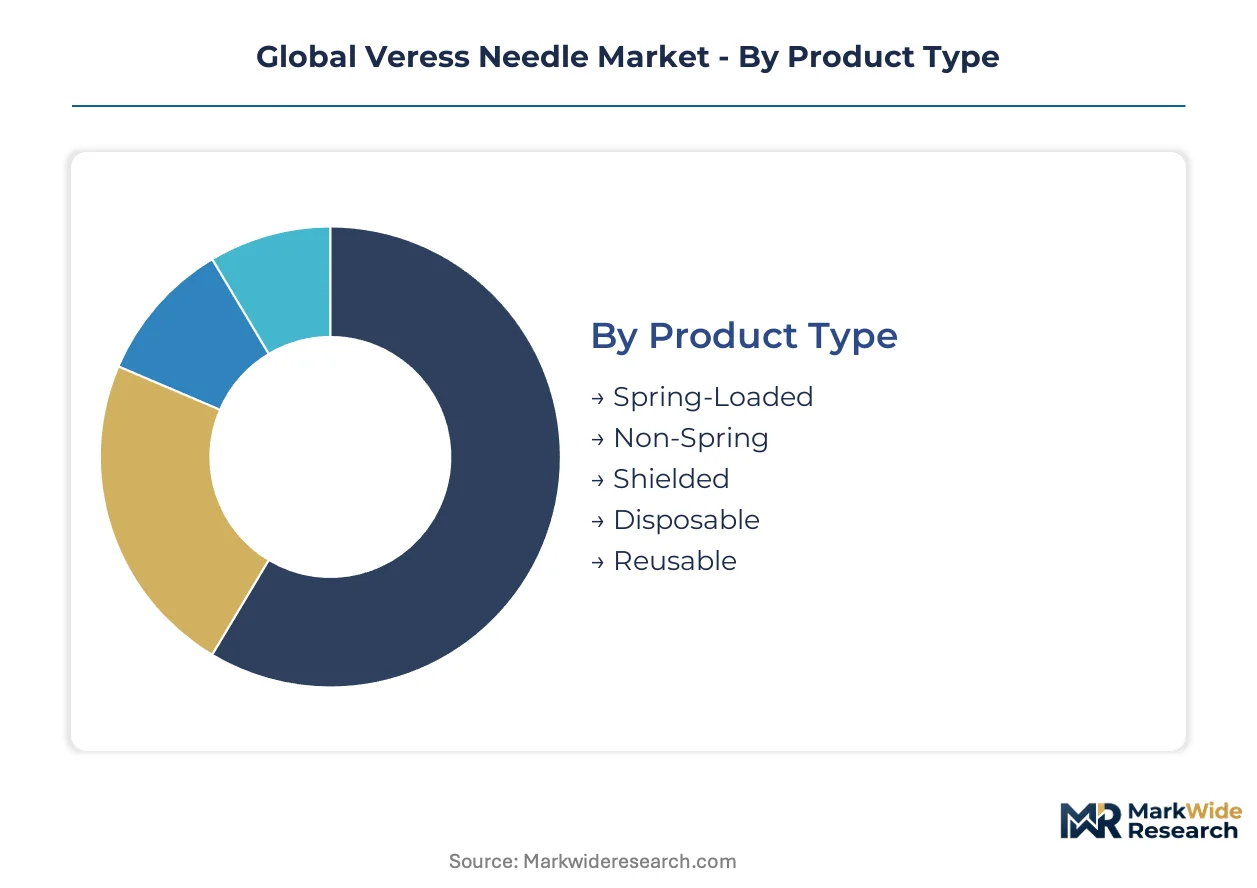
Veress needle procurement patterns diverge sharply across product configurations, clinical applications, and institutional settings. Understanding these fault lines reveals where pricing power concentrates and which technology transitions threaten incumbent positions.
Product Type:
Supply concentration for precision-manufactured safety mechanisms has tilted procurement leverage toward vendors with captive spring-loaded production capabilities.
- Spring-Loaded:These devices incorporate retractable obturator mechanisms that deploy upon fascial penetration, manufactured from surgical-grade stainless steel with calibrated spring constants. Demand concentrates in German and United States tertiary hospitals where EU MDR and FDA mandates enforce mechanical fail-safe compliance. Replacement cycles accelerate as legacy inventories face regulatory obsolescence.
- Disposable:Single-use polymer and metal assemblies eliminate sterilization logistics entirely. North American procurement channels enforce single-use protocols through infection control committees, while Brazilian and Indian cost-constrained systems resist conversion despite tertiary hospital adoption. Premium pricing persists where GPO consolidation limits vendor competition.
- Shielded:External sleeve mechanisms protect against inadvertent stick injuries during insertion. Japanese PMDA registration pathways favor these designs for their documented mechanical reliability.
- Non-Spring:Fixed-obturator designs rely on manual technique rather than automated safety deployment. Cost-sensitive hospital systems in Brazil retain these instruments where sterilization infrastructure amortization delays disposable conversion.
- Reusable:Surgical stainless steel constructions withstand repeated autoclave cycles. German sterilization equipment vendors anchor supply chains for these segments, creating geographic dependencies.
Today's leader: Disposable. Tomorrow's challenger: Spring-Loaded.
Application:
Procedure volume distribution across surgical specialties determines inventory turnover rates and contract bundling opportunities.
- Laparoscopy:Minimally invasive abdominal procedures constitute the core demand driver, with carbon dioxide insufflation protocols standardized across United States, German, and Japanese surgical suites. Tertiary hospital procurement committees consolidate Veress needle replenishment within broader laparoscopy kit agreements.
- Gynecology:Hysteroscopic and diagnostic procedures employ smaller-gauge variants with modified insertion angles. Ambulatory surgical centers in Germany adopt shielded-tip configurations to eliminate sterilization overhead.
- General Surgery:Cholecystectomy and appendectomy volumes sustain consistent instrument consumption across hospital tiers.
- Urology:Retroperitoneal access procedures require specialized needle lengths and tip geometries.
- Thoracic Surgery:Pleural cavity insufflation applications remain specialized, with limited vendor competition.
Procurement committees weight laparoscopy volume heaviest; gynecology ambulatory conversion offers the steepest expansion trajectory.
End User:
Capital intensity and sterilization infrastructure economics segment institutional willingness to absorb disposable premium pricing.
- Hospitals:Tertiary surgical suites in the United States, Germany, and Japan drive volume through high laparoscopy caseloads. Total cost-of-ownership calculations now dominate procurement committee vendor selection, favoring subscription replenishment models over spot purchasing.
- Ambulatory Surgical Centers:United States outpatient facilities eliminate sterilization capital entirely, adopting disposable spring-loaded designs to reduce per-procedure labor requirements. German freestanding surgical centers replicate this model.
- Specialty Clinics:Gynecology-focused practices in Japan prefer shielded-tip configurations for diagnostic hysteroscopy.
- Diagnostic Centers:Lower procedural volumes sustain reusable instrument economics where autoclave infrastructure exists.
Hospital GPO consolidation tightens vendor access; ambulatory centers offer whitespace for automated replenishment pilots.
Technology:
Regulatory compliance costs for mechanical safety features have concentrated R&D investment among manufacturers with established clinical evidence portfolios.
- Safety Mechanism:FDA 510(k) and EU MDR Class IIa certification requirements now mandate post-market surveillance data on obturator failure rates. German notified bodies enforce this most stringently, extending certification timelines for designs lacking sufficient clinical follow-up.
- Auto-Recoil:Pressure-sensitive retraction systems expand into outpatient settings previously served by reusable instruments. These mechanisms reduce per-procedure technical training requirements.
- Ergonomic Handle:Surgeon-specific grip configurations address repetitive strain concerns in high-volume Japanese surgical centers.
- Anti-Stick Coating:Surface treatments reduce tissue adhesion during insertion and withdrawal.
- Sterilization Method:Ethylene oxide and autoclave validation protocols determine reusable segment logistics compatibility.
Safety mechanism certification absorbs disproportionate investment; auto-recoil configurations gain share fastest in ambulatory conversion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's tertiary hospital density exceeds Japan's surgical suite concentration, yet both markets enforce stricter mechanical safety mandates than cost-sensitive systems in Brazil or India.
United States
Ambulatory surgical centers in Florida and Texas drive disposable spring-loaded adoption to eliminate sterilization overhead. FDA 510(k) clearance timelines extend for mechanical safety designs lacking post-market surveillance data. Hospital GPO consolidation in the Midwest tightens vendor access through multi-instrument laparoscopy kit contracts.
Germany
Tertiary surgical suites in Bavaria and North Rhine-Westphalia generate consistent pneumoperitoneum instrument demand for laparoscopic procedures. EU MDR Class IIa certification enforced by German notified bodies accelerates replacement cycles for legacy needle inventories. Stuttgart-based sterilization equipment vendors anchor reusable segment supply chains.
Japan
High-volume surgical centers in Tokyo and Osaka prefer shielded-tip configurations for documented mechanical reliability. PMDA registration pathways favor designs with ISO 13485 quality management certification. Kanto region procurement committees bundle Veress needle replenishment within broader minimally invasive surgery agreements.
Brazil
Cost-constrained hospital systems in São Paulo and Minas Gerais retain reusable instrument economics despite tertiary hospital disposable conversion. ANVISA regulatory pathways lag EU MDR stringency, delaying mechanical safety mandate adoption. Southern region sterilization infrastructure amortization slows single-use protocol penetration.
India
Metropolitan tertiary centers in Maharashtra and Karnataka pilot disposable conversion for infection control protocol alignment. CDSCO medical device registration requirements intensify for imported mechanical safety designs. Delhi-NCR procurement committees weight total cost-of-ownership calculations in vendor selection.
Global Veress Needle Market Competitive Landscape
Top-tier vendors anchor hospital GPO contracts, while mid-cap specialists compete through sterilization logistics and regional regulatory expertise. The market structure concentrates procurement leverage among manufacturers with captive spring-loaded production capabilities and established clinical evidence portfolios. Two strategic archetypes dominate: diversified medical technology conglomerates leveraging bundled instrument agreements, and focused surgical instrument specialists competing on compliance velocity. Competitive moves center on subscription replenishment model deployment and backward integration into precision spring manufacturing.
Among diversified medical technology conglomerates, Medtronic, Johnson & Johnson, and B. Braun Melsungen AG exemplify distinct competitive positioning. Medtronic represents the GPO-anchored service model archetype. Johnson & Johnson occupies a position within bundled laparoscopy kit competition. B. Braun Melsungen AG exemplifies the sterilization logistics differentiation vector. These three entities collectively illustrate how scale, integration depth, and service layering segment competitive terrain without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| CONMED Corporation |
| Teleflex Incorporated |
| Olympus Corporation |
| Stryker Corporation |
| Applied Medical Resources Corporation |
| Karl Storz SE & Co. KG |
| Others |
Supply & Pricing Matrix
Tertiary hospital procurement committees in Germany and the United States command subscription-based pricing leverage through consolidated GPO contracts, compressing spot-market premiums for standalone Veress needle purchases.
Pricing Analysis
Capacity additions in precision spring manufacturing across Switzerland and Germany are reshaping price floors for safety mechanism components. Three-tier pricing structure across premium, standard, and economy levels segments by FDA 510(k) clearance tier and ISO 13485 certification status. Cost compression in the reusable segment intensifies because surgical stainless steel price volatility erodes margin buffers. Ambulatory surgical centers in the United States exhibit highest price sensitivity; Japanese tertiary hospitals demonstrate lowest sensitivity due to PMDA-mandated reliability premiums.
Supply Chain Analysis
ISO 13485 certification gates supplier eligibility for Japanese PMDA and South Korean MFDS registration pathways, concentrating qualified manufacturing in Germany, Switzerland, and the United States. Precision spring mechanisms, surgical-grade stainless steel, and polymer sterilization barriers anchor raw material dependencies. Single-source vulnerability concentrates in German sterilization equipment vendors serving reusable segment logistics. Distribution runs through hospital GPO consolidated procurement channels and ambulatory surgical center direct agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Veress needle market compounds regulatory value as EU MDR Class IIa clinical evaluation requirements extend certification timelines and accelerate replacement demand for legacy inventories.
For Market Incumbents: Acquire captive spring-loaded manufacturing capabilities to secure safety mechanism supply autonomy against precision component bottlenecks. Deepen backward integration into surgical stainless steel sourcing to buffer raw material volatility. Consolidate GPO contract anchoring through bundled laparoscopy kit expansion. For New Entrants and Emerging Players: Brazilian tertiary hospitals converting from reusable protocols represent the most penetrable buyer archetype for infection control protocol upgrades. Target ANVISA regulatory pathway expertise as a differentiated market access capability. Deploy sterilization logistics partnerships to offset disposable premium pricing resistance in cost-constrained systems. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking mechanical safety design portfolios and clinical evidence databases. Mid-cap specialists with EU MDR technical documentation capabilities and German notified body relationships offer prime acquisition profiles. Monitor obturator failure rate post-market surveillance data releases as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | German notified body relationships accelerate Class IIa certification timelines for mechanical safety designs. |
| Spring-Loaded Manufacturing Backward Integration | Captive precision component production insulates against qualified supplier pool constraints. |
| Hospital GPO Contract Consolidation | Multi-instrument laparoscopy kit agreements reduce administrative burden and secure volume pricing. |
| Brazilian Tertiary Hospital Partnership | ANVISA pathway expertise enables first-mover advantage in disposable conversion whitespace. |
| Post-Market Surveillance Data Infrastructure | Obturator failure rate documentation satisfies PMDA and FDA mechanical reliability mandates. |
Research Methodology
Direct dialogue with hospital procurement managers, GPO contracts specialists, biomedical engineers, and sterilization logistics coordinators grounded qualitative insights. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, PMDA registration filings, and hospital procurement contract records. Bottom-up and top-down triangulation cross-checked manufacturer capacity disclosures against surgical procedure volume estimates.
Bottom-up modeling aggregated segment-level demand across product type, application, end user, and technology dimensions. Top-down validation calibrated aggregate market expansion against laparoscopic surgery volume trajectories in Germany, the United States, and Japan. CAGRs derived from procedure growth elasticity to instrument consumption ratios and regulatory replacement cycle acceleration effects.
Underlying measurement precision varies by segment; disposable product types carry tighter precision than reusable segments due to consolidated procurement data availability. Forecasts reflect assumptions about EU MDR enforcement consistency and ANVISA pathway convergence timelines. A model refresh is warranted upon material change in German notified body certification backlog durations or surgical stainless steel price volatility regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygen Concentrators Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
Infusion Pump Market
Medical Devices
United Kingdom Anesthesia Devices Market
Medical Devices
Smart Pills Drug Delivery Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Hemoconcentrators Market
Medical Devices
Submucosal Injections Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Intubation Accessories Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Breathing Circuits Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Digital X-Ray Devices Market