
 Surgical and Examination Gloves Market | 2026-2036
Surgical and Examination Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical and Examination Gloves Market Analysis
REACH is restructuring the cost-of-entry calculus for European glove imports by mandating full chemical disclosure and restricting certain accelerators in nitrile formulations. Hartalega Holdings Berhad leverages its fully automated production lines to sustain cost leadership in nitrile examination gloves. Kossan Rubber Industries Bhd anchors its position through backward integration into rubber compounding and chemical manufacturing. Ansell Ltd differentiates via specialized surgical portfolios targeting orthopedic and microsurgery segments.
Surgical and examination gloves are personal protective barriers manufactured from latex, nitrile, vinyl, or polyethylene, typically ranging from 0.05 mm to 0.15 mm in thickness, designed to prevent pathogen transmission between healthcare workers and patients during invasive or diagnostic procedures. The nitrile material segment leads value contribution due to latex allergy prevalence and superior puncture resistance, while the sterile product category commands premium positioning in operating theaters. Medical grade classification dominates procurement volumes as hospital infection control protocols mandate ASTM D3578 or EN 455 compliance for all patient-contact applications.
The FDA enforces Quality System Regulation and biocompatibility testing under ISO 10993 for all surgical glove submissions, while the EMA through its MDR framework now requires clinical evaluation reports for Class I sterile devices. Malaysia's Department of Standards administers MS ISO 13485 certification as a de facto export license requirement for glove manufacturers serving regulated markets. Stakeholders must monitor accelerator-free nitrile formulations and single-use plastic directives as the next wave of product redesign mandates.
Market Dynamics
Malaysia's production concentration is creating supply vulnerability as three manufacturers control over half of nitrile capacity, while REACH chemical disclosure mandates force reformulation investments across European-bound shipments.
Growth Catalysts
- Outpatient Procedure Expansion:Ambulatory surgical centers in the United States are consuming higher glove volumes per procedure as same-day surgery protocols multiply touchpoints requiring barrier protection.
- ISO 10993 Biocompatibility Testing:The FDA's harmonization with international biocompatibility standards is accelerating sterile surgical glove approvals for manufacturers with established toxicological dossiers.
- Nitrile Material Superiority:Accelerant-free nitrile formulations are capturing preference in allergy-sensitive hospital systems due to elimination of thiuram and carbamate sensitizers.
Market Restraints
- Butadiene Price Volatility:Nitrile rubber feedstock costs fluctuate with crude oil derivatives, compressing margin stability for non-integrated compounders.
- Single-Use Plastic Directives:The EU Green Deal's packaging waste regulations threaten polyethylene glove categories with material bans or extended producer responsibility levies.
- Accelerator-Free Curing Limitations:Alternative cross-linking chemistry for nitrile reduces tensile strength and elongation, constraining performance in high-stress surgical applications.
Strategic Opportunities
- India Healthcare Infrastructure:The country's PLI scheme for medical devices is incentivizing domestic glove manufacturing to reduce import dependence from Southeast Asian suppliers.
- Orthopedic Surgery Specialization:Double-gloving protocols for joint replacement procedures create demand for colored indicator systems enabling immediate breach detection.
- E-Commerce Direct Procurement:Hospital group purchasing organizations are piloting platform-based ordering that disintermediates traditional medical distributors.
Industry Challenges
- Automation Engineering Talent:Fully automated production lines require mechatronics specialists scarce in traditional rubber manufacturing regions.
- MDR Clinical Evaluation Timelines:Class I sterile device recertification under the EU Medical Device Regulation extends approval cycles by 12-18 months.
- Legacy Latex Production Footprint:Conversion of chlorinated latex lines to nitrile requires capital outlays for dipping tank reconfiguration and curing oven modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical and Examination Gloves Market |
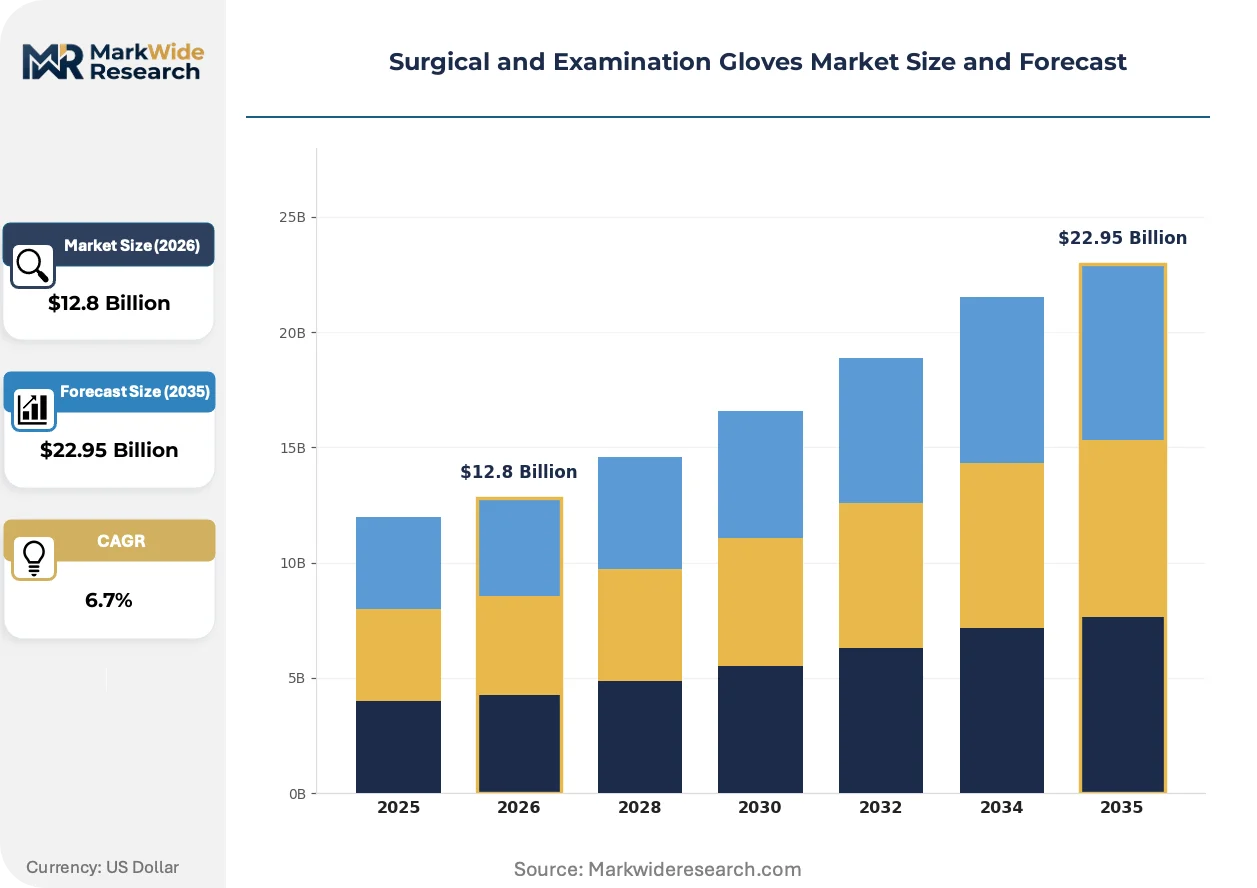
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
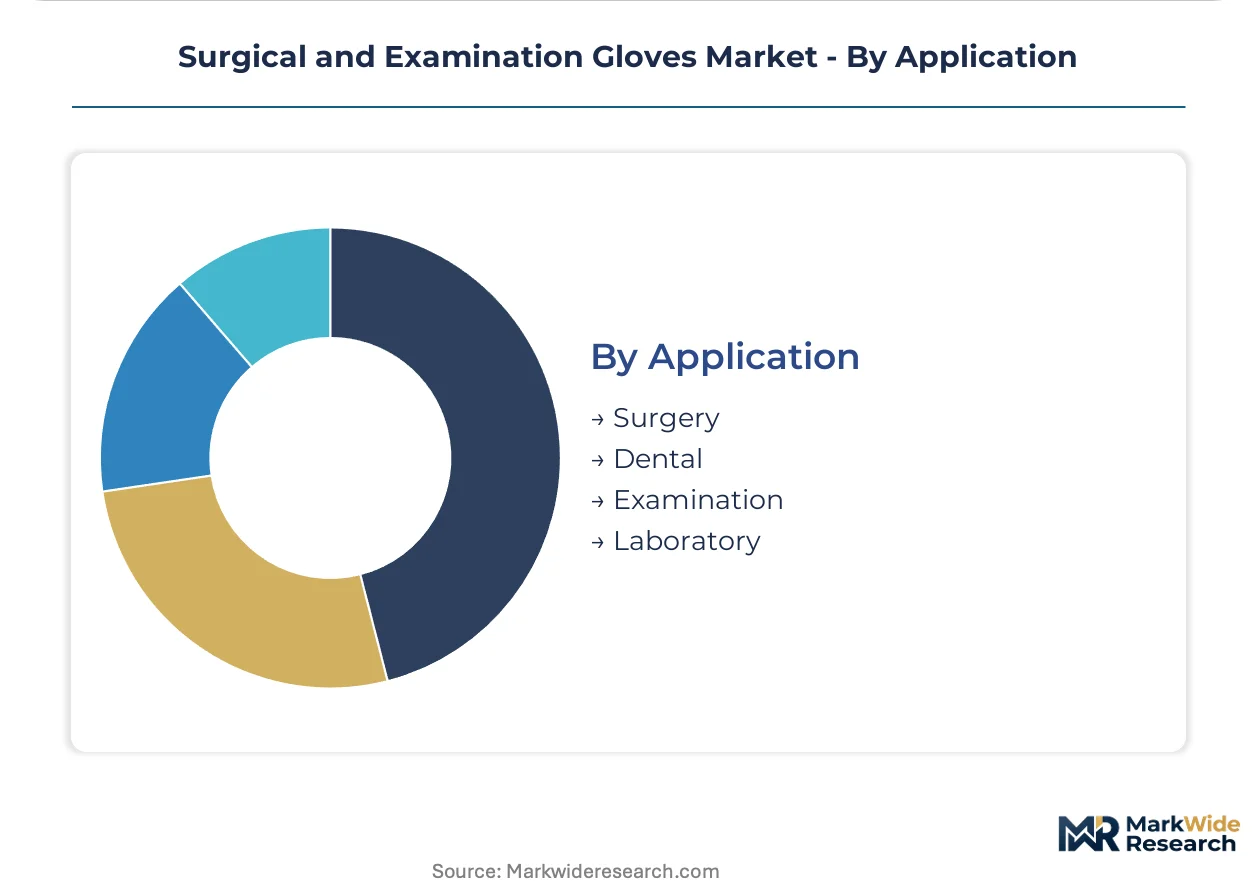
| Segmentation | Product Type: Disposable, Reusable, Sterile, Non-Sterile Material: Latex, Nitrile, Vinyl, Polyethylene Grade: Medical Grade, Industrial Grade, Food Grade, General Purpose Application: Surgery, Dental, Examination, Laboratory |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Kossan Rubber Industries Bhd, Ansell Ltd, Cardinal Health, Medline Industries, Semperit, Supermax, Mölnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical and Examination Gloves Market Emerging Trajectories
Material science breakthroughs and regulatory convergence are compressing product development cycles while reshaping competitive advantage around chemical transparency and automated manufacturing scale.
Accelerator-free nitrile compounding is electrifying the high-sensitivity examination segment by eliminating allergenic rubber chemicals while maintaining puncture resistance. Dermatology clinics and pediatric wards in Germany and France are specifying these formulations in tender documents. The technology is compressing market share for traditional nitrile among European healthcare procurement coalitions.
REACH Annex XVII restrictions on certain rubber accelerators are forcing disclosure of full chemical constituent lists for nitrile gloves entering the European Economic Area. Manufacturers must now submit Substance of Very High Concern declarations to ECHA. Sterile surgical portfolios face the steepest compliance burden as hospitals demand batch-level traceability documentation.
Hospital buying consortia are consolidating purchasing power through multi-year framework agreements that specify performance metrics beyond ASTM compliance. In the United States, integrated delivery networks are unbundling glove procurement from broad medical supply contracts. This concentration is most visible in the Northeast and Midwest where Catholic health systems and academic medical centers dominate bed capacity.
Surgical and Examination Gloves Market Segmentation
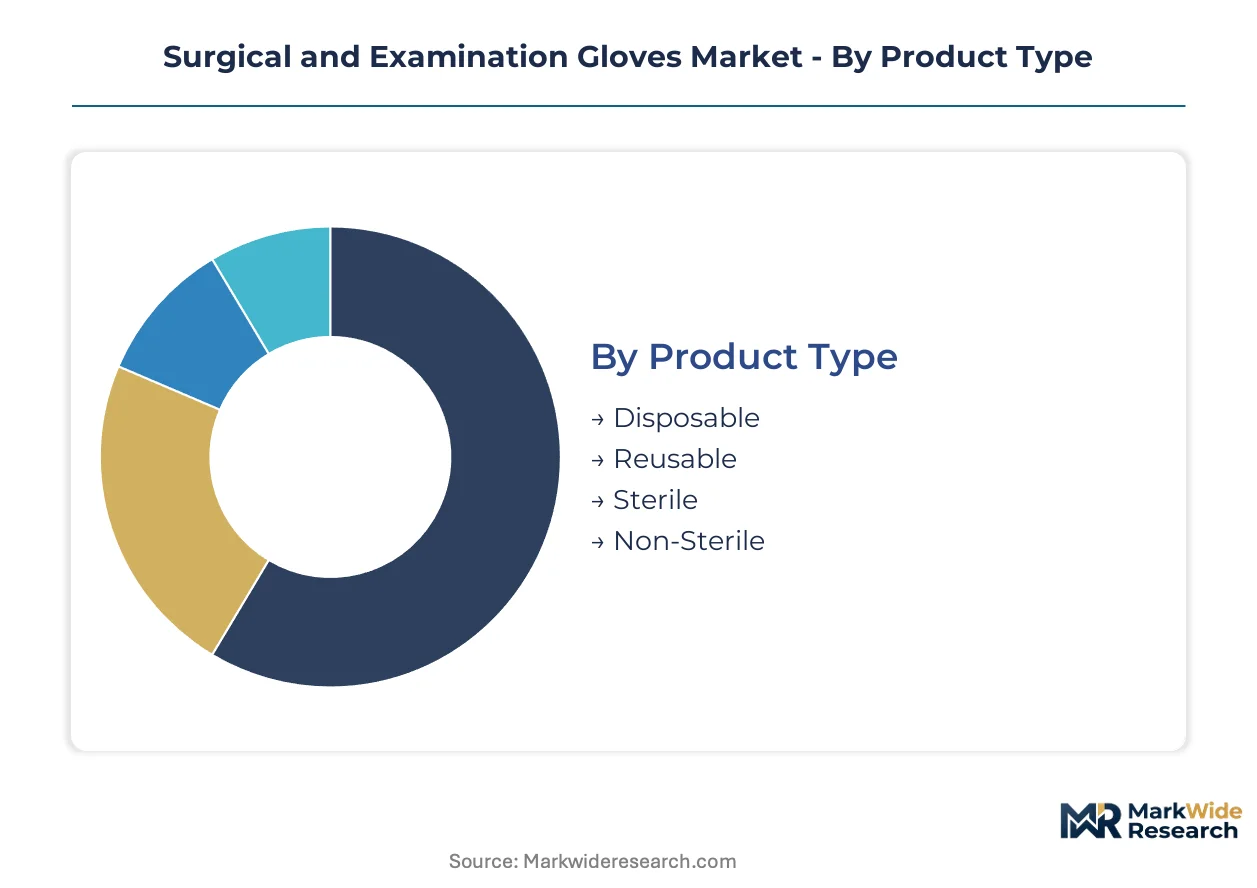
Glove procurement decisions cascade through four interlocking dimensions: sterility requirements dictate workflow protocols, material chemistry determines allergy compatibility and tactile precision, grade classifications enforce regulatory compliance boundaries, and application specificity governs performance thresholds for barrier protection.
Product Type:
Standardization dominates high-volume categories while customization concentrates in sterile portfolios requiring lot-specific certification documentation.
- Disposable:Single-use nitrile and latex formulations dominate hospital procurement at 0.05-0.15 mm thickness specifications. Ambulatory surgical centers in the United States are driving per-procedure consumption multiples through same-day surgery touchpoint protocols.
- Sterile:Individually packaged pairs undergo gamma irradiation or ethylene oxide treatment with lot-level traceability documentation. Orthopedic surgery suites specify colored indicator systems for immediate breach detection during joint replacement procedures.
- Reusable:Autoclavable latex and silicone variants serve cost-constrained veterinary and educational settings with 50-100 cycle durability ratings.
- Non-Sterile:Bulk-packaged examination variants for low-risk diagnostic touchpoints where barrier integrity exceeds sterility requirements.
Leading the category by volume: Disposable. Growing fastest: Sterile.
Material:
Cost tiers stratify from petroleum-derived synthetics through natural rubber feedstocks, with performance premiums commanding hospital infection control budgets.
- Nitrile:Acrylonitrile-butadiene copolymer delivers puncture resistance 3-5x superior to latex with complete protein allergen elimination. REACH Annex XVII accelerator restrictions are forcing European-bound manufacturers toward thiuram-free curing chemistry disclosure to ECHA.
- Latex:Natural rubber hevea brasiliensis sap provides unmatched tactile sensitivity for microsurgical applications. Conversion of chlorinated production lines to nitrile requires capital-intensive dipping tank reconfiguration and curing oven modification.
- Vinyl:Polyvinyl chloride compounds serve cost-sensitive food handling and janitorial segments where puncture risk remains minimal.
- Polyethylene:Cast film variants for brief patient contact face EU Green Deal packaging waste regulation threats through extended producer responsibility levies.
Dominating procurement value: Nitrile. Narrowing the cost gap fastest: Vinyl.
Grade:
Customer type segmentation separates regulated healthcare procurement from commercial and consumer channels through certification threshold enforcement.
- Medical Grade:ASTM D3578 or EN 455 compliance mandates govern all patient-contact applications with biocompatibility testing under ISO 10993. FDA Quality System Regulation enforcement accelerates approval timelines for manufacturers with established toxicological dossiers.
- Industrial Grade:Chemical resistance specifications for manufacturing and automotive maintenance without patient-contact certification overhead.
- Food Grade:FDA 21 CFR 177.2600 compliance for handling applications with migration testing for plasticizer content.
- General Purpose:Unregulated consumer retail channels with minimal barrier performance guarantees.
Capturing procurement volume: Medical Grade. Expanding most quickly: Food Grade.
Application:
Geography-of-use patterns concentrate sterile surgical demand in tertiary hospital clusters while examination volumes distribute through primary care networks.
- Surgery:Sterile double-gloving protocols for invasive procedures demand 0.08-0.12 mm thickness with textured fingertip surfaces. EMA MDR Class I sterile device recertification extends European approval cycles by 12-18 months.
- Examination:Non-sterile diagnostic touchpoints drive highest absolute unit volumes through physician office and clinic networks. India's PLI scheme for medical devices is incentivizing domestic manufacturing to reduce Southeast Asian import dependence.
- Dental:Latex and nitrile variants optimized for fine motor control during endodontic and prosthodontic procedures.
- Laboratory:Chemical-resistant nitrile formulations for biological containment and reagent handling protocols.
Commanding premium pricing: Surgery. Scaling volume fastest: Examination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks and ambulatory surgical centers drive the highest absolute glove procurement volumes through infection control mandates and same-day surgery expansion. Demand concentrates in integrated delivery networks across the Northeast and Midwest.
United States
FDA Quality System Regulation enforcement accelerates sterile surgical glove approvals for manufacturers with established ISO 10993 toxicological dossiers. Ambulatory surgical centers in Texas and Florida multiply per-procedure consumption through expanded outpatient touchpoint protocols. Cardinal Health and Medline Industries anchor distribution through group purchasing organization contracts.
Germany
EMA MDR Class I sterile device recertification extends approval cycles by 12-18 months for European-bound manufacturers. REACH Annex XVII accelerator restrictions force thiuram-free curing chemistry disclosure to ECHA for all nitrile formulations. Dermatology clinics in Bavaria specify accelerator-free nitrile in tender documents.
Malaysia
Department of Standards administers MS ISO 13485 certification as de facto export license requirement for regulated markets. Top Glove, Hartalega, and Kossan operate major nitrile and latex facilities concentrated in Selangor and Perak. Automation engineering talent scarcity constrains fully automated production line expansion.
India
PLI scheme for medical devices incentivizes domestic glove manufacturing to reduce Southeast Asian import dependence. CDSCO medical device rules mandate quality management system compliance for all patient-contact applications. Tamil Nadu and Maharashtra clusters attract compounding and dipping facility investments.
China
NMPA medical device registration requirements govern sterile surgical glove market access with biocompatibility testing harmonized to international standards. Nitrile production capacity expands in Shandong and Jiangsu provinces to serve domestic hospital procurement. Dual carbon goals pressure energy-intensive vulcanization processes.
Surgical and Examination Gloves Market Vendor Landscape
Malaysian producers anchor one tier; United States and European specialists hold differentiated positions through distribution integration and surgical portfolio depth. Three manufacturers control over half of nitrile capacity, creating supply vulnerability. Strategic archetypes include automated scale operators, backward-integrated compounders, and specialty surgical portfolio builders. Capacity expansion and regulatory compliance investments dominate competitive moves.
Within the automated production tier, Hartalega Holdings Berhad exemplifies cost leadership through fully automated lines. Kossan Rubber Industries Bhd occupies a position as backward-integrated compounder with captive rubber and chemical manufacturing. Ansell Ltd anchors the specialty surgical segment through differentiated portfolios targeting orthopedic and microsurgery applications.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Kossan Rubber Industries Bhd |
| Ansell Ltd |
| Cardinal Health |
| Medline Industries |
| Semperit |
| Supermax |
| Mölnlycke Health Care |
| Others |
Supply Flow & Price Mechanics
Accelerator-free nitrile compounding simultaneously escalates reformulation costs and consolidates pricing power among manufacturers with captive chemical synthesis capabilities, compressing margin structures for compounders dependent on third-party accelerator suppliers while rewarding backward-integrated producers in Selangor and Perak.
Pricing Analysis
High-volume examination gloves trade on razor-thin unit economics while sterile surgical portfolios sustain premium capture through lot-specific certification and ASTM D3578 compliance tiers. Price differentiation rests on ISO 10993 toxicological dossier completeness and gamma irradiation documentation depth. Pricing pressure stems from butadiene feedstock volatility transmitted through non-integrated nitrile rubber suppliers. Cost-sensitive ambulatory surgical centers in Texas and Florida drive procurement consolidation, while orthopedic surgery suites in academic medical centers exhibit minimal price elasticity for breach-detection indicator systems.
Supply Chain Analysis
India's PLI scheme for medical devices is reshaping sourcing patterns by mandating domestic-content thresholds for hospital procurement tenders, diverting volume from traditional Southeast Asian suppliers toward Tamil Nadu and Maharashtra production clusters. Raw material dependencies center on acrylonitrile-butadiene rubber, sulfur-based curing agents, and calcium carbonate fillers. Single-source vulnerability concentrates in Malaysian nitrile capacity where three producers control majority share. Distribution runs through Cardinal Health and Medline Industries group purchasing organization contracts anchoring United States hospital network access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian production concentration functions as a structural capacity bottleneck, insulating pricing from demand cyclicality while exposing buyers to allocation risk during feedstock disruptions.
For Market Incumbents: Deploy captive accelerator manufacturing to neutralize REACH Annex XVII disclosure burdens and ECHA submission costs threatening European-bound margins. Accelerate fully automated production line replication in Perak to offset automation engineering talent scarcity constraining capacity expansion. Defend against Indian PLI-subsidized domestic manufacturers by securing multi-year framework agreements with United States integrated delivery networks before local-content mandates proliferate.
For New Entrants and Emerging Players: Enter via India's CDSCO-registered domestic manufacturing to capture PLI scheme incentives and hospital procurement localization mandates in Tamil Nadu. Target accelerator-free nitrile formulations for European dermatology clinic tenders where thiuram-free chemistry specifications command procurement preference. Pursue direct e-commerce platform relationships with hospital group purchasing organizations piloting disintermediated procurement models in the Northeast and Midwest.
For Investors and Strategic Acquirers: Exit pathways concentrate in backward-integrated compounders with captive rubber and chemical manufacturing assets resilient to feedstock volatility. Long-term viability favors producers with MS ISO 13485 certification as de facto export license infrastructure for regulated market access. Monitor FDA 510(k) powder-free claim submission volumes as inflection signal for compliance cost escalation reshaping competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Free Formulation Development | Eliminates thiuram and carbamate sensitizers for REACH-compliant European hospital procurement. |
| Fully Automated Production Scale-Up | Hartalega's cost leadership model in Selangor demonstrates mechatronics-driven unit economics compression. |
| Backward Integration into Rubber Compounding | Kossan's captive chemical manufacturing neutralizes butadiene price volatility transmission. |
| MDR Class I Sterile Recertification | EMA clinical evaluation report completion extends European market access continuity. |
| E-Commerce Direct Procurement Platform | Hospital GPO pilot programs disintermediate Cardinal Health and Medline distribution control. |
Methodological Framework
Independent corroboration across hospital purchasing committee interviews, biomedical engineer technical assessments, and GPO contracts manager consultations underwrites the qualitative findings. Primary fieldwork engaged sterile processing directors, infection control officers, and regulatory affairs leads at manufacturers with FDA Quality System Regulation submissions. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CDSCO medical device registration records, and Malaysian Department of Standards certification logs. Bottom-up demand modeling triangulated against top-down production capacity assessments across Selangor, Perak, Shandong, and Jiangsu facilities.
Rate-of-change decomposition separated volume expansion drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include sterility requirements, material chemistry tiers, medical grade certification levels, and application-specific performance thresholds. CAGRs derived from procedure volume elasticities tied to ambulatory surgical center expansion and outpatient protocol proliferation. Industry-specific forecast inputs incorporated butadiene derivative pricing indices and REACH Annex XVII amendment timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under single-use plastic directive enforcement acceleration or Malaysian export license suspension scenarios. Forecasts reflect documented assumptions regarding nitrile formulation substitution rates and automation engineering labor availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Smear Mask Market
Medical Supplies
Compression Socks Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Therapeutic Elastic Tapes Market
Medical Supplies
Premixed IV Minibags Market