
 Culture Media Preparators Market | 2026-2036
Culture Media Preparators Market Size, Share, and Industry Trends Forecast 2026-2036
Culture Media Preparators Market Outlook
Direct sales channels for high-volume media preparators is tilting toward integrated system vendors with full service contracts. Thermo Fisher Scientific leverages its consumables-recurring revenue model to lock in multi-year preparator placements. Merck KGaA anchors its position through deep integration with downstream filtration and purification workflows. bioMérieux competes by bundling preparators with its microbial identification platforms, creating closed-loop quality control systems.
Culture media preparators are automated systems that blend, heat, sterilize, and dispense nutrient formulations under controlled pH, osmolality, and sterility parameters for microbial or cell cultivation. These units operate at batch scales from laboratory-scale 2-liter vessels to production-scale 1000-liter systems, serving the foundational step where media consistency determines all downstream experimental or manufacturing outcomes. Ready-to-use media commands premium positioning as pharmaceutical quality units absorb validation and documentation burdens, while liquid media retains volume leadership in high-throughput research settings. Tissue culture application segments attract specialized vendors as serum-free and chemically defined formulations require precision blending capabilities that standard microbiology units cannot achieve.
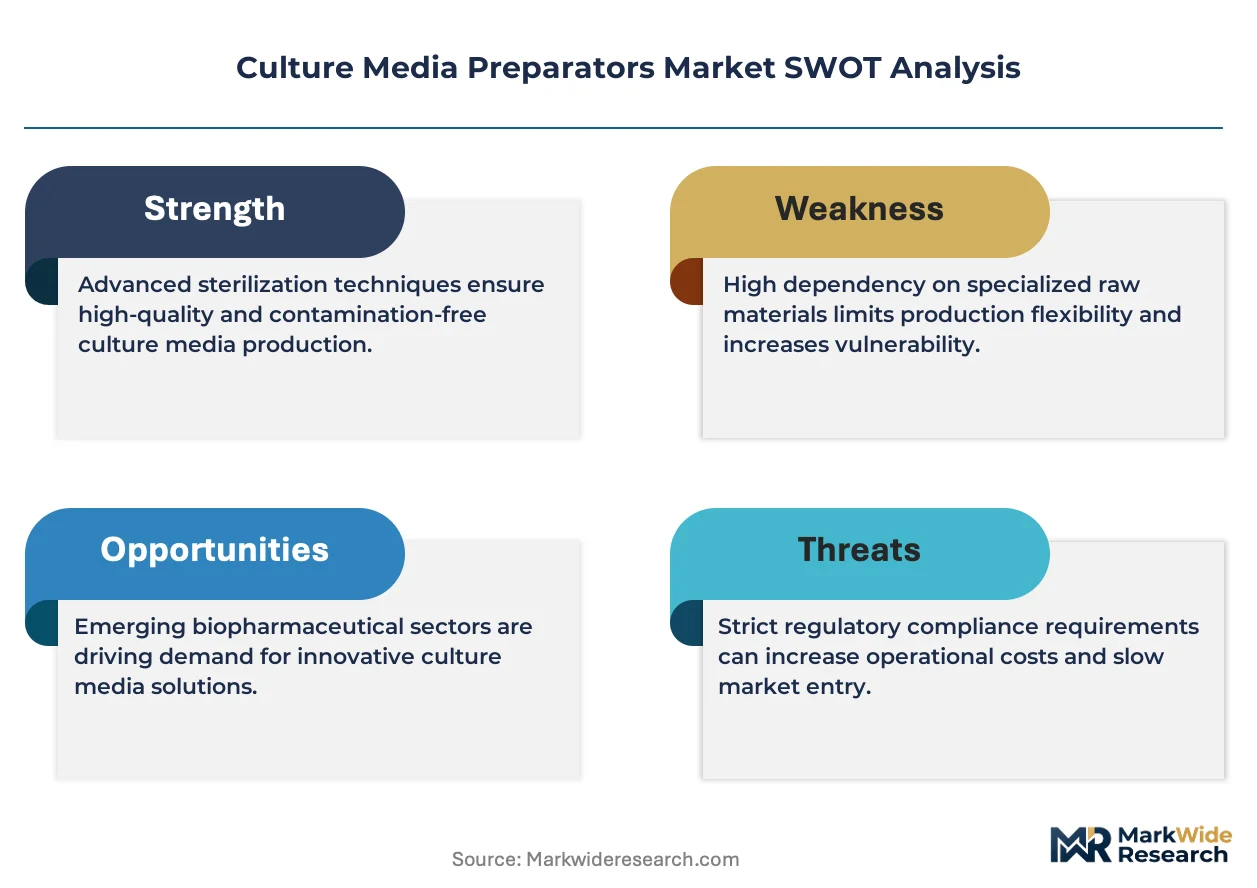
FDA current good manufacturing practice standards and EMA Annex 1 sterile manufacturing guidelines compel preparator vendors to embed continuous particle monitoring and electronic batch recording into new system designs. ISO 11137 sterilization validation requirements further constrain market entry for equipment lacking integrated biological indicator verification. Stakeholders must weigh capital deployment between standalone preparator upgrades and full manufacturing execution system integration as regulatory traceability expectations harden.
Market Dynamics
Automated media preparation systems are capturing capital allocation as biopharmaceutical manufacturers confront FDA sterility validation requirements and EMA Annex 1 electronic batch recording mandates that manual workflows cannot satisfy.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:Pharmaceutical facilities in Germany and Switzerland are retrofitting production lines with continuous particle monitoring capabilities that only automated preparators deliver.
- Cell and gene therapy manufacturing:Serum-free chemically defined media requirements for CAR-T production are pulling precision blending systems into GMP suites.
- Biologics capacity expansion:Contract development and manufacturing organizations in the United States are installing 500-liter to 1000-liter preparator systems to capture outsourced media preparation demand.
Market Restraints
- Stainless steel and borosilicate glass supply concentration:Vessel fabrication depends on specialized European and Japanese metallurgical suppliers with 18-month order backlogs.
- ISO 11137 sterilization validation:Biological indicator verification requirements extend equipment qualification timelines by 4-6 months for vendors lacking integrated verification modules.
- Single-use bag assemblies:Gamma-irradiated disposable liners are displacing reusable stainless steel vessels in clinical-scale applications below 200 liters.
Strategic Opportunities
- India biopharma manufacturing corridor:CDSCO manufacturing-linked incentive schemes are attracting preparator placements in Hyderabad and Bengaluru bioclusters.
- Manufacturing execution system integration:Convergence of preparator controls with Siemens and Rockwell automation platforms is enabling paperless batch records.
- Point-of-use media preparation:Distributed 50-liter systems at satellite research sites are reducing cold-chain logistics burdens for temperature-sensitive formulations.
Industry Challenges
- Validation engineering talent scarcity:GMP equipment qualification and computer system validation expertise concentrates with contractors commanding premium day rates.
- Legacy LIMS integration complexity:Preparator data historians must map to 1990s-era laboratory information management systems without native OPC-UA connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Culture Media Preparators Market |
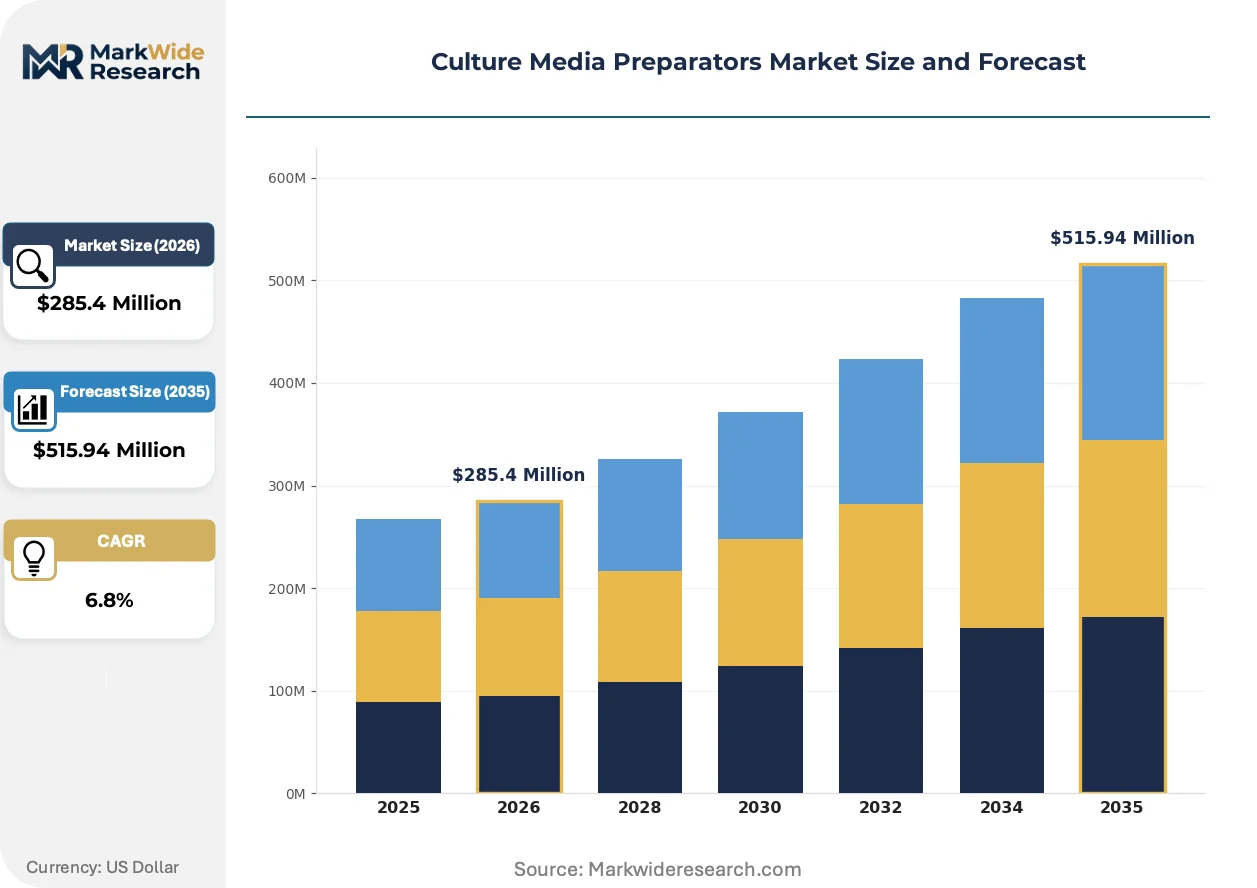
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Liquid Media, Solid Media, Semi-solid Media, Ready-to-use Media Application: Microbiology, Biochemistry, Tissue Culture, Environmental Testing End User: Research Laboratories, Pharmaceutical Companies, Diagnostics Centers, Academic Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, bioMérieux, CertoClav Sterilizer GmbH, INTEGRA Biosciences, Systec, Alliance Bio Expertise, Distek, Chr. Hansen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Culture Media Preparators Market Strategic Shifts
Digital traceability architectures and modular equipment designs are compressing validation timelines while expanding the addressable market beyond traditional pharmaceutical manufacturing into advanced therapy production facilities.
Artificial intelligence-driven predictive maintenance algorithms are digitizing equipment uptime optimization for culture media preparators. Biopharmaceutical manufacturers in the United States are deploying machine learning models on preparator sensor arrays to forecast pump seal failures and heating element degradation. This capability is digitizing the transition from calendar-based preventive maintenance to condition-based intervention, reducing unplanned downtime in 24/7 manufacturing environments.
FDA's emphasis on data integrity in CGMP guidance documents is forcing hardware redesigns across the supplier base. Equipment vendors must now embed audit trails and electronic signatures at the firmware level rather than relying on supervisory software overlays. Small and mid-sized contract manufacturers are delaying procurement decisions until vendors demonstrate ALCOA+ compliant data architectures, compressing sales cycles for non-compliant legacy platforms.
Consolidated procurement through integrated system vendors is displacing standalone preparator purchases in high-volume manufacturing accounts. Pharmaceutical quality units are bundling media preparation with downstream filtration and fill-finish equipment under single-source service contracts. This pattern is most visible in the United States and Germany, where Thermo Fisher Scientific and Merck KGaA are capturing multi-year commitments through consumables-recurring revenue lock-in structures.
Culture Media Preparators Market Segmentation
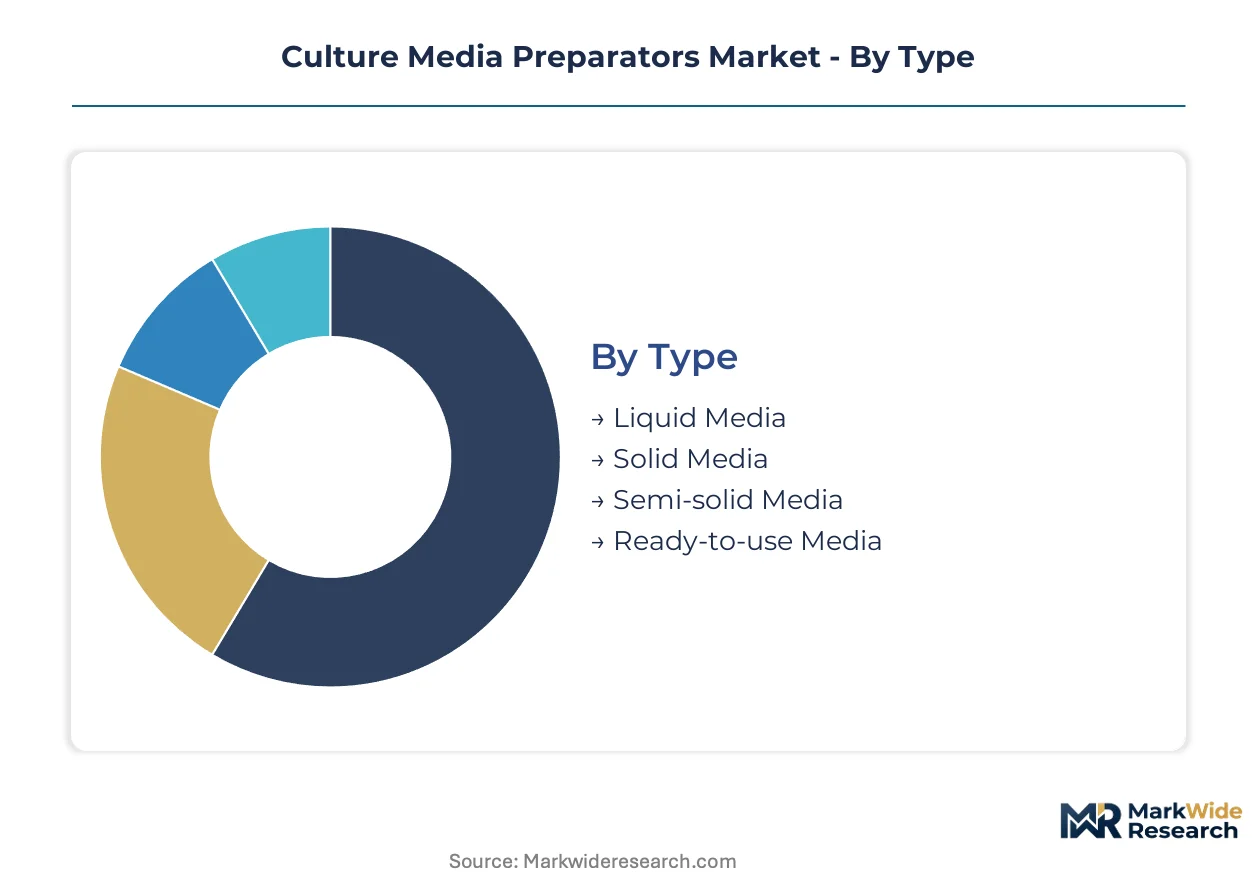
Culture media preparators serve heterogeneous workflows spanning GMP manufacturing and exploratory research. Segment-specific engineering requirements—sterility assurance levels, batch documentation, and formulation complexity—determine equipment specifications and vendor selection criteria across customer categories.
Type:
Mature formats dominate installed base volumes while emerging preparation modes reshape capital allocation patterns in quality-controlled environments.
- Liquid Media:Aqueous nutrient solutions requiring precise pH buffering and osmolality control for suspension cell cultivation. High-throughput screening facilities in the United States absorb the largest procurement volumes as biologics discovery pipelines expand.
- Ready-to-use Media:Pre-sterilized, validated formulations delivered in gamma-irradiated containers eliminate in-house preparation burdens. Pharmaceutical quality units in Germany and Switzerland absorb premium positioning to satisfy EMA Annex 1 documentation requirements.
- Solid Media:Agar-based formulations solidified in petri dishes or slants for colony isolation and enumeration. Academic microbiology departments retain steady replacement demand for teaching and reference laboratories.
- Semi-solid Media:Reduced agar concentrations enabling motility testing and anaerobic cultivation. Specialized diagnostics centers deploy these formats for clinical microbiology workflows requiring motility assessment.
Liquid media retains volume leadership; ready-to-use media holds the steepest expansion curve.
Application:
Application segmentation traces the divergence between regulated manufacturing and research environments, with compliance burdens intensifying across therapeutic production categories.
- Microbiology:Conventional bacterial and fungal cultivation for identification, enumeration, and susceptibility testing. Diagnostics centers in China deploy automated preparators to standardize quality control across high-volume clinical laboratories.
- Tissue Culture:Mammalian and insect cell propagation demanding serum-free or chemically defined formulations with tight specification windows. CAR-T manufacturing suites in the United States pull precision blending systems into GMP environments to meet FDA sterility validation standards.
- Biochemistry:Enzymatic assay support and metabolite production requiring defined minimal media. Research laboratories sustain steady demand for configurable preparation systems supporting diverse experimental protocols.
- Environmental Testing:Water, soil, and air quality assessment media for indicator organism detection. Regulatory laboratories in Germany expand capacity to meet EU Water Framework Directive monitoring obligations.
Microbiology commands the largest installed base; tissue culture is expanding most quickly.
End User:
Customer type determines capital intensity and service contract structures, with pharmaceutical procurement consolidating through integrated vendor relationships.
- Pharmaceutical Companies:GMP manufacturing operations requiring validated batch records and continuous process verification. Contract development and manufacturing organizations in the United States install 500-liter to 1000-liter systems to capture outsourced media preparation demand.
- Research Laboratories:Discovery and development settings prioritizing formulation flexibility over regulatory documentation. Biotechnology clusters in China absorb mid-scale preparators for antibody and vaccine candidate screening.
- Diagnostics Centers:Clinical microbiology and molecular testing facilities requiring high-throughput media standardization. Hospital networks in Germany consolidate procurement through regional laboratory consortia.
- Academic Institutions:Teaching and fundamental research operations with constrained capital budgets. Public universities in the United States delay equipment refresh cycles amid endowment pressure.
Pharmaceutical companies anchor revenue concentration; diagnostics centers are gaining share fastest.
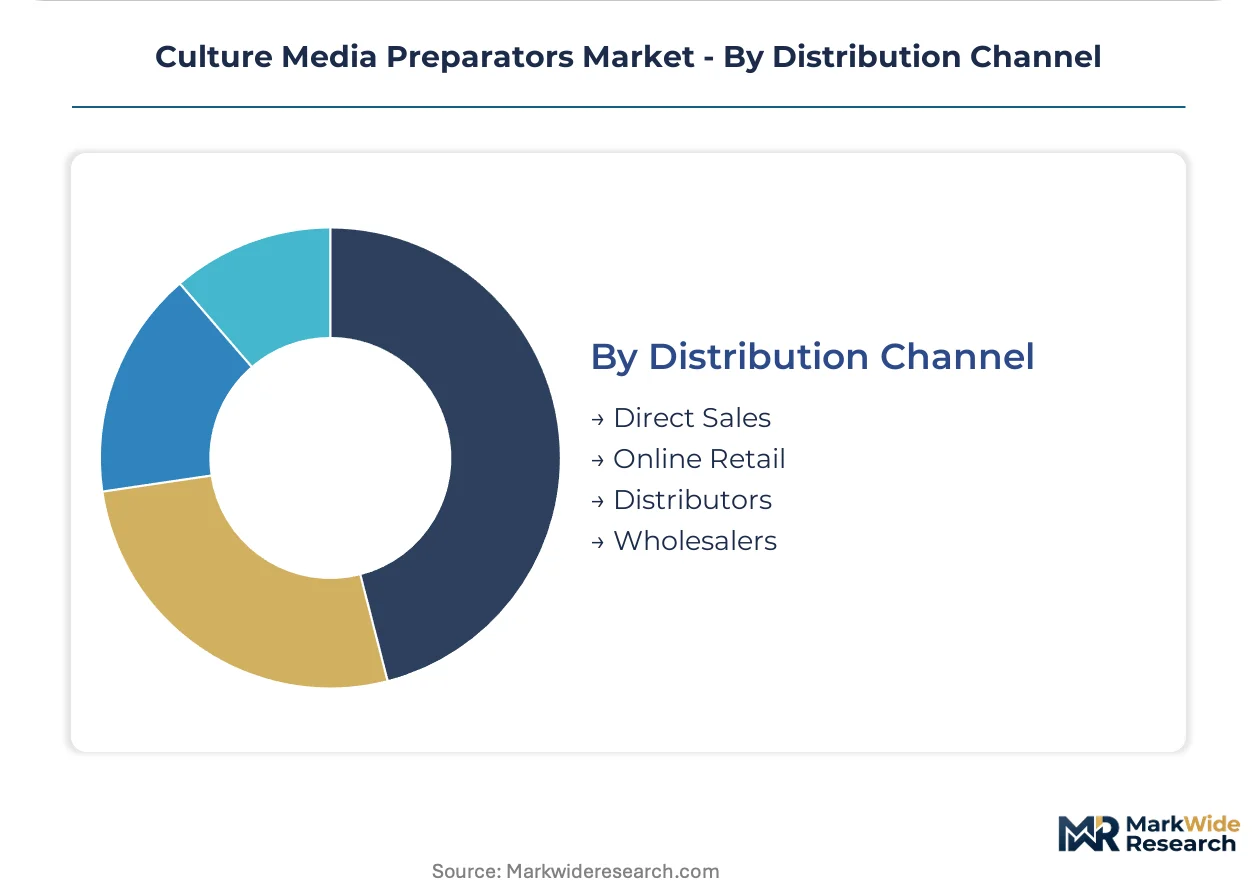
Distribution Channel:
Channel configuration reflects customer scale and technical support requirements, with direct engagement displacing intermediaries in high-value manufacturing accounts.
- Direct Sales:Manufacturer-led commercial engagement with integrated service and qualification support. Thermo Fisher Scientific and Merck KGaA lock multi-year preparator placements through consumables-recurring revenue structures in the United States and Germany.
- Distributors:Regional intermediaries stocking standard configurations for rapid fulfillment. Indian bioclusters in Hyderabad and Bengaluru access preparators through specialized life science distributors serving CDSCO-registered facilities.
- Online Retail:E-commerce platforms facilitating small-scale and replacement component procurement. Academic institutions in China leverage domestic marketplace channels for consumables and accessories.
- Wholesalers:Bulk inventory aggregation for standard laboratory supply chains. General research supply wholesalers retain relevance in European markets with fragmented end-user geography.
Direct sales capture the highest value transactions; distributor channels sustain the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's biologics distribution network, while the Shanghai Yangshan deep-water port anchors Asia-Pacific media logistics. These maritime assets determine where preparator manufacturers concentrate service and qualification resources.
United States
CAR-T manufacturing expansion in Greater Boston and the San Francisco Bay Area drives demand for precision blending systems. FDA sterility validation requirements under 21 CFR Part 211 compel electronic batch recording capabilities. Contract development and manufacturing organizations in Research Triangle Park install 500-liter to 1000-liter preparator systems to capture outsourced media preparation contracts.
Germany
EMA Annex 1 sterile manufacturing guidelines mandate continuous particle monitoring that only automated preparators deliver. The country's national pharmaceutical regulator enforces strict validation protocols for GMP manufacturing equipment. Pharmaceutical quality units in Baden-Württemberg and Bavaria absorb premium positioning for ready-to-use media to satisfy documentation requirements.
China
NMPA biologics approval acceleration expands antibody and vaccine manufacturing capacity. The national medical products administration tightens data integrity requirements for electronic batch records. Biotechnology clusters in Suzhou and Shanghai's Zhangjiang Hi-Tech Park deploy mid-scale preparators for candidate screening pipelines.
Switzerland
Swissmedic oversight of sterile manufacturing drives equipment qualification standards across Basel's pharmaceutical corridor. The national regulatory agency aligns with EMA Annex 1 for cross-border manufacturing compliance. Precision blending systems serve Roche and Novartis manufacturing networks concentrated in the Basel region.
India
CDSCO manufacturing-linked incentive schemes attract preparator placements in emerging bioclusters. The central drugs standard control organization streamlines approvals for contract manufacturing organizations. Hyderabad and Bengaluru facilities access preparators through specialized life science distributors serving CDSCO-registered operations.
Culture Media Preparators Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in vessel fabrication and sensor supply. The vendor base stratifies between consolidated instrumentation conglomerates and specialized automation houses. Three archetypes dominate: diversified life science conglomerates with consumables-recurring revenue models, precision engineering specialists with deep GMP qualification expertise, and emerging automation vendors targeting modular distributed systems. Competitive moves concentrate on manufacturing execution system integration partnerships and qualification service bundling.
Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the platform-integrator archetype through consumables-recurring revenue lock-in structures. bioMérieux occupies a position within the diagnostics-integrated tier, bundling preparators with microbial identification platforms. These three entities represent distinct strategic postures: full-system integration, downstream workflow anchoring, and closed-loop quality control systems respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| bioMérieux |
| CertoClav Sterilizer GmbH |
| INTEGRA Biosciences |
| Systec |
| Alliance Bio Expertise |
| Distek |
| Chr. Hansen |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's cold-chain infrastructure anchors European biologics distribution, with freight cost volatility transmitting through stainless steel vessel fabrication in Germany and Japan to create sharp price differentiation between validated GMP systems and research-grade units. Pharmaceutical quality units absorb 40-60% premiums for integrated electronic batch recording, while academic buyers face compressed procurement budgets that favor distributor-channel sourcing.
Pricing Analysis
Volume-discount tiering structures separate multi-unit pharmaceutical contracts from single-system academic purchases, with three-tier pricing stratification across premium GMP-validated, standard automated, and economy manual systems. Price differentiation centers on ISO 11137 sterilization certification and integrated MES connectivity, with FDA data integrity mandates forcing firmware-level redesigns that widen the premium tier. Cost compression in the economy segment intensifies as Chinese manufacturers expand 50-liter distributed system capacity. Contract development and manufacturing organizations exhibit lowest price sensitivity due to qualification cost amortization across batch volumes, while public universities face procurement freezes that extend replacement cycles.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized European and Japanese metallurgical suppliers holding 18-month order backlogs for 316L stainless steel and borosilicate glass vessels. Raw material dependencies draw from German specialty steel foundries, Japanese precision glassworks, and Swiss sensor manufacturers, creating single-source vulnerability for biological indicator verification modules. Tariff exposure runs through specialized heating element suppliers concentrated in South Korea. Distribution runs through direct manufacturer engagement for GMP accounts above 500-liter capacity, with regional distributors serving CDSCO-registered Indian facilities and domestic marketplace channels capturing Chinese academic replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as CAR-T manufacturing penetration pulls precision blending systems into GMP suites faster than replacement demand from mature microbiology segments.
For Market Incumbents: Harden defensive moats through backward integration into consumables-recurring revenue lock-in structures that bundle preparator placements with filtration media and biological indicator supplies. Anchor capacity expansion in United States CDMO corridors and German pharmaceutical clusters where EMA Annex 1 validation requirements create switching costs. Invest in firmware-level ALCOA+ data architectures before FDA enforcement hardens.
For New Entrants and Emerging Players: Build out modular 50-liter distributed systems targeting satellite research sites in China's biotechnology clusters, where point-of-use preparation reduces cold-chain logistics burdens for temperature-sensitive formulations. Penetrate the India biopharma manufacturing corridor through specialized life science distributors serving CDSCO-registered Hyderabad and Bengaluru facilities. Lead with manufacturing execution system integration partnerships with Siemens and Rockwell automation platforms.
For Investors and Strategic Acquirers: Precision engineering specialists with deep GMP qualification expertise and integrated biological indicator verification modules represent the most defensible acquisition archetype. Long-term viability hinges on regulatory traceability convergence rather than hardware differentiation alone. Watch for inflection when FDA issues draft guidance on AI-driven predictive maintenance algorithm validation, signaling which vendors have embedded machine learning capabilities at the sensor-array level.
| Strategic Initiative | Industry Significance |
|---|---|
| MES Integration Partnership | Convergence with Siemens and Rockwell platforms enables paperless batch records for EMA Annex 1 compliance. |
| Biological Indicator Verification Module Development | Integrated ISO 11137 validation compresses equipment qualification timelines by 4-6 months. |
| Consumables-Recurring Revenue Lock-In | Bundled filtration media and indicator supplies secure multi-year preparator placements at CDMOs. |
| Distributed 50-Liter System Launch | Point-of-use preparation reduces cold-chain burdens for temperature-sensitive serum-free formulations. |
| AI Predictive Maintenance Algorithm Deployment | Machine learning on sensor arrays forecasts pump seal failures in 24/7 manufacturing environments. |
Study Parameters
A spread of perspectives from biopharmaceutical manufacturing executives, GMP equipment qualification specialists, CDMO procurement directors, and regulatory affairs consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 483 inspection databases, EMA GMP inspection reports, and ISO 11137 sterilization standards documentation. Bottom-up installed base estimates triangulated against top-down capital expenditure disclosures from contract development and manufacturing organizations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning preparation format, application workflow, end-user capital intensity, and distribution channel structure. Modeled CAGRs derived from unit shipment trajectories by capacity tier and average selling price evolution by certification grade. Industry-specific forecast inputs incorporated NMPA biologics approval velocity in China and CDSCO manufacturing-linked incentive scheme uptake in India.
Stress conditions across stainless steel supply backlogs, single-use bag assembly displacement rates, and validation engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement timing and biologics capacity expansion cadence. Quarterly review of FDA data integrity guidance enforcement patterns and EMA Annex 1 inspection deficiency trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Gloves Market
Medical Supplies
Blood Bags Market
Medical Supplies
Global Swab Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Medical Disposables Market