
 Single-Use Sterilization Wraps Market | 2026-2036
Single-Use Sterilization Wraps Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Sterilization Wraps Market Analytics
Ambulatory surgery centers is consolidating demand for single-use sterilization wraps as outpatient procedural volumes shift away from inpatient settings. Cardinal Health leverages its direct sales infrastructure to anchor hospital system contracts across North America. Medline Industries sustains broad SKU coverage across polypropylene and SMS grades, competing on fulfillment speed rather than material innovation. Owens & Minor dominates government and group purchasing organization channels through its distribution scale.
Single-use sterilization wraps are non-woven synthetic or cellulose-based barriers engineered to maintain sterility of packaged medical devices while permitting steam or gas sterilization penetration; SMS laminates rated at 40-60 gsm deliver bacterial filtration efficiency above 98% with minimal particle shedding. Polypropylene spunbond dominates current volume owing to cost-positioning and compatibility with gamma and ethylene oxide sterilization cycles. Non-woven cellulose alternatives occupy niche demand among European facilities prioritizing incineration-compatible waste streams. Laboratory equipment applications represent the fastest-growing segment as diagnostic automation expands sterile field requirements beyond traditional surgical suites.
FDA 510(k) clearance requirements for sterilization packaging materials constrain market entry and elevate testing documentation burdens for new substrate formulations. EPA medical waste incineration standards under the Clean Air Act shape disposal cost structures that favor lighter-weight synthetic wraps over cellulose predecessors. ISO 11607 compliance on sterile barrier systems remains the baseline quality threshold for export eligibility into regulated markets. Stakeholders must monitor evolving state-level single-use plastic restrictions that could force material transitions before next-generation biodegradable non-wovens achieve comparable barrier performance.
Market Dynamics
Hospital procurement consolidation around single-use formats is compressing supplier margins while elevating material performance requirements, as infection control protocols tighten across ambulatory and inpatient settings alike.
Growth Catalysts
- EPA Clean Air Act medical waste standards:Incineration regulations favor lighter-weight synthetic wraps over cellulose alternatives, accelerating substrate transitions in US facilities.
- Ambulatory surgery center expansion:Outpatient procedural volume migration drives concentrated volume procurement of SMS and polypropylene grades.
- ISO 11607 sterile barrier compliance:Export eligibility requirements push manufacturers toward validated substrate formulations with documented bacterial filtration performance.
Market Restraints
- Petrochemical input cost volatility:Polypropylene resin prices fluctuate with crude oil indices, squeezing margin stability for spunbond manufacturers.
- FDA 510(k) documentation burdens:New substrate formulations face extended clearance timelines and elevated testing costs that deter market entry.
- Biodegradable non-woven performance gap:Next-generation cellulose alternatives fail to match SMS bacterial filtration efficiency above 98% at comparable basis weights.
Strategic Opportunities
- Diagnostic laboratory automation:Sterile field requirements beyond surgical suites create application expansion for high-barrier wraps in equipment packaging.
- State-level single-use plastic restrictions:Regulatory pressure on petroleum-based substrates creates first-mover advantage for bio-based material innovators.
- Direct hospital system contracting:Bypassing group purchasing organizations enables margin capture through fulfillment speed and SKU customization.
Industry Challenges
- Gamma sterilization compatibility testing:Validating substrate performance across multiple sterilization modalities extends product development cycles.
- Legacy cellulose incineration infrastructure:European facilities with captive waste-to-energy systems resist synthetic wrap transitions despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Sterilization Wraps Market |
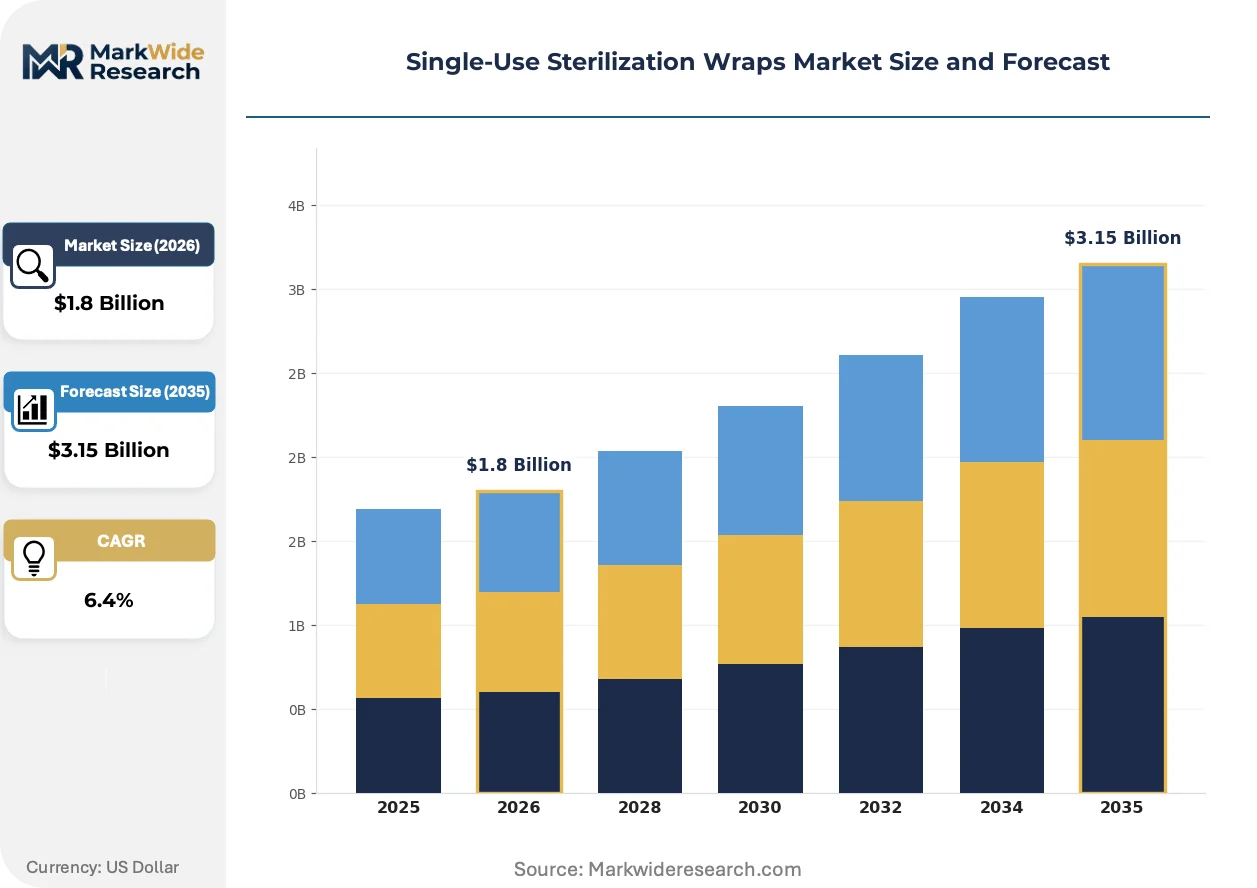
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethene, SMS, Non-Woven Application: Surgical Instruments, Medical Devices, Laboratory Equipment, Cosmetic Procedures End User: Hospitals, Surgery Centers, Laboratories, Research Facilities Distribution Channel: Direct Sales, Online Retail, Medical Supply Stores, Distributors |
| Companies Covered | Owens & Minor, Ahlstrom-Munksjo, Cardinal Health, Medline Industries, Dynarex Corporation, STERIS, Kimberly-Clark, Cygnus Medical, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Sterilization Wraps Market Evolving Landscape
Material science advances and sterilization modality diversification are reconfiguring product specifications, while procurement centralization reshapes how suppliers compete for hospital system contracts.
Smart barrier monitoring technologies incorporating color-change indicators are automating sterility assurance verification at the point of use. Ambulatory surgery centers with high throughput requirements adopt these formats to reduce manual inspection labor. The technology is automating compliance documentation and reducing liability exposure from packaging failures.
EU MDR sterile barrier system requirements are elevating traceability and biocompatibility testing for wraps exported into European markets. Manufacturers must now maintain technical documentation on substrate composition and endotoxin levels. SMS laminate producers serving EU hospitals are investing in dedicated validation laboratories to maintain market access.
Consolidated buying through integrated delivery networks is displacing fragmented procurement across individual hospital materials management departments. Large health systems negotiate multi-year supply agreements with performance guarantees on bacterial filtration and particle shedding. This pattern concentrates most visibly in United States metropolitan markets where IDN coverage exceeds 60% of licensed beds.
Single-Use Sterilization Wraps Market Segmentation
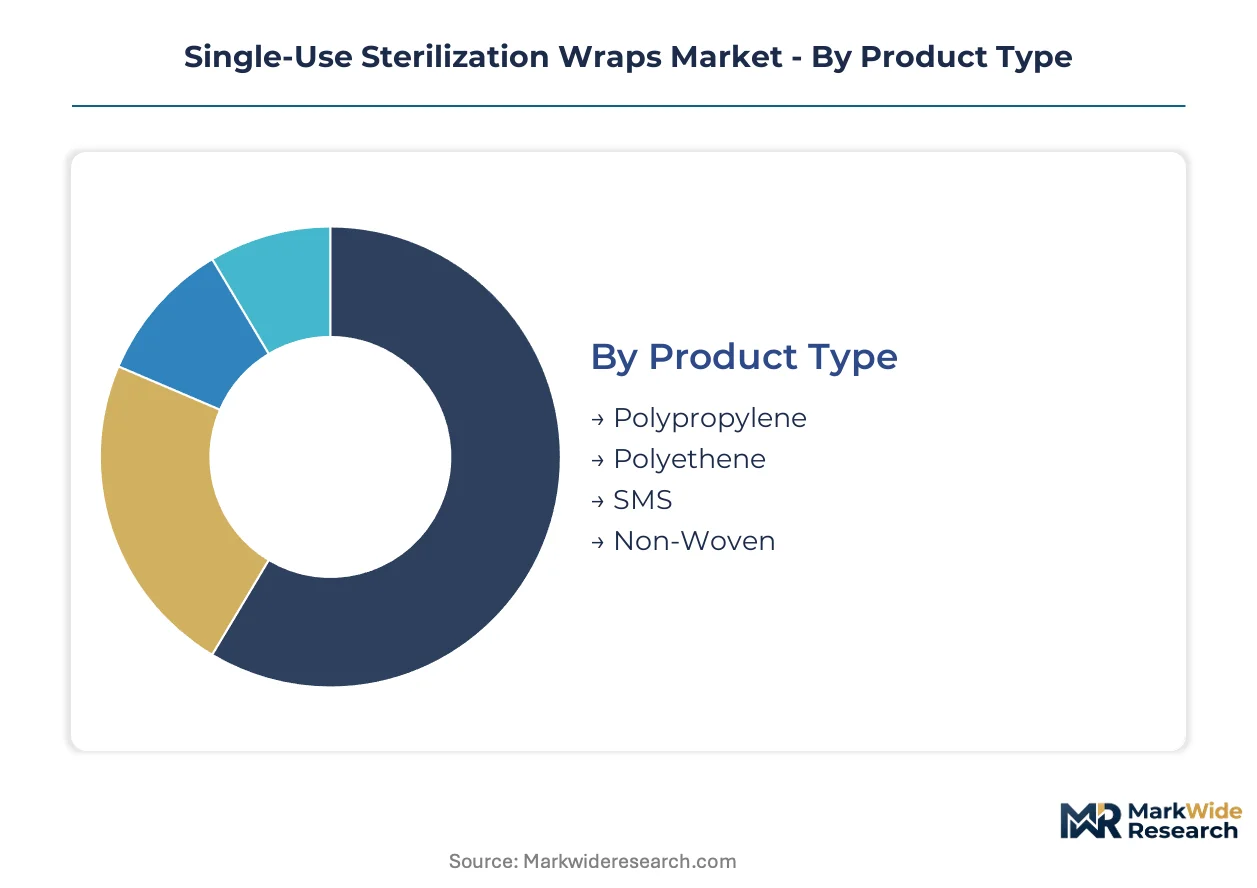
Material substrate selection and sterilization modality compatibility dictate procurement decisions across healthcare settings. Each segmentation dimension reveals distinct margin structures and competitive dynamics that suppliers must navigate to secure long-term contracts.
Product Type:
Cost-performance positioning determines substrate adoption, with weight and bacterial filtration efficiency serving as primary technical gatekeepers.
- Polypropylene:Spunbond non-woven construction delivers gamma and ethylene oxide sterilization compatibility at the lowest unit cost. Ambulatory surgery centers in the United States favor this grade for high-volume instrument turnover where barrier performance requirements remain standard.
- SMS:Spunbond-meltblown-spunbond laminates achieve bacterial filtration efficiency above 98% at 40-60 gsm basis weights. Hospital systems with stringent infection control protocols specify SMS for implantable device packaging where particle shedding minimization is critical.
- Polyethene:Cast film variants offer moisture barrier properties for humidity-sensitive devices. Research facilities with climate-controlled storage requirements specify this format for long-duration sterile field maintenance.
- Non-Woven:Cellulose-based alternatives prioritize incineration compatibility over synthetic barrier performance. European facilities with captive waste-to-energy infrastructure maintain demand despite regulatory pressure toward lighter substrates.
Volume sits with polypropylene; growth tilts toward SMS.
Application:
Procedural setting complexity shapes wrap specification, with automation intensity and sterility assurance requirements creating tiered demand patterns.
- Surgical Instruments:Standard reusable instrument sets require validated sterile barrier systems compliant with ISO 11607. Hospital central sterile processing departments specify SMS or polypropylene grades based on instrument classification and turnover velocity.
- Laboratory Equipment:Diagnostic automation platforms demand high-barrier packaging for reagent cartridges and analytical modules. This segment is expanding most quickly as point-of-care testing decentralizes sterile field requirements beyond traditional surgical suites.
- Medical Devices:Implantable and single-use device manufacturers specify validated sterile barrier systems with documented endotoxin levels. FDA 510(k) clearance requirements for packaging materials constrain supplier qualification.
- Cosmetic Procedures:Aesthetic practice settings prioritize cost-efficient polypropylene grades for non-critical instrument coverage. Medspa volume procurement concentrates in metropolitan United States markets with high outpatient procedural density.
Revenue concentrates in surgical instruments; steepest expansion trajectory belongs to laboratory equipment.
End User:
Procurement centralization intensity varies by facility type, dictating contract structure and fulfillment speed requirements.
- Hospitals:Integrated delivery network consolidation has compressed supplier margins while elevating performance guarantee requirements. Multi-year agreements with bacterial filtration and particle shedding specifications now dominate metropolitan United States markets.
- Surgery Centers:High-throughput outpatient settings prioritize fulfillment velocity and SKU breadth over material innovation. Direct sales infrastructure investments by major distributors target this segment for volume capture.
- Laboratories:Clinical and research laboratory procurement emphasizes traceability documentation and endotoxin testing compliance. EU MDR sterile barrier system requirements elevate technical documentation burdens for substrate suppliers.
- Research Facilities:Academic and pharmaceutical research settings specify custom dimensions and low-volume production runs. Distributor relationships with flexible manufacturing capabilities capture this fragmented demand.
Procurement scale favors hospitals; contract velocity advantages surgery centers.
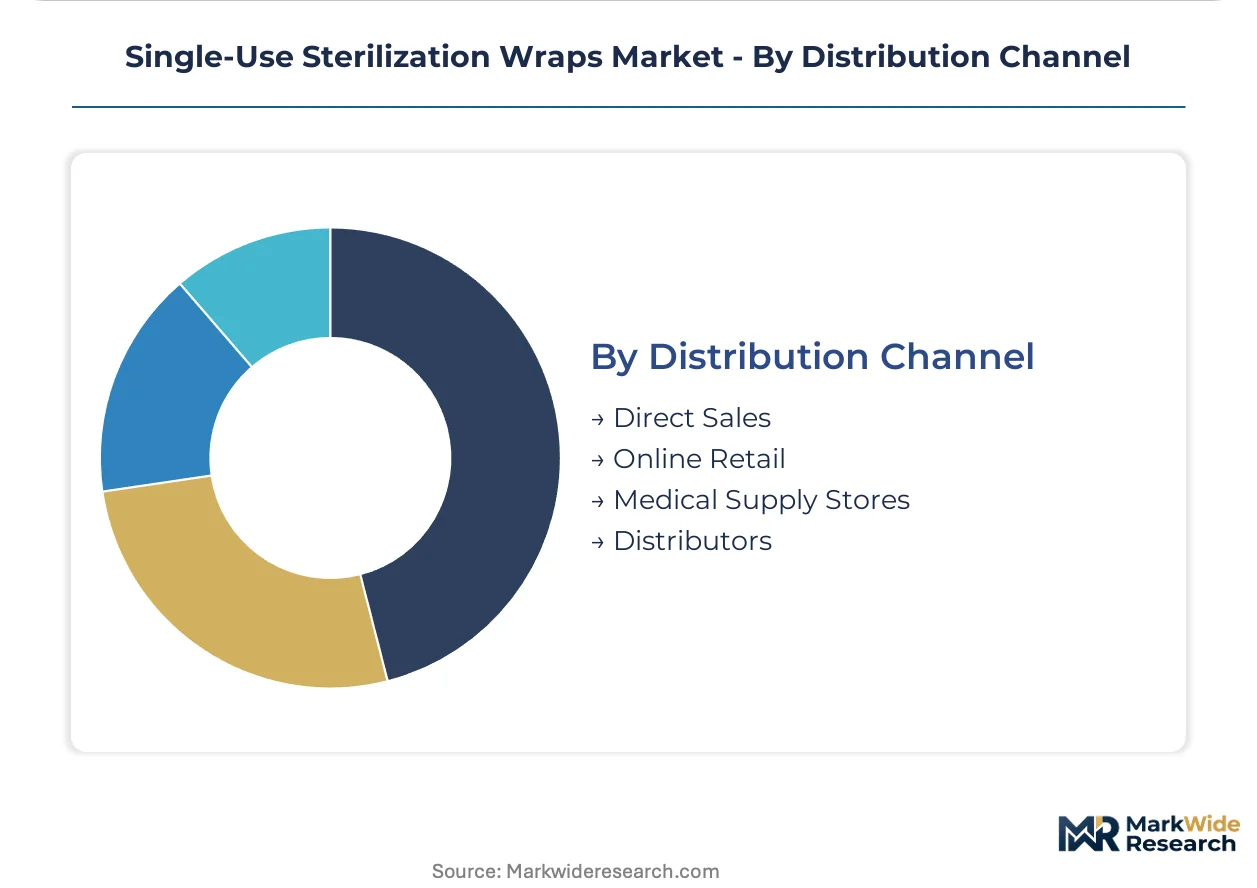
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with direct engagement displacing intermediaries among large accounts.
- Direct Sales:Manufacturer field representatives negotiate multi-year supply agreements with health system materials management. Performance guarantees on bacterial filtration and delivery reliability anchor these relationships.
- Distributors:Group purchasing organization and government channel access concentrates through national distribution networks. Owens & Minor and similar operators dominate this pathway through scale economies and contract aggregation.
- Medical Supply Stores:Regional and local procurement for smaller facilities and emergency restocking maintains this channel's relevance. Fulfillment speed and geographic proximity determine competitive positioning.
- Online Retail:E-commerce platforms serve low-volume purchasers and specialty size requirements with limited technical consultation. Price transparency pressures margin capture in this emerging channel.
Contract value concentrates in direct sales; channel expansion tilts toward distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical device manufacturing in Costa Rica and Malaysia are concentrating sterilization wrap demand near export-oriented production clusters.
United States
Ambulatory surgery center expansion across Texas and Florida drives concentrated procurement of SMS and polypropylene grades. EPA Clean Air Act medical waste standards under 40 CFR Part 60 favor lighter-weight synthetic substrates over cellulose alternatives. The Dallas-Fort Worth metroplex anchors distributor consolidation as Owens & Minor and Cardinal Health compete for integrated delivery network contracts.
Germany
EU MDR sterile barrier system requirements elevate traceability documentation for wraps exported into European markets. REACH chemical compliance and CE marking obligations constrain substrate formulation flexibility for manufacturers serving German hospitals. The Rhine-Ruhr industrial corridor concentrates non-woven textile production serving central European sterile processing departments.
China
NMPA medical device packaging regulations align with ISO 11607 standards to facilitate export eligibility for domestic manufacturers. Dual carbon goals under the 14th Five-Year Plan pressure synthetic wrap producers toward bio-based material transitions. The Yangtze River Delta around Shanghai anchors spunbond non-woven production serving domestic hospital procurement centralization.
India
CDSCO medical device rules and BIS certification requirements elevate quality thresholds for sterilization packaging materials. PLI scheme incentives for medical device manufacturing concentrate demand in Gujarat and Karnataka special economic zones. The Mumbai-Pune pharmaceutical corridor drives sterile barrier procurement for contract manufacturing organizations serving export markets.
Brazil
ANVISA medical device regulations enforce sterile barrier system validation for imported and domestically produced wraps. Mercosur technical standards create regional harmonization pressure on substrate specifications across South American markets. The São Paulo state medical device cluster concentrates demand as hospital procurement consolidates through group purchasing organizations.
Single-Use Sterilization Wraps Market Competitive Landscape
Top-tier vendors anchor hospital system contracting, while mid-scale distributors compete on fulfillment velocity and SKU breadth. The vendor base separates into three functional tiers: direct sales specialists with integrated delivery network relationships, national distributors with group purchasing organization access, and regional fabricators serving custom dimension requirements. Strategic archetypes include scale-driven logistics operators, material science innovators, and compliance-focused validation laboratories. Competitive moves concentrate on multi-year supply agreement negotiation and dedicated validation infrastructure investment.
Within the direct sales tier, Cardinal Health and Medline Industries exemplify archetypes differentiated by fulfillment infrastructure depth rather than material innovation. Owens & Minor occupies a position anchoring government and group purchasing organization channel access through distribution scale. Ahlstrom-Munksjo represents the material science vector among European substrate specialists, while STERIS sits within the sterilization modality integration archetype bridging equipment and consumable supply.
| Leading Market Players |
|---|
| Owens & Minor |
| Ahlstrom-Munksjo |
| Cardinal Health |
| Medline Industries |
| Dynarex Corporation |
| STERIS |
| Kimberly-Clark |
| Cygnus Medical |
| DuPont |
| Others |
Value Network & Pricing Analysis
Polymer engineering talent concentration in the Rhine-Ruhr corridor and the Yangtze River Delta creates labor-cost differentials that widen pricing-tier spreads between European-produced SMS laminates and Asian-manufactured polypropylene grades. Hospital procurement centralization amplifies these spreads as integrated delivery networks negotiate performance-guaranteed contracts that compress margin capture for distributors while rewarding substrate suppliers with validated sterile barrier documentation.
Pricing Analysis
Short lead-time premiums of 15-25% over standard contract pricing capture ambulatory surgery centers facing instrument turnover bottlenecks, while spot inventory discounts of 8-12% clear excess polypropylene spunbond from distributors. Contract-based long-term offtake agreements anchor three-tier pricing structure across premium SMS grades for implantable devices, standard polypropylene for general surgical instruments, and economy cellulose alternatives for non-critical applications. Price differentiation hinges on FDA 510(k) clearance status and ISO 11607 validation documentation. Pricing pressure stems from petrochemical input cost volatility squeezing spunbond manufacturers. Ambulatory surgery centers exhibit highest price sensitivity; hospital systems with infection control mandates show lowest.
Supply Chain Analysis
Dual-sourcing requirements mandated by major integrated delivery networks in the United States and Germany force qualification of secondary substrate suppliers, extending vendor onboarding timelines by 6-12 months. Geographic supply concentration centers on China, Germany, and the United States for spunbond non-woven production, with Malaysia and Costa Rica emerging near medical device manufacturing clusters. Raw material dependencies draw from polypropylene resin, meltblown microfiber intermediates, and cellulose pulp feedstocks. Supply chain risk rests on single-source vulnerability for specialized SMS laminates meeting 98% bacterial filtration thresholds. Distribution runs through national distributors with group purchasing organization contracts, supplemented by direct sales for health system accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA 510(k) clearance requirements for sterilization packaging materials erect barrier-to-entry moats that favor incumbent suppliers with established validation laboratories and documented substrate performance histories.
For Market Incumbents: Extend sterile barrier validation infrastructure into EU MDR-compliant testing facilities to capture export eligibility for European hospital procurement. Fortify direct sales relationships with integrated delivery networks through multi-year performance guarantees on bacterial filtration and particle shedding metrics. Capacity expansion in Malaysia and Costa Rica special economic zones addresses ambulatory surgery center demand near medical device manufacturing clusters. Biodegradable non-woven R&D investment hedges against state-level single-use plastic restrictions threatening polypropylene demand. For New Entrants and Emerging Players: Enter via diagnostic laboratory equipment packaging, the fastest-expanding application segment with less entrenched supplier relationships than surgical instrument markets. Target research facilities and cosmetic procedure settings where custom dimension requirements and lower volume thresholds reduce qualification barriers. White-space concentration appears in smart barrier monitoring technologies incorporating color-change indicators for automated sterility verification. Go-to-market execution should emphasize fulfillment velocity and SKU breadth rather than material innovation. For Investors and Strategic Acquirers: The window for entry favors material science specialists with bio-based substrate pipelines capable of bridging the performance gap to SMS bacterial filtration efficiency. Long-term viability hinges on first-mover positioning in next-generation cellulose alternatives as regulatory pressure on petroleum-based materials intensifies. Acquisition target archetype: mid-scale SMS laminate producers with captive validation laboratories and EU MDR technical documentation capabilities. Signal to watch: state-level single-use plastic restriction enactment timelines accelerating material transition demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Validation Laboratory Investment | CE marking pathway secures export access into German hospital procurement channels. |
| Smart Barrier Technology Integration | Color-change indicator development automates compliance documentation for surgery centers. |
| Bio-Based Substrate R&D Program | Cellulose alternative pipelines hedge EPA Clean Air Act regulatory pressure on synthetics. |
| Direct Hospital System Partnership | Bypassing group purchasing organizations captures margin through fulfillment speed guarantees. |
| Malaysia SEZ Manufacturing Footprint | Proximity to medical device export clusters reduces logistics costs for Asia-Pacific demand. |
Research Methodology
Independent corroboration across hospital procurement databases, FDA 510(k) clearance filings, and EPA medical waste regulation records underwrites the qualitative findings on substrate transition dynamics. Primary interviews with central sterile processing directors, group purchasing organization contract managers, biomedical engineers, and non-woven textile R&D directors combined with secondary validation from ISO standard documentation, customs trade data, and hospital supply chain disclosures. Bottom-up demand modeling across ambulatory surgery center expansion trajectories triangulates against top-down market sizing from distributor revenue disclosures.
Rate-of-change decomposition across material substrate transitions, sterilization modality shifts, and procurement centralization patterns anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, application setting, end-user facility category, and distribution channel structure, with additional granularity on bacterial filtration efficiency tiers and sterilization cycle compatibility. CAGRs derived from volume-weighted average of segment trajectories, incorporating polypropylene resin price indices, ambulatory surgery center construction permits, and diagnostic automation platform deployment data as industry-specific forecast inputs.
Revisions become necessary when EPA medical waste incineration standards tighten beyond current Clean Air Act thresholds, FDA substrate clearance timelines extend materially, or biodegradable non-woven barrier performance achieves SMS-grade bacterial filtration efficiency. Deviation in state-level single-use plastic restriction enactment velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Asia Pacific Industrial Gloves Market
Medical Supplies
Global Enema Bags Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Global Povidone Iodine Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Nitrile Gloves Market