
 Japan Organ Preservation Market | 2026-2036
Japan Organ Preservation Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Organ Preservation Market Intelligence
Hypothermic machine perfusion is reshaping organ viability protocols in Japan, displacing static cold storage for marginal donor organs. Terumo Corporation leverages its cardiovascular device heritage to anchor perfusion pump development. Asahi Kasei Corporation sustains membrane oxygenator R&D for portable preservation units. Nipro Corporation dominates disposable circuit manufacturing for regional transplant networks.
Organ preservation encompasses the controlled maintenance of donor organ viability through temperature-regulated storage, perfusion circuits, and biochemical solutions designed to prevent ischemia-reperfusion injury during procurement-to-implant intervals. Static cold storage retains dominant share for standard criteria kidneys, though machine perfusion claims the fastest expansion as Tokyo transplant centers adopt normothermic regional perfusion for liver grafts. Hospitals represent the most concentrated end-user channel, while research facilities generate premium pricing for experimental oxygen carrier solutions.
PMDA regulates preservation solution classifications under pharmaceutical law, requiring clinical validation for extended storage claims. METI coordinates regenerative medicine infrastructure grants that subsidize perfusion equipment procurement at designated transplant institutions. JIS standards govern cold chain container performance specifications for inter-facility organ transport. Stakeholders must monitor PMDA deliberation timelines for xenograft preservation protocols that could reshape solution formulation requirements.
Market Dynamics
Machine perfusion technology is restructuring procurement patterns across Japanese transplant networks, with PMDA guidance on extended criteria donors accelerating capital deployment toward active preservation systems over static cold storage infrastructure.
Growth Catalysts
- Extended criteria donor protocols:PMDA guidance expanding eligible donor pools drives hospital investment in hypothermic machine perfusion for marginal liver and kidney grafts.
- Living-donor liver programs:Tokyo metropolitan clusters generate concentrated demand for portable preservation units supporting split-liver procedures and transport logistics.
- Regenerative medicine infrastructure:METI funding streams subsidize cold chain equipment procurement at designated transplant institutions, lowering capital barriers for regional centers.
Market Restraints
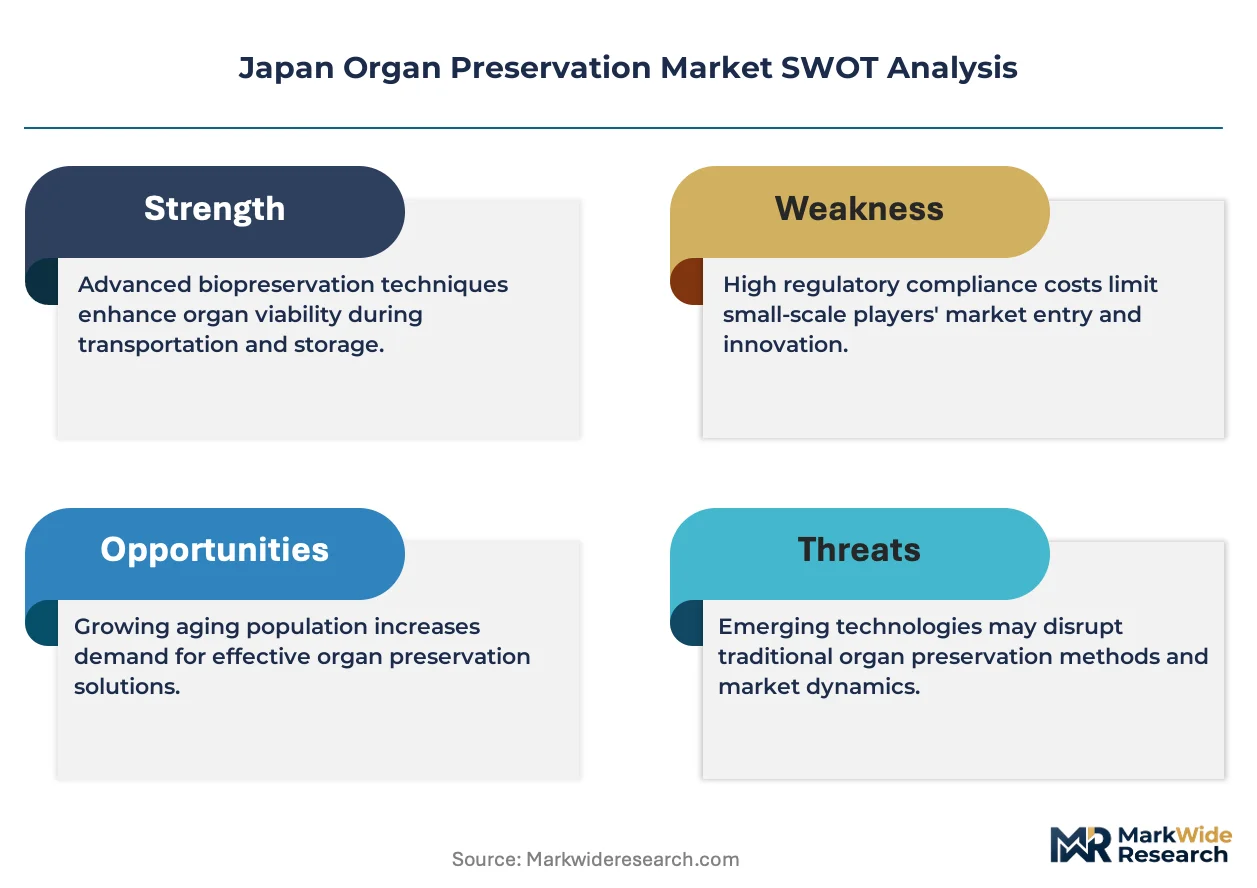
- Perfusion circuit supply concentration:Domestic manufacturing capacity for disposable oxygenator membranes remains limited to three qualified suppliers, creating single-source vulnerabilities.
- PMDA pharmaceutical classification:Preservation solutions face extended clinical validation timelines under pharmaceutical law, delaying formulation innovations for normothermic applications.
- Specialized technician scarcity:Certified perfusionists capable of operating machine systems command premium wages, constraining expansion at secondary transplant centers.
Strategic Opportunities
- Kansai regional network expansion:Osaka and Kyoto transplant hubs remain underpenetrated for normothermic regional perfusion, offering first-mover positioning for equipment vendors.
- Xenograft preservation protocols:PMDA deliberation pathways for porcine organ trials could establish entirely new solution formulation categories ahead of clinical adoption.
- Research facility premium channel:Experimental oxygen carrier development at university hospitals generates pricing power for customized biochemical formulations outside standard procurement.
Industry Challenges
- Perfusionist training pipeline gaps:Japan Society of Perfusionists certifies fewer than fifty new specialists annually, creating operational bottlenecks for machine system deployment.
- JIS cold chain container standardization:Inter-facility transport protocols lack unified performance specifications, forcing hospitals to maintain redundant equipment inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Organ Preservation Market |
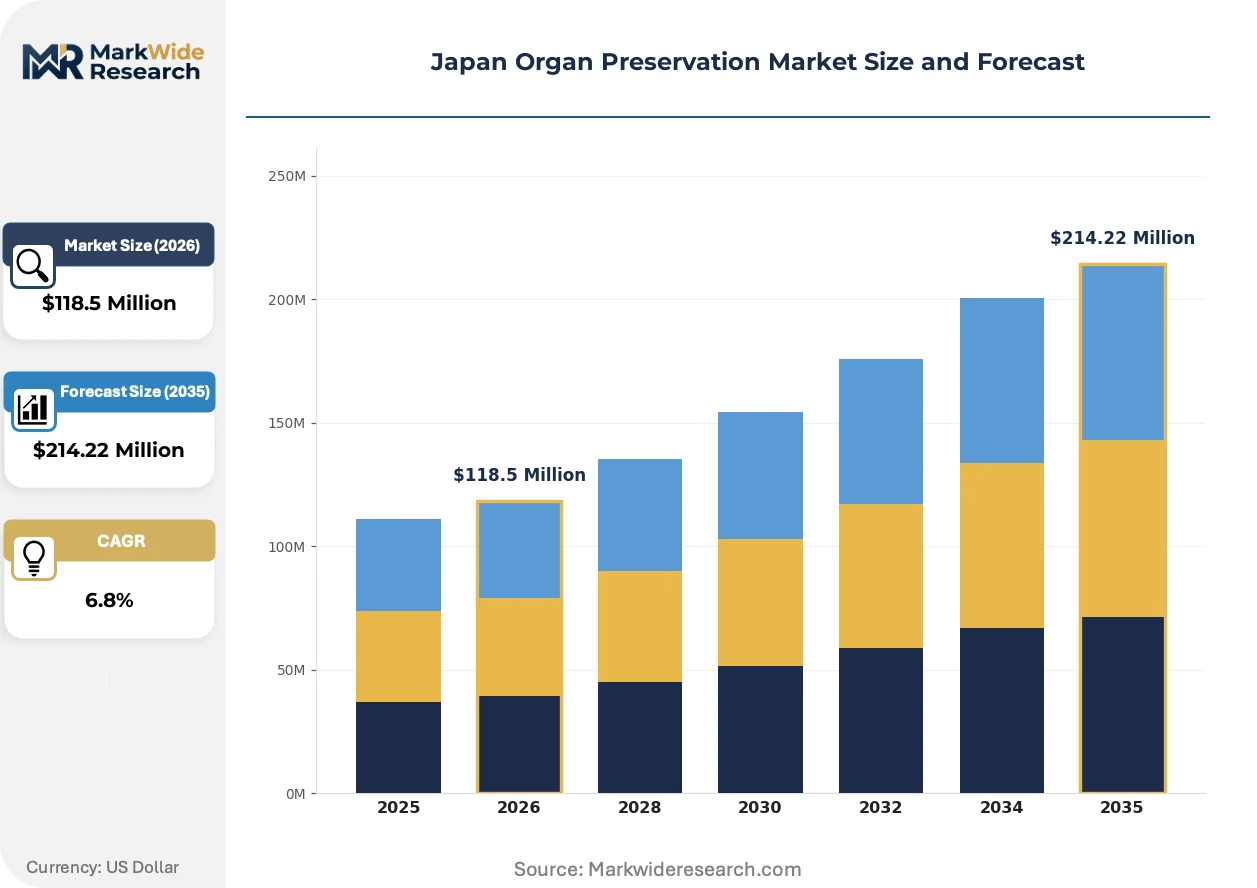
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $214.22 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Devices, Preservation Solutions, Storage Containers, Transport Systems Application: Heart Transplant, Kidney Transplant, Liver Transplant, Lung Transplant End User: Hospitals, Transplant Centers, Research Facilities, Medical Laboratories Technology: Static Cold Storage, Dynamic Preservation, Machine Perfusion, Hypothermic Preservation |
| Companies Covered | PorMedTec, Asahi Kasei Corporation, Terumo Corporation, Takeda Pharmaceutical Company, Fujirebio Holdings, Inc., Nipro Corporation, Heartseed Inc., SanBio Co., Ltd., Japan Tissue Engineering Co., Ltd. (J-TEC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Organ Preservation Market Strategic Shifts & Innovations
Preservation technology is converging toward active metabolic support systems that maintain organ function rather than merely slowing degradation, with regulatory frameworks and procurement models adapting to accommodate these capital-intensive platforms.
Hypothermic machine perfusion systems equipped with integrated oxygen carriers and pressure-controlled pulsatile flow are virtualizing traditional static cold storage workflows. Kanto region transplant centers deploy these platforms for kidney grafts with extended ischemic times. The technology is virtualizing procurement-to-implant logistics by enabling viability assessment during transport rather than at recipient sites.
METI coordinates regenerative medicine infrastructure grants that subsidize perfusion equipment procurement at designated transplant institutions. These funding mechanisms lower capital barriers for secondary centers seeking machine capability. Osaka and Nagoya hospital clusters respond by consolidating procurement through regional purchasing cooperatives to maximize subsidy capture.
Transplant coordinators now specify preservation modality in donor acceptance protocols, with machine perfusion becoming mandatory for certain marginal donor categories. This behavioral shift elevates equipment availability to a determinant of organ utilization rates. Tokyo metropolitan programs exhibit the most pronounced preference compression, rejecting static cold storage for liver grafts exceeding eight hours ischemic time.
Japan Organ Preservation Market Segmentation
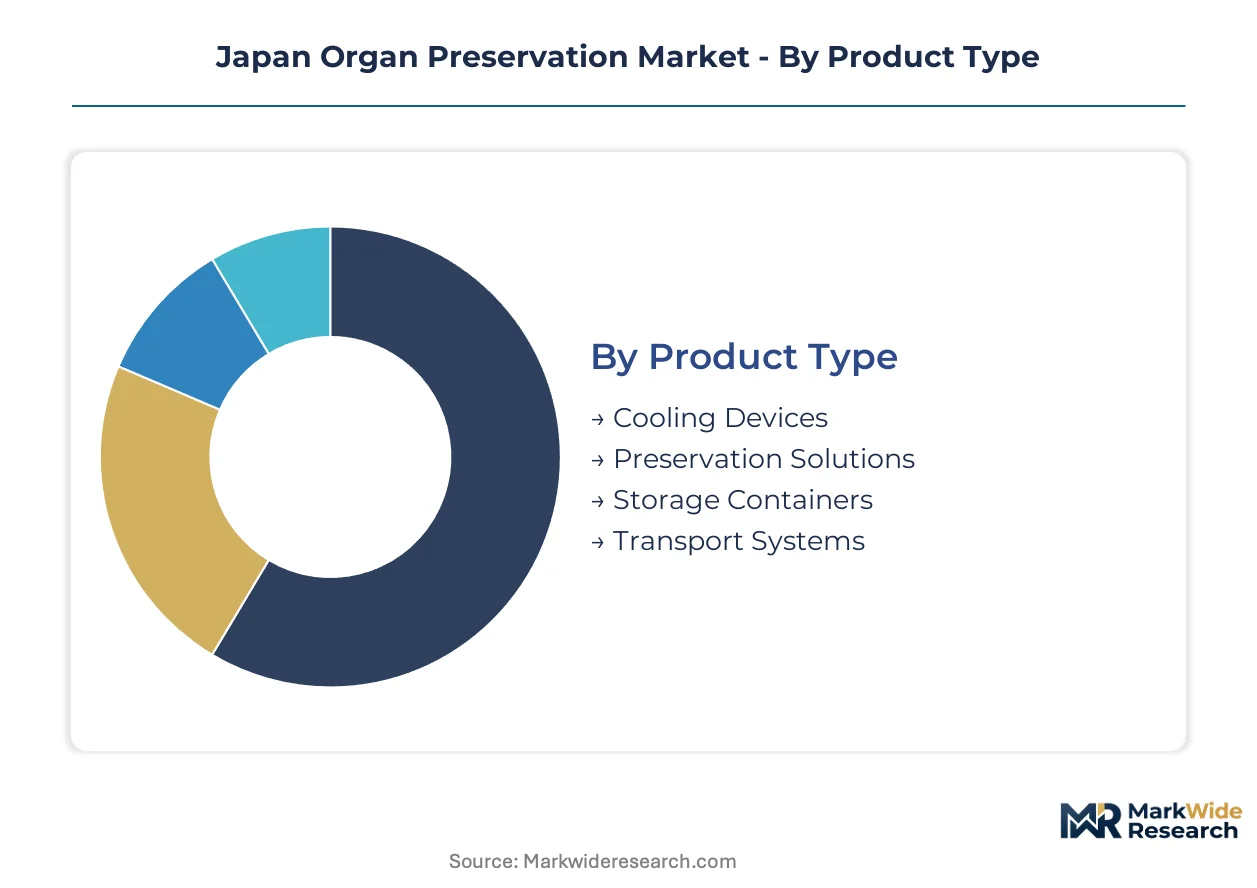
Segmentation in Japan's organ preservation market reveals distinct procurement rhythms across product categories. Cooling devices and disposable solutions turn over rapidly, while capital equipment like perfusion systems cycles slowly through METI-funded replacement schedules.
Product Type:
Cycle times vary dramatically—disposable solutions replenish monthly, cooling devices refresh every 3-5 years, and transport systems amortize over 7-10 year regulatory certification windows.
- Cooling Devices:Temperature-controlled units employing compressor-based or passive phase-change materials for static organ storage. Demand concentrates at Tokyo metropolitan transplant centers where living-donor liver programs require rapid temperature modulation during split-liver procedures.
- Preservation Solutions:Biochemical formulations including University of Wisconsin solution, histidine-tryptophan-ketoglutarate, and proprietary oxygen carriers. Procurement volumes track donor organ acceptance rates at Kanto region hospitals, with PMDA pharmaceutical classification extending validation timelines for novel formulations.
- Storage Containers:JIS-certified insulated vessels for inter-facility organ transport.
- Transport Systems:Integrated cold chain units combining GPS tracking with continuous temperature monitoring.
Preservation solutions anchor the volume base while machine perfusion-compatible oxygen carrier formulations gain share at the steepest rate.
Application:
Cost tiers stratify sharply—liver and heart procedures command premium preservation expenditures, while kidney transplants operate on compressed solution budgets with longer cold ischemic tolerance.
- Kidney Transplant:The most mature application with established static cold storage protocols and extended viability windows. Procurement concentrates at regional transplant networks in Osaka and Nagoya where deceased donor programs dominate and machine perfusion adoption lags Tokyo benchmarks.
- Liver Transplant:Split-liver and living-donor procedures demand portable perfusion capability with real-time viability assessment. Tokyo metropolitan clusters invest most aggressively, rejecting static storage for grafts exceeding eight hours ischemic time.
- Heart Transplant:Requires specialized cardioplegic solutions and short preservation windows.
- Lung Transplant:Emerging application with experimental ex-vivo lung perfusion protocols.
Kidney transplant anchors the volume base while liver transplant applications expand most quickly through living-donor program scale-up.
End User:
Customer type determines procurement authority—hospitals consolidate through regional purchasing cooperatives, while research facilities negotiate directly for experimental formulations.
- Hospitals:General medical institutions performing occasional organ retrievals with basic cold storage infrastructure. Procurement volumes track regional donor referral patterns, with secondary centers dependent on METI equipment subsidies for machine perfusion capability.
- Transplant Centers:Designated institutions with full surgical programs and specialized preservation protocols. Tokyo's metropolitan cluster generates concentrated demand for normothermic regional perfusion systems as PMDA guidance mandates active preservation for marginal donors.
- Research Facilities:University hospitals developing experimental oxygen carriers and xenograft preservation protocols.
- Medical Laboratories:Tissue typing and crossmatch facilities requiring short-term organ holding capability.
Hospitals anchor the volume base while research facilities climb the fastest through premium-priced experimental solution procurement.
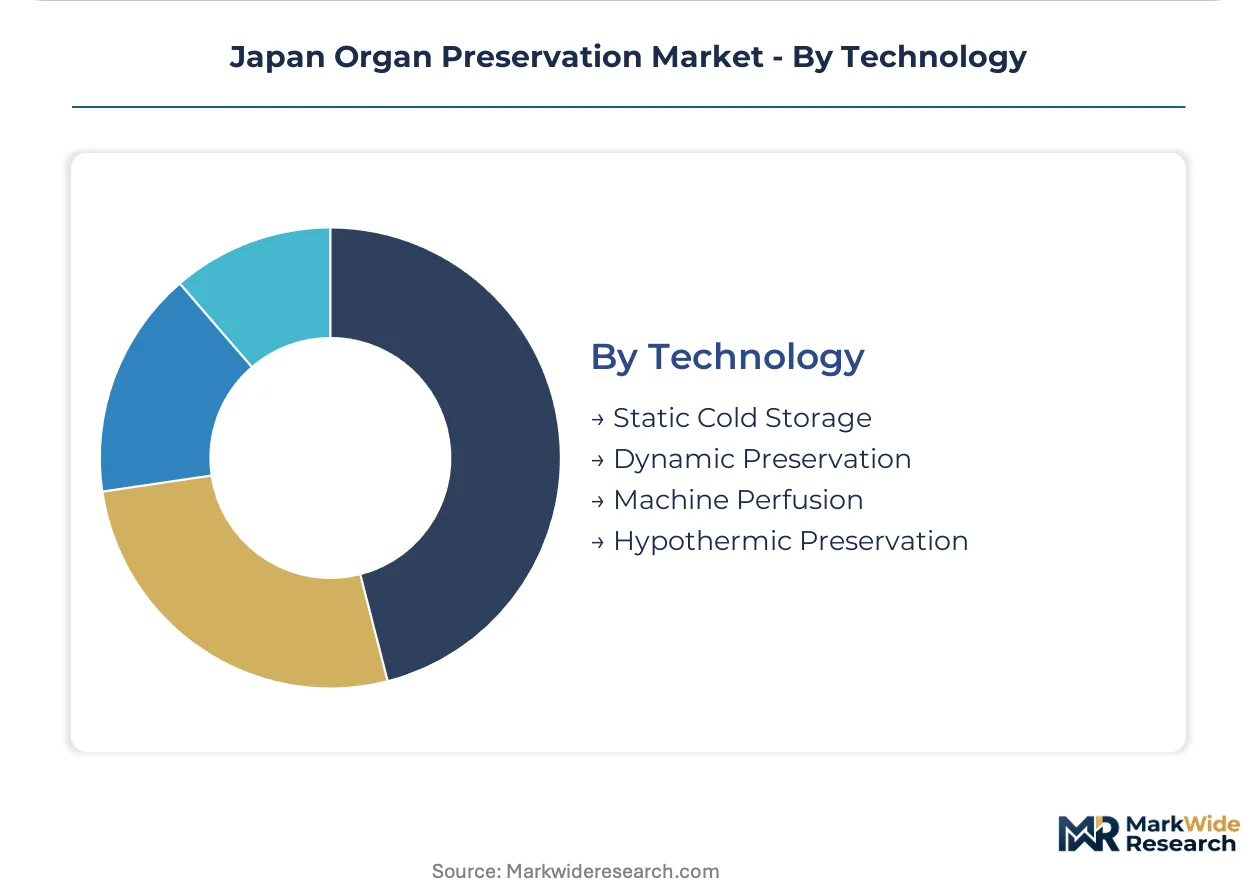
Technology:
Maturity curves diverge—static cold storage represents decades-old infrastructure, while normothermic machine perfusion sits at early commercialization with PMDA validation pathways still evolving.
- Machine Perfusion:Active circulation systems with oxygenated pulsatile flow maintaining metabolic function during preservation. Kanto region centers deploy hypothermic configurations for kidney grafts and normothermic systems for liver viability assessment during transport.
- Static Cold Storage:Ice-based or mechanical cooling without active perfusion, retaining dominant share for standard criteria kidneys. Procurement concentrates at cost-constrained regional centers where technician scarcity constrains machine system operation.
- Dynamic Preservation:Intermediate technologies including oxygen persufflation and subnormothermic perfusion.
- Hypothermic Preservation:Temperature reduction to 4°C with or without machine perfusion support.
Static cold storage anchors the volume base while machine perfusion systems gain share at the steepest rate through PMDA extended criteria donor protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports perfusion equipment and preservation solutions to Taiwan and South Korea as transplant infrastructure expands across Northeast Asia. Regional procurement patterns concentrate in metropolitan hospital clusters where living-donor programs operate at scale.
Kanto/Tokyo
Tokyo metropolitan transplant centers generate concentrated demand for normothermic regional perfusion systems following PMDA guidance on extended criteria donors. METI infrastructure grants subsidize machine perfusion procurement at designated institutions. The Keiyō Industrial Belt anchors domestic manufacturing of disposable oxygenator circuits for regional distribution networks.
Kansai/Osaka
Osaka and Kyoto transplant hubs remain underpenetrated for active preservation technology relative to Kanto benchmarks. PMDA pharmaceutical classification delays novel solution validation for regional hospitals. The Osaka Bay medical technology corridor hosts secondary manufacturing facilities for cold chain transport containers serving western Japan networks.
Chubu/Nagoya
Nagoya hospital clusters consolidate procurement through regional purchasing cooperatives to maximize METI subsidy capture. Technician scarcity constrains machine perfusion deployment at secondary transplant centers. The Chūkyō Industrial Area supplies JIS-certified insulated vessels for inter-facility organ transport across central Japan.
Kyushu
Fukuoka transplant networks rely on static cold storage infrastructure with limited machine perfusion capability. PMDA deliberation timelines for xenograft preservation protocols could reshape regional solution requirements. The Kitakyushu medical device cluster manufactures basic cooling equipment for cost-constrained procurement budgets.
Hokkaido
Sapporo-based transplant programs face extended ischemic times due to geographic isolation from donor sources. METI funding supports cold chain equipment procurement to maintain graft viability during transport. The Ishikari Bay industrial zone produces passive phase-change cooling materials for remote preservation applications.
Japan Organ Preservation Market Key Industry Players
Channel-controlling players compete with product-specialist players across Japan's organ preservation market. Domestic conglomerates with cardiovascular device heritage anchor perfusion pump development, while pharmaceutical firms sustain solution formulation R&D. Three archetypes dominate: diversified medical technology conglomerates, specialized membrane oxygenator developers, and disposable circuit manufacturers. Competitive moves center on METI grant alignment for equipment procurement and PMDA regulatory pathway navigation for solution classifications.
Among diversified technology conglomerates, Terumo Corporation and Asahi Kasei Corporation occupy positions reflecting cardiovascular and materials science heritage. Nipro Corporation exemplifies the disposable circuit specialist archetype serving regional transplant networks. These three entities represent distinct strategic postures within a market where PMDA pharmaceutical law and METI infrastructure funding collectively shape competitive positioning.
| Leading Market Players |
|---|
| PorMedTec |
| Asahi Kasei Corporation |
| Terumo Corporation |
| Takeda Pharmaceutical Company |
| Fujirebio Holdings, Inc. |
| Nipro Corporation |
| Heartseed Inc. |
| SanBio Co., Ltd. |
| Japan Tissue Engineering Co., Ltd. (J-TEC) |
| Others |
Cost & Logistics Intelligence
Domestic manufacturing concentration for disposable oxygenator membranes among three qualified Japanese suppliers concentrates margin capture in the perfusion circuit tier, while downstream transplant centers face asymmetric pricing power during METI subsidy allocation cycles.
Pricing Analysis
Machine perfusion systems command a three-generation pricing spread: legacy static cold storage infrastructure sits at economy positioning, current hypothermic perfusion platforms occupy standard tiers, and emerging normothermic regional perfusion units anchor premium brackets. Price differentiation separates PMDA-validated extended-criteria solutions from standard formulation tiers, with certification level and after-sales technician support bundling driving premium capture. Cost compression in static cold storage intensifies as regional centers consolidate procurement through purchasing cooperatives. Secondary transplant hospitals in Chubu and Kyushu exhibit highest price sensitivity, while Tokyo metropolitan transplant centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Single-source vulnerability in silicone membrane oxygenators dominates supply chain risk exposure between domestic Japanese suppliers and regional transplant networks. Component sourcing draws from domestic polymer manufacturers, German precision pump suppliers, and Taiwanese sensor module providers. Raw material dependencies center on medical-grade silicone elastomers, hollow-fiber membrane substrates, and biocompatible coating chemistries. Distribution runs through METI-designated procurement channels for subsidized equipment, with parallel direct sales for research facility premium formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's organ preservation market sits in early-cycle expansion as PMDA extended criteria donor protocols drive machine perfusion adoption from Tokyo outward through regional transplant networks.
For Market Incumbents: Harden supply chain positioning through captive membrane oxygenator manufacturing or exclusive supplier agreements, as disposable circuit concentration creates vulnerability to import disruption. Deepen technician training partnerships with the Japan Society of Perfusionists to constrain competitor deployment capacity at secondary centers. Prioritize METI grant alignment for normothermic regional perfusion equipment procurement at designated institutions. For New Entrants and Emerging Players: Kansai regional underpenetration offers first-mover positioning for portable perfusion units at Osaka and Kyoto transplant hubs, where machine adoption lags Kanto benchmarks by several procurement cycles. Research facility premium channels generate pricing power for experimental oxygen carrier formulations outside standard hospital procurement. Target university hospital development programs with customized biochemical solutions for xenograft preservation protocols. For Investors and Strategic Acquirers: Secondary-cycle assets sit with cardiovascular device heritage conglomerates seeking to monetize perfusion pump development capabilities accumulated through decades of cardiac surgery equipment manufacturing. Five-to-ten year viability hinges on PMDA deliberation timelines for porcine organ trials that would establish entirely new solution formulation categories. Monitor METI infrastructure grant allocation acceleration as the signal indicating machine perfusion transition from early-adopter to mainstream procurement.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Regulatory Pathway Navigation | Accelerated validation for extended-criteria preservation solutions unlocks premium pricing at Tokyo transplant centers. |
| Technician Training Partnership | Japan Society of Perfusionists certification pipeline constraints create competitive moats for equipment vendors with embedded training programs. |
| Regional Purchasing Cooperative Alignment | Osaka and Nagoya hospital cluster consolidation maximizes METI subsidy capture for machine perfusion procurement. |
| Research Facility Premium Channel Development | University hospital experimental oxygen carrier programs generate pricing power outside standard procurement frameworks. |
| Membrane Oxygenator Backward Integration | Captive silicone membrane manufacturing reduces single-source vulnerability in disposable circuit supply. |
Research Approach
The analysis maps perfusion equipment, preservation solutions, cold chain infrastructure, and transport systems, each validated through transplant surgeons, biomedical engineers, hospital procurement committees, and METI program officers. Primary interviews with perfusion system operators and GPO contracts managers combined with secondary validation against PMDA pharmaceutical classification filings, JIS standard certification records, and METI infrastructure grant disbursement data. Bottom-up equipment shipment tracking and top-down transplant procedure volume estimates provided triangulation anchors.
Fixed assumptions across the modeling period include PMDA extended criteria donor protocol maintenance, METI regenerative medicine funding continuity, and current perfusionist certification throughput. Segmentation dimensions modeled encompass product type, application, end-user category, and technology generation. CAGRs derived from procedure volume growth rates, equipment replacement cycles, and solution consumption per transplant. Forecast inputs incorporated living-donor liver program expansion trajectories and regional transplant network consolidation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or price disruption by cardiovascular device conglomerates would shift outcomes. Macroeconomic contraction affecting METI funding availability, regulatory acceleration of xenograft protocols, or breakthrough static preservation technology could prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Nipple Shield Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Cryopreservation & Fertilization Media Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Global Medical Supplies Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Filter Needles Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Global Biohazard Bag Market