
 Serum-Free Media Market | 2026-2036
Serum-Free Media Market Size, Share, and Industry Trends Forecast 2026-2036
Serum-Free Media Market Outlook
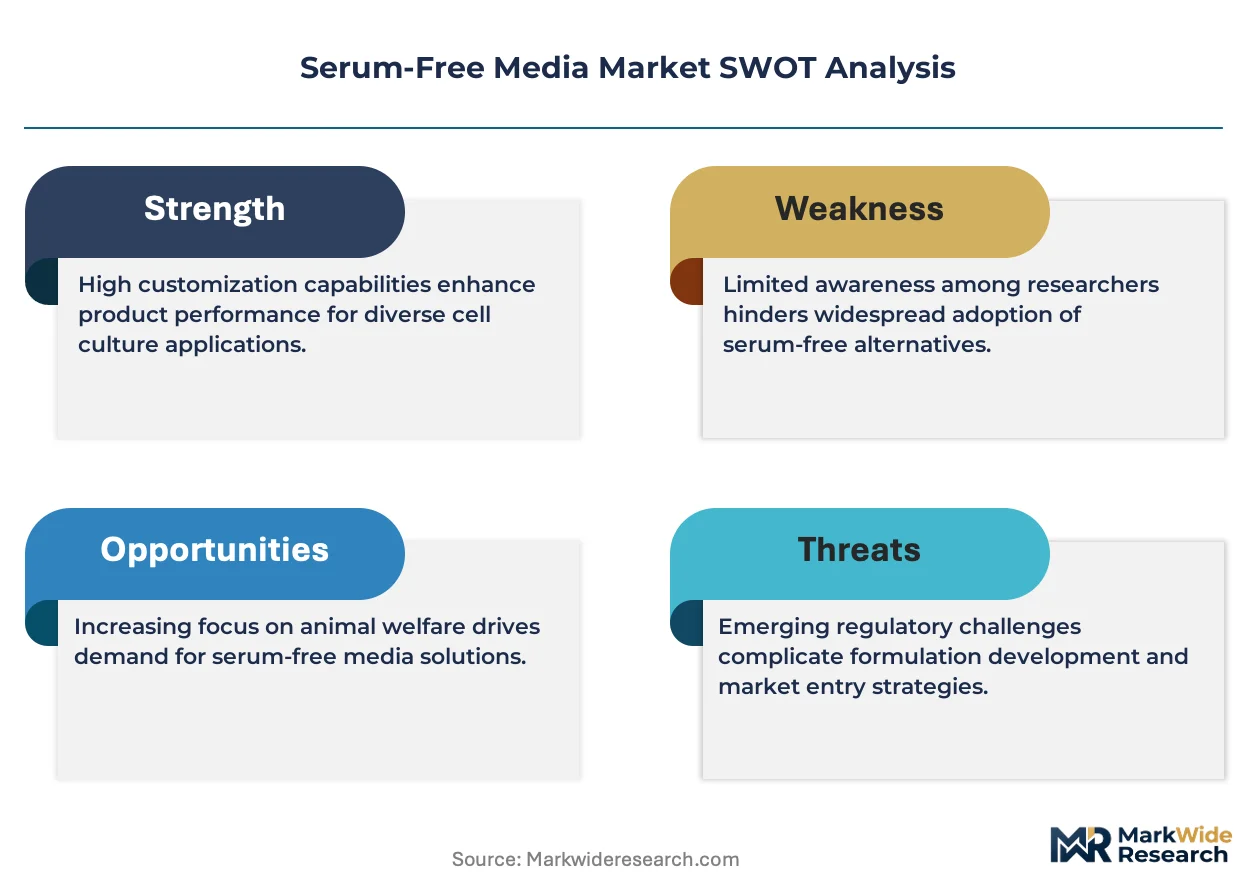
Platform licensing revenue is fragmenting between chemically defined formulations and protein-free alternatives. Thermo Fisher Scientific leverages its Gibco brand portfolio to dominate reagent standardization across North American biologics sites. Merck KGaA anchors European supply through its MilliporeSigma division, which sustains deep R&D ties with German academic research centers. Lonza Group specializes in custom media services for contract manufacturing organizations, while Danaher Corporation controls analytical instrumentation workflows that validate serum-free batch consistency.
Serum-free media refers to nutrient formulations engineered without animal-derived serum components, typically comprising basal media supplemented with defined growth factors, hormones, and trace elements at concentrations between 0.1 and 100 ng per milliliter. These formulations serve the primary purpose of eliminating lot-to-lot variability and immunogenic contamination risks during therapeutic protein and viral vector manufacturing. Cell therapy applications are absorbing the fastest margin expansion as autologous and allogeneic programs scale toward commercial manufacturing. Liquid formulations occupy the dominant share of procurement volumes, though powder and concentrate formats are gaining traction in facilities seeking to reduce cold-chain logistics burdens. Academic research end users represent a mature, price-sensitive segment where competition centers on catalog breadth rather than technical customization.
The FDA enforces Points to Consider guidance on raw materials of animal origin, while EMA's MDR framework and ECHA's REACH protocols impose traceability requirements on European bioprocessing supply chains. China's NMPA has aligned its biosimilar technical guidelines with ICH Q5D standards, compelling domestic manufacturers to validate serum-free alternatives for export-bound production. Stakeholders must monitor how dual-use export controls on precision fermentation equipment reshape regional access to growth factor manufacturing capabilities.
Market Dynamics
Biopharmaceutical manufacturers are consolidating manufacturing footprints around chemically defined media to satisfy FDA and EMA traceability mandates on animal-origin materials, compressing formulation diversity into standardized platforms.
Growth Catalysts
- EMA MDR Traceability Mandates:European bioprocessors must document supply chain provenance for all animal-derived inputs, forcing rapid serum-free validation.
- Monoclonal Antibody Manufacturing Scale-Up:Commercial biologics facilities in the United States and China are retrofitting lines for serum-free batch consistency.
- Cell Therapy Commercialization:Autologous and allogeneic programs require xeno-free formulations to minimize immunogenic risk in patient-derived cell expansion.
Market Restraints
- Recombinant Growth Factor Cost Volatility:Precision fermentation capacity for insulin-like growth factors remains concentrated among contract manufacturers, exposing media formulators to input price swings.
- Chinese Export Control Alignment:NMPA technical guidelines for biosimilar exports compel dual validation runs, extending qualification timelines.
- Serum Substitute Performance Gaps:Plant-derived hydrolysates exhibit lot-to-lot variability in critical quality attributes for viral vector production.
Strategic Opportunities
- Indian Biologics Manufacturing Expansion:CDSCO's alignment with ICH Q5D standards creates first-mover advantage for serum-free platform licensing to domestic biosimilar developers.
- Powder Media Cold-Chain Bypass:Concentrate and dry-powder formats reduce logistics costs for facilities in Brazil and Southeast Asia lacking liquid nitrogen infrastructure.
- ISO 20399 Convergence:International standardization of chemically defined media specifications enables cross-border formulation equivalency claims.
Industry Challenges
- Cell Culture Scientist Talent Scarcity:Formulation optimization for novel bioreactor configurations requires hybrid expertise in metabolomics and statistical design of experiments that outpaces academic pipeline output.
- Legacy Serum-Dependent Cell Line Conversion:Established CHO and HEK293 clones exhibit growth arrest during adaptation to protein-free conditions, demanding extended clone selection cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serum-Free Media Market |
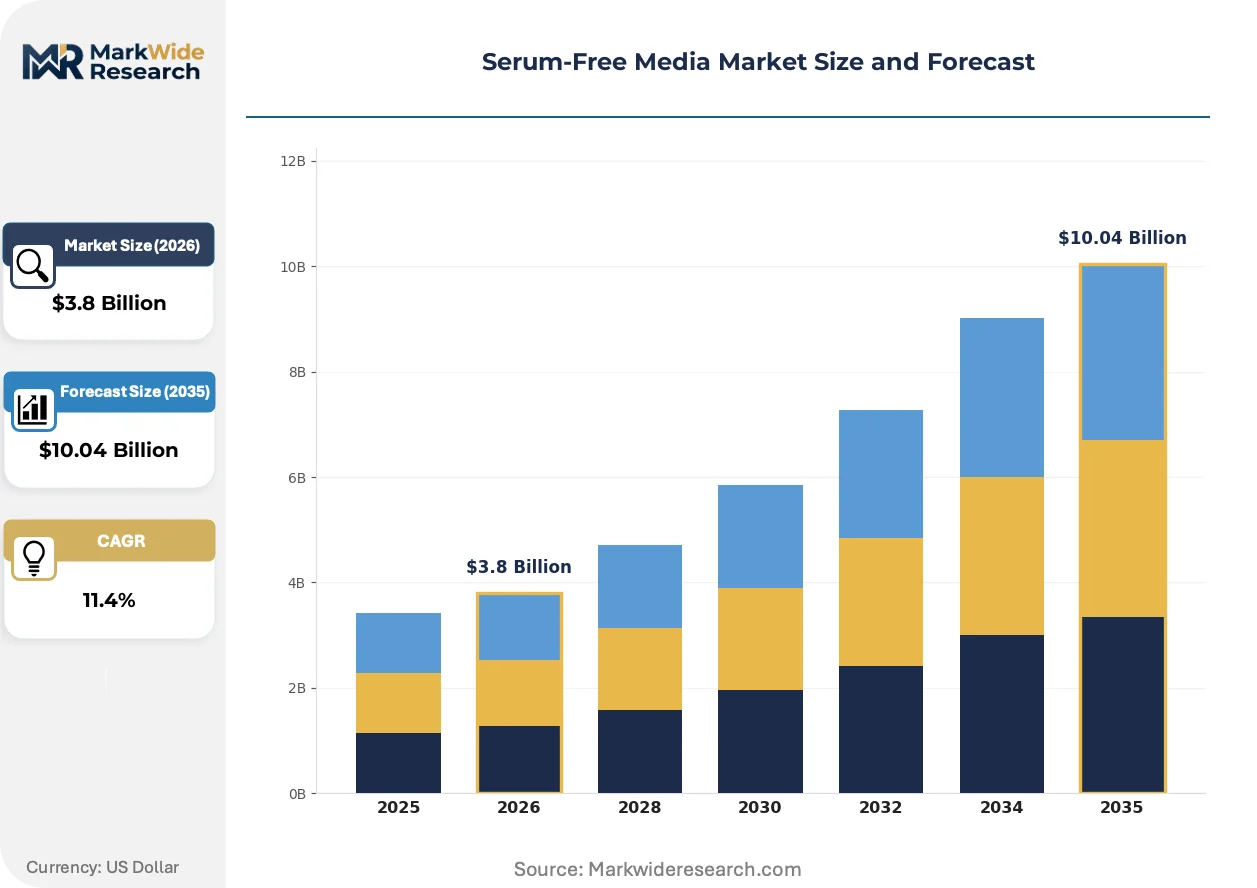
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Culture Media, Supplements, Buffers, Reagents Application: Biopharmaceuticals, Cell Therapy, Vaccines, Diagnostics End User: Academic Research, Pharmaceutical Companies, Contract Research Organizations, Hospitals Formulation: Liquid, Powder, Concentrate, Ready-to-use |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Lonza Group, FUJIFILM Irvine Scientific Inc., Corning Incorporated, Sartorius AG, HiMedia Laboratories, Danaher Corporation, STEMCELL Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serum-Free Media Market Strategic Shifts
Artificial intelligence is compressing media formulation development cycles while regulatory harmonization accelerates platform standardization across biopharmaceutical manufacturing networks.
High-throughput automated bioreactor systems is collapsing traditional Design of Experiments timelines for media optimization. Contract development organizations in Germany and Massachusetts are deploying machine learning algorithms to predict nutrient consumption rates across clone-specific metabolic profiles. This convergence is collapsing the 18-month media development cycle into 6-month qualification windows for commercial manufacturing slots.
EMA's MDR framework and FDA's Points to Consider guidance are converging on single-use technology compatibility requirements for serum-free processes. Bioprocessors must now validate extractables and leachables profiles for plastic-contact materials alongside media composition. Cell therapy manufacturers in Switzerland and the Netherlands are absorbing the highest compliance burden, retrofitting fill-finish lines to satisfy dual jurisdiction inspections.
Integrated supply contracts are displacing spot purchasing for growth factor raw materials. Large molecule CDMOs in South Korea and Ireland are negotiating multi-year offtake agreements with recombinant protein suppliers, locking in volume commitments that exclude smaller media formulators. This concentration is most visible in the United States, where Thermo Fisher and Danaher have secured captive fermentation capacity for insulin-like growth factor-1 production.
Serum-Free Media Market Segmentation
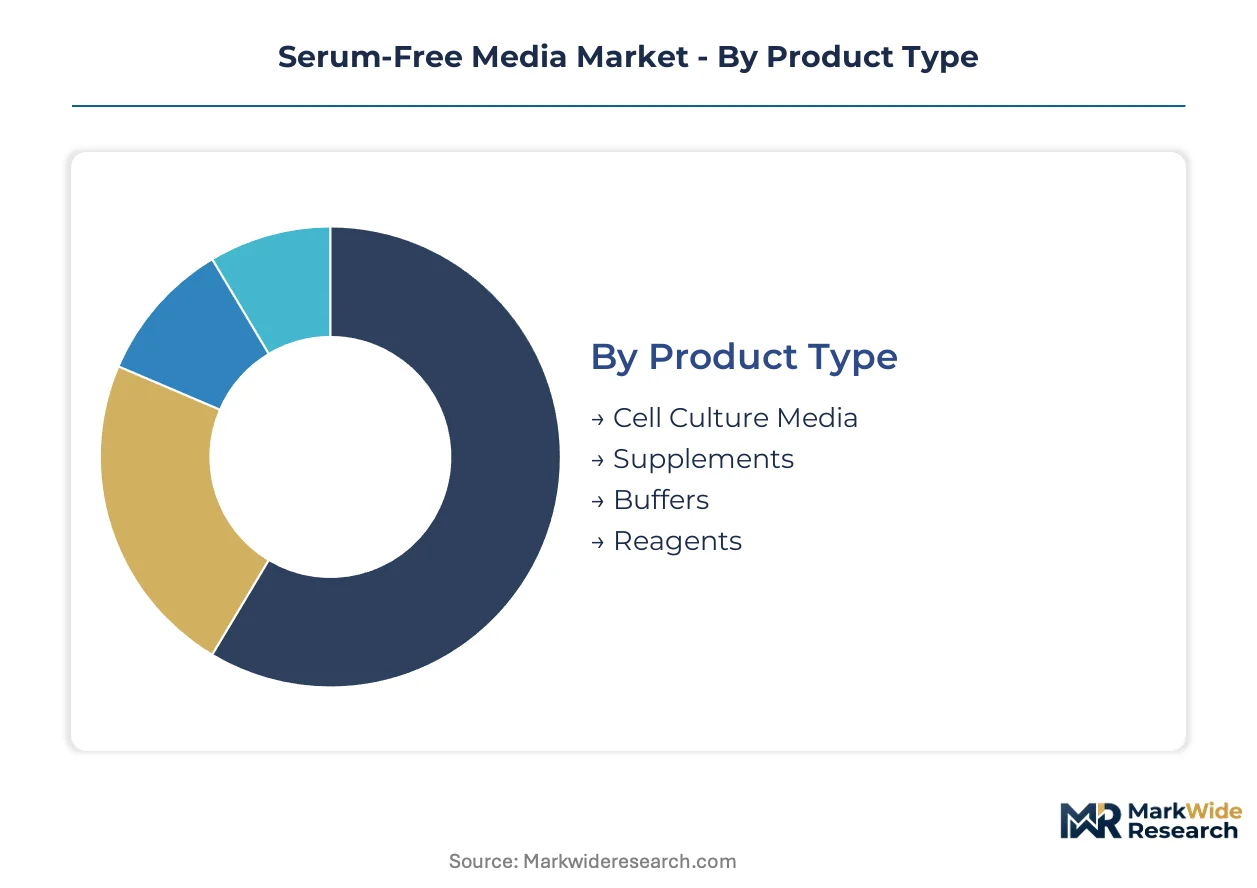
Serum-free media procurement patterns diverge sharply across formulation types and end-user sophistication. Technical support intensity, cold-chain logistics, and regulatory validation requirements reshape margin structures within each segment category.
Product Type:
After-sales service intensity peaks with cell culture media formulations requiring lot-to-lot consistency guarantees and regulatory documentation support.
- Cell Culture Media:Basal formulations and complete media constitute the formulation backbone for CHO and HEK293 bioproduction. Biopharmaceutical manufacturers in Germany and the United States absorb the highest service touchpoints for clone-specific adaptation protocols. Demand concentrates where FDA and EMA traceability mandates force rapid platform conversions from serum-dependent legacy processes.
- Supplements:Defined growth factors, hormones, and trace element cocktails enable customization of basal media for specialized cell lines. Cell therapy developers in Switzerland and the Netherlands drive premium pricing for xeno-free recombinant protein supplements. Precision fermentation supply constraints create intermittent availability gaps for insulin-like growth factor-1.
- Buffers:pH stabilization solutions support media preparation and bioreactor maintenance workflows.
- Reagents:Analytical and detection compounds validate media composition and cell health metrics.
By volume, cell culture media leads. By growth pace, supplements are ahead.
Application:
Cost tier stratification separates commodity vaccine applications from premium cell therapy formulations requiring extensive regulatory dossiers.
- Biopharmaceuticals:Monoclonal antibody and recombinant protein manufacturing consumes standardized chemically defined platforms. Commercial facilities in China and the United States retrofit production lines to satisfy NMPA and FDA guidelines on animal-origin materials. Scale-up timelines compress as CDMOs compete for limited commercial manufacturing slots.
- Cell Therapy:Autologous and allogeneic programs demand xeno-free formulations with exhaustive raw material traceability. Swissmedic and EMA inspections in Switzerland and the Netherlands impose the highest compliance burdens for patient-derived cell expansion. Cold-chain logistics and sterility assurance dominate operational cost structures.
- Vaccines:Viral vector and recombinant subunit production utilizes serum-free platforms for pandemic preparedness manufacturing.
- Diagnostics:Reference standards and control reagents require consistent, defined media for assay calibration.
Biopharmaceuticals commands procurement volumes. Cell therapy exhibits the steepest expansion trajectory.
End User:
Customer type determines pricing elasticity, with academic institutions exhibiting extreme price sensitivity compared to commercial bioprocessors.
- Pharmaceutical Companies:Integrated biologics manufacturers and large molecule developers purchase through multi-year supply agreements with embedded technical service tiers. German and US facilities prioritize formulation standardization across global manufacturing networks. Regulatory validation support and audit readiness constitute core vendor selection criteria.
- Contract Research Organizations:CDMOs and development service providers demand flexible formulation customization with rapid turnaround documentation. Irish and South Korean CROs negotiate captive supply arrangements for recombinant growth factors to secure manufacturing slots.
- Academic Research:University and institutional laboratories prioritize catalog breadth and educational pricing over technical customization.
- Hospitals:Clinical cell processing facilities require GMP-grade media for point-of-care therapeutic manufacturing.
Pharmaceutical companies dominate contract values. CROs are climbing the fastest in procurement growth.
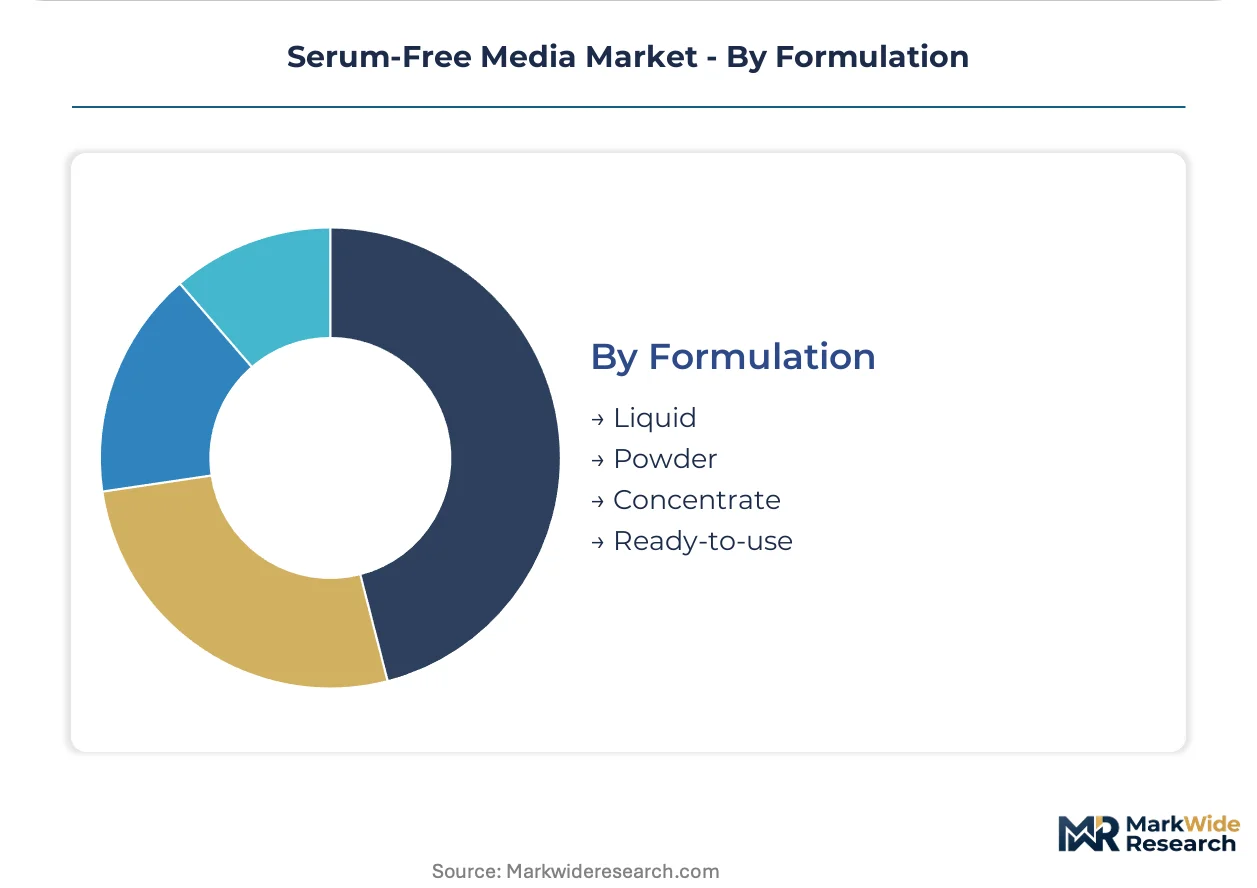
Formulation:
Supply concentration in liquid manufacturing creates logistics vulnerabilities that powder and concentrate formats exploit for geographic expansion.
- Liquid:Ready-to-use solutions dominate procurement volumes for facilities with established cold-chain infrastructure. North American and European bioprocessors favor liquid formats for operational simplicity and reduced contamination risk. Frozen and refrigerated distribution networks concentrate manufacturing proximity near demand clusters.
- Powder:Dry formulations eliminate cold-chain dependencies and extend shelf stability for facilities in Brazil and Southeast Asia lacking liquid nitrogen infrastructure. On-site hydration requires validated water-for-injection systems and trained personnel.
- Concentrate:10X and 50X formulations reduce shipping volumes while preserving formulation flexibility for custom dilution.
- Ready-to-use:Pre-aliquoted single-use formats minimize preparation time for clinical cell therapy applications.
Liquid formulations lead by procurement tonnage. Powder formats are gaining share fastest in emerging manufacturing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic laboratories in India and Southeast Asia exhibit extreme price elasticity, while commercial bioprocessors in Switzerland and the United States absorb premium pricing for regulatory-grade formulations without volume contraction.
United States
FDA Points to Consider guidance on animal-origin materials drives rapid platform conversion at commercial monoclonal antibody facilities. The agency's tightened traceability mandates compress qualification timelines for serum-free validation. Massachusetts and North Carolina biologics clusters retrofit production lines to secure manufacturing slots for export-bound therapeutics.
Germany
EMA MDR framework imposes exhaustive supply chain documentation requirements on European bioprocessors. REACH protocols from ECHA compound traceability burdens for growth factor raw materials. The Rhine-Main and Munich biotech corridors concentrate CDMO activity where MilliporeSigma anchors regional supply through academic R&D partnerships.
China
NMPA alignment with ICH Q5D standards compels domestic manufacturers to validate serum-free alternatives for biosimilar exports. Dual validation runs extend qualification timelines for facilities serving both domestic and international markets. Suzhou and Shanghai biologics parks attract multinational investment in chemically defined media production capacity.
Switzerland
Swissmedic inspections impose the highest compliance burden for cell therapy manufacturers expanding autologous programs. Xeno-free formulation demand concentrates in Basel and Zurich where Novartis and Roche supply chains mandate exhaustive raw material traceability. Cold-chain infrastructure investments support point-of-care therapeutic manufacturing scale-up.
India
CDSCO alignment with ICH Q5D standards creates first-mover licensing opportunities for domestic biosimilar developers. Price-sensitive academic research absorbs catalog breadth from regional formulators rather than technical customization. Hyderabad and Bangalore biotech clusters expand contract manufacturing capacity for export-bound vaccine production.
Serum-Free Media Market Competitive Environment
Diversified life science conglomerates and specialized cell culture suppliers split the market between platform standardization and custom formulation services. Three archetypes dominate: integrated reagent-instrumentation providers, dedicated media specialists, and contract manufacturing service integrators. Capacity expansion in precision fermentation capacity and strategic partnerships for growth factor supply security represent the dominant competitive moves.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the integrated instrumentation-reagent archetype through their Gibco and analytical workflow portfolios. Merck KGaA occupies a parallel position in European supply through its MilliporeSigma division. Lonza Group represents the specialist tier, anchoring custom media services for contract manufacturing organizations. FUJIFILM Irvine Scientific Inc. and STEMCELL Technologies Inc. sit within the dedicated formulation segment, serving cell therapy developers with xeno-free alternatives.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Lonza Group |
| FUJIFILM Irvine Scientific Inc. |
| Corning Incorporated |
| Sartorius AG |
| HiMedia Laboratories |
| Danaher Corporation |
| STEMCELL Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Precision fermentation capacity for recombinant growth factors concentrates in contract manufacturing facilities across South Korea and Ireland, concentrating margin capture upstream while biopharmaceutical formulators downstream absorb input cost volatility through long-term offtake commitments.
Pricing Analysis
After-sales service revenue from regulatory documentation support and clone-specific adaptation protocols drives lifetime value for cell culture media suppliers. Three-tier pricing structure across premium GMP-grade, standard research-grade, and economy catalog formulations separates biopharmaceutical manufacturers from academic laboratories. Cost compression in standard-grade segments is intensifying because regional formulators in India expand catalog breadth at lower price points. Academic research end users exhibit extreme price sensitivity, while cell therapy developers in Switzerland absorb premium pricing without volume contraction.
Supply Chain Analysis
Dual-use export controls on precision fermentation equipment from the United States and European Union limit technology transfer for growth factor manufacturing capabilities to emerging bioprocessing regions. Recombinant protein supply draws from captive fermentation capacity in South Korea, Ireland, and the United States, with insulin-like growth factor-1 production anchored in multi-year offtake agreements. Single-source vulnerability concentrates around contract manufacturers supplying defined growth factors to media formulators. Distribution runs through integrated supply contracts that displace spot purchasing for critical raw materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Serum-free media represents a high-growth disruption as FDA and EMA traceability mandates on animal-origin materials force rapid platform conversion across commercial biologics manufacturing networks.
For Market Incumbents: Harden formulation standardization advantages by securing captive precision fermentation capacity for insulin-like growth factor-1 production, insulating against recombinant protein supply constraints. Deepen technical service capabilities for clone-specific adaptation protocols to defend against emerging CDMOs offering bundled media-manufacturing services. Invest in ISO 20399 certification to enable cross-border formulation equivalency claims.
For New Entrants and Emerging Players: Establish a beachhead in powder media formats for facilities in Brazil and Southeast Asia lacking liquid nitrogen infrastructure, exploiting logistics vulnerabilities that incumbent liquid-format suppliers cannot address. Target price-sensitive academic research segments in India with catalog breadth strategies rather than technical customization. Pursue platform licensing arrangements with domestic biosimilar developers as CDSCO aligns with ICH Q5D standards.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized media formulators with established xeno-free formulation capabilities and deep R&D ties to cell therapy developers, positioned for premium margin capture as autologous programs scale toward commercial manufacturing. Watch for inflection signals in integrated supply contract announcements from large molecule CDMOs, which indicate concentration trends that will reshape competitive access to growth factor inputs.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captive supply of recombinant growth factors insulates Thermo Fisher and Danaher from input price volatility. |
| ISO 20399 Standardization Certification | Cross-border formulation equivalency claims enable MilliporeSigma to standardize across European manufacturing networks. |
| Powder Media Format Development | Cold-chain bypass reduces logistics costs for Lonza Group clients in Brazil and Southeast Asia. |
| Academic R&D Partnership Anchoring | Deep ties with German research centers sustain Merck KGaA's regional supply position against price-competitive entrants. |
| Cell Therapy Custom Formulation Services | Xeno-free adaptation protocols position STEMCELL Technologies for premium pricing in Swissmedic-regulated autologous programs. |
Study Parameters
The analysis maps cell culture media formulations, growth factor supplements, and buffer-reagent portfolios, each validated through cell culture scientists, bioprocess engineers, regulatory affairs leads at biopharmaceutical manufacturers, and procurement managers at contract manufacturing organizations. Primary interview insights triangulate against FDA Points to Consider guidance documents, EMA MDR framework submissions, NMPA technical guidelines, customs trade data for growth factor imports, and SEC filings from diversified life science conglomerates. Bottom-up demand modeling from end-user procurement patterns converges with top-down supply capacity assessments across precision fermentation facilities.
Assumptions around regulatory harmonization timelines and recombinant protein manufacturing capacity expansion were held fixed across the projection horizon, while cell therapy commercialization rates and biosimilar approval trajectories were varied across scenarios. Segmentation dimensions include formulation type, application area, end-user sophistication tier, and geographic regulatory cluster. CAGRs derive from weighted average growth across these segments, with inputs from biologics manufacturing capacity buildout announcements and CDMO manufacturing slot availability indicators.
Stress conditions across precision fermentation capacity constraints, dual-use export control enforcement intensity, and cell therapy clinical trial success rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Material shifts in FDA or EMA traceability mandate implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
US Disposable Face Mask Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Cryotubes Market
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
Luer Plug Market
Medical Supplies
Global Sharps Containers Market