
 Medical Gloves Market | 2026-2036
Medical Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Gloves Market Analysis
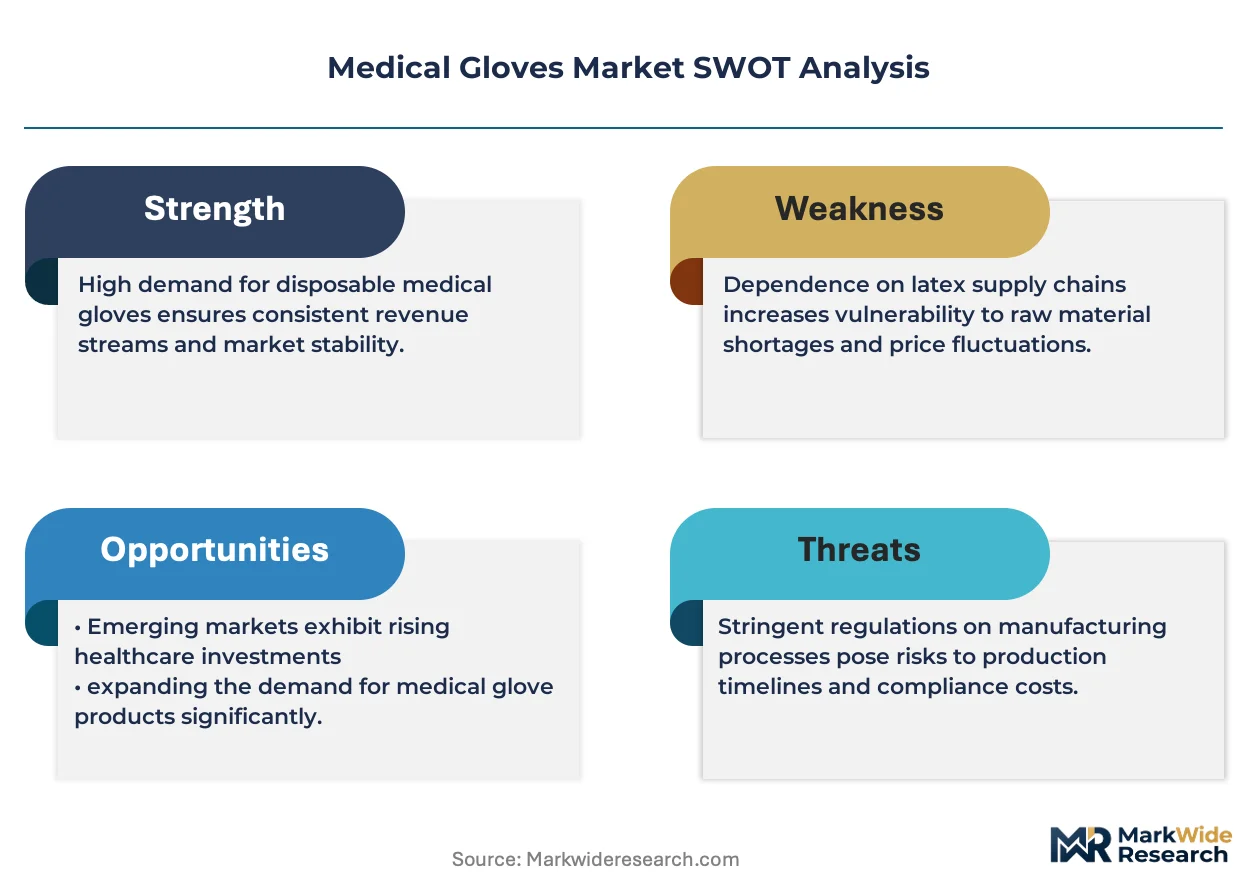
Aftermarket sterilization validation services is reconfiguring margin pools away from commodity glove production toward compliance-centered offerings. Top Glove Corporation Bhd leverages integrated nitrile butadiene rubber sourcing to sustain cost leadership across examination-grade volumes. Hartalega Holdings Berhad anchors premium positioning through proprietary thin-gauge nitrile formulations with enhanced tactile sensitivity. Ansell Limited competes in surgical segments through differentiated chemo-rated and extended-cuff product architectures.
Medical gloves are disposable or reusable hand coverings manufactured from latex, nitrile, vinyl, or polyethylene, typically ranging from 3 to 15 mil in thickness, designed to prevent pathogen transmission and chemical exposure during patient contact or laboratory procedures. Their primary purpose is to maintain aseptic barriers between healthcare workers and biological hazards while preserving manual dexterity. Nitrile material segments command expanding share due to latex allergy prevalence and superior puncture resistance, though vinyl persists in cost-sensitive examination settings. Sterile glove demand clusters in surgical applications where terminal sterilization via gamma irradiation or ethylene oxide processing creates margin premiums above non-sterile examination alternatives.
FDA Quality System Regulation and ASTM D6319/D6978 standards govern barrier performance and chemotherapeutic drug permeation resistance in the United States, while EU MDR and CE marking requirements under the EU AI Act's broader health product traceability mandates reshape European market access protocols. These frameworks compel manufacturers to maintain validated sterilization processes and biocompatibility documentation, effectively raising capital barriers for new entrants. Stakeholders must monitor evolving nitrile raw material price volatility against sustained hospital procurement consolidation to calibrate capacity expansion timing and product mix allocation.
Market Dynamics
Hospital procurement consolidation is compressing distributor margins and forcing manufacturers to absorb compliance costs directly, while Malaysia's Klang Valley production cluster concentrates nitrile butadiene rubber compounding capacity under unified quality frameworks.
Growth Catalysts
- FDA Quality System Regulation:ASTM D6319 tactile sensitivity standards are elevating barrier performance requirements, forcing subscale producers to exit and consolidating volume among validated manufacturers.
- Surgical suite expansion:Tertiary hospitals are expanding glove consumption per procedure through double-gloving protocols and extended-cuff chemo-rated specifications.
- Nitrile butadiene rubber:Superior puncture resistance and latex allergy elimination are displacing natural latex in examination-grade volumes across North American acute care networks.
Market Restraints
- Acrylonitrile price volatility:Nitrile raw material costs fluctuate with petrochemical feedstock markets, compressing margins for non-integrated compounders.
- Klang Valley concentration risk:Over 60% of global nitrile glove capacity sits within a 50-kilometer radius, exposing buyers to localized labor disruptions or environmental enforcement actions.
- Vinyl substitution ceiling:Polyethylene alternatives lack the tensile strength for surgical applications, trapping cost-sensitive buyers in an inferior performance tier.
Strategic Opportunities
- EU MDR traceability mandates:Unique device identification requirements under the EU AI Act's health product protocols create premium positioning for manufacturers with validated serialization systems.
- Home healthcare expansion:Post-acute and long-term care facilities in Germany and France are adopting hospital-grade glove specifications for wound care and catheter management.
- Sterilization-as-a-service:Third-party gamma irradiation and ethylene oxide validation providers are capturing margin pools previously retained by integrated manufacturers.
Industry Challenges
- Biocompatibility documentation gaps:ISO 10993 cytotoxicity and sensitization testing timelines extend product launch cycles by 8-14 months for novel nitrile formulations.
- Legacy ERP integration:Batch record automation and electronic device history file systems require capital deployment that mid-tier producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Gloves Market |
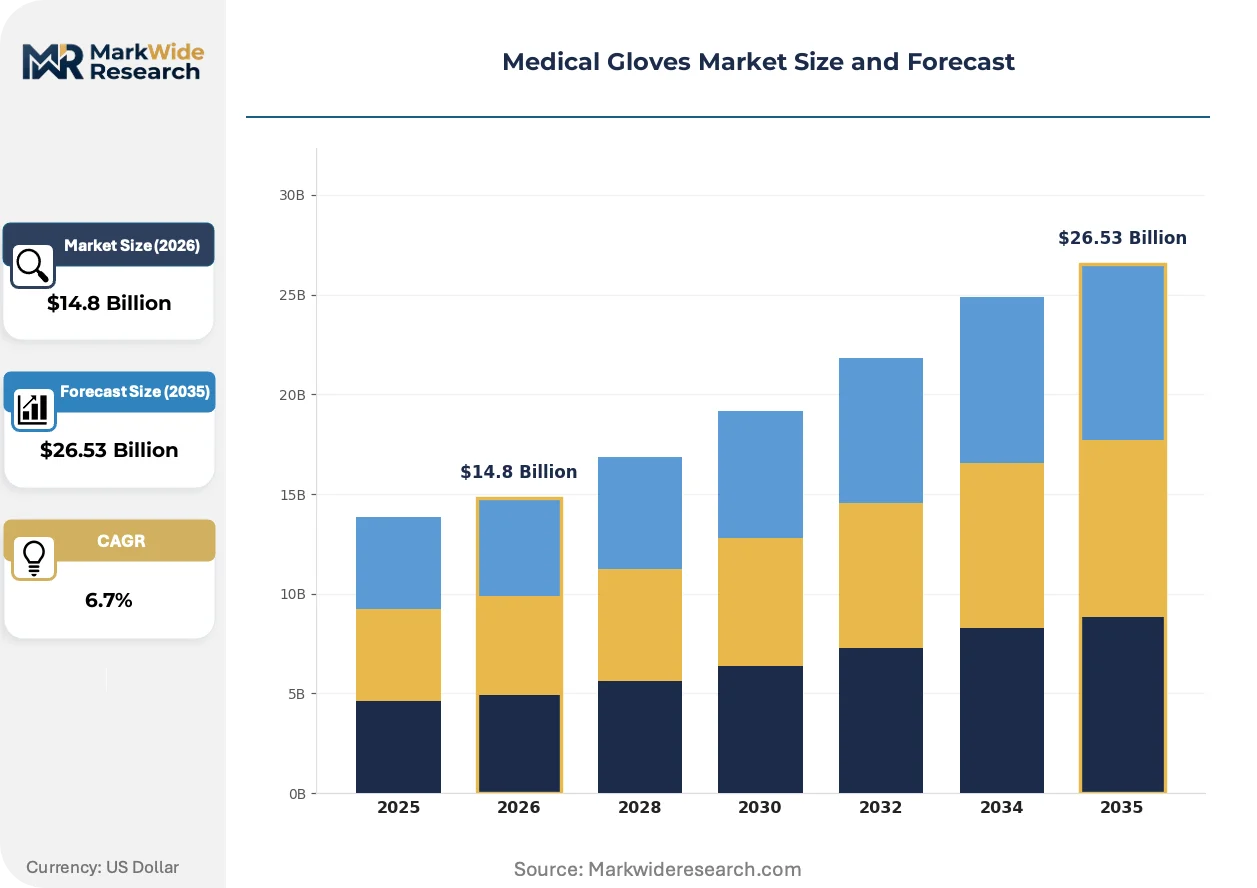
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Sterile, Non-Sterile Material: Latex, Nitrile, Vinyl, Polyethylene End User: Hospitals, Clinics, Dental Practices, Laboratories Application: Examination, Surgical, Protective, Household |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Ansell Limited, Kossan Rubber Industries, Supermax Corporation Berhad, Cardinal Health, Medline Industries, Kimberly-Clark Corporation, Molnlycke Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Gloves Market Emerging Trajectories
Material science convergence and regulatory digitization are compressing product lifecycles while elevating performance thresholds across sterile and non-sterile segments.
Thin-gauge nitrile formulations are hybridizing polymer crosslinking techniques with surface chlorination processes to achieve sub-4-mil thickness without sacrificing tensile strength. Surgical teams in academic medical centers are adopting these ultra-thin specifications for microsurgical procedures requiring haptic precision. The technology is hybridizing cost structures across premium and standard tiers, enabling single-facility production of multiple performance grades.
EU MDR Article 10 technical documentation requirements and the EU AI Act's health product traceability mandates are forcing manufacturers to deploy serialized unit-of-use labeling. European notified bodies are extending conformity assessment timelines for legacy latex products lacking clinical evidence packages. German and French hospital procurement consortia are now requiring MDR-compliant certificates of conformity as table-stake bidding qualifications.
Consolidated buying cooperatives are displacing traditional two-step distribution in North American acute care. Integrated delivery networks in Texas and California are negotiating direct manufacturer contracts with volume commitments exceeding 50 million units annually. This channel compression is most visible in surgical glove categories where sterile packaging and lot traceability justify bypassing distributor markups.
Medical Gloves Market Segmentation
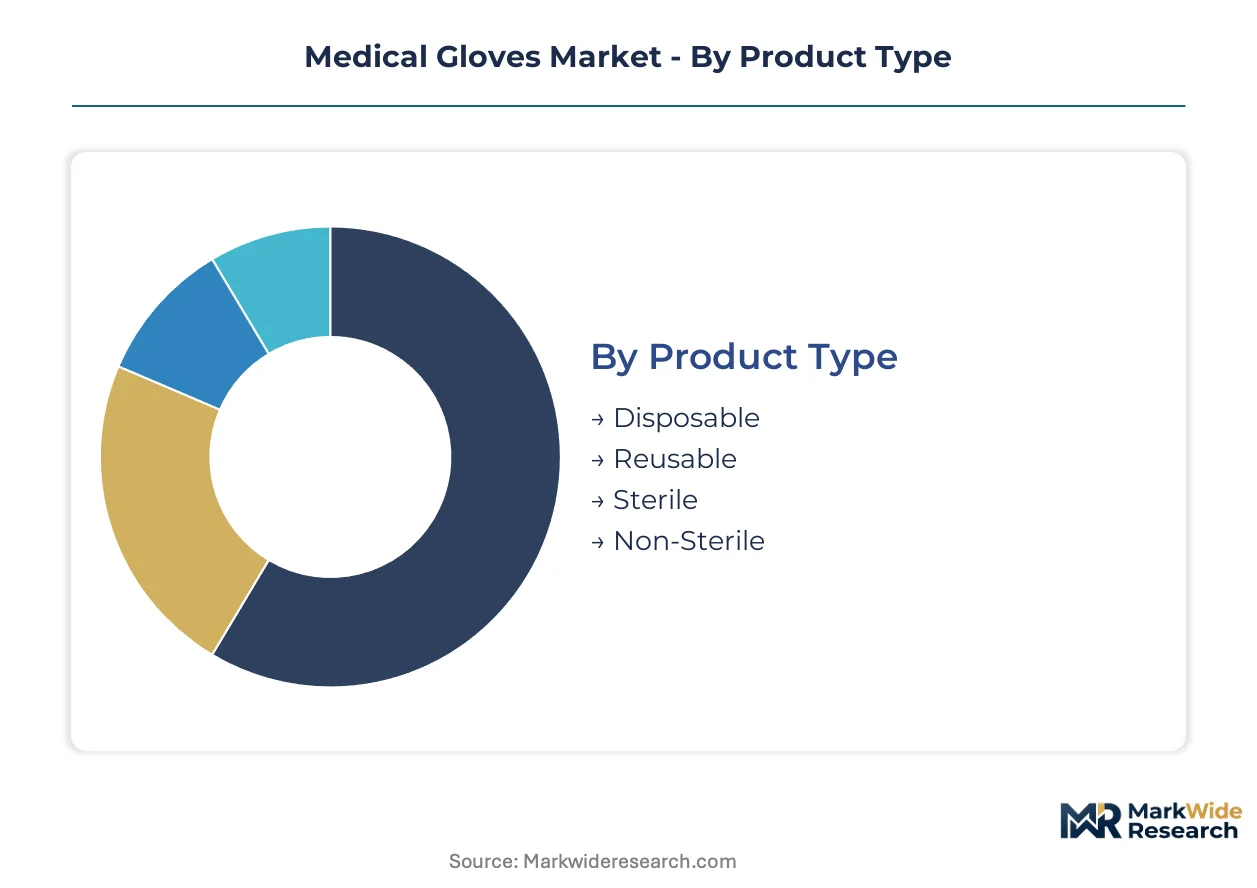
Medical glove procurement operates across distinct technical and usage boundaries that determine inventory velocity, sterilization requirements, and margin capture. Manufacturers calibrate production lines against these segment boundaries to optimize capacity allocation between high-turnover examination volumes and premium surgical tiers.
Product Type:
Cycle times vary dramatically across this category, with non-sterile examination gloves turning monthly while sterile surgical inventory carries 90-day validation windows.
- Disposable:Single-use nitrile and latex formulations dominate acute care procurement through high-volume automated dispensing systems. Hospital networks in Texas and California negotiate direct contracts exceeding 50 million units annually, compressing distributor margins.
- Sterile:Terminal sterilization via gamma irradiation or ethylene oxide processing adds 15-20% cost premiums and extends quality assurance timelines. Tertiary surgical suites in academic medical centers drive specifications for extended-cuff and chemo-rated variants.
- Reusable:Silicone and heavy-gauge rubber gloves persist in industrial laboratory settings where chemical resistance outweighs convenience factors. Limited penetration in clinical environments due to laundering validation costs.
- Non-Sterile:Examination-grade volumes flow through consolidated buying cooperatives with minimal lot traceability requirements. Vinyl alternatives concentrate in cost-sensitive long-term care facilities.
Disposable dominates installed base. Sterile is where expansion concentrates.
Material:
Raw material selection cascades through tensile strength specifications, allergen profiles, and petrochemical price exposure.
- Nitrile:Acrylonitrile-butadiene copolymer delivers superior puncture resistance and eliminates Type I hypersensitivity risks. Malaysia's Klang Valley cluster concentrates compounding capacity for North American hospital networks.
- Latex:Natural rubber maintains dominance in microsurgical applications requiring maximum tactile sensitivity. FDA enforcement of ASTM D6319 standards is elevating barrier performance requirements for remaining latex volumes.
- Vinyl:Polyvinyl chloride formulations serve cost-constrained examination settings where tensile strength requirements are minimal. German and French procurement consortia exclude vinyl from surgical bidding qualifications.
- Polyethylene:Cast film gloves occupy food-handling adjacent medical applications with minimal durability demands. Limited clinical penetration due to seam integrity failures under stress.
Nitrile dominates installed base. Nitrile is also where expansion concentrates.
End User:
Customer scale determines packaging configurations, from bulk institutional pallets to unit-dispensed retail formats.
- Hospitals:Integrated delivery networks command customized sterile packaging with serialized lot tracking for surgical suites. Double-gloving protocols in tertiary facilities are expanding per-procedure consumption rates.
- Clinics:Outpatient settings prioritize non-sterile examination gloves in space-efficient dispenser boxes. Procurement flows through group purchasing organizations with quarterly volume commitments.
- Dental Practices:Specialized nitrile formulations with textured fingertips address grip requirements for instrument manipulation. Smaller order quantities favor distributor intermediaries over direct manufacturer relationships.
- Laboratories:Research facilities specify extended-cuff and chemo-rated variants for hazardous material handling. EU MDR traceability mandates are reshaping certificate of conformity requirements for European research institutions.
Hospitals dominate installed base. Laboratories represent the steepest expansion trajectory.
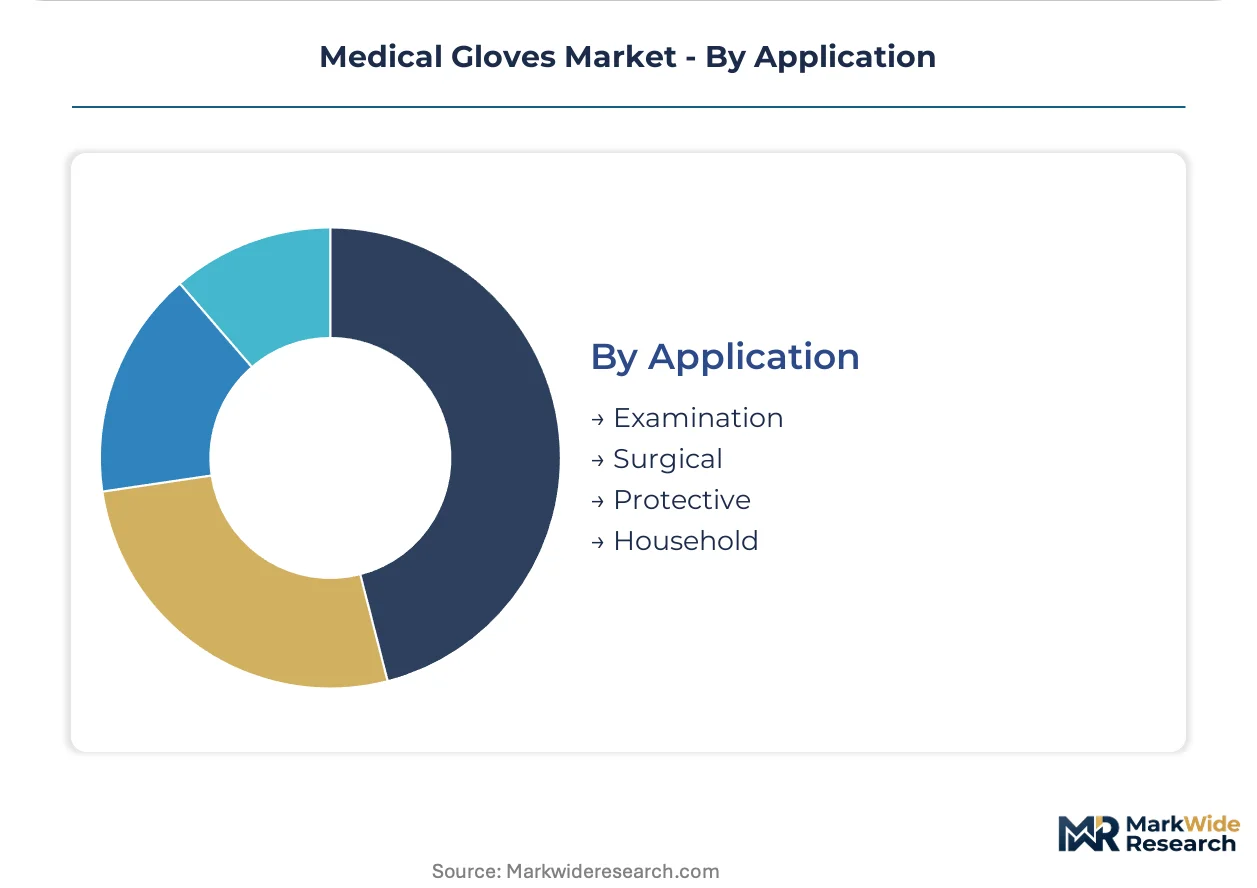
Application:
Clinical risk tiering separates barrier performance standards, from minimal protection in non-clinical settings to validated chemotherapeutic drug resistance.
- Surgical:Sterile packaging, extended cuffs, and ASTM D6978 chemo-rated specifications command premium positioning. Thin-gauge nitrile formulations below 4 mil are gaining adoption in microsurgical procedures.
- Examination:High-velocity consumption in emergency departments and primary care drives cost-optimized nitrile and vinyl procurement. Automated dispensing systems are reducing unit labor costs in high-throughput settings.
- Protective:Industrial and research applications specify chemical resistance and extended wear durability. Limited overlap with clinical glove specifications due to divergent testing protocols.
- Household:Consumer retail channels carry non-medical grade variants with minimal regulatory oversight. Price sensitivity drives polyethylene and thin-gauge vinyl concentration.
Examination dominates installed base. Surgical is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Klang Valley concentrates over 60 percent of global nitrile glove capacity within a 50-kilometer radius, creating supply-side leverage that shapes procurement economics across North American and European hospital networks. This geographic clustering amplifies both efficiency gains and concentration risk for buyers dependent on just-in-time sterile glove deliveries.
United States
Integrated delivery networks in Texas and California negotiate direct manufacturer contracts exceeding 50 million units annually, bypassing traditional distributor markups. FDA enforcement of ASTM D6319 tactile sensitivity standards and Quality System Regulation elevates barrier performance requirements, forcing subscale producers to exit. Sterile surgical glove demand concentrates in academic medical centers adopting double-gloving protocols and extended-cuff chemo-rated specifications.
Germany
Hospital procurement consortia in Bavaria and North Rhine-Westphalia require MDR-compliant certificates of conformity as table-stake bidding qualifications, reshaping supplier qualification timelines. EU MDR Article 10 technical documentation requirements and the EU AI Act's health product traceability mandates force manufacturers to deploy serialized unit-of-use labeling. Post-acute and long-term care facilities across Hesse and Baden-Württemberg are adopting hospital-grade glove specifications for wound care and catheter management.
Malaysia
Nitrile butadiene rubber compounding capacity in Selangor and Kuala Lumpur serves North American and European buyers under unified quality frameworks, though localized labor disruptions or environmental enforcement actions expose concentration risk. Top Glove Corporation Bhd and Hartalega Holdings Berhad anchor integrated production clusters with captive raw material sourcing. The country's rubber product manufacturing heritage supports backward integration into nitrile polymer production that non-integrated compounders cannot replicate.
France
ANSM oversight of medical device conformity assessment extends timelines for legacy latex products lacking clinical evidence packages, compressing viable supplier lists. Île-de-France hospital networks and Auvergne-Rhône-Alpes procurement alliances are consolidating glove purchasing through centralized tenders that favor manufacturers with validated sterilization documentation. Third-party gamma irradiation and ethylene oxide validation providers are capturing margin pools previously retained by integrated manufacturers.
China
NMPA medical device registration requirements and GB standards for disposable rubber gloves create parallel compliance pathways distinct from FDA or CE marking routes. Yangtze River Delta and Pearl River Delta production zones serve domestic hospital procurement and export markets with cost-optimized nitrile formulations. The country's petrochemical feedstock access moderates acrylonitrile price volatility exposure compared to Southeast Asian compounders dependent on imported monomers.
Medical Gloves Market Vendor Landscape
Scale-driven integrated producers and specialized premium-tier manufacturers split the market between high-volume examination-grade supply and differentiated surgical segments. Malaysian-domiciled players dominate nitrile butadiene rubber compounding through backward integration into polymer production, while Western healthcare conglomerates compete via sterile packaging expertise and direct hospital contracting relationships. Two strategic archetypes prevail: integrated nitrile compounders with captive raw material sourcing, and diversified health products groups with surgical suite channel access. Competitive moves concentrate on capacity expansion timing against raw material price cycles, and M&A targeting sterilization validation capabilities.
Within the integrated Malaysian tier, Top Glove Corporation Bhd exemplifies scale-driven cost leadership through examination-grade volume dominance, while Hartalega Holdings Berhad occupies a premium positioning anchored by proprietary thin-gauge nitrile formulations. Ansell Limited represents the diversified health products archetype with surgical segment focus through chemo-rated and extended-cuff product architectures. These three players illustrate the strategic divergence between commodity-scale nitrile production and compliance-centered premium positioning.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Ansell Limited |
| Kossan Rubber Industries |
| Supermax Corporation Berhad |
| Cardinal Health |
| Medline Industries |
| Kimberly-Clark Corporation |
| Molnlycke Health Care |
| Others |
Supply Flow & Price Mechanics
Malaysia's Klang Valley production cluster concentrates over sixty percent of global nitrile glove capacity within a fifty-kilometer radius, granting integrated compounders substantial leverage over hospital procurement networks in North America and Europe. This geographic chokepoint amplifies pricing power for validated manufacturers while exposing buyers to localized disruption risks.
Pricing Analysis
Sterilization-as-a-service revenue streams now drive lifetime value capture beyond unit glove sales, with third-party gamma irradiation and ethylene oxide validation providers extracting margins previously retained by integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates chemo-rated surgical specifications from examination-grade volumes, with FDA Quality System Regulation compliance costs widening spreads between validated and subscale producers. Cost compression in standard examination tiers intensifies because hospital procurement consolidation forces manufacturers to absorb compliance investments directly. Group purchasing organizations demonstrate highest price sensitivity, while academic medical centers prioritize barrier performance over unit cost.
Supply Chain Analysis
Top Glove Corporation Bhd and Hartalega Holdings Berhad anchor contract-manufacturing concentration through integrated nitrile butadiene rubber compounding facilities in Selangor and Kuala Lumpur. Malaysia, Thailand, and Indonesia dominate upstream acrylonitrile-butadiene copolymer production, drawing from petrochemical feedstock markets in Singapore and the Middle East. Single-source vulnerability concentrates in Klang Valley labor pools and environmental enforcement jurisdictions. Distribution runs through consolidated buying cooperatives in Texas and California, displacing traditional two-step distributor channels for high-volume sterile glove contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical glove demand follows cyclical recovery patterns tied to hospital capital expenditure cycles, with surgical suite expansion in tertiary facilities indicating upward phase entry.
For Market Incumbents: Pre-empt margin erosion from sterilization-as-a-service providers by acquiring third-party validation capabilities or building captive gamma irradiation capacity. Secure backward integration into nitrile polymer production to buffer acrylonitrile price volatility. FDA enforcement of ASTM D6319 standards presents consolidation opportunity to absorb subscale competitor volume. For New Entrants and Emerging Players: Post-acute and long-term care facilities in Germany and France represent the most penetrable entry point, as these settings adopt hospital-grade specifications without requiring sterile packaging infrastructure. Specialized thin-gauge nitrile formulations for dental practices offer differentiation path with lower capital barriers than surgical segments. Direct contracting with regional group purchasing organizations bypasses distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory digitization under EU MDR and FDA Quality System Regulation raises capital barriers faster than organic growth can overcome. Acquisition targets should display validated serialization systems and existing notified body relationships. Watch for acrylonitrile price inflection as signal for integrated compounder margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Polymer Production | Captive acrylonitrile-butadiene sourcing buffers Malaysian compounders against petrochemical feedstock volatility. |
| CE Marking Pathway under EU MDR | Serialized unit-of-use labeling compliance opens German and French hospital procurement consortia to qualified manufacturers. |
| Hospital System Partnership | Direct contracts exceeding fifty million units annually with Texas and California integrated delivery networks displace distributor intermediaries. |
| Sterilization Validation Capability Acquisition | Gamma irradiation and ethylene oxide processing expertise recaptures margin pools from third-party service providers. |
| Thin-Gauge Nitrile R&D Investment | Sub-4-mil formulations with preserved tensile strength command premium positioning in microsurgical applications. |
Methodological Framework
The analysis maps sterile surgical, non-sterile examination, and chemo-rated protective glove segments, each validated through hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs leads at Malaysian manufacturers. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data enabled bottom-up and top-down triangulation across volume and value estimates.
Forecasts assume stable FDA enforcement intensity and EU AI Act implementation timelines across the projection horizon, with segmentation dimensions spanning material type, sterility grade, end-user facility tier, and regional regulatory cluster. CAGRs derived from procedure volume growth, per-procedure consumption rate trends, and procurement consolidation patterns, with nitrile raw material price cycles and hospital capital expenditure cycles as industry-specific sensitivity inputs.
Practitioners should monitor Klang Valley labor disruption indicators, acrylonitrile price volatility spikes, and EU notified body capacity constraints for early signals of forecast revision. Quarterly review of hospital procurement tender awards, sterilization validation backlog durations, and Malaysian environmental enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Microcarrier Market
Medical Supplies
Medical Liners Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Disposable Medical Supplies Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Hydrocolloid Sponges Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Compression Stockings Market