
 Latin America Biodegradable Food Service Disposables Market | 2026-2036
Latin America Biodegradable Food Service Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Biodegradable Food Service Disposables Market Intelligence
The capital-intensity divergence between integrated biopolymer producers and finished-goods assemblers is unwinding competitive stability in Latin America's biodegradable disposables sector. Huhtamaki Oyj leverages its captive PLA sourcing and regional thermoforming footprint to sustain margin control across Brazil and Mexico. Ajover-Darnel anchors its position through vertical integration into sugarcane bagasse pulping in Colombia, while Vegware Ltd. competes via specialized compostable coatings that navigate varying municipal compost standards.
Biodegradable food service disposables comprise single-use tableware engineered from plant-derived polymers, molded fiber, or coated paperstock designed to decompose under industrial composting conditions within 90 to 180 days, with primary commercial purpose of replacing petroleum-based serviceware in high-volume food service environments. PLA-based cutlery dominates material value capture due to resin price volatility and performance thresholds for hot-food contact, while sugarcane bagasse plates occupy the fastest-expanding volume tier as Brazilian and Mexican mills convert agricultural residue into molded pulp capacity. Catering and events applications concentrate premium pricing power where temporary service mandates eliminate reuse economics and demand certified compostable verification.
Brazil's ANVISA and Mexico's COFEPRIS regulate food-contact migration limits for biopolymer serviceware, while INMETRO and NOM-252-SSA1-2011 standards shape compostability certification requirements that determine market access for imported and domestic manufacturers. Argentina's INTI and Chile's SUBPESCA frameworks are converging toward regional alignment on marine biodegradability testing protocols, creating compliance complexity for cross-border suppliers. Stakeholders must monitor whether municipal composting infrastructure deployment outpaces material certification timelines, as facility availability dictates actual end-of-life performance and consumer willingness to pay compostable premiums.
Market Dynamics
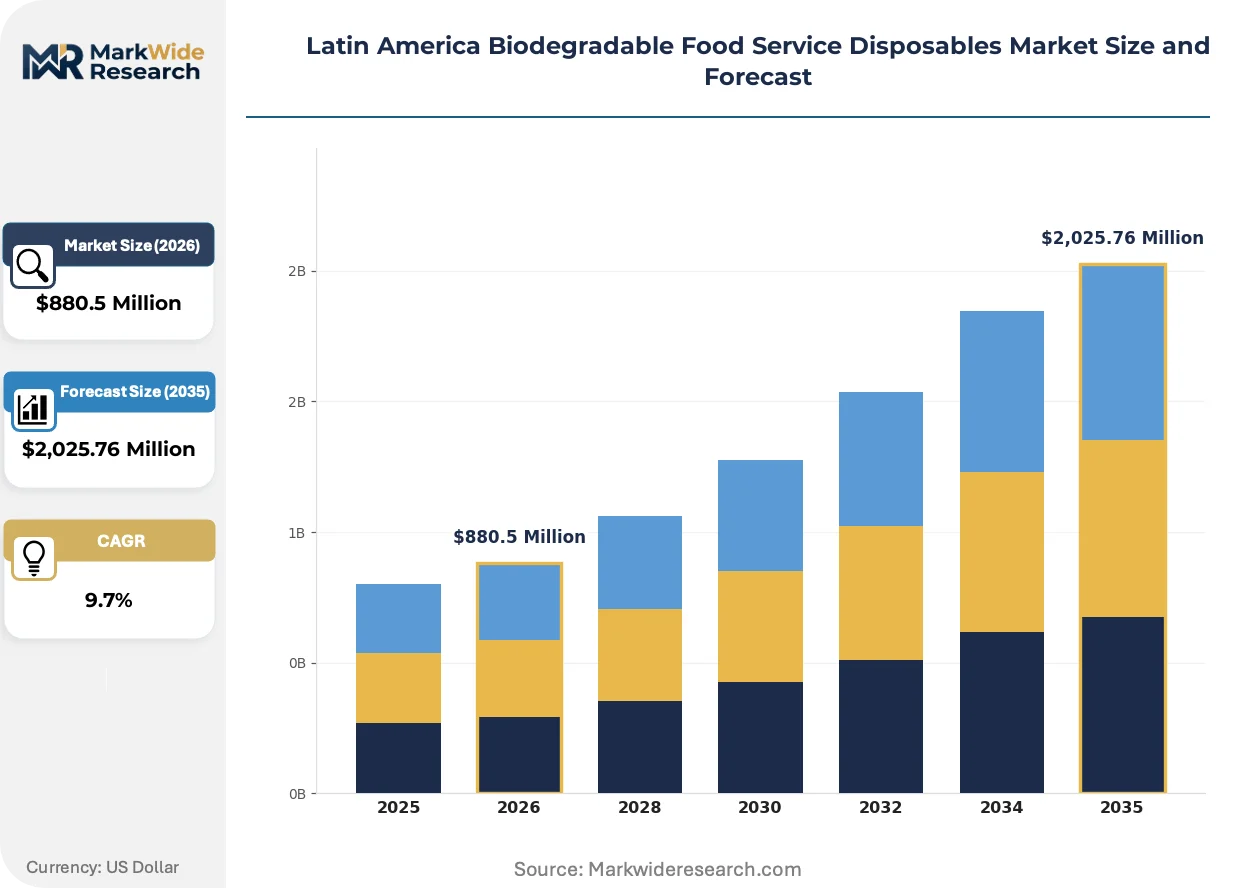
Industrial composting infrastructure deployment across Brazil and Mexico is outpacing material certification standardization, creating a structural lag between supply-side capacity and demand-side verification requirements that reshapes competitive positioning in Latin America's biodegradable disposables sector.
Growth Catalysts
- ANVISA Migration Limits:Brazil's food-contact safety standards for biopolymer serviceware are accelerating domestic manufacturing compliance investments and displacing uncertified imports from regional supply chains.
- Quick-Service Restaurant Conversion:Brazil's São Paulo state and Mexico's central corridor are witnessing systematic replacement of petroleum-based serviceware with compostable alternatives in high-volume food service environments.
- Sugarcane Bagasse Pulping:Colombian agricultural residue processing capacity is expanding molded fiber plate production, capturing volume-tier demand from catering and events applications requiring certified compostable verification.
Market Restraints
- PLA Resin Volatility:Polylactic acid feedstock price swings compress margin stability for cutlery manufacturers dependent on corn-derived polymer supply chains concentrated in North American and Asian sources.
- Cross-Border Certification Friction:Argentina's INTI and Chile's SUBPESCA marine biodegradability testing protocols are diverging from Brazilian INMETRO standards, fragmenting regional compliance requirements for multi-country suppliers.
- Petroleum-Based Substitution:Conventional polypropylene serviceware retains cost advantages in price-sensitive institutional procurement, particularly where municipal composting facility access remains limited.
Strategic Opportunities
- Peripheral State Expansion:Brazil's Minas Gerais and Rio de Janeiro states present underpenetrated demand corridors where urban food service density is accelerating faster than local compostable supply infrastructure.
- Coating Technology Convergence:Integration of compostable barrier coatings with molded fiber substrates is decomposing performance limitations for hot-liquid contact applications previously reserved for plastic-lined alternatives.
- Municipal Waste Mandate Tailwinds:Mexico's evolving state-level organic waste diversion requirements are creating procurement preference shifts toward verified compostable serviceware in government-contracted food service operations.
Industry Challenges
- Certification Timeline Compression:INMETRO and NOM-252-SSA1-2011 compostability verification processes require 12-18 month approval cycles that lag behind product development and commercial launch schedules.
- Industrial Composting Facility Scarcity:Actual end-of-life decomposition performance depends on facility availability that remains concentrated in São Paulo and Mexico City metropolitan zones, limiting market expansion into secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Biodegradable Food Service Disposables Market |
| Market Size in 2026 | $880.5 Million |
| Market Size in 2035 | $2,025.76 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cutlery, Straws Material: PLA, Bamboo, Sugarcane, Cardboard Application: Catering, Events, Restaurants, Food Trucks End User: Food Service Operators, Caterers, Retailers, Consumers |
| Companies Covered | Huhtamaki Oyj, Dart Container Corporation, Vegware Ltd., Biopak Pty Ltd., Sabert Corporation, Grupo Bimbo S.A.B. de C.V., ITC Limited, Ajover-Darnel, Carvajal, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Biodegradable Food Service Disposables Market Strategic Shifts & Innovations
Material science advancement and regulatory convergence are actively reshaping competitive differentiation in Latin American biodegradable serviceware, with coating technologies and certification standardization emerging as primary vectors of value capture.
Barrier coating formulations derived from polylactic acid and polyhydroxyalkanoate blends are decomposing the performance gap between molded fiber and plastic-lined serviceware for hot-food applications. Quick-service chains across Brazil's southeastern states are adopting these substrates at accelerated procurement cycles. This technology is decomposing traditional material segmentation in the cutlery and clamshell categories.
COFEPRIS is tightening food-contact migration limit enforcement for imported biopolymer serviceware, forcing Asian manufacturers to establish local testing partnerships or cede shelf space to certified domestic producers. Mexican distributors are responding by consolidating supplier relationships around COFEPRIS-prequalified inventory pools. The quick-service restaurant segment bears primary compliance burden as volume procurement contracts require documented certification maintenance.
Catering procurement officers are mandating batch-level compostability verification as a contract precondition, displacing generic sustainability claims in temporary service environments. Distributor sales teams are restructuring around certified product specialists who navigate municipal compost standard variations. This behavioral shift is most visible in Mexico's events corridor connecting Mexico City, Guadalajara, and Monterrey.
Latin America Biodegradable Food Service Disposables Market Segmentation
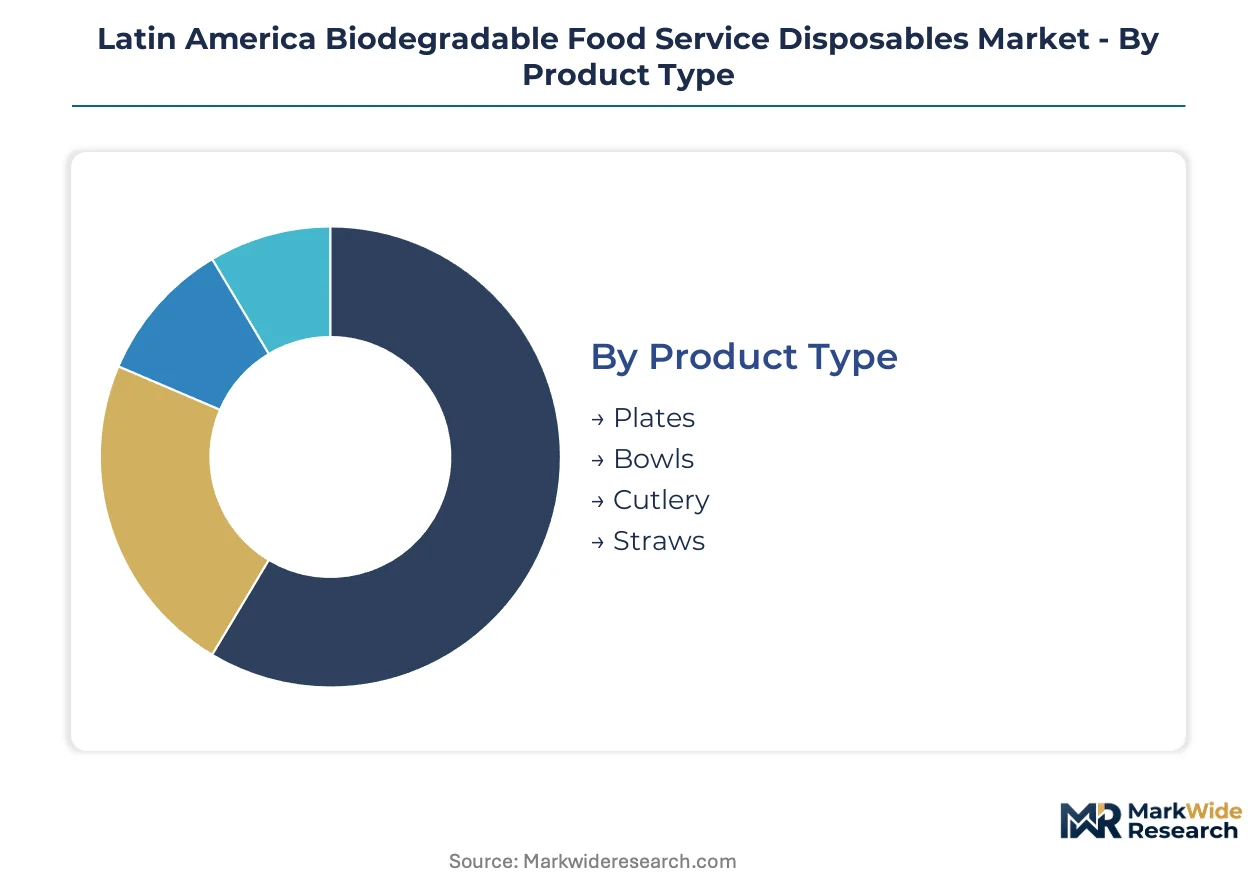
Segmentation in Latin America's biodegradable disposables sector reveals how regulatory frameworks, composting infrastructure maturity, and end-use economics allocate demand across material and product categories. Understanding these divisions exposes where certification investments concentrate and where supply gaps persist.
Product Type:
ANVISA and COFEPRIS food-contact migration limits apply differentially across product geometries, with surface-area-to-volume ratios determining testing burden and compliance cost allocation.
- Plates:Molded fiber and bagasse-based substrates dominate this category, with São Paulo and Mexico City quick-service chains driving procurement volumes. Sugarcane residue pulping capacity in Colombia supplies cost-competitive feedstock, though hot-food performance requirements favor PLA-coated variants in premium catering contracts.
- Cutlery:PLA resin dependence creates margin volatility for manufacturers serving Brazil's southeastern restaurant corridor. ANVISA certification timelines extend 12-18 months for injection-molded biopolymer utensils, compressing product launch windows relative to fiber-based alternatives.
- Bowls:Deep-draw geometries demand enhanced barrier coatings for liquid containment, limiting supplier base to firms with integrated PLA or PHA formulation capabilities.
- Straws:Regulatory bans on petroleum-based alternatives in multiple Brazilian states and Mexican municipalities have collapsed demand timelines, though industrial composting facility scarcity limits actual end-of-life performance verification.
Established volume favors plates; emerging adoption favors straws.
Material:
Cost tier differentiation separates commodity agricultural residues from engineered biopolymers, with certification complexity and performance thresholds determining procurement economics.
- PLA:Corn-derived polymer supply chains concentrate in North American and Asian sources, exposing Brazilian and Mexican converters to currency and feedstock price swings. COFEPRIS enforcement of food-contact migration limits is accelerating local testing partnerships.
- Sugarcane:Colombian and Brazilian agricultural residue processing capacity is expanding molded fiber plate production, capturing volume-tier demand from catering and events applications requiring certified compostable verification. Bagasse pulping integrates with existing sugar mill infrastructure.
- Bamboo:Mechanical processing requirements and fiber length consistency challenges limit scale economics, though premium positioning in Mexico City's events corridor sustains niche procurement.
- Cardboard:Recycled fiber substrates with compostable barrier coatings serve price-sensitive institutional procurement where petroleum-based substitution pressure concentrates.
Volume concentration favors sugarcane; margin expansion favors PLA.
Application:
Customer type determines reuse economics elimination and certification verification intensity, with temporary service mandates creating distinct procurement behavior patterns.
- Restaurants:São Paulo state's quick-service density and municipal waste mandates drive systematic petroleum-to-compostable conversion, with procurement contracts requiring documented INMETRO certification maintenance.
- Catering:Batch-level compostability verification is displacing generic sustainability claims in Mexico's events corridor connecting Mexico City, Guadalajara, and Monterrey. Temporary service mandates eliminate reuse economics entirely.
- Events:Stadium and festival procurement officers mandate certified compostable verification as contract precondition, with distributor sales teams restructuring around product specialists navigating municipal compost standard variations.
- Food Trucks:Mobile service constraints and inconsistent municipal composting facility access limit premium pricing capture, though Rio de Janeiro and Minas Gerais state expansion is accelerating demand formation.
Procurement scale favors restaurants; certification intensity favors events.
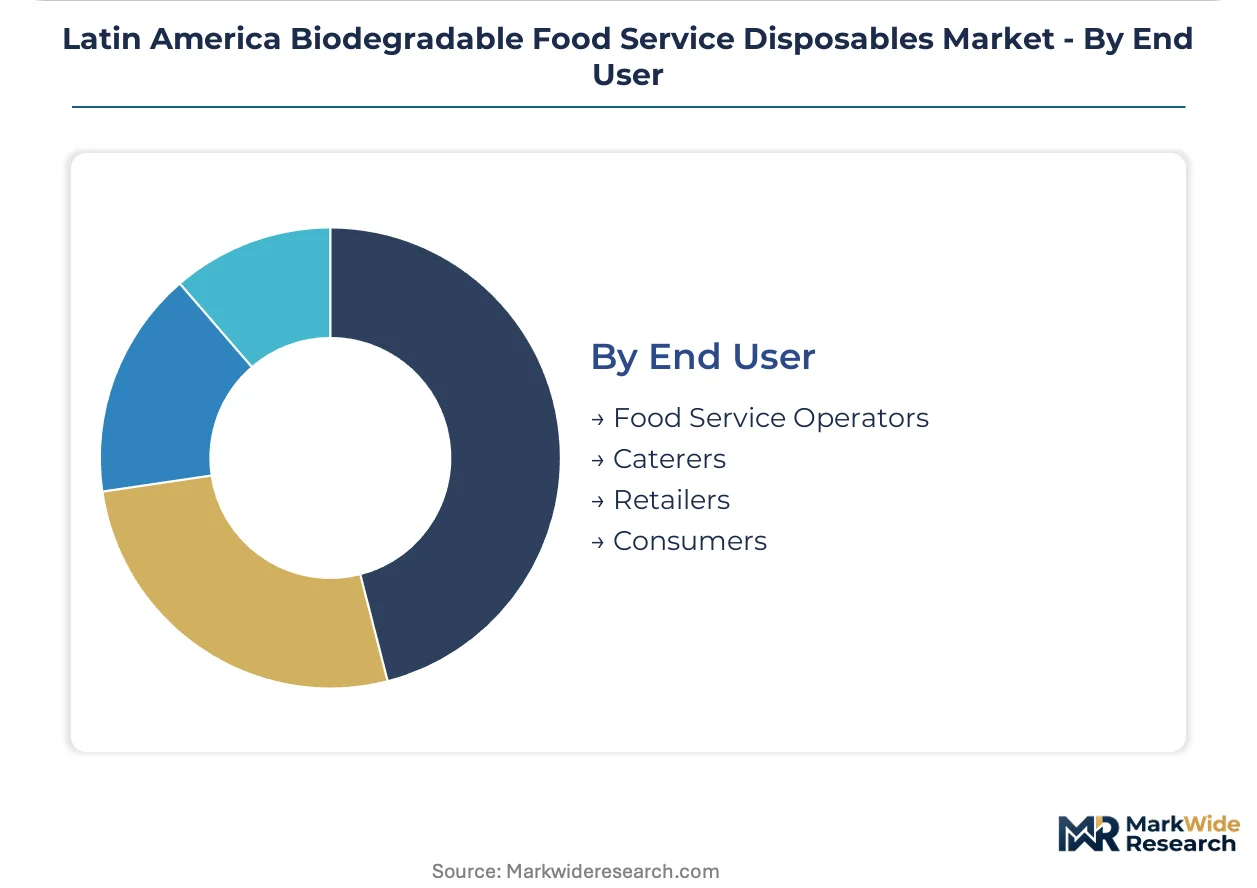
End User:
Supply chain position determines volume aggregation power and specification control, with direct food service operators capturing procurement economics relative to intermediary channels.
- Food Service Operators:Quick-service chains across Brazil's southeastern states and Mexico's central corridor wield consolidated procurement volumes, forcing supplier certification investments and inventory pool consolidation.
- Caterers:Mexico's events corridor procurement officers are mandating batch-level verification, displacing distributor-generic sustainability claims with contract-specific compostability documentation.
- Retailers:Supermarket and convenience store channels face petroleum-based substitution pressure in price-sensitive segments, particularly where municipal composting infrastructure remains undeveloped.
- Consumers:Direct purchase volumes concentrate in urban cores with visible industrial composting facility presence, with willingness-to-pay compostable premiums tied to actual end-of-life performance verification.
Specification control favors food service operators; price sensitivity favors retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Brazil's São Paulo industrial corridor while Mexican procurement clusters absorb compliance premiums. Colombia's sugarcane processing belt captures volume-tier positioning through agricultural residue integration. Argentina and Chile impose divergent marine biodegradability protocols that fragment cross-border supplier economics.
Brazil
São Paulo state's quick-service restaurant density and municipal waste mandates drive systematic petroleum-to-compostable conversion. ANVISA food-contact migration limits extend certification timelines to 12-18 months for injection-molded biopolymer utensils. Minas Gerais and Rio de Janeiro states present underpenetrated demand corridors where urban food service density accelerates faster than local compostable supply infrastructure.
Mexico
Central corridor procurement clusters connecting Mexico City, Guadalajara, and Monterrey mandate batch-level compostability verification for catering contracts. COFEPRIS enforcement of food-contact migration limits forces Asian manufacturers to establish local testing partnerships or cede shelf space. State-level organic waste diversion requirements create procurement preference shifts toward verified compostable serviceware in government-contracted operations.
Colombia
Agricultural residue processing capacity in sugarcane belt regions expands molded fiber plate production for volume-tier catering demand. Bagasse pulping integrates with existing sugar mill infrastructure, capturing cost advantages relative to corn-derived polymer supply chains. Domestic manufacturers leverage geographic proximity to Andean quick-service chains requiring certified compostable verification.
Argentina
Buenos Aires metropolitan procurement officers navigate INTI marine biodegradability testing protocols that diverge from Brazilian INMETRO standards. Cross-border certification friction elevates compliance costs for multi-country suppliers serving Mercosur-integrated food service operators. Local distributors consolidate inventory around prequalified domestic producers to avoid import verification delays.
Chile
Santiago's events corridor procurement mandates certified compostable verification for stadium and festival contracts. SUBPESCA marine biodegradability frameworks create compliance complexity relative to regional neighbors, fragmenting supplier qualification requirements. Industrial composting facility concentration in metropolitan zones limits market expansion into secondary cities.
Latin America Biodegradable Food Service Disposables Market Key Industry Players
Concentration sits with integrated biopolymer producers who control captive resin sourcing and regional thermoforming footprints. Finished-goods assemblers without upstream polymer access face margin compression from feedstock volatility and extended certification timelines. Three archetypes dominate: vertically integrated material-to-product manufacturers, specialized coating technology developers, and agricultural residue processors with pulp-to-molded-fiber capabilities. Competitive moves center on backward integration into sugarcane bagasse pulping and strategic partnerships with municipal composting operators to secure end-of-life verification channels.
Among Nordic-based packaging specialists, Huhtamaki Oyj exemplifies the integrated archetype through regional manufacturing presence. Ajover-Darnel occupies a position within agricultural residue processing, representing Colombian vertical integration into bagasse supply chains. Vegware Ltd. sits within the specialized coating tier, anchoring compostable barrier technology development for varying municipal standards. These three entities illustrate how geographic origin and structural positioning determine competitive stability across certification-intensive procurement environments.
| Leading Market Players |
|---|
| Huhtamaki Oyj |
| Dart Container Corporation |
| Vegware Ltd. |
| Biopak Pty Ltd. |
| Sabert Corporation |
| Grupo Bimbo S.A.B. de C.V. |
| ITC Limited |
| Ajover-Darnel |
| Carvajal |
| Others |
Cost & Logistics Intelligence
Sugarcane bagasse substitution for corn-derived PLA is redrawing raw material geography across Latin America, compressing polymer-dependent pricing tiers while elevating agricultural residue processors to cost leadership positions in molded fiber categories.
Pricing Analysis
The customization-premium spread separates standard bagasse plates from PLA-coated variants engineered for hot-liquid contact, with certification-grade differentiation commanding procurement premiums in São Paulo and Mexico City catering contracts. Three-tier pricing structure across premium, standard, and economy levels reflects INMETRO verification status, volume scale, and barrier coating complexity. Pricing pressure stems from PLA resin feedstock volatility concentrated in North American supply sources, with Asian import competition intensifying cost compression in uncertified tiers. Institutional procurement through government-contracted food service operations exhibits highest price sensitivity, while events procurement officers demonstrate lowest sensitivity due to temporary service mandates eliminating reuse economics.
Supply Chain Analysis
Just-in-time inventory strategies dominate quick-service restaurant procurement in Brazil's southeastern corridor, whereas strategic stockpiling of certified PLA resin prevails among Mexican converters navigating COFEPRIS verification delays. Geographic supply concentration centers on Colombia for sugarcane bagasse pulping, Brazil for integrated biopolymer conversion, and Mexico for thermoforming and distribution hub functions. Raw material dependencies include corn-derived PLA resin, sugarcane agricultural residue, and compostable barrier coating formulations. Supply chain risk hinges on single-source vulnerability in PLA polymer supply chains tethered to North American feedstock markets. Distribution runs through specialized foodservice distributors consolidating certified inventory pools around prequalified manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's biodegradable disposables sector constitutes a high-growth disruption propelled by ANVISA and COFEPRIS regulatory convergence on food-contact migration limits, which is systematically displacing uncertified petroleum-based alternatives from high-volume procurement channels.
For Market Incumbents: Compound defensive positioning through backward integration into Colombian sugarcane bagasse pulping capacity and captive PLA resin sourcing partnerships that insulate margin structures from feedstock volatility. Accelerate INMETRO and NOM-252-SSA1-2011 certification investments to extend compliance lead times as a competitive moat against Asian import encroachment. Channel control through exclusive distributor relationships in São Paulo and Mexico City procurement clusters remains essential for specification maintenance.
For New Entrants and Emerging Players: Batch-level compostability verification services represent an underserved layer where incumbents under-serve catering procurement officers demanding contract-specific documentation rather than generic sustainability claims. Penetrate Brazil's Minas Gerais and Rio de Janeiro state corridors where urban food service density outpaces local compostable supply infrastructure. Deploy direct sales teams staffed with certified product specialists who navigate municipal compost standard variations as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed agricultural residue processors possessing integrated pulp-to-molded-fiber capabilities and established sugar mill feedstock relationships. Five-to-ten year viability frames around industrial composting infrastructure deployment velocity outpacing material certification timelines, with facility availability dictating actual end-of-life performance realization. Monitor municipal waste mandate implementation timelines across Brazilian and Mexican state governments as the critical inflection signal for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Pulping | Captive agricultural residue supply secures cost advantages against PLA-dependent competitors in São Paulo procurement corridors. |
| COFEPRIS Prequalification Partnership | Local testing relationships accelerate Mexican market access and displace uncertified Asian import competition. |
| Municipal Composting Facility Joint Venture | End-of-life verification channels substantiate compostable premium pricing and consumer willingness-to-pay. |
| Barrier Coating R&D Investment | PLA-PHA formulation capabilities unlock hot-food application markets previously reserved for plastic-lined alternatives. |
| Peripheral State Distribution Expansion | Minas Gerais and Rio de Janeiro penetration captures demand formation ahead of incumbent supply infrastructure deployment. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with food service procurement directors, regulatory affairs managers at biopolymer converters, industrial composting facility operators, and specialized distributor sales teams; alongside secondary validation through ANVISA certification registries, COFEPRIS food-contact filings, Colombian agricultural ministry production statistics, and Brazilian customs trade records. Bottom-up triangulation aggregated product-level volume estimates across plates, cutlery, bowls, and straws, while top-down reconciliation anchored aggregate market sizing against national organic waste diversion policy targets and quick-service restaurant conversion rates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, material substrate, application segment, and end-user category, with geographic granularity at country-state level for Brazil and Mexico and national level for Colombia, Argentina, and Chile. CAGRs were derived from regression analysis of historical certification timeline compression, municipal composting facility deployment schedules, and quick-service restaurant procurement contract conversion patterns. Industry-specific inputs included PLA resin price volatility indices, sugarcane harvest yield variations, and state-level organic waste mandate implementation status.
Underlying assumptions cover sustained ANVISA and COFEPRIS enforcement trajectory, industrial composting facility deployment pacing, and quick-service restaurant procurement contract renewal cycles, with deviation risk concentrated in regulatory timeline delays and petroleum-based price competition in uncertified tiers. Revision becomes warranted when municipal composting infrastructure availability crosses thresholds that substantiate or undermine end-of-life performance claims.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
North America Food Service Market
Food Service
New Zealand Foodservice Market
Food Service
Smart Food Logistics Market
Food Service
Italy Foodservice Market
Food Service
Philippines Foodservice Market
Food Service
Food Service Gloves Market
Food Service
Takeout Dinner Market
Food Service
Commercial Griddle Market
Food Service
Electric Tiffin Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
India Inflight Catering Market
Food Service
Switzerland Food Service Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Smokeless Grill Market