
 Europe Out of Home (OOH) Delivery Market | 2026-2036
Europe Out of Home (OOH) Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Out of Home (OOH) Delivery Market Insights
E-commerce buyers are gaining share against traditional restaurant clients as the demand base is bifurcating across urban fulfillment networks. Deutsche Post DHL Group leverages its parcel locker density to anchor last-mile coverage in German metropolitan zones. InPost competes through automated locker placement at retail-adjacent sites, while GeoPost sustains cross-border scheduled delivery corridors linking Benelux hubs to French and Spanish markets.
Europe Out of Home (OOH) Delivery encompasses logistics services where parcels, meals, or retail goods reach consumers at designated alternative points rather than residential addresses, utilizing temperature-controlled containers, real-time tracking APIs, and dynamic route optimization algorithms to maintain service-level agreements. The primary commercial purpose centers on reducing failed delivery attempts, lowering per-drop costs, and accommodating urban consumers who lack consistent home presence. Same-day delivery and on-demand delivery represent the fastest-expanding service types as consumer tolerance for waiting periods compresses, while bicycle delivery and vehicle delivery dominate the mode mix with divergent margin structures—cycling yields lower per-unit cost in dense city cores whereas vans sustain economies in suburban radius extensions. Eco-friendly packaging is attracting regulatory preference and buyer procurement mandates, creating margin pools distinct from standard packaging segments.
The EU Green Deal, REACH packaging standards, and GDPR data governance frameworks collectively shape fleet electrification timelines, material compliance costs, and customer data handling protocols across European OOH delivery operations. France's CNIL and Germany's KBA add national enforcement layers that operators must navigate for locker network deployment and vehicle certification. Stakeholders should monitor how the EU AI Act's risk classifications apply to automated dispatch algorithms before committing to platform upgrades.
Market Dynamics
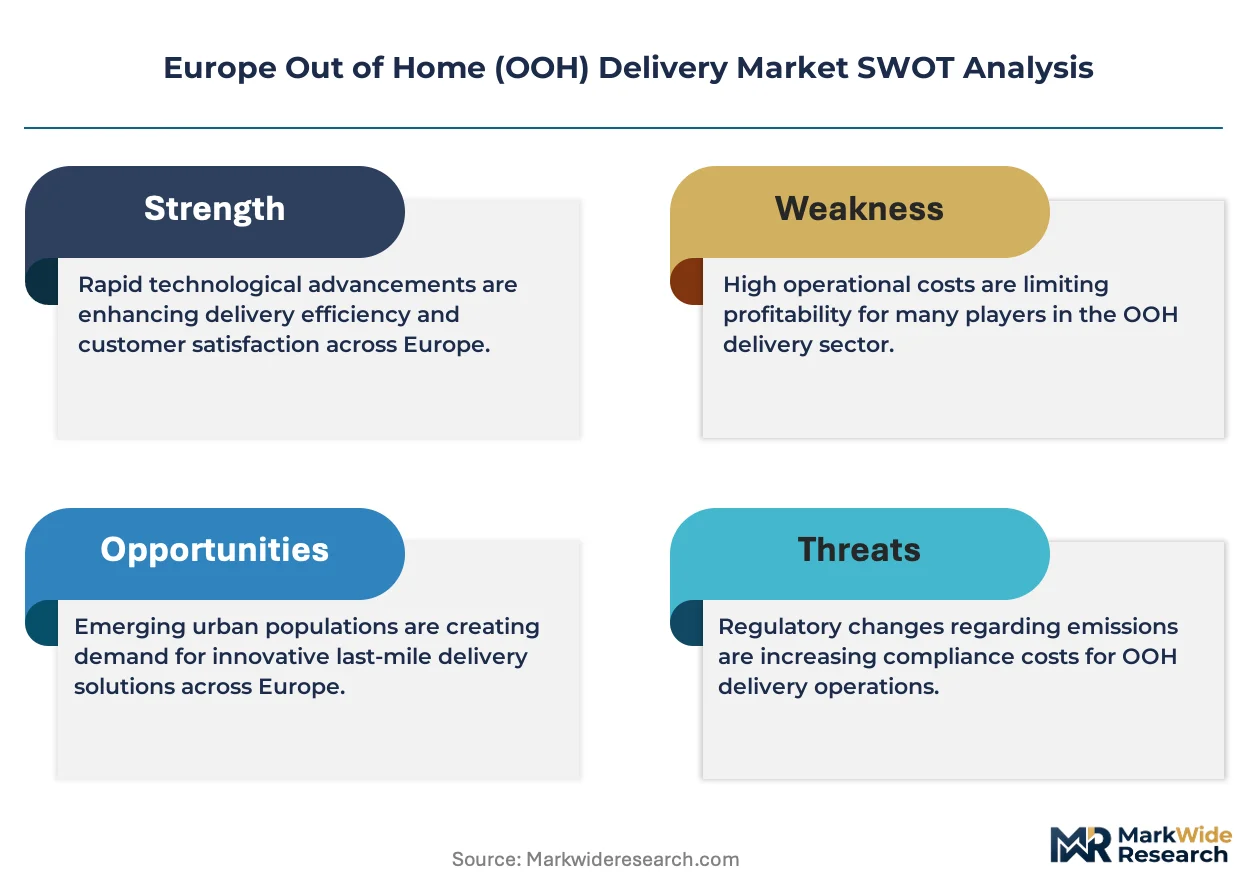
Urban consolidation is compressing last-mile delivery economics across European capitals, forcing operators to densify pickup point networks and electrify fleets ahead of EU Green Deal timelines. Temperature-controlled container deployment and dynamic route algorithms now determine margin survival.
Growth Catalysts
- EU Green Deal packaging directives:REACH-compliant sustainable logistics infrastructure attracts procurement mandates from quick-service restaurant chains expanding off-premises operations.
- Parcel locker density:Automated locker placement at retail-adjacent sites reduces failed delivery attempts and per-drop costs in German and French metropolitan zones.
- Same-day service compression:Consumer tolerance for waiting periods is collapsing, pulling bicycle and electric van deployment into dense urban cores.
Market Restraints
- Battery mineral supply concentration:Fleet electrification depends on cobalt and lithium supply chains concentrated outside Europe, exposing operators to input cost volatility.
- GDPR data governance friction:Real-time tracking APIs and automated dispatch algorithms face compliance complexity that slows locker network deployment.
- Suburban radius economics:Van-based delivery in low-density zones sustains higher per-unit costs that bicycle fleets cannot match, constraining margin recovery.
Strategic Opportunities
- Benelux-France-Spain corridors:Cross-border scheduled delivery networks linking regional hubs remain underpenetrated relative to domestic urban density.
- AI Act risk classification alignment:Automated dispatch platforms that preemptively classify algorithmic risk tiers gain regulatory preference ahead of enforcement deadlines.
- E-commerce buyer consolidation:Logistics providers capturing e-commerce parcel volume can displace traditional restaurant client dependence through urban fulfillment network control.
Industry Challenges
- Temperature-controlled container certification:Cold-chain compliance timelines for food and pharmaceutical delivery stretch procurement cycles and capex planning.
- API integration with legacy retail systems:Real-time inventory synchronization across quick-service restaurant point-of-sale networks creates technical debt and deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Out of Home (OOH) Delivery Market |
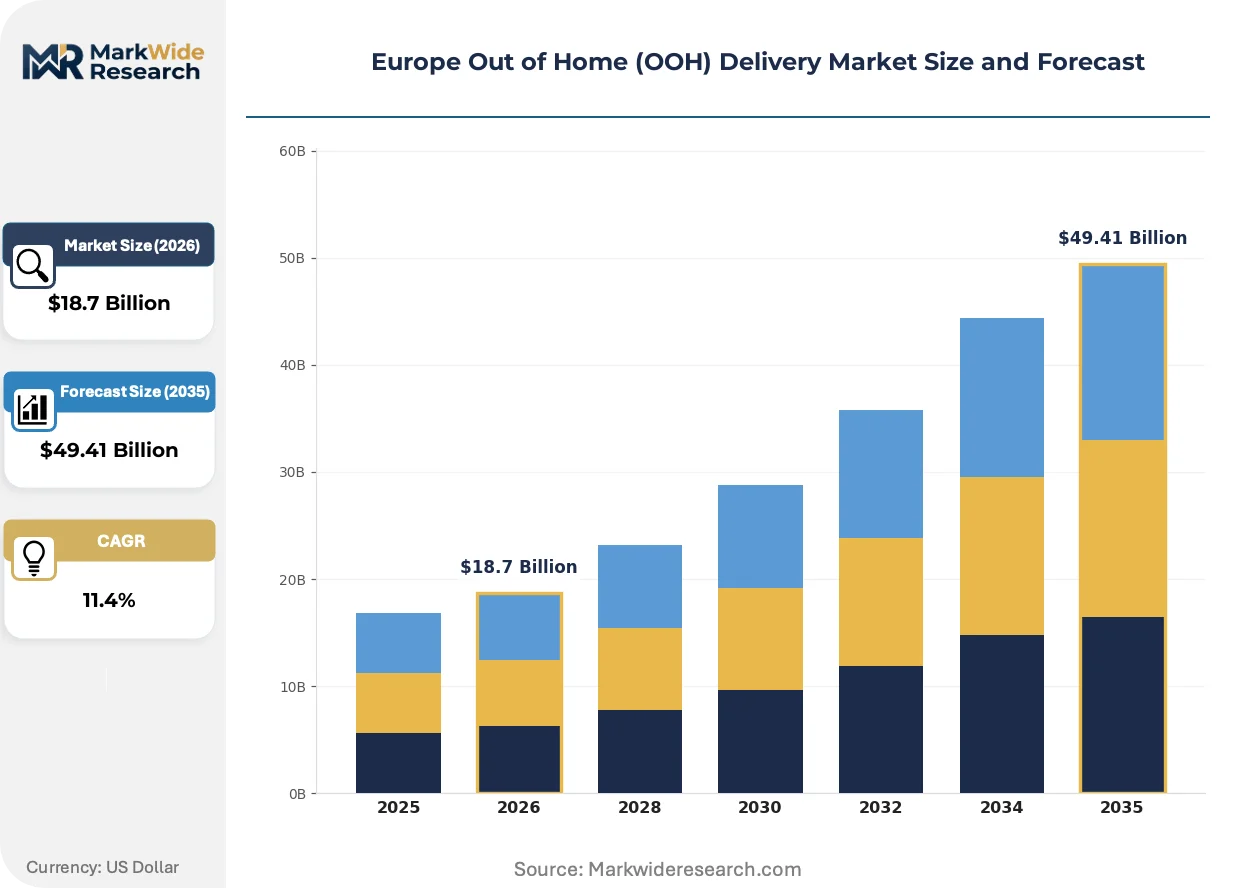
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Direct Delivery, Scheduled Delivery, Same-Day Delivery, On-Demand Delivery Delivery Mode: Drone Delivery, Bicycle Delivery, Vehicle Delivery, Walk Delivery End User: Restaurants, Supermarkets, E-Commerce, Convenience Stores Packaging Type: Eco-Friendly Packaging, Insulated Packaging, Bulk Packaging, Standard Packaging |
| Companies Covered | Deutsche Post DHL Group, InPost, GeoPost, GLS Group, UPS, DSV, Evri, Poste Italiane, DB Schenker, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Out of Home (OOH) Delivery Market Trends and Innovations
Dynamic route optimization and electrified micro-fulfillment are restructuring how European operators compete on speed and compliance. The convergence of algorithmic dispatch with sustainable packaging mandates is creating new capability thresholds.
AI-powered predictive dispatch systems analyze traffic patterns, order density, and vehicle state in real time to compress delivery windows. Quick-service restaurant chains and grocery platforms are adopting these tools fastest in London, Paris, and Berlin. Human dispatch oversight is supplanting static route planning, enabling same-day service guarantees that previously required 48-hour buffers.
France's CNIL and Germany's KBA are enforcing vehicle certification and data handling protocols that accelerate fleet electrification timelines. Operators must now document algorithmic decision transparency and battery supply chain provenance to maintain locker network licenses. French metropolitan zones face the tightest enforcement, pushing DHL and GeoPost to front-load electric van procurement ahead of 2027 inspection cycles.
Urban consumers are abandoning residential delivery preference for workplace and transit-hub pickup points. Quick-service restaurant off-premises revenue now flows through corporate campus lockers and train station kiosks as primary channels. This pattern concentrates most visibly in London's financial district and Berlin's S-Bahn corridors, where residential absence rates exceed sixty percent during business hours.
Europe Out of Home (OOH) Delivery Market Segmentation
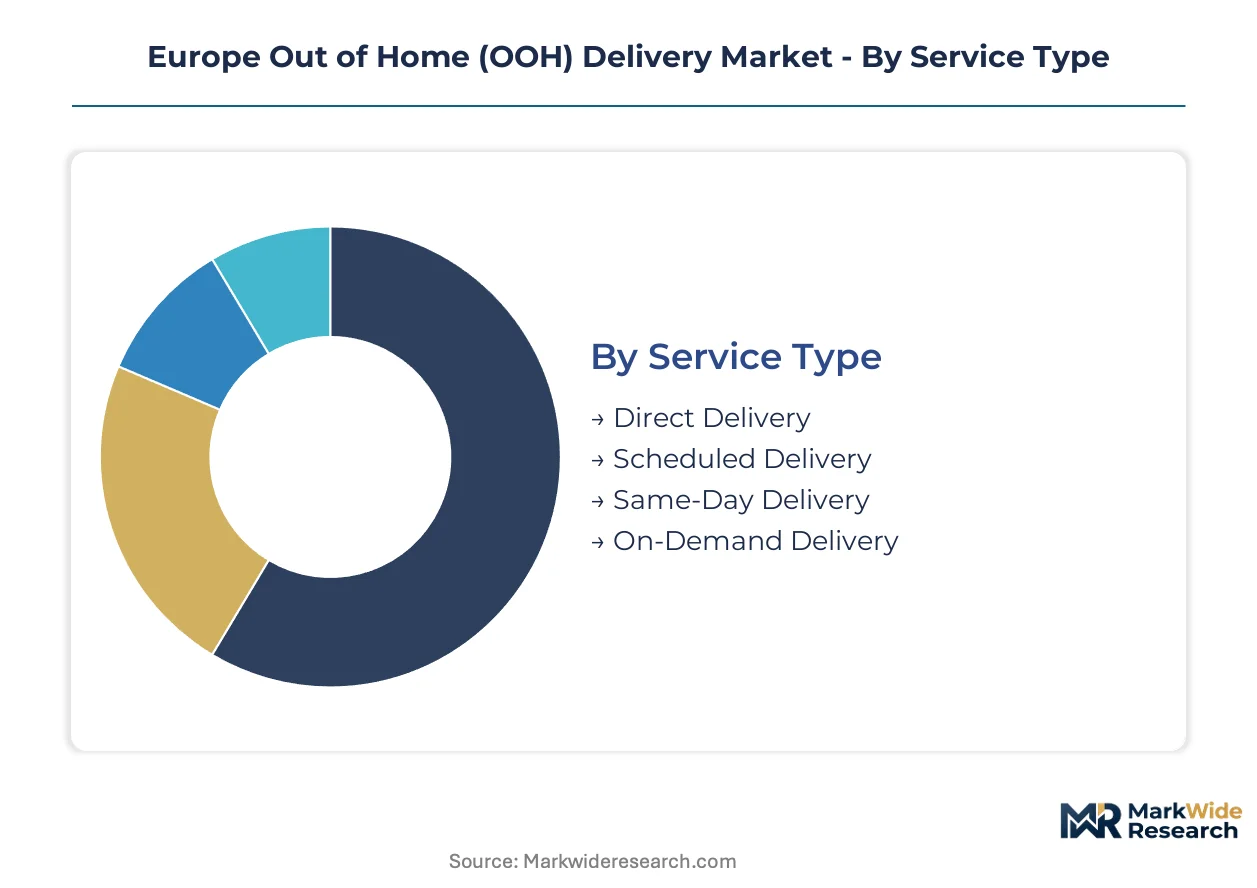
European OOH delivery operators structure service portfolios around regulatory compliance tiers and urban density gradients. Segmentation choices directly determine fleet capital requirements, locker network placement, and margin sustainability across German, French, and British metropolitan zones.
Service Type:
EU Green Deal timelines and GDPR data governance frameworks differentiate service tiers through electrification mandates and algorithmic transparency requirements.
- Direct Delivery:Point-to-point logistics without intermediary consolidation points. Demand concentrates in suburban French zones where residential presence rates exceed urban cores, though per-drop costs remain elevated versus locker-based alternatives.
- Scheduled Delivery:Pre-arranged time windows enabling route batching and load optimization. German quick-service restaurant chains leverage this tier for corporate campus contracts, capturing volume through predictable demand patterns that justify dedicated electric van allocation.
- Same-Day Delivery:Compressed fulfillment windows requiring dynamic route algorithms and micro-fulfillment positioning. Bicycle and electric van deployment in London and Berlin dense cores supports this tier's expansion.
- On-Demand Delivery:Sub-hour fulfillment triggered by real-time consumer requests. High labor cost exposure and algorithmic dispatch complexity limit penetration outside Paris and London premium zones.
Established volume favors Scheduled Delivery; emerging adoption favors Same-Day Delivery.
Delivery Mode:
Cost tier differentiation separates capital-intensive aerial systems from low-capex human-powered alternatives.
- Drone Delivery:Aerial last-mile systems operating under national aviation authority waivers. Limited deployment to Irish and Scottish rural corridors where ground infrastructure gaps justify regulatory complexity.
- Bicycle Delivery:Human-powered cargo bikes with refrigerated container attachment. Demand concentrates in Amsterdam, Copenhagen, and Berlin city centers where EU Green Deal emission zones ban combustion vehicles and street width constraints favor narrow-frame designs.
- Vehicle Delivery:Electric and combustion van fleets sustaining suburban radius economics. British and French operators front-load electric procurement ahead of KBA and CNIL enforcement cycles.
- Walk Delivery:Pedestrian couriers serving ultra-dense districts with parcel trolley or backpack systems. London's financial district and Milan's centro storico deploy this mode for sub-kilometer drops where vehicle parking penalties exceed labor costs.
Vehicle Delivery captures current volume concentration; Bicycle Delivery gains regulatory preference fastest.
End User:
Application-based segmentation reveals diverging margin structures between food service and retail logistics.
- Restaurants:Quick-service and full-service operators expanding off-premises revenue through temperature-controlled container networks. French and German chains consolidate procurement around REACH-compliant packaging mandates.
- Supermarkets:Grocery platforms deploying dark store micro-fulfillment for click-and-collect and home delivery hybrid models. British operators lead locker placement at retail-adjacent sites.
- E-Commerce:Parcel volume from online retail displacing traditional restaurant client dependence. Deutsche Post DHL Group and InPost compete for this segment through automated locker density in metropolitan zones.
- Convenience Stores:Small-format retail acting as pickup points and localized fulfillment nodes. Urban consolidation trends position this tier for network integration rather than standalone delivery demand.
E-Commerce parcel flows favor automated infrastructure investment; Restaurant demand anchors temperature-controlled fleet specialization.
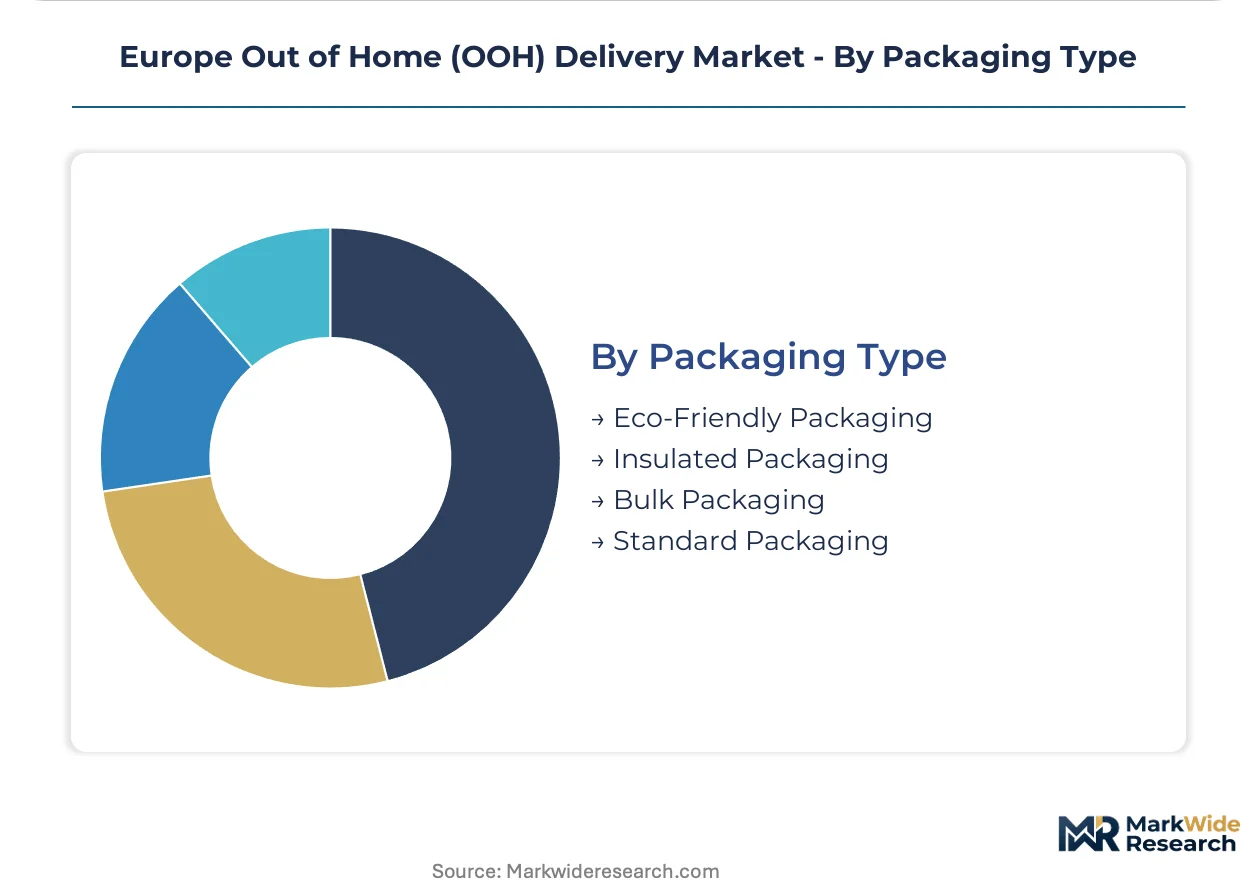
Packaging Type:
Margin differentiation emerges between regulatory-compliant sustainable materials and standard alternatives facing procurement exclusion.
- Eco-Friendly Packaging:Biodegradable and recyclable materials meeting REACH and EU Green Deal directives. Quick-service restaurant chains mandate this tier for off-premises operations, creating distinct margin pools from standard alternatives.
- Insulated Packaging:Temperature-retention containers for food and pharmaceutical cold chains. Cold-chain compliance timelines stretch procurement cycles for German and French pharmaceutical delivery networks.
- Bulk Packaging:Consolidated shipment containers reducing per-unit material cost for B2B corridor flows. Benelux-France-Spain scheduled delivery networks utilize this format for hub-to-hub efficiency.
- Standard Packaging:Conventional materials without sustainability certification. Procurement mandates from EU Green Deal-aligned buyers accelerate displacement toward eco-friendly alternatives.
Eco-Friendly Packaging captures regulatory-driven procurement shifts; Insulated Packaging sustains premium positioning through cold-chain compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parcel locker density and fleet electrification timelines concentrate competitive advantage in German, French, and British metropolitan zones. Urban consolidation pressures force operators to densify pickup networks ahead of EU Green Deal enforcement cycles. National regulators in Paris, Berlin, and London impose divergent compliance burdens that reshape cross-border corridor economics.
Germany
Deutsche Post DHL Group leverages automated locker placement to anchor last-mile coverage in Berlin, Hamburg, and Munich metropolitan zones. The KBA enforces vehicle certification protocols that accelerate electric van procurement ahead of inspection cycles. North Rhine-Westphalia's logistics corridor sustains scheduled delivery batching for quick-service restaurant corporate campus contracts.
France
GeoPost sustains cross-border scheduled delivery corridors linking Benelux hubs to French and Spanish markets through temperature-controlled container networks. CNIL data governance requirements impose algorithmic transparency mandates on real-time tracking APIs deployed in Paris and Lyon. Île-de-France's urban consolidation tightens fastest, pushing bicycle and electric van deployment into dense city cores.
United Kingdom
Evri competes for e-commerce parcel volume through retail-adjacent locker placement in London, Birmingham, and Manchester. GDPR compliance complexity slows automated dispatch algorithm deployment across British fulfillment networks. The capital's financial district drives workplace and transit-hub pickup point preference as residential absence rates exceed sixty percent during business hours.
Italy
Poste Italiane maintains domestic parcel locker density in Rome and Milan against cross-border carrier penetration. REACH packaging standards enforce sustainable logistics infrastructure procurement for quick-service restaurant off-premises expansion. Northern Italy's industrial triangle concentrates temperature-controlled pharmaceutical delivery demand with stretched cold-chain compliance timelines.
Netherlands
InPost competes through automated locker placement at retail-adjacent sites in Amsterdam and Rotterdam urban cores. EU Green Deal emission zones ban combustion vehicles in dense city centers, favoring narrow-frame cargo bike designs. The Randstad's logistics integration sustains Benelux-France-Spain corridor efficiency for bulk packaging consolidation flows.
Europe Out of Home (OOH) Delivery Market Competitive Landscape
Concentration sits with integrated postal incumbents and specialized locker network operators rather than fragmented regional carriers. The vendor base structures around three archetypes: state-affiliated postal groups with parcel locker density, independent automated locker specialists, and global express carriers with cross-border scheduled delivery capabilities. Strategic moves center on electric fleet procurement front-loading ahead of national enforcement cycles and API integration with quick-service restaurant point-of-sale networks.
Among integrated postal operators, Deutsche Post DHL Group and Poste Italiane exemplify state-affiliated archetypes with domestic locker network control. InPost represents the independent locker specialist model competing through retail-adjacent site placement. GeoPost occupies a position linking Benelux hub consolidation to southern European corridor reach.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| InPost |
| GeoPost |
| GLS Group |
| UPS |
| DSV |
| Evri |
| Poste Italiane |
| DB Schenker |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with electric van manufacturers lock in fleet procurement visibility while insulating German and French operators from lithium carbonate spot volatility. These contractual structures tether pricing power to battery supply chain access under EU Green Deal enforcement timelines.
Pricing Analysis
EU Green Deal packaging directives dictate the pricing tier structure across European OOH delivery markets. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified sustainable packaging from conventional alternatives, with quick-service restaurant chains mandating the premium tier for off-premises operations. Price differentiation hinges on cold-chain compliance certification and urban density delivery cost, with suburban van-based services facing margin compression from higher per-drop economics. Pricing pressure stems from battery mineral input volatility as cobalt and lithium supply chains concentrate outside Europe. E-commerce parcel buyers exhibit highest price sensitivity due to volume consolidation power, while pharmaceutical cold-chain clients accept premium positioning for temperature-controlled container certification.
Supply Chain Analysis
Strait of Hormuz transit underwrites a portion of European battery mineral imports, though primary supply chain vulnerability sits with cobalt and lithium concentration in the Democratic Republic of Congo, Chile, and Australia. Fleet electrification draws from nickel-manganese-cobalt cathode chemistry, lithium iron phosphate alternatives, and rare earth magnet motors for electric van propulsion. Single-source vulnerability in cobalt refining exposes operators to procurement disruption. Distribution runs through Rotterdam and Hamburg port clusters into German and Benelux manufacturing zones, with final-mile deployment via parcel locker networks and micro-fulfillment positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urban consolidation is fragmenting demand across workplace pickup points, transit hubs, and residential alternatives, creating niche specialization opportunities beyond integrated postal incumbents.
For Market Incumbents: Secure locker network density in metropolitan cores ahead of KBA and CNIL enforcement cycles. Deutsche Post DHL Group and GeoPost must preempt electric van procurement commitments to defend against battery supply chain disruption threatening fleet transition timelines. Backward integration into temperature-controlled container manufacturing reduces pharmaceutical client procurement friction. For New Entrants and Emerging Players: REACH packaging certification fast-track enables white-space entry into quick-service restaurant supply chains displacing standard packaging alternatives. Target Benelux-France-Spain corridor scheduled delivery networks where cross-border consolidation remains underpenetrated relative to domestic urban density. Deploy API-first integration with legacy retail point-of-sale systems as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Capital is best deployed toward automated locker specialists with retail-adjacent site control rather than asset-heavy fleet operators facing electrification capex burdens. Long-term viability favors platform architectures integrating dynamic route algorithms with sustainable packaging procurement mandates. Monitor EU AI Act risk classification enforcement as inflection signal for automated dispatch algorithm regulatory preference.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | Front-loaded electric van procurement ahead of KBA inspection cycles secures German metropolitan operating licenses. |
| Parcel Locker Network Densification | Retail-adjacent automated placement reduces failed delivery attempts and per-drop costs in French urban zones. |
| API Integration with QSR Systems | Real-time inventory synchronization with quick-service restaurant point-of-sale networks captures off-premises revenue flows. |
| Cross-Border Corridor Expansion | Benelux-France-Spain scheduled delivery batching exploits underpenetrated hub consolidation relative to domestic density. |
| Sustainable Packaging Transition | REACH-compliant biodegradable materials procurement meets EU Green Deal mandates for quick-service restaurant chains. |
Research Methodology
A spread of perspectives from logistics operations directors, quick-service restaurant supply chain managers, parcel locker network engineers, and regulatory compliance officers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation across EU Green Deal policy documentation, KBA vehicle certification filings, CNIL algorithmic transparency guidance, and customs trade data for battery mineral imports. Bottom-up service-type segmentation triangulated against top-down metropolitan zone demand modeling.
Service type, delivery mode, end-user application, and packaging compliance tier structured the analytical framework across the projection horizon. CAGRs derived from logistic curve penetration modeling for same-day delivery adoption and electrified fleet replacement cycles. Temperature-controlled container deployment density and dynamic route algorithm API integration velocity served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable battery mineral supply access assumptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Air Fryer Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
United States Quick Service Restaurants Market
Food Service
Haute Cuisine Market
Food Service
Food Service Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Oman Food Service Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Food Trays Market
Food Service
Commercial Air Fryer Oven Market
Food Service
China Online Food Delivery Market
Food Service
Commercial Charbroiler Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Chile Food Delivery Market
Food Service
Beverage Coaster Market
Food Service
Meal Voucher Market