
 Hops Essential Oil Market | 2026-2036
Hops Essential Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Hops Essential Oil Market Foresight
REACH compliance is shifting the cost-of-entry calculus for European suppliers, forcing upstream documentation of pesticide residues and terpene profiles. Yakima Chief Hops Inc. leverages its integrated Pacific Northwest supply chain to control raw material provenance from field to distillation. Barth-Haas Group anchors its position through proprietary CO₂ extraction infrastructure serving pharmaceutical-grade contracts. Hopsteiner Group competes on solvent-free supercritical processing that meets evolving EU purity thresholds without reformulation costs.
Hops essential oil is a concentrated volatile extract derived from Humulus lupulus flowers, typically comprising 30-60% humulene, 20-45% myrcene, and trace lupulin bitter acids, obtained through steam distillation or supercritical CO₂ extraction for use in flavoring, fragrance, and therapeutic applications. Organic product type commands premium positioning as clean-label procurement policies at cosmetics formulators reject conventional solvent residues. Food & Beverage application leads volume through craft brewing's pivot to precise bitterness modulation, while aromatherapy extracts represent the fastest-growing margin pool as wellness retailers stock single-origin hop oil for sleep and anxiety positioning.
EMA guidelines on herbal medicinal products and FDA GRAS self-affirmation pathways create divergent compliance burdens for suppliers targeting pharmaceutical versus food-grade channels. ISO 17025 laboratory accreditation is becoming a non-negotiable filter for contract eligibility with multinational flavor houses. Stakeholders must monitor terroir traceability investments as downstream buyers harden provenance requirements ahead of anticipated supply chain disclosure mandates.
Market Dynamics
REACH documentation mandates are forcing upstream consolidation as smaller Pacific Northwest growers lack capital for ISO 17025 laboratory accreditation and terpene traceability systems required by European fragrance houses.
Growth Catalysts
- Craft brewing precision dosing:Breweries in Oregon and Washington deploy CO₂-extracted hop oils for batch-to-batch bitterness consistency, eliminating vegetal matter variability from whole-cone additions.
- REACH purity thresholds:ECHA's elevated residue documentation requirements for imported essential oils are filtering out non-compliant suppliers, concentrating contract volumes among accredited German and Czech cooperatives.
- Supercritical CO₂ extraction:Solvent-free processing technology captures heat-sensitive myrcene fractions at sub-critical temperatures, preserving aroma compounds degraded by traditional steam distillation.
Market Restraints
- Input cost volatility:Lupulin gland yields fluctuate with Hallertau weather patterns, compressing margins for aroma-fraction suppliers locked into annual fragrance-house contracts.
- Supply concentration risk:Germany's Hallertau region controls roughly sixty percent of EU noble hop oil output, creating single-point vulnerability to fungal pressure or labor shortages.
- Substitution threat:Synthetic terpene blends from petrochemical feedstocks undercut natural hop oil pricing in mass-market beer flavoring, though they fail clean-label requirements.
Strategic Opportunities
- Wellness channel expansion:Aromatherapy retailers in California and Colorado are stocking single-origin Humulus lupulus extracts for sleep-positioning SKUs, commanding three-to-four-fold cosmetic-grade premiums.
- Pharmaceutical-grade contracts:EMA herbal medicinal product guidelines create a compliance moat for suppliers investing in GMP-certified CO₂ infrastructure, locking out commodity players.
- Terroir traceability systems:Blockchain-verified field-to-flask documentation aligns with anticipated EU supply chain disclosure mandates, enabling premium pricing for Yakima Valley and Slovenian Styrian provenance claims.
Industry Challenges
- Analytical chemistry talent scarcity:Gas chromatography-mass spectrometry operators capable of terpene profiling to ISO 17025 standards command salaries exceeding rural Washington extraction facility budgets.
- Dual certification timelines:Simultaneous FDA GRAS self-affirmation and EMA quality dossier preparation stretches quality assurance bandwidth, delaying market entry by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hops Essential Oil Market |
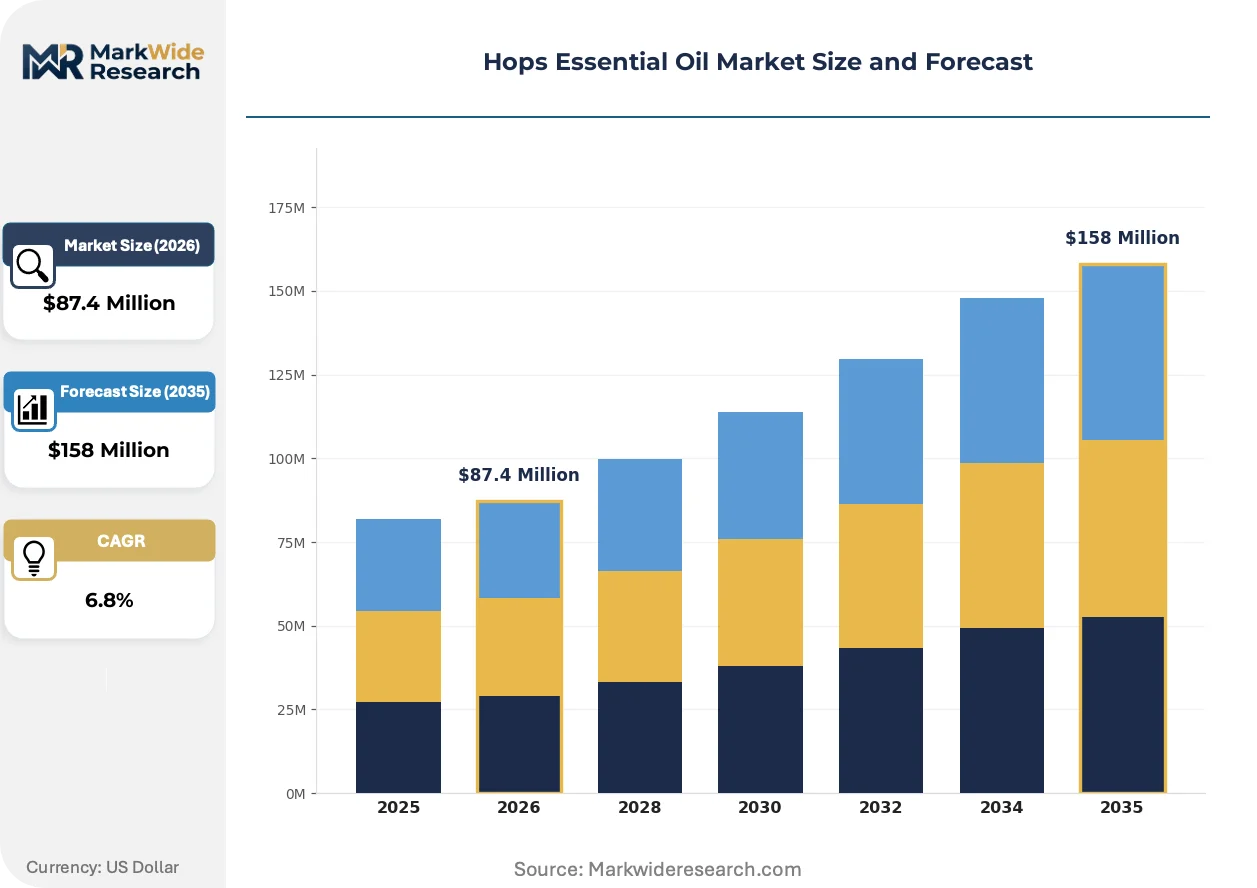
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Wildcrafted, Extracts Application: Cosmetics, Food & Beverage, Aromatherapy, Health Supplements End User: Manufacturers, Retailers, Distributors, Individual Consumers Distribution Channel: Online, Offline, Specialty Stores, Wholesale |
| Companies Covered | Yakima Chief Hops Inc., Barth-Haas Group, Hopsteiner Group, Kalsec Inc., Steiner Hops Ltd, John I. Haas, Inc., BSG Hops, Brewers Select Limited, Hollingberry & Son Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hops Essential Oil Market Shifts & Advancements
Extraction technology maturation and regulatory disclosure requirements are compressing the supplier base while opening margin pools in pharmaceutical and wellness channels previously inaccessible to commodity hop processors.
Supercritical CO₂ extraction with fractional separation capabilities is decentralizing aroma oil production away from centralized steam distillation cooperatives toward craft-scale brewery laboratories. Mid-sized Oregon brewers now lease mobile processing units for on-site lupulin extraction, bypassing tolling fees and capturing freshness premiums. This technology is decentralizing geographic supply concentration by enabling Yakima Valley growers to bypass German fragrance-house intermediaries entirely.
REACH SVHC candidate list expansion to include residual pesticide metabolites is forcing reformulation of conventional solvent-extracted hop oils. ECHA's 2024 updated guidance on essential oil impurities requires sub-ppm documentation for pyrethroid traces, disqualifying non-accredited suppliers. German Hallertau cooperatives are responding by deploying in-house LC-MS/MS screening, while US Pacific Northwest exporters face exclusion from EU pharmaceutical contracts.
Direct-to-brewer contracting is displacing spot-market purchasing as craft breweries seek terroir-specific bitterness profiles. Oregon and Washington brewers now sign three-year offtake agreements with named growers, specifying harvest dates and drying protocols. This procurement evolution is most visible in the Pacific Northwest, where vertical coordination between Yakima Valley farms and Portland brewing collectives has eliminated two distribution tiers.
Hops Essential Oil Market Segmentation
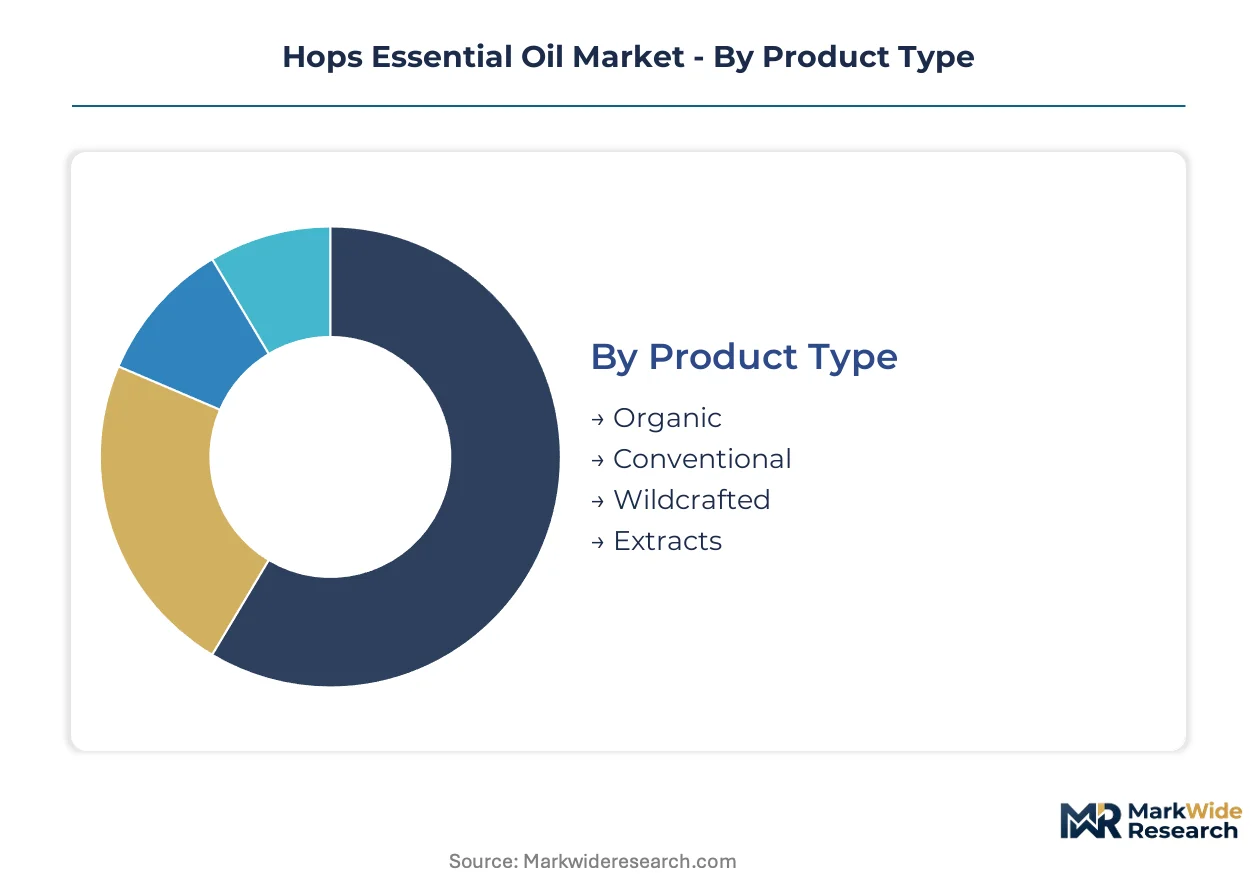
Segmentation in hops essential oil markets reveals how capital intensity, regulatory thresholds, and channel economics partition value capture. Distinct investment profiles separate pharmaceutical-grade infrastructure from commodity extraction, while application-driven purity requirements reshape procurement patterns across end-use verticals.
Product Type:
Capital intensity varies sharply across extraction and certification tiers, with organic and supercritical CO₂ infrastructure demanding the heaviest upfront outlays.
- Organic:Requires certified pesticide-free cultivation, third-party accreditation, and dedicated processing lines to prevent cross-contamination. Premium positioning at cosmetics formulators in Germany and France rejects conventional solvent residues, concentrating contract volumes with Hallertau cooperatives possessing ISO 17025 laboratory infrastructure.
- Conventional:Steam-distilled oils from standard agriculture dominate volume through established fragrance-house supply chains. REACH documentation burdens are filtering out smaller Pacific Northwest growers lacking capital for residue testing systems, concentrating supply among accredited German and Czech processors.
- Wildcrafted:Hand-harvested lupulin from unmanaged populations in Slovenian Styrian hills commands scarcity premiums at artisanal brewers.
- Extracts:Standardized oleoresins and terpene fractions serve mass-market beer flavoring with lower purity thresholds.
Conventional absorbs the bulk of installed capacity; organic is expanding most quickly.
Application:
Margin architecture diverges by end-use, with therapeutic and pharmaceutical channels capturing value multiples over commodity flavoring.
- Food & Beverage:Craft breweries in Oregon and Washington deploy CO₂-extracted hop oils for precise bitterness modulation, eliminating vegetal matter variability. Three-year offtake agreements with named Yakima Valley growers now displace spot-market purchasing as brewers seek terroir-specific profiles.
- Aromatherapy:Single-origin Humulus lupulus extracts for sleep and anxiety positioning command three-to-four-fold cosmetic-grade premiums at wellness retailers in California and Colorado. EMA herbal medicinal product guidelines create compliance moats for suppliers investing in GMP-certified infrastructure.
- Cosmetics:Clean-label procurement policies at European formulators drive rejection of pyrethroid traces above sub-ppm thresholds.
- Health Supplements:Encapsulated lupulin bitter acids target niche botanical supplement channels with specialized extraction requirements.
Food & Beverage anchors volume throughput; aromatherapy climbs the fastest on margin expansion.
End User:
Procurement scale and technical sophistication stratify buyer power across the value chain.
- Manufacturers:Fragrance houses and multinational flavor companies impose ISO 17025 accreditation and blockchain-verified provenance as non-negotiable contract filters. Dual certification timelines for FDA GRAS and EMA quality dossiers stretch quality assurance bandwidth, delaying supplier qualification.
- Retailers:Wellness chains and specialty cosmetics buyers stock single-origin SKUs with field-to-flask documentation aligned with anticipated EU supply chain disclosure mandates.
- Distributors:Traditional intermediaries face margin compression as direct-to-brewer contracting eliminates distribution tiers in the Pacific Northwest.
- Individual Consumers:Direct e-commerce purchases of aromatherapy oils remain fragmented and price-sensitive.
Manufacturers concentrate procurement volume; retailers are gaining share fastest on premium positioning.
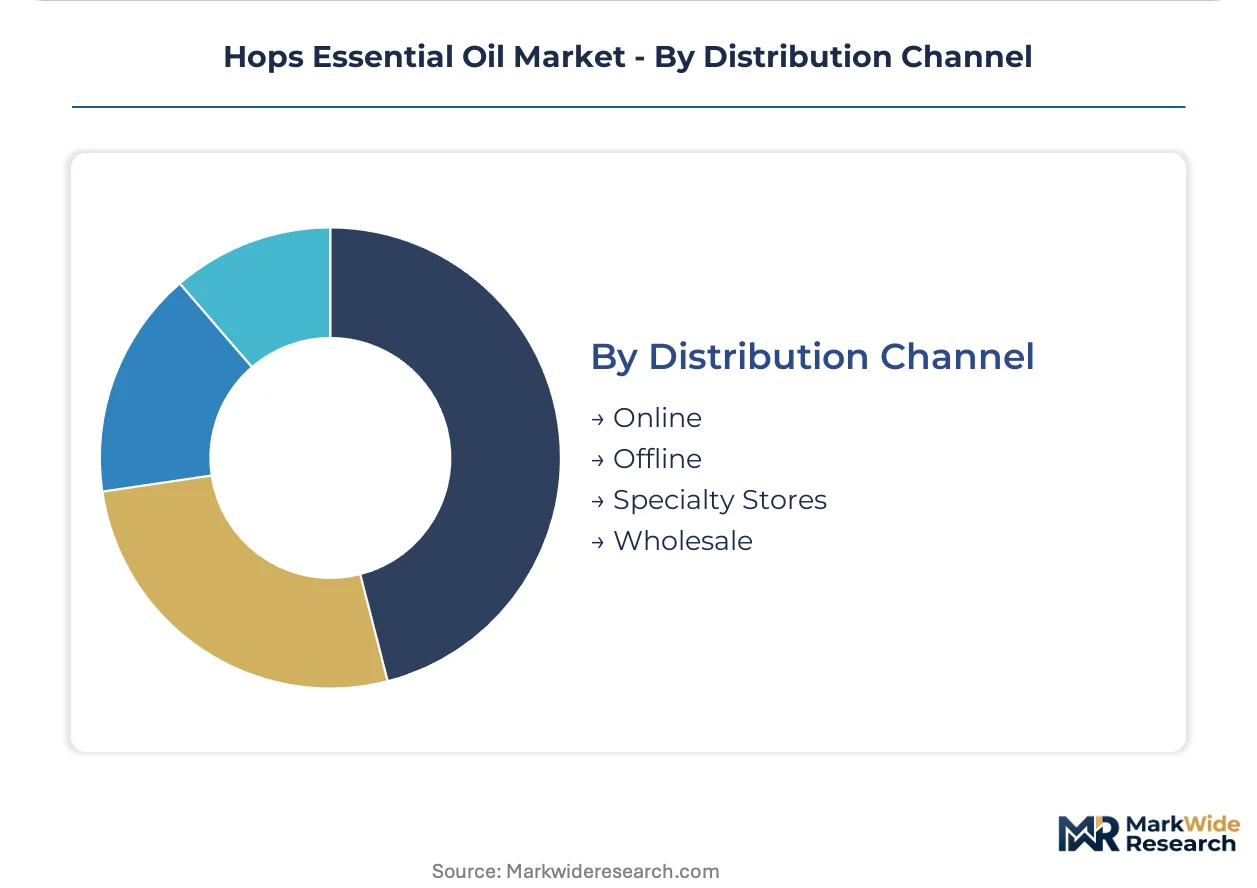
Distribution Channel:
Channel economics reflect customer acquisition costs and technical support requirements.
- Wholesale:Bulk contracts to fragrance houses and brewing collectives minimize per-unit logistics overhead. German cooperatives leverage established relationships with European fragrance houses to lock in annual volumes despite Hallertau weather volatility.
- Specialty Stores:Curated aromatherapy and craft brewing suppliers provide education-intensive sales environments for premium SKUs.
- Online:Direct-to-brewer platforms enable Yakima Valley growers to bypass German intermediaries entirely.
- Offline:Conventional agricultural commodity channels serve undifferentiated extract volumes.
Wholesale commands the greatest throughput; specialty stores post the steepest expansion trajectory on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Craft brewing precision dosing concentrates procurement power in Germany's Hallertau region and the United States Pacific Northwest, where terroir-specific aroma profiles command contract premiums.
Germany
Fragrance houses in Frankfurt and Hamburg source noble hop oils from Hallertau cooperatives for premium cosmetic formulations. REACH documentation mandates from ECHA require sub-ppm pesticide residue testing, filtering out non-accredited suppliers. Bavarian extraction facilities deploy in-house LC-MS/MS screening to maintain EU pharmaceutical contract eligibility.
United States
Oregon and Washington brewers sign three-year offtake agreements with Yakima Valley growers for CO₂-extracted oils with batch-to-batch consistency. FDA GRAS self-affirmation pathways enable rapid food-grade market entry compared to European regulatory timelines. Portland brewing collectives now contract directly with named farms, eliminating traditional distribution intermediaries.
Czech Republic
Saaz variety preservation programs sustain traditional steam distillation output for heritage lager producers. National agricultural subsidies support smallholder cooperatives maintaining ISO 17025 laboratory infrastructure. Žatec processing clusters supply terpene fractions to German fragrance houses facing Hallertau weather volatility.
Slovenia
Styrian hillside wildcrafting operations harvest unmanaged Humulus lupulus populations for artisanal brewers seeking scarcity positioning. EU organic certification requirements shape cultivation protocols for export-bound volumes. Maribor-area extraction units serve wellness retailers demanding single-origin documentation for sleep-positioning SKUs.
Hops Essential Oil Market Competitive Landscape
German cooperatives anchor one tier; Pacific Northwest integrated suppliers hold contract volume through provenance control. The supplier base compresses as REACH documentation burdens and ISO 17025 accreditation costs filter out smaller growers. Three archetypes dominate: integrated agricultural processors with captive raw material supply, specialized CO₂ extraction technology licensors, and heritage cooperative structures with established fragrance-house relationships. Competitive moves center on backward integration into cultivation assets and GMP-certified infrastructure investment for pharmaceutical-grade qualification.
Among integrated processors, Yakima Chief Hops Inc. and Barth-Haas Group exemplify the provenance-control archetype, each leveraging geographic concentration to secure multi-year contracts. Hopsteiner Group occupies a position within the technology-specialist tier, representing solvent-free processing capabilities that align with tightening EU purity thresholds. These three entities collectively illustrate how capital intensity and regulatory compliance reshape competitive positioning across extraction technology and certification tiers.
| Leading Market Players |
|---|
| Yakima Chief Hops Inc. |
| Barth-Haas Group |
| Hopsteiner Group |
| Kalsec Inc. |
| Steiner Hops Ltd |
| John I. Haas, Inc. |
| BSG Hops |
| Brewers Select Limited |
| Hollingberry & Son Inc. |
| Others |
Supply & Pricing Matrix
Supercritical CO₂ extraction maturation simultaneously compresses per-unit processing costs and decentralizes supply away from German cooperative monopolies, enabling Pacific Northwest growers to capture margin previously ceded to fragrance-house intermediaries while REACH compliance investments concentrate contract eligibility among accredited suppliers.
Pricing Analysis
Volume concentrates in conventional steam-distilled fractions serving mass-market beer flavoring, while margins accrue to organic-certified and pharmaceutical-grade tiers commanding three-to-four-fold premiums at cosmetics formulators and wellness retailers. Price differentiation rests on ISO 17025 accreditation status and provenance documentation depth, with Hallertau cooperatives leveraging EMA compliance to sustain premium positioning. Pricing pressure intensifies in conventional grades as synthetic terpene blends undercut natural extracts in undifferentiated applications. Craft breweries exhibit lowest price sensitivity, prioritizing batch-to-batch consistency and terroir specificity over per-unit cost.
Supply Chain Analysis
Direct-to-brewer platforms and three-year offtake agreements now displace traditional distribution tiers in the Pacific Northwest, though wholesale contracts to European fragrance houses still anchor global throughput. Geographic supply concentrates in Germany's Hallertau region, the United States Pacific Northwest, and the Czech Republic's Žatec processing clusters. Raw material dependencies center on lupulin gland yields from Humulus lupulus cultivars, noble hop varietal preservation, and seasonal harvest labor availability. Single-source vulnerability to Hallertau weather volatility and fungal pressure represents the dominant structural risk, with no near-term geographic diversification capable of matching aroma fraction quality.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
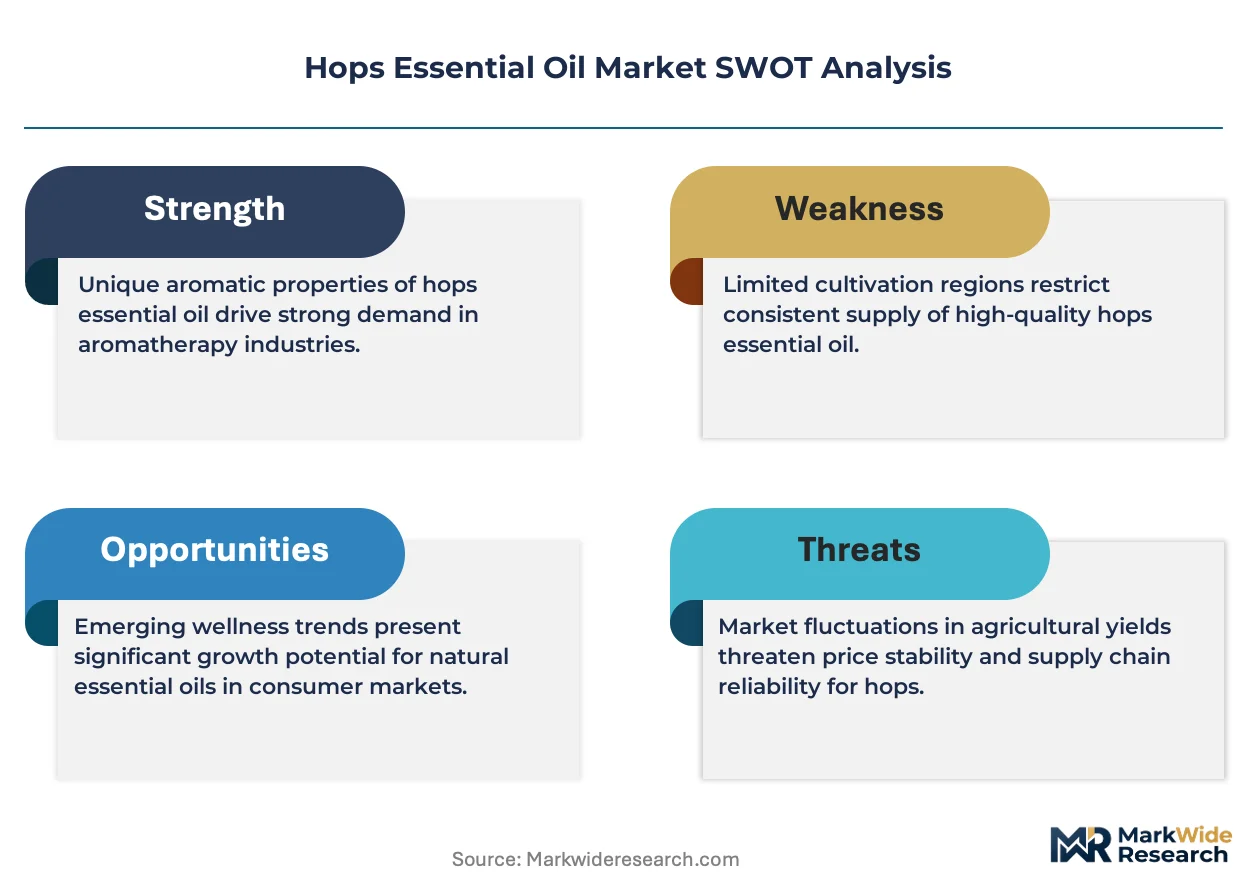
This market functions as a vertical-integration race where control over cultivation assets and GMP-certified extraction infrastructure determines contract eligibility for pharmaceutical-grade and premium wellness channels.
For Market Incumbents: Hedge against synthetic terpene substitution threats by deepening backward integration into certified organic cultivation and deploying blockchain-verified provenance systems ahead of anticipated EU supply chain disclosure mandates. Prioritize captive CO₂ extraction capacity to eliminate tolling dependencies and sustain margin capture as REACH documentation burdens filter out smaller competitors. For New Entrants and Emerging Players: Begin with aromatherapy and wellness retail channels where single-origin positioning commands scarcity premiums and regulatory barriers remain lower than pharmaceutical-grade thresholds. Target Slovenian Styrian wildcrafting operations and Pacific Northwest craft-scale brewery laboratories as penetrable geographies with established demand for terroir-specific extracts. Pursue direct-to-brewer contracting models that eliminate distribution intermediaries entirely. For Investors and Strategic Acquirers: Re-rating potential sits with integrated agricultural processors possessing captive raw material supply and ISO 17025 laboratory infrastructure given REACH compliance concentration effects. Long-term viability over the next decade hinges on GMP certification completion and EMA herbal medicinal product dossier preparation. Monitor ECHA SVHC candidate list expansion for residual pesticide metabolites as the critical inflection signal for supplier exclusion waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cultivation | Yakima Valley growers secure multi-year brewery contracts through field-to-flask provenance control. |
| GMP-Certified CO₂ Infrastructure Investment | EMA herbal medicinal product guidelines lock out commodity processors from pharmaceutical channels. |
| Blockchain-Verified Terroir Documentation | EU supply chain disclosure mandates enable premium pricing for named geographic origin claims. |
| Direct-to-Brewer Contracting Platforms | Pacific Northwest brewing collectives eliminate two distribution tiers through named grower agreements. |
| Mobile Processing Unit Leasing | Oregon craft brewers capture freshness premiums through on-site lupulin extraction bypassing tolling fees. |
Research Methodology
Document review covered ECHA REACH guidance documents, FDA GRAS self-affirmation pathways, and EMA herbal medicinal product quality guidelines, complemented by interviews with extraction facility operators, craft brewery procurement leads, fragrance house technical directors, and cooperative agricultural managers. Secondary validation drew from customs trade data, SEC filings of publicly traded flavor houses, ISO accreditation registries, and agricultural yield databases. Bottom-up triangulation across named grower contracts and top-down reconciliation against fragrance-house procurement volumes anchored market sizing integrity.
Segmented outputs across the projection horizon reflect modeled dimensions including extraction technology tier, certification grade, end-use application, and geographic production cluster. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and technology adoption curves. Industry-specific forecast inputs incorporated lupulin gland yield variability by cultivar and REACH documentation cost escalation curves for residue testing infrastructure.
Underlying measurement precision varies by segment; pharmaceutical-grade and organic-certified tiers carry tighter precision than conventional steam-distilled volumes given more transparent contract disclosure. Forecasts assume continuation of current regulatory trajectories and technology cost curves, with revision triggers including ECHA SVHC list expansion, synthetic terpene blend performance improvements, or fungal pressure events in the Hallertau region. Practitioners should monitor EMA herbal medicinal product guideline enforcement intensity and craft brewery direct contracting adoption rates for early signals of supplier consolidation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
Sea Urchin and Roe Flavor Ingredients Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
American Spikenard Extract Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Licorice Extract Market