
 Asia-Pacific Cloud Kitchen Market | 2026-2036
Asia-Pacific Cloud Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cloud Kitchen Market Analytics
Premium hygiene certification tiers are redrawing competitive boundaries across the Asia-Pacific cloud kitchen sector. Rebel Foods leverages its proprietary operating system to sustain quality consistency across fragmented urban markets. Swiggy Platform anchors last-mile density through exclusive dark-store partnerships in Indian cities. Zomato Ltd. differentiates via integrated supply-chain controls that reduce ingredient variability for franchise partners.
Cloud kitchens are centralized food-production facilities designed exclusively for off-premise consumption, equipped with commercial-grade ventilation systems, temperature-calibrated prep zones, and order-routing software that synchronizes kitchen output with delivery fleet dispatch. The primary commercial purpose is to eliminate front-of-house costs while maximizing throughput per square meter of production space. Delivery-only service type leads volume share but hybrid formats are capturing margin pools by combining ghost production with limited customer pickup. Franchise business models dominate capital deployment as operators seek to limit real-estate exposure in high-rent Asian metros. Online ordering technology underpins the entire operational stack, though food preparation software is emerging as the critical differentiator for multi-brand operators managing complex SKU portfolios.
FSSAI in India enforces standardized kitchen hygiene audits that determine platform visibility and consumer trust scores. Singapore's NEA grading system and Australia's Food Standards Code create comparable compliance thresholds that shape market access for regional operators. China's SAMR oversees food safety traceability requirements that cloud kitchens must integrate into their digital order-management systems. Stakeholders should monitor how regulatory digitization of inspection data alters the cost structure of multi-jurisdiction expansion.
Market Dynamics
India's FSSAI hygiene grading mandates are forcing cloud kitchen operators to invest in centralized compliance infrastructure, redrawing competitive boundaries across the Asia-Pacific region.
Growth Catalysts
- Urban millennial demand concentration:Quick-service restaurant chains are expanding cloud kitchen footprints to serve dense metropolitan corridors where delivery-only consumption dominates meal occasions.
- FSSAI digitization:India's food safety regulator is mandating standardized kitchen hygiene audits that determine platform visibility and consumer trust scores, accelerating operator investment in compliance infrastructure.
- Last-mile density economics:Exclusive dark-store partnerships in Indian cities are anchoring delivery fleet utilization rates that improve unit economics per square meter of production space.
Market Restraints
- Real-estate cost escalation:High-rent Asian metros constrain capital deployment, pushing operators toward franchise models to limit direct property exposure.
- Supply concentration in tier-1 cities:Demand clusters in India's metropolitan corridors create dependency on limited geographic zones for volume generation.
- Ingredient variability:Multi-brand operators face complexity managing SKU portfolios across fragmented urban procurement networks.
Strategic Opportunities
- Secondary city penetration:Underpenetrated Indian tier-2 and tier-3 urban centers offer whitespace for delivery-only facility expansion beyond saturated metros.
- Hybrid format adoption:Ghost production combined with limited customer pickup is capturing margin pools unavailable to pure delivery-only operations.
- NEA grading alignment:Singapore's national environmental agency certification creates pathway for regional operators to access premium market tiers through hygiene standard portability.
Industry Challenges
- Multi-jurisdiction compliance scaling:Operators expanding across India, Singapore, and Australia must integrate disparate regulatory digitization requirements into unified order-management systems.
- Food preparation software integration:Multi-brand operators require sophisticated SKU management platforms that synchronize kitchen output with delivery dispatch across fragmented brand portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cloud Kitchen Market |
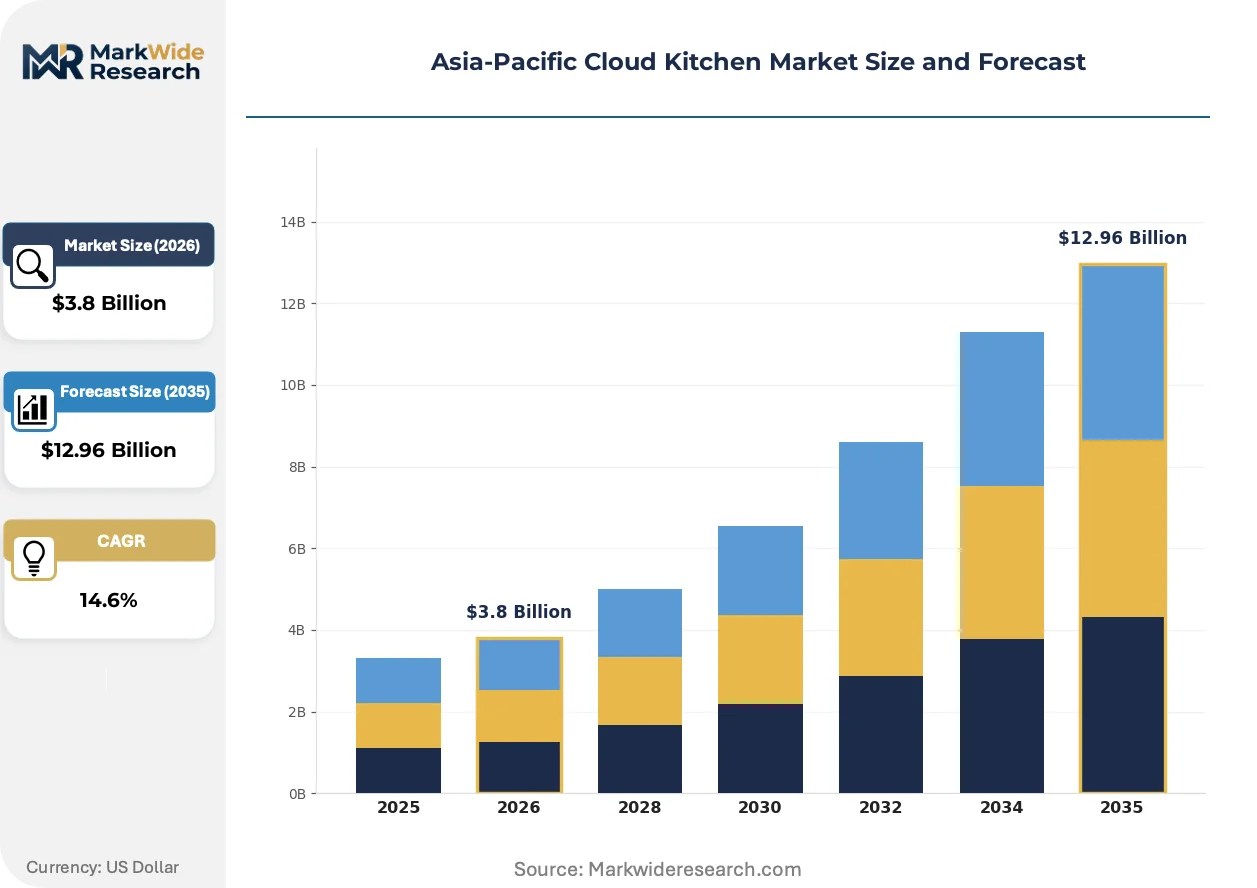
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Delivery-Only, Hybrid, Virtual Brands, Cloud Cafes Business Model: Franchise, Independent, Partnership, Corporation Technology: Online Ordering, Food Preparation Software, POS Systems, Customer Management Customer Segment: Busy Professionals, Families, Students, Food Enthusiasts |
| Companies Covered | Zomato Ltd., Ghost Kitchens Private Limited, Rebel Foods, CloudKitchens, kitchens@, Kitopi, Curefoods, DoorDash Inc., Swiggy Platform, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cloud Kitchen Market Evolving Landscape
Cloud kitchen technology stacks are converging around order-routing software that synchronizes production with fleet dispatch, compressing the operational gap between kitchen output and last-mile delivery.
Proprietary operating systems for quality consistency are displacing fragmented point solutions across Asia-Pacific cloud kitchen networks. Rebel Foods and regional operators are deploying integrated platforms that calibrate temperature-controlled prep zones and ventilation systems across distributed facilities. This technology convergence is displacing manual quality oversight and enabling centralized control over hygiene compliance in markets with divergent regulatory requirements.
FSSAI's digitization of inspection data is altering cost structures for multi-jurisdiction expansion across India. The regulator's standardized audit protocols now determine platform algorithmic visibility and consumer-facing trust scores, forcing operators to build compliance infrastructure that transcends local health department variations. Kitchen operators in Mumbai, Bangalore, and Delhi are responding by centralizing documentation systems that feed directly into aggregator platform APIs.
Aggregator platform procurement consolidation is compressing supplier relationships for cloud kitchen operators. Swiggy Platform and Zomato Ltd. are tightening supply-chain controls that reduce ingredient variability for franchise partners, replacing traditional wholesale market sourcing with captive procurement networks. This shift is most visible in Indian metropolitan corridors where platform-integrated kitchens now represent the dominant buyer segment for processed ingredients and standardized food inputs.
Asia-Pacific Cloud Kitchen Market Segmentation
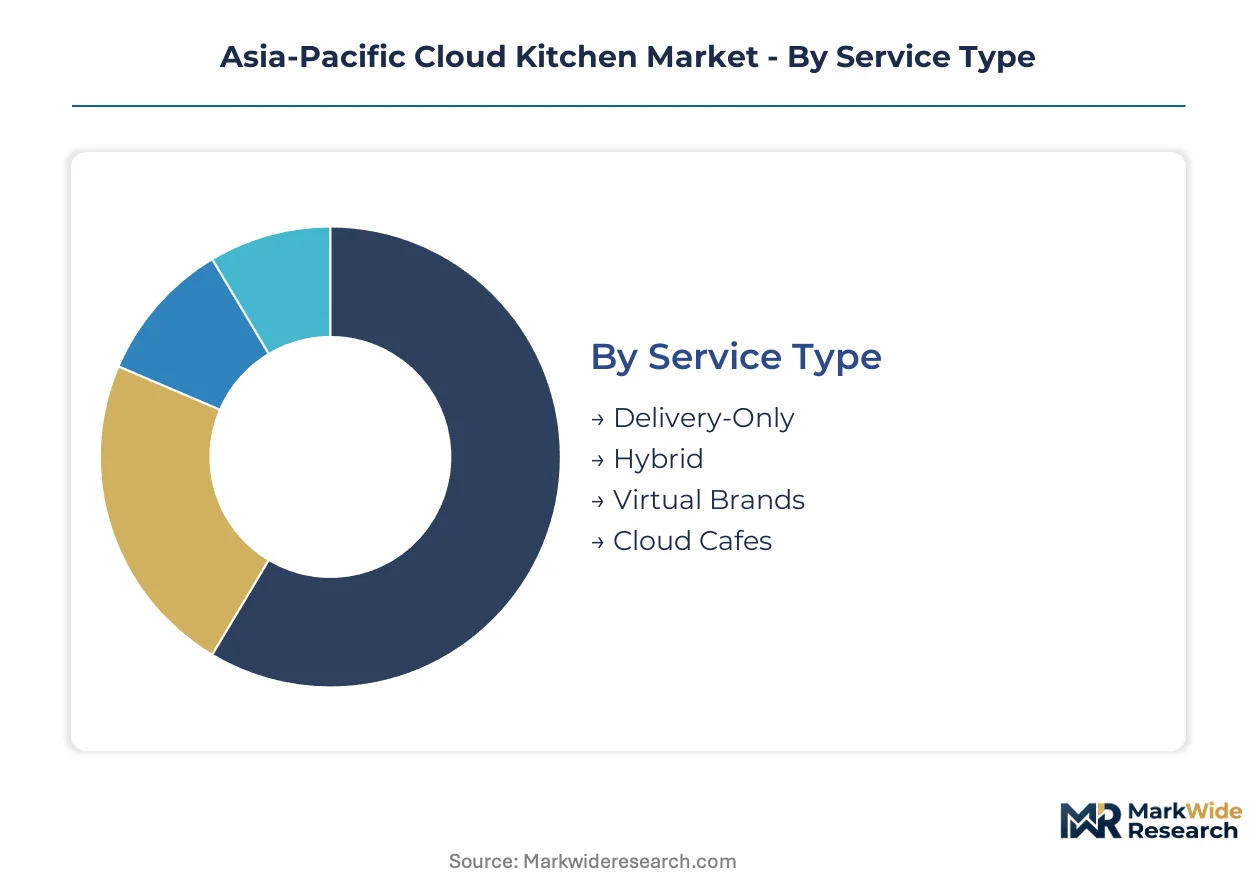
Segmentation in the Asia-Pacific cloud kitchen market reveals how regulatory differentiation, technology integration, and customer behavior intersect to create distinct operational archetypes. Each dimension carries implications for compliance infrastructure, capital intensity, and margin structure across Indian metros, Singapore, and Australian urban corridors.
Service Type:
FSSAI hygiene grading mandates in India and Singapore's NEA certification system create divergent compliance burdens across service formats, with delivery-only facilities facing distinct ventilation and temperature-control specifications versus hybrid operations.
- Delivery-Only:Centralized food-production facilities equipped with commercial-grade ventilation systems and temperature-calibrated prep zones, designed exclusively for off-premise consumption. Demand concentrates in Mumbai, Bangalore, and Delhi metropolitan corridors where Rebel Foods and Swiggy Platform operate dense networks of dark-store facilities. FSSAI digitization of inspection data forces these operators into centralized compliance infrastructure that transcends local health department variations.
- Hybrid:Ghost production combined with limited customer pickup, capturing margin pools unavailable to pure delivery-only operations through reduced platform commission exposure and direct consumer relationships. Adoption accelerates in Singapore and Australian cities where NEA grading alignment and Food Standards Code requirements reward physical presence with premium certification tiers.
- Virtual Brands:Digital-native restaurant concepts operating without physical storefront visibility, leveraging aggregator platform algorithms for customer acquisition.
- Cloud Cafes:Production facilities optimized for beverage-forward menus with specialized equipment configurations and rapid throughput design.
Established volume favors Delivery-Only; emerging adoption favors Hybrid.
Business Model:
Real-estate cost escalation across high-rent Asian metros is concentrating capital deployment into models that limit direct property exposure, with franchise structures absorbing location risk while partnership formats leverage platform-controlled supply chains.
- Franchise:Dominant capital deployment mechanism where operators license proprietary operating systems and brand portfolios to local investors who assume real-estate and regulatory compliance obligations. Zomato Ltd. and regional aggregators use this structure to penetrate Indian tier-2 and tier-3 urban centers without balance-sheet property concentration.
- Independent:Owner-operated facilities with full control over menu development and supplier relationships, prevalent among single-brand specialists in Australian metropolitan markets where Food Standards Code compliance rewards operational autonomy.
- Partnership:Exclusive dark-store arrangements between kitchen operators and aggregator platforms, anchoring last-mile density economics through captive procurement networks and integrated order-routing software.
- Corporation:Wholly owned facilities operated by quick-service restaurant chains expanding cloud kitchen footprints to serve urban millennial demand in dense metropolitan corridors.
Franchise models dominate current deployment; partnership structures are climbing the fastest as platform consolidation accelerates.
Technology:
Order-routing software that synchronizes kitchen output with delivery fleet dispatch has become the operational core, with food preparation software emerging as the critical differentiator for multi-brand operators managing complex SKU portfolios across fragmented urban procurement networks.
- Online Ordering:Digital storefront and payment infrastructure underpinning the entire operational stack, with aggregator platform APIs determining visibility algorithms and consumer trust scores in FSSAI-regulated Indian markets.
- Food Preparation Software:Integrated platforms calibrating temperature-controlled prep zones and ventilation systems across distributed facilities, displacing manual quality oversight and enabling centralized hygiene compliance. Rebel Foods deploys proprietary systems to sustain quality consistency across fragmented urban markets.
- POS Systems:Transaction processing and kitchen display coordination hardware, standardizing order flow in high-throughput environments.
- Customer Management:Data analytics and retention tooling for direct relationship maintenance outside aggregator platform dependency.
Online Ordering captures installed base; Food Preparation Software represents the steepest expansion trajectory as multi-brand complexity intensifies.
Customer Segment:
Demand concentration in India's metropolitan corridors and comparable Asian urban centers segments sharply by meal occasion frequency, platform loyalty, and price sensitivity, with each cohort driving distinct kitchen format and menu portfolio decisions.
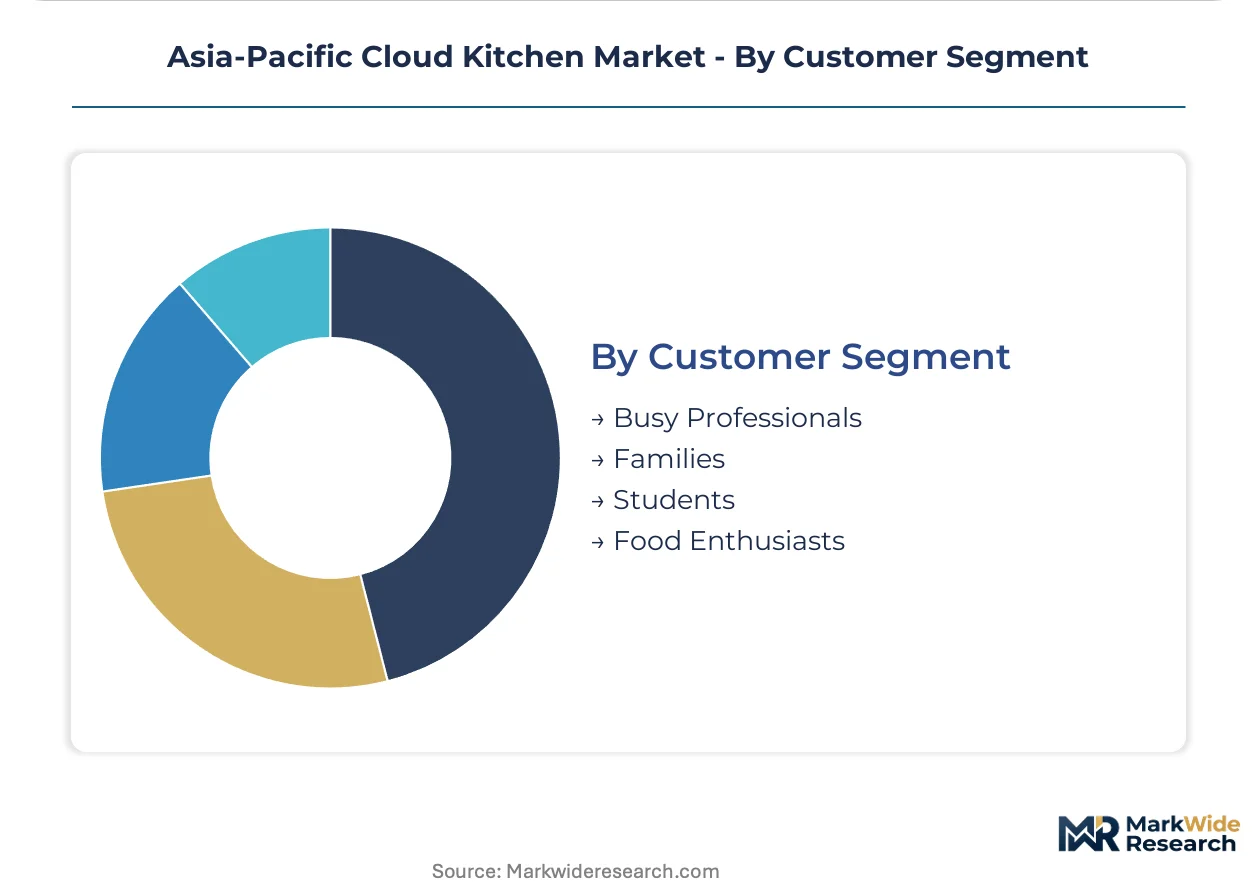
- Busy Professionals:High-frequency, convenience-driven ordering during weekday lunch and dinner occasions, concentrated in Bangalore and Delhi central business districts where delivery-only facilities optimize for sub-30-minute fulfillment windows.
- Families:Larger basket-size occasions with menu variety requirements, favoring multi-brand cloud kitchens and hybrid formats with pickup options for weekend aggregation.
- Students:Price-sensitive, promotion-responsive demand clustered near university corridors in Mumbai and Singapore, driving virtual brand proliferation and aggregator platform subsidy cycles.
- Food Enthusiasts:Quality-seeking, review-influenced customers responsive to FSSAI hygiene grades and NEA certification visibility, concentrated in premium Singapore and Australian metro segments.
Busy Professionals sustain current volume; Food Enthusiasts are gaining share fastest as certification transparency improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia-Pacific cloud kitchen sector, with Indian metropolitan consumers driving volume through promotion-responsive demand while Singapore and Australian buyers prioritize hygiene certification transparency over cost.
India
Urban millennial demand concentrates in Mumbai, Bangalore, and Delhi metropolitan corridors where delivery-only consumption dominates weekday meal occasions. FSSAI hygiene grading mandates now determine platform algorithmic visibility and consumer trust scores, forcing operators into centralized compliance infrastructure. Rebel Foods and Swiggy Platform operate dense networks of dark-store facilities across these cities, anchoring last-mile density economics through exclusive partnerships.
Singapore
Food enthusiasts and busy professionals generate premium-tier demand responsive to visible hygiene certification and rapid fulfillment windows. NEA grading alignment creates pathway for regional operators to access premium market tiers through certification portability and standardized audit protocols. Central business district clusters and university corridors host hybrid format adoption combining ghost production with limited customer pickup options.
Australia
Quality-seeking consumers in Sydney and Melbourne metropolitan markets reward operational autonomy and direct supplier relationships over platform dependency. Food Standards Code compliance requirements shape market access for independent owner-operated facilities and franchise structures alike. Multi-brand cloud kitchens penetrate suburban corridors where family-oriented demand favors menu variety and weekend aggregation occasions.
China
SAMR food safety traceability requirements integrate directly into digital order-management systems for cloud kitchens operating in Yangtze River Delta and Pearl River Delta urban clusters. Platform consolidation accelerates as aggregator procurement networks replace traditional wholesale market sourcing for processed ingredients. Tier-2 city penetration offers whitespace for delivery-only facility expansion beyond saturated Shanghai and Shenzhen metro areas.
Japan
Convenience-driven demand in Tokyo and Osaka metropolitan areas favors sub-30-minute fulfillment windows and standardized menu portfolios. METI oversight of food service digitization shapes technology adoption patterns for order-routing software and kitchen display systems. Compact urban geography supports high-throughput delivery-only facilities optimized for commercial-grade ventilation and temperature-calibrated prep zones.
Asia-Pacific Cloud Kitchen Market Competitive Landscape
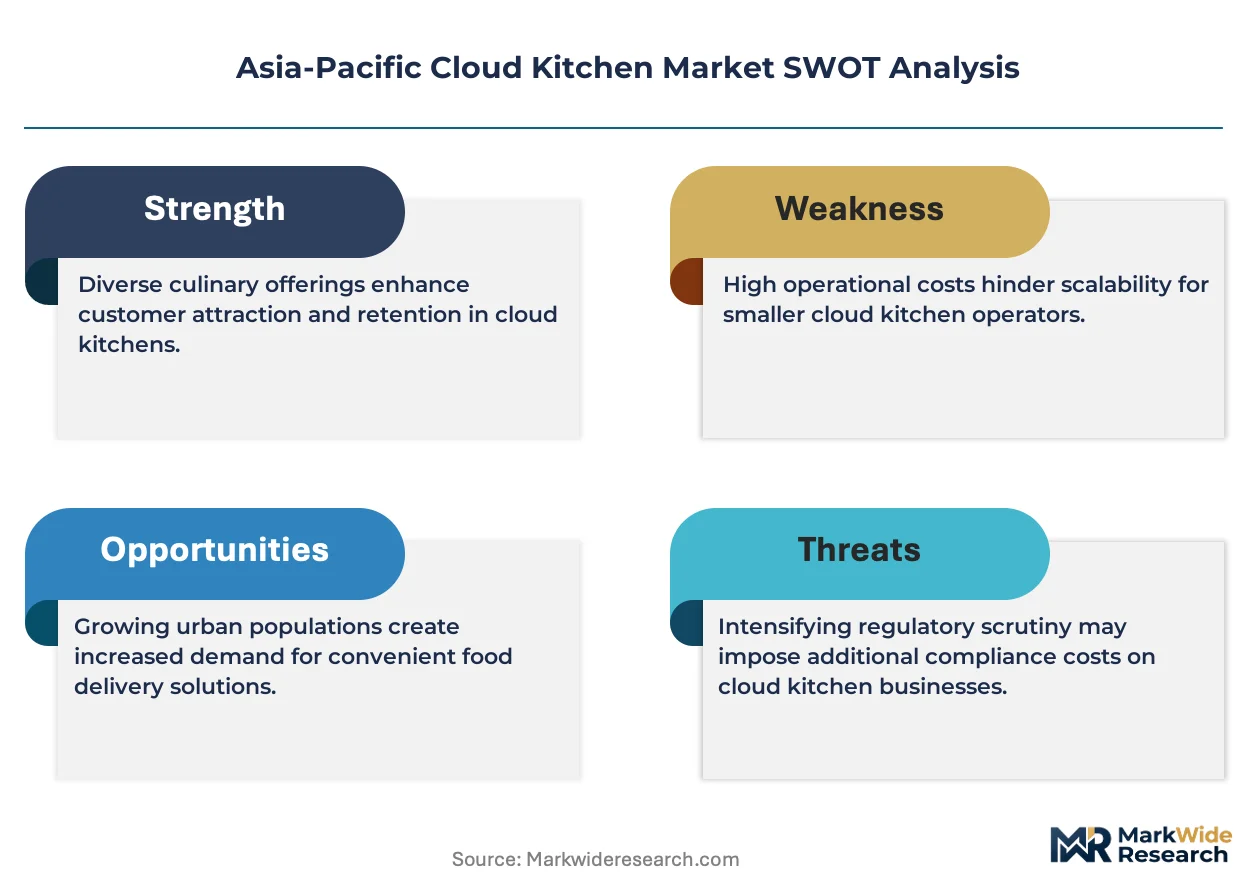
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific cloud kitchen sector. The market structure fragments across aggregator platforms, multi-brand operators, and single-concept specialists competing on distinct vectors. Three strategic archetypes dominate: platform-integrated networks leveraging captive procurement, vertically integrated operators controlling proprietary technology stacks, and asset-light franchise licensors expanding through local capital. Dominant competitive moves include exclusive dark-store partnerships anchoring last-mile density and proprietary operating system deployment for quality consistency across distributed facilities.
Among India-based multi-brand operators, Rebel Foods exemplifies technology-led vertical integration through proprietary kitchen operating systems. Zomato Ltd. and Swiggy Platform occupy positions as aggregator-anchored networks tightening supply-chain controls and integrating compliance infrastructure directly into platform APIs. These three entities represent the primary competitive anchors shaping capital deployment patterns and regulatory response strategies across the regional market.
| Leading Market Players |
|---|
| Zomato Ltd. |
| Ghost Kitchens Private Limited |
| Rebel Foods |
| CloudKitchens |
| kitchens@ |
| Kitopi |
| Curefoods |
| DoorDash Inc. |
| Swiggy Platform |
| Others |
Value Network & Pricing Analysis
Last-mile density economics in Mumbai and Bangalore anchor both supply concentration and price floors across the Asia-Pacific cloud kitchen sector. Swiggy Platform and Zomato Ltd. leverage exclusive dark-store partnerships to compress delivery costs, forcing independent operators into franchise models that absorb real-estate exposure while accepting thinner margins.
Pricing Analysis
FSSAI hygiene grading dictates the pricing tier structure across Indian metropolitan corridors. Three-tier pricing structure across premium, standard, and economy levels separates NEA-certified facilities from FSSAI-compliant kitchens from ungraded operations. Cost compression in the economy tier is intensifying because aggregator platform commission structures squeeze operator margins. Students clustered near university corridors exhibit highest price sensitivity, while food enthusiasts in Singapore premium segments prioritize certification visibility over cost.
Supply Chain Analysis
Port congestion on India-Singapore trade lanes elevates inbound logistics costs for temperature-controlled equipment imports. China, India, and Vietnam concentrate manufacturing of commercial-grade ventilation systems and kitchen display hardware. Raw material dependencies center on stainless steel fabrication, refrigerant gases, and IoT sensor components. Single-source vulnerability from Chinese HVAC component suppliers threatens equipment lead times. Distribution runs through aggregator platform captive procurement networks that displace traditional wholesale market sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in cloud kitchens hinges on API interoperability between compliance infrastructure and aggregator order-management systems. FSSAI's digitized inspection data feeds directly into Swiggy and Zomato algorithms, creating ecosystem lock-in that rewards early compliance integration.
For Market Incumbents: Shield market position by deepening proprietary operating system deployment across tier-2 and tier-3 expansion, countering Rebel Foods' technology-led vertical integration. Accelerate NEA grading alignment in Singapore to preempt regional competitors from capturing premium certification portability. Franchise model density in Indian metros remains the priority lever against emerging platform-integrated partnership structures. For New Entrants and Emerging Players: FSSAI fast-track certification programs in underpenetrated Indian tier-2 cities offer immediate whitespace penetration before incumbent network effects solidify. Target hybrid format adoption in Australian suburban corridors where family-oriented demand favors direct pickup relationships over pure delivery dependency. Anchor go-to-market through exclusive dark-store arrangements with secondary aggregator platforms seeking last-mile density. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-brand operators with food preparation software differentiation over single-concept specialists facing SKU complexity barriers. Long-term viability across the analysis window rests on compliance infrastructure portability across India, Singapore, and Australian regulatory frameworks. Monitor FSSAI algorithmic visibility weighting as inflection signal for platform-dependent valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Operating System Deployment | Rebel Foods calibrates temperature-controlled prep zones across distributed facilities without manual oversight. |
| NEA Grading Alignment | Singapore certification portability opens premium market tiers for regional operators expanding from India. |
| Exclusive Dark-Store Partnership | Swiggy Platform anchors last-mile density economics through captive procurement network integration. |
| Hybrid Format Expansion | Ghost production with limited pickup captures margin pools unavailable to pure delivery-only operations. |
| Tier-2 City Penetration | Zomato franchise structures absorb real-estate exposure in underpenetrated Indian urban centers. |
Research Methodology
Initial hypotheses were tested against primary input from cloud kitchen operations directors, aggregator platform supply chain leads, FSSAI compliance officers, and franchise development managers and refined through secondary validation. Bottom-up facility count modeling triangulated against top-down addressable meal occasion estimates. Secondary sources included FSSAI digitization directives, NEA grading protocols, aggregator platform API documentation, and Australian Food Standards Code compliance frameworks.
Variance decomposition across service type, business model, technology stack, and customer segment dimensions shaped the analytical framework over the projection horizon. CAGRs derived from facility deployment trajectories, urban millennial consumption frequency shifts, and regulatory digitization timelines. Food preparation software adoption curves and hybrid format penetration rates served as industry-specific forecast inputs alongside metropolitan corridor real-estate cost indices.
Underlying assumptions cover sustained aggregator platform consolidation, stable FSSAI algorithmic visibility weighting, and continued urban millennial demand concentration, with deviation risk concentrated in regulatory digitization pace and tier-2 city infrastructure readiness. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Bangladesh Food Service Market
Food Service
One-Off Chopsticks Market
Food Service
North America Online Grocery Delivery Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Food Delivery Services Market
Food Service
Pizza Foodservice Market
Food Service
China Online Food Delivery Market
Food Service
Lunch Takeout Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Italy Foodservice Market
Food Service
Africa Foodservice Market
Food Service
Steam Tables and Food Well Market
Food Service
Bottled Water Cooler Market
Food Service
Europe Pizza Oven Market
Food Service
Portion Cups Market