
 Philippines Foodservice Market | 2026-2036
Philippines Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Foodservice Market Analytics
DTI's streamlined business registration procedures is repositioning the cost structure for new foodservice entrants. Jollibee Foods Corporation leverages its vertically integrated commissary network to sustain pricing power across provincial rollouts. Shakey's Pizza Asia Ventures anchors its expansion in community mall formats that dominate secondary city retail.
Philippines foodservice encompasses all commercial establishments preparing meals and beverages for immediate consumption, ranging from street food stalls to full-service restaurants with standardized kitchen equipment and cold-chain logistics. The sector serves daily nutrition, social gathering, and convenience needs across urban and peri-urban populations. Quick Service leads volume throughput due to standardized menus and drive-thru penetration, while Delivery service models capture the fastest expansion as logistics platforms integrate with restaurant POS systems. Full Service occupies the premium margin pool in business districts and tourism corridors where extended dining occasions justify higher per-check averages.
FSSAI-aligned local health codes, DTI's consumer protection standards, and city-level sanitation inspections collectively shape operational compliance burdens and facility design requirements. The Department of Labor and Employment's wage regulations influence front-of-house staffing models and automation timing. Stakeholders must monitor how provincial government units adapt national franchising rules to local zoning constraints.
Market Dynamics
DTI's business registration compression is electrifying provincial market entry timelines, collapsing permit windows from months to weeks and accelerating quick-service rollout velocity across secondary cities.
Growth Catalysts
- Metro Manila satellite expansion:Middle-class household formation in Quezon City, Muntinlupa, and Parañaque is generating sustained dine-out frequency growth. These clusters now anchor national demand concentration.
- DTI Ease-of-Doing-Business reforms:Streamlined national permitting procedures eliminate redundant municipal clearances. New entrants face compressed regulatory timelines that reduce pre-revenue burn.
- Integrated logistics platforms:Third-party delivery aggregators embedding directly into restaurant POS systems is enabling full-service operators to capture off-premise revenue without proprietary fleet investment.
Market Restraints
- Imported protein cost volatility:Swine and poultry supply disruptions elevate menu input unpredictability. Operators struggle to maintain margin stability across value-tier offerings.
- Cold-chain infrastructure gaps:Provincial distribution networks outside Luzon lack temperature-controlled last-mile capacity. This constrains fresh ingredient reach into Visayas and Mindanao expansion zones.
- FSSAI-aligned local health code complexity:Municipal sanitation inspection schedules vary across city government units. Multi-unit operators face fragmented compliance calendars that elevate administrative overhead.
Strategic Opportunities
- Cebu secondary city anchoring:Central Visayas presents underpenetrated full-service density relative to population scale. Community mall formats dominate local retail and offer turnkey expansion templates.
- Department of Labor wage regulation timing:Front-of-house automation investments accelerate as minimum wage adjustments compress labor margin pools. Self-service kiosk deployment is defensible against regulatory compression.
- Cloud kitchen convergence with delivery platforms:Virtual brand proliferation eliminates dine-in real estate requirements. Dark kitchen infrastructure enables rapid menu testing without storefront capex.
Industry Challenges
- Certified kitchen equipment technician scarcity:Commercial refrigeration and ventilation system maintenance requires specialized training. Provincial labor pools lack depth in food-safe equipment servicing.
- Legacy POS integration friction:Aggregator platform APIs often conflict with established restaurant management software. Data synchronization failures disrupt order flow and inventory accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Foodservice Market |
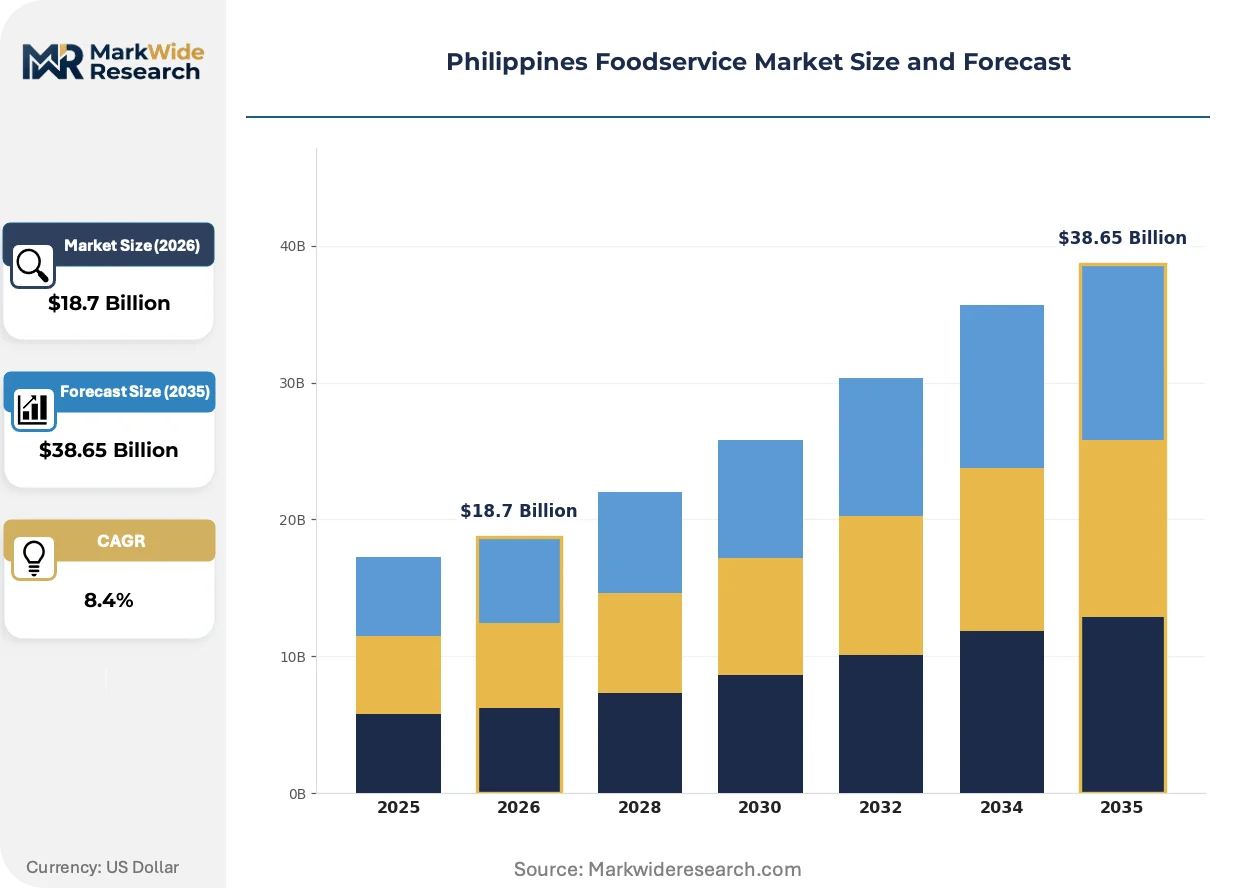
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverages, Quick Service, Full Service, Fast Casual Customer Type: Millennials, Families, Business Travelers, Tourists Service Model: Dine-in, Takeaway, Delivery, Catering Food Category: Asian Cuisine, Western Cuisine, Desserts, Vegan Options |
| Companies Covered | Shakey's Pizza Asia Ventures, Chowking, Jollibee Foods Corporation, KFC, Greenwich Pizza, McDonald's (Alliance Global Group), Starbucks Corporation, Fruitas Holdings, Max's Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Foodservice Market Evolving Landscape
Digital ordering infrastructure is compressing traditional service models across all format tiers. Three concurrent shifts are restructuring how Filipino consumers access prepared food.
Integrated kitchen display systems with predictive prep algorithms are electrifying back-of-house throughput efficiency. Quick-service chains deploy these systems to synchronize cook times with delivery driver arrival windows. The technology compresses customer wait intervals while reducing food waste from order abandonment.
Department of Labor and Employment wage board schedules are accelerating automation capex cycles across full-service segments. Operators front-load kiosk and mobile ordering investments ahead of mandated increases. The policy pressure is concentrating technology deployment in Metro Manila labor markets where wage floors bite hardest.
Community mall developers now anchor foodservice tenancy at 35-40% of gross leasable area. Provincial consumers treat these formats as default social gathering venues. Davao and Cagayan de Oro developments demonstrate this behavioral shift most visibly, with weekend foot traffic concentrating around dining clusters rather than traditional retail.
Philippines Foodservice Market Segmentation
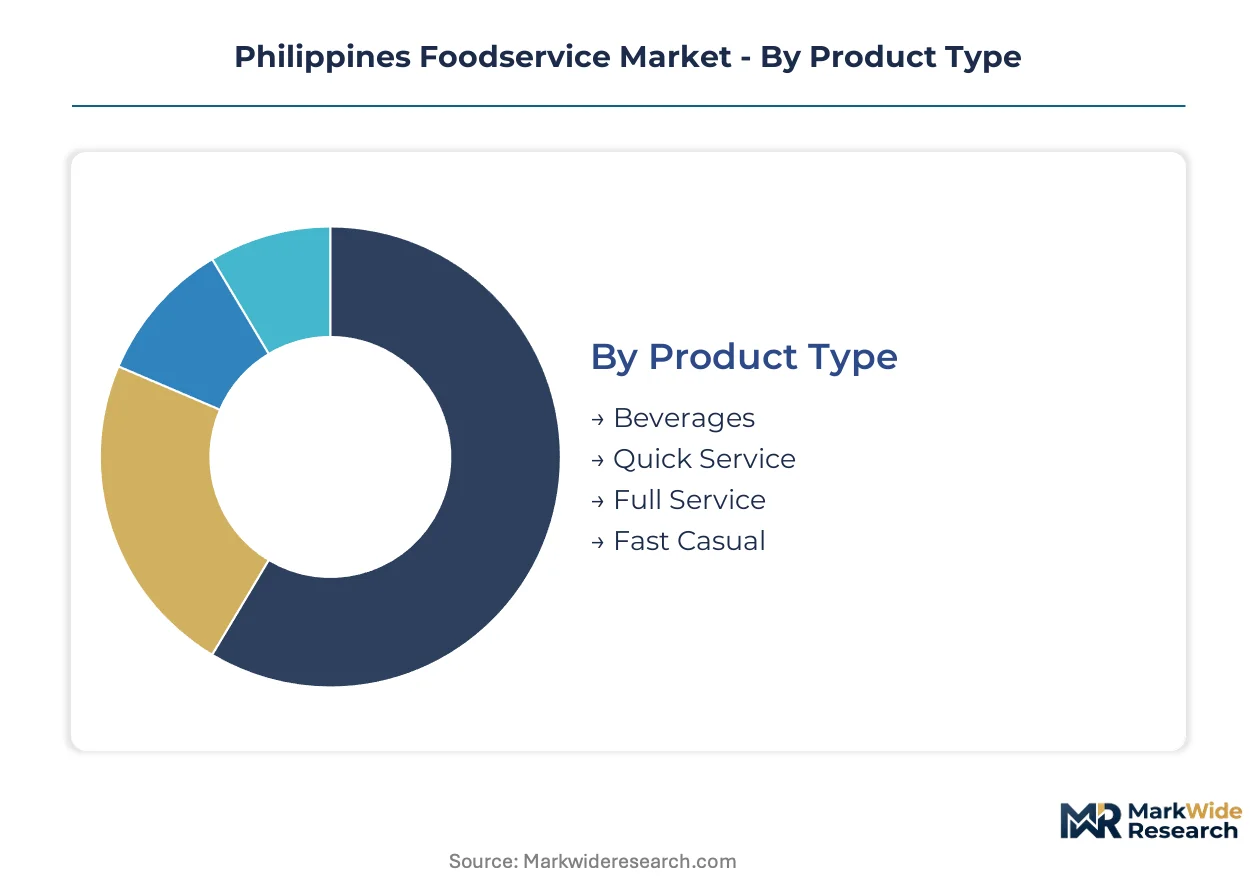
Segmentation in the Philippines foodservice market reveals how distinct operational models and consumer cohorts create divergent margin profiles. Each axis—product format, customer demographic, service channel, and cuisine type—commands separate capital allocation strategies from operators expanding across Metro Manila satellite cities and provincial capitals.
Product Type:
Standardized kitchen equipment and menu engineering specifications differentiate operational intensity across format tiers.
- Quick Service:Drive-thru infrastructure and commissary-fed supply chains enable volume throughput at compressed price points. Demand concentrates in Quezon City and Muntinlupa where middle-class household formation sustains daily transaction frequency.
- Full Service:Extended dining occasions require specialized ventilation systems and trained front-of-house staffing. Business districts in Makati and tourism corridors in Cebu anchor premium per-check averages through experiential positioning.
- Beverages:Compact equipment footprints and minimal cold-chain requirements suit high-rent mall kiosk deployment.
- Fast Casual:Hybrid counter-service models with upgraded ingredients target lunch-hour office workers in Ortigas and Bonifacio Global City clusters.
Quick Service leads on scale; Fast Casual leads on momentum.
Customer Type:
Disposable income distribution and dining occasion frequency vary sharply across generational and occupational cohorts.
- Families:Weekend gathering occasions drive large-party table turns in community mall formats. Parañaque and Davao developments show concentrated foot traffic around dining clusters during Saturday-Sunday peaks.
- Millennials:Digital-native ordering behavior and delivery platform integration define this cohort's access patterns. Mobile-first engagement in Metro Manila satellite cities accelerates off-premise revenue capture.
- Business Travelers:Expense-account dining concentrates in airport-adjacent and central business district locations.
- Tourists:Seasonal demand spikes in Boracay and Palawan require flexible staffing models.
Families dominate transaction volume; Millennials drive channel shift velocity.
Service Model:
Real estate requirements and labor deployment patterns diverge based on consumption location.
- Delivery:Third-party aggregator integration eliminates dine-in capex while expanding geographic reach. Dark kitchen proliferation in Mandaluyong and Pasig enables virtual brand testing without storefront investment.
- Dine-in:Full experiential delivery depends on location-specific zoning compliance and seating density optimization.
- Takeaway:Counter pickup suits high-footfall transit hubs and hospital-adjacent zones.
- Catering:Institutional contracts with corporate offices and educational facilities provide revenue stability.
Delivery expands most quickly; Dine-in retains margin concentration.
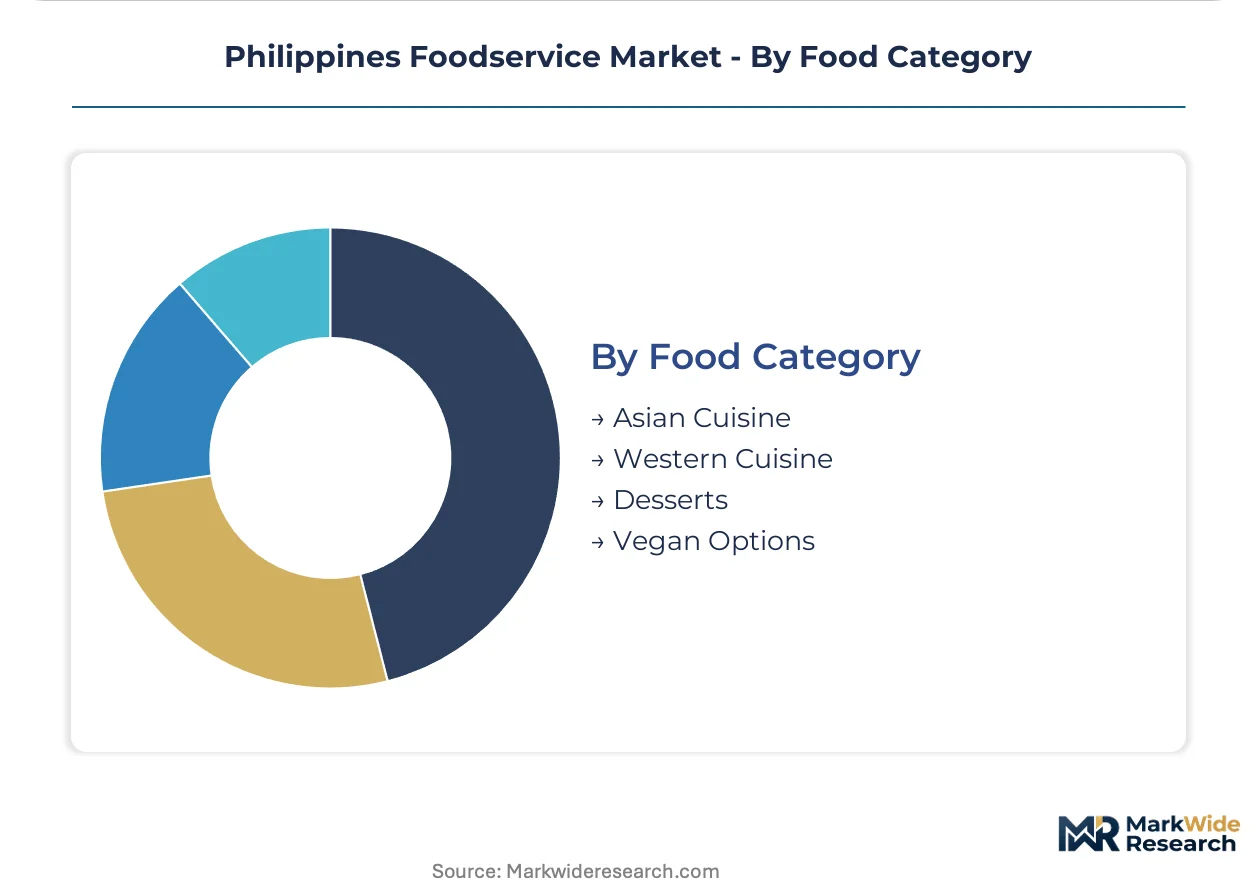
Food Category:
Ingredient sourcing complexity and kitchen skill requirements shape category economics.
- Asian Cuisine:Local supply chain maturity for rice, seafood, and tropical produce supports margin stability. Filipino, Chinese, and Japanese sub-formats dominate provincial acceptance in Cebu and Cagayan de Oro.
- Western Cuisine:Imported protein dependency elevates cost volatility. Premium positioning in Bonifacio Global City and Rockwell clusters justifies higher per-check pricing.
- Desserts:Specialized equipment for temperature-controlled preparation suits kiosk and food hall formats.
- Vegan Options:Emerging demand from health-conscious Millennials in Metro Manila drives menu innovation.
Asian Cuisine commands volume leadership; Vegan Options gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila's dense culinary workforce concentration anchors national foodservice capacity, with commissary-trained talent migrating to satellite cities and provincial capitals as chains accelerate rollout velocity.
Metro Manila
Middle-class household formation in Quezon City, Muntinlupa, and Parañaque sustains daily transaction frequency across quick-service and fast-casual formats. The Department of Trade and Industry's ease-of-doing-business reforms compress permitting timelines from months to weeks for new entrants. Makati and Bonifacio Global City business districts anchor premium full-service density through corporate lunch-hour demand and expense-account dining.
Central Luzon
Provincial capital expansion in Angeles City and San Fernando leverages Metro Manila's commissary supply networks for menu consistency at lower real estate costs. Local government units adapt national franchising rules to municipal zoning constraints, creating variable compliance calendars. Subic Bay and Clark Freeport zones concentrate tourism-oriented foodservice with flexible staffing models for seasonal demand spikes.
Calabarzon
Industrial corridor workers in Laguna and Cavite generate sustained lunch-hour demand for value-tier quick-service formats. Department of Labor and Employment wage board schedules accelerate automation investments ahead of mandated increases. Lipa and Santa Rosa community malls anchor weekend family gathering occasions, with dining clusters capturing 35-40 percent of gross leasable area.
Central Visayas
Cebu's underpenetrated full-service density relative to population scale presents turnkey expansion opportunities through community mall formats. Provincial distribution networks face cold-chain infrastructure gaps that constrain fresh ingredient reach. Mandaue and Lapu-Lapu industrial zones support dark kitchen proliferation for delivery-platform virtual brand testing.
Davao Region
Davao City and Cagayan de Oro developments demonstrate behavioral shifts where weekend foot traffic concentrates around dining clusters rather than traditional retail. Municipal sanitation inspection schedules vary across city government units, elevating administrative overhead for multi-unit operators. Certified kitchen equipment technician scarcity limits commercial refrigeration maintenance capacity in provincial labor pools.
Philippines Foodservice Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic conglomerates with captive commissary networks and franchised international operators with standardized global systems. Two strategic archetypes dominate: heritage Filipino brands with backward-integrated supply chains and multinational quick-service chains with drive-thru infrastructure expertise. Competitive moves concentrate on provincial market entry timing and front-of-house automation deployment ahead of wage regulatory pressure.
Within the heritage conglomerate tier, Jollibee Foods Corporation and Max's Group exemplify vertically integrated operational models with in-house commissary production. Among pizza-focused specialists, Shakey's Pizza Asia Ventures and Greenwich Pizza occupy positions anchored in community mall format penetration. The multinational quick-service segment includes McDonald's through its Alliance Global Group franchise partnership and KFC, both representing standardized drive-thru and delivery platform integration archetypes.
| Leading Market Players |
|---|
| Shakey's Pizza Asia Ventures |
| Chowking |
| Jollibee Foods Corporation |
| KFC |
| Greenwich Pizza |
| McDonald's (Alliance Global Group) |
| Starbucks Corporation |
| Fruitas Holdings |
| Max's Group |
| Others |
Value Network & Pricing Analysis
Imported protein feedstocks flow from global livestock markets through Jollibee Foods Corporation's captive commissary network into three distinct price tiers: value-tier quick-service menus absorb cost volatility through volume scale, mid-market fast-casual formats pass through selective ingredient upgrades, and premium full-service operators in Makati and Bonifacio Global City deploy experiential positioning to defend margin.
Pricing Analysis
Bundled meal combinations dominate quick-service transactions while unbundled à la carte pricing anchors full-service checks. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient sourcing tier and location-specific rent burdens. Pricing pressure stems from Department of Labor wage board schedules compressing front-of-house labor pools. Value-tier quick-service customers exhibit highest price sensitivity; corporate expense-account diners in central business districts show lowest.
Supply Chain Analysis
Regional distribution centers in Metro Manila, Central Luzon, and Cebu operate hub-and-spoke patterns feeding provincial quick-service rollouts. Raw material dependencies center on Australian beef, Brazilian poultry, and domestic rice and seafood harvests. Supply chain risk concentrates in single-source cold-chain logistics gaps reaching Visayas and Mindanao. Distribution runs through vertically integrated commissary networks for heritage conglomerates and third-party logistics platforms for delivery-native virtual brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Philippine foodservice rests on automation capex cycles front-loading self-service kiosk deployment ahead of mandated wage adjustments, alongside premium-tier experiential positioning in underpenetrated provincial capitals.
For Market Incumbents: Deepen backward integration into captive protein processing to buffer imported feedstock volatility threatening value-tier margin stability. Accelerate kitchen display system deployment with predictive prep algorithms across provincial commissary-fed networks. Counter emerging cloud kitchen virtual brands through exclusive tenancy negotiations with community mall developers anchoring 35-40 percent foodservice gross leasable area. For New Entrants and Emerging Players: Begin with dark kitchen infrastructure in Mandaue and Lapu-Lapu industrial zones, leveraging delivery-platform API integration to test virtual brands without storefront capex. White-space concentration sits in Cebu's underpenetrated full-service density relative to population scale. Go-to-market angle targets community mall turnkey expansion templates with localized Asian cuisine menu engineering. For Investors and Strategic Acquirers: Consolidation pressure builds where certified kitchen equipment technician scarcity limits commercial refrigeration maintenance capacity in provincial labor pools. Long-term viability favors vertically integrated domestic conglomerates with captive commissary networks over pure-play delivery aggregators lacking supply chain control. Signal to watch: Department of Trade and Industry's ease-of-doing-business reform adoption rates across city government units as rollout velocity inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Network Expansion | Jollibee Foods Corporation's vertical integration sustains pricing power across provincial rollouts. |
| Front-of-House Automation Deployment | Self-service kiosk investment ahead of Department of Labor wage board schedules defends labor margin pools. |
| Community Mall Format Penetration | Shakey's Pizza Asia Ventures anchors expansion in retail formats dominating secondary city foot traffic. |
| Delivery Platform API Integration | Third-party aggregator embedding enables full-service off-premise revenue without proprietary fleet investment. |
| Dark Kitchen Infrastructure Buildout | Virtual brand proliferation in Mandaluyong and Pasig eliminates dine-in real estate requirements for rapid menu testing. |
Research Methodology
Direct dialogue with quick-service chain operations directors, full-service restaurant group executives, community mall development managers, third-party delivery platform integration specialists, and Department of Trade and Industry regional officers grounded qualitative findings. Secondary validation drew from SEC filings of listed foodservice operators, DTI ease-of-doing-business metrics, Department of Labor wage board schedules, and municipal zoning records. Bottom-up outlet counts triangulated against top-down consumer expenditure surveys.
Bottom-up modeling tracked outlet expansion velocity and per-location revenue assumptions across the projection horizon. Segmentation dimensions spanned product format tier, service model channel, customer demographic cohort, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy reform acceleration and infrastructure investment timing. Industry-specific inputs incorporated cold-chain logistics maturity indices and provincial household formation rates.
Several conditions sit outside the modeled scope, including extreme climate events disrupting domestic agricultural supply, geopolitical trade restrictions on imported protein, and unforeseen regulatory reversals on franchising rules. Forecasts reflect documented assumptions around DTI reform implementation consistency and wage board schedule predictability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Philippines Quick Service Restaurants Market
Food Service
Self-Heating Hot Pot Market
Food Service
Pizza Foodservice Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
Steam Tables and Food Well Market
Food Service
Commercial Griddle Market
Food Service
India Foodservice Market
Food Service
Rotisseries Market
Food Service
Smokeless Grill Market
Food Service
Vietnam Food Service Market
Food Service
Ice Cream Carts Market
Food Service
Street Vendors Market
Food Service
India Quick Service Restaurant Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Inflight Catering Market
Food Service
Electric Tiffin Market