
 United Kingdom Quick Service Restaurant Market | 2026-2036
United Kingdom Quick Service Restaurant Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Quick Service Restaurant Market Insights
Mobile-first ordering infrastructure is narrowing the operational gap between legacy chains and digital-native competitors. McDonald's Corporation leverages its proprietary app ecosystem and drive-thru automation to sustain throughput leadership across high-traffic UK locations. Greggs Plc anchors its expansion in transport hubs and retail parks, competing on price-positioned hot food accessibility. Domino's Pizza Group PLC differentiates through predictive delivery algorithms and localized kitchen networks that control last-mile execution.
A quick service restaurant operates as a limited-service food establishment characterized by standardized menus, speed of service under three minutes at the counter, and production systems built on batch-prepared components with final assembly to order. The sector serves mass-market consumers seeking convenience, predictability, and price transparency in meal occasions. Burgers and chicken segments dominate transaction volume in the UK, with chicken posting the fastest structural growth as operators expand spicy and boneless portfolios to capture younger demographics. The value price tier absorbs the largest share of traffic, though premium positioning around provenance and dietary customization commands disproportionate margin contribution per check.
The Food Standards Agency mandates calorie disclosure on menus, while the Competition and Markets Authority scrutinizes delivery platform fees that reshape franchisee economics. Local authority environmental health inspections and forthcoming Extended Producer Responsibility packaging rules compel capital redeployment toward sustainable materials and waste-stream redesign. Stakeholders must weigh regulatory compliance costs against the speed advantage of digital integration as the defining axis of competitive durability.
Market Dynamics
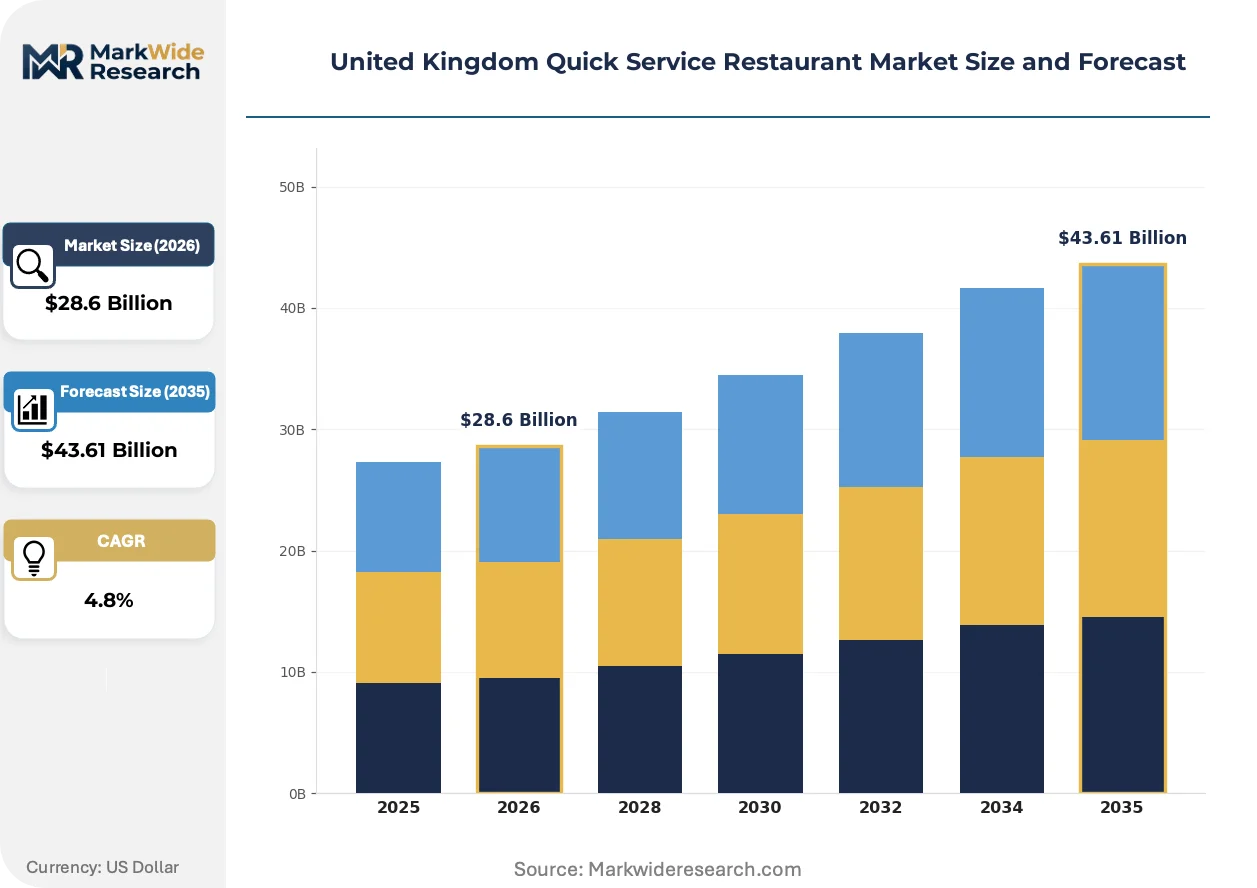
Mobile-first ordering infrastructure is compressing the operational gap between legacy chains and digital-native competitors across UK quick service restaurants. The Food Standards Agency's calorie disclosure mandates and Extended Producer Responsibility packaging rules are forcing simultaneous compliance investments that reshape capital allocation priorities.
Growth Catalysts
- Delivery platform density:Urban professionals in Greater London and the South East corridor now route the majority of meal occasions through aggregator apps, expanding addressable demand beyond physical footprint constraints.
- FSA allergen transparency mandates:Standardized disclosure protocols reduce consumer friction and liability exposure, accelerating trial among dietary-restricted households previously excluded from mass-market QSR.
- Spicy chicken portfolio expansion:Boneless and heat-forward formulations capture younger demographics, driving check frequency in a segment already posting structural volume growth.
Market Restraints
- Delivery platform fee structures:The Competition and Markets Authority scrutiny of aggregator commissions compresses franchisee margins, particularly for independent operators lacking volume leverage.
- Protein input volatility:Chicken supply concentration in specific processing geographies exposes operators to price shocks that resist menu-price pass-through in the value tier.
- Extended Producer Responsibility compliance:Forthcoming packaging rules mandate capital redeployment toward sustainable materials and waste-stream redesign before cost curves flatten.
Strategic Opportunities
- Transport hub penetration:Retail parks and railway station footprints remain underpenetrated relative to urban core saturation, offering captive commuter traffic with limited nearby competition.
- Drive-thru automation convergence:Computer vision and license-plate recognition technologies reduce labor dependency while sustaining throughput during peak demand windows.
- Predictive kitchen networks:Localized production nodes with algorithmic demand forecasting compress last-mile delivery times, opening suburban markets previously outside viable service radii.
Industry Challenges
- Environmental health inspection variability:Local authority enforcement inconsistency creates compliance uncertainty across multi-site operators, requiring redundant quality systems.
- Legacy POS integration friction:Mobile ordering platforms must interface with decades-old franchisee systems, slowing unified data architecture deployment and loyalty program coherence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Quick Service Restaurant Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drive-Thru, Delivery, Dine-In, Takeaway Product Type: Burgers, Chicken, Pizza, Sandwiches Price Tier: Budget, Mid-Range, Premium, Value Customer Type: Families, Students, Professionals, Tourists |
| Companies Covered | McDonald's Corporation, Greggs Plc, Domino's Pizza Group PLC, KFC, Subway, Burger King, Pizza Hut, Costa Coffee, Pret A Manger, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Quick Service Restaurant Market Trends and Innovations
Digital ordering interfaces and automated production systems are compressing service-delivery timelines while regulatory pressure on transparency and sustainability intensifies operator investment requirements. These forces are reconfiguring competitive durability around speed-to-compliance rather than scale alone.
Artificial intelligence-powered demand forecasting is collapsing the latency between order placement and kitchen preparation. Mid-market chains operating localized kitchen networks deploy these systems to pre-position ingredients and labor before peak windows materialize. The structural consequence is collapsing inventory waste rates and labor idle time, compressing unit economics toward digital-native benchmarks.
The Food Standards Agency mandates calorie disclosure on menus and digital interfaces, with enforcement expanding through local authority inspection regimes. This industrial consequence pressures smaller operators to invest in nutritional analysis infrastructure previously unnecessary at their scale. The value-price tier absorbs disproportionate compliance burden, accelerating consolidation as independent outlets exit rather than absorb fixed-cost increments.
Subscription-based meal plans and app-native loyalty currencies are displacing traditional promotional calendars among urban professional segments. Aggregator platforms and proprietary chain apps compete to own the recurring-revenue relationship, replacing broadcast discounting with personalized offer algorithms. This pattern concentrates most visibly in Greater London, where commute-integrated ordering now dominates breakfast and lunch occasions.
United Kingdom Quick Service Restaurant Market Segmentation
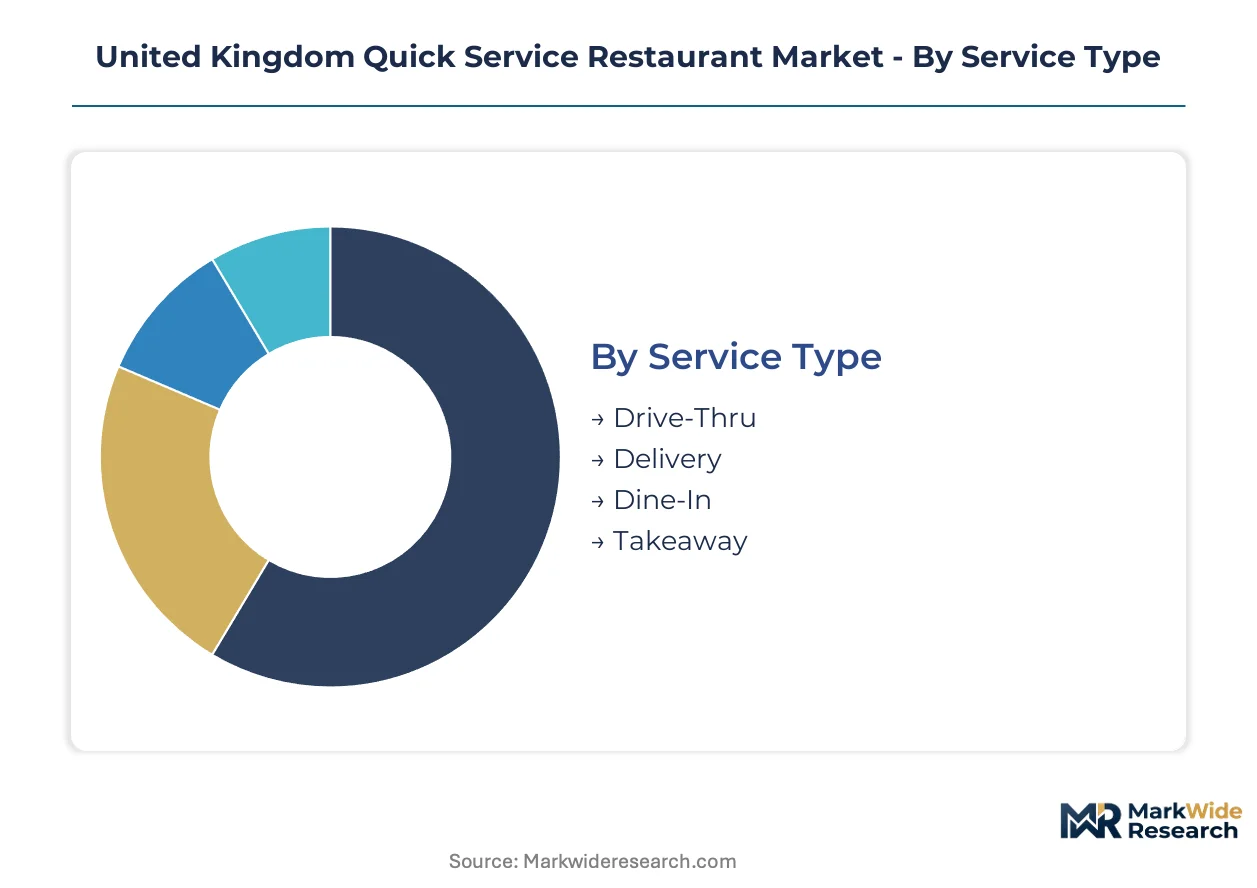
Segmentation in the United Kingdom Quick Service Restaurant Market reveals how distinct operational models and consumer occasions command divergent capital allocation priorities. Operators must align format investments with traffic patterns across commuter corridors, residential suburbs, and transport interchanges where demand density varies sharply.
Service Type:
After-sales intensity in UK quick service restaurants concentrates on order accuracy recovery and delivery exception handling, with digital-native formats demanding more sophisticated customer service infrastructure than legacy dine-in estates.
- Drive-Thru:Purpose-built lane configurations with dual-menu boards and payment stations process vehicles in under three minutes. Demand clusters along A-road corridors and retail park peripheries in Greater London's outer boroughs, where car dependency among families sustains throughput. Drive-thru automation investments are compressing labor costs while maintaining speed benchmarks during peak morning and evening windows.
- Delivery:Kitchen-to-door logistics managed through aggregator platforms or proprietary rider networks. Urban professionals in Manchester and Birmingham city centers now route the majority of evening meal occasions through these channels, expanding addressable demand beyond physical footprint constraints. The Food Standards Agency's allergen disclosure mandates add compliance complexity to menu digitization.
- Dine-In:Limited seating formats with counter service and self-clear protocols. High-street locations in town centers retain relevance for family occasions and elderly consumers less adapted to mobile ordering interfaces.
- Takeaway:Walk-up counter service with minimal dwell time, dominant in transport hubs and railway stations. Greggs Plc has anchored expansion in this format across the South East corridor.
By volume, Takeaway leads across UK transaction counts. By growth pace, Delivery is ahead.
Product Type:
Menu architecture in the United Kingdom Quick Service Restaurant Market stratifies around protein center-of-plate decisions that determine supply chain configuration and kitchen equipment investment.
- Burgers:Beef and plant-based patty formats with standardized bun specifications and condiment protocols. The value tier absorbs the largest share of traffic, though premium positioning around provenance commands disproportionate margin contribution per check.
- Chicken:Bone-in, boneless, and spicy heat-forward formulations. Younger demographics in Leeds and Bristol drive check frequency in this segment, which is expanding most quickly as operators broaden portfolio depth.
- Pizza:Hand-stretched or conveyor-baked formats with regional topping variations. Localized kitchen networks in suburban markets compress last-mile delivery times for this occasion-driven category.
- Sandwiches:Cold and hot-filled formats with shorter holding windows. Transport hub penetration favors this segment for captive commuter traffic with limited nearby competition.
Chicken gains share fastest among protein categories, while Burgers retain the largest revenue base.
Price Tier:
Consumer wallet allocation in UK quick service restaurants maps directly to occasion frequency and trade-up willingness across demographic cohorts.
- Budget:Entry-level price points with minimized ingredient cost and limited customization. Student populations in university cities sustain volume, though margin compression limits expansion appetite.
- Mid-Range:Balanced quality-positioning with modest customization options. The broadest addressable base, capturing family trade-up occasions and professional lunch routines.
- Premium:Provenance-marketed ingredients and dietary customization at elevated price points. Disproportionate margin contribution per check justifies higher occupancy costs in central London and affluent suburban catchments.
- Value:Promotional bundling and loyalty-program-driven discounting. The largest traffic absorber, though Extended Producer Responsibility compliance costs are accelerating independent operator exits from this tier.
Value tier commands transaction volume leadership, while Premium climbs the fastest on revenue-per-unit expansion.
Customer Type:
Occasion-based targeting in the United Kingdom Quick Service Restaurant Market requires format and menu adaptation to divergent decision-speed and group-size requirements.
- Families:Multi-portion occasions with child-focused menu options and drive-thru preference for convenience. Weekend demand concentrates in retail park locations with parking availability.
- Students:Price-sensitive, high-frequency users with mobile-first ordering behavior. University town operators compete on app-native loyalty currencies and late-night service windows.
- Professionals:Speed-prioritized breakfast and lunch occasions integrated with commute patterns. Greater London's transport network shapes demand geography, with grab-and-go formats dominating station concourses.
- Tourists:Brand-familiarity-driven selection with limited price sensitivity. Central London and major transport terminals concentrate this occasional but high-check segment.
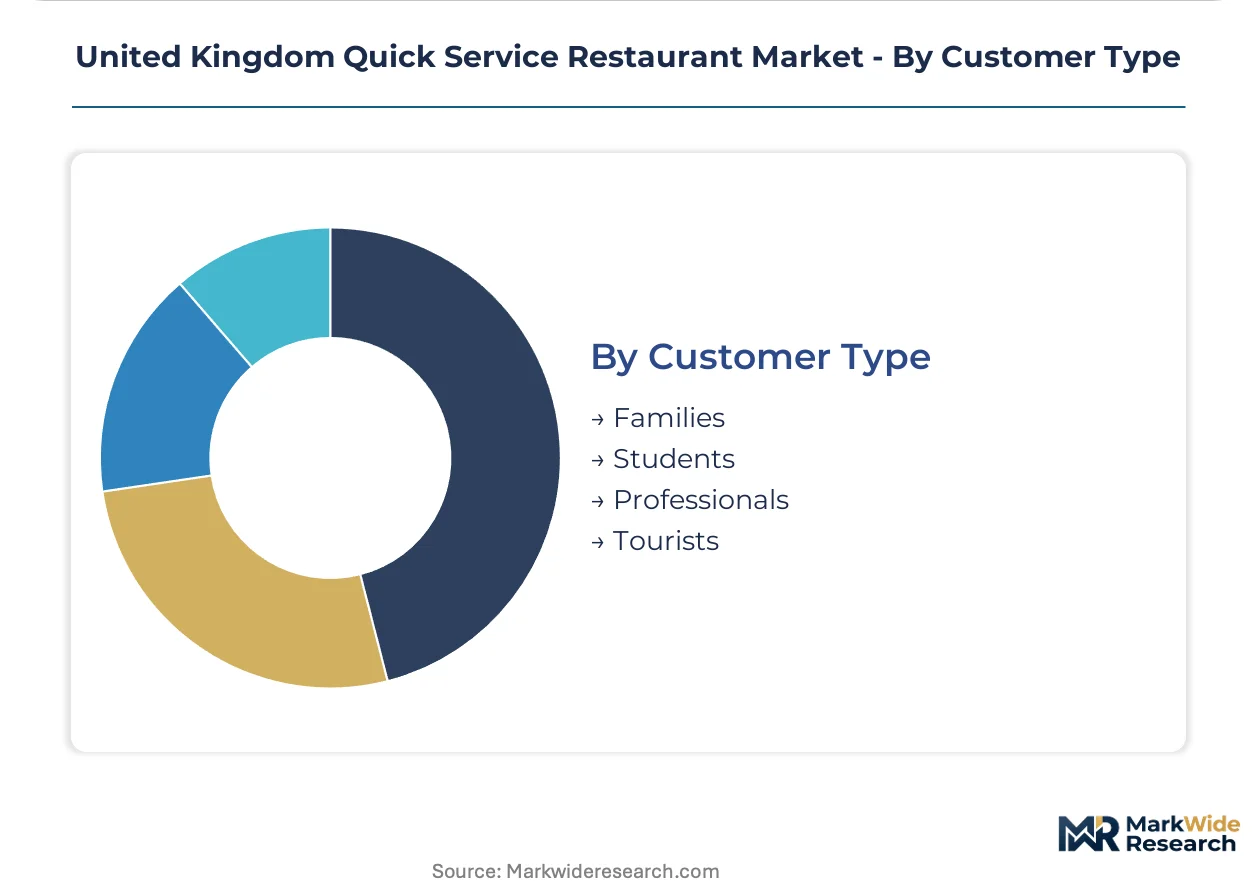
Professionals generate the highest frequency, while Tourists produce the steepest per-check expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom imports foodservice equipment and packaging materials from Germany, the Netherlands, and Italy, with Greater London acting as the primary distribution hub for onward supply to regional markets.
Greater London and South East
Urban professionals drive breakfast and lunch occasion density through commute-integrated mobile ordering. The Food Standards Agency enforces calorie disclosure mandates across digital and physical menu interfaces. Canary Wharf and the City of London concentrate premium-tier operators targeting high-frequency professional traffic with grab-and-go formats.
Midlands
Transport hub penetration along the M1 and M6 corridors sustains drive-thru and retail park expansion. Local authority environmental health inspections create compliance variability across Birmingham, Leicester, and Nottingham metropolitan areas. The region's logistics infrastructure supports distribution network optimization for chains operating national kitchen networks.
North England
Student populations in Manchester, Leeds, and Liverpool sustain value-tier volume through price-sensitive, high-frequency usage patterns. Extended Producer Responsibility packaging rules compel capital redeployment toward sustainable materials before cost curves flatten. Sheffield and Newcastle retain dine-in relevance for family occasions less adapted to mobile-first interfaces.
Scotland
Edinburgh and Glasgow city centers concentrate delivery platform density among young professional demographics. The Scottish Government's public health regulations on high-fat, salt, and sugar products add compliance complexity beyond England-wide FSA mandates. Aberdeen's energy sector employment sustains premium-tier check averages in workplace-adjacent locations.
Wales
Cardiff and Swansea retail parks anchor drive-thru development along A-road corridors with limited nearby competition. Welsh Government procurement guidelines for public sector food contracts influence operator nutrition disclosure investments. The M4 corridor connects South Wales to Bristol and London distribution networks, compressing supply lead times.
United Kingdom Quick Service Restaurant Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: multinational chains with proprietary digital infrastructure, domestic specialists with transport hub penetration, and aggregator-dependent independents facing margin compression. Strategic archetypes include app-native throughput leaders, price-positioned convenience operators, and algorithmic delivery optimizers. Dominant competitive moves encompass drive-thru automation deployment and predictive kitchen network expansion.
Among US-based multinational operators, McDonald's Corporation exemplifies the throughput-leader archetype through drive-thru automation and proprietary app ecosystems. Greggs Plc, a UK public limited company, anchors the price-positioned convenience tier with transport hub and retail park concentration. Domino's Pizza Group PLC, another UK plc, occupies the algorithmic delivery optimization position through localized kitchen networks and predictive demand forecasting.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Greggs Plc |
| Domino's Pizza Group PLC |
| KFC |
| Subway |
| Burger King |
| Pizza Hut |
| Costa Coffee |
| Pret A Manger |
| Others |
Pricing and Supply Chain Analysis
The M6 corridor freight lanes connecting Birmingham distribution hubs to Greater London outlets transmit cost volatility directly into price differentiation across operator tiers. Poultry processing concentration in the East Midlands and packaging material sourcing from German suppliers create asymmetric margin pressure that chains absorb through tiered menu architecture rather than uniform pass-through.
Pricing Analysis
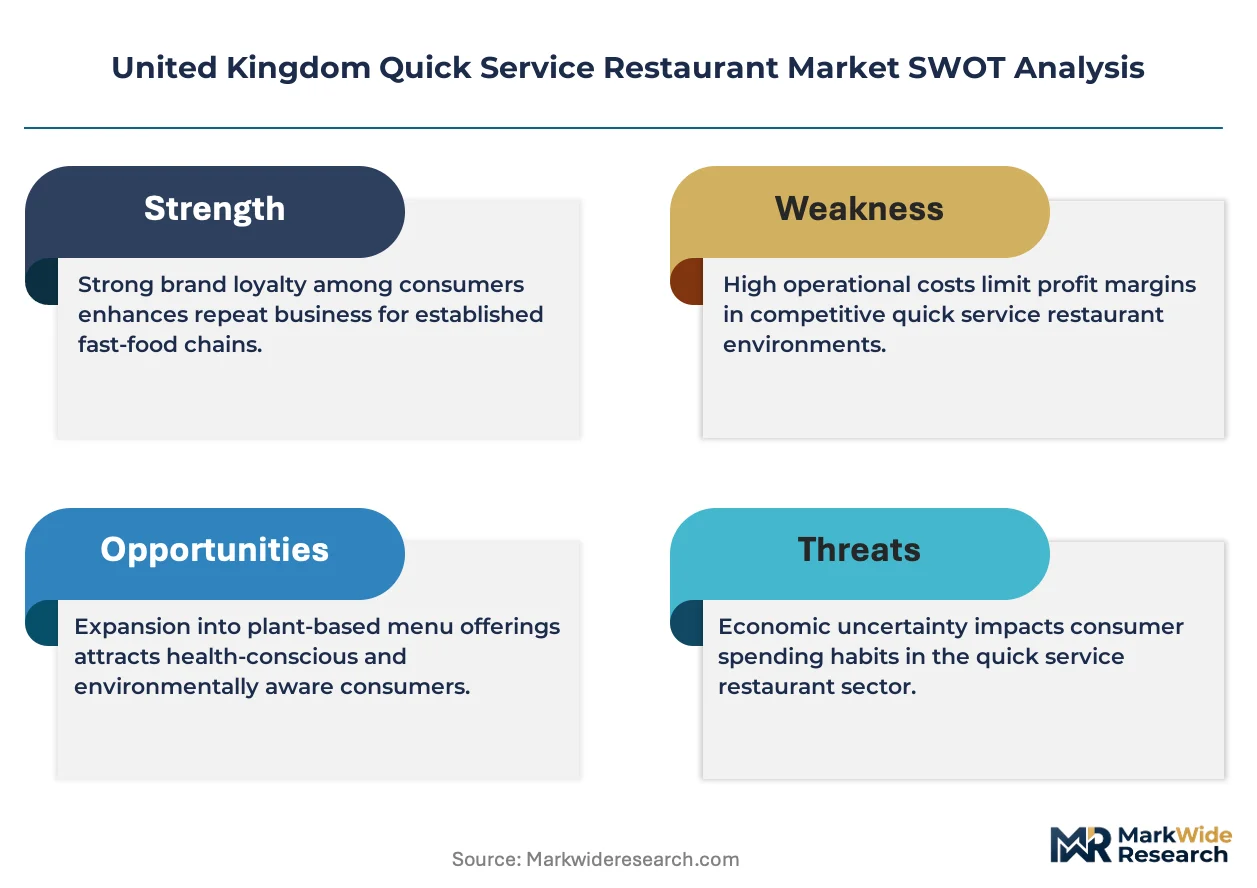
Legacy point-of-sale infrastructure versus AI-native demand forecasting systems versus forthcoming computer-vision drive-thru deployments stratifies pricing power across technology generations. Three-tier pricing structure across premium, standard, and economy levels captures divergent willingness-to-pay, with provenance-marketed ingredients and dietary customization commanding margin premiums while promotional bundling absorbs traffic volume. Cost compression in the value tier intensifies because Extended Producer Responsibility compliance adds fixed-cost increments that independents cannot distribute across scale. Students and price-sensitive commuters exhibit highest price sensitivity; tourists and central London professionals demonstrate lowest.
Supply Chain Analysis
Upstream feedstock for chicken processing draws from concentrated operations in Brazil, Thailand, and domestic East Midlands facilities. Wheat flour for bakery formats and specialty oils for frying systems rest on agricultural commodity markets with limited near-term hedging instruments. Single-source vulnerability in poultry supply exposes operators to input shocks that resist menu-price pass-through in competitive corridors. Distribution runs through regional cold-chain hubs in Milton Keynes and Coventry before last-mile deployment to franchise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Quick Service Restaurant Market represents high-growth disruption as mobile-first ordering infrastructure and FSA calorie disclosure mandates simultaneously compress operational timelines and expand compliance investment requirements.
For Market Incumbents: Pre-empt margin erosion from delivery platform fee compression by deploying proprietary app ecosystems with integrated loyalty currencies that reduce aggregator dependency. Accelerate drive-thru automation capital deployment to sustain throughput leadership during peak demand windows. Vertical integration into localized kitchen networks defends last-mile execution against algorithmic delivery optimizers.
For New Entrants and Emerging Players: Transport hub penetration in underpenetrated railway stations and retail parks along the M1 and M6 corridors represents the most penetrable entry point for capturing captive commuter traffic with limited nearby competition. Suburban markets outside viable delivery radii of urban kitchen networks offer white-space expansion for predictive production node deployment. Go-to-market execution should anchor in algorithmic demand forecasting partnerships with existing logistics providers rather than greenfield infrastructure buildout.
For Investors and Strategic Acquirers: Domestic specialists with transport hub real estate portfolios and established local authority compliance systems present attractive acquisition targets for multinational chains seeking format diversification. Long-term viability over the coming decade hinges on regulatory compliance speed rather than scale alone. Monitor Food Standards Agency enforcement expansion patterns and Extended Producer Responsibility implementation timelines as inflection indicators for capital redeployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Drive-Thru Automation Deployment | Computer vision and license-plate recognition reduce labor dependency while sustaining three-minute throughput benchmarks. |
| Proprietary App Ecosystem Development | Integrated ordering and loyalty platforms displace aggregator dependency and capture recurring-revenue relationships. |
| Predictive Kitchen Network Expansion | Localized production nodes with algorithmic demand forecasting compress last-mile delivery times into suburban markets. |
| Extended Producer Responsibility Compliance | Sustainable packaging material transition ahead of regulatory deadlines defends against local authority enforcement actions. |
| Transport Hub Real Estate Acquisition | Railway station and retail park footprints capture captive commuter traffic with limited nearby competitor presence. |
Research Methodology
Operator-level perspectives from franchise operations directors, supply chain procurement leads, digital platform managers, and local authority environmental health officers anchored the qualitative base. Primary interview insights combined with secondary validation from Food Standards Agency disclosure filings, Competition and Markets Authority delivery platform reviews, UK trade customs data, and operator SEC filings. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates across segmentation dimensions.
Scenario-bracketing around regulatory implementation timelines and technology adoption curves structured the analytical framework across the projection horizon. Segmentation modeling incorporated service type, product category, price tier, and customer occasion dimensions with regional demand density weighting. CAGRs derived from historical trajectory analysis adjusted for structural shift inflection points including mobile ordering penetration rates and compliance cost absorption capacity.
Practitioners should monitor Food Standards Agency enforcement expansion, Extended Producer Responsibility implementation delays, and delivery platform commission renegotiations for early signals requiring forecast revision. Cross-checking against UK Hospitality sector employment data and retail footfall indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Gas Fryers Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Commercial Tableware Services Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
Pasteurized Eggs Market
Food Service
Online Grocery Market
Food Service
India Inflight Catering Market
Food Service
Pizza Oven Market
Food Service
Food & Beverage in Asia Market
Food Service
Train Catering Service Market
Food Service
Food Service Dairy Products Market
Food Service
GCC Online Grocery Market
Food Service
Canada Food Service Market
Food Service
South Africa Fast Food Market
Food Service
Global Food Platform-To-Consumer Delivery Market