
 UK Organic Food Market | 2026-2036
UK Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
UK Organic Food Market Insights
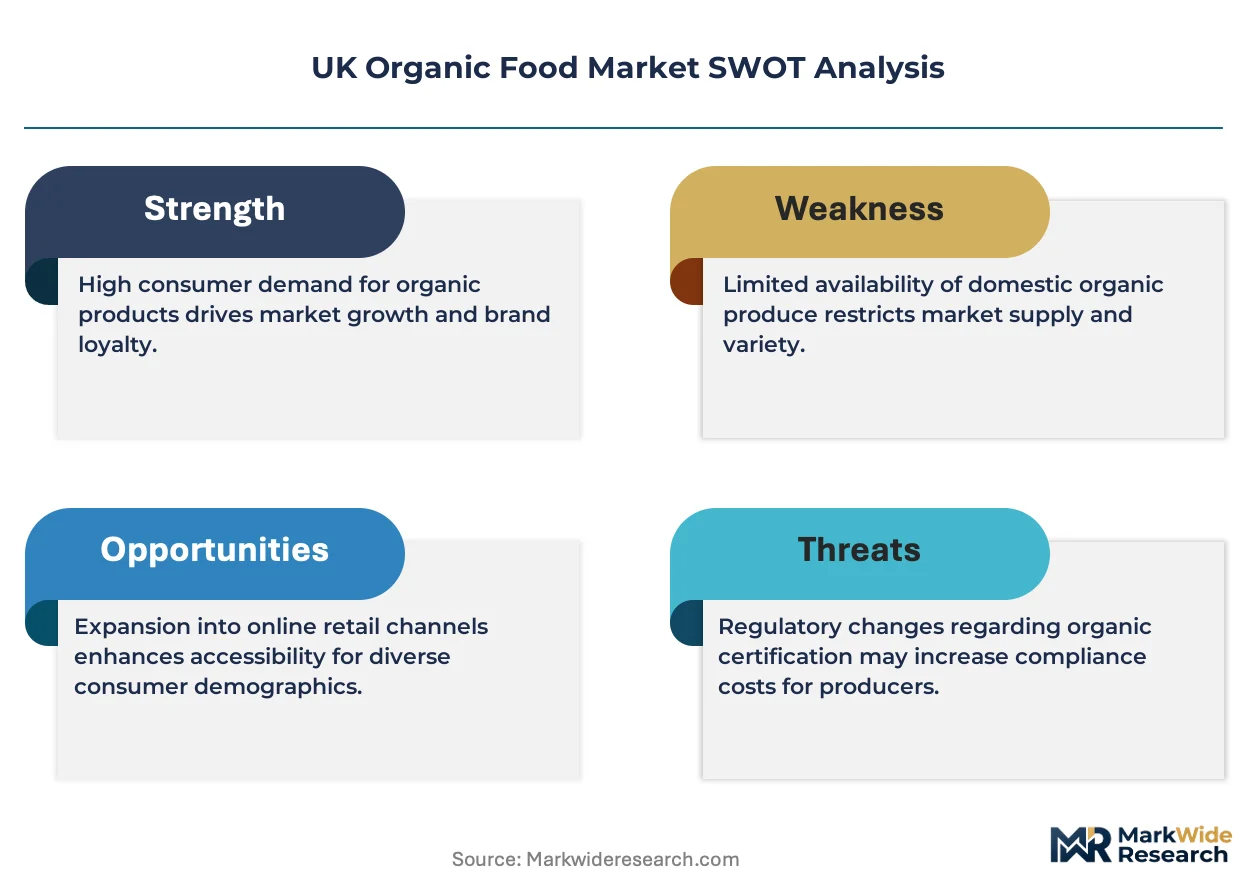
England's organic farmland conversion is narrowing the historical supply gap that forced retailers to rely on continental imports. Sainsbury's leverages its in-house organic label development to control shelf positioning and margin capture across store formats. Tesco anchors volume through aggressive price matching on staple categories such as milk and carrots. Waitrose differentiates via premium provenance storytelling and tighter farmer partnership terms.
Organic food denotes crops and livestock raised without synthetic pesticides, genetically modified organisms, or routine antibiotic use, with production governed by accredited certification standards such as Soil Association criteria mandating minimum conversion periods and traceability protocols; the category serves consumer demand for reduced chemical exposure and environmental stewardship alongside nutritional quality claims. Fruits and vegetables occupy the dominant value share given high purchase frequency and visible certification labeling at point of sale. Online retailers represent the fastest-expanding distribution channel as subscription models and rapid delivery infrastructure mature. Supermarkets retain the deepest margin pools through private-label organic ranges and slotting fee structures.
Soil Association certification functions as the primary quality signal for UK consumers, while DEFRA administers farm-level compliance through retained EU organic regulations post-Brexit. The Competition and Markets Authority monitors greenwashing claims, tightening enforcement against uncertified organic labeling. Stakeholders must track how post-Brexit trade agreements reshape import certification reciprocity and domestic producer subsidy access.
Market Dynamics
DEFRA's Environmental Land Management scheme is redirecting farm subsidies toward ecological practices, accelerating domestic supply conversion and narrowing the historical reliance on continental imports that has structured UK organic retail procurement for decades.
Growth Catalysts
- DEFRA subsidy reallocation:The Environmental Land Management scheme redirects payments toward soil health and biodiversity outcomes, incentivizing conventional farms to begin conversion periods.
- Soil Association certification expansion:Rising consumer recognition of this quality signal drives retailer shelf-space allocation and private-label development across multiple store formats.
- London-South East demand concentration:Disposable income density and specialty retail cluster proximity in these regions sustain premium pricing power and trial rates for new organic SKUs.
Market Restraints
- Conversion period economics:The mandatory two-year transition to Soil Association certification imposes revenue loss on converting farms before premium pricing access begins.
- Continental import dependency:Domestic production gaps in fresh produce categories force retailers to maintain complex cross-channel supply relationships with EU growers.
- Input cost volatility:Organic feed and approved fertilizer prices fluctuate with conventional agricultural commodity cycles, compressing farm-level margins unpredictably.
Strategic Opportunities
- Online subscription channels:Rapid delivery infrastructure maturity enables direct-to-consumer models that bypass supermarket slotting fee structures entirely.
- Scottish and Welsh supply expansion:Underdeveloped organic acreage in these regions offers land availability and lower rental costs for scaling domestic production.
- Post-Brexit trade agreement leverage:Reciprocal certification recognition in new bilateral deals could unlock export markets for UK-certified processed organic goods.
Industry Challenges
- Competent inspector scarcity:DEFRA and accredited body capacity constraints lengthen certification timelines and create compliance backlogs for converting operations.
- Legacy IT traceability gaps:Many small-scale producers lack integrated farm-management software capable of generating the audit trails required for export documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Organic Food Market |
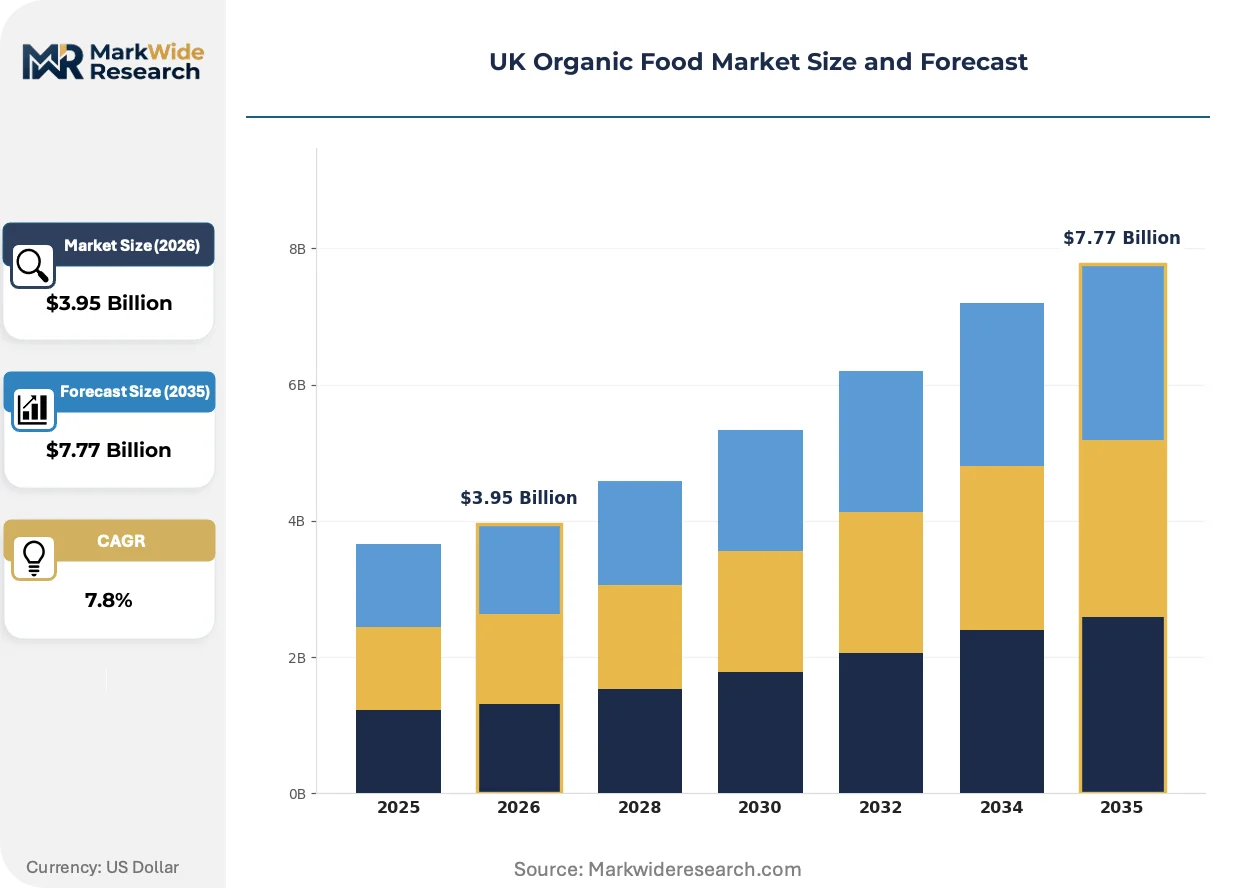
| Market Size in 2026 | $3.95 Billion |
| Market Size in 2035 | $7.77 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits & Vegetables, Dairy Products, Meat & Poultry, Beverages, Grains & Cereals Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Farmers Markets, Foodservice Outlets Certification: Soil Association, Organic Farmers & Growers, EU Organic Logo, Demeter, BioGro Consumer Type: Health-Conscious Adults, Eco-Friendly Buyers, Families, Millennials |
| Companies Covered | Sainsbury's, Tesco, Waitrose, Ocado, Lidl, Marks & Spencer, Aldi, Yeo Valley Farms, Riverford Organic Farmers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Organic Food Market Trends and Innovations
Digital infrastructure and regulatory tightening are compressing traditional supply chain layers while reshaping how authenticity is verified and communicated to end consumers.
Blockchain-enabled provenance tracking is collapsing the information asymmetry between farm gate and retail shelf. Mid-sized supermarket chains are piloting these systems for high-value meat and dairy SKUs. The technology is collapsing audit costs and enabling real-time compliance verification that reduces certification dispute resolution timeframes.
DEFRA's retained EU organic regulations post-Brexit are tightening enforcement scope through enhanced cross-border inspection protocols. This regulatory consolidation is forcing import brokers to maintain dual documentation standards for EU and UK certification equivalence. Fresh produce importers face the steepest compliance burden as seasonal sourcing patterns require rapid certification verification.
Subscription-based replenishment models are displacing traditional weekly supermarket trips among urban professional households. Digital-native retailers capture this behavioral shift through algorithmic basket curation and flexible delivery windows. London and the South East exhibit the highest penetration of these services, with expansion into secondary cities contingent on cold-chain infrastructure density.
UK Organic Food Market Segmentation
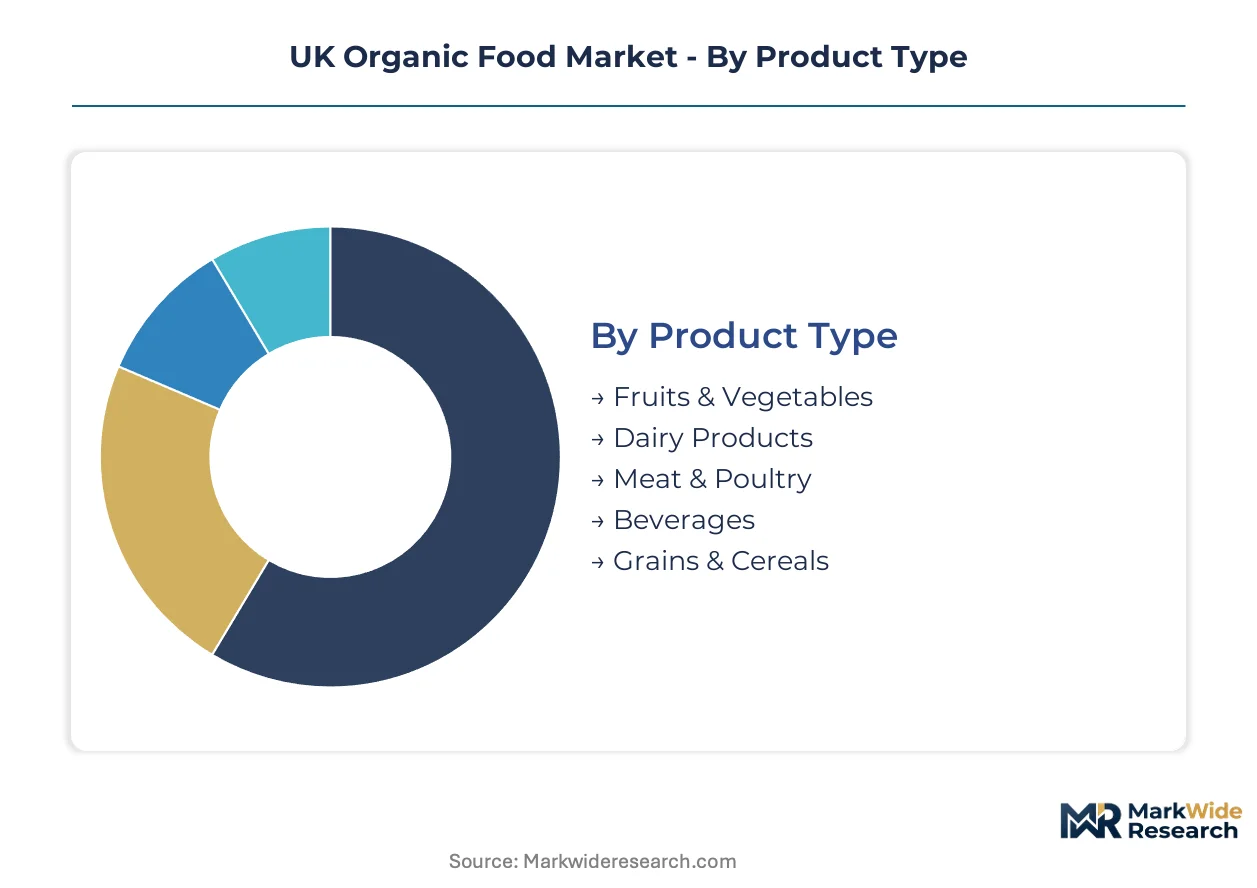
Segmentation reveals how certification tiers, channel economics, and consumer psychographics fragment purchasing power across the UK organic landscape. Distinct margin profiles attach to each slice, shaping where retailers and producers allocate capital.
Product Type:
Mature categories anchor weekly basket spend while emerging segments capture premium pricing through supply scarcity.
- Fruits & Vegetables:High-frequency purchase items with visible Soil Association labeling at point of sale. London and South East supermarkets move the deepest volume through promotional placement near store entrances.
- Dairy Products:Milk, yogurt, and cheese SKUs carry strong private-label penetration. Tesco's price-matching on organic milk compresses branded margins while expanding household penetration.
- Meat & Poultry:Premium provenance storytelling supports elevated price points. Waitrose leverages tighter farmer partnership terms to secure exclusive supply windows.
- Beverages:Organic juice and plant-based milk alternatives gain shelf space in urban specialty retail clusters. Health-conscious adults drive trial through subscription box inclusion.
- Grains & Cereals:Breakfast and baking staples face import dependency for domestic supply gaps. DEFRA subsidy reallocation targets arable conversion to narrow this reliance.
Fruits & Vegetables retains volume leadership; Grains & Cereals holds the steepest expansion curve as domestic acreage conversion accelerates.
Distribution Channel:
Cost tier stratification separates capital-intensive infrastructure plays from low-asset direct models.
- Supermarkets:Sainsbury's and Tesco dominate through private-label organic ranges and slotting fee structures. Deep margin pools fund aggressive price matching on staple categories.
- Online Retailers:Algorithmic basket curation and flexible delivery windows capture urban professional households. London penetration rates exceed secondary cities contingent on cold-chain density.
- Specialty Stores:Independent retailers concentrate in affluent postcode clusters. Premium positioning supports full-margin pricing absent competitive pressure from national chains.
- Farmers Markets:Direct producer-consumer relationships bypass certification documentation layers. Seasonal availability constraints limit year-round household reliance.
- Foodservice Outlets:Restaurants and catering operations source through wholesale intermediaries. Menu labeling requirements tighten under Competition and Markets Authority greenwashing enforcement.
Supermarkets command the deepest revenue pool; Online Retailers are climbing the fastest as subscription infrastructure matures.
Certification:
Margin structure attaches to recognition intensity and compliance burden differential.
- Soil Association:The dominant quality signal for UK consumers with strict conversion periods and traceability mandates. Retailer shelf-space allocation follows this accreditation hierarchy.
- Organic Farmers & Growers:Alternative UK-accredited body with streamlined inspection protocols for smaller operations. Scottish and Welsh producers leverage this pathway to accelerate market entry.
- EU Organic Logo:Retained regulatory equivalence post-Brexit supports continental import flows. Fresh produce importers maintain dual documentation standards for cross-channel verification.
- Demeter:Biodynamic certification commands ultra-premium positioning in specialty retail. Limited acreage and labor-intensive practices constrain volume scalability.
- BioGro:New Zealand-based accreditation supports southern hemisphere import relationships. Seasonal counter-cyclical sourcing fills domestic production gaps.
Soil Association retains volume leadership; Online Retailers are expanding most quickly through algorithmic curation models.
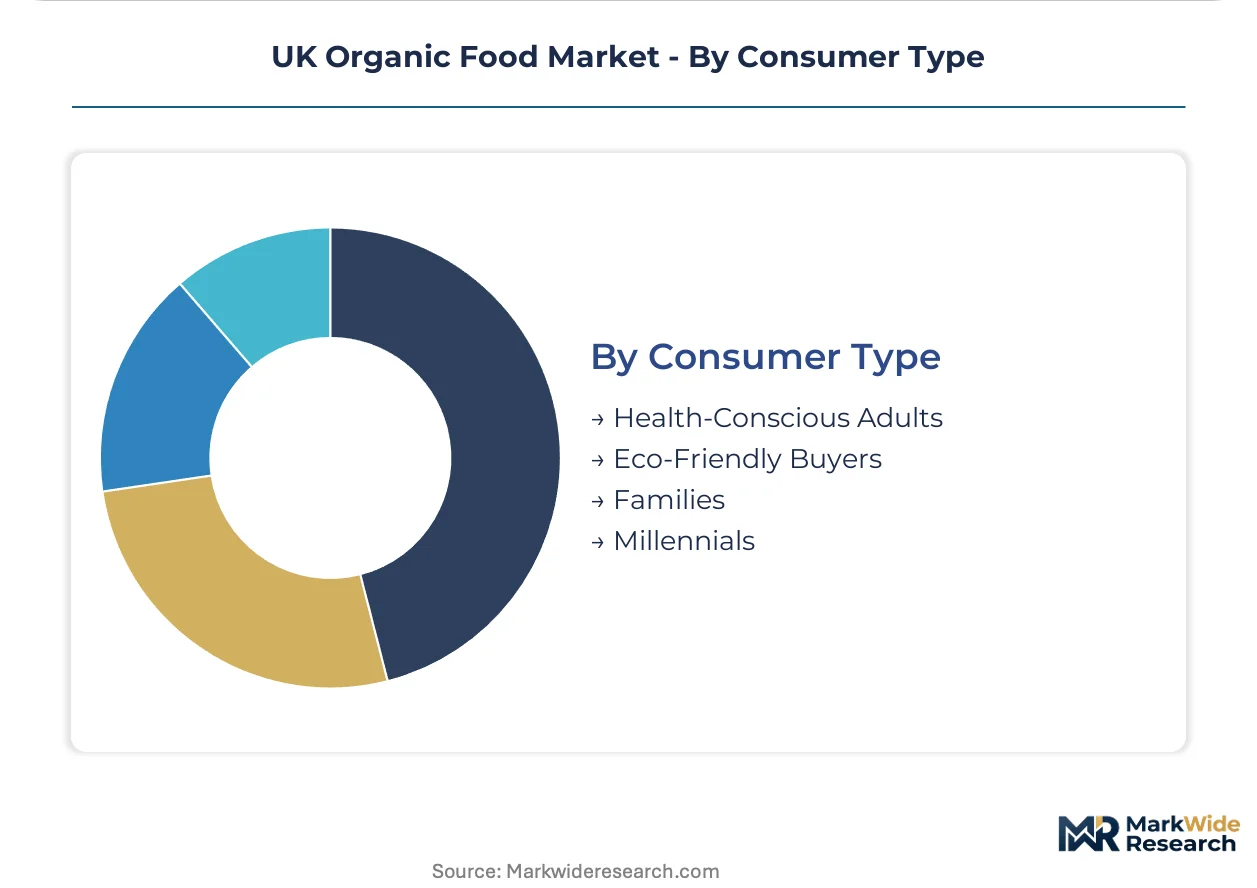
Consumer Type:
Application focus separates health-motivated purchasers from values-driven buyers with distinct media consumption and channel preferences.
- Health-Conscious Adults:Primary decision-makers seeking reduced chemical exposure through certified produce. Weekly grocery spend shifts toward organic SKUs as disposable income permits.
- Eco-Friendly Buyers:Environmental stewardship motivates premium tolerance and brand loyalty. DEFRA's Environmental Land Management scheme messaging resonates with this cohort.
- Families:Child-focused nutrition concerns drive dairy and produce category concentration. Subscription models reduce shopping friction for time-constrained households.
- Millennials:Digital-native purchasing patterns favor rapid delivery and provenance transparency. Blockchain-enabled tracking pilots align with this segment's verification expectations.
Health-Conscious Adults anchor current volume; Millennials are gaining share fastest through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between affluent urban corridors and peripheral agricultural zones. London households allocate disproportionate weekly spend to certified organic produce through subscription channels, while northern regions exhibit stronger price elasticity and slower conversion from conventional staples.
London and the South East
Disposable income density drives the deepest organic penetration rates nationally. DEFRA's Environmental Land Management scheme channels subsidy flows toward Kent and Sussex farmland conversion. Specialty retail clusters in Richmond, Kensington, and Brighton sustain premium positioning for Soil Association-certified SKUs.
Midlands
Manufacturing heritage towns show emerging demand for organic processed goods rather than fresh produce. The Competition and Markets Authority monitors greenwashing claims in Birmingham and Leicester supermarket chains. Derbyshire and Shropshire dairy operations are converting to organic certification to supply private-label ranges.
North England
Price sensitivity constrains household penetration below southern benchmarks. Yorkshire Dales and Cumbrian hill farms leverage DEFRA ecological subsidies for sheep and cattle conversion. Manchester and Leeds retail developments are testing organic fresh produce sections in regenerated urban cores.
Scotland
Underdeveloped organic acreage offers land availability and lower rental costs for scaling domestic production. Scottish Government rural development programs complement DEFRA schemes with additional conversion grants. Aberdeenshire and Perthshire arable operations are piloting grain and vegetable certification for UK supermarket supply contracts.
Wales
Small-scale producer density favors farmers market and direct-to-consumer channels over supermarket distribution. Welsh Government agricultural support frameworks prioritize organic conversion in Pembrokeshire and Gwynedd. Soil Association inspector capacity constraints create certification backlogs for converting livestock operations.
UK Organic Food Market Competitive Landscape
Capability concentration sits with premium-tier specialists; scale advantage sits with national supermarket chains. The market structures around three tiers: volume-driven multiples with private-label dominance, mid-market grocers balancing price and provenance, and digital-native disruptors bypassing slotting fee structures. Two strategic archetypes predominate: integrated retailers controlling shelf positioning through in-house organic development, and farmer-producer hybrids capturing margin through direct distribution. Competitive moves center on private-label range expansion and rapid delivery infrastructure deployment.
Among UK-based supermarket operators, Sainsbury's, Tesco, and Waitrose occupy distinct positions within the organic tier. Sainsbury's exemplifies the integrated retailer archetype through proprietary label development and format-spanning distribution. Tesco anchors the scale-driven end with aggressive price matching on staple categories. Waitrose represents premium provenance positioning through tighter supply partnerships and regional storytelling. Ocado and Riverford Organic Farmers sit outside this structure as digital-native and direct-to-consumer alternatives respectively.
| Leading Market Players |
|---|
| Sainsbury's |
| Tesco |
| Waitrose |
| Ocado |
| Lidl |
| Marks & Spencer |
| Aldi |
| Yeo Valley Farms |
| Riverford Organic Farmers |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Scottish and Welsh organic acreage concentrates pricing power with England's established Soil Association-certified farms, driving supplier behavior toward premium contract negotiations while retailers absorb margin compression through private-label development.
Pricing Analysis
Long-term offtake agreements between Waitrose and Kent vegetable growers anchor the upper pricing tier, while spot-market procurement from continental EU suppliers fills seasonal gaps at compressed margins. Price differentiation hinges on Soil Association certification grade and volume scale, with family-pack SKUs commanding standard-tier positioning against single-origin premium lines. Cost compression in dairy categories is intensifying because Tesco's aggressive price matching on organic milk erodes branded supplier leverage. Health-conscious adults in London and the South East exhibit the lowest price sensitivity, while northern England households drive promotional dependency.
Supply Chain Analysis
Contract-manufacturing concentration for processed organic goods sits with Yeo Valley Farms and dedicated co-packing facilities in Somerset and Gloucestershire. Raw material sourcing draws from Spanish citrus growers, Italian pasta wheat suppliers, and domestic East Anglian grain producers. Single-source vulnerability runs through the Dover-Calais logistics corridor for fresh produce imports. Distribution runs through supermarket regional distribution centers and Ocado's automated fulfillment hubs, with direct-to-consumer channels bypassing traditional wholesale layers entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK organic food market functions as a defensive-moat story where Soil Association certification entrenchment creates switching costs that lock retailer shelf access and consumer recognition against uncertified competitors.
For Market Incumbents: Entrench certification advantage through accelerated inspector capacity investment to shorten conversion timelines for partner farms. Deepen backward integration into East Anglian arable land to secure grain supply against import volatility. Ocado's algorithmic curation and rapid delivery infrastructure represents the primary channel threat requiring defensive response. For New Entrants and Emerging Players: Build out direct-to-consumer subscription models targeting Welsh and Scottish underdeveloped acreage where land rental costs enable competitive sourcing. The most penetrable segment is grains and cereals, where domestic supply gaps force retailers toward import-dependent procurement. A provenance-first go-to-market angle leveraging blockchain-enabled tracking aligns with millennial verification expectations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across online retail infrastructure as cold-chain density matures in secondary cities. Long-term viability over the coming decade rests on certification body consolidation and inspector capacity scaling. Acquisition target archetype: mid-scale organic producers with Soil Association accreditation and underutilized processing capacity. The signal to watch is DEFRA subsidy reallocation velocity as an indicator of domestic supply expansion pace.| Strategic Initiative | Industry Significance |
|---|---|
| Soil Association Certification Expansion | Accelerates market entry for converting farms while locking retailer shelf allocation hierarchy. |
| Direct-to-Consumer Channel Launch | Bypasses supermarket slotting fees through subscription models targeting urban professional households. |
| Backward Integration into Arable Land | Secures grain and cereal supply against continental import dependency and currency volatility. |
| Blockchain Provenance Tracking Deployment | Collapses audit costs for Waitrose and Sainsbury's while meeting millennial transparency demands. |
| Scottish and Welsh Supply Expansion | Captures lower rental costs and DEFRA complementary subsidies for domestic production scaling. |
Research Methodology
The analysis maps organic product categories, distribution channels, certification tiers, and consumer psychographics, each validated through farm operations managers, supermarket category buyers, Soil Association certification officers, and online retail supply planners. Primary interview findings triangulate against DEFRA subsidy disbursement records, Soil Association membership databases, Nielsen retail audit data, and customs import statistics. Bottom-up farm-level production estimates and top-down retail revenue aggregation cross-validate volume and value outputs.
Assumption sets held fixed include retained EU organic regulatory equivalence, current DEFRA Environmental Land Management scheme funding levels, and existing Soil Association inspection capacity. The projection horizon models segmentation across product type, distribution channel, certification body, and consumer archetype. CAGRs derive from acreage conversion velocity, household penetration curves, and channel shift elasticity. Forecast inputs incorporate organic feed price indices and cold-chain infrastructure deployment timelines.
Stress conditions across inspector capacity constraints, post-Brexit trade agreement reciprocity, and input cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors. Quarterly review of DEFRA subsidy allocation rates, Soil Association certification backlog durations, and online retailer delivery density metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
UAE Organic Food Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
South Korea Organic Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Canada Organic Food Market
Organic Food and Beverages
Global Organic Packaged Food Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Organic Superfood Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Global Organic Chocolate Spreads Market