
 Food Service Utensils Market | 2026-2036
Food Service Utensils Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Utensils Market Analytics
EU REACH compliance is rebalancing the cost-of-entry calculus for European utensil suppliers, forcing reformulation of plastic resins and expanded migration testing budgets. The Vollrath Co., L.L.C. leverages its domestic stainless steel forging capacity to bypass import tariff exposure on Asian metalware. Cambro Manufacturing Co. anchors its position through proprietary thermal resin formulations that sustain repeated high-temperature dishwashing cycles.
Food service utensils comprise hand-manipulated implements used to prepare, portion, transfer, or consume food in commercial and institutional settings, typically fabricated from stamped stainless steel, injection-molded thermoplastics, or laminated wood composites with heat resistance thresholds exceeding 120°C. These tools enable sanitary food handling, portion control, and operational efficiency across high-throughput kitchen environments. Stainless steel utensils command the dominant share of commercial procurement due to lifecycle durability and dishwasher compatibility, while silicone spatulas represent the fastest-expanding material category as operators seek heat-flexible tools that resist scratching on non-stick cookware surfaces. The commercial usage segment generates the deepest margin pools, driven by volume contracts with multi-unit restaurant chains and institutional foodservice management companies.
FDA food contact substance regulations govern polymer selection and additive migration limits for US-distributed utensils, while the EU F-Gas Regulation indirectly shapes manufacturing energy costs for European melamine and thermoset producers. China's GB standards for food-contact plastics impose additional testing protocols on exporters serving the country's state-owned hospitality sector. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based content certification schemes as procurement criteria harden across institutional buyers.
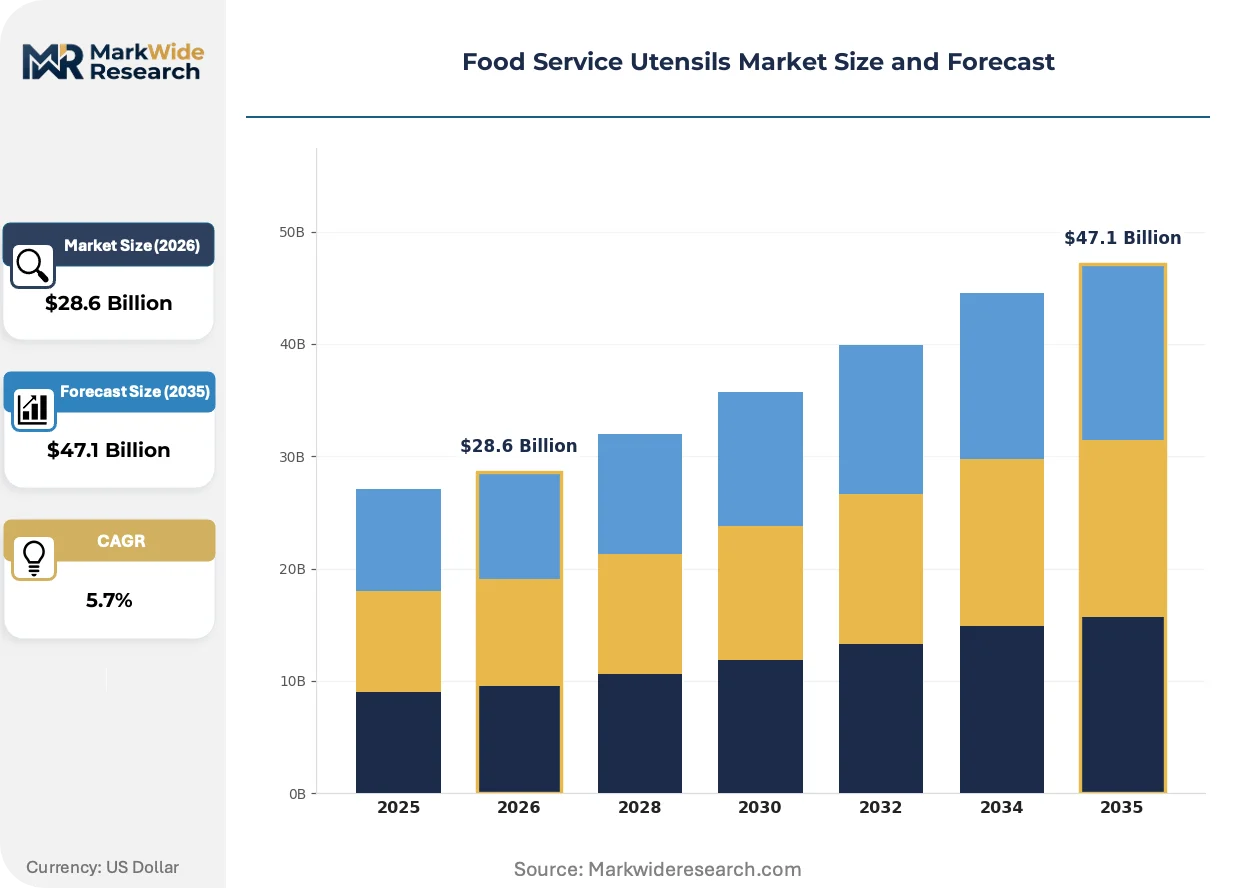
Market Dynamics
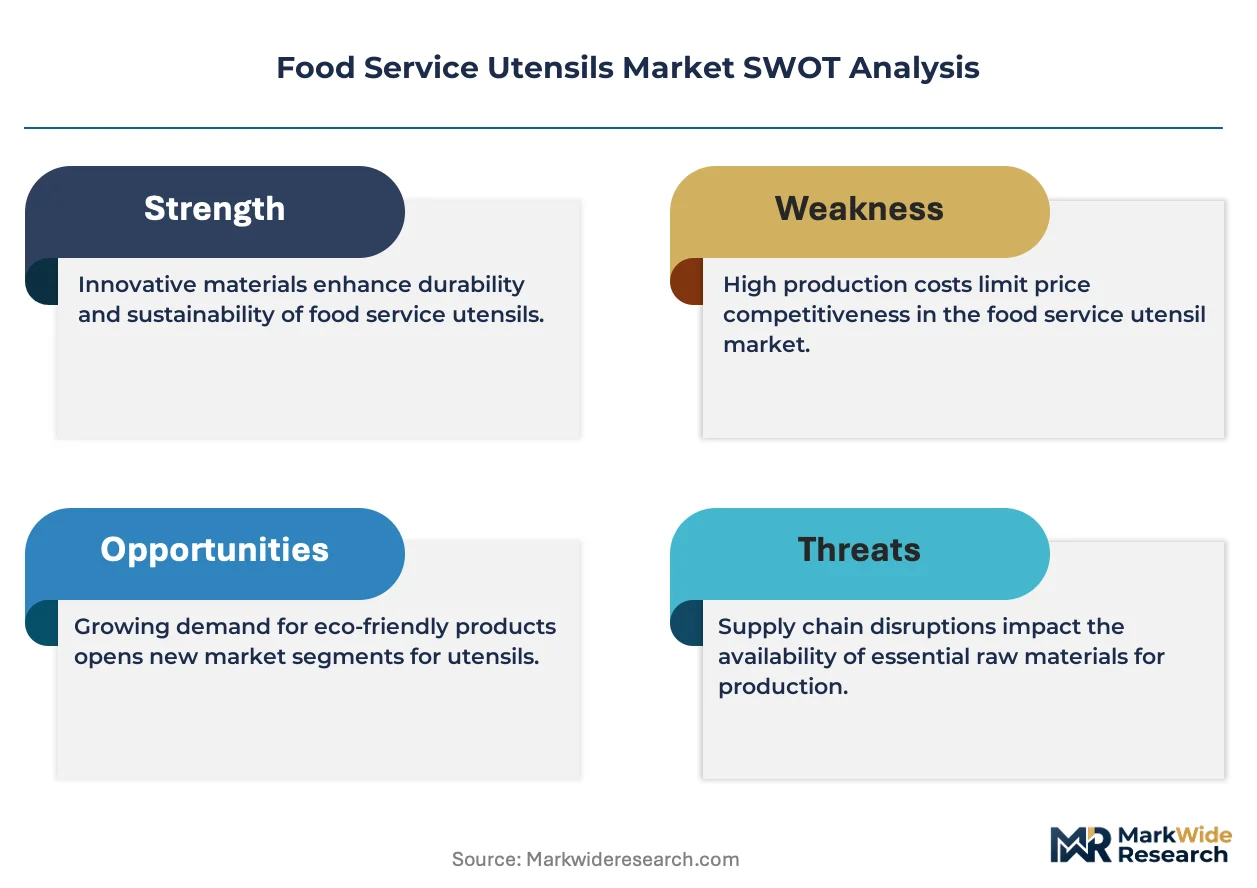
The EU Single-Use Plastics Directive is compressing demand for conventional petroleum-based utensils while redirecting manufacturing investment toward bio-polymer compounding facilities and industrial composting infrastructure.
Growth Catalysts
- Cloud Kitchen Networks:India's organized foodservice sector requires standardized utensil sets at procurement volumes that justify dedicated molding contracts and regional distribution hubs.
- REACH Compliance:ECHA's expanded migration testing mandates are accelerating substitution of conventional plasticizers with bio-based alternatives in European-sourced polymer resins.
- Reusable Set Procurement:Quick-service restaurant chains across Southeast Asia are contracting directly with stainless steel forgers for durable serving tools that withstand commercial dishwashing cycles.
Market Restraints
- Nickel Price Volatility:Stainless steel utensil margins compress when London Metal Exchange nickel futures spike, forcing contract renegotiations between foundries and foodservice distributors.
- Melamine Supply Concentration:Thermoset resin production clusters in eastern China expose global buyers to port congestion risk and tariff uncertainty on molded servingware imports.
- Compostable Certification Gaps:Industrial composting infrastructure lags behind bio-plastic utensil output in North American municipalities, creating disposal friction for operators.
Strategic Opportunities
- State-Owned Hospitality Procurement:China's GB standards compliance creates a captive market entry point for exporters with certified food-contact polymer testing capabilities.
- Silicone Spatula Demand:Heat-flexible tools that resist scratching on non-stick cookware surfaces are displacing nylon implements in premium kitchen supply channels.
- Extended Producer Responsibility Frameworks:EU member state take-back mandates are creating service revenue streams for utensil suppliers with reverse logistics infrastructure.
Industry Challenges
- Migration Testing Bottlenecks:FDA food contact substance notification queues extend lead times for novel polymer formulations seeking US market entry.
- Polymer Reformulation Costs:Shifting from conventional resins to certified compostable materials requires capital investment in twin-screw extrusion lines and additive blending systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Utensils Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.1 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Utensil Type: Forks, Spoons, Knives, Spatulas Material Type: Plastic, Stainless Steel, Wood, Silicone Usage: Commercial, Residential, Catering, Events Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | The Vollrath Co., L.L.C., Cambro Manufacturing Co., Server Products, Winston Foodservice, Alto-Shaam, Inc., Hatco Corporation, Choice Equipment Company, Comstock-Castle Stove Co., Inc., Ambro Manufacturing Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Utensils Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape competitive positioning in commercial serving tools, with durability claims now requiring documented lifecycle testing rather than manufacturer assertions.
Plant-fiber reinforced thermoplastics are rewriting material specifications for disposable cutlery. Quick-service operators in Nordic markets are piloting molded fiber utensils with heat resistance exceeding 100°C. This substitution is compressing demand for conventional polystyrene implements in European institutional procurement.
F-Gas Regulation energy cost pressures are forcing melamine and thermoset producers toward electrified curing ovens. German manufacturers report 15-20% production cost increases from natural gas price spikes. The shift is accelerating investment in microwave-assisted polymerization systems that reduce cycle times and energy intensity.
Consolidated buying by multi-unit restaurant chains is displacing fragmented distributor networks. Foodservice management companies now contract directly with Asian metalware forgers for containerized shipments of standardized utensil sets. The compression of intermediary margins is most visible in North American group purchasing organization contract renegotiations.
Food Service Utensils Market Segmentation
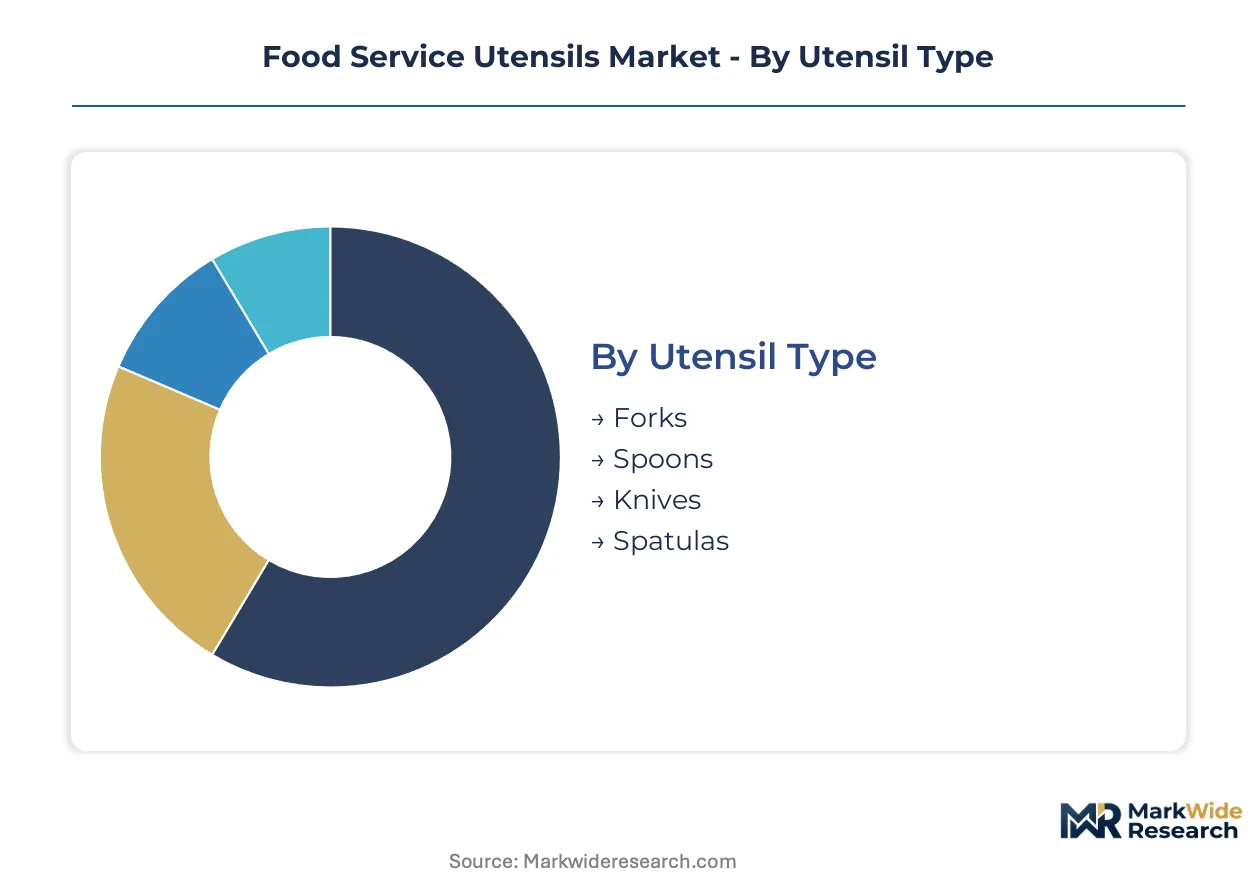
Segmentation in food service utensils reveals how procurement specifications diverge between high-volume institutional contracts and fragmented retail channels. Material selection and distribution pathways determine margin structures, compliance burdens, and supplier qualification requirements across distinct buyer ecosystems.
Utensil Type:
The customization-to-standardization spectrum spans from commodity flatware with minimal specification variance to specialized tools requiring ergonomic design validation for high-throughput kitchen environments.
- Forks:Tine geometry and weight distribution determine suitability for protein-dense menus versus salad-forward concepts. Quick-service chains in Southeast Asia specify 18/0 stainless steel dinner forks with reinforced necks to withstand automated dishwashing systems.
- Spoons:Bowl depth and handle length differentiate soup service from dessert applications. India's cloud kitchen networks standardize on 6.5-inch stainless steel tablespoons to reduce SKU complexity across multi-brand operations.
- Knives:Serrated edge retention and bolster design separate steak service from general-purpose cutting. Serrated blades with stamped handles dominate commercial procurement for cost efficiency.
- Spatulas:Blade flexibility and heat resistance thresholds distinguish silicone variants from nylon and metal implements. Heat-flexible silicone spatulas are expanding fastest in premium kitchen supply channels due to non-stick cookware compatibility.
Leading the category by volume: Spoons. Growing fastest: Spatulas.
Material Type:
Cost tier stratification separates disposable single-use implements from capital-equipment-grade durable tools with decade-long replacement cycles.
- Stainless Steel:18/8 and 18/10 chromium-nickel grades dominate commercial procurement through lifecycle durability and dishwasher compatibility. Vollrath Co. leverages domestic forging capacity to bypass import tariff exposure on Asian metalware.
- Silicone:Platinum-cured formulations resist degradation above 200°C while maintaining flexibility below freezing. FDA food contact substance regulations govern additive migration limits for US-distributed silicone tools.
- Plastic:Injection-molded polypropylene and polystyrene serve cost-sensitive disposable applications. EU Single-Use Plastics Directive is compressing demand for conventional petroleum-based variants.
- Wood:Laminated bamboo composites and hardwood implements satisfy aesthetic requirements in front-of-house service. Heat resistance thresholds exceeding 120°C require specific resin impregnation treatments.
Stainless steel commands the dominant procurement share. Silicone is climbing the fastest as operators replace nylon implements.
Usage:
Application context determines sanitation protocols, replacement frequency, and specification stringency across buyer segments.
- Commercial:High-throughput restaurants, institutional cafeterias, and foodservice management companies require NSF-certified implements with documented heat resistance. Volume contracts with multi-unit chains generate the deepest margin pools.
- Catering:Mobile service operations prioritize lightweight, stackable designs with rental-compatible durability profiles. Event-based demand fluctuates seasonally across wedding and corporate entertainment calendars.
- Residential:Consumer-grade implements emphasize aesthetic coordination with kitchen décor over functional specification. Retail distribution through big-box channels dominates this segment.
- Events:Single-use and rental hybrid models serve stadium concessions, festival vendors, and temporary food installations. Compostable certification requirements are tightening for outdoor event procurement.
Commercial usage generates the highest contract values. Catering applications are expanding most quickly as experiential dining formats proliferate.
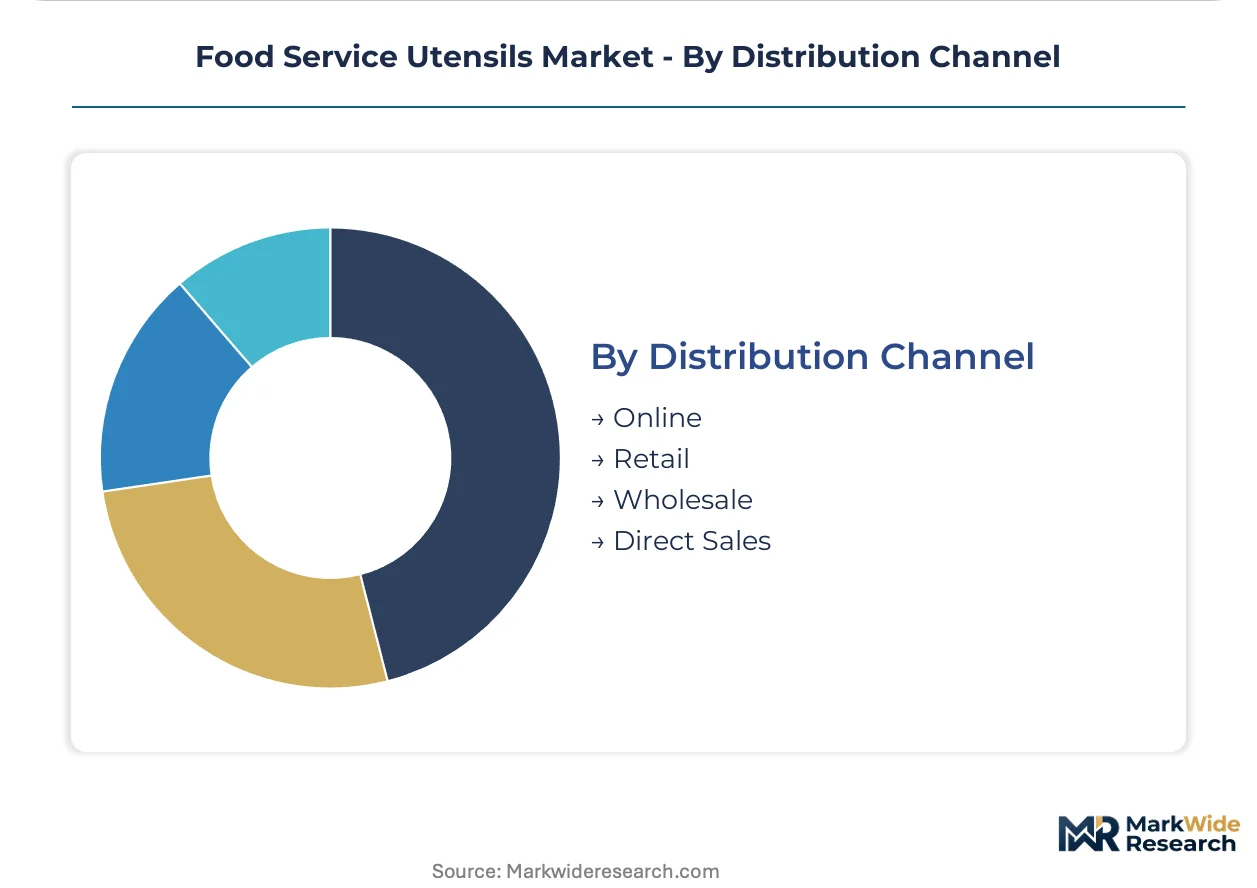
Distribution Channel:
Customer type and volume scale determine whether procurement flows through intermediary networks or direct manufacturer relationships.
- Wholesale:Broadline foodservice distributors aggregate demand from independent restaurants and institutional buyers. Cambro Manufacturing Co. anchors position through proprietary thermal resin formulations sustaining repeated high-temperature dishwashing.
- Direct Sales:Multi-unit chains contract directly with Asian metalware forgers for containerized shipments of standardized utensil sets. Consolidated buying is displacing fragmented distributor networks in North American group purchasing organization renegotiations.
- Retail:Consumer-facing channels including specialty kitchen stores and mass merchants serve residential replacement demand. Three-tier pricing structure separates premium, standard, and economy levels based on material grade and origin.
- Online:E-commerce platforms enable small-format operators to access commercial-grade specifications without minimum order quantities. Digital procurement is gaining share fastest among independent restaurant startups.
Wholesale channels maintain the largest transaction volumes. Online distribution is expanding most quickly as digital procurement platforms penetrate small-operator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones for food processing in Gujarat and Maharashtra concentrate molded-plastic utensil fabrication for cloud kitchen supply chains. These tax-advantaged corridors attract compounding equipment investment from domestic and multinational polymer suppliers.
United States
Multi-unit restaurant chains consolidate procurement through group purchasing organizations, driving containerized import volumes from Asian metalware forgers. FDA food contact substance notification queues extend lead times for novel polymer formulations. Shreveport-Bossier City in Louisiana hosts stainless steel distribution hubs serving institutional foodservice management companies.
Germany
EU F-Gas Regulation energy cost pressures force melamine and thermoset producers toward electrified curing ovens. ECHA's expanded migration testing mandates accelerate substitution of conventional plasticizers with bio-based alternatives. The Ruhr industrial corridor concentrates microwave-assisted polymerization system investment.
China
State-owned hospitality sector procurement under GB standards for food-contact plastics creates captive market entry points for certified exporters. Dual carbon goals compress energy-intensive thermoset production in eastern provinces. The Yangtze River Delta clusters melamine resin production serving global servingware demand.
India
Cloud kitchen networks in Bengaluru and Mumbai require standardized utensil sets at procurement volumes justifying dedicated molding contracts. FSSAI compliance frameworks tighten food-contact polymer specifications for organized foodservice. Gujarat's Special Economic Zones concentrate injection-molding capacity for quick-service restaurant supply chains.
Vietnam
Quick-service restaurant chains expand procurement of reusable stainless steel sets from regional forging networks. Import tariff exposure on Asian metalware redirects sourcing toward ASEAN fabrication clusters. Ho Chi Minh City's industrial zones attract Taiwanese and South Korean polymer compounding joint ventures.
Food Service Utensils Market Competitive Landscape
United States producers anchor one tier of stainless steel forging capacity; Asian specialists hold molded-polymer and metalware fabrication at scale. The market structures around three tiers: domestic stainless steel forgers with tariff-shielded supply chains, Asian contract manufacturers serving volume procurement, and regional thermoplastic compounders navigating bio-polymer transitions. Consolidation pressures concentrate among multi-unit chain procurement offices. Strategic moves center on backward integration into polymer resin compounding and direct contracting with cloud kitchen networks.
Within the domestic forging tier, The Vollrath Co., L.L.C. represents North American stainless steel capacity. Among molded-servingware specialists, Cambro Manufacturing Co. occupies a position in thermal resin formulation. Server Products exemplifies the mid-scale fabrication archetype serving institutional channels. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| The Vollrath Co., L.L.C. |
| Cambro Manufacturing Co. |
| Server Products |
| Winston Foodservice |
| Alto-Shaam, Inc. |
| Hatco Corporation |
| Choice Equipment Company |
| Comstock-Castle Stove Co., Inc. |
| Ambro Manufacturing Co. Inc. |
| Others |
Value Network & Pricing Analysis
Nickel futures on the London Metal Exchange transmit volatility directly through 18/8 and 18/10 stainless steel forging tiers, compressing margins for distributors serving quick-service restaurant chains while rewarding domestic forgers with captive scrap supply. This cost cascade stratifies procurement across premium certified grades, standard commercial specifications, and economy spot purchases.
Pricing Analysis
Short lead-time premiums command substantial markups over contract-scheduled deliveries, with spot inventory from Asian forgers trading at discounts to containerized direct shipments. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified implements with documented heat resistance from unmarked commercial grades and disposable polymer alternatives. Pricing pressure stems from consolidated buying by multi-unit chains renegotiating group purchasing organization contracts. Independent restaurants exhibit highest price sensitivity; institutional foodservice management companies prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with melamine resin production clusters in China's Yangtze River Delta, where port congestion and tariff uncertainty expose global servingware buyers to supply interruptions. Raw material flows draw from Indonesian nickel laterite, South Korean polymer compounding, and German specialty steel finishing. Supply chain risk centers on concentrated thermoset curing capacity facing EU F-Gas Regulation energy cost pressures. Distribution runs through broadline foodservice distributors aggregating fragmented independent restaurant demand alongside direct containerized contracts with multi-unit chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food service utensils represent a vertical-integration race where backward control over polymer resin compounding and stainless steel forging capacity determines margin defense. Players are pursuing captive supply of bio-based polymer feedstocks as the decisive downstream lever.
For Market Incumbents: Anchor market position through proprietary thermal resin formulations that sustain repeated high-temperature dishwashing cycles, differentiating from commodity polymer suppliers. Defend against emerging bio-polymer compounders by securing dedicated molding contracts with India's cloud kitchen networks. Prioritize certification investment for EU REACH compliance and FDA food contact substance notifications to maintain institutional procurement eligibility. For New Entrants and Emerging Players: Plant-fiber reinforced thermoplastics with heat resistance exceeding 100°C offer a technology-first wedge into Nordic quick-service procurement piloting molded fiber cutlery. Target India's organized foodservice sector where FSSAI compliance frameworks tighten specifications and favor certified entrants. Pursue direct sales channels with Bengaluru and Mumbai cloud kitchen operators seeking standardized utensil sets without distributor markups. For Investors and Strategic Acquirers: Taiwanese and South Korean polymer compounding joint ventures in Vietnam's Ho Chi Minh City industrial zones are the leading indicator that ASEAN fabrication clusters are capturing redirected sourcing from tariff-exposed Chinese metalware. Long-term viability favors vertically integrated specialists controlling both resin formulation and regional distribution infrastructure. Watch for extended producer responsibility framework implementation across EU member states as the signal for reverse logistics service revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive bio-polymer supply secures EU Single-Use Plastics Directive compliance and insulates margin from resin price volatility. |
| Direct Contracting with Cloud Kitchen Networks | Multi-brand operators in India's Special Economic Zones generate volume commitments justifying dedicated molding capacity investment. |
| Certification Investment for GB Standards | China's state-owned hospitality procurement creates captive entry points for exporters with documented food-contact polymer testing capabilities. |
| Reverse Logistics Infrastructure Buildout | EU member state take-back mandates transform utensil suppliers into service providers capturing extended producer responsibility revenue streams. |
| Microwave-Assisted Polymerization Adoption | German manufacturers reduce cycle times and energy intensity as F-Gas Regulation pressures force abandonment of natural gas curing ovens. |
Research Methodology
Independent corroboration across foodservice management company procurement directors, polymer compounding plant managers, and stainless steel forging operations heads underwrites the qualitative findings. Secondary validation draws from customs and trade data tracking containerized utensil shipments, SEC filings of listed foodservice equipment manufacturers, EU ECHA migration testing notification databases, and India's FSSAI compliance registries. Bottom-up volume estimates from regional molding capacity and top-down demand aggregation from institutional contract values were reconciled through iterative triangulation.
Comparable historical periods anchored the projection horizon to documented procurement cycles preceding regulatory inflection points. Segmentation dimensions modeled span utensil type, material grade tier, usage context, and distribution channel structure across geographic production hubs. CAGRs were derived from elasticity-adjusted demand curves incorporating cloud kitchen network expansion rates and bio-polymer substitution trajectories. Forecast inputs included London Metal Exchange nickel price band assumptions and EU extended producer responsibility implementation timelines.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting ASEAN metalware tariffs and unanticipated breakthroughs in biodegradable polymer heat resistance. Forecasts reflect assumptions about regulatory enforcement consistency and industrial composting infrastructure deployment rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Foodservice Market
Food Service
Europe Vending Machine Market
Food Service
United Kingdom Foodservice Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
France Foodservice Market
Food Service
North America Cafes & Bars Market
Food Service
GCC Biodegradable Food Service Disposables Market
Food Service
Latin America Online Grocery Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Takeout Dinner Market
Food Service
Chile Food Delivery Market
Food Service
Cambodia Foodservice Market
Food Service
Haute Cuisine Market
Food Service
Commercial Steam Table Market
Food Service
UAE Food Service Market
Food Service
North America Food Service Disposable Market