
 North America Food Service Market | 2026-2036
North America Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Service Market Insights
Chain-restaurant procurement consolidation among multi-unit operators is rebalancing negotiating leverage toward large distributors. Sysco Corporation leverages its captive distribution network to secure long-term contract stability with national accounts. Performance Food Group competes through specialized protein and produce sourcing that sustains margin control in volatile commodity cycles. Gordon Food Service anchors its position in the Midwest through direct-store delivery infrastructure that dominates independent operator channels.
Food service encompasses the commercial preparation, assembly, and delivery of ready-to-consume meals through institutional, retail, and restaurant channels, operating under HACCP temperature controls and standardized portion specifications to ensure safety and consistency at scale. Fast-casual and quick-service formats lead volume throughput while fine dining captures disproportionate margin pools through beverage attachment and experiential pricing. Delivery and catering channels are expanding fastest as ghost kitchen infrastructure reduces real estate overhead, though dine-in retains structural importance for customer acquisition and brand building.
FDA Food Code updates and USDA FSIS inspection protocols govern cross-border ingredient sourcing and processing standards across the United States, while Health Canada and CFIA requirements shape parallel compliance obligations for suppliers operating in both countries. State-level plastic packaging bans and municipal composting mandates in California, New York, and Vancouver are forcing operational redesigns in disposable serviceware and waste management. Stakeholders must monitor diverging provincial and state sustainability timelines to avoid stranded inventory in packaging and equipment commitments.
Market Dynamics
Multi-unit restaurant chains are consolidating procurement decisions into centralized category management offices, stripping independent distributors of historic relationship-based selling advantages and compressing supplier margins through volume-tiered contract structures.
Growth Catalysts
- Quick-service format expansion:Fast-casual operators are scaling ghost kitchen footprints in Texas and Florida metro corridors to capture delivery-native demand without dine-in real estate overhead.
- FDA Food Code harmonization:Updated temperature control and allergen labeling requirements are standardizing equipment specifications across state lines, reducing compliance fragmentation for multi-jurisdictional operators.
- Protein processing automation:Robotic portioning and cook-chill systems are cutting labor dependency in high-volume institutional cafeterias serving healthcare and education sectors.
Market Restraints
- Input cost volatility:Beef and poultry commodity swings are compressing distributor margins on protein-forward menu items, forcing hedging costs onto balance sheets.
- Supply concentration risk:Cold storage capacity bottlenecks in California's Central Valley are creating regional fulfillment delays during peak harvest windows.
- Regulatory friction:Divergent state-level sodium reduction mandates between California and Texas are forcing product formulation splits that fragment production runs.
Strategic Opportunities
- Underpenetrated Canadian institutional channel:Healthcare and senior living food service contracts in Ontario and British Columbia remain fragmented among regional players with limited national scale.
- Regulatory tailwind:Municipal composting mandates in Vancouver and San Francisco are creating first-mover advantages for suppliers with certified biodegradable serviceware portfolios.
- Technology convergence:IoT-enabled temperature monitoring combined with blockchain traceability is opening premium contract tiers for safety-verified supply chains.
Industry Challenges
- Culinary talent scarcity:Shortages of certified food safety managers are extending kitchen supervisory hiring cycles and inflating wage premiums in high-cost metros.
- Legacy system integration:ERP migration from on-premise inventory platforms to cloud-native procurement suites is disrupting order-to-cash workflows during multi-month transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Service Market |
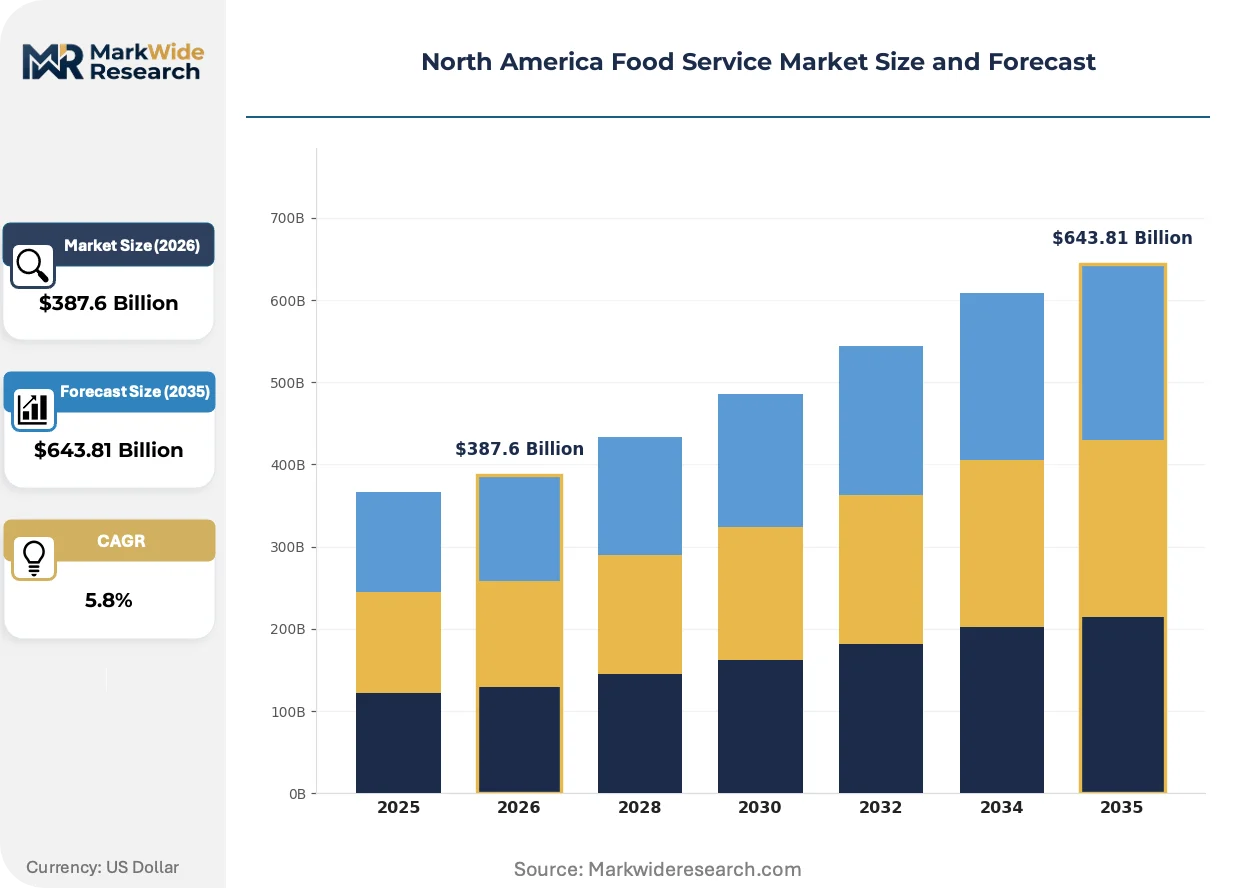
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fast Food, Casual Dining, Fine Dining, Food Trucks Customer Type: Families, Singles, Millennials, Seniors Distribution Channel: Dine-in, Takeout, Delivery, Catering Cuisine Type: Italian, Mexican, American, Asian |
| Companies Covered | Sysco Corporation, Performance Food Group, Gordon Food Service, McDonald's Corporation, Starbucks Corporation, Yum! Brands Inc., Restaurant Brands International, Compass Group North America, Aramark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Service Market Trends and Innovations
Automation and regulatory compliance technology are compressing operational slack across the food service value chain, forcing capital deployment decisions that separate scalable platforms from stranded facility investments.
Automated cook-chill and sous-vide production systems are consolidating batch preparation into centralized commissaries. Quick-service chains with 50-plus unit footprints are deploying these systems to replace on-site cooking infrastructure. This consolidation is compressing the addressable market for traditional kitchen equipment distributors while expanding demand for refrigerated logistics and rethermalization technology.
USDA FSIS inspection protocol updates are mandating enhanced microbial testing documentation for ground beef and poultry suppliers. Processing facilities must now maintain electronic lot-tracking systems that interface directly with customer procurement portals. Small and mid-sized protein distributors lacking IT integration capabilities are losing institutional contract eligibility in California and New York school nutrition programs.
Contract food service operators are unbundling beverage programs from consolidated procurement agreements. Universities and corporate campuses are negotiating direct relationships with specialty coffee roasters and craft beverage suppliers, bypassing incumbent broadline distributors. This disintermediation is most pronounced in Pacific Northwest and Northeast corridor markets where local brand preference overrides volume discount incentives.
North America Food Service Market Segmentation
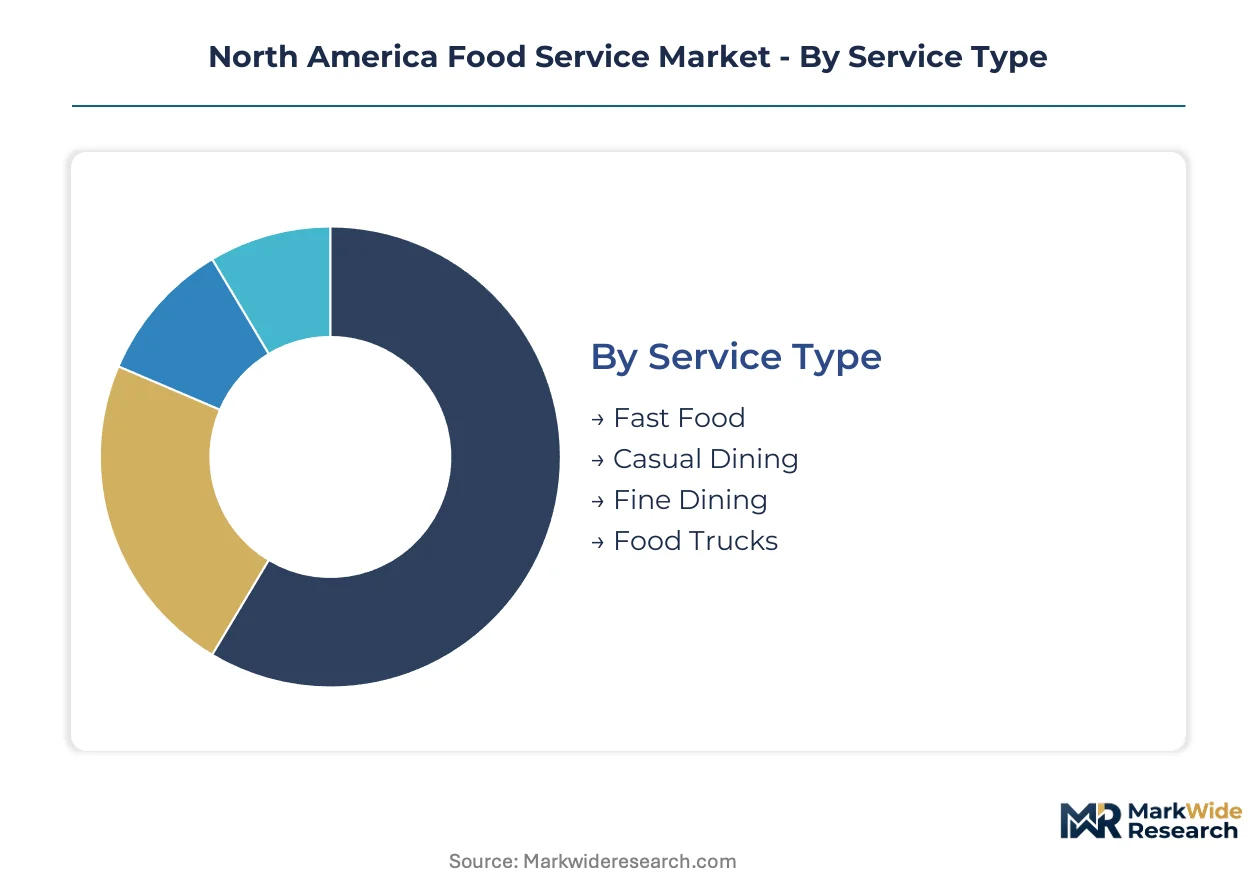
Segmentation in North American food service reveals how procurement priorities, consumption occasions, and channel economics fragment the addressable market. Distributors and operators calibrate inventory, labor deployment, and real estate investments against these fault lines to optimize margin capture.
Service Type:
Capital intensity and throughput velocity drive operator selection across formats, with real estate costs and labor models determining regional viability.
- Fast Food:High-volume, limited-menu operations with standardized cook-chill workflows and drive-thru throughput optimization. Demand concentrates in Texas and Florida suburban corridors where land costs support freestanding prototypes and drive-thru lane stacking.
- Casual Dining:Full-service restaurants with bar-forward beverage programs and experiential dining rooms averaging 5,000-7,000 square feet. California and New York metro operators are retrofitting ghost kitchen appendages to defend delivery share without cannibalizing dine-in margins.
- Fine Dining:Chef-driven concepts with tasting-menu pricing and wine cellar investments requiring sommelier staffing.
- Food Trucks:Mobile kitchen units leveraging commissary prep and municipal permit corridors for lunch-hour density.
Fast Food leads on scale; Food Trucks lead on momentum.
Customer Type:
Meal occasion frequency and price elasticity vary sharply by household composition and generational cohort, reshaping menu engineering and loyalty program design.
- Families:Multi-cover dining occasions with shared-plate preferences and kid-menu requirements driving portion bundling and high-chair infrastructure investment. Suburban corridor locations in California's Inland Empire and Texas's Collin County capture this demographic's weekend clustering patterns.
- Singles:Solo dining occasions with snack-forward dayparts and counter-service preference minimizing table-turn friction. Urban cores in Seattle, Toronto, and Austin see concentrated demand for single-seat bar dining and grab-and-go formats.
- Millennials:Digital-native ordering with sustainability credential sensitivity and experience-over-stuff spending patterns.
- Seniors:Early-bird daypart concentration and dietary-modification requests requiring menu transparency and accessible seating.
Families anchor volume throughput; Singles are climbing the fastest on per-capita transaction frequency.
Distribution Channel:
Channel selection determines packaging specifications, temperature control handoffs, and commission structures that reshape operator economics.
- Dine-in:On-premise consumption with full-service or quick-service staffing models and dine-in amenity investment. Texas and Florida operators are expanding patio square footage to capture climate-advantaged outdoor dining demand.
- Takeout:Customer-collected orders requiring packaging for transport stability and order accuracy systems. Counter-service operators in Vancouver and San Francisco are redesigning pickup lobbies to accommodate municipal composting mandates for disposable serviceware.
- Delivery:Third-party platform or in-house courier fulfillment with commission structures and insulated packaging requirements.
- Catering:Large-format group feeding with drop-off or full-service execution and event-specific menu customization.
Dine-in retains structural importance for brand building; Delivery is gaining share fastest as ghost kitchen infrastructure matures.
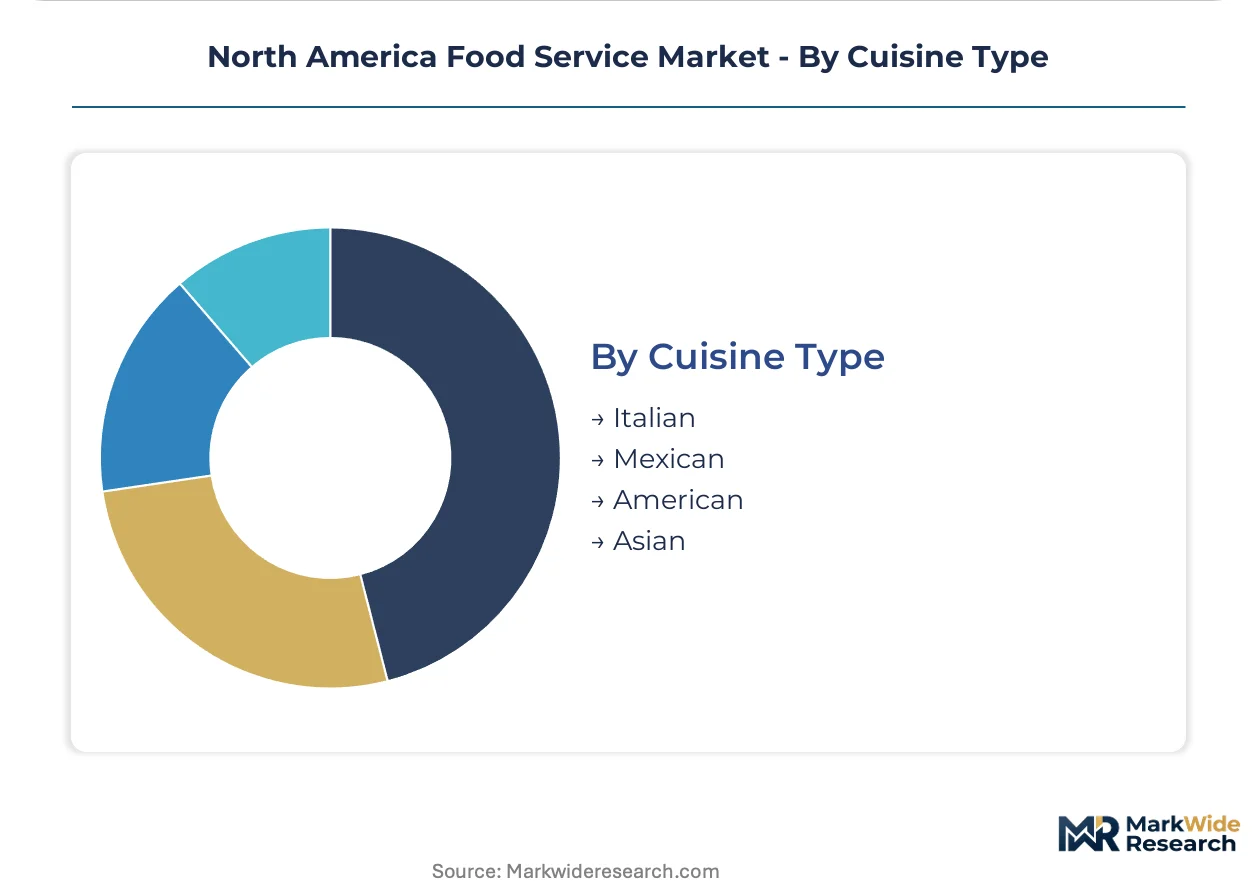
Cuisine Type:
Ingredient sourcing networks and labor skill requirements create divergent margin profiles across culinary traditions.
- Italian:Pasta-forward menus with centralized sauce production and wine program integration. Independent operators in Ontario's Greater Toronto Area compete with national chains through regional Italian wine procurement and house-cured charcuterie programs.
- Mexican:Tortilla and masa supply chains with salsa-bar customization and beverage attachment through agave spirits. Texas and California operators leverage proximity to Mexican ingredient suppliers for freshness differentiation.
- American:Burger and sandwich-centric menus with broad protein sourcing and fryer-heavy back-of-house configurations.
- Asian:Wok-fired or sushi-prep kitchens requiring specialized ventilation and skilled line cook labor.
American cuisine leads on unit count; Mexican formats show the steepest expansion trajectory in Texas and California corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater procurement volume than Canada, though Mexico's quick-service expansion is narrowing the per-capita gap in certain metro corridors. Regulatory divergence across the three markets is forcing distributors to maintain parallel compliance systems for food safety, packaging, and labor standards.
United States
Texas and Florida metro corridors drive ghost kitchen proliferation, with Dallas-Fort Worth and Miami-Dade seeing concentrated delivery-native format expansion. FDA Food Code harmonization efforts are standardizing temperature control equipment specifications across state lines, reducing compliance fragmentation. California's Central Valley cold storage bottlenecks create regional fulfillment delays during peak agricultural harvest windows.
Canada
Ontario and British Columbia healthcare and senior living contracts remain fragmented among regional operators with limited national scale, creating acquisition opportunities for US distributors. Health Canada and CFIA requirements shape compliance obligations parallel to FDA rules, particularly for cross-border protein suppliers. Vancouver's municipal composting mandates are accelerating biodegradable serviceware adoption in British Columbia food service operations.
Mexico
Quick-service chains are scaling commissary production in Mexico City and Monterrey to serve delivery demand in dense urban corridors. Mexico's national food safety regulator enforces HACCP-aligned standards for institutional suppliers, with increasing alignment to US FDA protocols for export-oriented processors. Nuevo León's manufacturing base is attracting US-based equipment suppliers for automated cook-chill system deployment.
North America Food Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with broadline distributors holding structural advantages in national account consolidation. The market exhibits tiered concentration: three large distributors command institutional and chain-restaurant channels, while hundreds of regional players serve independent operators. Strategic archetypes include captive-network broadliners, specialized protein sourcers, and direct-store delivery specialists. Dominant competitive moves center on procurement consolidation through centralized category management and ghost kitchen infrastructure partnerships.
Within the broadline distribution tier, Sysco Corporation and Performance Food Group exemplify scale-driven procurement consolidation strategies. Gordon Food Service anchors the Midwest independent operator channel through direct-store delivery infrastructure. These three entities represent divergent responses to multi-unit chain consolidation: Sysco leverages captive distribution networks for contract stability, Performance Food Group competes through specialized sourcing, and Gordon Food Service dominates relationship-based selling in fragmented geographies.
| Leading Market Players |
|---|
| Sysco Corporation |
| Performance Food Group |
| Gordon Food Service |
| McDonald's Corporation |
| Starbucks Corporation |
| Yum! Brands Inc. |
| Restaurant Brands International |
| Compass Group North America |
| Aramark Corporation |
| Others |
Pricing and Supply Chain Analysis
Beef cutout values and poultry composite indices cascade through distributor markups into operator menu pricing, with commodity volatility compressing margins on protein-forward items and forcing volume-tiered contract structures that stratify large chains from independent operators.
Pricing Analysis
Capacity additions in California's Central Valley cold storage are reshaping price floors for perishable produce, though regional bottlenecks during peak harvest windows sustain premium tiers for guaranteed fulfillment. Three-tier pricing structure across premium, standard, and economy levels segments procurement contracts by volume commitment and temperature-control specifications. Cost compression in economy tiers is intensifying because multi-unit chains consolidate purchasing into centralized category management offices. Quick-service chains with 50-plus unit footprints exhibit lowest price sensitivity due to captive commissary infrastructure, while independent single-location operators face highest exposure to spot-market protein swings.
Supply Chain Analysis
FDA Food Code certification and HACCP compliance documentation gate supplier eligibility for institutional contracts in California and New York school nutrition programs. Protein processing concentrates in the United States, Canada, and Mexico under USDA FSIS, CFIA, and Mexican federal inspection protocols. Raw material flows draw from Midwest grain belts, Alberta cattle ranches, and Baja California produce corridors. Single-source vulnerability in California's Central Valley cold storage creates fulfillment risk during peak agricultural windows. Distribution runs through broadline distributors for national accounts and direct-store delivery networks for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
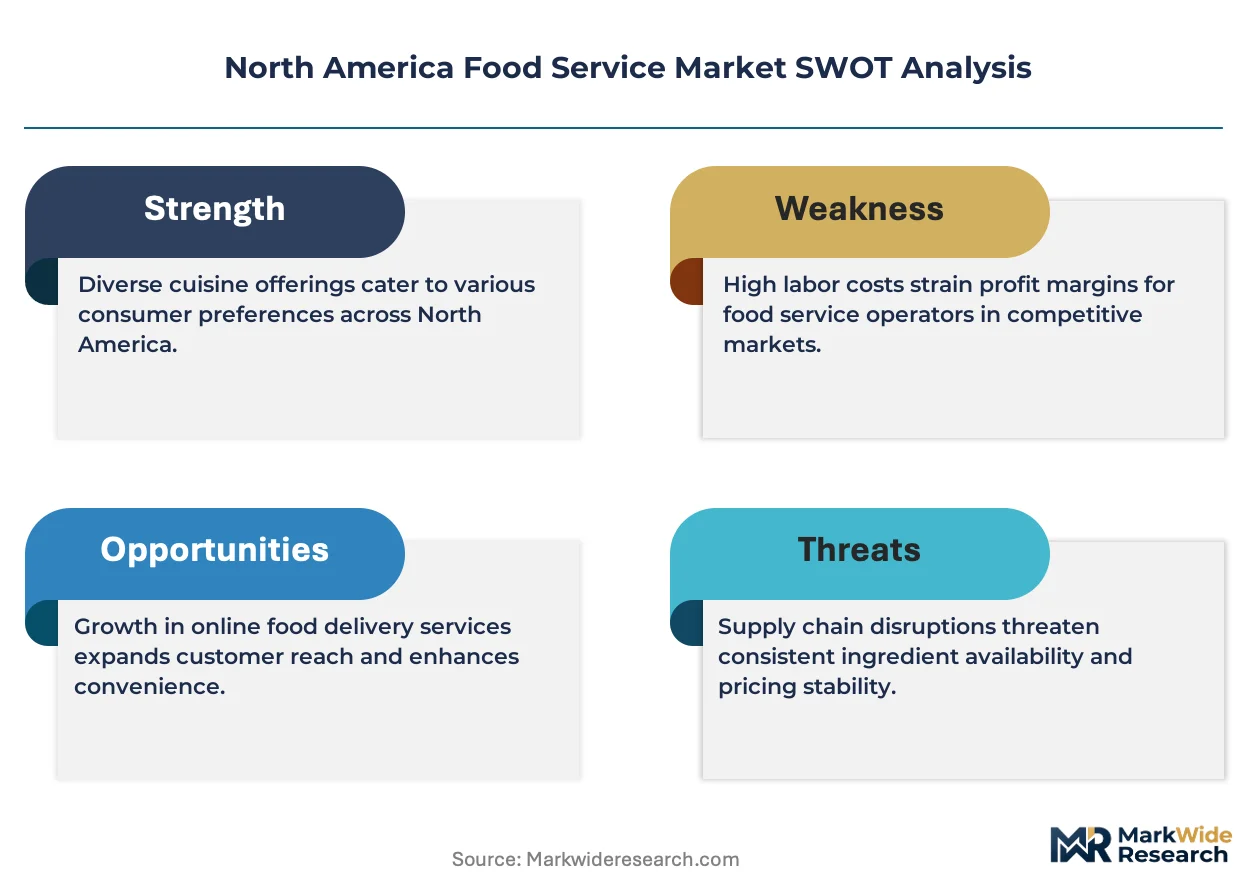
The North America food service market functions as a geographic-arbitrage play where Texas and Florida ghost kitchen expansion captures lower real estate costs against California's regulatory compliance burdens and cold storage bottlenecks.
For Market Incumbents: Cement contract stability through captive distribution infrastructure investments in Texas and Florida metro corridors where delivery-native format expansion accelerates. Fortify position against disintermediation threats in beverage procurement by acquiring specialty roaster and craft supplier relationships in Pacific Northwest markets. Backward integration into automated cook-chill commissary production anchors margin control against labor inflation in high-cost metros. For New Entrants and Emerging Players: Third-party delivery platform partnerships offer the lowest-friction route to operator visibility without dine-in real estate overhead. Target underpenetrated Canadian healthcare and senior living contracts in Ontario and British Columbia where regional players lack national scale. Municipal composting mandates in Vancouver and San Francisco create first-mover positioning for certified biodegradable serviceware portfolios. For Investors and Strategic Acquirers: Consolidation pressure builds where regional distributors lack IT integration capabilities for electronic lot-tracking systems mandated by USDA FSIS protocol updates. Long-term viability favors mid-cap specialists with protein sourcing expertise and cloud-native procurement platforms over legacy on-premise inventory operators. Watch FDA Food Code harmonization progress across state lines as signal for multi-jurisdictional operator expansion appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Infrastructure Partnership | Reduces real estate overhead for delivery-native formats in Texas and Florida corridors. |
| Automated Cook-Chill System Deployment | Replaces on-site cooking infrastructure for quick-service chains with 50-plus units. |
| Biodegradable Serviceware Certification | Captures municipal composting mandate advantages in Vancouver and San Francisco markets. |
| Blockchain Traceability Integration | Opens premium contract tiers for safety-verified supply chains in institutional channels. |
| Direct-Store Delivery Network Expansion | Dominates independent operator channels in Midwest fragmented geographies. |
Research Methodology
Bottom-up restaurant operator and institutional cafeteria modeling reconciled against top-down distributor shipment tracking forms the analytical core of this study. Primary interviews with chain procurement directors, broadline distributor category managers, food safety compliance officers, and ghost kitchen facility operators combined with secondary validation from FDA Food Code update documentation, USDA FSIS inspection protocol filings, Health Canada regulatory guidance, and state-level sodium reduction mandate records.
Input-output matrices map protein commodity indices, labor cost differentials, and real estate expense ratios across service type and customer type segments over the projection horizon. Modeled dimensions include fast food versus casual dining format economics, family versus single household occasion patterns, dine-in versus delivery channel cost structures, and Italian versus Mexican versus American cuisine ingredient sourcing networks. CAGRs derive from volume-weighted average of segment growth trajectories incorporating ghost kitchen penetration rates and automated production system adoption curves.
Commodity price volatility, regulatory divergence between California and Texas sodium mandates, and cold storage capacity constraints are the dominant revision risks to modeled forecasts. Deviation in protein input cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Workplace Service Market
Food Service
Mobile Food Services Market
Food Service
Quick-Service Restaurants Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Latin America Online Grocery Market
Food Service
Halal Food and Beverages Market
Food Service
North America Online Food Delivery Market
Food Service
Commercial Cutlery Market
Food Service
Global Cafe and Bars Market
Food Service
Air Fryer Meal Kits Market
Food Service
Food Service Utensils Market
Food Service
Meal Voucher Market
Food Service
Beverage Napkins Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Vacuum Flask Market