
 Food Service Equipment Market | 2026-2036
Food Service Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Equipment Market Intelligence
The expansion of online retailers and direct sales channels is rewriting traditional procurement pathways for commercial kitchen operators. Middleby Corporation leverages its extensive brand portfolio to address varied customer needs from quick service to fine dining. Hobart Corporation sustains a strong market presence through its focus on warewashing and food preparation equipment. Electrolux Professional differentiates with its emphasis on sustainable and energy-efficient integrated kitchen systems.
Food service equipment comprises machinery designed for preparing, cooking, storing, and serving food in commercial environments. These devices, often constructed from 304-grade stainless steel for hygiene, are engineered to optimize workflow and ensure food safety. Cooking equipment constitutes the largest product segment, driven by replacement cycles and menu innovation. The Quick Service Outlets end-user category is expanding rapidly, demanding compact and multi-functional units.
Regulatory compliance is a critical barrier to entry, shaped by bodies like NSF International and national authorities. The US FDA's Food Code influences equipment design for safety, while CE marking is mandatory for market access in the European Union. These frameworks enforce standards for material safety, sanitation, and electrical performance. Future competitiveness will depend on how manufacturers integrate automation and data connectivity for predictive maintenance and operational efficiency.
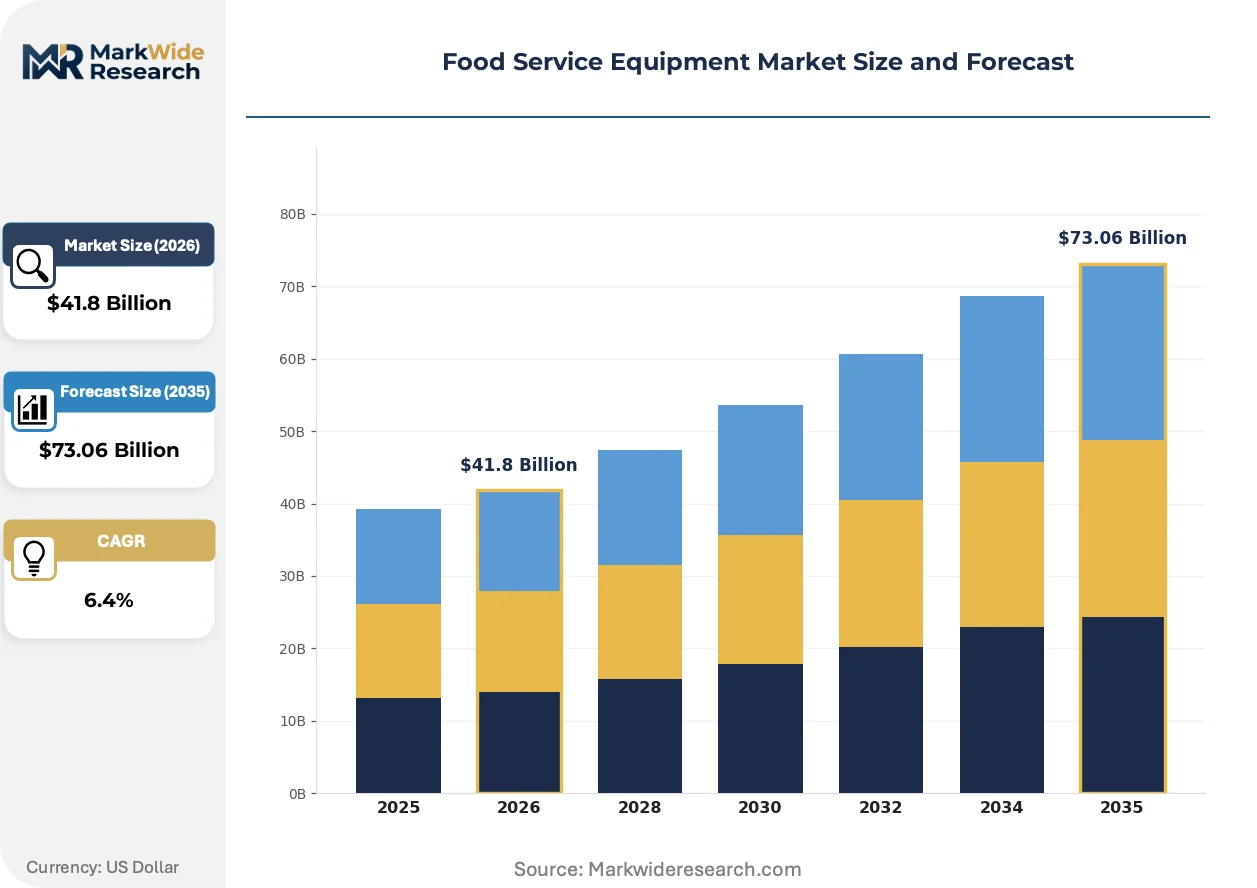
Market Dynamics
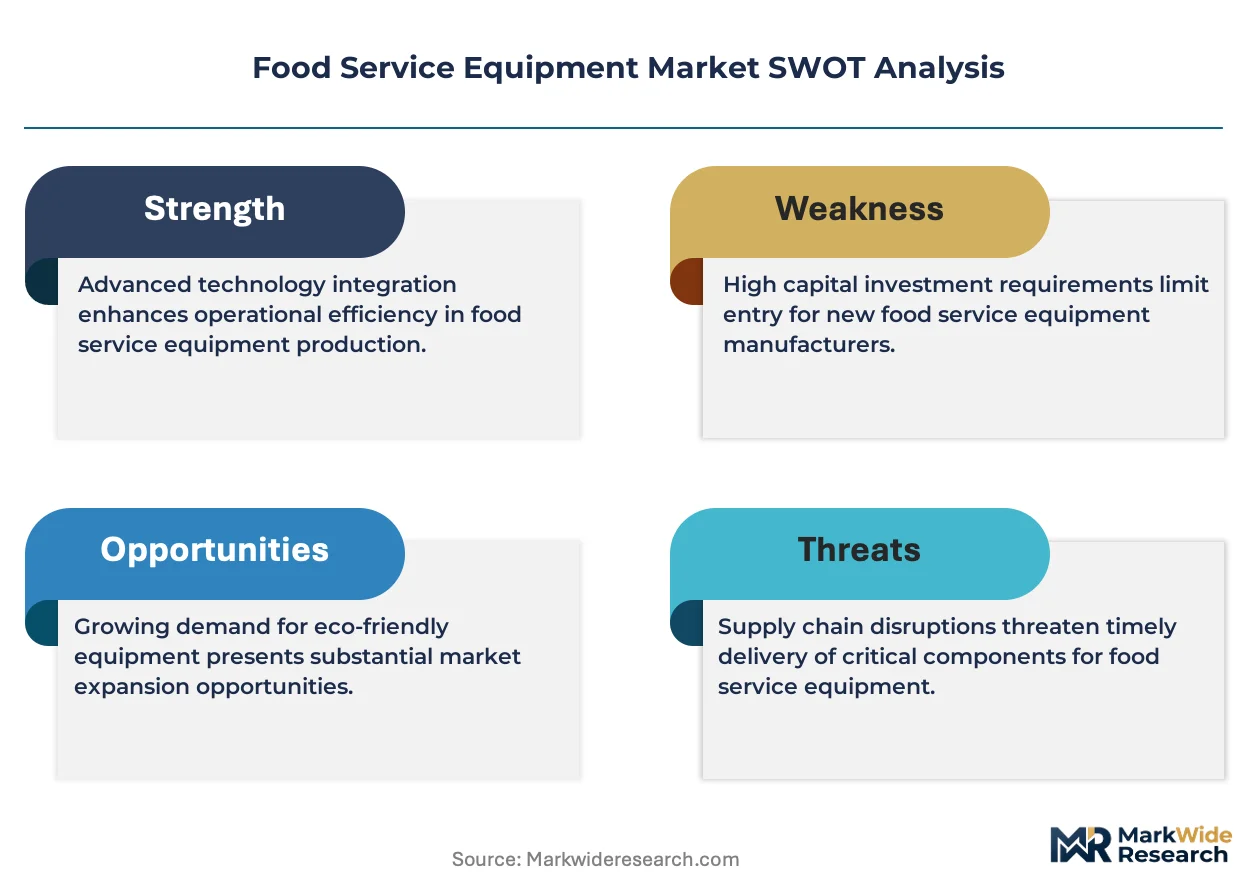
The convergence of IoT connectivity with stringent energy efficiency standards is the central force altering the food service equipment market. This dual pressure is redefining product design, compelling manufacturers to embed smart technology and comply with regulations like the US ENERGY STAR program.
Growth Catalysts
- Ghost Kitchen Proliferation:The expansion of delivery-only kitchens in urban centers requires compact, high-output equipment, creating a specific demand for multi-functional cooking units.
- Food Safety Regulation:Stricter codes from bodies like NSF International mandate equipment with advanced sanitation features, compelling operators to upgrade and driving replacement sales.
- Automation in Quick Service:Quick Service Outlets are adopting automated fryers and processors to address labor shortages, boosting demand for robotic kitchen systems.
Market Restraints
- High Capital Expenditure:The substantial upfront cost of professional-grade equipment presents a significant barrier for independent restaurants and startups.
- Input Material Volatility:Price fluctuations of 304-grade stainless steel directly impact manufacturing costs, creating pricing instability for both vendors and buyers.
- Divergent Regulatory Hurdles:Securing separate certifications like NSF in the US and CE marking in the EU adds cost and complexity, slowing market entry for new products.
Strategic Opportunities
- Emerging Market Kitchen Upgrades:Modernizing commercial kitchens in urbanizing economies across Southeast Asia and Latin America provides a substantial avenue for market expansion.
- Data-Driven Maintenance Services:Integrating IoT sensors allows manufacturers to offer subscription-based predictive maintenance, creating recurring revenue from operational data.
- Energy Efficiency Rebates:Government incentives for adopting equipment compliant with the EU's Ecodesign Directive or US ENERGY STAR standards provide a direct sales driver.
Industry Challenges
- Skilled Technician Shortage:A deficit of service technicians qualified to install and repair IoT-enabled and automated kitchen equipment constrains after-sales support capabilities.
- Legacy System Integration:Integrating new, connected appliances with older, non-digital kitchen management systems presents significant technical and operational hurdles for many operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Equipment Market |
| Market Size in 2026 | $41.8 Billion |
| Market Size in 2035 | $73.06 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooking Equipment, Refrigeration Units, Food Preparation Tools, Beverage Dispensers, Holding & Warming Devices End User: Restaurants, Catering Companies, Cafeterias, Hotels, Quick Service Outlets Application: Commercial Kitchens, Outdoor Catering, Institutional Dining, Food Trucks, Event Catering Distribution Channel: Direct Sales, Distributors, Online Retailers, Dealers, Leasing Services |
| Companies Covered | Hobart Corporation, The Vollrath Company, Ali Group Worldwide, Illinois Tool Works Inc., Dover Corporation, Middleby Corporation, HOSHIZAKI CORPORATION, Alto-Shaam, Electrolux Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Equipment Market Strategic Shifts & Innovations
Automation is fundamentally reconfiguring kitchen workflows, shifting the market's focus from standalone hardware to integrated, data-rich ecosystems. This evolution prioritizes operational efficiency, predictive analytics, and remote management capabilities over simple cooking performance.
Digital twin technology is gaining traction for modeling commercial kitchen environments. Quick Service Outlets and large hotel chains are the primary adopters, using it to simulate operational workflows before physical build-outs. This technology is virtualizing the entire kitchen design and equipment selection process, allowing for optimization of space and energy use before capital is committed.
The European Union's Ecodesign Directive is setting stricter mandatory minimum energy performance standards for professional refrigeration and cooking appliances. This framework, combined with F-Gas regulations phasing out high global warming potential refrigerants, is forcing a redesign of core product lines. Manufacturers targeting the EU market must now prioritize natural refrigerants and document energy consumption to maintain compliance.
A notable shift in acquisition models is moving from capital expenditure-heavy purchases toward subscription-based Equipment-as-a-Service (EaaS) contracts. This model disrupts traditional dealer channels by bundling hardware, maintenance, and software updates into a single operational expense. This trend is most prominent among multi-unit casual dining chains in the United States seeking predictable costs and technology flexibility.
Food Service Equipment Market Segmentation
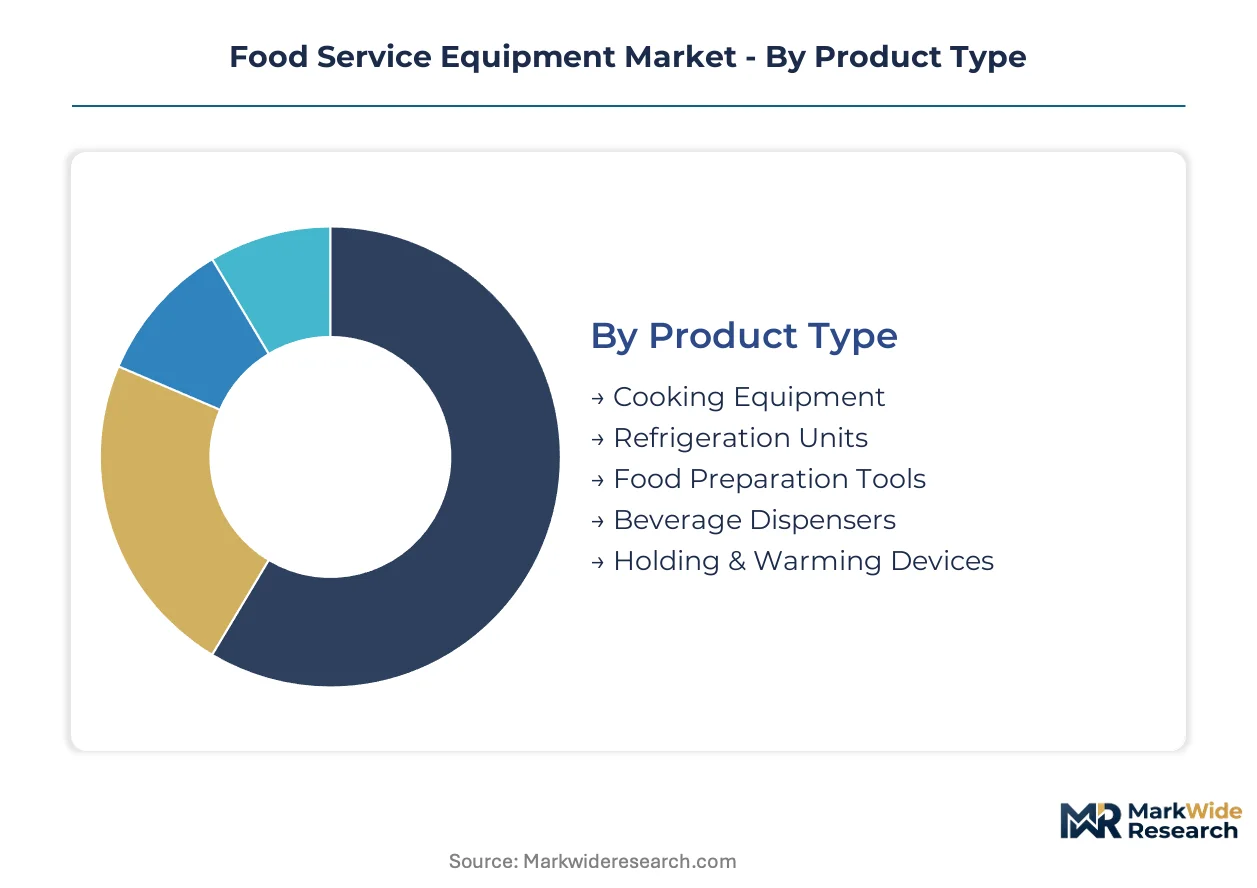
The Food Service Equipment Market comprises diverse product types and end-user requirements, necessitating granular segmentation for effective market analysis. Understanding these distinct segments allows manufacturers to tailor product development and sales strategies to specific operational needs and regulatory landscapes. This detailed breakdown highlights areas of concentrated demand and emerging growth trajectories.
Product Type:
The product type segment spans a diverse maturity spectrum, from established core machinery to rapidly evolving smart appliances.
- Cooking Equipment:This segment includes ovens, ranges, fryers, and griddles, forming the core of any commercial kitchen. Demand for cooking equipment is driven by menu innovation and regular replacement cycles.
- Refrigeration Units:Comprising commercial refrigerators, freezers, and blast chillers, these units are critical for food preservation and safety. Their design is increasingly influenced by energy efficiency standards like the US ENERGY STAR and EU F-Gas regulations.
- Food Preparation Tools:This category encompasses mixers, slicers, processors, and specialized cutting tools essential for raw ingredient handling.
- Beverage Dispensers:Equipment such as coffee machines, soda fountains, and juice dispensers serve the specific needs of drink service in various outlets.
- Holding & Warming Devices:These units, including heated cabinets and food warmers, maintain food at safe temperatures before serving.
Cooking Equipment retains volume leadership; Refrigeration Units hold the steepest expansion curve.
End User:
Customer application focus drives distinct equipment requirements across various end-user segments.
- Quick Service Outlets:These establishments prioritize compact, multi-functional, and automated equipment to maximize speed and efficiency. The proliferation of urban ghost kitchens fuels specific demand for high-output, space-saving units.
- Restaurants:This broad category includes fine dining, casual dining, and fast-casual establishments, demanding a wide range of specialized and versatile equipment. Menu diversity and operational scale define equipment choices for restaurants.
- Catering Companies:Mobility and adaptability are key for catering operations, requiring portable and robust equipment solutions.
- Cafeterias:Institutional settings like schools and hospitals operate large-scale cafeterias, focusing on high-volume production and durability.
- Hotels:Hotels integrate diverse equipment for multiple dining venues, including banquets, room service, and fine dining restaurants.
Quick Service Outlets concentrate the highest equipment volume; Hotels demand specialized multi-functional units.
Application:
Operational environments dictate equipment form factors and durability requirements within the application segment.
- Commercial Kitchens:These fixed, high-volume environments demand robust, high-performance equipment designed for continuous operation and strict food safety compliance. Workflow optimization and integration with smart systems are key considerations.
- Food Trucks:Limited space and mobility define equipment needs for food trucks, which require compact, energy-efficient, and multi-functional units. Durability against constant movement is also a factor.
- Outdoor Catering:This application necessitates portable, durable, and weather-resistant equipment capable of operating in varied external conditions.
- Institutional Dining:Large-scale operations in schools, hospitals, and corporate campuses focus on high-capacity cooking and serving equipment.
- Event Catering:Equipment for event catering balances portability with the ability to handle fluctuating demand and varied menus.
Commercial Kitchens represent a stable base; Food Trucks are gaining share fastest.
Distribution Channel:
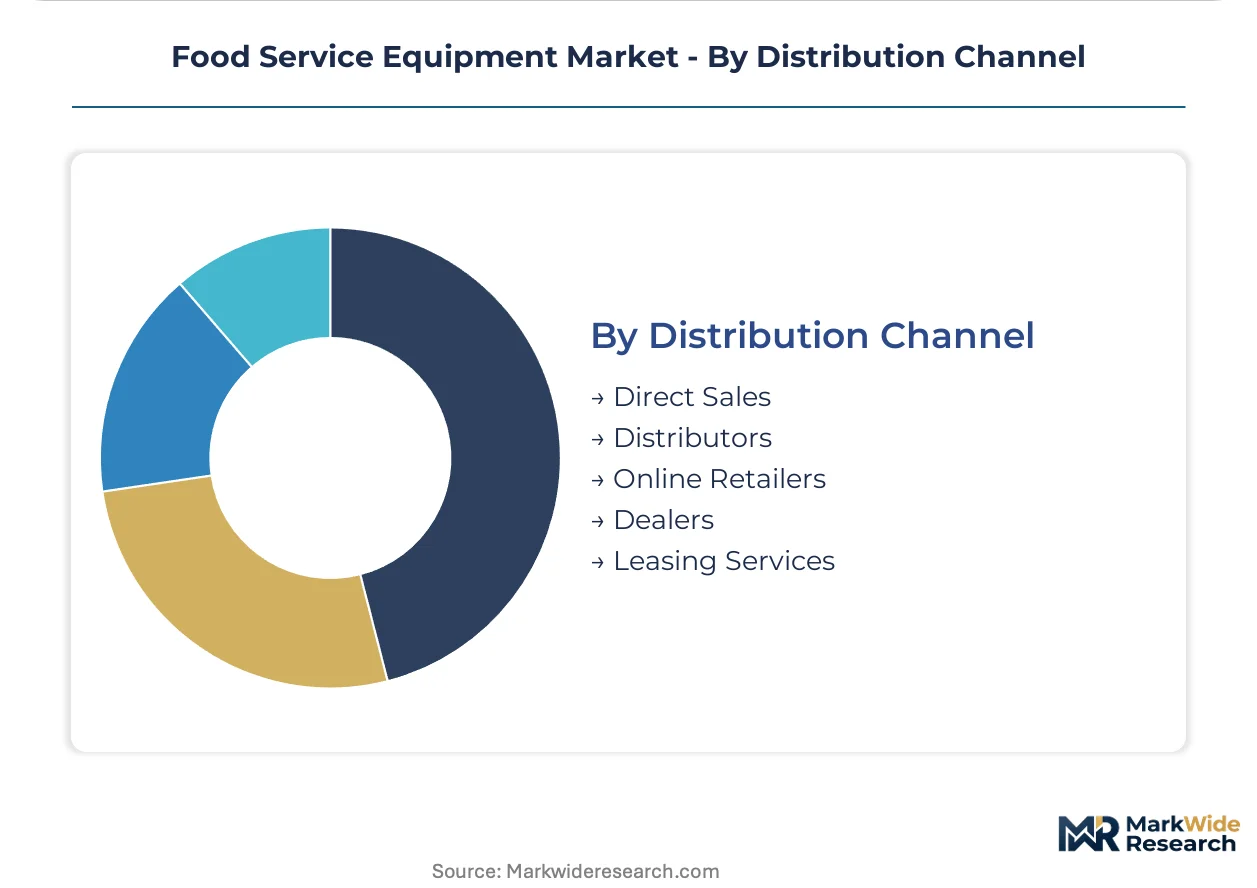
Procurement is shifting across distribution channels, reflecting evolving operator preferences and technology integration.
- Online Retailers:The expansion of online platforms is rewriting traditional procurement pathways, offering convenience and broader product access. This channel supports direct-to-operator sales and comparison shopping for commercial kitchen operators.
- Leasing Services:This acquisition model reduces high capital expenditure for operators, bundling hardware, maintenance, and software updates. Subscription-based Equipment-as-a-Service (EaaS) contracts are gaining traction, especially among multi-unit casual dining chains.
- Direct Sales:Manufacturers engage directly with large chains or institutional buyers for customized solutions and volume purchases.
- Distributors:These intermediaries provide a wide array of products, logistics, and regional support to various commercial clients.
- Dealers:Local dealers often offer installation, maintenance, and personalized service to independent restaurants and smaller businesses.
Distributors maintain a mature market presence; Online Retailers exhibit a steep growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry often favors manufacturers in the United States due to established brand loyalty, while European markets experience intense competition from cost-effective Asian imports. Urbanization and the expansion of organized food service drive equipment demand across major global economies. Regulatory frameworks significantly influence product design and market entry requirements in each region.
United States
Ghost kitchen proliferation and quick service automation drive demand for compact, high-output equipment in the United States. The US ENERGY STAR program encourages energy-efficient appliance adoption through various incentives. Cities like New York City and Los Angeles see significant investment in multi-functional cooking units for delivery-centric models.
China
China's rapid expansion of food service chains creates substantial demand for commercial kitchen upgrades and new installations. GB standards regulate food contact materials and electrical safety for all equipment sold in the country. Metropolitan areas such as Shanghai and Beijing are centers for automated kitchen system deployment.
Germany
Germany's market prioritizes energy-efficient, integrated kitchen systems, reflecting strong sustainability mandates. The EU's Ecodesign Directive enforces strict minimum energy performance standards for professional appliances across Europe. Bavarian manufacturing hubs lead in precision-engineered solutions for commercial refrigeration and cooking equipment.
India
Modernizing commercial kitchens in India's urbanizing economies represents a significant market expansion opportunity. The FSSAI (Food Safety and Standards Authority of India) guidelines influence hygiene and material safety standards for food preparation equipment. Bengaluru and Mumbai are experiencing upgrades in catering and restaurant equipment to meet evolving consumer expectations.
Brazil
Brazil's growing out-of-home dining sector and quick service expansion fuel demand for robust and versatile food service equipment. ANVISA (National Health Surveillance Agency) establishes rigorous safety and sanitation standards for all commercial kitchen appliances. São Paulo's hospitality sector is increasingly adopting advanced food preparation tools for diverse culinary offerings.
Food Service Equipment Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical sub-assemblies. The market structure exhibits a tiered consolidation, with a few global players offering comprehensive solutions alongside numerous niche specialists. Strategic archetypes include integrated solution providers, specialized equipment manufacturers, and regional distributors. Competitive moves often involve portfolio diversification through mergers and acquisitions or technology integration for smart features.
Integrated solution providers, such as Middleby Corporation, exemplify a strategy of addressing varied customer needs from quick service to fine dining through extensive brand portfolios. Hobart Corporation represents a specialized approach, sustaining strong market presence through its focus on warewashing and food preparation equipment. Ali Group Worldwide anchors a broad range of equipment offerings, serving diverse segments of the global food service industry.
| Leading Market Players |
|---|
| Hobart Corporation |
| The Vollrath Company |
| Ali Group Worldwide |
| Illinois Tool Works Inc. |
| Dover Corporation |
| Middleby Corporation |
| HOSHIZAKI CORPORATION |
| Alto-Shaam |
| Electrolux Professional |
| Others |
Cost & Logistics Intelligence
Volatile 304-grade stainless steel prices, a critical upstream input, directly influence manufacturing costs, impacting equipment pricing across the food service sector. This input volatility shifts margin pressure toward equipment producers and end-users, affecting investment in new technologies.
Pricing Analysis
Pricing for configured-to-order integrated kitchen systems commands a premium over standard, off-the-shelf units. The dominant model blends per-unit transactional sales with emerging subscription-based Equipment-as-a-Service contracts. Price differentiation stems from regulatory compliance, such as NSF certification, brand premium, and bundled after-sales service. Pricing softness stems from intense competition, particularly from cost-effective Asian imports, with independent restaurants exhibiting the highest price sensitivity.
Supply Chain Analysis
Raw material sourcing for food service equipment heavily relies on global supplies of 304-grade stainless steel, IoT sensors, and microcontrollers. Key manufacturing centers for these inputs include China, Germany, and parts of the United States. The market's supply chain is vulnerable to commodity price volatility, particularly for stainless steel, alongside potential logistics chokepoints. Distribution runs through a fragmented network of distributors, dealers, and increasingly, online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food service equipment market is in an early-cycle expansion phase, driven by the accelerating proliferation of urban ghost kitchens. This tailwind creates significant opportunities for innovative equipment solutions and service models.
For Market Incumbents: Insulate core market share by deepening vertical integration into critical component manufacturing, mitigating input volatility. Invest in robust IoT platform development to counter the threat from agile, tech-focused entrants. Leverage existing extensive dealer networks for enhanced after-sales support and predictive maintenance services. Prioritize certification investment for new product lines to maintain regulatory advantage.
For New Entrants and Emerging Players: Underpenetration in Southeast Asian urbanizing economies presents a significant white-space opportunity. Target multi-unit casual dining chains in the United States with subscription-based Equipment-as-a-Service models. Focus on compact, multi-functional units for Quick Service Outlets, leveraging digital twin technology for optimized kitchen design. A go-to-market strategy emphasizing operational efficiency and predictable costs will resonate.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated solution providers with strong IoT platforms and established global service networks. The market demonstrates long-term viability, driven by automation, energy efficiency mandates, and ghost kitchen expansion. Seek specialized equipment manufacturers offering unique automation or sustainable refrigeration technologies. The signal to watch for inflection is the sustained quarter-over-quarter growth in Equipment-as-a-Service contract values.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Development | Enhances predictive maintenance capabilities, optimizing operational efficiency for commercial kitchens. |
| Energy Star Certification | Boosts sales and adoption rates in the United States due to government incentives. |
| Ecodesign Directive Compliance | Ensures critical market access and competitive differentiation within the European Union. |
| Ghost Kitchen Equipment Line Expansion | Addresses specific demand for compact, high-output units in urban centers for delivery-only models. |
| Subscription-based Equipment-as-a-Service Launch | Shifts the revenue model from capital expenditure to operational expense for multi-unit casual dining chains. |
Research Approach
The analysis maps cooking equipment, refrigeration units, and food preparation tools, each validated through extensive interviews with commercial kitchen operators. Primary research involved discussions with equipment manufacturers, distribution channel partners, and regulatory compliance officers. Secondary data sources included company annual reports, industry association publications, and government regulatory documents. This approach ensured robust bottom-up and top-down triangulation of market insights.
Assumptions regarding economic growth and regulatory stability were held fixed across the analysis window, while technological adoption rates varied. The model segmented data by product type, end-user, application, and distribution channel. Compound annual growth rates were derived from historical trends and projected technological shifts in automation. Key forecast inputs included ghost kitchen expansion rates and IoT integration costs.
Practitioners should monitor shifts in raw material prices and regulatory updates for early signals of market revision. Forecasts reflect underlying assumptions, but input material volatility and geopolitical trade policies represent key risk factors. Quarterly review of stainless steel prices and new energy efficiency mandates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Used Commercial Kitchen Equipment Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Prepared Food Equipment Market
Food Service Equipment
Commercial Electric Restaurant Ranges Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
North America Countertop Ice Makers Market