
 New Zealand Foodservice Market | 2026-2036
New Zealand Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Foodservice Market Foresight
Market Context
Plant-based proteins are pivoting away from traditional meat inputs across New Zealand's commercial kitchen procurement. Restaurant Brands New Zealand Ltd leverages its multi-brand portfolio to secure supply chain efficiencies across Pizza Hut, KFC, and Carl's Jr. operations. McDonald's Corporation sustains dense outlet coverage in Auckland's metropolitan corridor, while Domino's Pizza Inc specializes in digital-first ordering infrastructure that captures delivery-centric households.
Technical Definition and Segment Structure
New Zealand foodservice encompasses all commercial establishments preparing meals for immediate consumption away from home, spanning quick-service counters through full-table-service venues with standardized HACCP temperature controls and MPI-registered food control plans. Full-Service Restaurants and Fast Casual formats anchor the service type dimension, with Fast Casual capturing weekday lunch traffic from professionals in Christchurch and Dunedin. The distribution channel structure shows Delivery and Online Orders gaining transaction velocity as third-party platforms deepen penetration into suburban markets, while Dine-In retains margin concentration in premium tourism corridors.
Regulatory Environment
Ministry for Primary Industries food act regulations and registered food control plan obligations shape operator compliance costs and kitchen capital requirements across all sixteen New Zealand regions. Health and safety standards administered by WorkSafe New Zealand enforce staff training protocols that influence labor scheduling and front-of-house productivity benchmarks. Stakeholders must monitor how MPI's evolving allergen labeling mandates and proposed container return scheme legislation will reshape packaging procurement and menu transparency obligations.
Market Dynamics
Digital ordering infrastructure and third-party delivery platforms are compressing traditional dine-in margins while redistributing transaction volume toward suburban and commuter corridors across New Zealand's major metropolitan areas.
Growth Catalysts
- WorkSafe New Zealand training mandates:Standardized staff certification protocols are elevating operational professionalism across quick-service and full-service formats, reducing insurance premiums and liability exposure for compliant operators.
- Plant-based protein R&D pipelines:Domestic food technology ventures are developing textured vegetable proteins calibrated for commercial kitchen equipment, expanding menu engineering possibilities beyond traditional meat suppliers.
- Queenstown-Auckland tourism corridor:International visitor dining expenditure is concentrating in premium full-service venues, driving equipment upgrade cycles and specialized labor recruitment in these geographies.
Market Restraints
- Dairy and meat input cost volatility:Fonterra commodity price fluctuations and livestock supply constraints are compressing menu margin stability for protein-centric operators.
- Commercial refrigeration supply concentration:Equipment procurement depends on limited Australasian distributor networks, extending lead times for HACCP-compliant cold chain infrastructure.
- Substitution by meal-kit direct delivery:Prepared ingredient boxes are capturing household dinner occasions previously served by casual dining formats, particularly in Wellington and Christchurch suburbs.
Strategic Opportunities
- MPI food control plan digitization:Cloud-based compliance documentation platforms are creating first-mover advantages for operators seeking to streamline audit preparation and reduce administrative labor.
- Canterbury region underserved corridors:Rolleston and Lincoln satellite communities lack quick-service density relative to population growth, presenting greenfield site development potential.
- Contactless payment and kitchen display integration:Converging point-of-sale and back-of-house workflow technologies are reducing order error rates and labor coordination friction during peak service windows.
Industry Challenges
- Certified chef skill scarcity:Immigration policy constraints and training pipeline gaps are limiting qualified kitchen management availability, forcing wage inflation and retention investment.
- Container return scheme compliance preparation:Anticipated packaging stewardship obligations are requiring operational redesign and supplier contract renegotiation ahead of formal implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Foodservice Market |
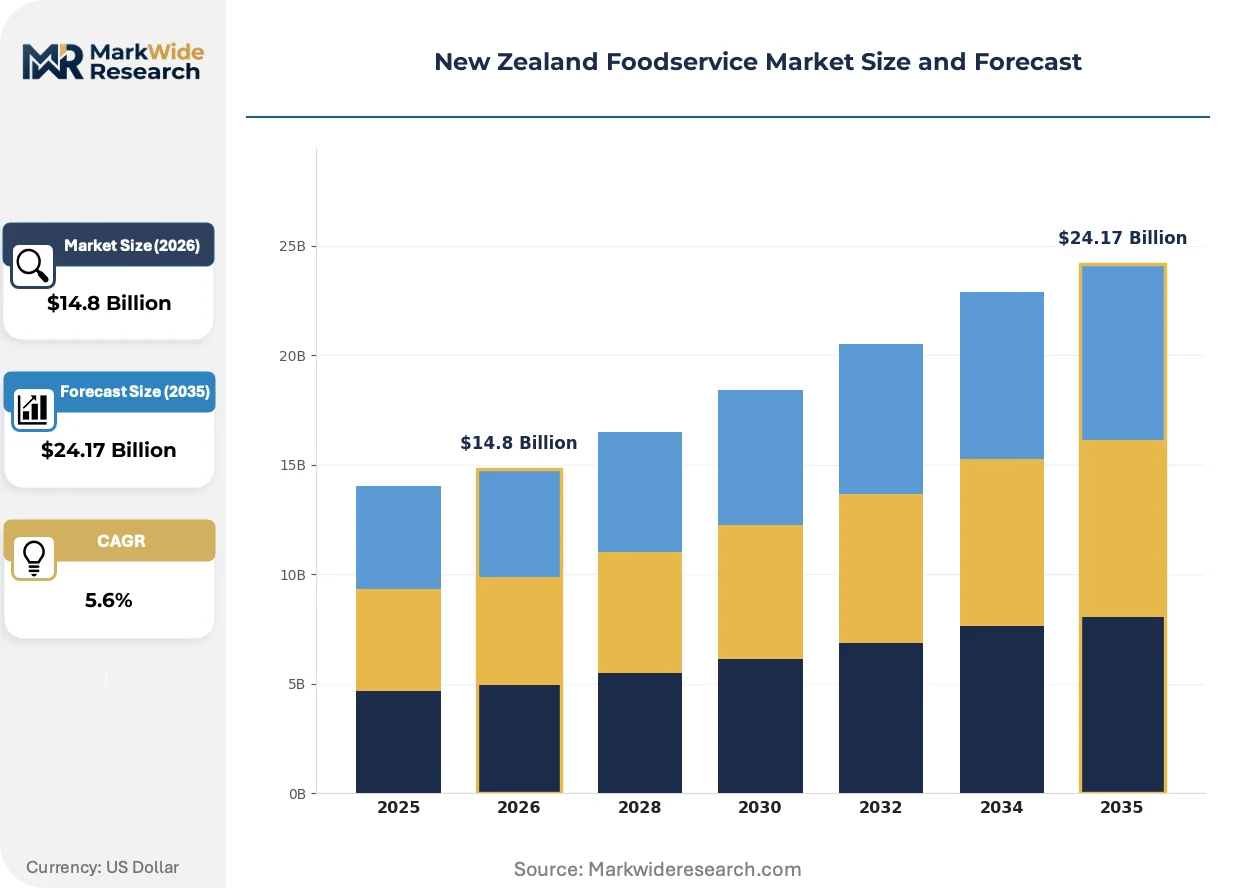
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Casual, Cafés, Catering Customer Type: Families, Students, Professionals, Tourists Food Category: Vegetarian, Gluten-Free, Organic, Locally Sourced Distribution Channel: Dine-In, Takeaway, Delivery, Online Orders |
| Companies Covered | BurgerFuel Group Ltd, Subway, Restaurant Brands New Zealand Ltd, Burger King NZ, Hell Pizza, McDonald's Corporation, Starbucks Corporation, Wendy's Hamburgers NZ, Domino's Pizza Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Foodservice Market Shifts & Advancements
Automation and data-driven inventory management are compressing labor dependency while reshaping how New Zealand foodservice operators configure kitchen workflows and supplier relationships.
Cloud-based kitchen display systems are consolidating order routing across dine-in, delivery, and aggregator channels into unified preparation queues. Mid-size quick-service operators in Auckland and Wellington are adopting these platforms fastest, replacing paper ticket systems within eighteen-month upgrade cycles. This consolidation is compressing front-of-house coordination labor and reducing order completion variance during peak traffic periods.
MPI's evolving allergen labeling mandates are forcing ingredient disclosure granularity beyond current menu formatting standards. Full-service restaurants face the steepest compliance redesign costs, reconfiguring point-of-sale interfaces and kitchen prep protocols to capture cross-contamination risks. Premium tourism venues in Queenstown and Rotorua are responding earliest, viewing transparent allergen communication as competitive differentiation for international visitors.
Subscription-based equipment maintenance is displacing break-fix service relationships for refrigeration and cooking infrastructure. National multi-site operators are consolidating vendor relationships around predictive monitoring contracts that guarantee uptime thresholds. This shift is most visible among quick-service franchise networks seeking to standardize performance across Auckland, Christchurch, and Dunedin metropolitan clusters.
New Zealand Foodservice Market Segmentation
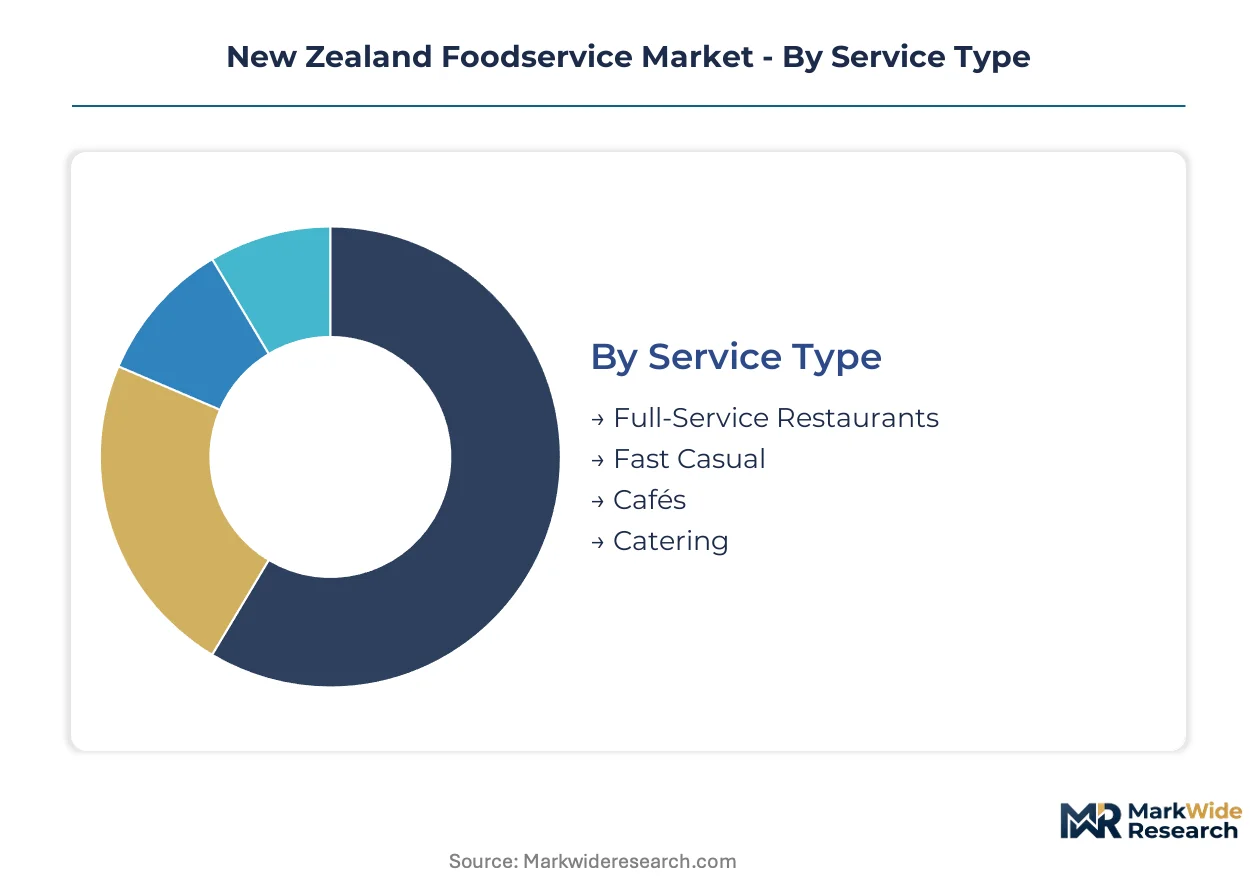
New Zealand foodservice operators configure distinct operational models, customer targeting, and supply protocols across each segmentation dimension. Understanding these divides reveals where capital deployment concentrates and where margin structures diverge most sharply.
Service Type:
Standardization dominates quick formats while full-service venues retain customization latitude across menu engineering and service protocols.
- Full-Service Restaurants:Table-service venues with dedicated front-of-house staff and kitchen brigade structures. Demand concentrates in Queenstown and Auckland's premium tourism corridors where international visitors sustain higher per-cover expenditure and extended dining occasions.
- Fast Casual:Counter-service formats with elevated ingredient transparency and limited table service. Weekday lunch traffic from Wellington and Christchurch professionals drives volume, with MPI food control plan compliance costs factored into standardized operational templates.
- Cafés:Beverage-forward operations with limited food preparation. Morning commuter density in Auckland's central business district and Dunedin's university precincts shapes site selection.
- Catering:Off-premise meal production for events and institutions. Corporate contracts in Wellington's government precinct and conference venues in Rotorua anchor revenue stability.
Most installed capacity flows through Full-Service Restaurants. Expansion is steepest in Fast Casual.
Customer Type:
Volume scales with household size while spend per visit tracks disposable income and occasion formality.
- Families:Multi-cover occasions with dietary accommodation requirements. Suburban Auckland and Christchurch locations with parking infrastructure and children's menu options capture recurring weekend traffic.
- Students:Price-sensitive demand concentrated around University of Otago, University of Auckland, and Victoria University of Wellington campuses. Value-oriented formats with digital ordering integration dominate.
- Professionals:Time-constrained weekday demand seeking speed without quality compromise. Wellington's central business district and Auckland's metropolitan corridor show highest transaction frequency.
- Tourists:International visitors with currency advantage and experience-seeking behavior. Queenstown, Rotorua, and Auckland's waterfront precincts concentrate spend in premium-positioned venues.
Professionals generate the highest transaction velocity. Tourists deliver the steepest per-visit spend expansion.
Food Category:
Ingredient sourcing transparency and dietary accommodation create tiered procurement cost structures across operator portfolios.
- Vegetarian:Plant-forward menu engineering excluding meat proteins. Fast Casual operators in Wellington and Auckland adopt these specifications fastest to capture professional commuter segments.
- Gluten-Free:Celiac-safe preparation protocols with cross-contamination controls. Full-Service Restaurants in tourism corridors invest in dedicated equipment to serve international visitors with dietary restrictions.
- Organic:Certified ingredient procurement with supply chain documentation. Premium-positioned cafés and full-service venues in Auckland and Christchurch differentiate through this positioning.
- Locally Sourced:Domestic supplier relationships with shortened logistics chains. MPI food safety modernization incentivizes traceability investments that align with this category's requirements.
Locally Sourced commands the broadest operator adoption. Gluten-Free shows the steepest compliance-driven investment trajectory.
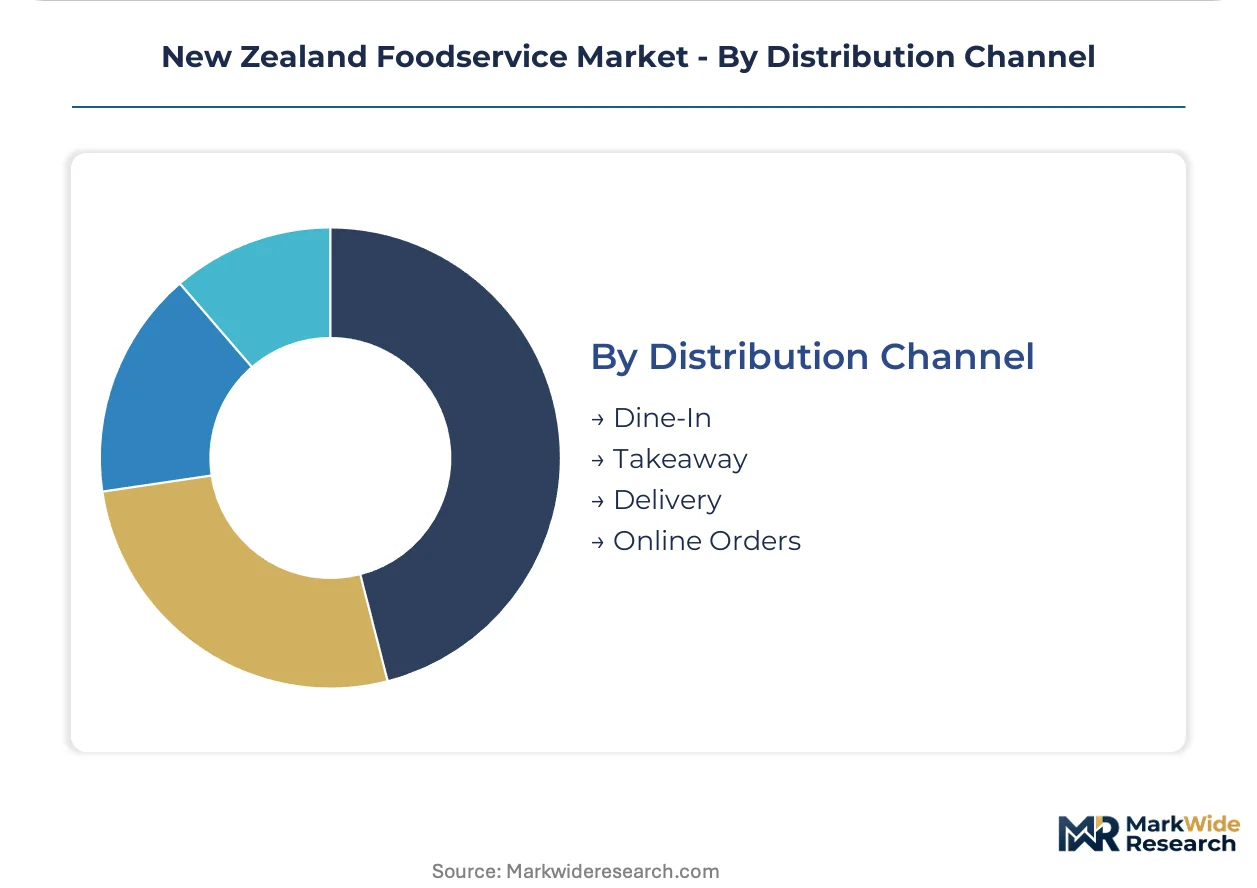
Distribution Channel:
Channel mix determines kitchen workflow design, labor scheduling, and real estate requirements with diverging margin profiles.
- Dine-In:On-premise consumption with full service or self-service models. Tourism corridors in Queenstown and Rotorua retain margin concentration here despite channel share erosion elsewhere.
- Takeaway:Counter collection with packaging and timing coordination. Suburban quick-service locations across Auckland and Christchurch optimize production workflows for this channel.
- Delivery:Third-party platform or in-house courier fulfillment. Wellington and Auckland metropolitan areas show deepest platform penetration with compressed operator margins offset by volume scaling.
- Online Orders:Digital-first transaction origination with scheduled pickup or delivery. Fast Casual formats invest in proprietary app infrastructure to reduce aggregator dependency.
Dine-In retains the highest margin per transaction. Delivery is gaining share fastest in metropolitan clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland's metropolitan corridor anchors foodservice transaction volume through dense quick-service outlet coverage and professional commuter density. The Ministry for Primary Industries' food safety modernization is prompting equipment upgrades and compliance investments across all sixteen regions.
Auckland Region
Tourism expenditure and corporate dining contracts drive premium full-service venue development along the waterfront and central business district. WorkSafe New Zealand training mandates are elevating operational standards across quick-service franchise networks. The metropolitan corridor shows steepest adoption of cloud-based kitchen display systems and third-party delivery platform integration.
Wellington Region
Government precinct proximity sustains catering contract stability and weekday lunch traffic from professional segments. MPI food control plan digitization is creating first-mover compliance advantages for operators investing in cloud-based documentation platforms. The central business district concentrates fast casual formats optimized for time-constrained commuter demand.
Canterbury Region
Christchurch metropolitan recovery and satellite community growth in Rolleston and Lincoln are outpacing quick-service density. Health and safety standards administered by WorkSafe New Zealand influence labor scheduling protocols across reopened and newly developed venues. The region presents greenfield site development potential relative to population expansion rates.
Otago Region
University of Otago student enrollment sustains value-oriented format demand with digital ordering integration requirements. The country's national food safety regulator's evolving allergen labeling mandates are forcing menu redesign and point-of-sale reconfiguration. Dunedin's campus precinct and Queenstown's tourism corridor represent divergent operational models within the same regional boundary.
Bay of Plenty Region
Rotorua international visitor concentration drives premium full-service investment in transparent allergen communication and specialized labor recruitment. Domestic supplier relationship requirements under MPI traceability incentives align with locally sourced menu positioning strategies. The tourism corridor shows earliest compliance redesign investment among premium-positioned venues.
New Zealand Foodservice Market Competitive Landscape
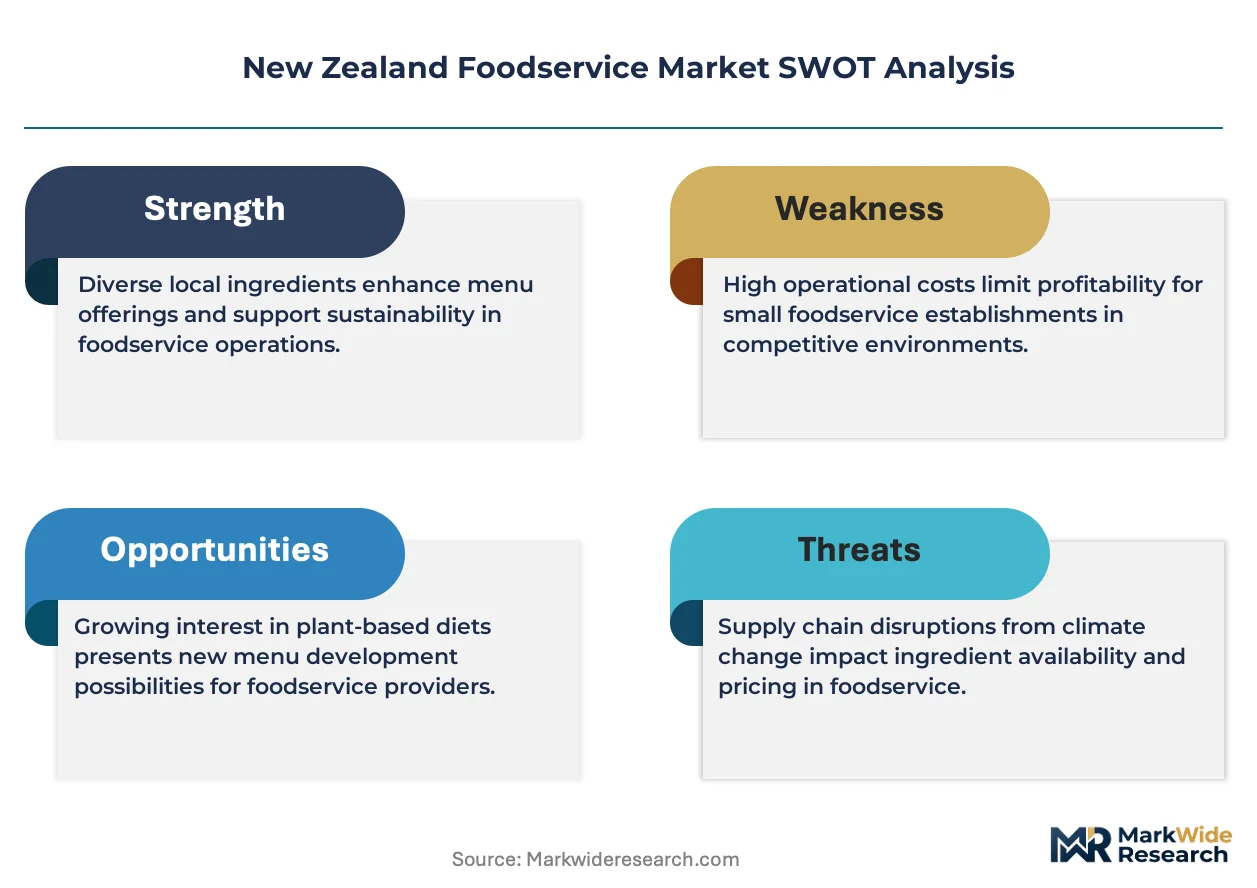
Global majors compete with regional champions across brand portfolio breadth and digital infrastructure depth. The market structure shows consolidated quick-service segments alongside fragmented full-service and fast casual tiers. Three archetypes dominate: multi-brand portfolio operators leveraging supply chain scale, single-brand specialists optimizing digital-first customer acquisition, and tourism-corridor premium venues emphasizing experience differentiation. Competitive moves concentrate on kitchen equipment modernization responding to MPI compliance mandates and third-party delivery platform negotiation strategies protecting margin structures.
Within the multi-brand portfolio tier, Restaurant Brands New Zealand Ltd exemplifies supply chain efficiency aggregation across Pizza Hut, KFC, and Carl's Jr. operations. McDonald's Corporation anchors global-scale density in Auckland's metropolitan corridor. Domino's Pizza Inc represents digital-first ordering infrastructure specialization capturing delivery-centric household segments.
| Leading Market Players |
|---|
| BurgerFuel Group Ltd |
| Subway |
| Restaurant Brands New Zealand Ltd |
| Burger King NZ |
| Hell Pizza |
| McDonald's Corporation |
| Starbucks Corporation |
| Wendy's Hamburgers NZ |
| Domino's Pizza Inc |
| Others |
Supply & Pricing Matrix
MPI's proposed container return scheme legislation gates qualified supply access and premium-tier pricing authorization for foodservice operators across New Zealand. Compliance-ready packaging vendors command tier-one procurement relationships while non-compliant suppliers face exclusion from major quick-service and full-service contracts.
Pricing Analysis
Input-cost pass-through from Fonterra dairy commodity fluctuations and livestock supply constraints compresses menu margin stability for protein-centric operators. Three-tier pricing structure across premium, standard, and economy levels separates tourism-corridor full-service venues from suburban quick-service formats and value-oriented student precincts. Price differentiation hinges on MPI food control plan certification status and allergen-labeling compliance investment. Pricing pressure stems from third-party delivery platform commission structures that extract 15-30% per transaction. Students exhibit highest price sensitivity; tourists demonstrate lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in Australian and Chinese manufacturing geographies extend lead times for HACCP-compliant commercial refrigeration and kitchen display systems. Equipment procurement draws from concentrated Australasian distributor networks with limited domestic assembly capacity. Raw material dependencies center on stainless steel fabrication inputs, compressor assemblies, and digital control modules. Single-source vulnerability pervades specialized cold-chain infrastructure where replacement parts require trans-Tasman shipping coordination. Distribution runs through national equipment distributors serving Auckland, Wellington, and Christchurch metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand foodservice represents a late-cycle quality story as international visitor dining expenditure concentrates in premium full-service venues with transparent allergen communication and specialized labor recruitment.
For Market Incumbents: Lock in cloud-based kitchen display system deployments across multi-site networks to compress labor coordination friction and reduce order completion variance during peak traffic windows. Deepen backward integration into domestic plant-based protein R&D pipelines to secure supply chain efficiencies ahead of commodity volatility. MPI food control plan digitization creates first-mover compliance advantages worth defending through sustained IT investment. For New Entrants and Emerging Players: Enter via Canterbury Region satellite communities in Rolleston and Lincoln where quick-service density lags population growth rates. Target fast casual formats optimized for weekday lunch traffic from Wellington and Christchurch professionals with time-constrained demand. Deploy proprietary app infrastructure to reduce aggregator dependency and capture direct customer relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional fast casual chains because fragmented ownership structures and standardized operational templates enable margin expansion through procurement consolidation and shared compliance infrastructure. Five-to-ten year viability hinges on tourism corridor recovery trajectory and MPI regulatory implementation pace. Monitor third-party delivery platform contract renegotiation cycles as inflection indicator for operator margin restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Equipment Modernization | MPI food safety modernization mandates drive HACCP-compliant cold chain upgrades nationwide. |
| Cloud-Based Compliance Digitization | Documentation platforms streamline audit preparation and reduce administrative labor costs. |
| Plant-Based Menu Engineering | Domestic R&D pipelines expand procurement options beyond traditional meat suppliers. |
| Aggregator Independence Programs | Proprietary app infrastructure reduces third-party platform commission extraction. |
| Tourism Corridor Premium Positioning | Queenstown and Rotorua venues differentiate through transparent allergen communication. |
Research Methodology
Coverage spans Auckland, Wellington, Canterbury, Otago, and Bay of Plenty regions, with primary inputs from each. The analysis combines structured interviews with quick-service franchise operations directors, full-service restaurant group executives, commercial kitchen equipment distributors, and MPI compliance officers with secondary validation. Secondary sources include WorkSafe New Zealand training mandate documentation, MPI food control plan registration databases, tourism expenditure statistics, and customs records for imported equipment. Bottom-up outlet density modeling triangulates against top-down regional consumption estimates.
Rate-of-change decomposition separates volume growth from mix-shift and pricing components across the projection horizon. The analytical framework models service type, customer segment, food category, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs derive from fitted trend extrapolation adjusted for policy implementation timelines and tourism recovery patterns. Forecast inputs incorporate MPI allergen labeling mandate compliance cost curves and third-party delivery platform penetration saturation thresholds.
Inputs from MPI registration databases and tourism expenditure surveys were available through the study window; gaps in real-time equipment procurement cost indices introduce uncertainty bands around capital expenditure forecasts. Forecasts reflect documented assumptions regarding regulatory implementation pace and international visitor recovery trajectory. Material deviation in MPI container return scheme legislation timing or Fonterra commodity price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food & Beverage in Asia Market
Food Service
Mexico Foodservice Market
Food Service
Food Away from Home Market
Food Service
India Full Service Restaurants Market
Food Service
Personal Chef Services Market
Food Service
GCC Food Service Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Germany Foodservice Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Italy Foodservice Market
Food Service
Meal Kit Delivery Services Market
Food Service
Cambodia Foodservice Market
Food Service
Philippines Quick Service Restaurants Market
Food Service
Benelux Foodservice Market
Food Service
Food Service Pasta Market