
 Commercial Griddle Market | 2026-2036
Commercial Griddle Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Griddle Market Analysis
Aftermarket service revenue is reconfiguring margin capture across the commercial griddle value chain. Middleby Corporation leverages its extensive service network to lock in multi-year maintenance contracts with chain operators. Illinois Tool Works anchors its position through proprietary temperature control technologies that reduce operator error. The Vollrath Company specializes in compact countertop configurations for constrained kitchen footprints.
A commercial griddle is a flat metal cooking surface, typically constructed from polished steel or chrome over aluminum heat spreaders, heated by gas burners or electric elements to temperatures between 300°F and 450°F for searing proteins and preparing breakfast items in high-volume foodservice environments. Gas griddle configurations retain dominant placement in legacy restaurant infrastructure where natural gas hookups pre-exist, while electric griddle demand accelerates in food trucks and catering operations where portability and ventless operation override thermal response preferences. Built-in installations command premium positioning within new-construction commercial kitchens, whereas countertop formats address retrofit demand across aging cafeteria and institutional facilities.
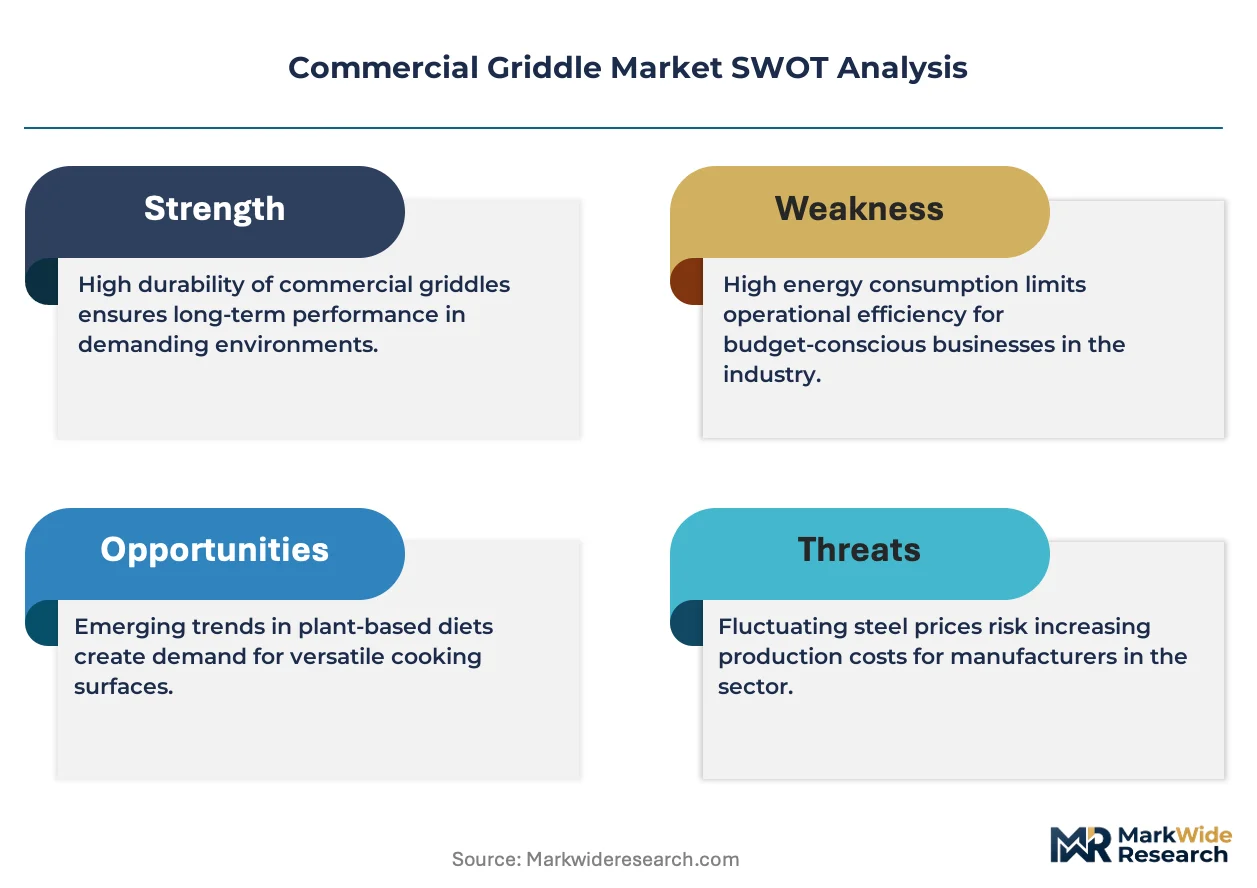
The U.S. Department of Energy mandates minimum cooking efficiency standards for commercial griddles, compelling manufacturers to redesign burner geometry and insulation packages. NSF International certification requirements govern food-contact surface safety and cleanability, filtering non-compliant imports from price-sensitive procurement channels. Stakeholders must monitor emerging electrification mandates in California and New York that threaten to strand gas-powered equipment investments before end-of-useful-life.
Market Dynamics
The U.S. Department of Energy's tightening efficiency mandates are forcing burner geometry redesigns across gas griddle portfolios while electrification mandates in California and New York accelerate equipment replacement cycles.
Growth Catalysts
- Full-service restaurant chain expansion:National operators are adding dedicated griddle lines to capture breakfast dayparts and smash-burger formats, driving equipment procurement across new-build locations.
- EPA commercial cooking efficiency standards:Federal minimums for thermal efficiency are compelling operators to retire legacy equipment ahead of depreciation schedules.
- Fast-casual kitchen reconfiguration:Texas and California operators are retrofitting compact electric griddles into existing ventilation-constrained footprints.
Market Restraints
- Stainless steel input volatility:Grade 304 and 430 sheet pricing fluctuations compress manufacturer margins on quoted projects with extended delivery windows.
- Gas infrastructure lock-in:Pre-existing natural gas hookups in legacy restaurant infrastructure delay electric conversion economics despite operating cost advantages.
- NSF certification timeline:Food-contact surface testing and cleanability validation extends new product introduction cycles by 8-14 months for imported equipment.
Strategic Opportunities
- Ventless electric penetration:Food trucks and catering operations without fixed exhaust infrastructure represent underserved demand for portable, code-compliant equipment.
- Aftermarket service bundling:Multi-year maintenance contracts with temperature calibration and surface restoration lock in recurring revenue from chain operators.
- California electrification mandates:Local building codes prohibiting new gas connections in commercial construction create captive demand for electric griddle specifications.
Industry Challenges
- Cross-trained technician scarcity:Simultaneous competency in gas combustion systems and electric control diagnostics limits service network expansion.
- Legacy control integration:Proprietary temperature management protocols from established manufacturers complicate third-party automation and kitchen management system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Griddle Market |
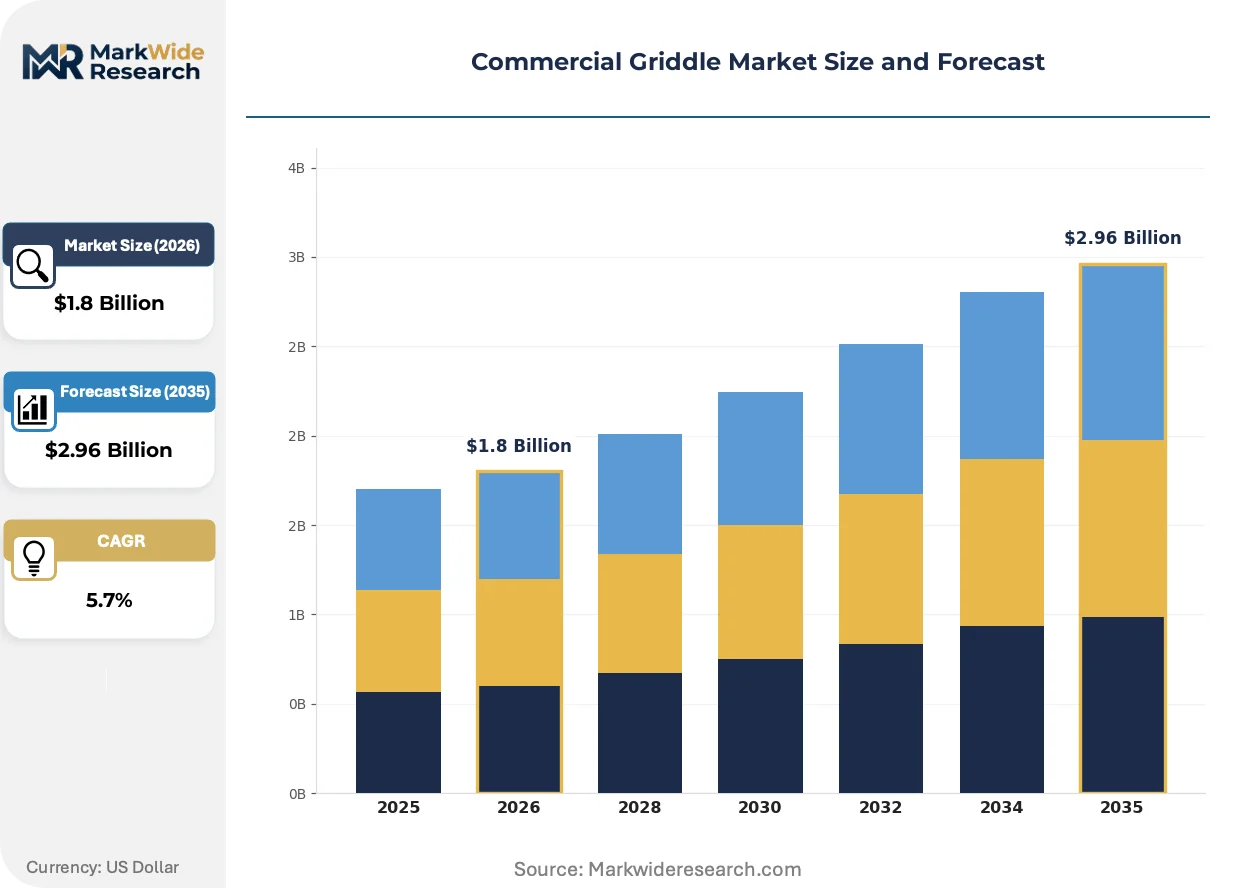
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Top Griddle, Gas Griddle, Electric Griddle, Charbroiler End User: Restaurants, Food Trucks, Catering Services, Cafeterias Size: Small, Medium, Large, Extra Large Installation: Built-in, Portable, Countertop, Freestanding |
| Companies Covered | Electrolux, Illinois Tool Works, Middleby Corporation, Welbilt, The Vollrath Company, Ali Group, AccuTemp Products, Standex International Corporation, ELAG Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Griddle Market Emerging Trajectories
Equipment architecture is bifurcating between precision electric systems for new construction and ruggedized gas configurations for retrofit markets, with control intelligence becoming the primary differentiation vector.
Chromed steel cooking surfaces with embedded thermocouple arrays are collapsing the performance gap between gas and electric thermal response. Fast-casual chains in California are specifying chrome-over-aluminum configurations for consistent sear marks across high-volume protein production. This specification shift is collapsing the historical advantage of gas burners in recovery time metrics.
The EPA's commercial cooking equipment standards are mandating minimum idle energy rates and cooking energy efficiency thresholds. Manufacturers are redesigning insulation packages and burner geometry to maintain surface uniformity at reduced input levels. Gas griddle portfolios face the steepest redesign burden, particularly for legacy cast-iron burner configurations.
Chain procurement teams are consolidating vendor relationships around equipment-agnostic service providers. Independent restaurant operators are shifting from transactional parts purchasing to subscription-based maintenance plans covering surface refinishing and control calibration. This behavioral shift is most pronounced in Texas, where multi-unit franchisees negotiate enterprise service agreements separate from initial equipment acquisition.
Commercial Griddle Market Segmentation
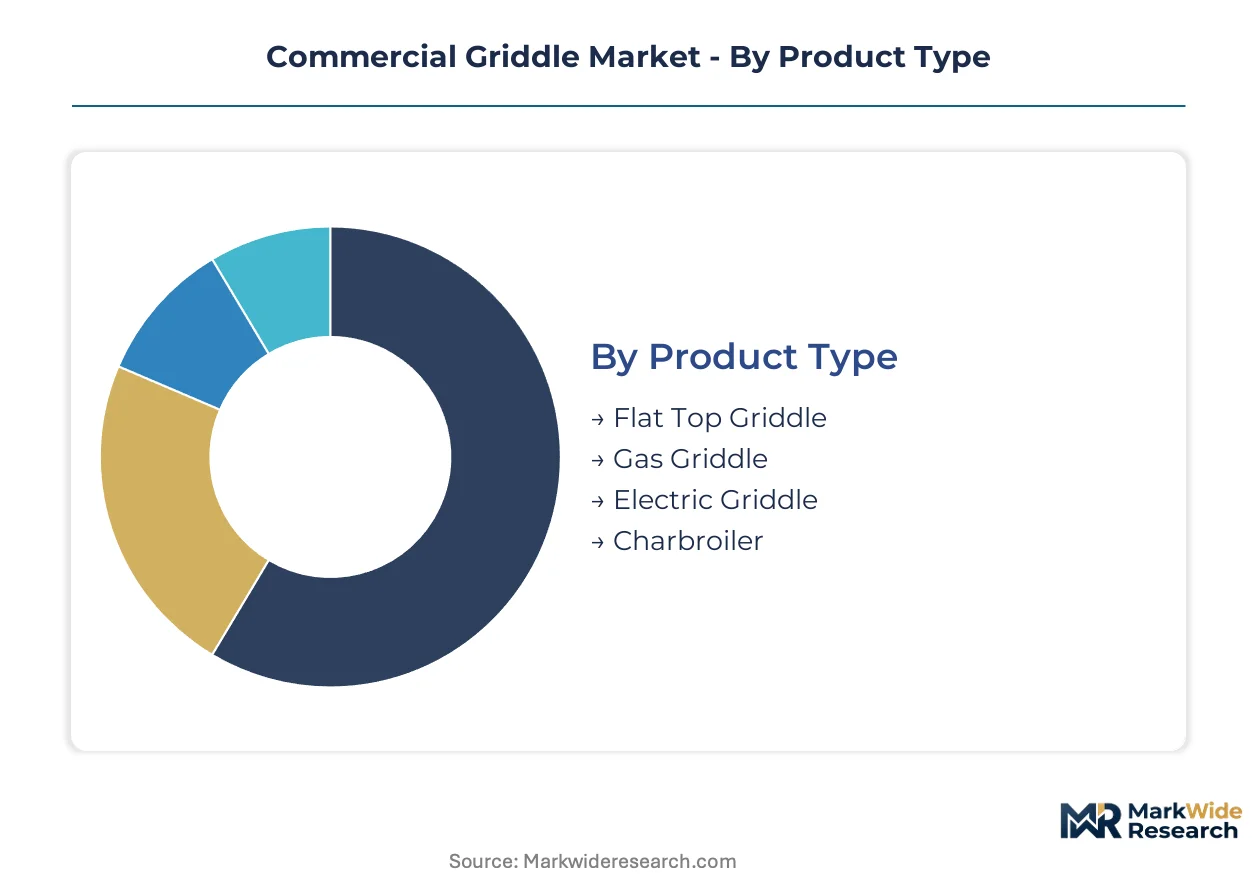
Equipment replacement cycles vary dramatically across griddle categories, with portable units turning over every 3-5 years while built-in installations persist for 15-20 years. Procurement patterns diverge between chain operators standardizing specifications and independent operators prioritizing flexibility over longevity.
Product Type:
Flat top griddles cycle fastest in high-volume breakfast operations where surface degradation forces replacement, while charbroilers retain the longest service intervals in steakhouse configurations.
- Flat Top Griddle:Polished steel or chrome-over-aluminum cooking surfaces dominate fast-casual breakfast chains. Texas operators specify these for smash-burger production where thermal uniformity across the full width drives throughput consistency.
- Gas Griddle:Cast-iron burner configurations with manual thermostat controls anchor legacy full-service restaurant infrastructure. Pre-existing natural gas hookups in established locations delay electrification despite tightening EPA efficiency mandates.
- Electric Griddle:Embedded thermocouple arrays and rapid-response heating elements serve food trucks and catering operations where ventless operation is mandatory.
- Charbroiler:Radiant or lava rock configurations with cast-iron grates target high-heat protein searing in steakhouse and barbecue formats.
Flat top griddles anchor the volume base while electric griddles gain share at the steepest rate.
End User:
Cost tiers separate enterprise procurement teams negotiating multi-year service bundles from independent operators purchasing on transactional terms.
- Restaurants:Full-service chains and fast-casual operators drive the largest equipment procurement volumes with standardized specifications across location footprints.
- Food Trucks:Compact electric and portable gas configurations dominate where space constraints and ventilation limitations override thermal performance preferences. California mobile food vendors prioritize NSF-certified ventless electric units to satisfy local air quality regulations.
- Catering Services:Lightweight, rapid-deployment griddles with quick-disconnect fuel lines support off-site event production.
- Cafeterias:Institutional facilities with aging infrastructure favor countertop retrofit formats over built-in replacements.
Restaurants anchor the volume base while food trucks expand most quickly.
Size:
Application intensity determines size selection, with high-throughput protein production demanding maximum surface area while constrained urban kitchens sacrifice capacity for footprint efficiency.
- Small:24-inch widths serve food trucks and compact catering setups where every square inch of kitchen space carries opportunity cost.
- Medium:36-inch configurations balance throughput and footprint for independent restaurants and mid-scale cafeterias.
- Large:48-inch to 60-inch surfaces dominate high-volume breakfast chains. California fast-casual operators specify large chrome surfaces for simultaneous egg, pancake, and protein production during peak morning rushes.
- Extra Large:72-inch and wider custom configurations serve stadium concessions and institutional feeding operations with continuous batch cooking requirements.
Large griddles anchor the volume base while small configurations climb the fastest.
Installation:
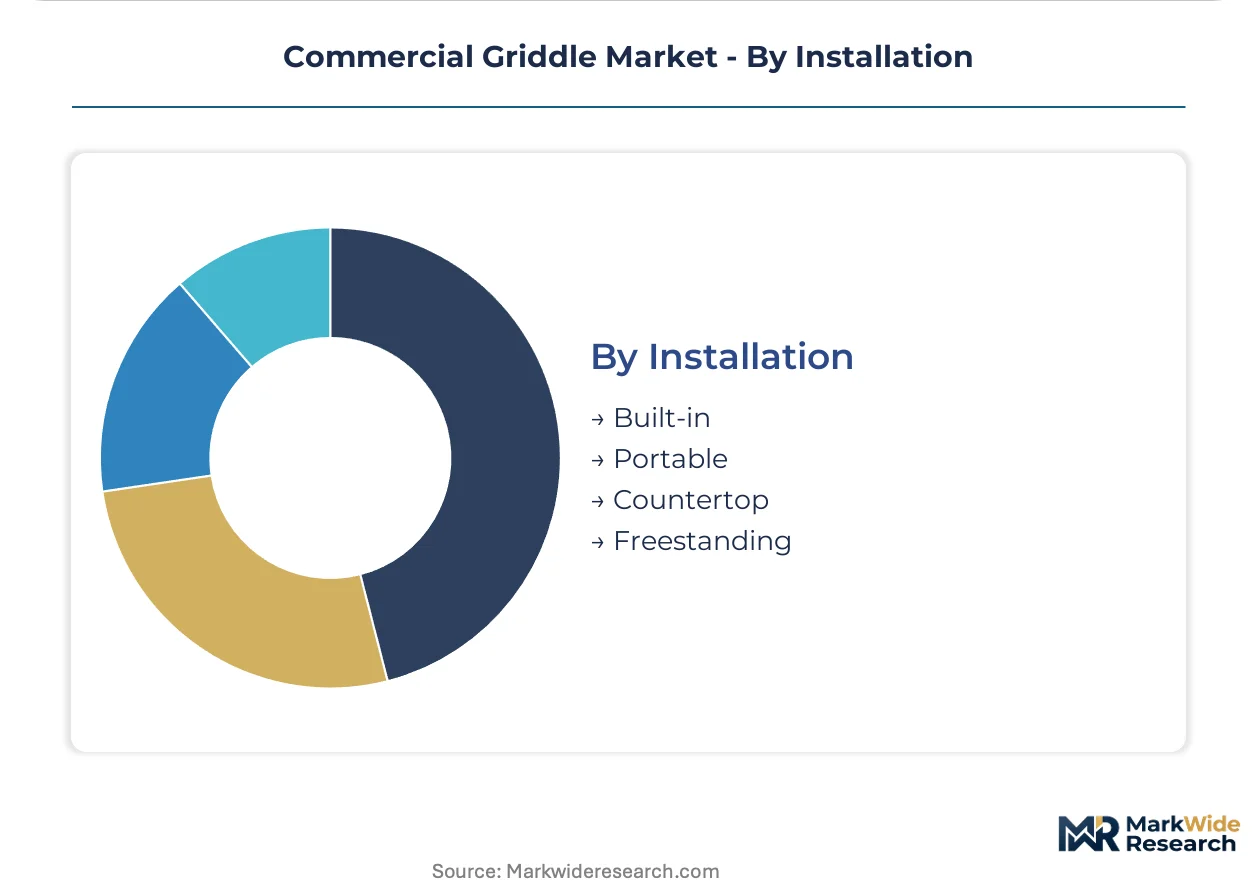
Customer type bifurcates between new-construction projects specifying built-in systems and retrofit operators seeking minimal infrastructure disruption.
- Built-in:Drop-in configurations with integrated ventilation and utility connections command premium positioning in ground-up restaurant construction. California electrification mandates prohibiting new gas connections drive electric built-in specifications in commercial developments.
- Portable:Casters, quick-disconnect utilities, and self-contained ventilation support catering and event production mobility.
- Countertop:Plug-and-operate electric units with minimal installation requirements address aging cafeteria and institutional retrofit demand. Texas school districts specify countertop electric griddles to extend equipment life without kitchen reconstruction.
- Freestanding:Self-supporting gas or electric cabinets with integrated storage serve mid-scale independent restaurants lacking custom millwork.
Countertop installations anchor the volume base while built-in configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in the United States, Germany, and China, with assembly operations clustering near major foodservice distribution hubs. Regional demand patterns diverge sharply based on kitchen infrastructure age, energy regulation stringency, and chain restaurant expansion velocity.
United States
Texas and California operators drive replacement demand through fast-casual chain expansion and electrification mandates. The EPA's commercial cooking efficiency standards compel early retirement of legacy gas configurations. Dallas-Fort Worth and Los Angeles metropolitan clusters anchor procurement volume for large-format chrome-surface installations.
Germany
Precision engineering traditions support premium electric griddle manufacturing for export markets. The EU Ecodesign Directive and national Energieeinsparverordnung tighten thermal efficiency minimums for imported equipment. Bavaria's industrial kitchen equipment corridor around Nuremberg hosts specialized control system suppliers.
China
Domestic foodservice modernization and export manufacturing capacity expand in parallel. The national standardization administration issues GB standards for commercial cooking equipment safety and energy consumption. Guangdong Province's Pearl River Delta concentration serves both domestic chain growth and OEM supply to North American brands.
Japan
Compact kitchen footprints in urban centers accelerate demand for high-efficiency electric configurations. METI's Top Runner program establishes progressive efficiency targets for commercial cooking equipment. The Osaka-Kobe industrial zone maintains specialized steel surface finishing capabilities for premium export specifications.
United Kingdom
Post-pandemic hospitality recovery drives equipment refresh cycles across independent restaurant segments. The Climate Change Act 2008 and subsequent carbon budgets pressure operators toward electric alternatives. Greater London's dense foodservice cluster prioritizes ventless countertop configurations for basement and retrofit kitchens.
Commercial Griddle Market Vendor Landscape
Full-service equipment conglomerates and specialized thermal technology firms split the market between integrated portfolio breadth and focused control system depth. Consolidation pressure runs high as chain procurement teams reduce vendor counts. Two strategic archetypes dominate: diversified foodservice equipment platforms leveraging service network density, and precision thermal control specialists monetizing proprietary sensor arrays. Competitive moves center on multi-year service contract bundling and electrification-ready product platform development.
Within the diversified platform tier, Middleby Corporation and Illinois Tool Works exemplify scale-driven consolidation strategies, while The Vollrath Company occupies a position among specialized compact-configuration fabricators. Electrolux and Welbilt represent European-headquartered multinational portfolios with broad foodservice equipment coverage. Standex International Corporation and Ali Group sit within the mid-scale diversified segment, with AccuTemp Products and ELAG Products representing narrower thermal equipment specialization. These archetype groupings reflect procurement pattern segmentation rather than operational equivalence.
| Leading Market Players |
|---|
| Electrolux |
| Illinois Tool Works |
| Middleby Corporation |
| Welbilt |
| The Vollrath Company |
| Ali Group |
| AccuTemp Products |
| Standex International Corporation |
| ELAG Products |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese stainless steel rolling mills is compressing Grade 304 sheet margins and forcing North American fabricators to renegotiate quarterly contract terms. This utilization imbalance grants procurement leverage to large-scale chain operators while squeezing mid-tier manufacturers locked into fixed-price agreements.
Pricing Analysis
The EPA's commercial cooking efficiency standards dictate the pricing tier structure across the commercial griddle market. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified electric systems with embedded thermocouples from basic gas configurations and uncertified imports. Price differentiation centers on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because tariff exposure on Chinese sheet steel is forcing margin sacrifices. Independent restaurant operators exhibit the highest price sensitivity, while enterprise procurement teams at national chains prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Grade 304 and 430 stainless steel sheet feeds from rolling mills in China, Germany, and the United States. Aluminum heat spreaders and chromed cooking surfaces draw from specialized finishing operations in Japan and Germany. Single-source vulnerability concentrates in thermocouple array supply from Japanese sensor specialists. Distribution runs through foodservice equipment distributors with regional warehousing in Dallas-Fort Worth and Los Angeles metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial griddle market is experiencing high-growth disruption as California and New York electrification mandates force premature replacement of gas-powered infrastructure. This regulatory inflection compresses equipment lifecycles and redirects capital flows toward electric-ready supply chains.
For Market Incumbents: Insulate service revenue streams by embedding multi-year maintenance contracts into initial equipment sales. Capture captive demand from California fast-casual chains facing electrification deadlines. Deepen backward integration into thermocouple calibration capabilities to lock out third-party service competitors. For New Entrants and Emerging Players: Pursue ventless electric configurations for food trucks and catering operations where incumbent coverage remains thin. California mobile food vendors represent the most penetrable segment given air quality enforcement gaps. Lead with NSF-certified compact units priced below established brands while building service partnerships with regional distributors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diversified platforms with captive service networks. Long-term viability favors equipment-agnostic service providers capable of absorbing electrification transition costs. The signal to watch is consolidation velocity among mid-scale fabricators lacking electric platform development resources.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification-Ready Platform Development | California building codes prohibiting new gas connections mandate electric-first engineering investment. |
| Aftermarket Service Network Expansion | Multi-year maintenance contracts with temperature calibration lock in recurring revenue from chain operators. |
| Chromed Surface Manufacturing Scale-Up | Fast-casual chains in Texas and California specify chrome-over-aluminum for thermal uniformity. |
| NSF Certification Fast-Track Investment | Food-contact surface testing timelines delay new product introduction by 8-14 months for imports. |
| Compact Configuration Engineering | Food trucks and constrained urban kitchens prioritize footprint efficiency over maximum surface area. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with equipment procurement managers at national restaurant chains, aftermarket service directors, and commercial kitchen design consultants; and secondary validation through EPA efficiency standard filings, NSF certification databases, customs import records for stainless steel sheet, and foodservice distributor inventory reports. Bottom-up equipment shipment data triangulated against top-down chain expansion announcements.
Forecast inputs span product type, installation format, end-user category, and regional regulatory cluster across the projection horizon. CAGRs derive from modeled replacement cycles intersecting with electrification mandate phase-ins. Specific forecast inputs include California and New York building code adoption timelines and fast-casual chain unit growth trajectories in Texas.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity pricing and commercial construction lending rates would shift the trajectory. Material shifts in EPA efficiency standard stringency or state-level electrification acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Asia-Pacific Food Away from Home Market
Food Service
Rotisseries Market
Food Service
South America Free from Food Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Benelux Foodservice Market
Food Service
Mobile Food Services Market
Food Service
Quick-Service Restaurants Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Latin America Inflight Catering Market
Food Service
Charbroiler Market
Food Service
Commercial Steam Table Market
Food Service
Meal Voucher Market
Food Service
Countertop Pressure Fryer Market
Food Service
United States Online Food Delivery Market
Food Service
Instant Noodle Vending Machine Market
Food Service
United Arab Emirates Foodservice Market