
 India Inflight Catering Market | 2026-2036
India Inflight Catering Market Size, Share, and Industry Trends Forecast 2026-2036
India Inflight Catering Market Insights
Asset-light leasing of flight kitchen infrastructure is tilting competitive dynamics toward operators who avoid capital-heavy real estate commitments. TajSATS Air Catering Limited leverages its vertical integration into airport-adjacent commissaries to sustain throughput advantages at India's busiest hubs. Ambassador's Sky Chef anchors its position through specialization in premium vegetarian meal portfolios that align with dominant dietary preferences on domestic routes.
India inflight catering encompasses the preparation, assembly, and airborne delivery of ready-to-serve meals and beverages under strict time-temperature controls, with HACCP protocols governing cold-chain integrity from kitchen to cabin. The industry's primary purpose centers on passenger satisfaction metrics and ancillary revenue capture for airlines operating thin-margin networks. Meal delivery dominates service type revenue given full-service carrier contracts, while biodegradable packaging represents the fastest-expanding segment as airports enforce plastic waste bans under municipal solid waste rules. Vegetarian meals command disproportionate menu share reflecting India's dietary demographics, with non-vegetarian options concentrating on international routes and premium cabins.
FSSAI licensing mandates, Bureau of Indian Standards packaging specifications, and DGCA operational directives collectively govern food safety, material compliance, and loading protocols for airborne service. These frameworks elevate entry barriers for unorganized caterers while channeling procurement toward certified flight kitchen operators with documented cold-chain capabilities. Stakeholders must monitor evolving airport concession terms and sustainability mandates that will determine which packaging formats and service models retain operational viability.
Market Dynamics
FSSAI's mandatory food safety audits are compressing operational timelines for flight kitchen operators while simultaneously elevating capital requirements for cold-chain infrastructure compliance across India's aviation network.
Growth Catalysts
- Regulatory Standardization:FSSAI licensing mandates and DGCA operational directives are consolidating procurement toward certified operators with documented HACCP protocols, eliminating unorganized competitors from airline vendor pools.
- Airport Traffic Concentration:Mumbai, Delhi, and Bangalore generate sufficient flight density to support centralized commissary operations that achieve economies of scale in meal production and logistics coordination.
- Biodegradable Packaging Mandates:Municipal solid waste rules enforcing plastic bans at airports are accelerating format innovation among packaging suppliers serving flight kitchens.
Market Restraints
- Perishable Input Volatility:Fresh produce and protein costs fluctuate with monsoon patterns and supply chain disruptions, compressing margins on fixed-price airline contracts.
- Real Estate Concentration:Airport-adjacent land scarcity in Mumbai and Delhi limits expansion options for new entrants seeking proximity to loading gates.
- Substitution Pressure:Low-cost carriers increasingly substitute buy-on-board retail models for complimentary meal service, reducing contract volumes for traditional caterers.
Strategic Opportunities
- Secondary Airport Penetration:Hyderabad, Chennai, and Kochi exhibit rising international traffic without commensurate flight kitchen capacity, creating whitespace for operators with modular kitchen designs.
- Technology Convergence:IoT temperature sensors combined with blockchain traceability are enabling premium positioning for operators demonstrating end-to-end cold-chain integrity to full-service carriers.
- Export Logistics:India's geographic position as a South Asian hub creates potential for transshipment catering services to third-country carriers operating Delhi-Mumbai-Singapore routes.
Industry Challenges
- Certification Bottlenecks:FSSAI flight kitchen licensing timelines extend 12-18 months, delaying revenue recognition for greenfield investments and complicating capital planning.
- Specialized Workforce Scarcity:HACCP-trained kitchen supervisors and aviation logistics coordinators command premium wages, inflating fixed costs relative to commercial catering benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Inflight Catering Market |
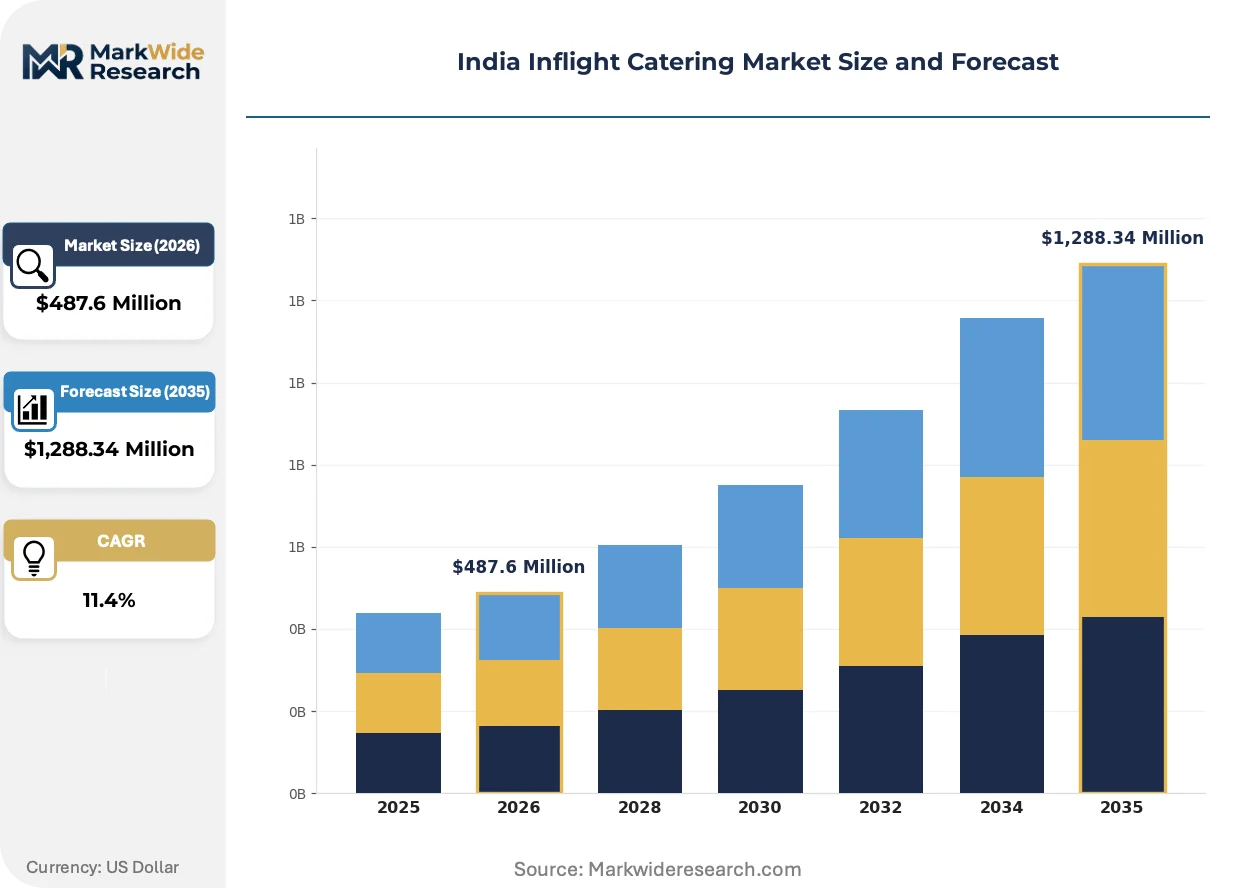
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Delivery, Snack Services, Beverages, Inflight Entertainment Food Type: Vegetarian Meals, Non-Vegetarian Meals, Desserts, Kids Meals End User: Commercial Airlines, Charter Flights, Private Jets, Cargo Services Packaging Type: Plastic Containers, Biodegradable Packaging, Tray Packs, Wrappers |
| Companies Covered | TajSATS Air Catering Limited, Ambassador's Sky Chef, Lulu Flight Kitchen Private Limited, Gate Group, Skygourmet Catering Private Limited, Oberoi Flight Services, Lufthansa Flight Kitchen, Uday Sky Kitchen, Casino Air Caterers & Flight Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Inflight Catering Market Trends and Innovations
Digital infrastructure is virtualizing kitchen operations while sustainability mandates reshape material specifications and passenger-facing service models across Indian aviation.
Cloud-based kitchen management systems are virtualizing inventory tracking, production scheduling, and airline billing workflows. Mid-tier flight kitchens in Bangalore and Hyderabad are adopting these platforms fastest, attracted by subscription pricing that avoids capital expenditure. This virtualization is compressing the competitive gap between established operators and technology-enabled challengers.
FSSAI's 2022 amendments to food safety protocols for airline catering introduced mandatory third-party audit frequencies and documentation standards. Bureau of Indian Standards specifications for food-grade packaging materials now require migration testing for all plastic substitutes. Full-service carriers operating international routes face the steepest compliance burden, driving consolidation toward vertically integrated suppliers with in-house testing laboratories.
Vegetarian meal preferences are reshaping menu engineering and procurement patterns across domestic route networks. Low-cost carriers now default to Jain and standard vegetarian options with non-vegetarian selections available through pre-booking channels. This preference concentration is most visible on Delhi-Mumbai and Bangalore-Delhi trunk routes where religious and cultural dietary observance rates exceed national averages.
India Inflight Catering Market Segmentation
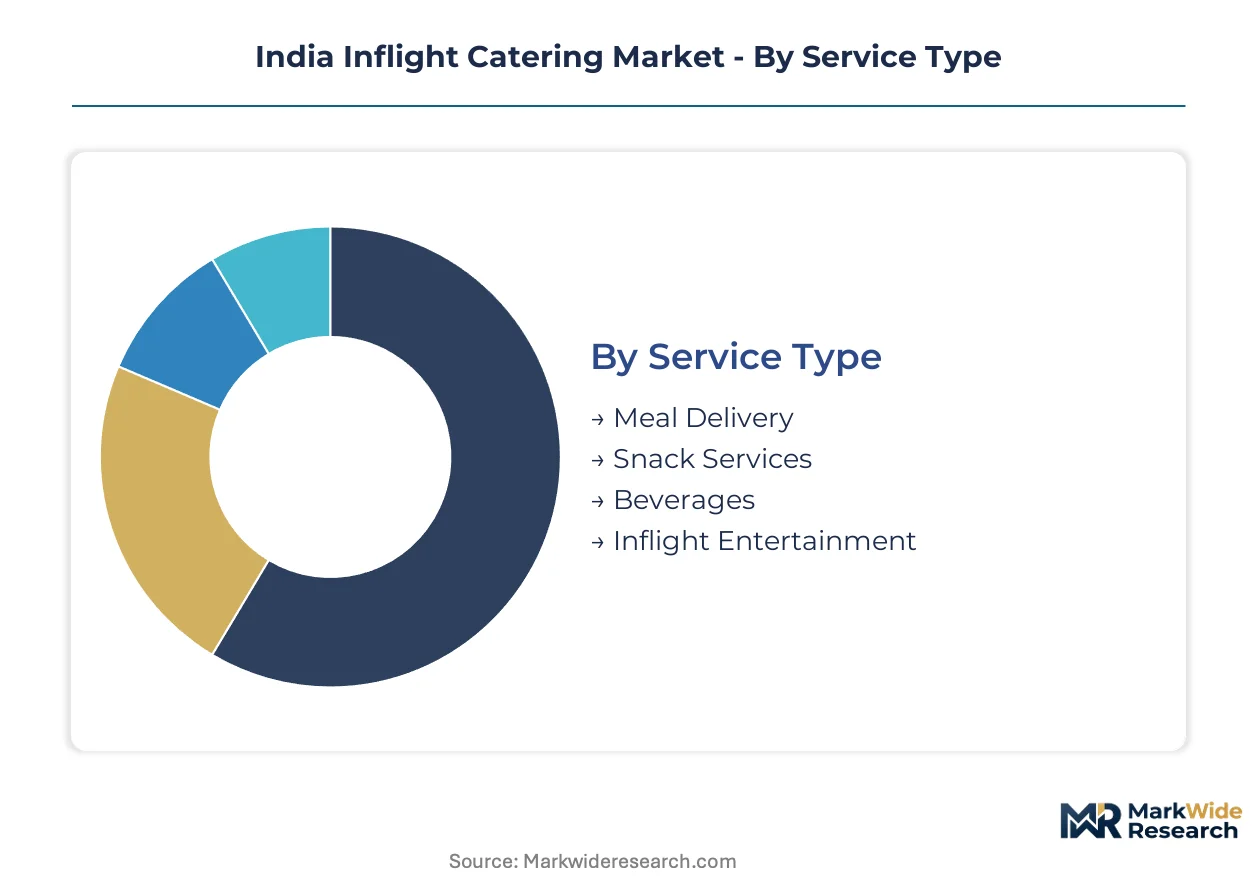
Segmentation in Indian inflight catering reveals how regulatory pressure, dietary demographics, and airline business models fragment procurement requirements across distinct operational profiles. Each dimension carries unique compliance burdens and margin structures that determine supplier viability.
Service Type:
Full-service carriers, low-cost operators, and charter services each demand differentiated service configurations spanning hot meal provision to retail-style buy-on-board models.
- Meal Delivery:Hot and cold meal assembly under HACCP protocols dominates revenue for full-service carriers operating trunk routes between Mumbai, Delhi, and Bangalore. TajSATS and Ambassador's Sky Chef compete intensely for these contracts where FSSAI audit compliance is non-negotiable.
- Snack Services:Pre-packaged savory and sweet items support low-cost carrier buy-on-board retail models with lower per-unit margins but higher volume velocity on dense domestic sectors.
- Beverages:Alcoholic and non-alcoholic drink provisioning requires separate licensing under state excise frameworks, complicating interstate route operations for caterers without multi-state permits.
- Inflight Entertainment:Headset distribution and media content loading represents ancillary service bundling that some flight kitchens package with meal contracts to deepen airline relationships.
Established volume favors Meal Delivery; emerging adoption favors Snack Services.
Food Type:
India's dietary landscape forces precise menu engineering where religious observance rates vary dramatically by route corridor and cabin class.
- Vegetarian Meals:Standard and Jain preparations command majority menu allocation on domestic networks, with Delhi-Mumbai and Bangalore-Delhi routes showing highest preference concentration. Ambassador's Sky Chef has built specialization here.
- Non-Vegetarian Meals:Chicken, mutton, and seafood options concentrate on international routes and premium cabins where passenger demographics shift and per-meal revenue thresholds justify protein costs.
- Desserts:Mithai-inspired and Western-style sweet courses differentiate premium cabin service on full-service carriers targeting corporate travelers.
- Kids Meals:Nutritionally formulated smaller portions with allergen controls address family travel segments on leisure-heavy routes to Goa and Kerala.
Vegetarian Meals retain volume leadership; Non-Vegetarian Meals gain share fastest on international expansion.
End User:
Customer scale and contract stability diverge sharply between scheduled commercial operators and fragmented private aviation demand.
- Commercial Airlines:Scheduled carriers with daily flight banks generate predictable production volumes that justify dedicated commissary investment at Mumbai and Delhi hubs.
- Charter Flights:Irregular scheduling and destination variability force caterers toward flexible production models with higher per-meal logistics costs.
- Private Jets:Ultra-high-net-worth travelers demand bespoke menu customization with 24-hour turnaround capability, supporting premium pricing but limiting scale.
- Cargo Services:Crew meal provisioning for freighter operations represents stable but low-margin contract opportunities at cargo-dominant airports.
Commercial Airlines anchor production scale; Private Jets command margin premiums.
Packaging Type:
Municipal solid waste rules and DGCA loading specifications are forcing rapid material transition across all packaging categories.
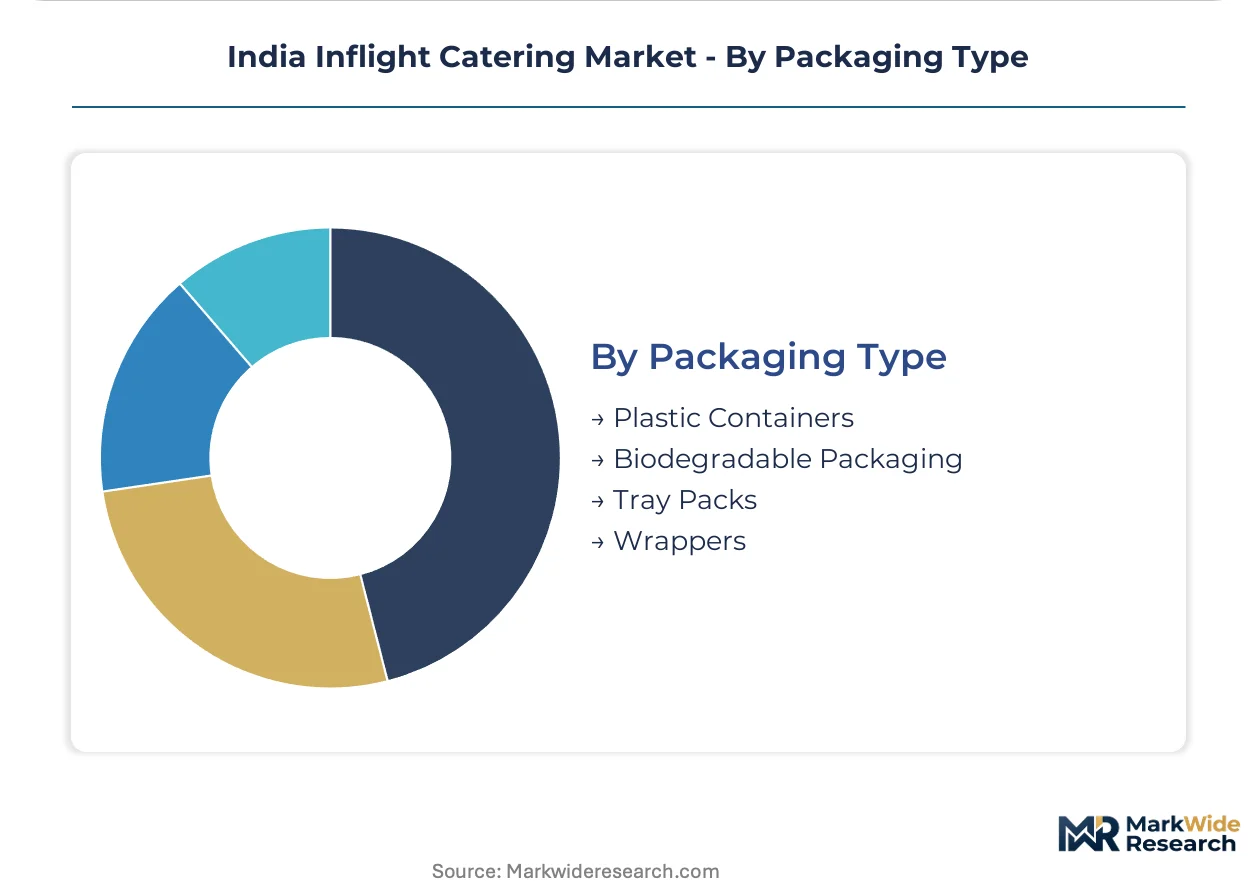
- Biodegradable Packaging:Bagasse, palm leaf, and PLA alternatives are climbing the fastest as airports enforce plastic bans under municipal solid waste rules. Bureau of Indian Standards migration testing requirements apply.
- Plastic Containers:Legacy PP and PET formats retain cost advantage for international carriers not yet subject to Indian airport waste mandates, though regulatory risk is rising.
- Tray Packs:Multi-compartment meal presentation systems remain standard for full-service carrier economy and business class service.
- Wrappers:Foil and paper-based individual item packaging supports snack and bread roll presentation with lower unit cost than rigid containers.
Plastic Containers retain installed base; Biodegradable Packaging shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's inflight catering trade balance tilts toward domestic production absorption, with limited export activity concentrated in transshipment services for Gulf carriers operating through Mumbai and Delhi hubs. Import dependency remains negligible given localized agricultural supply chains and FSSAI-mandated domestic certification requirements.
Maharashtra
Mumbai's Chhatrapati Shivaji Maharaj International Airport processes the nation's densest flight banks, supporting TajSATS Air Catering Limited's commissary operations with direct apron access. The state's Municipal Solid Waste Management Rules enforce plastic bans across airport concessions, accelerating biodegradable packaging adoption. Pune's emerging IT corridor generates secondary demand for charter catering services targeting business aviation.
Delhi-NCR
Indira Gandhi International Airport's dual-terminal configuration sustains round-the-clock production cycles for full-service and low-cost carrier contracts. FSSAI's zonal licensing office in Delhi processes flight kitchen approvals with 12-18 month timelines that shape capital deployment schedules. Gurugram's logistics warehousing cluster provides cold-chain staging facilities for perimeter-limited airport real estate.
Karnataka
Bangalore Kempegowda International Airport's rapid international expansion outpaces installed flight kitchen capacity, creating whitespace for modular kitchen entrants. The state's aerospace manufacturing corridor generates corporate aviation demand distinct from scheduled carrier patterns. Mysore's organic agriculture belt supplies premium ingredient sourcing for premium cabin vegetarian portfolios.
Telangana
Hyderabad Rajiv Gandhi International Airport's cargo-dominant operations sustain crew meal provisioning contracts with thinner margins than passenger service. The Telangana State Industrial Infrastructure Corporation allocates land parcels for airport-adjacent food processing with DGCA clearance pathways. Shamshabad's dedicated aviation zone concentrates ground handling and catering logistics in coordinated proximity.
Tamil Nadu
Chennai International Airport's Sri Lankan and Southeast Asian route network demands HACCP-compliant international meal standards beyond domestic regulatory minima. The state's packaged food manufacturing base supplies processed ingredients to flight kitchens across southern India. Coimbatore's absence of centralized flight kitchen infrastructure forces carriers to uplink meals from Bangalore with added logistics cost.
India Inflight Catering Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated operators with captive airport real estate and certified cold-chain infrastructure. Mid-tier challengers compete through technology-enabled kitchen management platforms that compress operational gaps with established players. Two strategic archetypes dominate: hub-anchored commissary operators exploiting throughput scale, and specialized vegetarian portfolio providers capturing domestic route preferences. Competitive moves concentrate on lease-based infrastructure expansion to avoid capital-heavy real estate commitments, and backward integration into airport-adjacent agricultural procurement.
Among India-based operators, TajSATS Air Catering Limited and Ambassador's Sky Chef occupy distinct positioning archetypes that exemplify the market's bifurcation. TajSATS represents the hub-anchored scale model with commissary proximity to Mumbai and Delhi loading gates. Ambassador's Sky Chef exemplifies specialization-driven positioning through premium vegetarian meal engineering. Lulu Flight Kitchen Private Limited sits within the Gulf-investment-backed challenger tier, leveraging parent-group logistics capabilities for cost-positioned entry. These three operators collectively illustrate how capital access, geographic positioning, and menu specialization determine competitive viability under tightening FSSAI compliance frameworks.
| Leading Market Players |
|---|
| TajSATS Air Catering Limited |
| Ambassador's Sky Chef |
| Lulu Flight Kitchen Private Limited |
| Gate Group |
| Skygourmet Catering Private Limited |
| Oberoi Flight Services |
| Lufthansa Flight Kitchen |
| Uday Sky Kitchen |
| Casino Air Caterers & Flight Services |
| Others |
Pricing and Supply Chain Analysis
The Delhi-Mumbai air freight corridor's volatile fuel surcharges and slot-constrained ground handling costs concentrate supply power among TajSATS and Ambassador's Sky Chef while forcing three-tier pricing stratification across premium, standard, and economy service levels for downstream airline buyers.
Pricing Analysis
Full-service carriers anchor contract pricing through multi-year offtake agreements with cold-chain compliance premiums, while low-cost operators drive price compression via buy-on-board retail models. Price differentiation hinges on FSSAI certification tier and volume scale, with HACCP-audited kitchens commanding substantial premiums over uncertified competitors. Cost compression in the snack services tier is intensifying because low-cost carriers substitute pre-packaged retail for complimentary meals. Charter operators exhibit highest price sensitivity due to irregular demand patterns; private jet clients show lowest sensitivity given bespoke customization requirements.
Supply Chain Analysis
Fresh produce procurement draws from Maharashtra's Nasik belt, Karnataka's Mysore organic corridor, and Telangana's vegetable wholesale markets, creating geographic diversification against monsoon disruption. Protein inputs and specialized packaging materials rest on cold-chain logistics coordination and Bureau of Indian Standards-compliant biodegradable substitutes. Single-source vulnerability concentrates in airport-adjacent real estate where DGCA clearance requirements limit supplier substitution. Distribution runs through hub-and-spoke commissary networks radiating from Mumbai, Delhi, and Bangalore with apron-direct loading protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's inflight catering sector sits at a platform-economics inflection where cloud-based kitchen management systems enable mid-tier operators to virtualize inventory and production workflows, eroding the historical data advantages of established commissary operators.
For Market Incumbents: Build regulatory certification moats through captive FSSAI audit infrastructure and in-house HACCP training academies. Deepen backward integration into Mysore and Nasik agricultural procurement to lock premium vegetarian ingredient streams. Expand modular kitchen deployments at Hyderabad and Chennai before technology-enabled challengers capture secondary airport whitespace. For New Entrants and Emerging Players: Kochi's absence of centralized flight kitchen capacity offers immediate contract traction with international carriers operating Southeast Asian routes. Target Chennai's Sri Lankan and Southeast Asian route network where HACCP compliance requirements exceed domestic minima and incumbent capacity strains under growth. Penetrate through IoT-enabled cold-chain traceability platforms that demonstrate end-to-end integrity to full-service carrier procurement teams. For Investors and Strategic Acquirers: Carve-out targets emerge from Gulf-investment-backed flight kitchen divisions seeking operational rationalization. Five-to-ten-year viability favors vertically integrated operators with captive airport real estate and certified cold-chain infrastructure over asset-light technology platforms lacking physical throughput. Monitor FSSAI licensing timeline compression as inflection signal for regulatory barrier effectiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Kitchen Deployment | Hyderabad and Chennai whitespace capture enables scale without Mumbai-grade real estate commitments. |
| Biodegradable Packaging Transition | Bureau of Indian Standards migration testing compliance secures municipal solid waste rule adherence at Delhi and Mumbai airports. |
| Cloud-Based Kitchen Management | Virtualized inventory tracking compresses operational gaps between mid-tier challengers and TajSATS-scale incumbents. |
| Backward Agricultural Integration | Captive procurement from Mysore organic belt locks premium vegetarian ingredient supply for premium cabin contracts. |
| IoT Cold-Chain Certification | Blockchain-traceable temperature monitoring enables premium positioning with full-service carrier procurement teams. |
Research Methodology
Initial hypotheses were tested against primary input from flight kitchen operations directors, airline procurement managers, FSSAI compliance officers, and airport concession administrators and refined through secondary validation against Bureau of Indian Standards packaging specifications, DGCA operational directives, FSSAI audit protocols, and customs trade data for food-grade material imports. Bottom-up meal volume modeling triangulated against top-down aviation passenger traffic projections.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning service type, food category, end-user archetype, and packaging format alongside airport hub density tiers. CAGRs derived from logistic curve fitting to observed contract value trajectories incorporated FSSAI licensing timeline delays and biodegradable packaging transition costs as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Gulf-investment-backed challengers or accelerated FSSAI timeline compression would shift outcomes substantially. Cross-checking against DGCA flight movement statistics and airport authority passenger traffic disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Hospital Food Services Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Meal Kit Delivery Services Market
Food Service
Ice Cream Carts Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
United States Full Service Restaurants Market
Food Service
Food Service Disposables Market
Food Service
Germany Smokeless Indoor Grills Market
Food Service
Steam Stew Pot Market
Food Service
Netherlands Food Service Market
Food Service
Food Service Utensils Market
Food Service
Philippines Foodservice Market
Food Service
Thailand Food Service Market
Food Service
Food Trays Market
Food Service
Workplace Service Market