
 Italy Foodservice Market | 2026-2036
Italy Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Foodservice Market Foresight
Corporate catering is rebalancing toward hybrid workplace models as Italian businesses reduce permanent canteen contracts. Autogrill SpA leverages its dominance in motorway and airport concessions to sustain volume across transit corridors. Cremonini SpA anchors the railway catering segment through long-term service agreements with Trenitalia. Compass Group Italia SpA competes aggressively in the business and education sectors with centralized kitchen infrastructure.
Foodservice encompasses the commercial preparation and delivery of meals outside domestic settings, spanning from standardized quick-service production to bespoke full-service dining experiences with controlled supply chains and regulated food safety protocols. The service type dimension shows quick-service restaurants capturing urban commuter traffic while full-service establishments retain higher per-transaction margins in tourist zones. Within distribution channels, online ordering and food delivery platforms are displacing traditional dine-in dependence, though takeaway maintains strong positioning in Italy's dense city centers where proximity supports foot-traffic recovery.
Italy's foodservice operators navigate oversight from the Ministry of Health's food safety directorate alongside EU-level EFSA standards and the EU Green Deal's traceability requirements, which mandate documented sustainable sourcing for public sector contracts. The CSRD disclosure framework will compel larger catering groups to report supply chain emissions, reshaping procurement priorities. Stakeholders must monitor how digital platform commission structures and evolving labor regulations for delivery workers reshape unit economics across service models.
Market Dynamics
Italy's foodservice sector confronts a structural compression between EU Green Deal sourcing mandates and the operational economics of high-frequency urban dining. Operators must reconcile traceable supply chains with thin margins in quick-service formats.
Growth Catalysts
- EU Green Deal procurement mandates:Public sector contracts now require documented sustainable sourcing, creating preferential access for compliant operators in institutional catering.
- Digital platform penetration:Food delivery aggregators are capturing commuter meal occasions across Milan, Rome, and Turin with algorithmic demand forecasting.
- Railway transit volumes:Trenitalia's passenger corridors sustain captive foodservice demand through long-term concession agreements at major stations.
Market Restraints
- Olive oil and wheat input volatility:Climate stress on Mediterranean agriculture compresses margin predictability for pasta and prepared meal producers.
- CSRD disclosure timelines:The Corporate Sustainability Reporting Directive imposes emissions audit costs that disproportionately burden mid-scale catering groups.
- Platform commission structures:Delivery aggregator fees of 25-30% per order erode unit economics for independent restaurant operators.
Strategic Opportunities
- Southern Italy underpenetration:Naples and Palermo foodservice density remains below northern benchmarks, offering whitespace for format expansion.
- Centralized kitchen infrastructure:Hub-and-spoke production models reduce per-unit labor costs for multi-site operators in dense metropolitan zones.
- Plant-forward menu mandates:Lombardy and Emilia-Romagna regional procurement guidelines favor vegetarian options in public canteen contracts.
Industry Challenges
- Delivery worker classification compliance:Italian labor courts are reinterpreting gig-economy status, forcing platform-dependent operators to absorb payroll tax liabilities.
- Legacy POS integration friction:Smaller trattoria operators face technical barriers connecting traditional order systems to aggregator APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Foodservice Market |
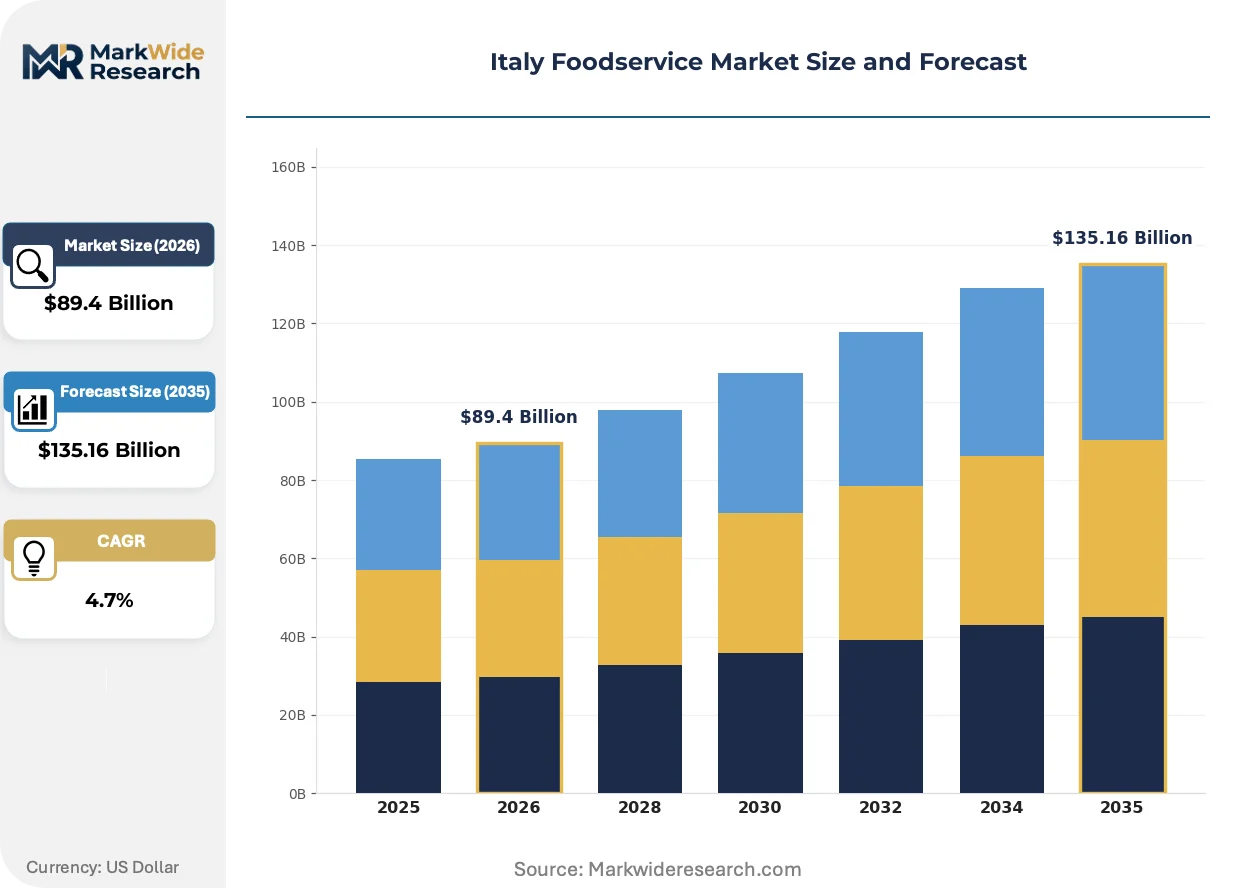
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $135.16 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Quick-Service Restaurants, Cafés, Catering Services End User: Consumers, Businesses, Institutions, Schools Distribution Channel: Online Ordering, Dine-In, Takeaway, Food Delivery Product Type: Appetizers, Main Courses, Desserts, Beverages |
| Companies Covered | Autogrill SpA, McDonald's Corporation, Cremonini SpA, CIGIERRE SpA, Elior Italia SpA, Compass Group Italia SpA, Sodexo Italia SpA, CIRFOOD, Camst, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Foodservice Market Shifts & Advancements
Automation and algorithmic demand management are compressing traditional service models while regulatory disclosure requirements reshape procurement priorities across Italian foodservice.
Cloud-based kitchen management systems are overtaking on-premise software stacks in multi-unit operations. Autogrill and motorway concessionaires deploy these platforms to synchronize inventory across dispersed locations. Real-time data feeds from point-of-sale terminals are enabling dynamic menu pricing that responds to traffic patterns.
The EU Green Deal's traceability requirements are mandating blockchain-verified sourcing documentation for public sector catering contracts. Compass Group Italia and institutional operators must now maintain immutable records from farm to fork. Smaller suppliers face exclusion from procurement rosters without certification infrastructure.
Commuter consumption patterns are fragmenting across hybrid work schedules, dispersing lunch-hour concentration that once anchored urban restaurant economics. Milan's business district sees demand compression on Tuesdays and Thursdays while Fridays hollow out. Operators are responding with subscription meal plans and corporate account structures that secure volume commitments regardless of daily foot traffic.
Italy Foodservice Market Segmentation
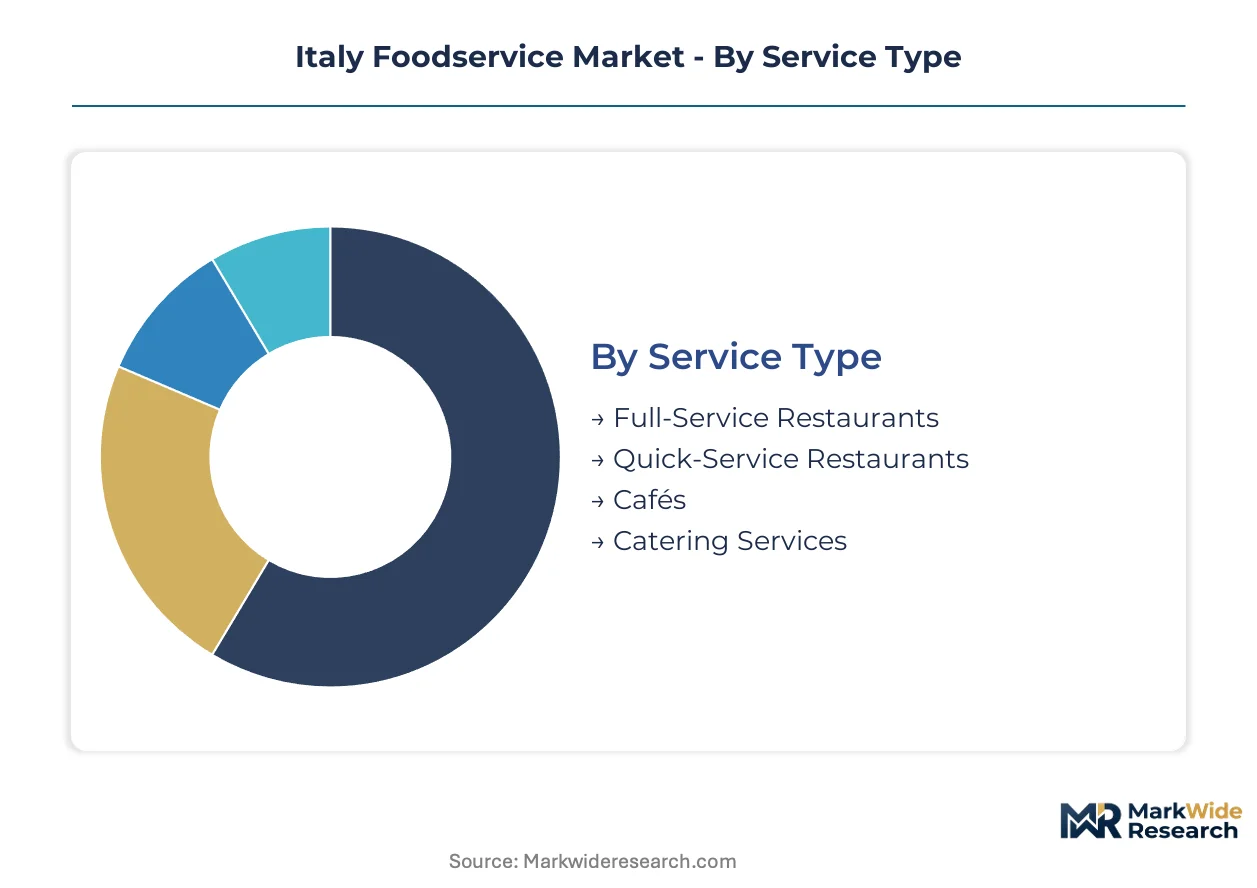
Service type distinctions in Italian foodservice determine which operators must comply with EFSA traceability protocols versus simplified municipal health inspections. End user and channel configurations further segment procurement requirements, from EU Green Deal mandates for institutional contracts to platform commission structures for digital channels.
Service Type:
Full-service and quick-service formats diverge sharply in certification burden: table-service establishments face ASL provincial health inspections for on-premise preparation, while quick-service operators navigate additional EFSA documentation for standardized supply chains.
- Full-Service Restaurants:Table-service establishments with controlled kitchen environments and wine service protocols. Demand concentrates in Rome's historic center and Florence's tourist corridors where per-transaction margins absorb higher labor costs.
- Quick-Service Restaurants:Standardized production formats with limited menus and counter service. Milan's commuter rail nodes and Turin business districts sustain volume through high-frequency turnover, though EU Green Deal sourcing mandates compress procurement flexibility.
- Cafés:Beverage-forward formats with limited food preparation, regulated under simplified ASL protocols for coffee service equipment.
- Catering Services:Off-premise meal preparation for events and institutions, requiring HACCP certification and documented cold-chain compliance for mobile service.
Leading the category by volume: Quick-Service Restaurants. Expanding most quickly: Catering Services adapting to hybrid workplace contracts.
End User:
Customer type determines contract structure and margin stability, with institutional and business segments offering volume commitments against consumer volatility.
- Businesses:Corporate canteen and meeting catering contracts with centralized billing. Milan's financial district and Rome's government quarter anchor demand, though hybrid work patterns compress permanent seat commitments.
- Institutions:Hospital and care facility meal provision with mandatory nutritional compliance. EU Green Deal procurement rules now require documented sustainable sourcing for public healthcare contracts.
- Consumers:Individual dining decisions across discretionary occasions, fragmented across platform-mediated discovery and traditional loyalty.
- Schools:Regional education authority contracts with price caps and nutritional guidelines, concentrated in Emilia-Romagna and Lombardy procurement frameworks.
Dominant by contract value: Businesses. Steepest expansion trajectory: Institutions adapting to CSRD disclosure timelines.
Distribution Channel:
Channel selection dictates labor classification exposure and technology infrastructure requirements, from POS integration to delivery fleet management.
- Online Ordering:Direct-to-consumer digital platforms with proprietary payment processing. Naples and Palermo operators lag northern adoption rates due to legacy POS fragmentation.
- Dine-In:Traditional table service with on-premise consumption, sustained in tourist zones despite urban commuter decline.
- Takeaway:Counter collection without platform intermediation, maintaining strong positioning in Italy's dense historic centers where proximity supports foot-traffic recovery.
- Food Delivery:Aggregator-mediated service with 25-30% commission structures. Italian labor courts are reinterpreting gig-economy status, forcing payroll tax absorption.
Highest volume share: Dine-In. Gaining share fastest: Food Delivery in metropolitan corridors.
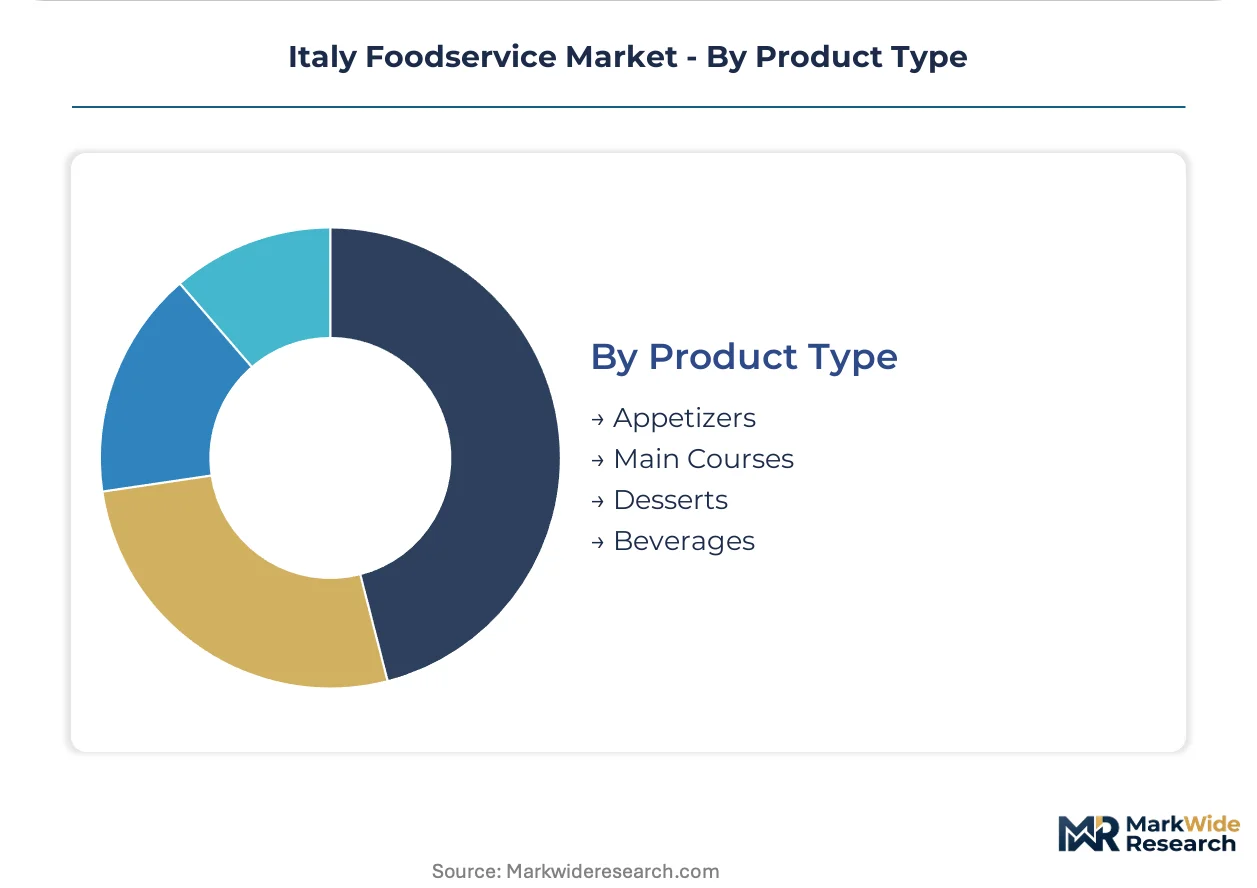
Product Type:
Menu category determines input cost volatility and preparation complexity, with wheat and olive oil price exposure concentrated in core offerings.
- Main Courses:Protein and carbohydrate-centered plates with highest per-item revenue. Pasta and prepared meal producers face climate-driven input volatility from Mediterranean agricultural stress.
- Beverages:Coffee, wine, and soft drink service with distinct margin profiles. Wine service requires specialized ASL licensing for alcohol retail.
- Appetizers:Antipasti and starter portions with lower ingredient cost but higher labor intensity for preparation.
- Desserts:Sweet course offerings, often outsourced to specialized suppliers with frozen distribution compliance.
Leading by revenue contribution: Main Courses. Climbing the fastest: Beverages through premium coffee and wine pairings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lombardy Region's tax incentives for agri-food industrial districts concentrate foodservice infrastructure investment around Milan's metropolitan corridor.
Lombardy
Corporate catering contracts and quick-service density drive volume in Milan's business district. EU Green Deal procurement mandates from the Lombardy Regional Administration require documented sustainable sourcing for public canteen contracts. Bergamo and Brescia host centralized kitchen facilities serving hub-and-spoke distribution networks across the northern industrial triangle.
Lazio
Institutional catering for government and healthcare facilities anchors demand in Rome's administrative core. The Ministry of Health's food safety directorate enforces EFSA-aligned inspection protocols for hospital meal providers. Fiumicino Airport's concession agreements sustain transit-corridor foodservice volume through captive passenger traffic.
Emilia-Romagna
Food manufacturing integration and regional procurement frameworks concentrate catering innovation in Bologna's logistics hub. Regional education authority contracts mandate plant-forward menu ratios in school canteens. Parma's agri-food technology cluster supplies processed ingredients to institutional operators under traceability requirements.
Piedmont
Turin's automotive industry heritage supports business catering contracts with manufacturing sector clients. The Piedmont Region's agri-food quality certifications create procurement preferences for local supply chain integration. Alessandria and Novara host distribution centers feeding quick-service networks across the northwest corridor.
Veneto
Tourism-dependent full-service establishments concentrate in Venice's historic center with elevated per-transaction margins. The Veneto Region's hospitality training programs address labor shortages in table-service formats. Verona and Padua sustain catering volume through pharmaceutical and university sector contracts.
Italy Foodservice Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with motorway concessionaires and railway caterers commanding distinct territorial monopolies. The vendor base concentrates around four operational archetypes: transit-corridor concessionaires, institutional contractors, quick-service franchise operators, and regional catering cooperatives. Consolidation pressure operates through long-term public procurement awards rather than horizontal M&A. Vertical integration into upstream food processing and backward integration into agricultural sourcing represent the dominant competitive moves.
Among Italy-based institutional contractors, Autogrill SpA, Cremonini SpA, and Compass Group Italia SpA occupy positions across distinct service archetypes. Autogrill SpA exemplifies the transit-corridor concessionaire model through motorway and airport network control. Cremonini SpA anchors railway catering through Trenitalia service agreements. Compass Group Italia SpA represents the centralized-kitchen institutional contractor competing in business and education sectors. These three operators illustrate how procurement scale and concession tenure structure competitive positioning differently than brand recognition or menu innovation.
| Leading Market Players |
|---|
| Autogrill SpA |
| McDonald's Corporation |
| Cremonini SpA |
| CIGIERRE SpA |
| Elior Italia SpA |
| Compass Group Italia SpA |
| Sodexo Italia SpA |
| CIRFOOD |
| Camst |
| Others |
Supply & Pricing Matrix
Culinary workforce concentration in Emilia-Romagna's agri-food corridor feeds labor-cost differentials that widen pricing-tier spreads between Milan's premium full-service establishments and quick-service formats in peripheral markets.
Pricing Analysis
Lead-time-driven pricing angles separate premium table-service bookings from spot-market counter transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and EU Green Deal compliance documentation. Price differentiation hinges on ASL provincial inspection tiers and EFSA traceability protocols. Cost compression in quick-service tiers is intensifying because delivery aggregator commissions absorb margin buffers, while institutional buyers in Rome's government quarter show lowest price sensitivity due to long-term concession tenure.
Supply Chain Analysis
Direct-to-catering channels handle hyperscale institutional demand from hospital and education authority contracts. Geographic supply concentration centers on Italy's domestic wheat and olive oil production, with secondary sourcing from Spain and Tunisia for climate-stressed inputs. Raw material dependencies rest on durum wheat semolina, extra virgin olive oil, and Parmigiano-Reggiano DOP supply quotas. Single-source vulnerability concentrates in Trenitalia concession corridors where Cremonini SpA holds exclusive railway catering rights. Distribution runs through hub-and-spoke centralized kitchen networks feeding metropolitan quick-service nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's foodservice market reads as supply-constrained through certified ingredient bottlenecks, where EU Green Deal traceability requirements prop pricing for compliant operators against excluded mid-scale competitors.
For Market Incumbents: Acquire centralized kitchen infrastructure in Milan's metropolitan corridor to consolidate hub-and-spoke production economics against platform-dependent independents. Backward integration into Parmigiano-Reggiano DOP and San Daniele ham supply quotas secures preferential procurement positioning under Lombardy Regional Administration sustainability mandates. Channel control through long-term Autostrade and Trenitalia concession renewals defends territorial monopolies from emerging railway caterers. For New Entrants and Emerging Players: Begin with underpenetrated whitespace in Naples and Palermo where foodservice density trails northern benchmarks and legacy POS fragmentation delays platform adoption. Target institutional catering in Southern Italy's hospital and education sectors where EU Green Deal compliance requirements have not yet fully displaced regional suppliers. A subscription meal plan go-to-market angle secures volume commitments from hybrid workplace clients regardless of daily foot-traffic volatility. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated catering cooperatives given CSRD disclosure timelines forcing mid-scale groups toward consolidation or exit. Long-term viability over a five-to-ten year window favors operators with captive agricultural sourcing and concession tenure exceeding a decade. The signal to watch as inflection indicator is Trenitalia's re-tendering schedule for major station concessions, which triggers competitive repositioning across railway foodservice.| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Kitchen Expansion | Hub-and-spoke models reduce per-unit labor costs for multi-site operators in dense metropolitan zones like Milan and Turin. |
| EU Green Deal Compliance Investment | Blockchain-verified sourcing documentation unlocks preferential access to Lombardy and Emilia-Romagna public sector contracts. |
| Railway Concession Renewal | Trenitalia long-term service agreements sustain captive demand volumes across Italy's major passenger corridors. |
| Plant-Forward Menu Development | Regional procurement guidelines in Emilia-Romagna mandate vegetarian ratios that compliant operators can premium-price. |
| Delivery Platform Integration | API connectivity to aggregator networks captures commuter meal occasions in Milan, Rome, and Turin business districts. |
Research Methodology
Document review covered trade association filings, EU regulatory databases, and regional procurement records, complemented by interviews with foodservice operations directors, Trenitalia concession managers, and ASL provincial health inspectors. Secondary validation drew from Ministry of Health food safety directorate publications, EFSA traceability guidelines, and Lombardy Regional Administration sustainability mandates. Bottom-up site-level capacity assessments and top-down sectoral expenditure analysis provided cross-referencing discipline across the analysis window.
Historical volume trajectories were cross-referenced against panel input from institutional procurement officers and quick-service franchise operators. Segmentation modeling tracked service type, end user category, distribution channel, and product type dimensions alongside EU Green Deal compliance tier as an industry-specific stratifier. CAGRs were derived through trend extrapolation adjusted for regulatory phase-in schedules and platform penetration curves. Forecast inputs incorporated climate stress projections for Mediterranean wheat and olive oil yields alongside labor court reinterpretations of delivery worker classification.
Underlying measurement precision varies by segment; quick-service restaurant volume data carry tighter precision than fragmented trattoria operations. Forecasts reflect assumptions about EU Green Deal enforcement intensity and platform commission stability that stress-testing against regulatory delay scenarios or aggregator fee renegotiations could materially revise. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Light Meal Market
Food Service
Chained Consumer Foodservice Market
Food Service
International Food Subscription Box Service Market
Food Service
Air Fryer Meal Kits Market
Food Service
Netherlands Food Service Market
Food Service
Cutting Boards Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Chile Food Delivery Market
Food Service
Breakfast Takeout Market
Food Service
China Food Service Market
Food Service
Contract Catering Market
Food Service
US Food Trucks Services Market
Food Service
Takeout Dinner Market
Food Service
Fast Food and Quick Service Restaurant Market
Food Service
Global Food Retail Market
Food Service
Commercial Beverage Dispenser Market