
 Smokeless Grill Market | 2026-2036
Smokeless Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Smokeless Grill Market Analytics
Market Context with Strategic Players
A shift from single-source OEM arrangements toward multi-source component procurement is broadening supply flexibility for smokeless grill manufacturers. Koninklijke Philips N.V. leverages its appliance R&D infrastructure to sustain technology leadership in infrared heating platforms. Weber-Stephen Products LLC anchors its competitive position through specialized outdoor-to-indoor product extensions and controlled distribution through specialty retail channels. SharkNinja Operating LLC differentiates via aggressive channel control across online retail and department store placements, competing on brand velocity rather than component sourcing depth.
Technical Definition and Structural Segments
A smokeless grill is an electrically powered cooking appliance that employs enclosed heating elements—typically infrared quartz, ceramic, or induction coils—combined with integrated grease-collection trays and smoke-extraction fans to enable indoor grilling without open flame or significant particulate emission. The device serves residential kitchens, commercial catering operations, and cooking instruction facilities where ventilation constraints prohibit traditional charcoal or gas grilling. Electric grills occupy the mature volume tier, while infrared grills command the fastest expansion due to superior searing performance and reduced preheat cycles. Multi-functional grills capture margin concentration as consumers consolidate countertop appliances, though non-stick coating technology faces structural pressure from evolving food-contact safety standards.
Regulatory Frame and Forward-Looking Close
The United States Environmental Protection Agency sets particulate and energy-efficiency benchmarks that shape product design cycles, while the Department of Energy tests standby power draw for electric cooking appliances. The Consumer Product Safety Commission governs surface temperature limits and cord safety for residential countertop equipment. In Europe, REACH compliance and RoHS substance restrictions constrain coating chemistries and electrical component selection. Stakeholders must monitor whether efficiency standard tightening in North America and chemical disclosure requirements in the European Union will force material substitutions that alter cost structures and competitive positioning.
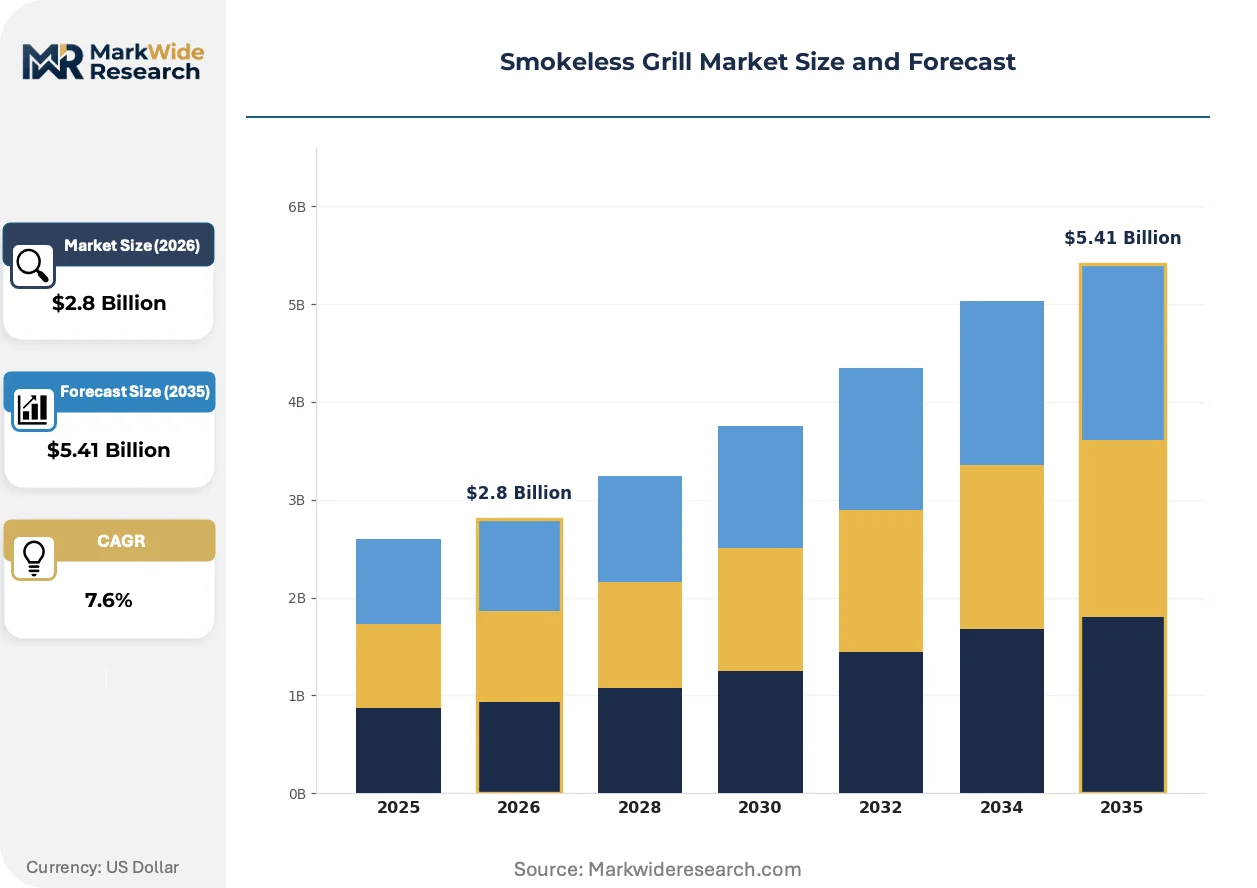
Market Dynamics
Residential kitchen space constraints are compressing demand toward multi-functional countertop appliances that consolidate grilling, air-frying, and roasting capabilities into single-footprint units.
Growth Catalysts
- Urban Housing Density:Apartment dwellers in Tokyo, New York, and London face strict open-flame prohibitions, creating built-in demand for electric alternatives that bypass ventilation infrastructure.
- REACH Chemical Disclosure:European coating reformulation requirements are accelerating migration toward ceramic and diamond-infused non-stick surfaces that command premium positioning.
- Infrared Quartz Platforms:Rapid preheat cycles and superior Maillard reaction performance are pulling performance-oriented home cooks away from conventional electric coil designs.
Market Restraints
- Copper and Aluminum Input Volatility:Heating element raw material costs swing with energy-intensive smelting economics, compressing margin stability for mid-tier manufacturers.
- Guangdong Supply Concentration:Contract manufacturers cluster in China's Pearl River Delta, creating single-source vulnerability for brands without multi-continent tooling redundancy.
- Power Draw Limitations:North American 120V residential circuits cap wattage at approximately 1,800 watts, constraining peak searing performance versus commercial 240V installations.
Strategic Opportunities
- Indian Metro Expansion:Bangalore, Mumbai, and Delhi apartment complexes increasingly prohibit balcony charcoal use, opening virgin territory for compact electric grill penetration.
- Smart Home Convergence:Integration of temperature probes with Wi-Fi-enabled recipe apps creates recurring revenue streams through subscription cooking content.
- US DOE Efficiency Incentives:Pending standby power draw rebates favor manufacturers achieving sub-1-watt idle consumption, rewarding early inverter-technology adopters.
Industry Challenges
- Thermal Engineer Scarcity:Infrared optics and computational fluid dynamics expertise concentrates in aerospace and automotive sectors, forcing appliance makers to compete for limited talent pools.
- Multi-Certification Timelines:Simultaneous UL, CE, and PSE testing for a single SKU stretches launch windows by 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smokeless Grill Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Grills, Electric Grills, Infrared Grills, Multi-functional Grills End User: Residential, Restaurants, Catering Services, Cooking Schools Technology: Induction Heating, Electric Heating, Ceramic Technology, Non-stick Coating Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | SharkNinja Operating LLC, Weber-Stephen Products LLC, Koninklijke Philips N.V., Hamilton Beach Brands, Inc., Groupe SEB (T-fal), Spectrum Brands Holdings, Inc. (George Foreman), Conair LLC (Cuisinart), Breville Pty Limited, Zojirushi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smokeless Grill Market Evolving Landscape
Product architecture is pivoting from standalone grilling function toward modular countertop ecosystems that share power bases and control interfaces across multiple cooking modalities.
Ceramic infrared emitters are expanding into residential price tiers previously dominated by metal-sheathed heating elements. Premium kitchen renovators in Germany and South Korea specify these platforms for built-in cooktop integration. The technology is compressing preheat latency from eight minutes to ninety seconds, collapsing the performance gap with open-flame alternatives.
EPA testing protocols for electric cooking appliance standby consumption are tightening disclosure requirements ahead of potential mandatory limits. Manufacturers must now submit third-party verification of phantom power draw across multiple operating modes. The rule change most affects value-tier products with basic electromechanical controls rather than solid-state inverter designs.
Specialty retail placement is losing ground to direct-to-consumer configuration tools that let buyers customize plate materials, voltage standards, and accessory bundles before factory fulfillment. Younger household formations in Scandinavia and Pacific Northwest US markets demonstrate strongest affinity for this build-to-order model, bypassing big-box inventory constraints entirely.
Smokeless Grill Market Segmentation
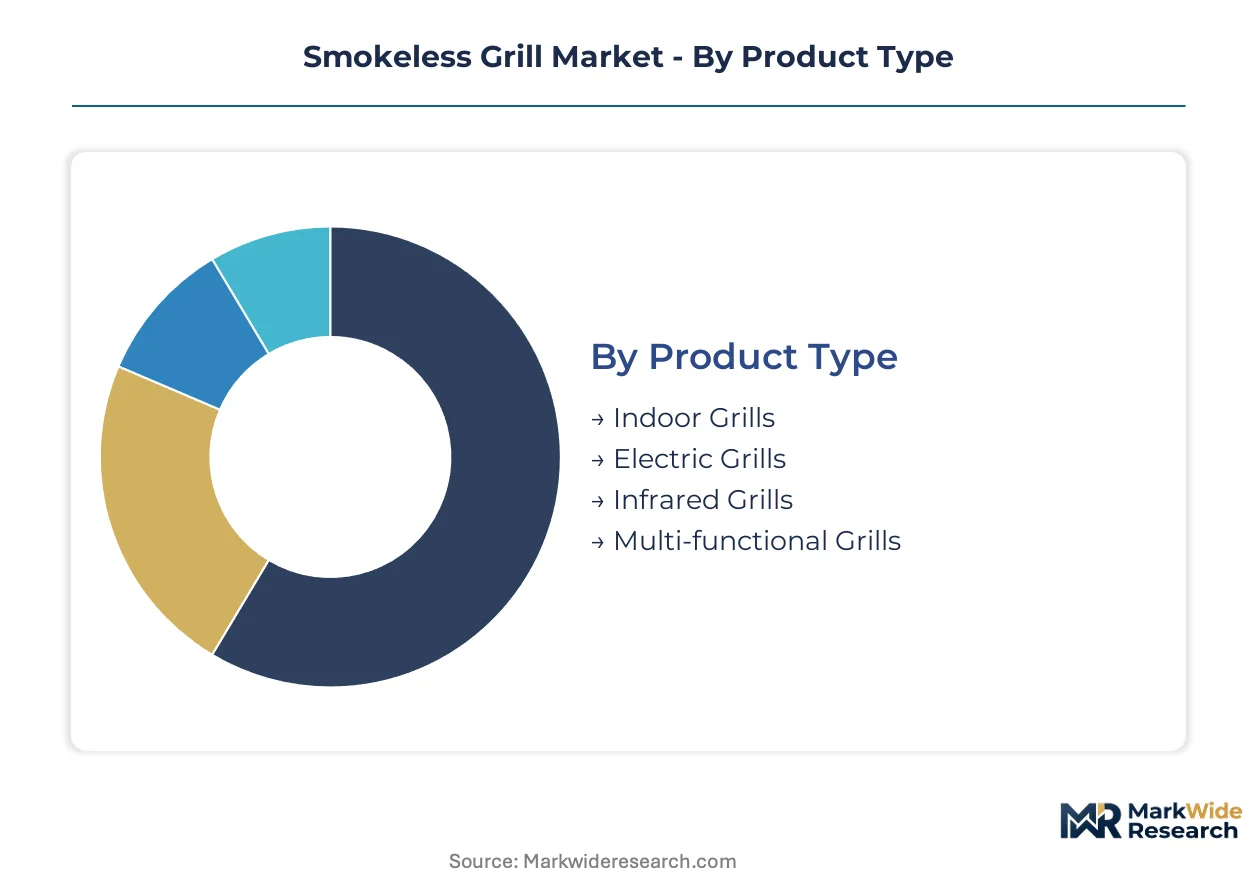
Smokeless grill purchasing decisions split across cooking performance requirements, kitchen infrastructure constraints, and channel accessibility. Upgrade cycles accelerate where infrared and multi-functional platforms displace first-generation electric coil units.
Product Type:
Replacement dynamics favor platforms that compress preheat latency while expanding cooking modality flexibility beyond standalone grilling.
- Indoor Grills:Enclosed heating architecture with integrated smoke extraction targets apartment dwellers facing ventilation restrictions. Demand clusters in Tokyo and New York where balcony fire codes prohibit open-flame alternatives.
- Electric Grills:Metal-sheathed coil elements dominate entry-tier placements through mass-market retail. Cost-conscious household formations in Germany and South Korea select these units for occasional use rather than daily meal preparation.
- Infrared Grills:Quartz and ceramic emitters achieve surface temperatures exceeding 500°C within ninety seconds. Premium kitchen renovators in Seoul and Munich specify these for built-in cooktop integration where searing performance matches gas alternatives.
- Multi-functional Grills:Modular bases accommodate air-fryer and roasting attachments. Scandinavian and Pacific Northwest consumers demonstrate strongest affinity for configuration tools that customize plate materials before factory fulfillment.
Volume placements concentrate in Electric Grills; the faster expansion belongs to Infrared Grills.
End User:
Application context determines durability specifications, duty-cycle ratings, and compliance documentation burdens.
- Residential:Countertop units with 1,200-1,800 watt draw serve urban apartments where 120V circuits constrain peak output. EPA standby power testing most affects basic electromechanical controls in this segment.
- Restaurants:NSF-certified stainless construction withstands continuous operation. Front-of-house installations in New York and Chicago deploy these for tableside preparation where open flame violates fire suppression protocols.
- Catering Services:Portable units with rapid breakdown facilitate off-site event execution. Operators prioritize grease-collection tray capacity over preheat speed given intermittent use patterns.
- Cooking Schools:Dual-voltage compatibility supports international student cohorts and facility relocation. Curriculum requirements drive demand for transparent lid designs that enable instructor visibility.
Residential captures absolute unit volume; Restaurants generate the steepest expansion trajectory through front-of-house deployment.
Technology:
Heating platform selection governs energy efficiency certification eligibility and coating chemistry compliance.
- Induction Heating:Magnetic field excitation delivers 90% energy conversion efficiency. REACH disclosure requirements in Europe accelerate ceramic and diamond-infused surface migration away from legacy PTFE formulations.
- Electric Heating:Resistive coil construction maintains lowest bill-of-materials cost. DOE standby power draw testing disadvantages basic electromechanical control architectures prevalent in this category.
- Ceramic Technology:Infrared emitter substrates withstand thermal cycling without oxidation. German and South Korean built-in cooktop specifications favor these platforms for seamless countertop integration.
- Non-stick Coating:Surface chemistry faces structural pressure from evolving food-contact safety standards. ECHA substance restrictions constrain fluoropolymer formulations, accelerating ceramic alternative adoption.
Electric Heating retains volume leadership; Induction Heating climbs the fastest on efficiency certification incentives.
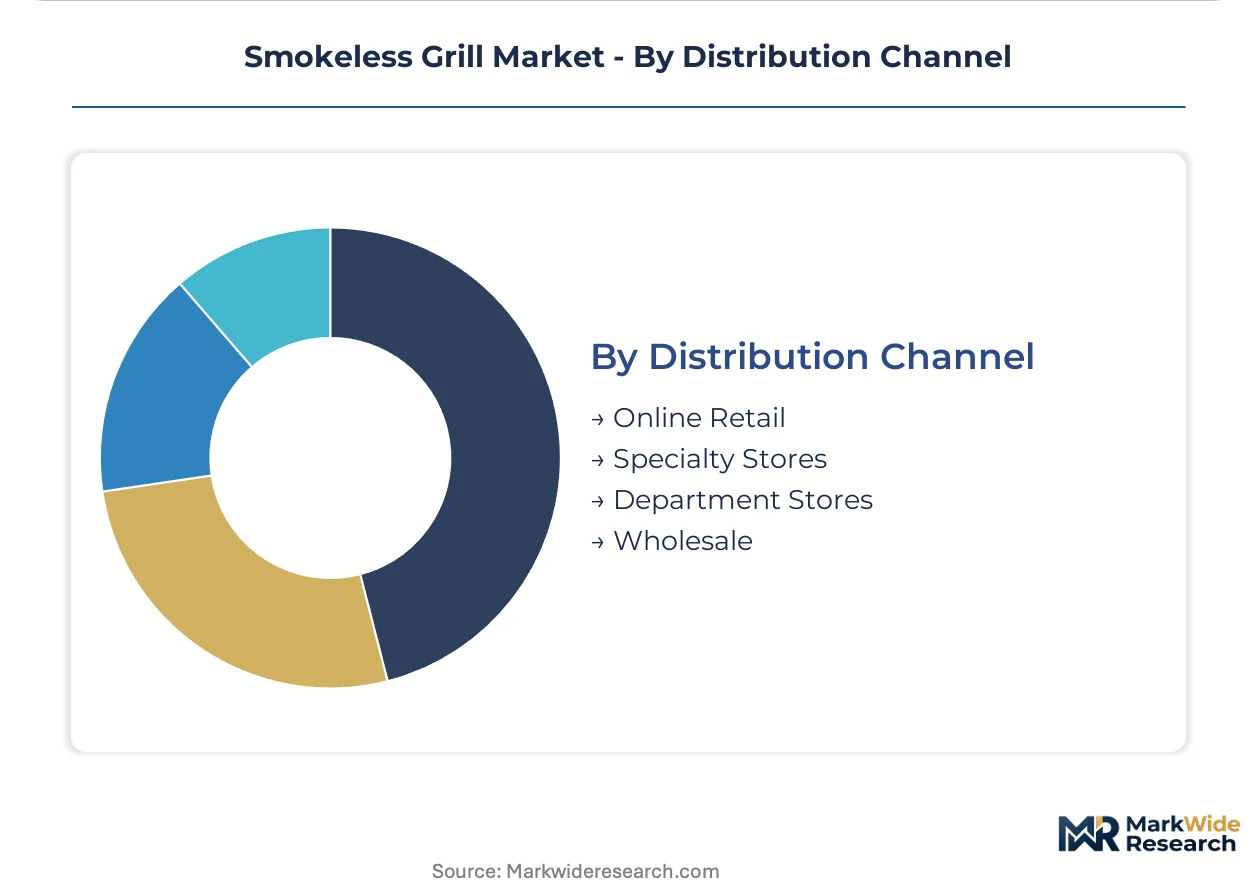
Distribution Channel:
Channel selection determines configuration flexibility, warranty terms, and accessory bundle economics.
- Online Retail:Direct-to-consumer configuration tools bypass inventory constraints. Younger household formations in Scandinavia and the Pacific Northwest demonstrate strongest affinity for build-to-order fulfillment.
- Specialty Stores:Staff expertise supports premium positioning and extended demonstration protocols. Weber-Stephen anchors competitive position through controlled distribution and outdoor-to-indoor product extension.
- Department Stores:Seasonal promotional calendars concentrate volume in gift-giving quarters. SharkNinja competes on brand velocity through aggressive placement across these channels.
- Wholesale:Institutional procurement contracts favor standardized SKUs with multi-year parts availability. Catering and cooking school demand flows predominantly through this channel.
Department Stores maintain volume concentration; Online Retail gains share fastest through configuration customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province's Pearl River Delta anchors contract manufacturing capacity for smokeless grill assembly, with Shenzhen and Dongguan housing the dominant share of tooling infrastructure serving export-bound brands.
United States
Balcony fire codes in New York and Chicago drive apartment dwellers toward electric alternatives that bypass ventilation infrastructure. The Environmental Protection Agency tests standby power draw for electric cooking appliances under tightening efficiency protocols. Dallas-Fort Worth metroplex distribution centers handle bulk import consolidation before specialty retail channel allocation.
Germany
Premium kitchen renovators in Munich and Hamburg specify ceramic infrared platforms for built-in cooktop integration. ECHA substance restrictions under REACH accelerate coating reformulation toward ceramic and diamond-infused surfaces. Bavaria's appliance engineering clusters concentrate R&D talent for heating element optimization.
China
Urban apartment density in Shanghai and Beijing prohibits open-flame cooking, creating built-in demand for compact electric units. MIIT efficiency standards shape domestic product design cycles for low-wattage infrared platforms. Guangzhou contract manufacturers cluster production lines for export-bound brands serving North American and European markets.
South Korea
Seoul apartment complexes enforce strict balcony grilling prohibitions, pulling demand toward countertop electric alternatives. MFDS food-contact safety standards constrain non-stick coating chemistries in domestic circulation. Gyeonggi-do industrial corridors host final assembly operations for ceramic emitter integration.
India
Bangalore, Mumbai, and Delhi apartment complexes increasingly prohibit balcony charcoal use, opening virgin territory for compact electric grill penetration. BIS certification requirements extend product launch timelines for imported units. Maharashtra warehousing hubs manage inland distribution before regional retail placement.
Smokeless Grill Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend outdoor grilling expertise into indoor electric platforms and consolidate countertop appliance functionality. The vendor base splits between diversified appliance conglomerates with multi-category R&D infrastructure and specialized grill manufacturers with controlled distribution depth. Three archetypes define competitive positioning: technology-led conglomerates leveraging infrared heating patents, brand-velocity operators prioritizing channel presence over component sourcing, and outdoor heritage players extending into balcony-friendly formats. M&A activity and multi-source component procurement represent the dominant competitive moves reshaping supply flexibility.
Among diversified appliance conglomerates, Koninklijke Philips N.V. and Groupe SEB occupy positions anchored by multi-category R&D infrastructure and European regulatory compliance expertise. SharkNinja Operating LLC exemplifies the brand-velocity archetype through aggressive placement across online retail and department store channels. Weber-Stephen Products LLC represents outdoor heritage extension into indoor formats through controlled specialty retail distribution. Hamilton Beach Brands, Inc. and Spectrum Brands Holdings, Inc. sit within the mass-market volume tier, competing on standardized SKU economics rather than platform differentiation. These five entities collectively illustrate the strategic segmentation between technology depth, channel control, and brand heritage that structures competitive rivalry.
| Leading Market Players |
|---|
| SharkNinja Operating LLC |
| Weber-Stephen Products LLC |
| Koninklijke Philips N.V. |
| Hamilton Beach Brands, Inc. |
| Groupe SEB (T-fal) |
| Spectrum Brands Holdings, Inc. (George Foreman) |
| Conair LLC (Cuisinart) |
| Breville Pty Limited |
| Zojirushi Corporation |
| Others |
Value Network & Pricing Analysis
EPA standby power draw testing gates qualified supply access and premium-tier pricing power, as manufacturers achieving sub-1-watt idle consumption capture DOE efficiency incentives while value-tier competitors face margin compression from basic electromechanical control architectures.
Pricing Analysis
Warranty and service bundling separates premium positioning from unbundled economy tiers, with ceramic emitter platforms commanding extended coverage terms against coil-element alternatives. Three-tier pricing structure across premium, standard, and economy levels differentiates on UL certification grade and infrared preheat performance, while cost compression in the economy tier intensifies from Guangdong contract manufacturer consolidation. Residential apartment dwellers in Tokyo and New York exhibit highest price sensitivity, whereas German built-in kitchen renovators show lowest elasticity for searing-matched performance.
Supply Chain Analysis
India's phased manufacturing program and local-content rules for appliance assembly are reshaping sourcing footprints away from pure Pearl River Delta dependence. Heating element production concentrates in China, South Korea, and Germany, with quartz emitter substrates and ceramic coatings drawing from specialized foundries in each jurisdiction. Single-source vulnerability persists in Guangdong tooling infrastructure, while distribution runs through Dallas-Fort Worth consolidation centers before specialty retail channel allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA standby power testing creates a barrier-to-entry moat for manufacturers with inverter-technology R&D infrastructure.
For Market Incumbents: Deploy multi-source component procurement to dilute Guangdong concentration risk, while accelerating ceramic infrared patent filings to defend against emerging induction-platform entrants. Backward integration into heating element substrates secures margin stability against copper and aluminum input volatility.
For New Entrants and Emerging Players: Direct-to-consumer configuration tools offer the most penetrable route, targeting Scandinavian and Pacific Northwest younger household formations with build-to-order plate material customization. White-space exists in Indian metro balcony-prohibition markets where BIS certification delays have slowed established brand entry.
For Investors and Strategic Acquirers: MFDS coating reformulation announcements in South Korea are the leading indicator that food-contact safety standard tightening will accelerate ceramic alternative adoption across Asian markets. Acquisition targets should screen for solid-state inverter design capability and REACH-compliant coating chemistry portfolios, with thermal engineering talent scarcity signaling long-term viability for technology-led platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Component Procurement | Dilutes Guangdong single-source vulnerability for brands with tooling redundancy across Shenzhen and Dongguan. |
| Ceramic Infrared Platform Extension | Captures German and South Korean built-in cooktop specifications where searing performance matches gas alternatives. |
| Direct-to-Consumer Configuration Launch | Bypasses big-box inventory constraints for Scandinavian and Pacific Northwest younger household formations. |
| Smart Home Integration Development | Creates recurring revenue streams through Wi-Fi-enabled recipe app subscriptions with temperature probe connectivity. |
| Indian Market Certification Investment | Accelerates BIS approval timelines to capture Bangalore, Mumbai, and Delhi balcony-prohibition demand. |
Research Methodology
Multi-period observation of EPA standby power draw filings, ceramic emitter patent grants, and REACH coating reformulation timelines anchored the trend analysis, supplemented by interviews with appliance R&D directors, thermal engineering specialists, specialty retail category managers, and Guangdong contract manufacturing executives. Secondary validation drew from DOE efficiency standard dockets, ECHA substance restriction updates, customs trade records for heating element imports, and SEC 10-K appliance segment disclosures. Bottom-up SKU-level volume modeling and top-down category expenditure estimates were triangulated against channel inventory data.
The input-output matrix mapped electric grill wattage tiers, infrared emitter substrate types, non-stick coating chemistries, and distribution channel mixes against residential apartment density and balcony fire code enforcement intensity across the analysis window. CAGRs derived from segment-level growth rate reconciliation with macro appliance expenditure forecasts, incorporating MIIT efficiency standard trajectories for China and MFDS food-contact safety evolution for South Korea as industry-specific demand shapers.
The model holds under steady regulatory tightening trajectories for standby power and coating chemistry; deviation in raw material smelting economics or sudden tariff restructuring on Guangdong exports would shift competitive positioning. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Plates Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Global Digital Grocery Market
Food Service
Beverage Vending Machine Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Contract Catering Market
Food Service
Pizza Foodservice Market
Food Service
Ice Cream Carts Market
Food Service
Smoker Grill Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Australia Foodservice Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Mexico Foodservice Market