
 Takeout Dinner Market | 2026-2036
Takeout Dinner Market Size, Share, and Industry Trends Forecast 2026-2036
Takeout Dinner Market Analytics
ServSafe Certification is rotating as the baseline credential that determines which restaurant operators and delivery kitchens qualify for platform partnerships. DoorDash leverages its logistics network to sustain last-mile density in suburban corridors. McDonald's anchors volume through proprietary drive-thru architecture that competes with aggregator economics.
Takeout dinner refers to prepared meals produced in commercial kitchens for off-premises consumption, typically held at temperatures between 140°F and 165°F through insulated packaging to ensure food safety during transit. The category serves time-constrained consumers seeking restaurant-quality meals without on-site dining. Pizza and Chinese product types dominate transaction volume due to structural advantages in heat retention and transport durability, while sushi commands premium positioning through raw-fish handling protocols that elevate margin pools. App-based order methods capture the fastest expansion trajectory as smartphone penetration and stored-payment integration reduce friction in repeat purchasing.
FDA Food Code standards, state-level cottage food laws, and municipal health department permitting collectively govern kitchen sanitation, allergen disclosure, and third-party delivery intermediary liability. These frameworks shape capital requirements for cloud kitchen entrants and determine which operators qualify for multi-state platform listings. Stakeholders must monitor evolving delivery fee caps and packaging waste mandates as local jurisdictions experiment with consumer protection and environmental rules that directly alter unit economics.
Market Dynamics
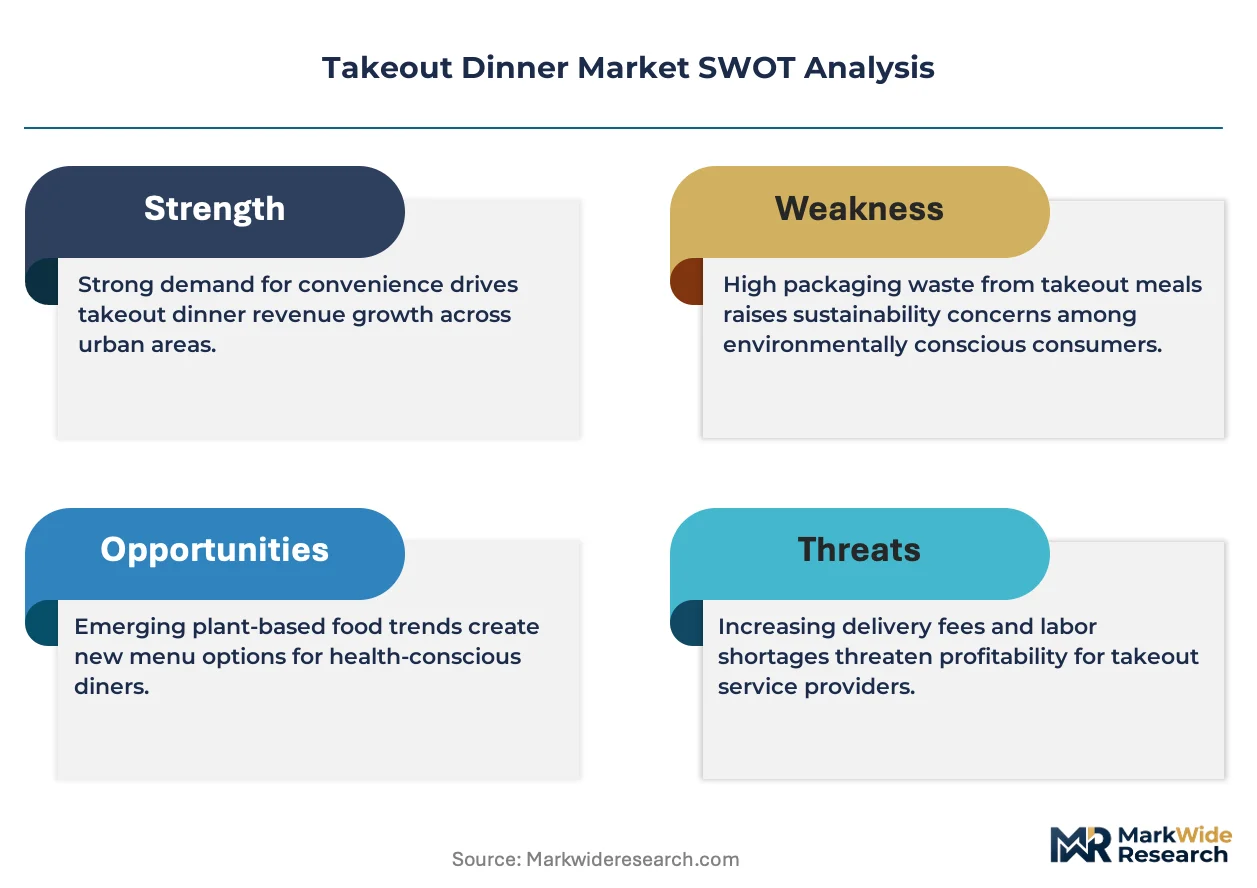
Platform-dependent demand concentration is restructuring the Takeout Dinner Market as aggregator algorithms determine kitchen visibility and order flow allocation. This algorithmic gatekeeping function compresses margins for independent operators while rewarding logistics density and proprietary customer data assets.
Growth Catalysts
- Smartphone penetration in India:Digital payment infrastructure expansion through UPI rails reduces checkout friction for first-time app users in tier-2 cities. Restaurant onboarding through FSSAI-compliant cloud kitchens accelerates supply-side density.
- FDA Food Code modernization:Harmonized temperature control standards across state jurisdictions enable multi-state platform listings for ghost kitchen operators. Compliance automation tools lower permitting timeline variability.
- Insulated packaging innovation:Phase-change material integration extends safe holding windows from 45 to 90 minutes. Suburban delivery zones become economically viable for premium cuisine categories previously confined to urban cores.
Market Restraints
- Delivery fee compression:Municipal caps in New York, San Francisco, and Chicago directly reduce per-order platform revenue. Kitchens absorb margin pressure through volume commitments or exit aggregator networks.
- Input cost volatility in petroleum-based packaging:Expanded polystyrene alternatives face price instability tied to resin supply chains. Biodegradable substitutes carry 40-60% cost premiums that resist full pass-through.
- Substitution by meal kit assembly:Direct-to-consumer ingredient shipping captures occasion-based demand from time-constrained households. Blue Apron and HelloFresh models displace prepared meal occasions with cooking-adjacent experiences.
Strategic Opportunities
- Underpenetrated suburban corridors:Last-mile density gaps in US exurban rings reward operators deploying micro-fulfillment nodes. Dark kitchen clustering around highway interchanges captures commute-pattern demand.
- EU packaging waste directive tailwinds:Extended producer responsibility frameworks in Germany and France mandate reusable container systems. First-mover platforms secure regulatory goodwill and municipal partnership preferences.
- AI-driven demand forecasting convergence:Kitchen management systems integrating weather data and event calendars reduce preparation waste. Inventory carrying costs compress while fill rates improve for peak-hour demand surges.
Industry Challenges
- Certification timeline compression:ServSafe credential backlogs in high-growth metropolitan areas delay kitchen launch schedules. Operators face revenue loss during mandatory 30-45 day inspection queues.
- Integration complexity with legacy POS:Fragmented restaurant technology stacks resist seamless aggregator API connectivity. Middleware costs erode margins for independent operators lacking technical staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Takeout Dinner Market |
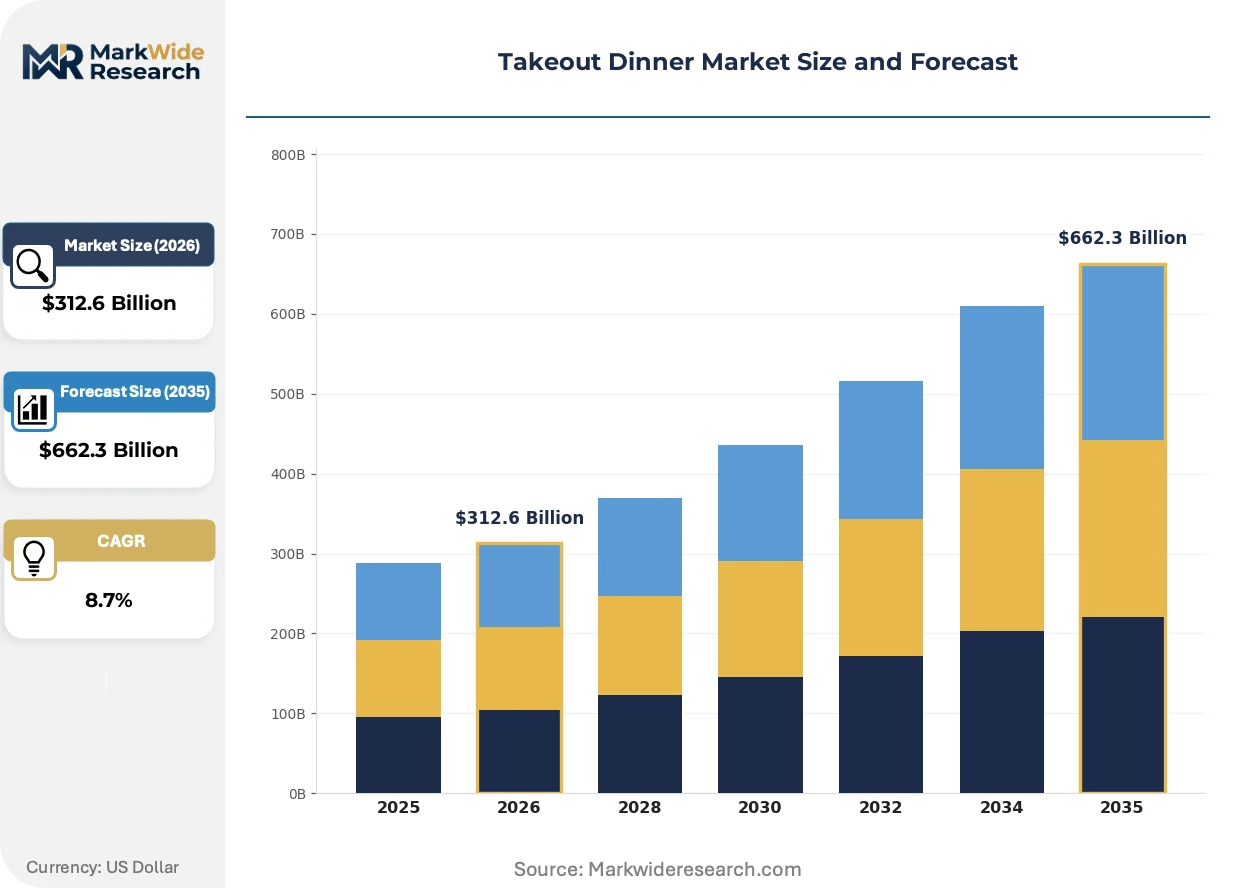
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pizza, Sushi, Chinese, Indian Order Method: Online, Phone, In-Person, App Customer Type: Families, Singles, Professionals, Students Service Model: Dine-In, Delivery, Curbside, Takeaway |
| Companies Covered | DoorDash, Uber Eats, Grubhub, Domino's Pizza, McDonald's, Yum! Brands, Just Eat Takeaway, Starbucks, Panda Express, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Takeout Dinner Market Evolving Landscape
Operational technology deployment is splitting kitchen functions into modular, geographically distributed components. This decomposition trend redefines asset ownership patterns and capital efficiency benchmarks across the prepared meal value chain.
Cloud kitchen infrastructure is decomposing the traditional restaurant model into specialized production, packaging, and dispatch nodes. National aggregator platforms deploy this architecture fastest in Dallas-Fort Worth and Atlanta suburbs where real estate costs support dedicated fulfillment-only sites. The structural consequence is collapsing the minimum viable scale for cuisine-specific market entry from full-service buildouts to 400-square-foot production bays.
REACH-compliant packaging material restrictions in the European Union are accelerating fiber-based container R&D investment. Industrial consequence includes mandatory elimination of per- and polyfluoroalkyl substances in food-contact materials by 2026. Premium sushi and hot-bowl operators in Germany and Netherlands face the steepest reformulation timelines as grease-resistant properties prove hardest to replicate.
Subscription-based ordering patterns among US dual-income households are displacing impulse-driven meal selection. Platform loyalty programs capture recurring revenue commitments that reduce per-order acquisition costs. This behavior concentrates most visibly in Seattle and Austin metro areas where household density and tech-sector employment overlap.
Takeout Dinner Market Segmentation
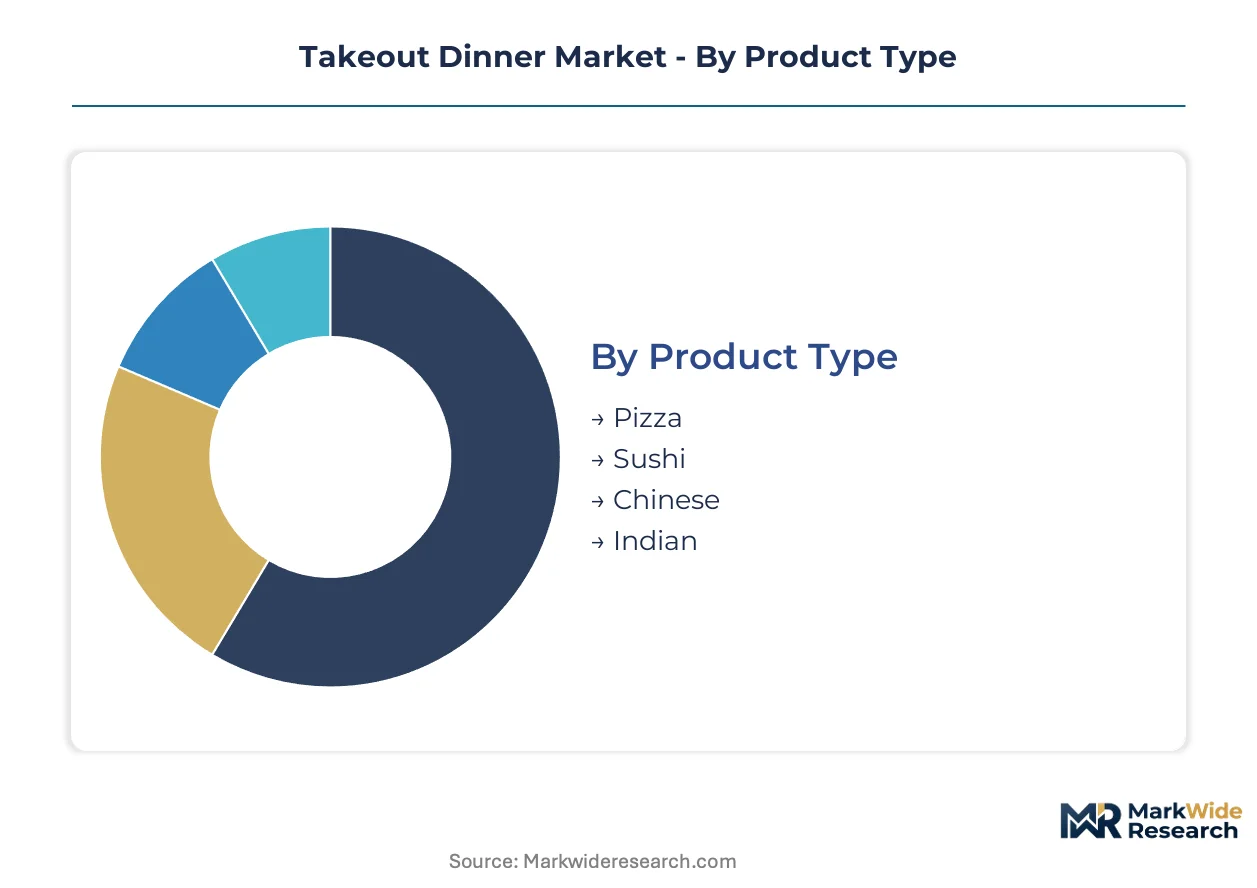
Channel-mix dynamics in the Takeout Dinner Market determine which segments capture platform algorithmic visibility and which remain dependent on walk-in traffic. Understanding how product categories, order interfaces, and customer profiles intersect with service models reveals where margin pools concentrate and where operational complexity escalates.
Product Type:
Pizza and Chinese cuisines flow predominantly through aggregator platforms due to structural advantages in heat retention, while sushi and Indian product types split across premium direct-order channels and platform listings based on handling protocol complexity.
- Pizza:Cheese and sauce compositions maintain palatability across 60-90 minute delivery windows without specialized packaging. Demand concentrates in US suburban corridors where family order sizes justify per-delivery economics and platform density rewards high-frequency operators.
- Chinese:Stir-fry and rice-based formats utilize vented containers that release steam without compromising texture. Metropolitan India and tier-2 Chinese cities drive volume through UPI-integrated app platforms where combo pricing reduces per-meal decision friction.
- Sushi:Raw-fish handling protocols require HACCP-certified kitchens and temperature-controlled logistics chains that limit platform eligibility.
- Indian:Curry and bread combinations demand grease-resistant packaging that costs 40% more than standard containers, compressing margins for independent operators.
The dominant share belongs to Pizza, while Sushi is closing the gap fastest through premium positioning and subscription loyalty programs.
Order Method:
Cost-tier stratification separates high-friction legacy channels from low-friction digital interfaces, with capital requirements and customer acquisition economics diverging sharply across the four methods.
- Online:Web-browser ordering through restaurant proprietary sites captures corporate catering contracts and large-format family orders. US and UK markets concentrate demand where desktop penetration among office workers sustains mid-day volume spikes.
- Phone:Voice-based ordering retains share among demographic segments with lower smartphone penetration and serves as backup during app outages.
- In-Person:Counter-based transactions dominate cash-preferred customer segments and markets with underdeveloped digital payment infrastructure.
- App:Smartphone-native interfaces with stored-payment integration reduce checkout time to under 30 seconds. India and Southeast Asia show steepest expansion trajectories as UPI and e-wallet penetration accelerates first-time user conversion.
App-based ordering commands the largest volume share, while Online methods gain ground fastest in B2B catering segments.
Customer Type:
Volume concentration varies by household composition and employment status, with dual-income professionals driving frequency and families driving per-order ticket size across metropolitan corridors.
- Families:Multi-person households generate the highest average order values through combo meals and add-on beverages. Suburban US and Chinese tier-1 cities concentrate demand where weekend ordering peaks align with leisure time constraints.
- Singles:One-person households prioritize speed and portion control, accepting premium per-unit pricing for convenience. Tokyo, Seoul, and Singapore urban cores show highest density.
- Professionals:Time-constrained white-collar workers sustain weekday lunch and dinner frequency through subscription programs and express delivery tiers.
- Students:Price-sensitive demographic segments cluster near university districts and respond to promotional pricing and group-order discounts.
Families retain the dominant revenue share, while Singles are expanding most quickly through single-serve packaging innovation and micro-fulfillment density.
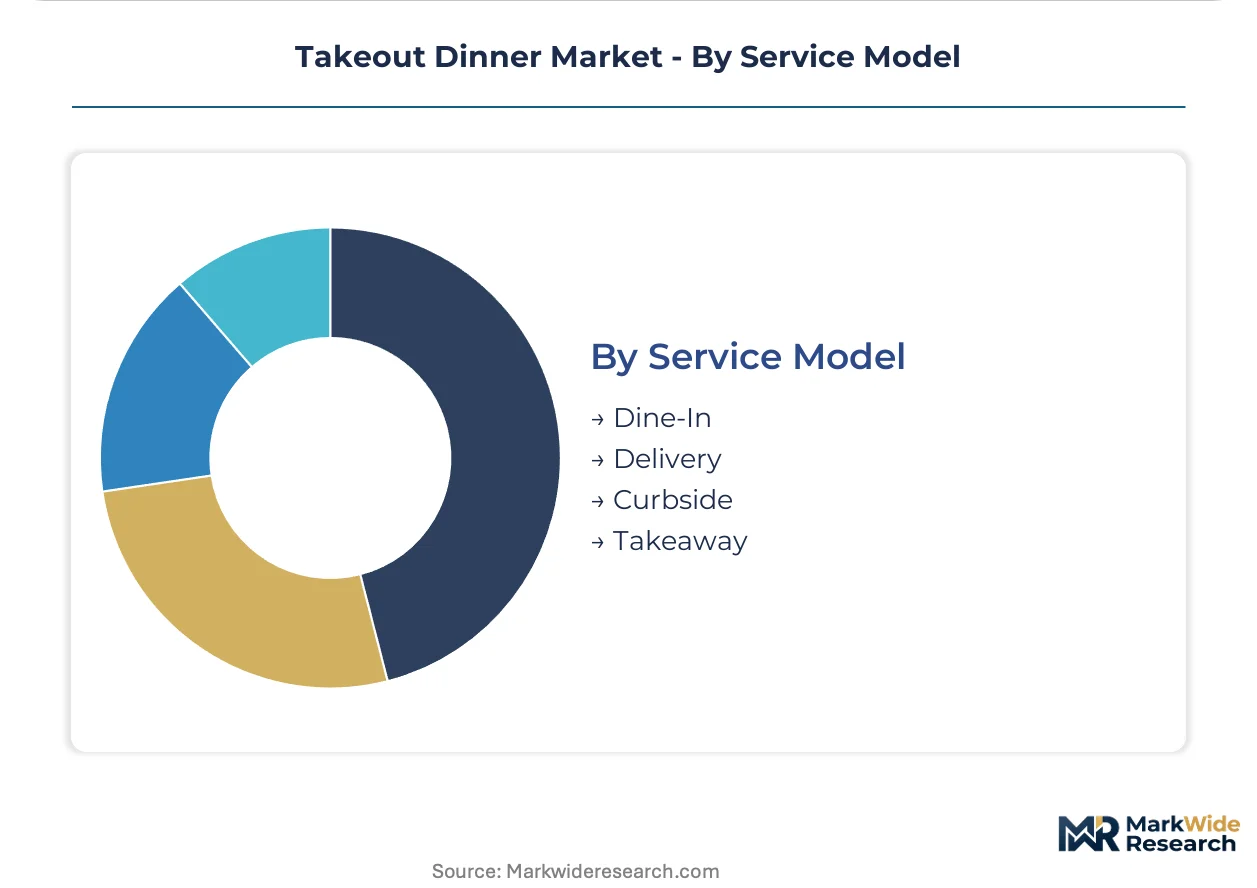
Service Model:
Maturity gradients separate established dine-in hybrids from emerging digital-native formats, with capital intensity and real estate requirements determining geographic penetration patterns.
- Dine-In:Traditional full-service restaurants with off-premises capability carry highest fixed costs but capture occasion-based demand from customers seeking brand trust. Established in all major markets with longest operational history.
- Delivery:Platform-coordinated last-mile service extends kitchen reach beyond walk-in trade. Ghost kitchen proliferation in Dallas-Fort Worth and Atlanta suburbs reduces minimum viable scale requirements.
- Curbside:Vehicle-based pickup without entering premises gained permanent adoption post-pandemic in US and Canadian markets where parking infrastructure supports the format.
- Takeaway:Counter-based collection remains the lowest-cost service model, dominant in emerging markets and dense urban cores where delivery logistics costs exceed customer willingness to pay.
Delivery captures the dominant transaction volume, while Curbside is climbing the fastest in North American suburban corridors with high vehicle ownership rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income professionals in metropolitan corridors drive order frequency, with demand clustering in urban centers where digital payment penetration and cloud kitchen density intersect. Platform algorithms allocate visibility based on logistics network coverage, favoring markets with established last-mile infrastructure.
United States
Suburban exurban rings around Dallas-Fort Worth and Atlanta attract micro-fulfillment node deployment as dark kitchen clustering captures commute-pattern demand. FDA Food Code modernization harmonizes temperature control standards across state lines, enabling multi-state platform listings for ghost kitchen operators. ServSafe certification backlogs in high-growth metropolitan areas delay kitchen launch schedules during mandatory inspection queues.
China
Tier-2 cities accelerate adoption as smartphone penetration expands digital payment infrastructure through integrated app platforms. SAMR oversight of food delivery platforms shapes commission structure regulations and rider labor classification rules. Yangtze River Delta urban cores concentrate cloud kitchen investment where real estate costs support dedicated fulfillment-only sites.
India
UPI rails reduce checkout friction for first-time app users in tier-2 cities as FSSAI-compliant cloud kitchens accelerate supply-side density. FSSAI allergen disclosure mandates and municipal health department permitting determine platform eligibility for kitchen operators. Bangalore and Mumbai metropolitan corridors show steepest expansion trajectories as household density and tech-sector employment overlap.
Germany
REACH-compliant packaging material restrictions accelerate fiber-based container R&D investment as mandatory PFAS elimination deadlines approach. Extended producer responsibility frameworks mandate reusable container systems, securing regulatory goodwill for first-mover platforms. Berlin and Hamburg urban cores concentrate premium sushi and hot-bowl operators facing steepest reformulation timelines.
United Kingdom
Corporate catering contracts sustain mid-day volume spikes through web-browser ordering channels where desktop penetration among office workers remains elevated. FSA allergen labeling requirements and municipal waste mandates reshape packaging procurement decisions. London Southeast corridor anchors platform logistics density as subscription-based ordering patterns displace impulse-driven meal selection among dual-income households.
Takeout Dinner Market Competitive Landscape
Player mix skews toward platform aggregators and quick-service chains with proprietary logistics or real estate assets. The vendor base concentrates around three strategic archetypes: algorithm-governed marketplace operators, vertically integrated restaurant chains with captive delivery infrastructure, and cloud-native kitchen operators dependent on platform visibility. Competitive moves center on last-mile density expansion through micro-fulfillment nodes and packaging innovation to extend safe holding windows.
Among platform aggregators, DoorDash and Uber Eats exemplify the algorithm-governed archetype, while Domino's Pizza represents the vertically integrated chain model with proprietary logistics control. McDonald's occupies a distinct position combining brand trust with drive-thru architecture that competes directly with aggregator economics.
| Leading Market Players |
|---|
| DoorDash |
| Uber Eats |
| Grubhub |
| Domino's Pizza |
| McDonald's |
| Yum! Brands |
| Just Eat Takeaway |
| Starbucks |
| Panda Express |
| Others |
Value Network & Pricing Analysis
Biodegradable packaging substitution for petroleum-based containers is redrawing supplier geography toward Southeast Asian fiber producers while compressing margin pass-through capacity for US and European operators facing municipal waste mandates.
Pricing Analysis
Cost-plus contracts with resin indexation dominate packaging procurement for large aggregator platforms, insulating them from spot volatility while independent operators absorb 40-60% biodegradable premiums without full tariff recovery. Three-tier pricing structure across premium sushi, standard fast-casual, and economy pizza tiers reflects certification grade and logistics density differentiation. Pricing pressure stems from municipal delivery fee caps in New York, San Francisco, and Chicago that compress per-order platform revenue. Students and price-sensitive single-person households exhibit highest price elasticity, while dual-income families with subscription commitments show lowest sensitivity.
Supply Chain Analysis
Just-in-time inventory protocols dominate perishable ingredient procurement, though phase-change material suppliers maintain strategic stockpiles of specialized thermal packaging substrates to buffer against resin supply disruptions. China, Vietnam, and Thailand concentrate biodegradable fiber container manufacturing, while US Gulf Coast and Rotterdam anchor petroleum-based packaging resin production. Raw material dependencies include expanded polystyrene alternatives, sugarcane bagasse fibers, and proprietary gel refrigerants. Single-source vulnerability runs through Southeast Asian fiber mills facing EU REACH compliance deadlines. Distribution runs through platform-coordinated last-mile networks and third-party logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around platform aggregators and subscription-committed dual-income households, fragmenting independent restaurant leverage and compressing kitchen-side margin negotiation capacity.
For Market Incumbents: Shield proprietary customer data assets through direct-order channel investment that reduces algorithmic dependency on DoorDash and Uber Eats. Deepen backward integration into cloud kitchen real estate in Dallas-Fort Worth and Atlanta suburbs to capture commute-pattern demand. Fortify ServSafe certification pipelines to preempt inspection queue delays that stall revenue recognition.
For New Entrants and Emerging Players: Lead with AI-driven demand forecasting tools that integrate weather data and event calendars to reduce preparation waste and improve fill rates during peak-hour surges. Target underpenetrated US exurban corridors where last-mile density gaps reward micro-fulfillment node deployment. Pursue municipal partnership preferences in Germany and France by deploying reusable container systems ahead of extended producer responsibility mandates.
For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors vertically integrated operators with captive logistics infrastructure and proprietary real estate assets. Long-term viability over the next decade hinges on regulatory compliance automation and packaging innovation R&D pipelines. Acquisition targets should demonstrate multi-state FDA Food Code permitting and established aggregator API connectivity. Watch for inflection when municipal ghost kitchen permitting timelines compress below 30 days in high-growth metropolitan areas.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Micro-Fulfillment Expansion | Dark kitchen clustering around Dallas-Fort Worth and Atlanta highway interchanges captures commute-pattern demand density. |
| Biodegradable Packaging R&D Investment | Fiber-based container innovation addresses EU REACH PFAS elimination deadlines for premium sushi operators. |
| Direct-Order Channel Development | Proprietary app investment reduces algorithmic gatekeeper dependency and preserves customer data ownership. |
| AI Demand Forecasting Integration | Kitchen management systems incorporating weather and event data compress inventory carrying costs during peak surges. |
| Reusable Container System Deployment | First-mover platforms in Germany and France secure regulatory goodwill under extended producer responsibility frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud kitchen operators, aggregator platform logistics directors, restaurant procurement managers, and municipal health department inspectors. Secondary validation drew from FDA Food Code filings, FSSAI compliance databases, EU REACH substance restriction notices, and platform commission structure disclosures. Bottom-up kitchen count estimates and top-down consumer expenditure patterns were triangulated to anchor market sizing.
Across the analysis window, forecasts model product type segmentation by heat retention characteristics, order method by payment infrastructure maturity, customer type by household composition, and service model by real estate intensity. CAGRs derive from logistic diffusion curves fitted to smartphone penetration and digital payment adoption rates. Industry-specific inputs include UPI transaction velocity in Indian tier-2 cities and ServSafe certification throughput in US metropolitan health departments.
Forecasts assume regulatory continuity in FDA Food Code modernization, EU REACH packaging restrictions, and FSSAI cloud kitchen permitting; material policy shifts would require re-modeling. Revision becomes warranted when biodegradable packaging cost premiums compress below 20% of petroleum-based alternatives or when municipal delivery fee caps spread beyond current New York, San Francisco, and Chicago jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Chained Consumer Foodservice Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Online Grocery Market
Food Service
Rotisseries Market
Food Service
India Full Service Restaurants Market
Food Service
Quick-Service Restaurants Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Restaurant Griddle Market
Food Service
Global Meal Kit Market
Food Service
Snack Subscription Box Service Market
Food Service
Instant Grocery Market
Food Service
Contract Blending Services Market
Food Service
Europe Online Grocery Market
Food Service
Plates Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
China Food Service Market