
 Latin America Automotive High Performance Electric Vehicle Market | 2026-2036
Latin America Automotive High Performance Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive High Performance Electric Vehicle Market Intelligence
Brazil's Rota 2030 program, with its tax incentives for energy-efficient vehicles, is pivoting the cost-of-entry calculus for premium EV brands. Porsche leverages its established brand prestige in the exclusive luxury sports car segment. Tesla sustains its market presence through a direct-to-consumer model and its proprietary Supercharger network. Meanwhile, BYD competes by introducing performance models derived from its broader, volume-focused electric vehicle platform.
Automotive high-performance electric vehicles are defined by rapid acceleration, often under 4.5 seconds 0-100 km/h, and large battery packs over 80 kWh. These vehicles serve a premium consumer base in Latin America by combining advanced powertrain technology with superior driving dynamics. Electric SUVs and Luxury Sedans represent the dominant vehicle types by sales. The expansion of public Fast Chargers is essential for market growth, more so than home charging solutions for this specific buyer.
Vehicle homologation and import policies are governed by national bodies like Brazil's National Traffic Council (CONTRAN) and through NOM standards in Mexico. These regulations directly impact vehicle specifications and final consumer pricing through complex tariff and tax structures. Therefore, strategic decisions regarding local partnerships versus a direct importation model will determine long-term market share.
Market Dynamics
The primary force shaping the Latin America high-performance EV market is the interplay between concentrated urban wealth and the strategic, yet uneven, deployment of fast-charging infrastructure. This dynamic creates pockets of high adoption in megacities while limiting broader geographic expansion.
Growth Catalysts
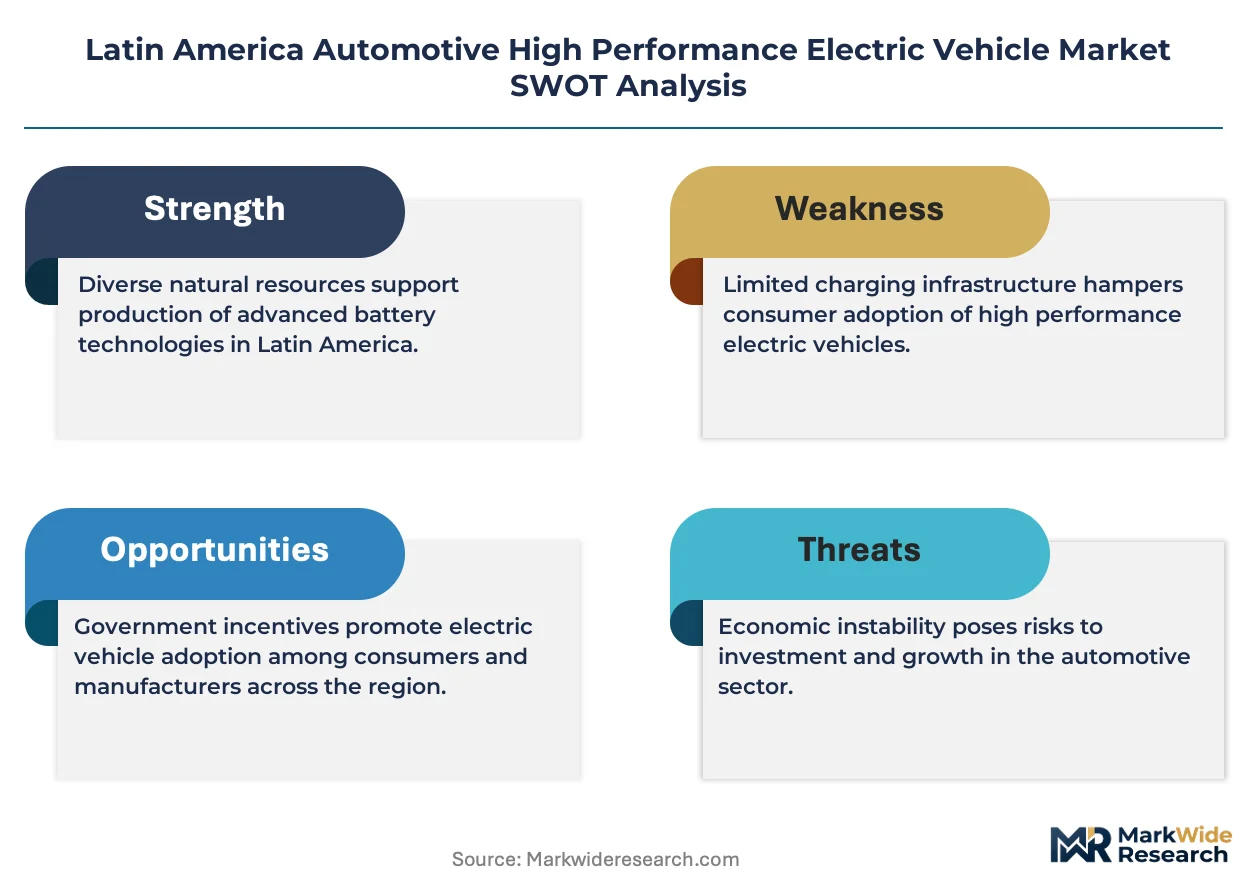
- Government Incentives:Brazil's Rota 2030 program is lowering the effective price of energy-efficient vehicles through tax reductions, making high-performance EVs more financially accessible to the premium consumer segment and stimulating import activity.
- Urban Infrastructure Expansion:The targeted build-out of public DC fast-charging stations in major metropolitan areas like Bogotá and São Paulo is alleviating range anxiety and increasing the day-to-day usability for city-dwelling owners.
- Status-Driven Consumer Demand:Affluent buyers in key urban centers are adopting high-performance EVs as symbols of technological sophistication and environmental consciousness, creating a strong pull for premium brands offering advanced powertrain technology.
Market Restraints
- High Import Tariffs:Complex tariff and tax structures imposed by national bodies in countries like Brazil and Mexico significantly inflate the final consumer price, limiting the addressable market to the highest income brackets.
- Fragmented Charging Networks:The lack of a standardized, interoperable fast-charging network between major cities and across national borders restricts long-distance travel and confines practical usage to metropolitan regions.
- Grid Instability:The high power demands of DC fast chargers and multiple high-performance EVs charging simultaneously can strain local electrical grids in certain districts, posing a barrier to widespread infrastructure deployment.
Strategic Opportunities
- Secondary City Expansion:With market activity concentrated in Brazil and Mexico, significant opportunity exists to develop sales and service infrastructure in other major, high-income Latin American cities like Santiago, Chile.
- Local Assembly Partnerships:Forming partnerships for semi-knocked-down (SKD) or complete-knocked-down (CKD) assembly can help automakers mitigate prohibitive import duties and navigate complex national homologation requirements more effectively.
- Performance Crossover Segment:While luxury sedans and large SUVs currently dominate, there is an untapped opportunity for high-performance electric crossover utility vehicles (CUVs) that blend sporty driving dynamics with a smaller footprint.
Industry Challenges
- Vehicle Homologation:Navigating the disparate and lengthy vehicle certification processes, such as Brazil's CONTRAN regulations and Mexico's NOM standards, creates significant administrative overhead and delays market entry for new models.
- Specialized Service Infrastructure:A scarcity of technicians trained in high-voltage battery systems and advanced EV diagnostics creates a service bottleneck, undermining the ownership experience and brand reputation outside of primary cities.
- Battery Logistics and Replacement:Managing the logistics of importing, storing, and handling large, heavy, and regulated battery packs for warranty claims or post-accident repairs presents a substantial operational and cost challenge across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive High Performance Electric Vehicle Market |
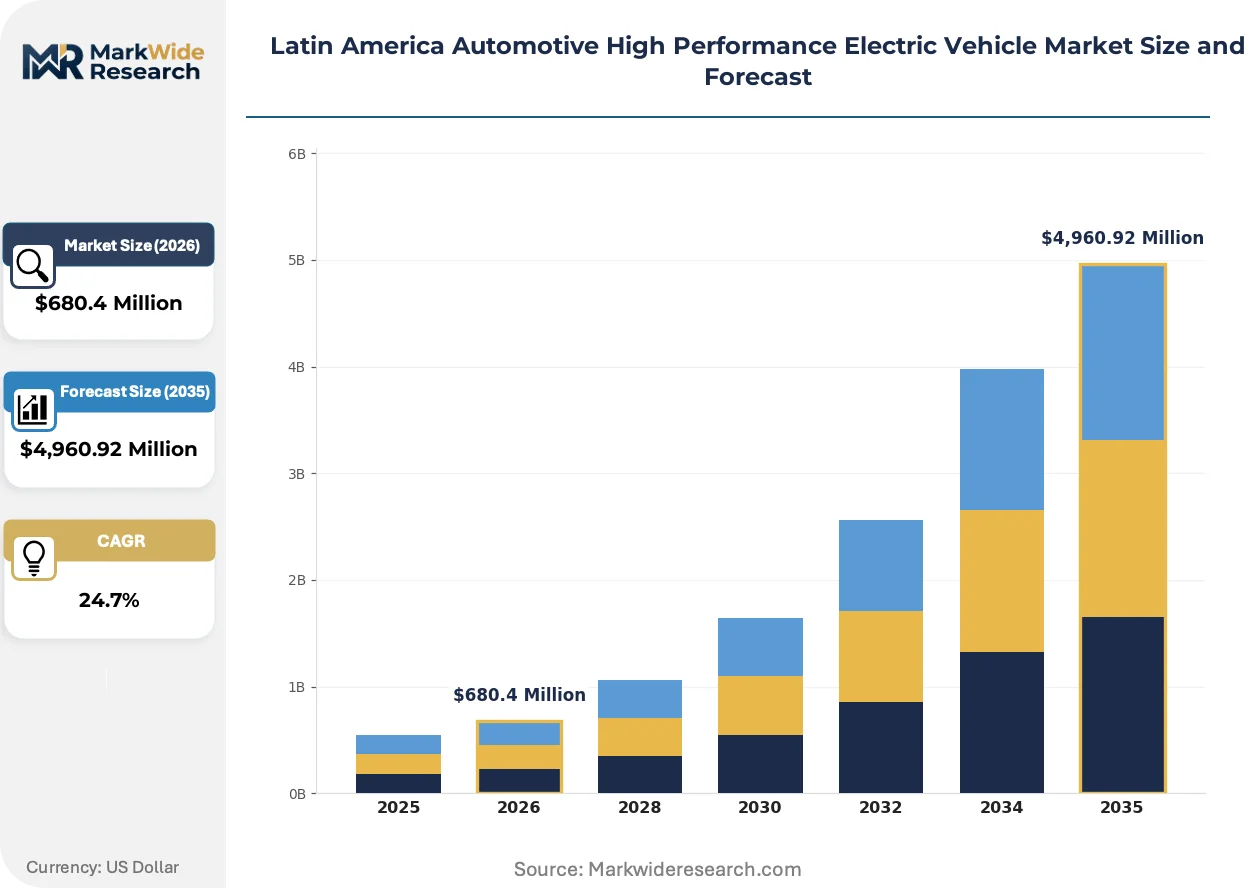
| Market Size in 2026 | $680.4 Million |
| Market Size in 2035 | $4,960.92 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sports Cars, Luxury Sedans, Electric SUVs, Performance Hatchbacks, Coupes Battery Technology: Lithium-ion, Solid-State, Nickel-Metal Hydride, Lithium-Polymer, Lead Acid Charging Infrastructure: Fast Chargers, Destination Chargers, Home Chargers, Wireless Chargers, Battery Swapping End User: Independent Dealerships, OEMs, Specialty Retailers, Fleet Operators, Private Buyers |
| Companies Covered | Mercedes-Benz Group, Ford, Tesla, Nissan Motor, Volkswagen, BYD, General Motors, Porsche, BMW Group, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive High Performance Electric Vehicle Market Strategic Shifts & Innovations
The market is defined by the adaptation of global electric vehicle platforms to meet the unique expectations of Latin America's premium consumer base. This involves balancing cutting-edge performance with the practical realities of regional infrastructure and import regulations.
Advanced battery and powertrain systems are the core technological enabler. These platforms typically feature large battery packs exceeding 80 kWh and dual-motor all-wheel-drive configurations for rapid acceleration. Affluent urban consumers in Brazil and Mexico are adopting these technologies immediately upon release. This trend is modularizing vehicle design, allowing brands to leverage a single performance-oriented electric architecture across multiple vehicle types, from sedans to SUVs.
National industrial policies are directly influencing which models are available and at what price. Brazil's Rota 2030 program, for instance, rewards energy efficiency and local investment with significant tax credits. The industrial consequence is a strategic shift by automakers to prioritize the importation of their most efficient high-performance variants. The luxury SUV and sedan segments are most affected, as brands carefully select their product mix to maximize these incentives.
A notable behavioral shift is occurring in how these premium vehicles are purchased. The direct-to-consumer (DTC) sales model, often featuring online configuration and ordering, is gaining traction over traditional dealership visits. This channel innovation disrupts the established networks of multi-brand luxury importers who have historically controlled market access. This trend is most prominent in the major metropolitan markets of Brazil and Mexico, appealing to a digitally native buyer cohort.
Latin America Automotive High Performance Electric Vehicle Market Segmentation
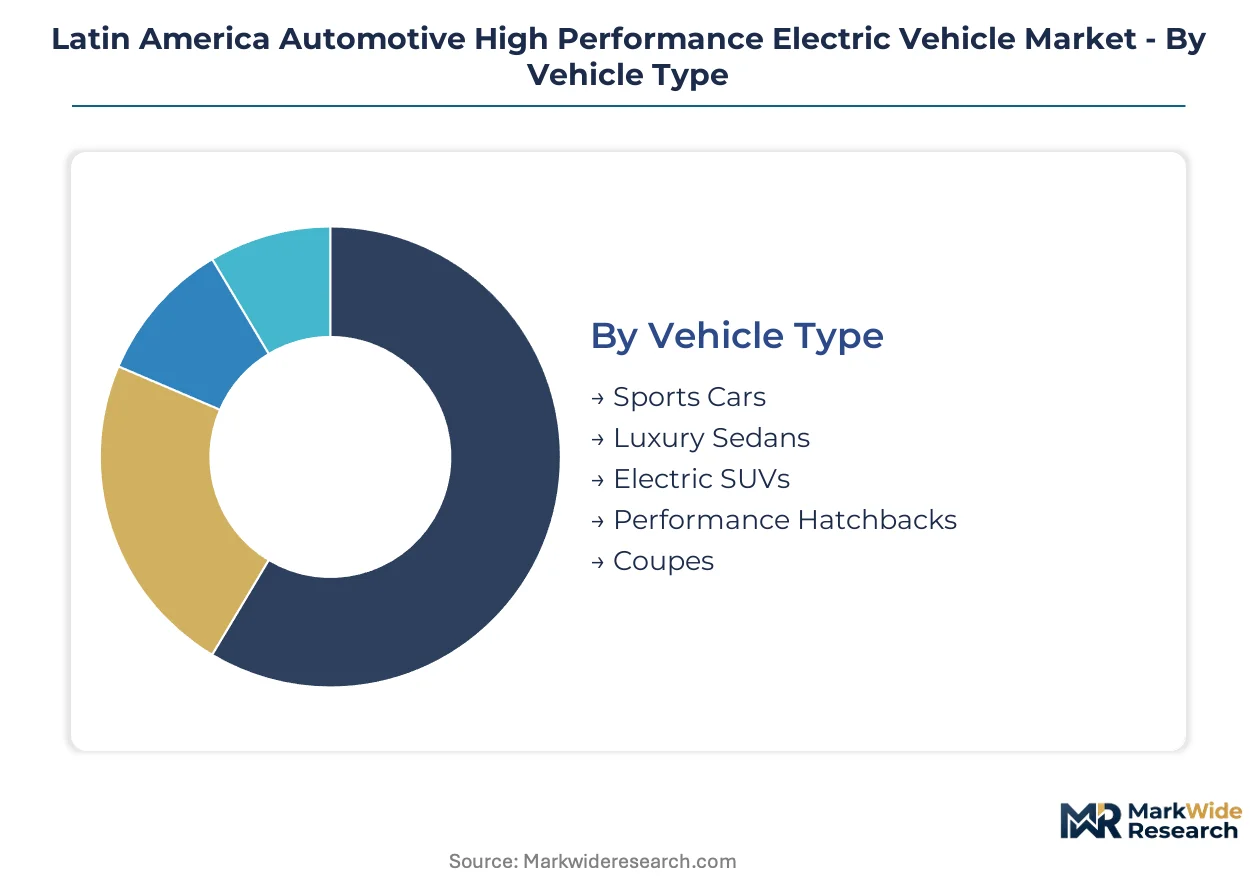
The Latin America automotive high-performance electric vehicle market is segmented to reveal distinct consumer preferences and technological adoption patterns. This analysis highlights how different vehicle types, battery technologies, charging solutions, and end-user groups contribute to the market's evolving structure. Understanding these segments is crucial for strategic market entry and product positioning across the region.
Vehicle Type:
The supply concentration for high-performance electric vehicles in Latin America currently favors models that blend luxury with advanced powertrain capabilities. Manufacturers are prioritizing the introduction of vehicle types that align with the purchasing power and status aspirations of affluent urban consumers, particularly in Brazil and Mexico.
- Electric SUVs:These vehicles feature large battery packs, powerful electric motors, and often all-wheel-drive configurations, providing both rapid acceleration and spacious interiors. Demand for electric SUVs is particularly strong among premium buyers in São Paulo and Mexico City, who value their versatility and commanding presence.
- Luxury Sedans:Defined by sophisticated design, advanced infotainment systems, and high-output electric powertrains, these sedans offer superior comfort and driving dynamics. Affluent consumers in major metropolitan areas are adopting luxury electric sedans as a primary vehicle, valuing their blend of performance and prestige.
- Sports Cars:These high-performance electric vehicles prioritize extreme acceleration and agile handling, often featuring bespoke chassis and advanced aerodynamic designs. Niche demand exists among enthusiasts who seek the ultimate driving experience, largely concentrated in exclusive urban enclaves.
- Performance Hatchbacks:Offering a compact footprint combined with robust electric motor performance, these vehicles target urban dwellers seeking agility and spirited driving. This segment is slowly gaining traction as more affordable high-performance options emerge.
- Coupes:Electric coupes deliver a blend of sporty aesthetics and strong acceleration, appealing to buyers who prioritize style and dynamic performance. Their market presence remains limited, catering to a specific design-conscious demographic.
Electric SUVs absorbs the bulk of installed capacity; Luxury Sedans is expanding most quickly.
Battery Technology:
The application requirements for high-performance electric vehicles necessitate battery technologies that deliver both high energy density for range and high power output for rapid acceleration. Material science advancements continue to shape the viability and cost-effectiveness of various battery chemistries, influencing their deployment in premium vehicles.
- Lithium-ion:This technology forms the backbone of current high-performance EVs, offering excellent energy density and power output suitable for large battery packs. Its widespread adoption is driven by established manufacturing processes and continuous performance improvements in range and charging speeds.
- Solid-State:Representing the next generation, solid-state batteries promise higher energy density, faster charging, and enhanced safety compared to traditional lithium-ion cells. Research and development efforts are intensifying to overcome manufacturing challenges and bring this technology to commercial scale within the decade.
- Nickel-Metal Hydride:Primarily found in older hybrid electric vehicles, this battery chemistry offers lower energy density and power output unsuitable for modern high-performance EVs. Its usage in new high-performance electric vehicle designs is negligible due to performance limitations.
- Lithium-Polymer:Similar to lithium-ion, these batteries use a polymer electrolyte, allowing for flexible form factors and potentially higher energy density in specific applications. Some manufacturers use variations of this technology for packaging flexibility in performance models.
- Lead Acid:This mature battery technology is unsuitable for high-performance EV propulsion due to its low energy density and heavy weight. It is typically confined to 12V auxiliary systems within electric vehicles, powering non-propulsion components.
Lithium-ion technology currently dominates the market; Solid-State solutions are experiencing the steepest expansion trajectory.
Charging Infrastructure:
The customer type significantly influences the demand for specific charging infrastructure solutions, with high-performance EV owners prioritizing convenience and speed. Public fast-charging networks are crucial for urban usability, while home charging remains important for daily convenience, albeit less critical for range anxiety for this segment.
- Fast Chargers:These high-power DC charging stations are essential for high-performance EV owners, enabling rapid replenishment of large battery packs for extended travel or quick turnaround. Their targeted build-out in major Latin American cities like Bogotá and São Paulo directly supports market growth by alleviating range anxiety.
- Home Chargers:Typically Level 2 AC chargers, these solutions provide convenient overnight charging for owners at their residences, ensuring a full battery for daily commutes. While important for routine use, home charging alone does not address the long-distance travel needs of high-performance EV owners.
- Destination Chargers:Located at hotels, shopping centers, and workplaces, these chargers offer convenient charging opportunities during longer stops, typically at Level 2 AC speeds. They enhance the overall usability of high-performance EVs by integrating charging into daily activities.
- Wireless Chargers:This emerging technology allows for inductive charging without physical cables, offering a high level of convenience for specific parking scenarios. Wireless charging adoption remains nascent, primarily in pilot programs and luxury concepts.
- Battery Swapping:Involving the rapid exchange of a depleted battery pack for a fully charged one, this solution aims to eliminate charging downtime entirely. This model faces significant standardization and infrastructure challenges, limiting its current applicability for high-performance EVs.
Fast Chargers cater to the most immediate need for high-performance EV owners; Home Chargers maintain consistent utility for daily use.
End User:
The margin structures and service expectations associated with high-performance electric vehicles dictate distinct approaches for various end-user segments. Direct-to-consumer models are gaining traction, while traditional sales channels adapt to the unique requirements of EV sales and service.
- Private Buyers:This segment comprises affluent individuals in urban centers who purchase high-performance EVs for personal use, driven by status, technology, and environmental consciousness. Their purchasing decisions are often influenced by brand prestige and vehicle performance metrics.
- OEMs:Original Equipment Manufacturers are both producers and sometimes direct sellers of high-performance EVs, particularly through direct-to-consumer models like Tesla's. They manage the entire value chain from manufacturing to after-sales service for their proprietary brands.
- Independent Dealerships:These multi-brand retailers sell and service various automotive brands, including high-performance EVs, acting as intermediaries between manufacturers and private buyers. They navigate complex import policies and local homologation requirements.
- Specialty Retailers:Focused on niche luxury or performance vehicle markets, these retailers offer curated selections of high-performance EVs, often providing bespoke customization options and white-glove service. They cater to a discerning clientele seeking exclusivity.
- Fleet Operators:This segment includes companies or organizations that acquire multiple high-performance EVs for specific business applications, such as luxury car rentals or executive transport services. Their purchasing decisions are based on operational efficiency and brand image.
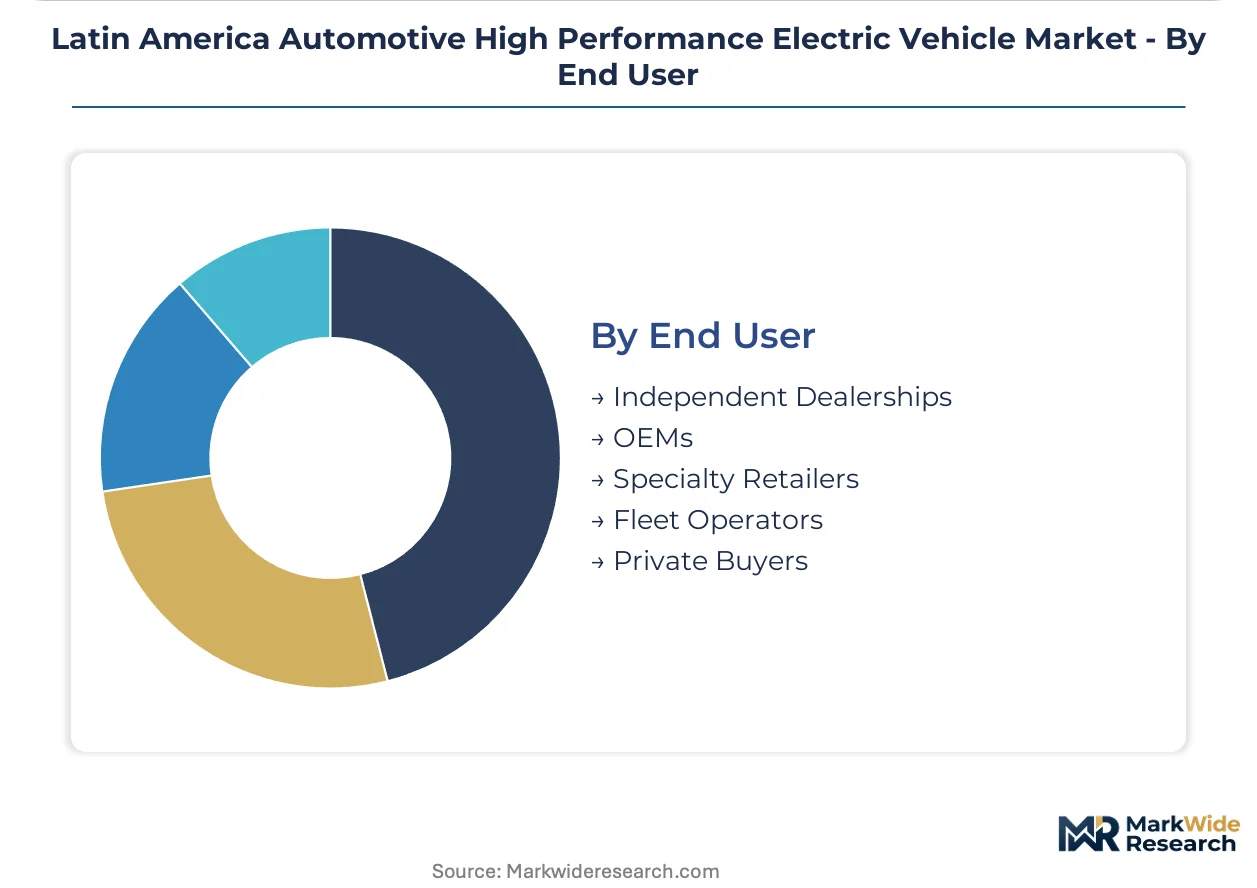
Private Buyers constitute the largest consumer base; OEMs are increasingly influencing sales channels through direct models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for high-performance electric vehicles concentrates in Latin America's major urban centers. Affluent private buyers in these cities drive premium segment growth. Strategic deployment of fast-charging infrastructure supports this localized expansion.
Brazil
Affluent buyers in São Paulo and Rio de Janeiro generate substantial demand for high-performance EVs. Brazil's Rota 2030 program offers tax incentives for energy-efficient vehicles, stimulating imports. São Paulo sees significant market activity and dedicated infrastructure build-out for these premium models.
Mexico
Premium consumers in Mexico City and Monterrey actively seek advanced electric vehicle options. Mexico's NOM standards govern vehicle homologation and import policies, influencing market entry. The Mexico City metropolitan area experiences high adoption of luxury electric vehicles.
Colombia
Urban consumers in Bogotá value advanced EV technology and sustainable mobility solutions. Government initiatives in Colombia support the expansion of public fast-charging networks. Bogotá is a key city for targeted infrastructure development and high-performance EV sales.
Chile
High-income consumers in Santiago demonstrate a strong preference for premium electric vehicles. Chile's import policies directly influence vehicle availability and final consumer pricing. Santiago presents a significant opportunity for sales and specialized service infrastructure development.
Latin America Automotive High Performance Electric Vehicle Market Key Industry Players
European and Asian automotive giants anchor one tier; specialized electric vehicle manufacturers hold another. The market exhibits a tiered structure, with established luxury brands competing against dedicated EV innovators. Traditional automakers leverage existing brand prestige, while direct-to-consumer models disrupt established sales channels. Geographic expansion into underserved urban centers and strategic partnerships for local assembly are dominant competitive moves.
Within the high-performance segment, Tesla, a US-based manufacturer, exemplifies the direct-to-consumer sales model. Porsche, a German luxury sports car producer, leverages its established brand prestige in exclusive markets. BYD, a Chinese multinational, occupies a position focused on introducing performance models derived from broader electric vehicle platforms. These companies collectively shape the competitive dynamics through distinct market approaches.
| Leading Market Players |
|---|
| Mercedes-Benz Group |
| Ford |
| Tesla |
| Nissan Motor |
| Volkswagen |
| BYD |
| General Motors |
| Porsche |
| BMW Group |
| Others |
Cost & Logistics Intelligence
Battery cell costs, originating from Asian manufacturing hubs, propagate through regional assembly plants, ultimately influencing the premium pricing tier for Latin American high-performance EVs.
Pricing Analysis
Demand for short lead-time delivery commands a premium in the Latin America high-performance EV market. The dominant pricing model is per-unit transactional, where brand prestige and advanced after-sales service drive significant price differentiation. Pricing pressure stems from high import tariffs, limiting the addressable market to the highest income brackets. Fleet operators exhibit the most price sensitivity, while affluent private buyers demonstrate lower price elasticity for premium models.
Supply Chain Analysis
Brazil's Rota 2030 program, with its local content mandates, reshapes component sourcing strategies for high-performance EV manufacturers. Geographic supply concentration draws from China for battery cells and Mexico for vehicle assembly. The market relies heavily on lithium and advanced semiconductor components. Tariff exposure represents a significant structural supply chain risk, inflating final consumer prices. Distribution runs through a dual model of direct-to-consumer channels and established independent dealerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America high-performance EV market operates as a supply-constrained environment, where limited public fast-charging infrastructure capacity props up premium vehicle pricing.
For Market Incumbents: Deploy strategic partnerships with local energy providers to expand fast-charging infrastructure, mitigating range anxiety and protecting market share from emerging direct-to-consumer brands. Focus on local assembly partnerships to navigate complex import duties, countering the threat of new market entrants leveraging more favorable national policies. Invest in specialized high-voltage service training programs across key metropolitan areas.
For New Entrants and Emerging Players: Affluent buyers in secondary urban centers like Santiago represent an underserved segment for high-performance electric vehicles. Target these cities by establishing localized sales and service hubs, offering bespoke customization options. A go-to-market angle focusing on advanced connectivity features and sustainable luxury appeals strongly to this discerning demographic.
For Investors and Strategic Acquirers: The expansion of public fast-charging networks is the leading indicator that broadens market accessibility beyond initial urban clusters. Long-term viability within the next five to ten years centers on companies capable of navigating complex national homologation requirements and establishing robust after-sales service networks. An acquisition target archetype involves specialized EV service providers or regional logistics firms with established infrastructure. Monitor government incentives for local manufacturing as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnerships | Mitigates import tariffs and complex homologation, reducing final consumer pricing. |
| Fast-Charging Network Expansion | Alleviates range anxiety for premium buyers, increasing daily vehicle usability. |
| Specialized Service Training | Addresses the scarcity of skilled technicians, improving ownership experience and brand loyalty. |
| Performance Crossover Development | Captures untapped demand for versatile, smaller-footprint high-performance electric vehicles. |
| Direct-to-Consumer Channel Investment | Streamlines sales processes and enhances customer relationships, disrupting traditional dealership models. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, which were then validated through primary interviews with industry stakeholders. This included conversations with OEM platform engineers, dealership operations managers, charging infrastructure developers, and national traffic council representatives. The approach combined bottom-up data aggregation with top-down market sizing for comprehensive analysis.
Data-stream reconciliation formed the basis of the analytical framework, modeling market dynamics across the projection horizon. Segmentation dimensions included vehicle class, propulsion architecture, battery technology, and regional urban clusters. Compound annual growth rates were derived through a proprietary algorithm considering historical trends and forecast inputs such as planned charging infrastructure deployments and evolving import policies.
Revisions become necessary when significant shifts in national industrial policy or major infrastructure investment patterns materialize. Forecasts reflect assumptions regarding economic stability and consumer purchasing power within the region. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Scooter Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Electric Van Market
Electric Vehicles
Solar Electric Car Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
Automotive EV HUB Market
Electric Vehicles
Electric Vehicle Relay Market