
 US Electric UTV and ATV Powertrain Market | 2026-2036
US Electric UTV and ATV Powertrain Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric UTV and ATV Powertrain Market Insights
FMVSS certification is bifurcating the competitive landscape into qualified suppliers and aspirants still navigating validation cycles. BorgWarner Inc. leverages its integrated e-axle architecture to anchor high-torque applications for commercial UTV platforms. DANA Limited sustains a dominant position in driveline electrification through its Spicer Electrified portfolio purpose-built for off-highway duty cycles. GKN Automotive Limited differentiates via its eDrive systems optimized for the transient loads characteristic of ATV terrain traversal.
The US electric UTV and ATV powertrain encompasses the complete electromechanical propulsion system—motor, inverter, reduction gearbox, and thermal management—typically delivering 5-20 kW continuous output with peak torque exceeding 300 Nm for utility-grade hill-climb and towing performance. Its primary purpose is replacing internal combustion engines in side-by-side and quad platforms with zero-emission alternatives capable of matching or exceeding diesel torque curves at low RPM. Lithium-ion battery configurations currently occupy the majority of new platform designs due to energy density advantages, though solid-state chemistries represent the fastest-growing R&D allocation as manufacturers pursue extended range without weight penalties. The 15-20 kW and above-20 kW power rating brackets concentrate margin pools, reflecting the premium pricing commanded by full-size utility platforms deployed in agricultural and industrial end uses where duty cycles demand sustained high output.
EPA emissions regulations for nonroad spark-ignition and compression-ignition engines are compelling OEMs to accelerate electrification roadmaps or face phased compliance penalties. NHTSA's evolving FMVSS applicability to low-speed vehicles creates additional certification burdens that favor established Tier 1 suppliers with validation infrastructure. OSHA workplace safety standards for industrial and agricultural equipment operation indirectly shape powertrain specification by mandating noise reduction and eliminating hot exhaust components in enclosed environments. Stakeholders must monitor how state-level zero-emission equipment mandates propagate from California's Advanced Clean Trucks framework into off-road categories, as this trajectory will determine whether battery-electric or hybrid architectures capture the dominant investment share.
Market Dynamics
EPA's Tier 4 Final emissions mandates for off-road compression-ignition engines are forcing agricultural OEMs to abandon diesel architectures entirely, compressing electrification timelines from decade-long roadmaps to immediate procurement decisions.
Growth Catalysts
- California's Advanced Clean Trucks Framework:State-level zero-emission mandates for off-road equipment are creating compliance-driven demand pull from fleet operators seeking to preempt federal standard adoption.
- Lithium iron phosphate chemistries:Thermal stability advantages in high-vibration ATV duty cycles are accelerating platform redesigns away from nickel-based cathode formulations.
- Texas Panhandle cotton operations:Large-scale irrigated farming complexes are consolidating vehicle procurement into electrified fleet contracts exceeding fifty units annually.
Market Restraints
- Neodymium price volatility:Rare-earth magnet supply concentration in Chinese processing facilities creates input cost instability for permanent-magnet motor architectures.
- Charging infrastructure gaps:Rural electrical grid capacity limitations in upper Midwest ranching territories constrain depot-based fleet charging at required power levels.
- FMVSS 500 low-speed vehicle certification:NHTSA validation timelines extending eighteen to twenty-four months delay platform launches for road-legal utility variants.
Strategic Opportunities
- Solid-state battery convergence:Sulfide electrolyte formulations paired with silicon anodes promise energy density doubling without thermal runaway risks in rough-terrain applications.
- Upper Midwest dairy cooperatives:Wisconsin and Minnesota milk haulage operations represent untapped demand for silent-running electric UTVs in barn-adjacent environments.
- USDA conservation incentive programs:Equipment cost-share grants for emission-reducing agricultural technology are subsidizing powertrain electrification investments.
Industry Challenges
- Power electronics thermal management:Inverter reliability under mud-immersion and shock-load conditions exceeds automotive-grade validation protocols.
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise for motor control systems commands premium compensation in a shallow talent pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric UTV and ATV Powertrain Market |
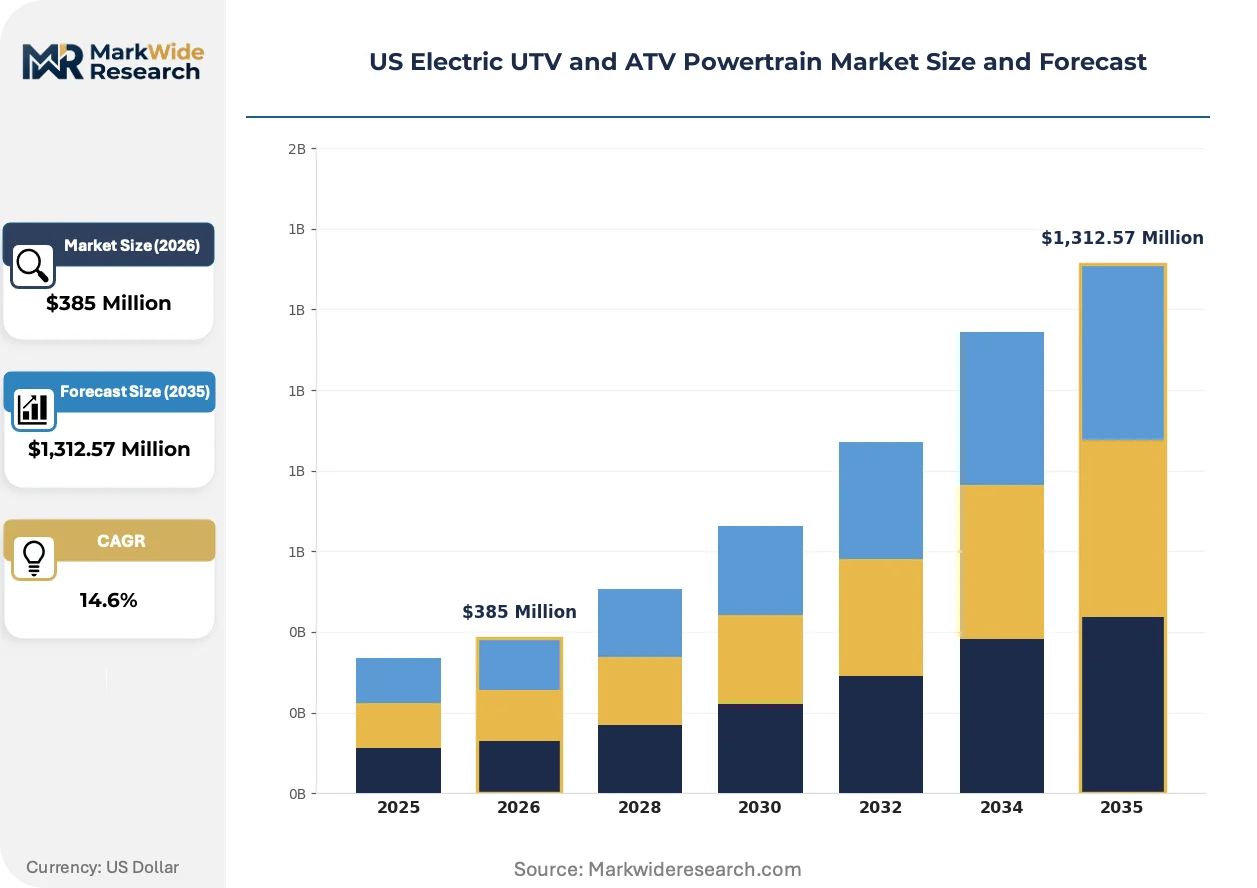
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $1,312.57 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric UTVs, Electric ATVs, Hybrid UTVs, Hybrid ATVs Power Rating: 5-10 kW, 10-15 kW, 15-20 kW, Above 20 kW Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state End User: Agriculture, Recreation, Military, Industrial |
| Companies Covered | DANA Limited, GKN Automotive Limited, BorgWarner Inc., HyperCraft, Curtis Instruments, Inc., American Axle & Manufacturing, Inc., NIDEC CORPORATION, Yamaha Motor Co., Ltd., Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric UTV and ATV Powertrain Market Trends and Innovations
Electrification architectures are diverging between integrated e-axle platforms and modular hub-motor configurations, with thermal management emerging as the decisive engineering battleground for sustained high-torque operation.
Silicon carbide MOSFETs are supplanting insulated-gate bipolar transistors in traction inverters, cutting switching losses by two-thirds. Texas-based cotton gin operators are specifying SiC-based powertrains for their twenty-four-hour harvest-season duty cycles. This semiconductor transition is compressing thermal packaging volumes and enabling liquid-cooled inverter designs that match diesel power density in confined chassis spaces.
OSHA's updated permissible exposure limits for industrial noise are compelling enclosed-cab UTV designs to eliminate engine-generated sound signatures entirely. Agricultural employers in California's Central Valley are retrofitting hearing conservation programs around electric fleet transitions. The regulation is accelerating demand for sub-seventy-decibel powertrains in material-handling and crop-monitoring applications.
Fleet managers are consolidating supplier relationships around powertrain-as-a-service contracts that bundle hardware, maintenance, and energy costs per operating hour. Large-scale vegetable growers in Arizona's Yuma County are piloting subscription-based electric UTV deployments that eliminate capital expenditure approval cycles. This procurement evolution is concentrating vendor selection criteria on total cost of ownership modeling rather than upfront platform pricing.
US Electric UTV and ATV Powertrain Market Segmentation
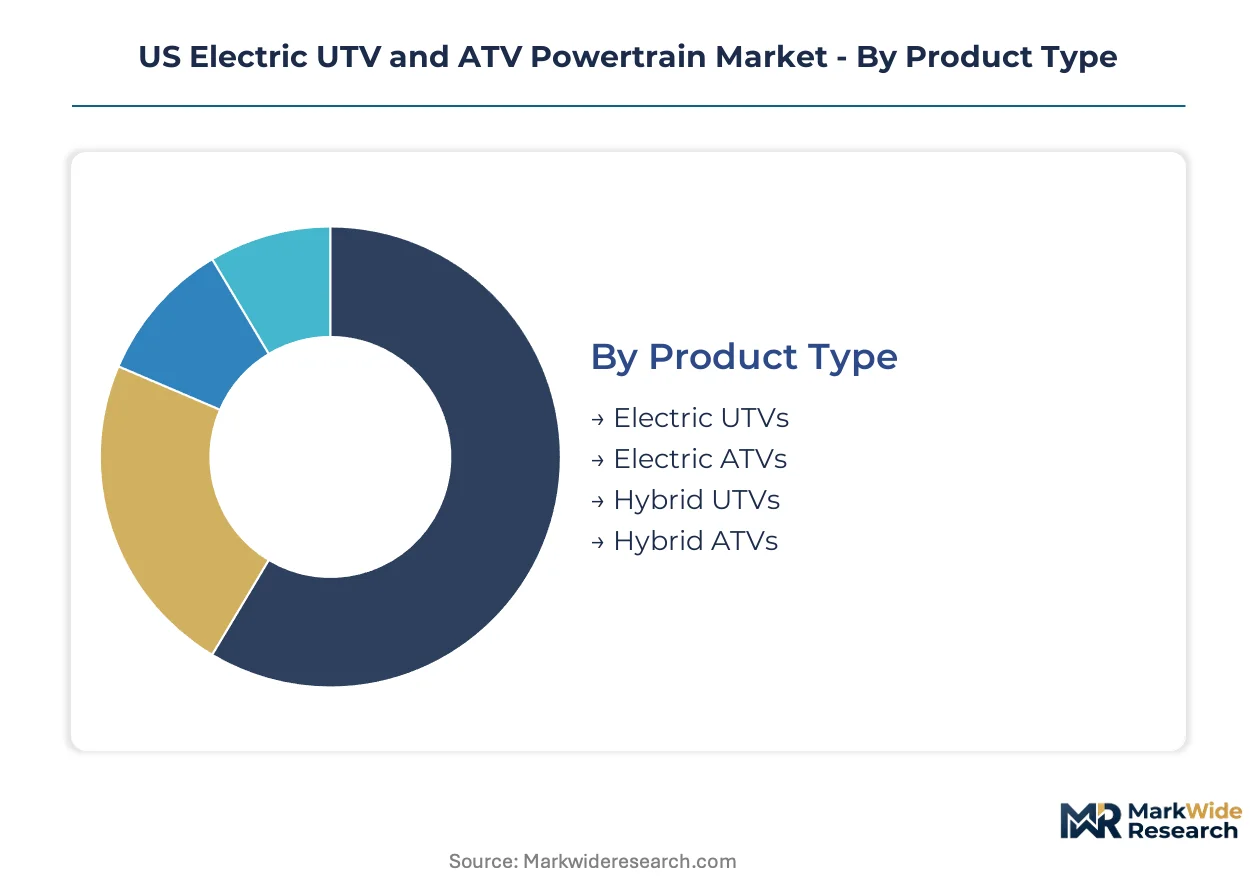
Powertrain specification varies sharply across duty cycles, with agricultural fleet procurement favoring high-torque continuous-output architectures while recreational demand prioritizes burst acceleration and weight reduction. Segmentation clarity enables suppliers to align thermal management strategies and battery chemistry selections with validated use-case economics.
Product Type:
Channel distribution bifurcates between OEM factory-fit programs for new platforms and aftermarket retrofit kits targeting diesel replacement cycles in existing fleets.
- Electric UTVs:Side-by-side configurations dominate agricultural and industrial procurement, with integrated e-axle architectures delivering sustained torque for towing and payload applications. Texas cotton operations and California Central Valley vegetable growers are consolidating fleet contracts around road-legal utility variants requiring FMVSS 500 certification.
- Electric ATVs:Quad-platform designs emphasize transient load response for terrain traversal, with hub-motor configurations gaining traction in recreational segments. Arizona desert recreation operators and upper Midwest hunting outfitters specify sealed powertrains for dust and water-immersion resistance.
- Hybrid UTVs:Range-extender architectures address charging infrastructure gaps in remote ranching territories.
- Hybrid ATVs:Series-hybrid configurations serve military and border patrol applications requiring silent-watch capability.
By volume, Electric UTVs lead. By growth pace, Electric ATVs are expanding most quickly.
Power Rating:
Cost tiering concentrates margin capture in higher-output brackets where thermal management complexity justifies premium positioning.
- 5-10 kW:Entry-level continuous output serves light utility and recreational trail riding, with air-cooled motor designs minimizing cost. California golf course maintenance and Arizona estate management operations specify these powertrains for low-speed material transport.
- 10-15 kW:Mid-tier output matches compact diesel torque curves for small-farm applications, with liquid-cooled inverters enabling sustained hill-climb performance. Wisconsin dairy operations and Minnesota organic vegetable farms are accelerating procurement in this bracket.
- 15-20 kW:Full-size utility duty cycles demand this output band for towing implements and operating PTO-driven equipment.
- Above 20 kW:Heavy-duty agricultural and industrial platforms require peak torque exceeding 400 Nm for deep-terrain traction.
By revenue concentration, 15-20 kW and Above 20 kW brackets dominate. By adoption velocity, 10-15 kW is climbing the fastest among mid-scale operators.
Battery Type:
Application requirements dictate chemistry selection, with thermal stability and cycle life trumping energy density in high-vibration duty cycles.
- Lithium-ion:Nickel-manganese-cobalt and lithium iron phosphate formulations occupy the majority of new platform designs, with LFP chemistries accelerating in ATV applications due to thermal stability advantages. Texas Panhandle cotton gins and Kansas grain elevators specify LFP packs for harvest-season reliability.
- Solid-state:Sulfide electrolyte formulations paired with silicon anodes represent the steepest expansion trajectory, promising doubled energy density without thermal runaway risks in rough-terrain immersion. R&D allocation is concentrating in defense and premium agricultural segments.
- Lead-acid:Flooded and AGM configurations persist in cost-sensitive retrofit applications.
- Nickel-metal Hydride:Limited presence in legacy hybrid architectures transitioning to full electrification.
By installed base, Lithium-ion leads. By technology investment, Solid-state is gaining share fastest.
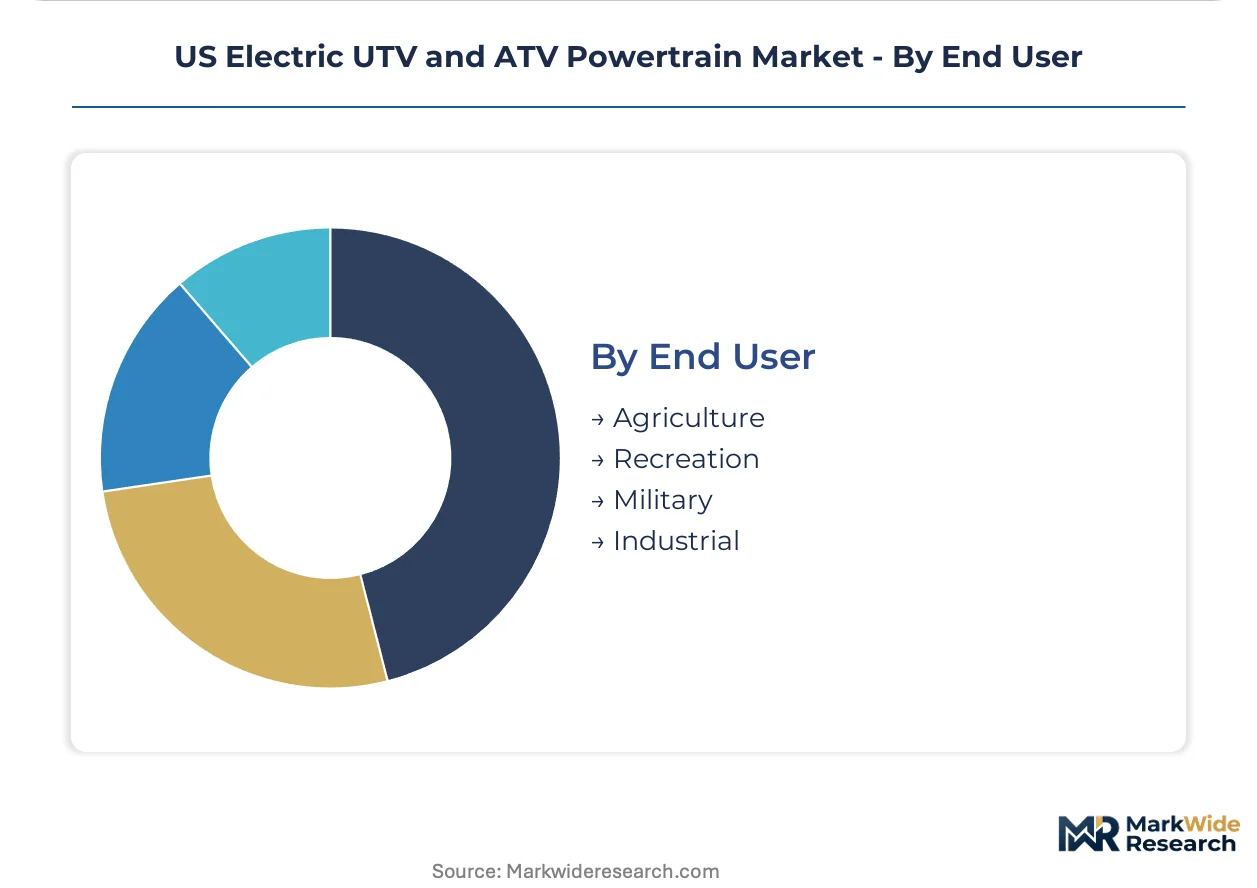
End User:
Customer type determines procurement modality, with agricultural buyers favoring powertrain-as-a-service contracts and military demand requiring hardened validation protocols.
- Agriculture:Large-scale farming and ranching operations dominate absolute demand, with EPA Tier 4 Final compliance deadlines forcing immediate diesel replacement decisions. USDA conservation incentive programs are subsidizing electrification investments across Texas, California, and the upper Midwest.
- Industrial:Material handling and facility maintenance applications prioritize OSHA noise compliance and elimination of exhaust emissions in enclosed environments.
- Recreation:Trail riding and hunting segments emphasize weight reduction and acceleration response over sustained output.
- Military:Silent mobility and reduced thermal signature requirements drive specification for special operations and base security applications.
By fleet scale, Agriculture leads. By contract value, Military is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA conservation incentive programs and EPA Tier 4 Final compliance deadlines are accelerating fleet electrification across agricultural heartlands. State-level zero-emission mandates in California propagate procurement standards into neighboring territories. Regional demand concentrates where large-scale farming operations intersect with road-legal utility requirements.
California
The Central Valley vegetable growing belt and Central Coast wine regions drive concentrated procurement of road-legal electric UTVs requiring FMVSS 500 certification. CARB's Advanced Clean Trucks framework extends compliance pressure into off-road equipment categories. Fresno County and Monterey County operations are consolidating fifty-plus unit fleet contracts around silent-running platforms for OSHA noise compliance in enclosed packing facilities.
Texas
Panhandle cotton gins and South Texas irrigated farming complexes specify high-torque powertrains for twenty-four-hour harvest duty cycles. The Texas Commission on Environmental Quality administers emission reduction incentive grants subsidizing diesel-to-electric conversions. Lubbock and Amarillo agricultural cooperatives are deploying subscription-based powertrain-as-a-service contracts eliminating capital expenditure barriers.
Upper Midwest
Wisconsin dairy operations and Minnesota organic vegetable farms prioritize silent-running electric UTVs for barn-adjacent environments and milk haulage logistics. The Minnesota Pollution Control Agency coordinates with USDA on equipment cost-share programs for emission-reducing technology. Dane County dairy cooperatives and Stearns County grain elevators are accelerating procurement in the 10-15 kW output bracket.
Arizona
Yuma County vegetable growers and Phoenix-area estate management operations specify sealed powertrains for dust-intensive environments and golf course maintenance. The Arizona Department of Environmental Quality administers voluntary emission reduction programs for agricultural equipment. Maricopa County landscape contractors are piloting fleet subscription models bundling hardware, maintenance, and energy costs per operating hour.
US Electric UTV and ATV Powertrain Market Competitive Landscape
Player mix skews toward integrated Tier 1 automotive suppliers with off-highway validation infrastructure. Market structure concentrates around three strategic archetypes: driveline electrification specialists with Spicer Electrified portfolios, integrated e-axle architects targeting high-torque commercial platforms, and power electronics houses optimizing inverter reliability under shock-load conditions. Dominant competitive moves include FMVSS certification capacity expansion and powertrain-as-a-service contract structuring.
Within the driveline electrification tier, DANA Limited, GKN Automotive Limited, and BorgWarner Inc. occupy positions representing distinct technical approaches to off-highway duty cycles. DANA exemplifies the legacy driveline supplier archetype with purpose-built electrified portfolios. GKN sits within the eDrive optimization specialist category targeting transient load applications. BorgWarner represents the integrated systems architect segment anchoring high-torque commercial platform supply.
| Leading Market Players |
|---|
| DANA Limited |
| GKN Automotive Limited |
| BorgWarner Inc. |
| HyperCraft |
| Curtis Instruments, Inc. |
| American Axle & Manufacturing, Inc. |
| NIDEC CORPORATION |
| Yamaha Motor Co., Ltd. |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
Powertrain-as-a-service contracts lock in multi-year supply access for agricultural fleet operators while capping per-hour energy and maintenance costs. This procurement structure insulates buyers from neodymium magnet price swings and FMVSS certification delays that disrupt spot-market transactions.
Pricing Analysis
Certification level (FMVSS 500 road-legal versus off-road-only) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects thermal management complexity and continuous output ratings. Cost compression in the 5-10 kW entry bracket is intensifying because Chinese motor suppliers are flooding aftermarket retrofit channels. Small-scale vegetable growers in Arizona and Wisconsin dairy cooperatives exhibit highest price sensitivity, while Texas Panhandle cotton operations prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Rare-earth magnet processing concentration in Chinese refining facilities creates single-source vulnerability for permanent-motor architectures. Neodymium-iron-boron magnets, silicon carbide wafers, and lithium iron phosphate cathode materials feed from concentrated Asian supply bases. Tariff exposure on processed rare-earth compounds threatens margin stability for US-based powertrain assemblers. Distribution runs through Tier 1 automotive supplier networks with validated off-highway testing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where FMVSS certification timelines and EPA compliance deadlines create switching costs that lock in qualified suppliers. Network effects concentrate around powertrain-as-a-service platforms that aggregate fleet-scale demand.
For Market Incumbents: Consolidate backward integration into silicon carbide semiconductor sourcing to secure inverter component supply against Chinese export restrictions. Expand FMVSS 500 validation capacity in Texas and California to capture agricultural fleet procurement cycles accelerated by EPA Tier 4 Final deadlines. Deepen powertrain-as-a-service contract structures that bundle hardware, software updates, and depot charging infrastructure. For New Entrants and Emerging Players: Lead with solid-state battery pilot programs targeting defense and premium agricultural segments where energy density premiums justify unproven technology adoption. Wisconsin and Minnesota dairy cooperatives represent the most penetrable white-space geography for silent-running electric UTV deployments. Pursue USDA conservation incentive program qualification as a go-to-market angle that subsidizes buyer acquisition costs. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated powertrain architects with captive thermal management and motor control expertise. Long-term viability across the analysis window rests on defensible positions in high-torque continuous-output architectures where ASIL-D functional safety certification creates scarcity rents. Watch California CARB rulemaking for off-road equipment as the inflection signal determining battery-electric versus hybrid architecture investment allocation.| Strategic Initiative | Industry Significance |
|---|---|
| FMVSS 500 Certification Expansion | Unlocks road-legal utility contracts in California Central Valley vegetable operations. |
| Solid-State Battery R&D Partnership | Positions suppliers for defense and premium agricultural segment capture. |
| Powertrain-as-a-Service Platform Launch | Eliminates capital expenditure barriers for mid-scale Midwest dairy cooperatives. |
| Silicon Carbide Inverter Integration | Matches diesel power density in confined chassis spaces for Texas cotton gins. |
| USDA Conservation Incentive Alignment | Subsidizes electrification investments across EPA compliance-driven replacement cycles. |
Research Methodology
The analysis maps electric UTV powertrain architectures, ATV hub-motor configurations, and hybrid range-extender systems, each validated through procurement directors at agricultural cooperatives, Tier 1 supplier platform engineers, and fleet maintenance supervisors. Primary interviews with off-highway OEM product planners and power electronics procurement leads combined with secondary validation against EPA regulatory filings, NHTSA FMVSS certification databases, and USDA equipment cost-share program records. Bottom-up unit shipment estimates triangulated against top-down powertrain revenue aggregation.
Consistency checks validated volume and value outputs against external benchmarks including state-level zero-emission equipment procurement databases and agricultural machinery trade flow data. Segmentation modeling spanned product type, power rating bracket, battery chemistry, and end-use application across the projection horizon. CAGRs derived from logistic diffusion curves fitted to replacement cycle timing and regulatory compliance deadline clustering. Industry-specific inputs included EPA Tier 4 Final enforcement schedules and CARB Advanced Clean Trucks framework propagation timelines.
Forecasts assume regulatory continuity in EPA emissions enforcement and NHTSA low-speed vehicle certification regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as solid-state battery commercialization timelines and rare-earth supply chain restructuring evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Asia-Pacific Recreational Vehicle Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Global Recreational Off-Highway Vehicles Market
Recreational Vehicles
Australia Trailer Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Electric Baby Car Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Global Houseboats Market
Recreational Vehicles
Europe Motor Home Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
RV Leisure Battery Market
Recreational Vehicles
Middle East and Africa Personal Watercraft Market
Recreational Vehicles
Australia Recreational Vehicle Rental Market
Recreational Vehicles
ATV-UTV Tire Market
Recreational Vehicles
Global Recreational Vehicle (RV) Market