
 Europe Electric Truck Market | 2026-2036
Europe Electric Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Truck Market Foresight
Buyer concentration among logistics providers is hardening as major freight operators consolidate electrification commitments across their fleets. Volvo Trucks leverages its established dealer network to sustain service coverage across Nordic and Central European corridors. Daimler Truck anchors its position through integrated battery-electric platforms spanning multiple weight classes. Scania AB competes on modular powertrain architectures that reduce total cost of ownership for high-mileage operators.
Europe electric trucks are battery-electric commercial vehicles engineered for freight and municipal duty cycles, typically employing lithium-ion packs with energy densities exceeding 200 Wh per kilogram and regenerative braking systems to maximize range. Their primary purpose is to eliminate tailpipe emissions from road freight while maintaining payload capacity comparable to diesel equivalents. Heavy-duty trucks dominate current revenue pools due to premium pricing and intensive fleet utilization patterns, while depot charging infrastructure attracts the fastest capacity additions as operators prioritize controlled overnight replenishment. Medium-duty trucks occupy a transitional position where municipal and last-mile logistics applications drive volume scaling ahead of long-haul electrification maturity.
The EU Green Deal and CO2 emission standards for heavy-duty vehicles shape product development timelines, with EMA guidelines on battery safety and REACH compliance on material sourcing further constraining supply chain configurations. Germany's KBA enforces type-approval protocols that delay market entry for non-compliant platforms. Stakeholders must monitor how the EU AI Act intersects with autonomous trucking pilots and whether the F-Gas Regulation accelerates thermal management system redesigns.
Market Dynamics
The EU Green Deal's tightening CO2 emission standards for heavy-duty vehicles are compressing product development timelines across OEMs. Fleet operators face compliance cliffs that accelerate electrification commitments while charging infrastructure buildout struggles to match vehicle deployment velocity.
Growth Catalysts
- EU Green Deal mandates:Binding CO2 reduction targets for heavy-duty vehicles force fleet turnover decisions toward zero-emission platforms before 2030 compliance deadlines.
- Depot charging infrastructure:Controlled overnight replenishment at logistics hubs enables predictable duty cycles for regional freight operators without public charging dependency.
- Lithium-ion energy density gains:Pack-level densities exceeding 200 Wh per kilogram extend operational range for medium-duty urban delivery applications.
Market Restraints
- Cell supply concentration:Asian battery cell manufacturers control cathode precursor refining capacity, exposing European OEMs to raw material bottlenecks and price volatility.
- KBA type-approval protocols:Germany's Federal Motor Transport Authority enforces validation timelines that delay market entry for non-compliant vehicle platforms by 12-18 months.
- Diesel total cost of ownership parity:Electric truck upfront premiums remain 40-60% above diesel equivalents without subsidy layering, compressing fleet replacement economics.
Strategic Opportunities
- Polish freight corridors:Underpenetrated Central European logistics routes connecting Baltic ports to German industrial zones offer first-mover positioning for regional haul electrification.
- Battery-as-a-service models:Unbundled pack ownership from vehicle purchase reduces capital barriers for mid-size fleet operators in France and Benelux markets.
- F-Gas Regulation thermal redesign:Mandated refrigerant phase-down accelerates demand for CO2-based climate systems in refrigerated electric trucks.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance networks lack certified personnel for 800V platform servicing, extending downtime and warranty risk exposure.
- REACH compliance material tracing:Supply chain documentation for conflict minerals and recycled content thresholds consumes procurement bandwidth without immediate revenue return.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Truck Market |
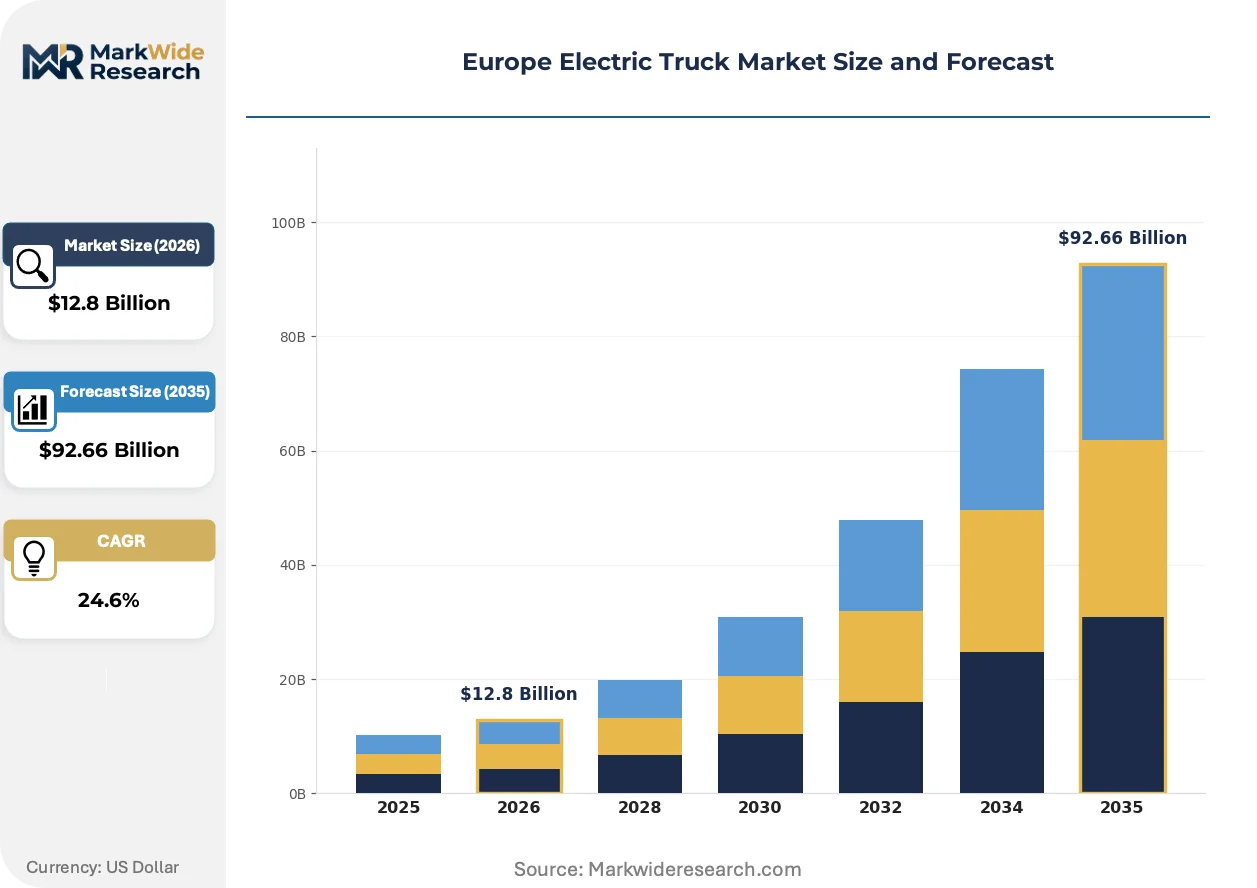
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $92.66 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium-Duty Trucks, Heavy-Duty Trucks, Light-Duty Trucks, Bus Chassis Power Rating: 150 kW, 200 kW, 300 kW, 500 kW Charging Infrastructure: Fast Charging, Ultra-Fast Charging, Depot Charging, Home Charging End User: Freight Companies, Logistics Providers, Municipalities, Construction Firms |
| Companies Covered | MAN Truck & Bus, Iveco, Volvo Trucks, Daimler Truck, Renault Trucks, Mercedes-Benz Trucks, DAF Trucks, Traton Group, Scania AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Truck Market Shifts & Advancements
Electrification architecture decisions are locking in competitive positions for the next decade as thermal management and energy storage systems determine vehicle performance ceilings. Technology roadmaps prioritize modular platforms that span weight classes without complete redesign cycles.
Silicon carbide power electronics is converging with 800V battery architectures to reduce charging duration and inverter losses. High-mileage fleet operators in Germany and the Netherlands are specifying SiC-based drivetrains for depot-charged regional routes. This convergence is compressing the total cost of ownership gap against diesel by reducing energy consumption per kilometer and enabling faster turnaround times.
The EU AI Act's risk classification framework is reshaping autonomous trucking pilot permissions across member states. Developers must demonstrate conformity with high-risk system requirements before deploying supervised automation on public motorways. Long-haul freight corridors through Belgium and western Germany face the steepest compliance documentation burdens as regulators prioritize dense traffic environments.
Leasing structures are displacing direct purchase for electric truck acquisition among mid-size logistics providers. Financial intermediaries in France and Italy now bundle vehicles, charging hardware, and energy supply into single contracts. This shift concentrates credit risk assessment with specialized fleet finance arms rather than traditional equipment lenders.
Europe Electric Truck Market Segmentation
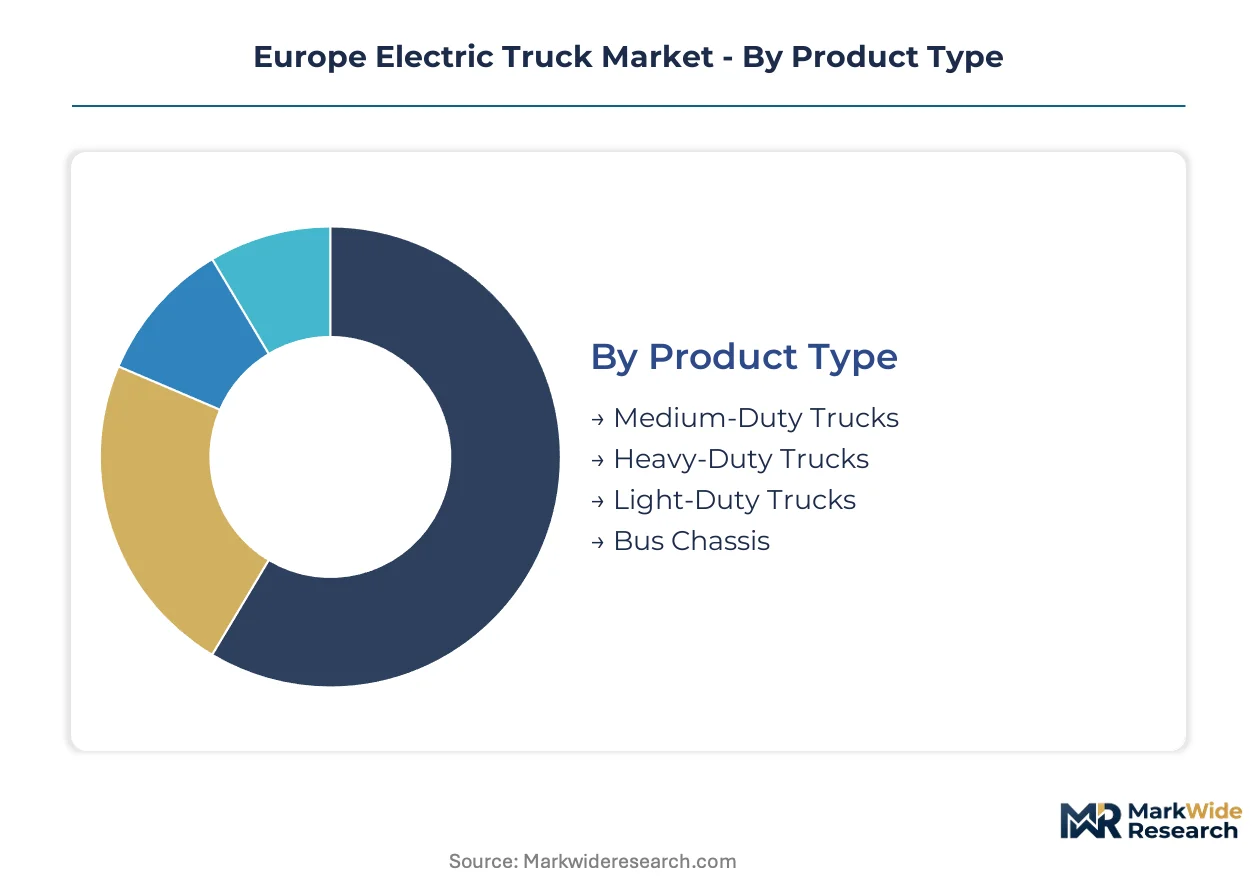
Segmentation in the Europe Electric Truck Market reveals how duty cycles, energy requirements, and operational constraints shape procurement patterns across fleet operators. Understanding these divides exposes where capital concentrates and which configurations face steepest adoption barriers.
Product Type:
Integration depth varies sharply—heavy-duty platforms function as standalone capital assets with dedicated charging infrastructure, while light-duty variants embed into mixed fleets with shared replenishment systems.
- Heavy-Duty Trucks:These vehicles employ battery packs exceeding 350 kWh with 800V architectures enabling 350 kW charging acceptance. Demand clusters along Germany's Rhine-Alpine freight corridor where logistics providers face binding EU CO2 emission standards compliance deadlines.
- Medium-Duty Trucks:Modular chassis designs accommodate refrigerated bodies and municipal equipment through standardized power take-off interfaces. French urban delivery fleets specify these for last-mile routes under Paris's low-emission zone enforcement.
- Light-Duty Trucks:Compact urban distribution vehicles with 100-150 kWh packs serve multi-drop delivery patterns in Benelux city centers.
- Bus Chassis:Low-floor electric platforms adapted for municipal waste collection and street-sweeping applications in Scandinavian cities.
Volume placements concentrate in Heavy-Duty Trucks; the faster expansion belongs to Medium-Duty Trucks.
Power Rating:
Cost tiering separates premium high-output configurations from economy-grade urban solutions, with mid-range ratings capturing transitional fleet operators.
- 500 kW:Dual-motor architectures deliver continuous gradeability for Alpine transit routes. Austrian timber haulers specify these for Grossglockner corridor operations where elevation changes exceed 2,000 meters.
- 300 kW:Single-motor rear-axle integration balances efficiency with payload preservation. Dutch refrigerated logistics operators favor this rating for Rotterdam-Berlin corridor runs with scheduled depot charging.
- 200 kW:Entry-point specification for municipal utility fleets with predictable duty cycles.
- 150 kW:Economy-tier rating for urban parcel delivery with sub-200 km daily range requirements.
Procurement concentrates in 300 kW configurations; 500 kW systems are climbing the fastest as long-haul electrification matures.
Charging Infrastructure:
Application context determines infrastructure choice—controlled environments favor depot systems while unpredictable routes demand public network resilience.
- Depot Charging:AC and DC hardware installed at logistics hubs enables overnight replenishment with demand charge management. German grocery distributors anchor fleet electrification strategies around 150 kW depot installations at regional distribution centers.
- Ultra-Fast Charging:350 kW CCS2 dispensers along motorway corridors extend operational radius for irregular-route operators. Spanish freight corridors connecting Madrid to Barcelona attract the densest deployment clusters.
- Fast Charging:50-150 kW public infrastructure for opportunistic mid-route replenishment.
- Home Charging:Residential AC solutions for owner-operator and small fleet applications.
Capital deployment concentrates in Depot Charging; Ultra-Fast Charging is gaining share fastest as corridor electrification accelerates.
End User:
Customer type segmentation exposes divergent procurement sophistication—integrated logistics providers leverage scale advantages unavailable to fragmented municipal buyers.
- Logistics Providers:Multi-national operators specify standardized platforms across national subsidiaries with centralized energy procurement. DHL Supply Chain and Kuehne+Nagel electrification commitments in Germany and the Netherlands drive volume aggregation.
- Freight Companies:Asset-owning carriers with dedicated routes optimize total cost of ownership through high-utilization depot charging. Polish road hauliers connecting Baltic ports to Silesian industrial zones represent emerging demand concentration.
- Municipalities:Public procurement frameworks prioritize local air quality compliance over lifecycle economics in French and Italian urban centers.
- Construction Firms:Site-specific duty cycles with intermittent usage patterns favor leased rather than owned electric truck assets.
Contract awards concentrate among Logistics Providers; Freight Companies show the steepest expansion trajectory as compliance cliffs approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics providers concentrate electrification commitments in Germany, where dense freight corridors and procurement incentives compress fleet turnover timelines. This demand concentration shapes regional deployment patterns across Northern and Central Europe.
Germany
The Rhine-Alpine corridor anchors heavy-duty electric truck deployment, with grocery distributors specifying 350 kWh platforms for regional distribution center replenishment. KBA type-approval protocols enforce validation timelines that filter non-compliant vehicle entries. Stuttgart and Munich industrial zones host the densest depot charging infrastructure clusters.
Netherlands
Rotterdam-Berlin freight routes drive 300 kW single-motor procurement for refrigerated logistics operators with scheduled overnight charging. The country's national environmental agency enforces low-emission zone mandates that accelerate municipal fleet transitions. Eindhoven's logistics hub concentration attracts ultra-fast charging corridor investments.
France
Paris low-emission zone enforcement compels last-mile operators toward medium-duty modular chassis for urban delivery applications. The national energy regulator structures electricity tariff frameworks that favor overnight depot replenishment. Lyon and Marseille freight clusters show emerging demand for battery-as-a-service acquisition models.
Poland
Baltic port-to-Silesian industrial zone corridors represent underpenetrated routes where freight companies optimize total cost of ownership through high-utilization depot charging. EU Green Deal CO2 compliance cliffs approach faster than fleet replacement cycles permit. Gdansk and Warsaw logistics hubs concentrate emerging electrification pilot programs.
Spain
Madrid-Barcelona motorway corridors attract the densest ultra-fast charging deployment clusters for irregular-route operators requiring mid-journey replenishment. The national climate change and energy transition law structures heavy-duty vehicle emission reduction pathways. Barcelona's port logistics zone anchors refrigerated electric truck trials with CO2-based thermal management systems.
Europe Electric Truck Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue service-model differentiation and battery-ownership unbundling. The market structure consolidates around integrated OEMs with captive financing arms and modular platform architectures spanning multiple weight classes. Three archetypes dominate: legacy truck manufacturers with electrified line extensions, battery-system specialists seeking vehicle integration partnerships, and energy-service providers bundling charging infrastructure with fleet procurement. Competitive moves concentrate on strategic partnerships for cell supply security and geographic expansion into underpenetrated Central European corridors.
Within the legacy manufacturer tier, MAN Truck & Bus and Volvo Trucks exemplify established European producers with dealer network coverage across Nordic and Central European freight corridors. Scania AB occupies a position among modular powertrain architects competing on total cost of ownership reduction for high-mileage operators. These Swedish and German anchors represent how regional production heritage translates into electrification platform development priorities.
| Leading Market Players |
|---|
| MAN Truck & Bus |
| Iveco |
| Volvo Trucks |
| Daimler Truck |
| Renault Trucks |
| Mercedes-Benz Trucks |
| DAF Trucks |
| Traton Group |
| Scania AB |
| Others |
Supply & Pricing Matrix
Heavy-duty versus medium-duty platform divergence separates premium 800V architectures from economy-grade 400V alternatives, with German logistics providers absorbing cell cost premiums through bundled service contracts while Polish freight operators face unbundled procurement exposure to cathode material volatility. This tier split concentrates margin capture with OEMs possessing captive battery financing arms, while tier-two assemblers without upstream cell agreements confront pricing pressure from nickel and lithium price swings.
Pricing Analysis
Volume placements in heavy-duty trucks sustain margin pools against compressed medium-duty unit economics. Three-tier pricing structure across premium, standard, and economy levels tracks battery energy density grades and KBA type-approval certification status. Cost compression in economy-tier municipal vehicles is intensifying because French procurement frameworks prioritize lowest-bid compliance over lifecycle value. Small fleet operators in Benelux urban zones exhibit highest price sensitivity; integrated logistics providers with centralized energy procurement show lowest.
Supply Chain Analysis
Lithium-ion cell supply rests on South Korean and Chinese cathode precursor producers, with European OEMs drawing from concentrated Asian refining capacity for nickel-manganese-cobalt formulations. High-voltage silicon carbide inverters and 800V thermal management hardware anchor second-tier dependencies. Single-source vulnerability in battery management system firmware exposes fleet operators to extended service downtime. Distribution runs through OEM captive financing arms and specialized fleet lessors rather than traditional equipment lenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell supply scarcity props pricing power for OEMs with secured cathode precursor offtake, compressing margin recovery timelines for assemblers without backward integration into battery pack production.
For Market Incumbents: To counter emerging battery-system specialists unbundling pack ownership from vehicle sales, MAN Truck & Bus and Volvo Trucks should deepen captive financing penetration in Polish and Spanish freight corridors while accelerating silicon carbide inverter in-house production to preserve drivetrain margin pools. For New Entrants and Emerging Players: Battery-as-a-service technology platforms offer entry into French and Italian mid-size fleet segments where upfront capital barriers block direct purchase adoption. Polish Baltic-to-Silesian corridor operators represent the most penetrable geography given underdeveloped depot charging infrastructure and approaching EU CO2 compliance cliffs. For Investors and Strategic Acquirers: Re-rating potential sits with modular powertrain architects given accelerating demand for standardized chassis spanning municipal and regional freight applications. Long-term viability centers on producers with REACH-compliant material tracing systems and KBA validation pipelines already cleared. Watch for F-Gas Regulation thermal system redesign completion as inflection signal for refrigerated electric truck market readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secured cathode precursor offtake from South Korean producers insulates Daimler Truck against nickel price volatility. |
| Platform Standardization | Modular 800V architectures spanning heavy-duty and medium-duty weight classes reduce Scania AB redesign cycle costs. |
| Charging Infrastructure Partnership | Depot hardware bundling with French energy suppliers accelerates Renault Trucks penetration in Paris low-emission zones. |
| Software-Defined Vehicle Investment | Over-the-air battery management updates enable Volvo Trucks to extend pack lifecycle across Nordic temperature extremes. |
| Geographic Manufacturing Footprint | Polish assembly localization for Iveco cuts delivery cost exposure on Baltic port-to-industrial zone routes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining structured interviews with fleet procurement directors, OEM platform engineers, and charging infrastructure developers against KBA type-approval databases and EU Green Deal implementation trackers. Primary fieldwork with logistics providers in Germany, the Netherlands, and Poland validated deployment timelines and total cost of ownership assumptions. Bottom-up vehicle registration projections triangulated against top-down freight volume elasticity models.
Granularity-level modeling segmented by vehicle weight class, power rating tier, charging infrastructure type, and end-user archetype across national freight corridors. CAGRs derived from logistic curve adoption parameters fitted to fleet replacement cycle data and CO2 compliance deadline proximity. Battery energy density improvement curves and depot charging capacity buildout schedules served as core forecast inputs.
Several conditions sit outside the modeled scope, including autonomous trucking pilot regulatory acceleration under EU AI Act revisions and potential F-Gas Regulation refrigerant phase-down timeline shifts. Forecasts reflect assumptions around lithium-ion cell cost trajectories and REACH compliance enforcement intensity. A small set of named triggers warrants ongoing watch: cathode precursor supply disruptions, KBA validation backlog extensions, and ultra-fast charging corridor deployment delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Spain Solar E-Bike Market