
 North America Electric Truck Market | 2026-2036
North America Electric Truck Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Truck Market Analytics
Asset-light leasing and battery-as-a-service models is rewriting capital deployment rules for fleet operators previously priced out of electric truck ownership. Rivian Automotive, LLC specializes in integrated last-mile delivery platforms with proprietary charging ecosystems. Tesla, Inc. dominates proprietary powertrain and energy storage verticals that compress operating costs for high-utilization fleets. PACCAR Inc. leverages established dealer-service networks to sustain uptime guarantees that electrification skeptics demand.
A North America electric truck constitutes a commercial vehicle propelled by electric drivetrains—battery electric, hydrogen fuel cell, hybrid, or plug-in hybrid architectures—delivering torque from zero RPM through permanent-magnet or induction motors with energy densities now exceeding 250 Wh/kg at cell level. Heavy-duty configurations command the steepest engineering premiums but anchor long-term margin pools as megawatt-charging standards mature. Light-duty vans and medium-duty distribution trucks represent the volume frontier where logistics end-users are consolidating procurement around standardized fleet charging infrastructure. Battery electric powertrains lead absolute unit shipments while hydrogen fuel cell variants occupy extended-range niche applications in cross-border freight corridors.
The Environmental Protection Agency's Phase 3 greenhouse gas standards and the Inflation Reduction Act's Section 45W commercial clean vehicle credits are structurally shifting total cost of ownership calculations toward electrification across the United States. Transport Canada's proposed medium- and heavy-duty vehicle regulations will extend parallel compliance obligations into Canadian provincial fleets. Stakeholders must monitor charging infrastructure buildout velocity against vehicle deployment curves, as grid interconnection delays in Texas and Ontario risk creating fleet utilization bottlenecks regardless of vehicle availability.
Market Dynamics
The Inflation Reduction Act's Section 45W commercial clean vehicle credits are compressing total cost of ownership gaps between battery-electric and diesel powertrains for high-utilization fleets. This structural subsidy recalibration is pulling forward electrification timelines that fleet operators previously deferred until mid-decade.
Growth Catalysts
- Advanced Clean Trucks Regulation:California's escalating zero-emission sales mandates force OEMs to electrify medium- and heavy-duty lineups, creating guaranteed demand absorption for compliant vehicles.
- Megawatt Charging System (MCS) standardization:Fleet operators in cross-border freight corridors are pre-ordering heavy-duty tractors compatible with 1+ MW charging, eliminating range anxiety for long-haul electrification.
- Battery cell cost curves:Lithium-iron-phosphate chemistry deployment in commercial vehicle packs is compressing upfront capital premiums versus diesel equivalents.
Market Restraints
- Charging infrastructure interconnection queues:Grid connection delays in ERCOT-served Texas markets and Ontario's IESO territory are creating fleet utilization bottlenecks regardless of vehicle availability.
- Critical mineral supply concentration:Cathode active material processing for North American battery plants remains dependent on concentrated Asian supply chains, exposing OEMs to input volatility.
- Technical limitation:Cold-weather range degradation in battery-electric configurations limits deployment viability for Canadian prairie freight operations without thermal management retrofits.
Strategic Opportunities
- Asset-light leasing models:Battery-as-a-service structures are rewriting capital deployment rules for small fleet operators previously priced out of electric truck ownership.
- Quebec's zero-emission vehicle mandate:Provincial regulations parallel to California's ACT create a second guaranteed demand anchor in Canadian markets with abundant low-carbon electricity.
- Telematics-converged energy management:Integration of route optimization software with vehicle-to-grid discharge protocols is opening new revenue streams for fleet operators.
Industry Challenges
- High-voltage technician scarcity:Dealer service networks face acute shortages of technicians certified for 800V+ battery pack diagnostics and repair, compressing uptime guarantees.
- Multi-standard charging interoperability:Fleet operators deploying across CCS, NACS, and MCS connector ecosystems face integration complexity with legacy depot infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Truck Market |
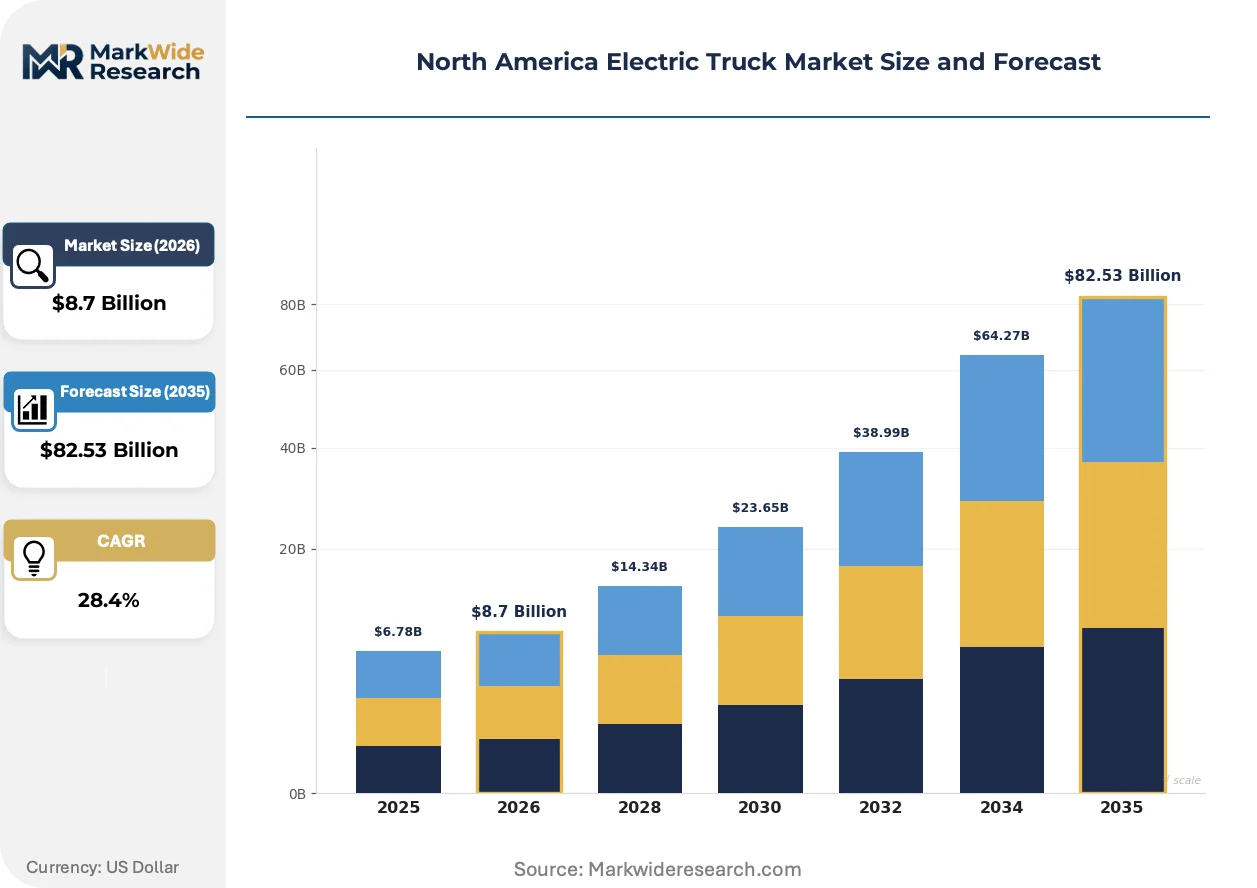
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Light Duty, Medium Duty, Heavy Duty, Vans Power Source: Battery Electric, Hydrogen Fuel Cell, Hybrid Electric, Plug-in Hybrid End User: Logistics, Public Sector, Retail, Construction Charging Infrastructure: Public Charging Stations, Home Charging, Fleet Charging, Wireless Charging |
| Companies Covered | BYD Motors Inc., PACCAR Inc., Tesla, Inc., Ford Motor Company, Freightliner Trucks, Rivian Automotive, LLC, Nikola Corporation, Lion Electric Co., Volvo Trucks North America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Truck Market Evolving Landscape
Powertrain architecture decisions are migrating from hardware-centric specifications toward software-defined energy management platforms. This shift is compressing development cycles and enabling over-the-air efficiency optimization that diesel platforms cannot replicate.
Solid-state battery prototyping is migrating from laboratory validation toward fleet demonstration programs with select last-mile operators. Daimler Truck North America and Volvo Group have deployed pre-production cells in controlled California routes. The technology is migrating from energy density limitations of liquid electrolyte designs toward 400+ Wh/kg targets that compress payload penalties for heavy-duty configurations.
EPA Phase 3 greenhouse gas standards are tightening CO2 gram-per-ton-mile requirements for model years 2027 through 2032. The regulation forces diesel engine manufacturers to accelerate electrification roadmaps or absorb steep compliance penalties. Heavy-duty day cab tractors serving regional haul routes face the most concentrated compliance pressure, driving accelerated battery-electric pilot programs.
Fleet procurement committees are consolidating vendor relationships around integrated charging infrastructure providers rather than decoupling vehicle and energy decisions. This behavioral shift compresses supplier negotiation leverage for standalone charging hardware vendors. The pattern is most visible in California's San Joaquin Valley agricultural logistics clusters, where cooperative buying groups are standardizing on single-vendor electrification stacks.
North America Electric Truck Market Segmentation
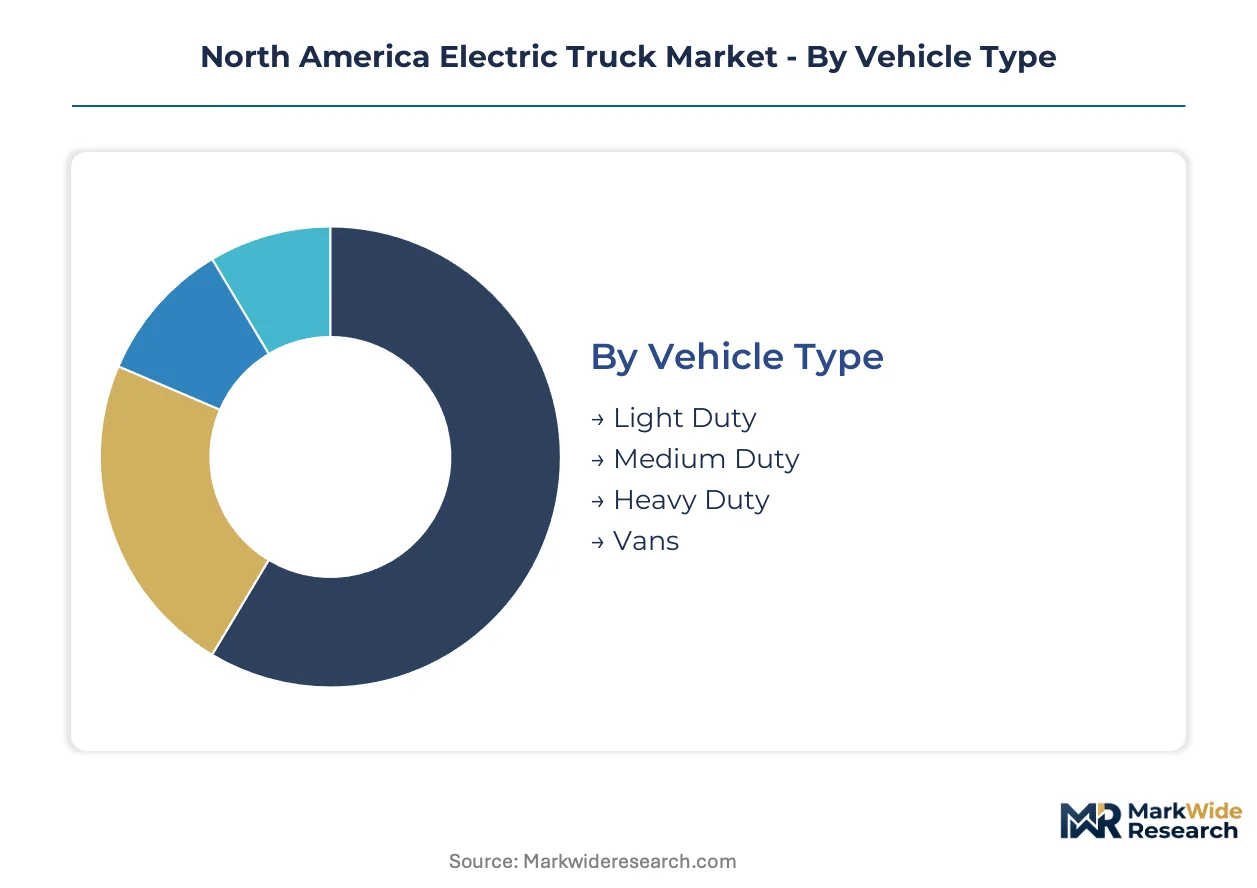
Electric truck segmentation reveals divergent technology maturities and capital deployment patterns across duty cycles and energy architectures. Fleet operators match vehicle specifications to route profiles, depot constraints, and regulatory exposure rather than pursuing one-size-fits-all electrification.
Vehicle Type:
Use-case spectrum spans urban parcel delivery to cross-border heavy-haul, with duty cycle intensity dictating powertrain architecture and battery sizing.
- Light Duty:Class 1-2 configurations dominate last-mile parcel and grocery delivery routes under 150 miles. California's Advanced Clean Trucks regulation mandates zero-emission sales percentages that pull forward procurement timelines for urban van fleets.
- Heavy Duty:Class 8 tractors face the steepest engineering premiums but anchor long-term margin pools as megawatt-charging standards mature for regional haul corridors.
- Medium Duty:Class 3-6 distribution trucks consolidate procurement around standardized depot charging infrastructure in logistics clusters.
- Vans:Compact urban delivery vehicles integrate proprietary charging ecosystems with route optimization software for high-stop-density operations.
Established volume favors Light Duty; emerging adoption favors Heavy Duty.
Power Source:
Cost tier separates mature battery-electric platforms from emerging hydrogen and hybrid alternatives with distinct total cost of ownership profiles.
- Battery Electric:Lithium-iron-phosphate chemistry deployment in commercial packs compresses upfront capital premiums versus diesel equivalents. Fleet operators in California's San Joaquin Valley agricultural logistics clusters standardize procurement around single-vendor electrification stacks.
- Hydrogen Fuel Cell:Extended-range niche applications occupy cross-border freight corridors where depot hydrogen fueling eliminates payload penalties from battery weight.
- Hybrid Electric:Transitional architecture preserves diesel range assurance while capturing regenerative braking efficiency for mixed-duty routes.
- Plug-in Hybrid:Grid-connected overnight charging supplements onboard generation for operators lacking full depot infrastructure commitment.
Technology maturity concentrates procurement in Battery Electric; infrastructure buildout pace determines Hydrogen Fuel Cell scaling.
End User:
Customer type segmentation exposes divergent procurement authority structures and compliance pressure intensity across institutional buyers.
- Logistics:Asset-light leasing and battery-as-a-service models rewrite capital deployment rules for fleet operators previously priced out of electric truck ownership.
- Public Sector:Municipal procurement committees consolidate vendor relationships around integrated charging infrastructure providers with uptime guarantees.
- Retail:Grocery and big-box chains deploy medium-duty distribution trucks with standardized fleet charging for last-mile fulfillment networks.
- Construction:Site-access constraints and intermittent utilization patterns limit battery-electric viability without mobile charging solutions.
Procurement standardization runs deepest in Logistics; regulatory mandate pressure concentrates in Public Sector.
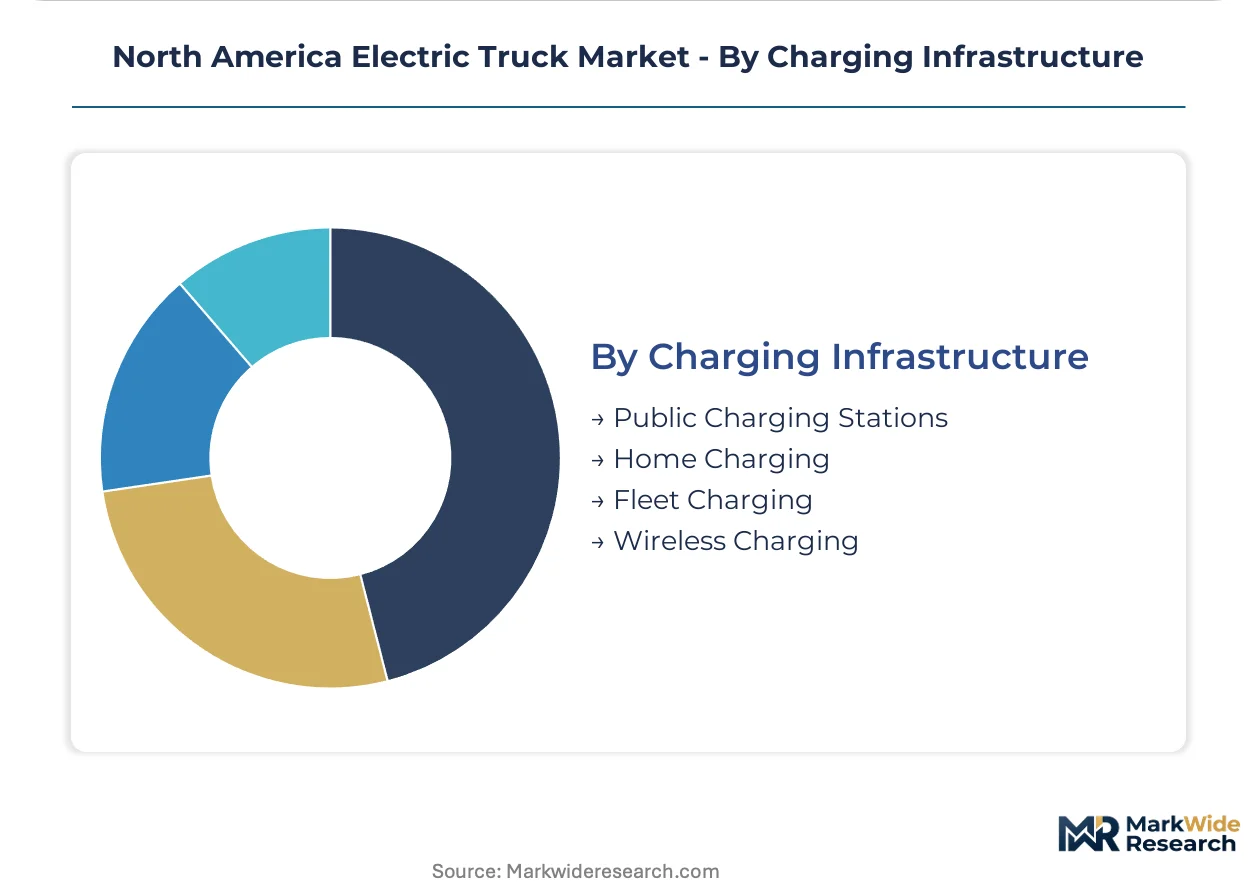
Charging Infrastructure:
Supply concentration in charging hardware vendors shapes fleet electrification sequencing and vendor lock-in risk.
- Fleet Charging:Depot-based megawatt systems anchor heavy-duty electrification economics with managed demand charges and vehicle-to-grid discharge protocols.
- Public Charging Stations:Corridor deployment along interstate freight routes enables battery-electric long-haul pilots without full depot infrastructure.
- Home Charging:Level 2 residential units serve owner-operator light-duty applications with overnight dwell-time adequacy.
- Wireless Charging:Inductive pad systems undergo pilot deployment for fixed-route urban applications with predictable stop patterns.
Capital deployment gravitates toward Fleet Charging; interoperability complexity multiplies across Public Charging Stations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates North American electric truck production capacity while Canadian fleets absorb cross-border vehicle exports. Mexico's manufacturing corridors supply battery pack assembly components to assembly plants in both northern markets. Sub-regional demand concentrates where regulatory mandates intersect with logistics density and grid infrastructure readiness.
United States
California's Advanced Clean Trucks regulation mandates escalating zero-emission sales percentages that pull forward procurement timelines for Class 4-8 vehicles. The Inflation Reduction Act's Section 45W commercial clean vehicle credits compress total cost of ownership gaps versus diesel powertrains. The San Joaquin Valley agricultural logistics cluster standardizes procurement around single-vendor electrification stacks with integrated charging infrastructure.
Canada
Quebec's zero-emission vehicle mandate creates a guaranteed demand anchor with abundant low-carbon hydroelectric generation supporting fleet charging economics. Transport Canada's proposed medium- and heavy-duty vehicle regulations extend parallel compliance obligations into provincial fleets. Ontario's IESO territory faces grid interconnection delays that risk creating fleet utilization bottlenecks regardless of vehicle availability.
Mexico
Cross-border freight corridors connecting manufacturing centers to US distribution hubs generate demand for extended-range electric configurations. The country's national energy regulator oversees grid expansion timelines that lag vehicle deployment curves in northern border states. Nuevo León's Monterrey metro area anchors pilot programs for medium-duty distribution trucks serving automotive and electronics supply chains.
North America Electric Truck Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers that bundle vehicles with charging infrastructure and energy management software. Three strategic archetypes dominate competitive positioning: legacy truck manufacturers leveraging dealer-service networks, technology-native entrants with proprietary powertrain verticals, and battery specialists pursuing asset-light leasing models. Capacity expansion and strategic partnerships represent the dominant competitive moves as players race to secure charging infrastructure real estate and battery cell supply commitments.
Among established manufacturers, PACCAR Inc. and Volvo Trucks North America exemplify the incumbent archetype that sustains uptime guarantees through dense service networks. Tesla, Inc. anchors the technology-native position with integrated energy storage and charging infrastructure. Rivian Automotive, LLC occupies a specialist position in last-mile delivery platforms with proprietary charging ecosystems.
| Leading Market Players |
|---|
| BYD Motors Inc. |
| PACCAR Inc. |
| Tesla, Inc. |
| Ford Motor Company |
| Freightliner Trucks |
| Rivian Automotive, LLC |
| Nikola Corporation |
| Lion Electric Co. |
| Volvo Trucks North America |
| Others |
Value Network & Pricing Analysis
Tariff exposure on Chinese-processed cathode active materials determines both pricing tier spreads and supply chain shape across North American electric truck manufacturing. Fleet procurement committees face widening capital premiums when sourcing battery packs from non-FTA jurisdictions, compressing margins for mid-duty configurations while heavy-duty platforms absorb cost pass-through via megawatt-charging value propositions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock lithium-iron-phosphate cell pricing across multi-year fleet deployment cycles. Price differentiation centers on certification grade — EPA Phase 3 compliance tiers versus California Air Resources Board zero-emission mandates — and volume scale commitments above 500-unit annual procurement. Cost compression in medium-duty segments is intensifying because cathode material spot volatility feeds directly into pack-level pricing. Small fleet operators exhibit acute price sensitivity, while national logistics consolidates negotiate service-bundled premiums with uptime guarantees.
Supply Chain Analysis
Lithium carbonate feedstock draws from Chilean and Australian extraction operations before concentration in Chinese and South Korean processing facilities. Battery-grade nickel sulfate and cobalt hydroxide rest on Indonesian and DRC mining outputs with concentrated Asian refining exposure. Single-source vulnerability in cathode active material supply creates fleet delivery delays when geopolitical chokepoints disrupt maritime logistics. Distribution runs through Tier 1 supplier hubs in Michigan and Ontario before final assembly at OEM plants in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
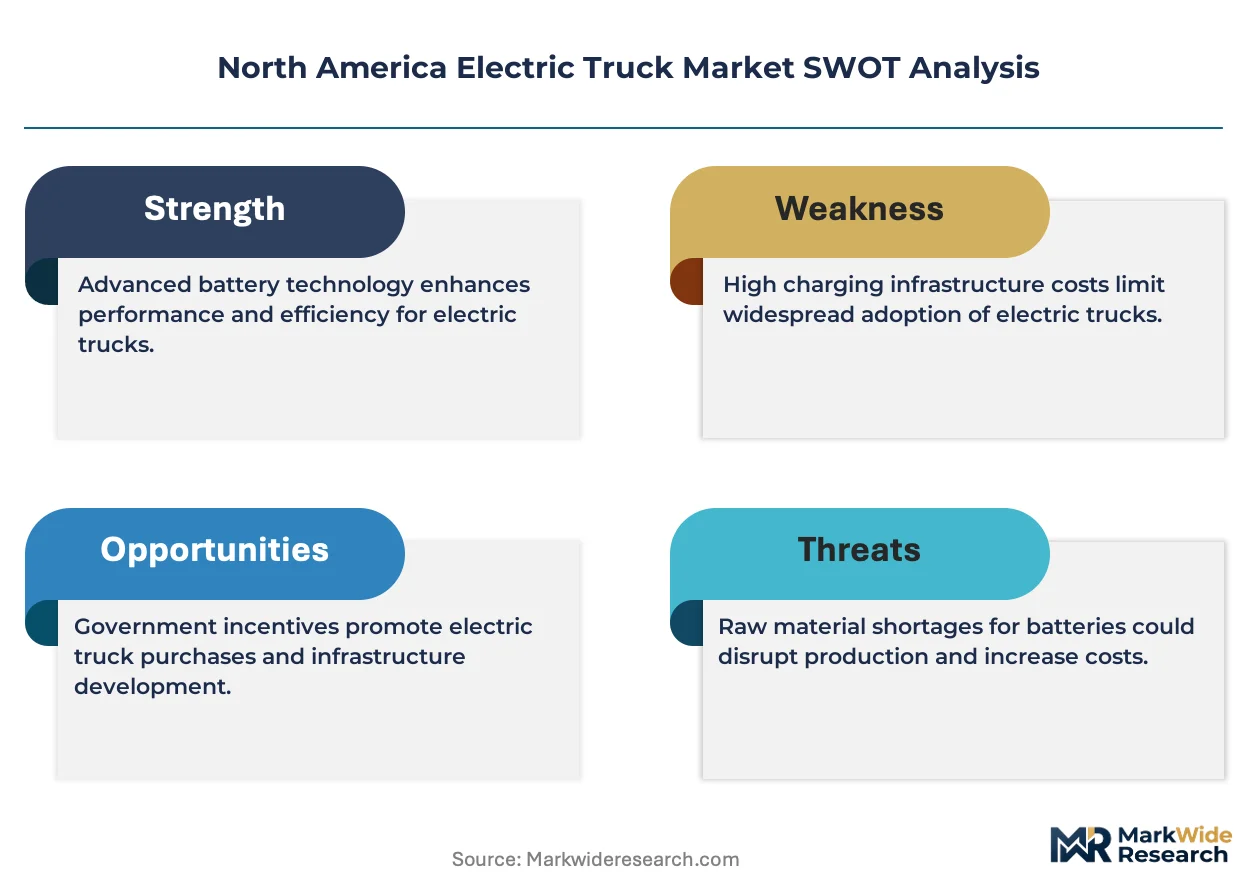
Incumbents must navigate hydrogen fuel cell substitution threats that capture extended-range freight corridors where battery weight penalties erode payload economics. The analysis frames defensive positioning around charging infrastructure control and cell chemistry diversification.
For Market Incumbents: Pre-empt hydrogen fuel cell encroachment by securing exclusive megawatt-charging real estate along cross-border freight corridors before infrastructure standardization locks in. Accelerate backward integration into lithium-iron-phosphate cell production through joint ventures with Canadian mining consortiums to reduce cathode material tariff exposure. Anchor dealer-service networks with 800V+ technician certification programs that sustain uptime guarantees against technology-native entrants. For New Entrants and Emerging Players: Establish a beachhead in Quebec's zero-emission vehicle mandate corridor where hydroelectric grid stability supports fleet charging economics without interconnection delays. Target agricultural logistics clusters in California's San Joaquin Valley with battery-as-a-service models that eliminate upfront capital barriers for cooperative buying groups. Deploy telematics-converged energy management platforms as the primary go-to-market wedge against hardware-centric incumbents. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated platform providers with captive charging infrastructure and energy management software stacks. Long-term viability concentrates on asset-light leasing specialists capable of scaling without manufacturing capital intensity. Watch EPA Phase 3 compliance penalty enforcement as the inflection signal that accelerates diesel fleet retirement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks lithium-iron-phosphate cell allocation from South Korean suppliers before capacity constraints tighten. |
| Charging Infrastructure Partnership | Secures depot real estate in Texas ERCOT zones where grid interconnection queues threaten fleet utilization. |
| Software-Defined Vehicle Investment | Enables over-the-air efficiency optimization that diesel platforms cannot replicate for logistics end-users. |
| Geographic Manufacturing Footprint | Positions assembly capacity in Ontario to exploit USMCA tariff preferences for Canadian-sourced battery minerals. |
| Platform Standardization | Reduces component complexity across Class 3-6 distribution trucks serving standardized fleet charging infrastructure. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, OEM platform engineers, charging infrastructure developers, and utility grid planning officers and refined through secondary validation against EPA regulatory filings, Transport Canada proposed rulemakings, IHS Markit vehicle registration databases, and SEC 10-K disclosures from publicly traded suppliers. Bottom-up unit deployment estimates across vehicle classes and powertrain architectures were triangulated with top-down market value projections derived from average selling price trends.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling vehicle class, propulsion architecture, charging infrastructure type, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from logistic adoption curves fitted to fleet procurement committee decision timelines and infrastructure buildout velocity. Industry-specific forecast inputs incorporated Megawatt Charging System standardization milestones and Inflation Reduction Act credit utilization rates by fleet operator size tier.
Sensitivities concentrate around grid interconnection approval timelines in ERCOT and IESO territories, cathode active material tariff regime shifts, and EPA Phase 3 enforcement stringency variations across presidential administrations. Cross-checking against California Air Resources Board zero-emission vehicle credit bank balances is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Asia-Pacific Electric Bus Market
Electric Vehicles
Foldable Electric Vehicle Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Wireless Electric Vehicle Charging Market