
 Solar Electric Car Market | 2026-2036
Solar Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Electric Car Market Insights
Subscription-based access to solar charging optimization software is shifting how manufacturers monetize vehicle ownership beyond the initial sale. Lightyear Technologies B.V. leverages its proprietary solar yield algorithms to differentiate long-range efficiency claims. Sono Motors GmbH anchors its business model on fleet-service contracts that bundle photovoltaic maintenance with vehicle leasing. Aptera Motors Corp. specializes in ultra-lightweight composite architectures that maximize solar surface-to-mass ratios.
A solar electric car integrates photovoltaic cells into body panels, hood, roof, or glass surfaces to supplement or extend battery range through direct solar energy conversion, typically achieving 15-45 kilometers of daily added range under optimal irradiance. The vehicle type dimension shows hatchbacks and compact sedans commanding early volume due to favorable surface-area-to-battery ratios that improve solar economics. Within charging technology, solar integration paired with bidirectional capability is attracting premium positioning as vehicle-to-grid services create secondary revenue streams for owners.
The EPA tailpipe-emission framework and NHTSA fuel-economy standards in the United States, alongside the EU Green Deal vehicle CO2 targets and CE marking requirements for electrical systems in Europe, collectively mandate cleaner propulsion architectures that solar-electric hybrids satisfy through reduced grid-dependency. India's PLI scheme for advanced chemistry cell manufacturing and BIS certification for solar photovoltaic modules are accelerating local supply chain formation for domestic producers like Mahindra & Mahindra Ltd. Stakeholders must monitor how battery-type transitions from lithium-ion toward solid-state architectures alter the optimal solar-to-storage interface design.
Market Dynamics
Fleet operators in urban logistics are accelerating solar electric car adoption as total-cost-of-ownership models demonstrate measurable fuel savings against conventional electric vehicles. This demand pull is concentrating engineering investment around photovoltaic integration methods that maximize surface-area yield.
Growth Catalysts
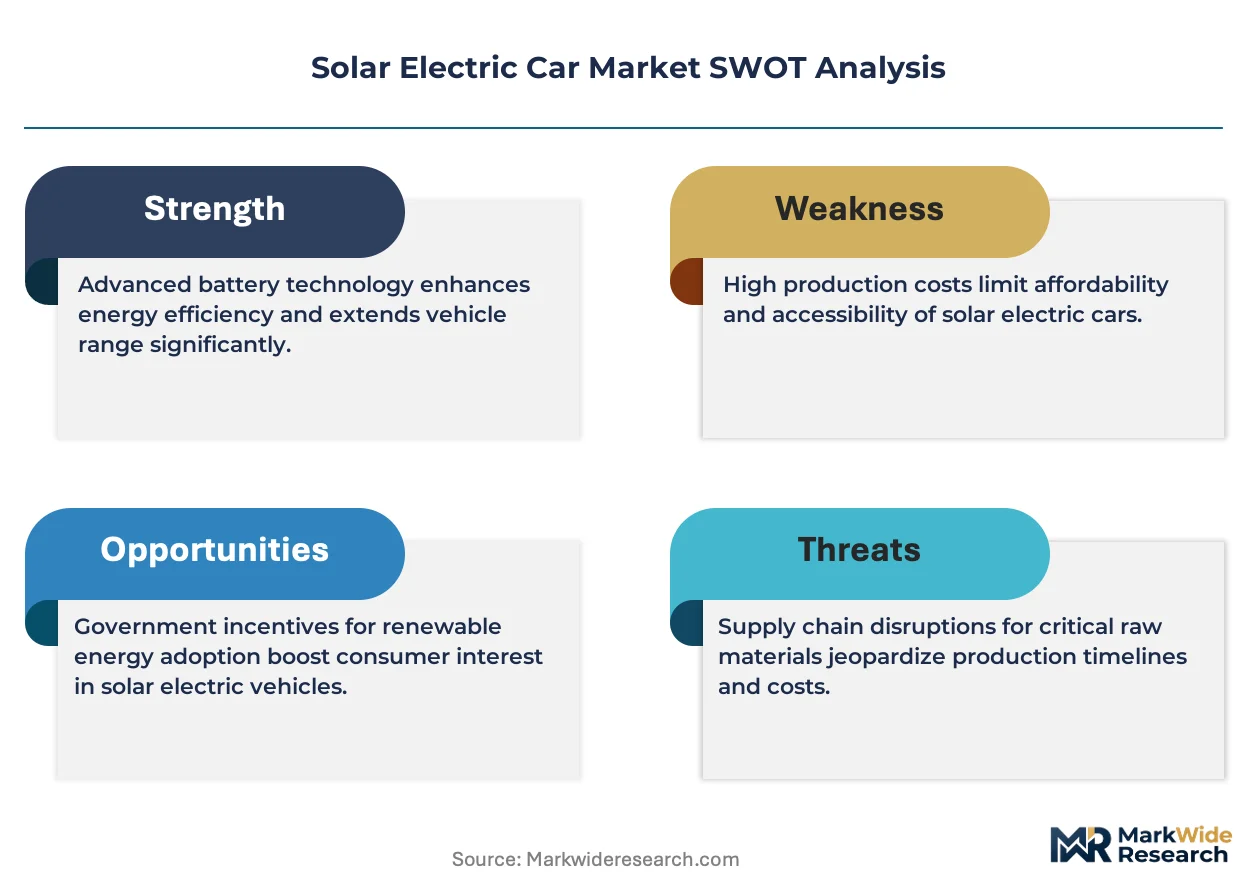
- EU Green Deal vehicle CO2 targets:Manufacturers must reduce fleet-average emissions, creating compliance value for solar-supplemented range that cuts grid electricity consumption per kilometer traveled.
- Thin-film photovoltaic integration:Engineering advances in flexible substrate deposition enable curved body-panel application, expanding harvestable surface beyond flat roof sections.
- Urban logistics fleet electrification:Last-mile delivery operators prioritize vehicles with minimal charging infrastructure dependency, making solar range extension operationally attractive.
Market Restraints
- Silicon wafer price volatility:Crystalline cell costs fluctuate with polysilicon supply constraints from concentrated Chinese ingot production, compressing module margins.
- Energy conversion efficiency ceiling:Commercial photovoltaic cells face theoretical Shockley-Queisser limits around 33% for single-junction silicon, constraining daily range addition.
- Vehicle safety homologation friction:NHTSA crash-test protocols for integrated solar glazing create extended certification timelines versus conventional body panels.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Domestic battery production incentives reduce import dependency for solar-electric hybrid manufacturers targeting price-sensitive fleet segments.
- Vehicle-to-grid bidirectional capability:Solar generation paired with grid-export functionality creates secondary revenue streams for owners during peak pricing periods.
- Subscription-based charging optimization:Software access models monetize ownership beyond initial sale through algorithmic yield maximization and predictive energy routing.
Industry Challenges
- Photovoltaic-electronics thermal management:Integrated cells require cooling systems that preserve efficiency without adding parasitic mass or aerodynamic drag.
- Multi-jurisdictional electrical certification:CE marking requirements for European markets diverge from BIS photovoltaic module standards, fragmenting validation pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Electric Car Market |
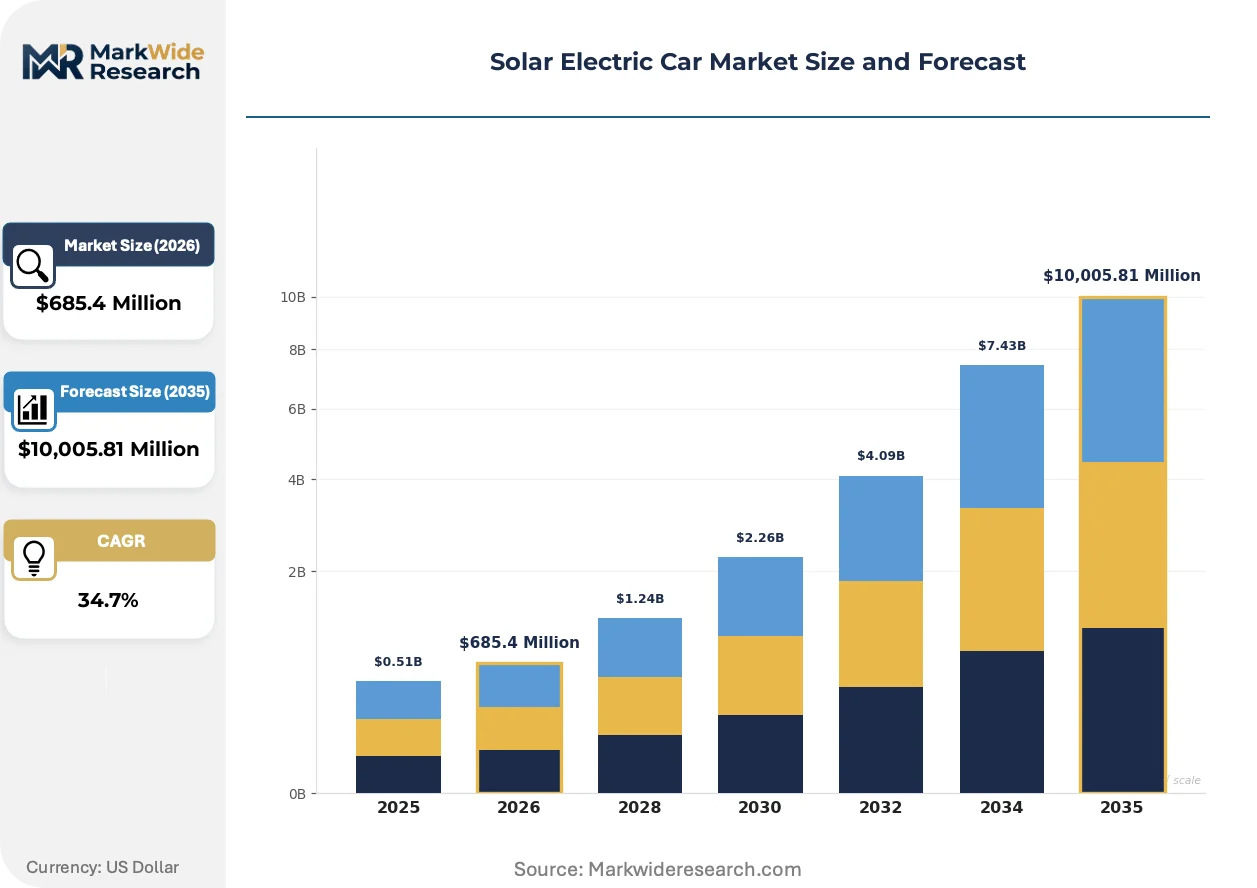
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $10,005.81 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Hatchbacks, Coupes Charging Technology: Solar Integration, Rapid Charging, Standard Charging, Wireless Charging Battery Type: Lithium-ion, Solid State, Nickel Metal Hydride, Lead Acid Market Strategy: Direct Sales, Leasing, Subscription, Fleet Sales |
| Companies Covered | Ford Motor Company, Toyota Motor Corporation, Lightyear Technologies B.V., Aptera Motors Corp., SONO MOTORS GmbH, Hyundai Motor Group, Mahindra & Mahindra Ltd., Venturi, Squad Mobility B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Electric Car Market Trends and Innovations
Photovoltaic integration methods are diverging between high-efficiency crystalline architectures and flexible thin-film approaches, each optimizing for different vehicle form factors and cost structures. This technical bifurcation is reshaping supplier relationships and manufacturing location decisions.
Perovskite tandem cell stacks are electrifying solar yield potential for automotive applications by stacking light-absorbing layers that capture broader spectrum segments. Tier 1 suppliers in Germany and Japan are piloting deposition equipment for curved glass integration. This architecture is compressing the efficiency gap between laboratory cells and mass-production modules, enabling meaningful daily range contribution even in temperate latitudes.
EPA tailpipe-emission frameworks and NHTSA fuel-economy standards are tightening compliance corridors for 2027-2032 model years, treating solar-supplemented range as off-grid credit toward fleet-average targets. Manufacturers are responding by reserving premium solar configurations for high-margin vehicle classes where certification costs amortize efficiently. California Air Resources Board zero-emission vehicle mandates create additional state-level pull for range-extending technologies.
Fleet procurement is consolidating around total-cost-of-ownership metrics that internalize fuel savings, maintenance reduction, and residual value uncertainty into lease-rate calculations. Third-party fleet managers are displacing direct manufacturer relationships in urban logistics segments. This concentration is most visible in German and Dutch metropolitan logistics networks where municipal low-emission zones penalize conventional diesel access.
Solar Electric Car Market Segmentation
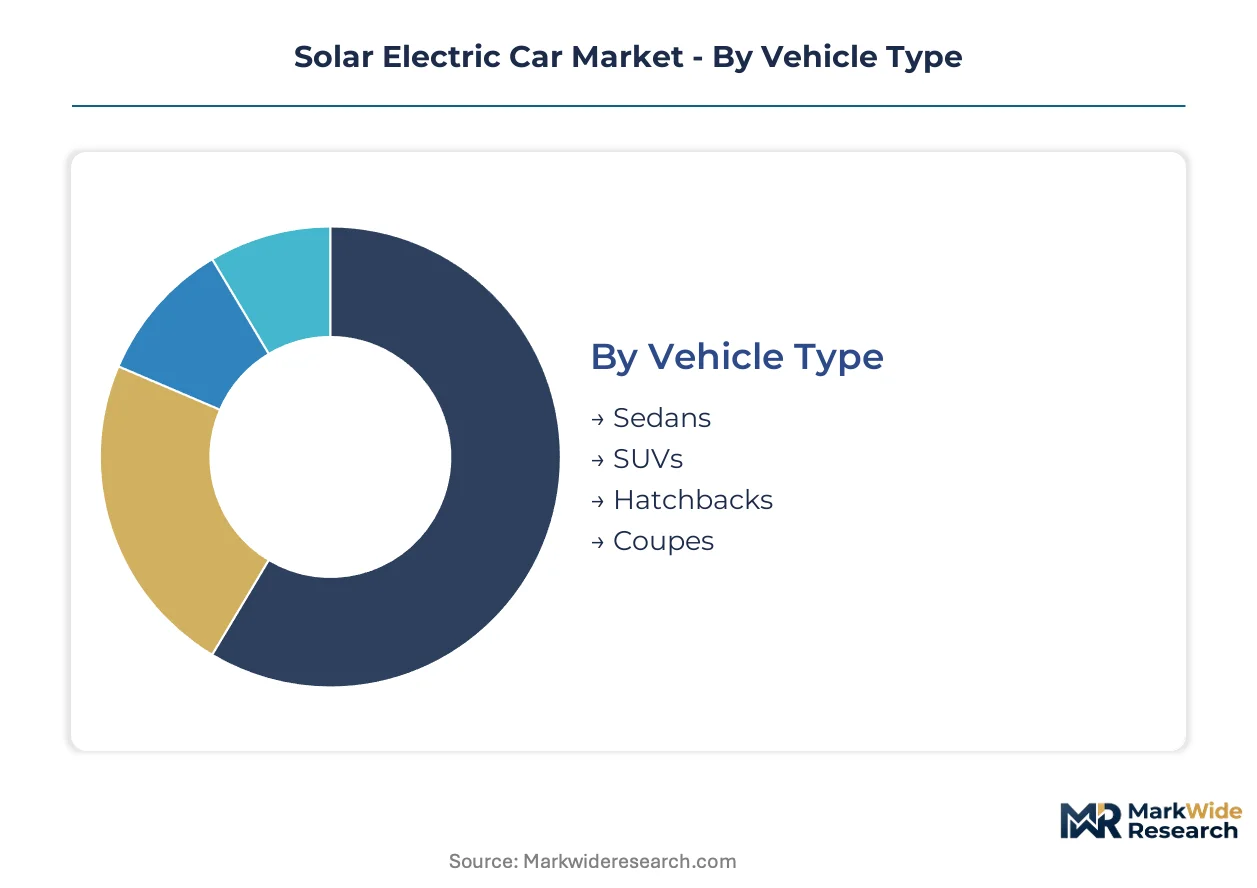
Segmentation in solar electric vehicles exposes how surface-area constraints, charging infrastructure maturity, and ownership economics create divergent value pools. Each dimension reveals distinct technical requirements and customer acquisition costs that reshape manufacturer positioning.
Vehicle Type:
Upgrade cycles in solar electric vehicles accelerate where body geometry maximizes photovoltaic yield per unit battery capacity, concentrating engineering investment on form factors with favorable surface-to-mass ratios.
- Sedans:Extended rooflines and hood surfaces accommodate larger photovoltaic arrays, making sedans the default choice for commuter-focused solar range extension in German and Japanese metropolitan markets. Fleet procurement managers in urban logistics prioritize sedan configurations for driver ergonomics combined with meaningful daily solar contribution.
- Hatchbacks:Compact dimensions with vertical rear surfaces sacrifice some roof area but enable lower curb weights that improve solar-to-mile efficiency metrics. European city-car segments show hatchbacks climbing fastest as parking-constrained buyers accept reduced range for maneuverability gains.
- SUVs:Higher ride heights expand hood and roof exposure angles, though increased mass demands larger battery packs that dilute solar economics.
- Coupes:Stylized rooflines compromise flat panel installation, relegating solar integration to hood and trunk surfaces with constrained daily yield.
Sedans sit at the top of the volume ranking, with hatchbacks climbing the fastest.
Charging Technology:
Cost tier differentiation in solar electric vehicles stratifies around infrastructure dependency, with premium configurations minimizing grid reliance while economy segments prioritize charging speed over energy autonomy.
- Solar Integration:Embedded photovoltaic cells convert irradiance directly to traction battery charge, extending effective range without grid connection. Dutch and Belgian fleet operators are consolidating procurement around solar-integrated vehicles to circumvent public charging queue times during peak delivery windows.
- Rapid Charging:High-amperage DC systems compress dwell times for commercial operators running multiple daily shifts, though infrastructure capital requirements concentrate deployment in German autobahn corridors and California interstate networks.
- Standard Charging:Level 2 AC equipment dominates residential and workplace installation due to lower electrical service upgrade costs.
- Wireless Charging:Inductive pad systems eliminate connector wear but impose efficiency penalties and alignment precision demands that slow adoption outside controlled fleet depots.
Solar Integration commands the highest margin tier, with Rapid Charging gaining share fastest among commercial buyers.
Battery Type:
Application-specific energy density requirements segment solar electric vehicle battery selection, with thermal management needs and cycle life expectations driving chemistry choices across climate zones and duty cycles.
- Lithium-ion:NMC and LFP chemistries dominate current production with established supply chains and recycling infrastructure, though energy density plateaus limit solar-to-storage optimization potential. Indian PLI scheme incentives are concentrating lithium-ion cell assembly capacity near Chennai and Bengaluru for domestic solar-electric vehicle integration.
- Solid State:Ceramic electrolyte architectures promise higher energy density with reduced thermal runaway risk, positioning solid state as the chemistry of record for premium solar vehicles targeting maximum range extension. Toyota Motor Corporation and QuantumScape Corporation pilot production lines target automotive qualification timelines that would enable next-generation solar integration designs.
- Nickel Metal Hydride:Mature chemistry persists in hybrid auxiliary applications where cost sensitivity outweighs energy density requirements.
- Lead Acid:Limited to low-voltage accessory systems and starter functions in hybrid architectures, excluded from traction applications due to mass and cycle life constraints.
Lithium-ion retains volume leadership, with Solid State expanding most quickly in premium vehicle classes.
Market Strategy:
Customer type concentration in solar electric vehicle distribution channels reflects capital availability, residual value risk appetite, and software monetization potential across private and commercial buyer segments.
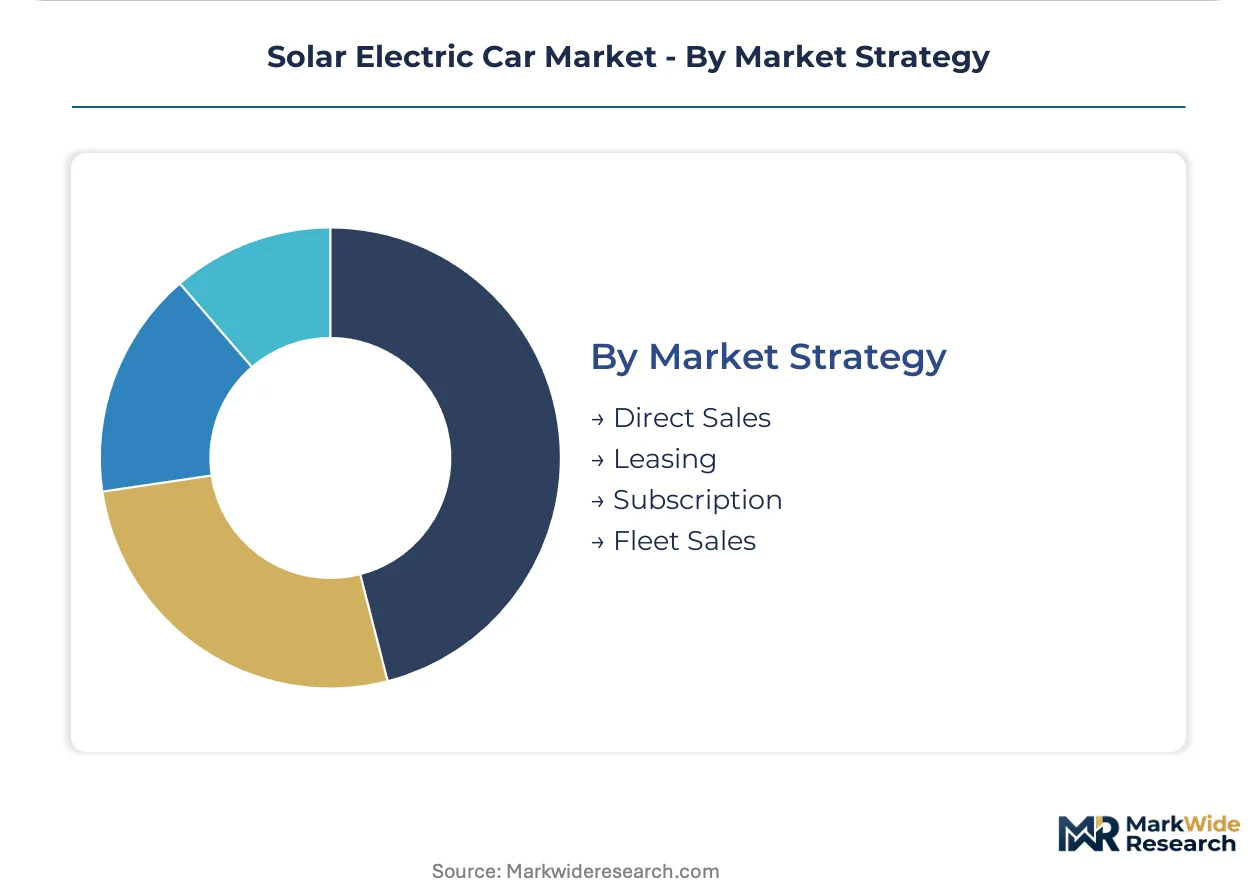
- Fleet Sales:Volume contracting with logistics operators and corporate mobility providers aggregates demand into predictable production schedules, enabling manufacturers to amortize solar integration tooling across guaranteed unit commitments. German last-mile delivery networks in Berlin, Hamburg, and Munich are consolidating procurement through third-party fleet managers rather than direct manufacturer relationships.
- Leasing:Residual value guarantees shift technology obsolescence risk from consumers to lessors, accelerating adoption among buyers skeptical of photovoltaic durability claims. Sono Motors GmbH structures leasing products that bundle solar panel maintenance with vehicle access to reduce total-cost-of-ownership uncertainty.
- Direct Sales:Manufacturer-controlled retail eliminates dealer markups but demands customer education investment around solar yield variability and seasonal performance expectations.
- Subscription:All-inclusive monthly access packages incorporate charging, maintenance, and software updates, targeting urban consumers prioritizing flexibility over asset ownership.
Fleet Sales anchor current volume, with Subscription models gaining traction fastest among metropolitan private buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates photovoltaic engineering investment while India accelerates domestic battery assembly through production-linked incentives, creating divergent regional pathways for solar-electric vehicle commercialization.
United States
Fleet operators in California and Texas prioritize solar range extension to minimize charging downtime during peak delivery windows. EPA tailpipe-emission frameworks and NHTSA fuel-economy standards mandate cleaner propulsion architectures through 2032. The San Francisco Bay Area hosts development clusters where vehicle-to-grid integration pilots attract venture capital.
Germany
Urban logistics operators in Berlin and Hamburg consolidate procurement through third-party fleet managers seeking total-cost-of-ownership advantages. EU Green Deal vehicle CO2 targets create compliance value for solar-supplemented range that reduces grid electricity consumption per kilometer. Munich anchors engineering investment in thin-film photovoltaic integration onto curved body panels.
India
Last-mile delivery fleets in Maharashtra and Karnataka demand vehicles with minimal charging infrastructure dependency. The PLI scheme for advanced chemistry cell manufacturing accelerates local supply chain formation alongside BIS certification requirements for solar photovoltaic modules. Chennai and Bengaluru concentrate lithium-ion cell assembly capacity for domestic solar-electric vehicle integration.
Netherlands
Metropolitan logistics networks in Amsterdam and Rotterdam penalize conventional diesel access through municipal low-emission zones. Dutch fleet operators circumvent public charging queue times by procuring solar-integrated vehicles for peak delivery windows. Eindhoven hosts thin-film deposition equipment pilots for curved glass integration.
Japan
Premium vehicle manufacturers target maximum range extension through solid-state battery architectures paired with solar integration. METI industrial policy supports ceramic electrolyte qualification timelines for next-generation solar-to-storage interface designs. Toyota Motor Corporation pilots production lines in the Nagoya region targeting automotive qualification.
Solar Electric Car Market Competitive Landscape
Top-tier vendors anchor premium solar integration tiers, while mid-scale specialists concentrate on fleet-service contracting and lightweight composite architectures. The market structure fragments across photovoltaic engineering approaches, with thin-film deposition specialists competing against crystalline cell integrators for body-panel applications. Three archetypes dominate: legacy automakers diversifying into solar-supplemented range, pure-play solar-electric vehicle developers, and component suppliers pivoting into vehicle integration. Competitive moves concentrate on strategic partnerships for photovoltaic supply security and geographic expansion into fleet-dense metropolitan logistics corridors.
Within the pure-play developer tier, Lightyear Technologies B.V. and SONO MOTORS GmbH exemplify divergent commercialization strategies, with the former emphasizing proprietary solar yield algorithms and the latter anchoring its position on bundled fleet-service contracts. Aptera Motors Corp. occupies a specialist niche in ultra-lightweight composite architectures that maximize solar surface-to-mass ratios. These three entities represent distinct archetypes: algorithmic differentiation, service-integrated leasing, and material-science specialization.
| Leading Market Players |
|---|
| Ford Motor Company |
| Toyota Motor Corporation |
| Lightyear Technologies B.V. |
| Aptera Motors Corp. |
| SONO MOTORS GmbH |
| Hyundai Motor Group |
| Mahindra & Mahindra Ltd. |
| Venturi |
| Squad Mobility B.V. |
| Others |
Pricing and Supply Chain Analysis
Thin-film photovoltaic deposition equipment migration toward German and Japanese engineering centers is compressing module production costs while simultaneously concentrating supply relationships among a narrowing tier of deposition-technology licensors. This dual concentration reshapes pricing power toward OEMs with captive photovoltaic engineering capabilities and away from vehicle assemblers sourcing commoditized cells.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for crystalline silicon modules used in solar-electric vehicle integration. Three-tier pricing structure across premium, standard, and economy levels stratifies by photovoltaic conversion efficiency and vehicle-to-grid certification tier. Cost compression in economy-tier hatchback configurations is intensifying because polysilicon supply volatility feeds through to module margins. Fleet procurement managers in urban logistics exhibit highest price sensitivity, while premium sedan buyers prioritize solar yield algorithms over per-watt module costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet operator demand, while Tier 1 photovoltaic suppliers maintain direct relationships with pure-play solar-electric vehicle developers. Polysilicon refining concentrates in China, cell fabrication in South Korea and Malaysia, and module assembly in Germany and the Netherlands. The supply chain draws from high-purity silicon metal, silver metallization paste, and ethylene-vinyl acetate encapsulant as critical inputs. Single-source vulnerability in transparent conductive oxide deposition equipment creates chokepoint exposure for curved glass integration programs. Distribution runs through automotive Tier 1 suppliers for legacy OEM programs and direct contracting for fleet-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar electric car market has transitioned into a late-cycle quality phase where fleet buyers now specify perovskite tandem compatibility and bidirectional charging certification as baseline procurement criteria. This specification escalation favors manufacturers with in-house photovoltaic engineering over assembly-only market participants.
For Market Incumbents: Acquire thin-film deposition equipment manufacturers to secure curved body-panel integration capabilities. Defensive consolidation around perovskite tandem cell supply agreements protects against pure-play solar-electric vehicle developers capturing premium fleet contracts. Capacity additions in German engineering corridors preserve pricing power against Chinese crystalline cell commoditization.
For New Entrants and Emerging Players: The mid-tier price gap between algorithmic premium sedans and economy hatchbacks offers white-space entry for lightweight composite architectures. Urban logistics fleet managers in Dutch and Belgian metropolitan networks represent the most penetrable buyer segment. A software-subscription go-to-market angle monetizes solar yield optimization beyond hardware margins.
For Investors and Strategic Acquirers: Valuations sit cheapest among photovoltaic-electronics thermal management specialists with automotive qualification timelines. Long-term viability hinges on solid-state battery interface design capabilities across the next technology cycle. Acquisition targets should demonstrate vehicle-to-grid software stacks and municipal fleet deployment references. The signal to watch is BIS certification acceleration for Indian domestic module production.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Tandem Cell Integration | Perovskite deposition pilots in Eindhoven and Nagoya compress efficiency gaps for temperate latitude range extension. |
| Fleet Service Contract Bundling | Sono Motors structures photovoltaic maintenance inclusion to reduce total-cost-of-ownership uncertainty for logistics operators. |
| Vehicle-to-Grid Software Development | California ISO pilots create secondary revenue streams through peak pricing arbitrage for solar-equipped fleet assets. |
| Backward Integration into Cell Assembly | Indian PLI scheme incentives concentrate lithium-ion capacity near Chennai for domestic solar-electric vehicle supply security. |
| Lightweight Composite Architecture Investment | Aptera Motors maximizes solar surface-to-mass ratios through specialized material-science differentiation. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, photovoltaic module production databases, and municipal fleet procurement records — were reconciled through structured primary interviews and secondary validation. Conversations with solar-electric vehicle development leads, Tier 1 photovoltaic supplier procurement managers, urban logistics fleet operators, and thin-film deposition equipment manufacturers informed demand-side and supply-side assessments. Secondary sources included EU Green Deal regulatory filings, EPA fuel-economy certification data, Indian PLI scheme beneficiary disclosures, and vehicle registration databases from German and Dutch metropolitan regions. Bottom-up unit economics and top-down market sizing were triangulated to constrain forecast variance.
Data-stream reconciliation across vehicle type, charging technology architecture, battery chemistry, and market strategy dimensions anchored the analytical framework across the analysis window. CAGRs were derived from segment-specific adoption curves weighted by fleet procurement concentration and consumer lease-rate sensitivity. Industry-specific forecast inputs incorporated photovoltaic conversion efficiency improvement trajectories, solid-state battery qualification timelines, and municipal low-emission zone expansion schedules.
Caveats apply where perovskite tandem cell manufacturing yield rates, solid-state battery interface standardization, or NHTSA solar glazing homologation timelines could materially shift the outlook. Forecasts reflect documented assumptions regarding polysilicon supply stability, fleet operator total-cost-of-ownership model adoption, and software-subscription monetization penetration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market