
 Germany Automotive High Performance Electric Vehicles Market | 2026-2036
Germany Automotive High Performance Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive High Performance Electric Vehicles Market Foresight
Fleet procurement among premium corporate mobility providers is pivoting toward high-performance electric vehicles as sustainability mandates harden. BMW Group anchors its position through in-house production of electric drivetrain components. Porsche AG differentiates via motorsport-derived battery thermal management. Mercedes-Benz AG extends its AMG electric line through dedicated performance architecture.
Germany automotive high performance electric vehicles are battery-electric passenger cars engineered for sustained output exceeding 300 kW, with acceleration benchmarks below four seconds and thermal management systems enabling repeated high-load cycles without performance degradation. Sports coupes and sedans occupy the core margin pool, while SUVs capture expanding buyer segments seeking utility without output compromise. Solid-state battery research programs are reshaping the technology hierarchy, though lithium-ion configurations sustain near-term volume leadership across fast-charging infrastructure deployments.
Germany's KBA type-approval protocols, EU Green Deal fleet emission targets, and REACH chemical compliance frameworks collectively elevate engineering investment thresholds for market access. The EU AI Act introduces emerging conformity requirements for autonomous performance features. Stakeholders must monitor regulatory calibration between performance benchmarks and sustainability metrics as certification standards evolve.
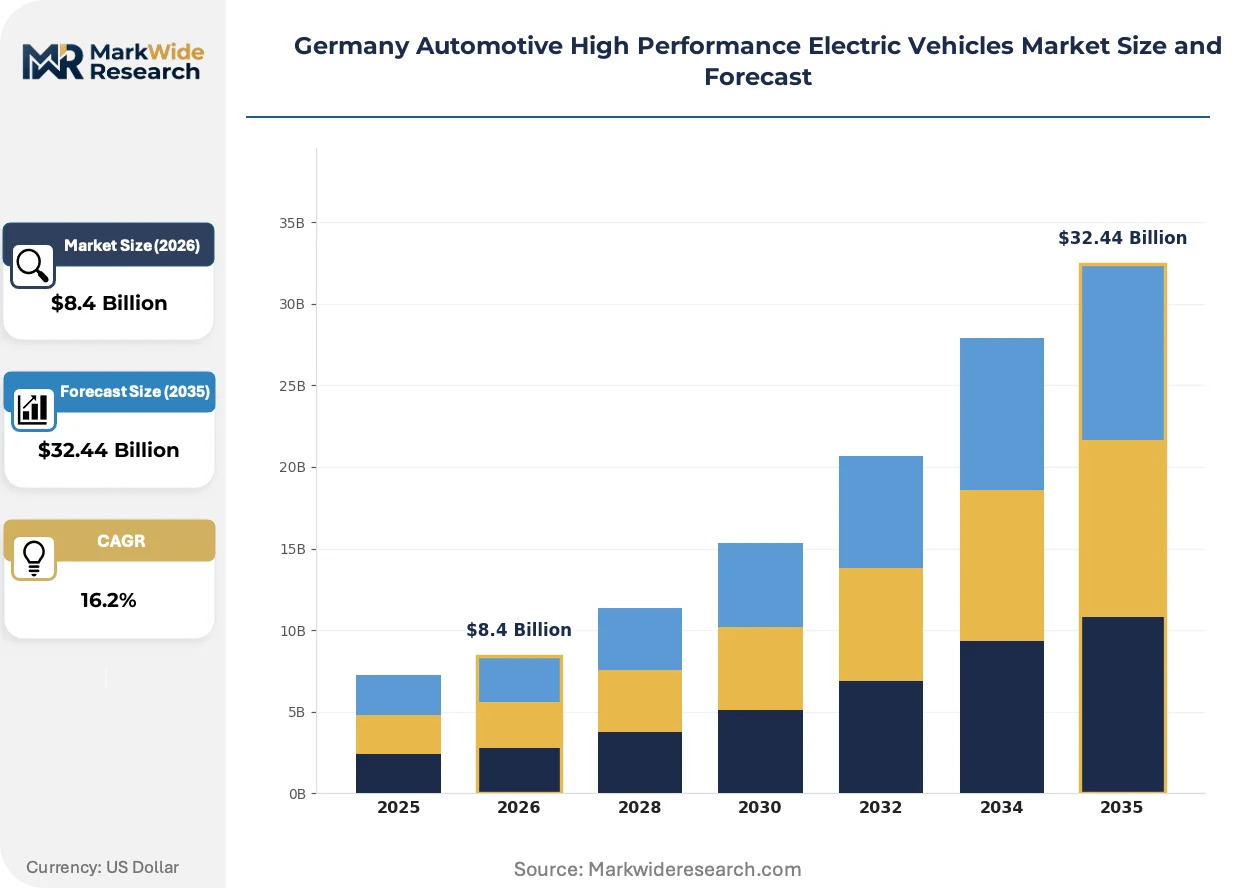
Market Dynamics
Fleet procurement among premium corporate mobility providers is pivoting toward high-performance electric vehicles as sustainability mandates harden. Engineering investment thresholds are elevating as KBA type-approval protocols intersect with EU Green Deal fleet emission targets.
Growth Catalysts
- EU Green Deal fleet emission targets:Corporate mobility providers face binding CO2 reduction obligations that accelerate procurement of zero-emission performance vehicles for executive transport services.
- Solid-state battery research programs:Public-private consortia in Baden-Württemberg are advancing energy density breakthroughs that will extend range capabilities beyond current lithium-ion limitations.
- Fast-charging infrastructure deployments:Autobahn corridor investments by Ionity and EnBW are compressing recharge downtime for sustained high-load driving cycles.
Market Restraints
- Raw material cost volatility:Lithium and cobalt price swings from DRC and Chilean supply corridors are compressing cell manufacturing margins.
- Thermal management complexity:Repeated high-load cycles demand motorsport-derived cooling architectures that escalate engineering hours and component counts.
- REACH chemical compliance frameworks:Restricted substance lists for battery chemistries are forcing reformulation of electrolyte compounds and separator materials.
Strategic Opportunities
- Battery-electric sports coupes:The segment between compact performance sedans and full-size grand tourers remains underdeveloped for enthusiast buyers seeking chassis purity.
- EU AI Act autonomous features:Emerging conformity pathways for intelligent drive systems create first-mover advantages in automated track-day coaching and adaptive suspension calibration.
- Corporate subscription mobility:Fleet operators are piloting flexible-tenure models that bundle vehicle access with charging and maintenance services.
Industry Challenges
- Power electronics engineering scarcity:SiC inverter design and thermal simulation expertise concentrates among motorsport-derived suppliers, constraining hiring pipelines.
- KBA type-approval timelines:Extended homologation cycles for novel battery architectures delay market entry by 12-18 months versus conventional drivetrain certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive High Performance Electric Vehicles Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $32.44 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sports Coupes, Sedans, SUVs, Hatchbacks Battery Technology: Lithium-Ion, Solid State, Flow Batteries, Nickel-Metal Hydride Charging Infrastructure: Fast Chargers, Level 2 Chargers, Wireless Charging, On-Route Charging End User: Retail Consumers, Fleet Operators, Corporate Users, Government Agencies |
| Companies Covered | Volkswagen AG, BMW Group, Daimler AG, Tesla Inc, Porsche AG, Audi AG, Ford Motor Company, Rimac Automobili, Mercedes-Benz AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive High Performance Electric Vehicles Market Shifts & Advancements
Powertrain architectures are fragmenting as silicon carbide inverters and axial-flux motors enable packaging efficiencies that reshape vehicle proportions. Three developments are compressing competitive cycles.
Axial-flux electric motors are decentralizing torque distribution possibilities in performance EVs. Stuttgart engineering houses are adopting compact pancake motor layouts for rear-axle torque vectoring. This topology is decentralizing the traditional central-driveshaft layout and enabling lower floor heights without sacrificing output.
KBA type-approval protocols are tightening validation requirements for battery thermal runaway containment. Manufacturers must demonstrate 30-minute flame resistance for cell-to-pack architectures before series production. Sports sedan segments are absorbing the steepest compliance costs as they pursue track-day repeatability ratings.
Fleet procurement departments are consolidating supplier relationships around vertically integrated drivetrain providers. Long-term service agreements are displacing transactional vehicle purchases among premium mobility services. Bavaria-based corporate leasing operators are piloting this model first, bundling energy management with residual value guarantees.
Germany Automotive High Performance Electric Vehicles Market Segmentation
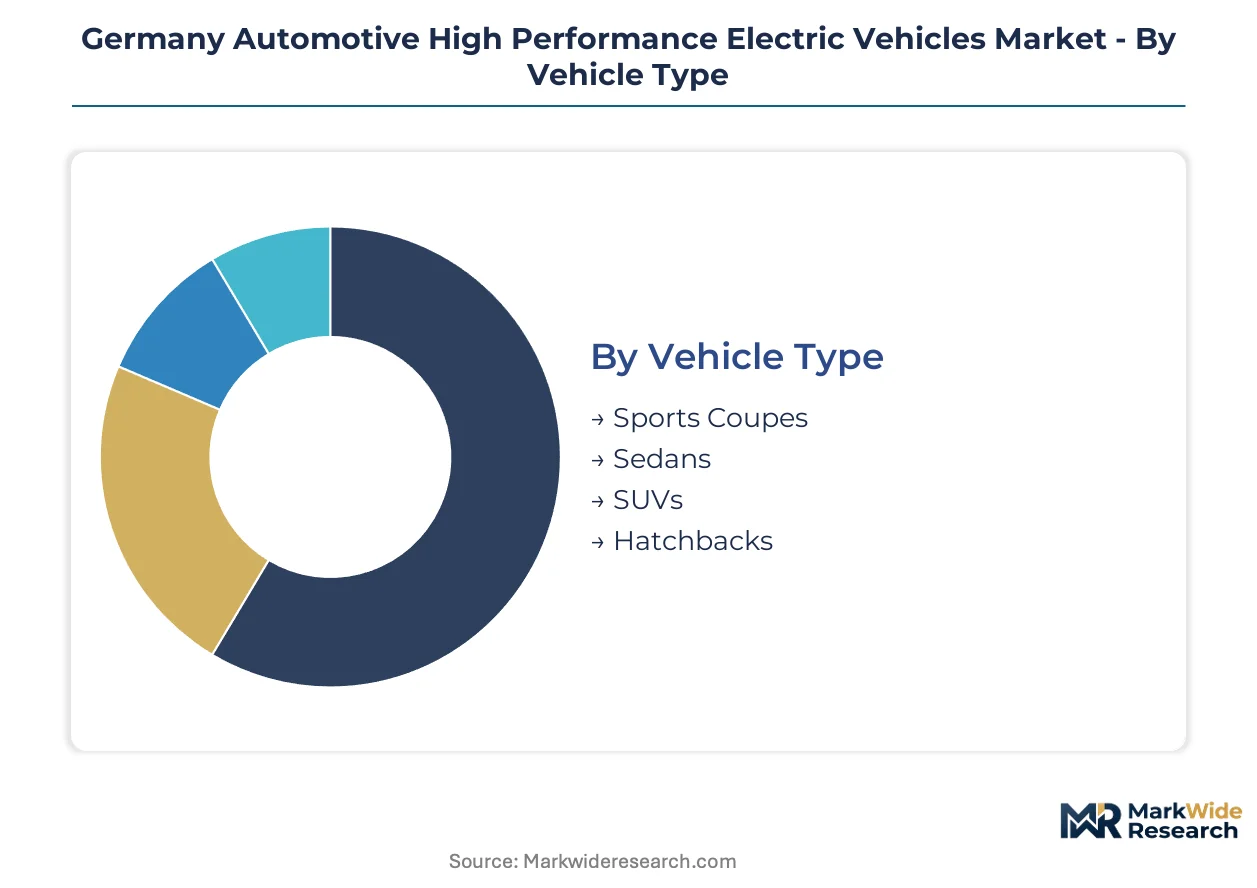
Segmentation in Germany's high-performance EV market reveals how engineering priorities diverge across buyer archetypes. Fleet operators prioritize thermal endurance for sustained Autobahn cruising, while retail enthusiasts demand chassis purity and acceleration benchmarks. Battery chemistry choices increasingly stratify around charging speed versus energy density trade-offs.
Vehicle Type:
Purchase decisions hinge on utility-positioning versus output purity, with Stuttgart engineering houses optimizing architectures for distinct driving profiles.
- Sports Coupes:Low-slung two-door architectures prioritize torsional rigidity and 50:50 weight distribution for Nürburgring lap consistency. Procurement concentrates among Baden-Württemberg's private collector community and track-day subscription services, where KBA type-approval for motorsport-derived cooling commands premium positioning.
- Sedans:Four-door configurations balance rear-seat accommodation with sustained output exceeding 300 kW for executive Autobahn transit. Corporate mobility providers in Bavaria are consolidating procurement around this format as fleet sustainability mandates harden.
- SUVs:Raised seating positions and expanded cargo volumes attract family-oriented buyers unwilling to compromise on acceleration benchmarks below four seconds.
- Hatchbacks:Compact footprints serve urban enthusiasts in Berlin and Hamburg seeking parking agility with performance credentials.
Volume sits with sedans; growth tilts toward SUVs as utility-conscious buyers enter the performance category.
Battery Technology:
Cell chemistry selection determines thermal headroom for repeated high-load cycles, directly impacting KBA homologation timelines and engineering investment thresholds.
- Lithium-Ion:NCM and LFP configurations sustain near-term volume leadership through established supply chains and Ionity fast-charging compatibility. Baden-Württemberg's public-private consortia are optimizing cell-to-pack architectures for 30-minute flame resistance certification.
- Solid State:Ceramic electrolyte research programs promise energy density breakthroughs beyond current lithium-ion limitations. Stuttgart engineering houses are prioritizing this trajectory for next-generation track-day repeatability ratings.
- Flow Batteries:Aqueous electrolyte systems enable rapid refueling concepts for commercial deployment scenarios.
- Nickel-Metal Hydride:Mature chemistry retains niche positioning for cost-sensitive performance variants.
Production scale concentrates with lithium-ion; R&D investment flows fastest toward solid-state architectures.
Charging Infrastructure:
Recharge downtime tolerance varies sharply across use cases, from fleet operators demanding corridor reliability to residential buyers accepting overnight cycles.
- Fast Chargers:350 kW DC systems along Autobahn corridors compress recharge intervals to 15-20 minutes for sustained high-load driving. EnBW and Ionity deployments in Bavaria and Baden-Württemberg anchor this infrastructure layer.
- Level 2 Chargers:AC systems up to 22 kW serve overnight residential and workplace parking scenarios.
- Wireless Charging:Inductive pad systems eliminate connector wear for premium corporate mobility services.
- On-Route Charging:Battery-swapping pilot programs target taxi and delivery fleet operators in Berlin.
Deployment density peaks with fast chargers; innovation investment clusters around wireless integration.
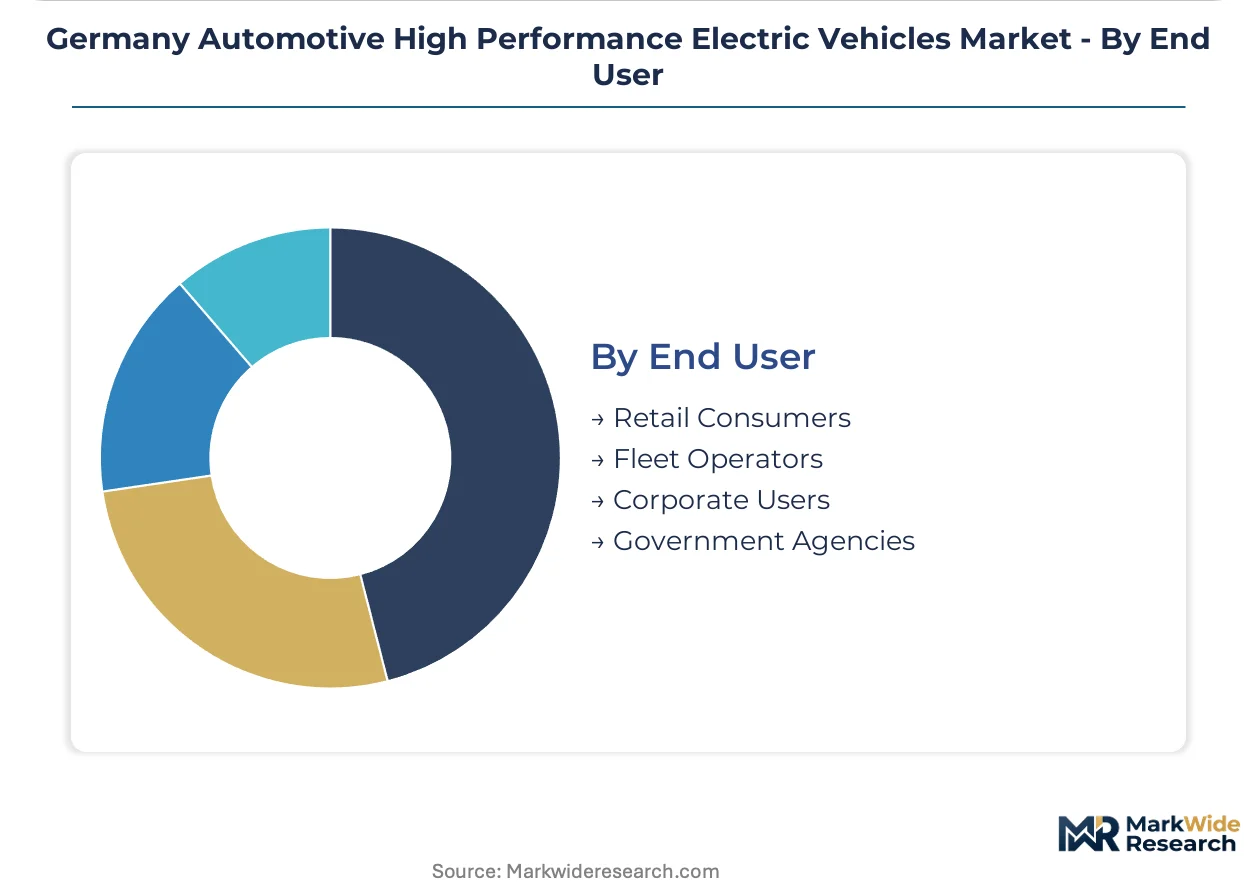
End User:
Procurement authority and total cost of ownership horizons reshape specification priorities across buyer categories.
- Fleet Operators:Premium corporate mobility providers in Munich and Frankfurt are pivoting procurement toward high-performance EVs as EU Green Deal fleet emission targets harden. Long-term service agreements bundle energy management with residual value guarantees.
- Retail Consumers:Enthusiast buyers in Stuttgart's automotive cluster prioritize acceleration benchmarks and chassis purity for weekend track-day usage.
- Corporate Users:Executive transport departments seek brand alignment with sustainability credentials without output compromise.
- Government Agencies:Federal and state procurement is piloting performance EVs for diplomatic and ceremonial fleets.
Transaction volume accumulates with fleet operators; specification innovation is steered by retail enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate fleet procurement concentrates in southern Germany's automotive corridor, where EU Green Deal mandates intersect with established engineering infrastructure. Regional demand patterns diverge sharply between Autobahn-intensive transit corridors and urban mobility zones.
Baden-Württemberg
Stuttgart's engineering houses anchor procurement for track-day subscription services and private collector networks. KBA type-approval protocols for motorsport-derived cooling systems command premium positioning here. Porsche AG and Audi AG concentrate R&D investment in Zuffenhausen and Neckarsulm for next-generation thermal management architectures.
Bavaria
Munich-based corporate leasing operators pilot flexible-tenure mobility models bundling energy management with residual value guarantees. EU AI Act conformity pathways for autonomous performance features attract engineering talent to the metropolitan zone. BMW Group anchors in-house production of electric drivetrain components across Dingolfing and Leipzig supply nodes.
North Rhine-Westphalia
Düsseldorf and Cologne host procurement headquarters for premium executive transport services facing binding CO2 reduction obligations. EnBW fast-charging corridor investments along the A3 and A4 Autobahn routes compress recharge intervals for sustained high-load driving. Ford Motor Company maintains development capacity in Cologne for performance EV adaptation.
Hesse
Frankfurt's financial services sector drives demand for brand-aligned sustainability credentials without output compromise. REACH chemical compliance frameworks for battery chemistries force reformulation of electrolyte compounds among suppliers in the Rhine-Main cluster. Mercedes-Benz AG extends AMG electric line development through dedicated performance architecture programs.
Lower Saxony
Wolfsburg anchors volume production integration for platform-sharing across performance variants. Volkswagen AG coordinates solid-state battery research consortia with public-private partnerships in the region. Ionity infrastructure deployment along the A2 and A7 corridors supports corridor reliability for fleet operators.
Germany Automotive High Performance Electric Vehicles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue motorsport-derived specialization and hypercar adjacent spaces. The vendor base concentrates among vertically integrated German OEMs with captive drivetrain production, supplemented by niche Croatian engineering houses and American scale players. Three archetypes dominate: legacy premium manufacturers with AMG/M/RS performance divisions, dedicated EV-native specialists, and technology-licensing platform providers. Competitive moves center on in-house production of electric drivetrain components and motorsport-derived battery thermal management partnerships.
Within the legacy premium tier, Volkswagen AG, BMW Group, and Porsche AG exemplify divergent strategic postures. Volkswagen AG occupies a position emphasizing platform scale and model-range breadth across multiple performance sub-brands. BMW Group represents the vertically integrated archetype with captive supply of electric drivetrain components and dedicated production infrastructure. Porsche AG anchors the motorsport-derived specialization vector, translating track-proven thermal architectures into series production compliance. These three German entities collectively exemplify how KBA type-approval expertise and EU regulatory navigation capability concentrate competitive advantage.
| Leading Market Players |
|---|
| Volkswagen AG |
| BMW Group |
| Daimler AG |
| Tesla Inc |
| Porsche AG |
| Audi AG |
| Ford Motor Company |
| Rimac Automobili |
| Mercedes-Benz AG |
| Others |
Supply & Pricing Matrix
Fleet operators in Bavaria and Baden-Württemberg anchor procurement volume for high-performance EVs, concentrating buying power around long-term service agreements that bundle energy management with residual value guarantees. This buyer archetype concentration elevates contract-based pricing over transactional spot purchases, compressing margins for suppliers lacking captive drivetrain production.
Pricing Analysis
Volume concentrates in sedans serving corporate mobility providers; margins concentrate in sports coupes where KBA type-approval for motorsport-derived cooling commands premium positioning. Price differentiation hinges on certification grade for thermal runaway containment and brand heritage in performance engineering. Pricing pressure stems from raw material cost volatility in lithium and cobalt supply corridors, squeezing cell manufacturing margins. Fleet operators exhibit highest price sensitivity due to total cost of ownership horizons; retail enthusiasts in Stuttgart's collector community show lowest sensitivity for track-day repeatability ratings.
Supply Chain Analysis
Engineering talent scarcity in silicon carbide inverter design and thermal simulation concentrates hiring competition in Stuttgart and Munich manufacturing zones. Cell production draws from South Korean and Chinese supply corridors for NCM cathode materials; cobalt sourcing rests on DRC extraction networks. Single-source vulnerability in SiC substrate supply creates chokepoint exposure for power electronics. Distribution runs through vertically integrated OEM captive networks rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's high-performance EV market is consolidating around vertically integrated producers as KBA type-approval timelines and thermal management complexity force weaker engineering houses toward exit. EU Green Deal fleet emission targets accelerate this pressure by binding procurement decisions to zero-emission compliance.
For Market Incumbents: Lock in SiC inverter supply agreements and motorsport-derived battery thermal management partnerships before engineering scarcity intensifies. Deepen captive production of electric drivetrain components to defend margin position against emerging EV-native specialists. Prioritize Baden-Württemberg R&D retention through dedicated performance architecture programs that leverage existing KBA type-approval expertise.
For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the lowest-friction entry vector for bypassing established dealership networks. Target corporate subscription mobility pilots in Munich and Frankfurt where flexible-tenure models remain underdeveloped. White-space exists in battery-electric sports coupes between compact performance sedans and full-size grand tourers for chassis-pure positioning.
For Investors and Strategic Acquirers: The window for entry favors motorsport-derived engineering houses with proven thermal management architectures and KBA homologation track records. Solid-state battery research consortia in Baden-Württemberg represent viable long-term viability bets as energy density breakthroughs reshape competitive hierarchies. Watch for EU AI Act conformity pathway announcements as inflection indicators for automated performance feature monetization.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures NCM cell allocation from South Korean producers for Stuttgart manufacturing. |
| Solid-State R&D Partnership | Positions Baden-Württemberg engineering houses for next-generation energy density leadership. |
| Fast-Charging Infrastructure Partnership | Compresses Autobahn corridor recharge intervals through Ionity and EnBW deployments. |
| Software-Defined Vehicle Investment | Enables EU AI Act-compliant autonomous track-day coaching and adaptive suspension. |
| Motorsport Thermal Management Licensing | Translates Porsche AG track-proven architectures into series production compliance. |
Research Methodology
KBA type-approval documentation, EU regulatory filings, and vehicle production databases formed the secondary backbone for this analysis. Primary fieldwork involved structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator sustainability directors, and Ionity infrastructure planners. Bottom-up triangulation across these stakeholder inputs validated top-down market sizing from registration data and corporate disclosure patterns.
Historical trendline analysis established baseline growth trajectories across vehicle type, battery technology, and end-user segmentation dimensions. The projection framework modeled propulsion architecture evolution and regional production cluster shifts throughout the forecast period. CAGRs were derived from weighted scenario analysis incorporating fast-charging deployment schedules and solid-state battery commercialization timelines.
The model holds under stable EU Green Deal enforcement and continued Ionity corridor investment; deviation in lithium supply disruption severity or KBA type-approval timeline extension would shift volume and value outputs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
UK Electric Vehicle Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market