
 Automotive EV HUB Market | 2026-2036
Automotive EV HUB Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive EV HUB Market Outlook
South Korea is rewriting the competitive map for hub motor production through Hyundai Mobis and its domestic battery supply chain. Nidec Corporation leverages its precision motor heritage to dominate axial-flux designs for compact urban vehicles. Robert Bosch GmbH sustains broad portfolio coverage across power electronics and integrated chassis systems, competing across multiple customer tiers.
An automotive EV hub integrates electric motor, inverter, and braking functions within the wheel assembly, typically delivering torque directly at 400-800V while eliminating driveshafts and reducing unsprung mass. The assembly serves commercial and passenger applications seeking packaging efficiency and modular platform scalability. Batteries and power electronics capture the dominant margin pools as cell chemistry advances and silicon-carbide inverters displace legacy IGBT architectures. Electric motors within the hub segment are gaining fastest in commercial vehicle applications where torque density and regenerative braking range extension prove decisive.
The EU Green Deal and F-Gas Regulation shape product standards by mandating CO2 fleet reductions and restricting high-GWP refrigerants in thermal management circuits. EPA tailpipe rules and NHTSA fuel economy standards in the United States force parallel investments in localized hub motor qualification and domestic content verification. Stakeholders must monitor how battery management system firmware certifications evolve alongside functional safety standards as hub architectures proliferate across OEM platforms.
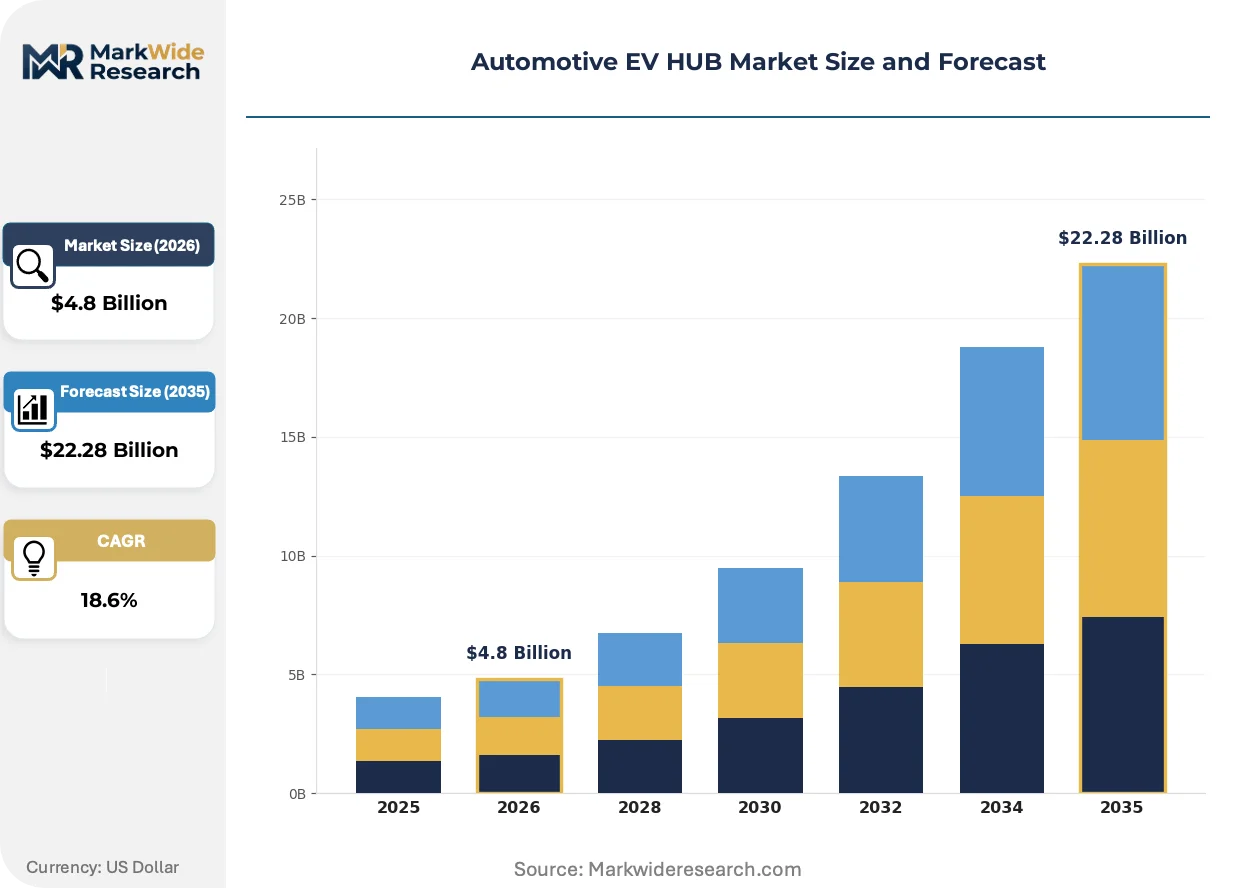
Market Dynamics
Silicon-carbide power electronics are collapsing cost barriers between centralized drivetrains and distributed hub architectures, forcing incumbent Tier 1 suppliers to requalify entire motor-inverter portfolios for wheel-integrated packaging.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating thermal management redesigns that favor hub motors' reduced cooling loads in commercial van platforms.
- Last-mile electrification:Parcel delivery fleet operators are specifying hub motor configurations to maximize cargo volume and enable flat-floor vehicle architectures.
- Axial-flux topology maturation:Torque density improvements in pancake-form motors are eliminating the packaging penalties that previously constrained hub adoption in passenger vehicles.
Market Restraints
- Permanent magnet supply concentration:Rare-earth processing dependence on Chinese refining infrastructure creates input cost volatility and qualification risks for NdFeB-dependent hub designs.
- Unsprung mass penalties:Wheel-integrated motors impose ride-quality trade-offs that limit adoption in premium passenger segments prioritizing NVH performance.
- Functional safety certification timelines:ISO 26262 ASIL-D compliance for distributed motor control systems extends development cycles by 18-24 months versus centralized architectures.
Strategic Opportunities
- Indian commercial vehicle retrofit:Hub motor kits for existing diesel chassis offer a compliance pathway under the country's stricter axle-load and emissions enforcement.
- Autonomous shuttle platforms:Skateboard architectures with corner modules enable independent wheel control essential for precision maneuvering in geofenced urban deployments.
- US Inflation Reduction Act:Domestic content bonuses for battery and power electronics assembly are incentivizing localized hub motor production near Midwestern battery cell plants.
Industry Challenges
- Embedded software talent scarcity:Motor control firmware engineers with functional safety expertise command premium compensation and extended recruitment timelines.
- Legacy brake system integration:Hub packaging constraints force complete redesigns of caliper-rotor architectures, disrupting established supplier relationships and tooling amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive EV HUB Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batteries, Charging Stations, Electric Motors, Power Electronics Application: Passenger Vehicles, Commercial Vehicles, Fleet Management, Ride-Sharing Technology: Fast Charging, Inductive Charging, Smart Grid Integration, Battery Management Systems Customer Type: OEMs, Aftermarket Providers, Fleet Operators, Utilities |
| Companies Covered | Nidec Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, Magna International Inc., Protean Electric, Elaphe Propulsion Technologies, Hyundai Mobis, Bonfiglioli Riduttori S.p.A., YASA Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive EV HUB Market Strategic Shifts
Electrification architectures are fragmenting into competing philosophies—centralized versus distributed—while material science and software-defined vehicle stacks determine which configuration wins platform slots.
Silicon-carbide MOSFETs are collapsing thermal management requirements for wheel-integrated inverters, enabling air-cooled hub designs that eliminate liquid cooling loops. Commercial van manufacturers are adopting these configurations fastest, prioritizing maintenance simplicity over peak performance margins. The technology is collapsing the historical cost gap between hub motors and axle-mounted drivetrains in 400V applications.
The EU Green Deal's CO2 fleet targets are mandating efficiency gains that favor regenerative braking optimization through independent wheel control. OEMs must demonstrate compliance through certified test cycles that reward hub motors' superior energy recovery rates. Germany's KBA is processing type approvals for hub-equipped platforms at accelerated rates to meet 2030 interim targets.
Fleet procurement departments are consolidating supplier relationships around vertically integrated hub module providers capable of delivering motor-inverter-brake assemblies as single part numbers. This behavior is displacing the traditional multi-source model where chassis engineers specified discrete components. The shift is most visible in North American last-mile delivery contracts, where total cost of ownership guarantees now dominate capital expenditure decisions.
Automotive EV HUB Market Segmentation
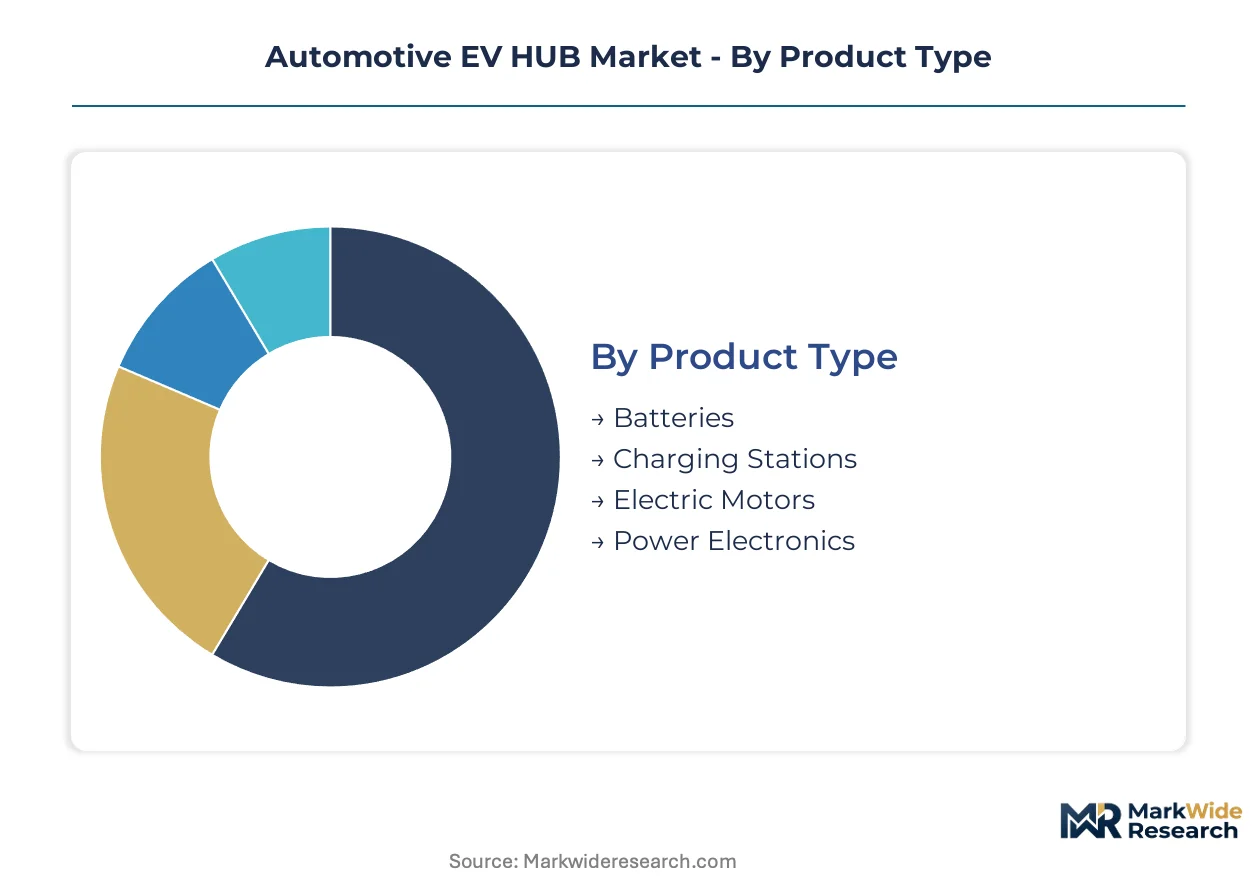
Hub motor architectures fragment across four critical dimensions that determine procurement patterns and platform economics. Product type segmentation reveals where margin pools concentrate, while application splits expose divergent performance requirements between passenger comfort and commercial duty cycles.
Product Type:
Batteries and power electronics refresh on 18-24 month cycles as cell chemistry and silicon-carbide inverter generations advance, while electric motors and charging infrastructure amortize over 7-10 year platform lives.
- Batteries:Cell chemistry advancements in lithium-iron-phosphate and solid-state architectures dominate hub motor cost structures. German OEMs are qualifying cylindrical formats for 800V hub platforms to maximize regenerative braking energy recovery.
- Power Electronics:Silicon-carbide MOSFET inverters integrated into wheel housings operate at switching frequencies above 50kHz, collapsing thermal management footprints. South Korean foundries are capturing inverter die supply contracts for Stuttgart and Munich development corridors.
- Electric Motors:Axial-flux pancake motors deliver torque density exceeding 15 Nm/kg for direct wheel mounting.
- Charging Stations:Fleet depot infrastructure scales through megawatt-class conductive systems for overnight commercial van replenishment.
Batteries dominate installed base value. Power electronics is where expansion concentrates.
Application:
Commercial vehicle procurement cycles run 3-5 years versus 6-8 years for passenger platforms, concentrating near-term volume in delivery van and shuttle segments.
- Commercial Vehicles:Last-mile delivery vans prioritize flat-floor architectures enabled by hub motors' elimination of driveshaft tunnels. North American fleet operators are specifying regenerative braking range extensions above 15% for urban stop-and-go duty cycles.
- Passenger Vehicles:Premium segments resist hub adoption due to unsprung mass penalties affecting NVH performance, while compact urban vehicles accept ride-quality trade-offs for packaging efficiency.
- Fleet Management:Telematics integration demands real-time motor health monitoring across distributed wheel units.
- Ride-Sharing:High-utilization autonomous shuttle platforms require independent wheel control for precision maneuvering in geofenced zones.
Commercial vehicles dominate current procurement volume. Passenger vehicles is where technology maturation will unlock scale.
Technology:
Fast charging and battery management systems mature on parallel tracks with vehicle electrification, while inductive charging and smart grid integration lag in standardization.
- Fast Charging:350kW conductive systems reduce commercial van downtime below 30 minutes for 80% state-of-charge, enabling hub motor platforms to maintain fleet utilization rates comparable to diesel equivalents.
- Battery Management Systems:Firmware architectures must achieve ASIL-D functional safety certification for distributed thermal monitoring across four independent wheel-integrated battery strings.
- Inductive Charging:Alignment tolerance requirements complicate wheel-integrated receiver packaging.
- Smart Grid Integration:Vehicle-to-grid bidirectional power flow from hub motor inverters remains pre-commercial for mass deployment.
Battery management systems dominate R&D investment. Fast charging is where infrastructure buildout accelerates adoption.
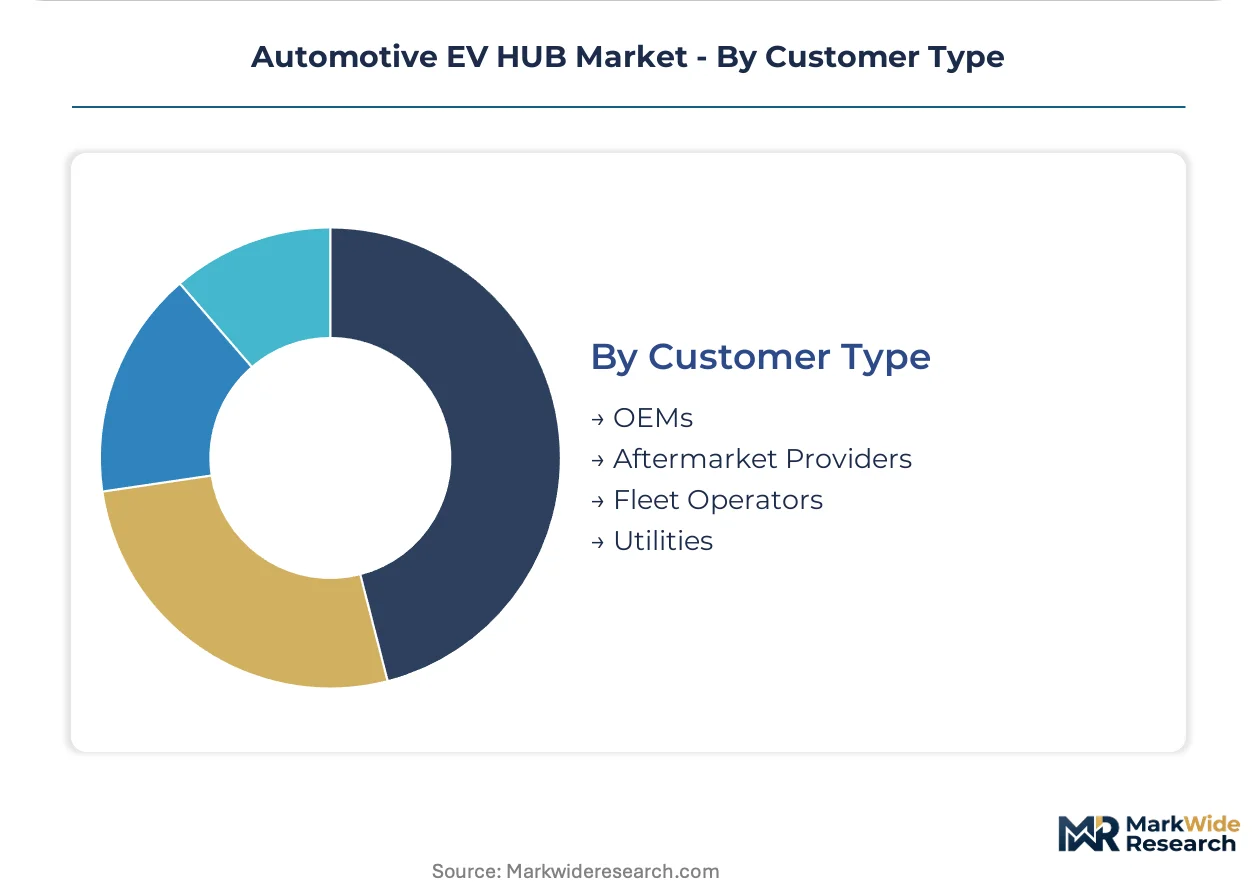
Customer Type:
OEMs and fleet operators consolidate purchasing power through multi-year platform contracts, while aftermarket providers and utilities fragment across service and infrastructure niches.
- OEMs:Volkswagen Group and Hyundai Motor Company are integrating hub motor qualification into modular electric platform architectures spanning multiple vehicle classes, collapsing supplier qualification costs through volume aggregation.
- Fleet Operators:Amazon and DHL procurement departments specify total cost of ownership guarantees that favor hub motor maintenance simplicity over axle-mounted drivetrain familiarity.
- Aftermarket Providers:Retrofit kit development targets Indian commercial vehicle diesel chassis compliance pathways.
- Utilities:Distribution grid upgrade planning incorporates hub motor fleet charging load profiles.
OEMs dominate design-in authority. Fleet operators is where purchasing consolidation reshapes supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hub motor supply chains concentrate in Germany, South Korea, and the United States, where Tier 1 suppliers co-locate with battery cell plants and automotive OEM engineering centers. Manufacturing clusters around Stuttgart, Seoul, and Detroit anchor procurement decisions for commercial van and passenger vehicle platforms.
Germany
Stuttgart and Munich development corridors host ZF Friedrichshafen and Bosch engineering centers driving hub motor qualification for EU CO2 fleet targets. The KBA processes type approvals for hub-equipped platforms under accelerated timelines aligned with 2030 interim mandates. Bavaria's automotive supplier density enables rapid prototype-to-production cycles for 800V hub architectures.
South Korea
Hyundai Mobis anchors domestic hub motor production alongside battery supply chain integration for export markets. MFDS certification pathways and national EV subsidy programs accelerate commercial vehicle adoption. The Seoul Capital Area concentrates inverter die foundry capacity serving Stuttgart and Munich development corridors.
United States
Midwestern battery cell plants near Detroit attract localized hub motor production seeking Inflation Reduction Act domestic content bonuses. EPA tailpipe rules and NHTSA fuel economy standards force parallel investments in hub motor qualification. Michigan and Ohio supplier parks integrate silicon-carbide inverter assembly with wheel-integrated motor packaging.
China
Domestic hub motor deployment concentrates in commercial vehicle retrofits and autonomous shuttle pilots under MIIT new energy vehicle mandates. Dual carbon goals and GB standards accelerate thermal management redesigns favoring air-cooled hub configurations. Yangtze River Delta battery cell plants feed hub module assembly for domestic last-mile delivery fleets.
Japan
Nidec Corporation leverages precision motor heritage from Nagoya engineering centers for axial-flux hub designs targeting compact urban vehicles. METI technology roadmaps prioritize torque density improvements in pancake-form motors. Kansai and Chubu regions concentrate rare-earth magnet processing partnerships reducing NdFeB supply volatility.
Automotive EV HUB Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying motor cores and inverter dies. The vendor base organizes around three archetypes: diversified automotive suppliers with chassis system portfolios, pure-play hub motor specialists with axial-flux IP, and precision motor manufacturers extending into wheel-integrated packaging. Competitive moves concentrate on silicon-carbide inverter qualification and functional safety certification acceleration.
Within the diversified automotive supplier tier, Robert Bosch GmbH and ZF Friedrichshafen AG occupy positions spanning power electronics and integrated chassis systems. Nidec Corporation represents the precision motor archetype extending axial-flux heritage into hub configurations. Hyundai Mobis anchors the integrated platform approach through domestic battery supply chain coordination.
| Leading Market Players |
|---|
| Nidec Corporation |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Magna International Inc. |
| Protean Electric |
| Elaphe Propulsion Technologies |
| Hyundai Mobis |
| Bonfiglioli Riduttori S.p.A. |
| YASA Limited |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in South Korean inverter foundries is compressing contract pricing for silicon-carbide die supply, forcing Tier 1 suppliers to renegotiate motor-inverter module terms while OEMs demand fixed-price multi-year commitments for hub motor platforms.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across hub motor procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified systems with full thermal integration from basic air-cooled configurations and retrofit-grade kits. Price differentiation stems from functional safety certification grade and volume scale commitments above 10,000 units annually. Cost compression in standard-tier hub modules is intensifying because silicon-carbide MOSFET supply is expanding faster than 800V platform adoption. Fleet operators exhibit highest price sensitivity, while premium passenger OEMs prioritize NVH performance margins over unit cost.
Supply Chain Analysis
South Korean foundries and German power electronics specialists hold the dominant contract-manufacturing capacity for wheel-integrated inverter assembly. Geographic supply concentration centers on Germany, South Korea, and the United States, with emerging module assembly in China for domestic commercial vehicle retrofits. The supply chain draws from rare-earth magnet processing, silicon-carbide substrate supply, and precision motor lamination steel. Single-source vulnerability in NdFeB magnet refining creates qualification risks for hub motor programs. Distribution runs through Tier 1 platform integrators delivering complete motor-inverter-brake assemblies to OEM vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from centralized 800V axle-mounted drivetrains that are closing the cost gap as silicon-carbide economics mature, requiring defensive repositioning around integrated chassis system value.
For Market Incumbents: Harden motor control firmware IP through accelerated ASIL-D certification timelines and captive supply of silicon-carbide inverter dies via foundry partnerships in South Korea. Centralized drivetrain suppliers are encroaching on commercial van segments with simplified thermal management. Backward integration into rare-earth magnet recycling reduces NdFeB supply volatility exposure. For New Entrants and Emerging Players: Pursue Indian commercial vehicle retrofit kits as the most penetrable white-space segment, where axle-load enforcement and emissions compliance create urgent demand without incumbent platform lock-in. Target autonomous shuttle corner module contracts through independent wheel control demonstrations in geofenced urban deployments. Partner with battery cell plants near Midwestern manufacturing corridors to qualify for domestic content incentives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hub motor specialists with fleet operator service contracts spanning predictive maintenance and over-the-air firmware updates. Long-term viability favors platform integrators with silicon-carbide inverter qualification and functional safety certification acceleration capabilities. Watch for inflection in fleet operator procurement consolidation around single-part-number hub module specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Inverter Qualification | Enables air-cooled hub designs that collapse thermal management costs for commercial van platforms. |
| Functional Safety Certification Acceleration | Compresses ISO 26262 ASIL-D timelines to match centralized drivetrain development cycles. |
| Rare-Earth Magnet Supply Partnership | Secures NdFeB processing capacity outside Chinese refining infrastructure for qualification stability. |
| Fleet Telematics Integration | Delivers predictive maintenance revenue streams through real-time motor health monitoring across distributed wheel units. |
| Autonomous Shuttle Corner Module Development | Captures precision maneuvering demand from geofenced urban mobility deployments requiring independent wheel control. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator maintenance directors, and silicon-carbide foundry planning officers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and customs records for rare-earth magnet trade flows. Bottom-up unit economics for hub motor content per vehicle were triangulated against top-down market sizing from fleet procurement contract aggregation.
Calibration against historical platform adoption curves and regulatory mandate timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from S-curve penetration modeling applied to fleet replacement cycles and passenger vehicle platform refresh timelines. Silicon-carbide cost decline trajectories and battery cell plant capacity buildout schedules served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in battery raw material costs, semiconductor capital expenditure cycles, or trade policy on rare-earth processing would shift the trajectory. Forecasts reflect assumptions around regulatory mandate enforcement timelines and fleet electrification commitment durability. Quarterly review of fleet operator procurement contract announcements and KBA type approval processing rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Lawn Mower Battery Market
Electric Vehicles
Asia-Pacific Electric Bus Battery Pack Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Europe Wireless Electric Vehicle Charging Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Electric Vehicle Battery on Demand Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Electric Vehicle High-Voltage DC-DC Converter Market
Electric Vehicles
Belgium E-Bike Market