
 Lithium Battery Electric Scooters Market | 2026-2036
Lithium Battery Electric Scooters Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Electric Scooters Market Insights
The premium-commodity split is repositioning around battery chemistry and connected features rather than motor power alone. Yadea Group Holdings Ltd. leverages its integrated battery supply chain to dominate mass-market pricing in China. NIU Technologies differentiates through IoT-enabled fleet management tools that sustain recurring software revenue. Segway-Ninebot competes on modular platform architectures that anchor its B2B shared mobility contracts.
Lithium battery electric scooters are two-wheeled personal mobility devices powered by rechargeable lithium-ion or lithium-iron-phosphate battery packs, typically operating at 36–72V with energy densities of 150–250 Wh/kg and regenerative braking systems. Their primary purpose is to replace internal-combustion short trips and last-mile connections with zero-emission alternatives. The commuter product type leads absolute volume as daily travel under 15 kilometers shifts away from cars and public transit. Smart connectivity features represent the fastest-expanding margin pool, with over-the-air updates and geofencing commanding pricing premiums. The 500W power rating segment occupies the sweet spot between regulatory thresholds and practical hill-climbing capability across European and Asian markets.
China's MIIT enforces GB/T standards that dictate battery safety testing and vehicle-connectivity protocols, directly filtering which manufacturers gain domestic homologation. The EU's F-Gas Regulation and Machinery Directive shape import compliance costs and technical file requirements for scooters entering European distribution. India's BIS certification and PLI scheme for advanced chemistry cell manufacturing are redirecting supply chain investment toward localized production. Stakeholders must monitor how subsidy phase-out timelines in major consumption markets reshape volume forecasts and capital deployment priorities.
Market Dynamics
Solid-state battery chemistry is compressing recharge cycles and extending thermal stability windows, forcing incumbent manufacturers to retool cell assembly lines or cede range benchmarks to chemistry-first entrants.
Growth Catalysts
- Urban congestion pricing:London's ULEZ and Singapore's ERP 2.0 schemes impose daily charges on combustion vehicles entering central districts, redirecting commuter spend toward electric two-wheelers.
- GB/T 36672 battery safety standards:China's MIIT mandates nail-penetration and thermal-runaway containment testing that filters out low-cost competitors and consolidates homologated supplier lists.
- Lithium-iron-phosphate cell cost curves:Cathode material processing improvements at Hunan and Hubei refining clusters are compressing pack-level costs for 48V commuter configurations.
Market Restraints
- Cobalt and nickel price volatility:DRC mining disruptions and Indonesian export licensing shifts transmit directly to NMC cell pricing, squeezing margin on performance-oriented 72V packs.
- Single-country cell supply concentration:Over 70 percent of cylindrical 21700 capacity sits in Fujian and Jiangsu provinces, creating geographic chokepoints for European and North American assemblers.
- Energy density ceiling in LFP chemistry:The 160-180 Wh/kg practical limit constrains range extension in sub-25kg chassis designs, forcing trade-offs between portability and daily commute coverage.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:The 18,100 crore rupee production-linked incentive is redirecting cathode and electrolyte investment toward Gujarat and Tamil Nadu manufacturing corridors.
- Battery-swapping infrastructure for delivery fleets:Last-mile logistics operators in Jakarta and Ho Chi Minh City are piloting hot-swappable 48V packs that eliminate dwell-time penalties.
- EU Battery Regulation due diligence mandates:Carbon footprint disclosure and recycled content thresholds create first-mover advantage for manufacturers with closed-loop material recovery systems.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell thermal management and solid-electrolyte interface optimization require specialized skill sets concentrated in Shenzhen and Seoul research clusters.
- Homologation timeline compression:Parallel certification tracks for EU Machinery Directive, US UL 2272, and India BIS AIS-156 extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Electric Scooters Market |
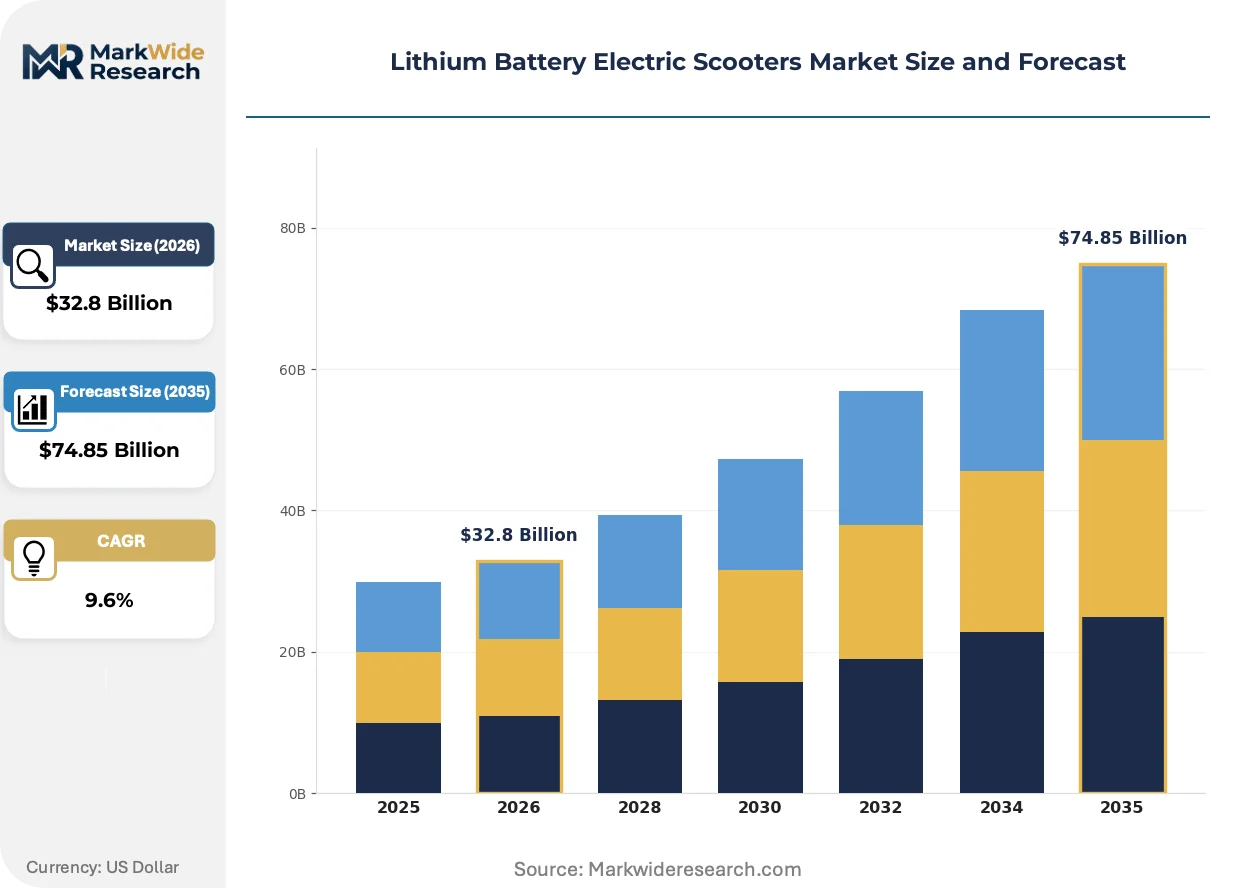
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $74.85 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Kick-Style, Off-Road, Commuter Power Rating: 250W, 500W, 750W, 1000W End User: Students, Urban Commuters, Delivery Personnel, Tourists Feature: Smart Connectivity, Anti-Theft, Adjustable Speed, LED Display |
| Companies Covered | Yadea Group Holdings Ltd., NIU Technologies, Segway-Ninebot, Gogoro Inc., Ola Electric, Ather Energy, Bajaj Auto Ltd., TVS Motor Company, BMW Motorrad International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Electric Scooters Market Trends and Innovations
Platform architectures are fragmenting into interchangeable subsystems that decouple battery, motor, and controller lifecycles, enabling upgrade pathways that resist full-vehicle obsolescence.
Cell-to-pack structural battery designs are eliminating module housings and cooling redundancies. Tier-one suppliers in Ningbo and Dongguan are adopting these architectures for 2026 model-year commuter lines. The approach is modularizing repair and refurbishment economics by allowing independent replacement of degraded cell arrays rather than full pack swaps.
The EU Battery Regulation's digital product passport requirements mandate full supply chain traceability from mining to end-of-life. Assemblers must integrate blockchain-verified material provenance into technical files by 2027. Premium commuter segments in Germany and the Netherlands are responding earliest, using passport compliance as a retail differentiation mechanism.
Fleet operators are unbundling vehicle ownership from energy and maintenance contracts. Shared mobility providers in Barcelona and Milan now procure scooters as capital assets while outsourcing battery health monitoring and predictive component replacement to third-party service platforms. This shift concentrates procurement authority with sustainability-certified fleet managers and compresses direct-to-consumer channel volumes in dense urban cores.
Lithium Battery Electric Scooters Market Segmentation
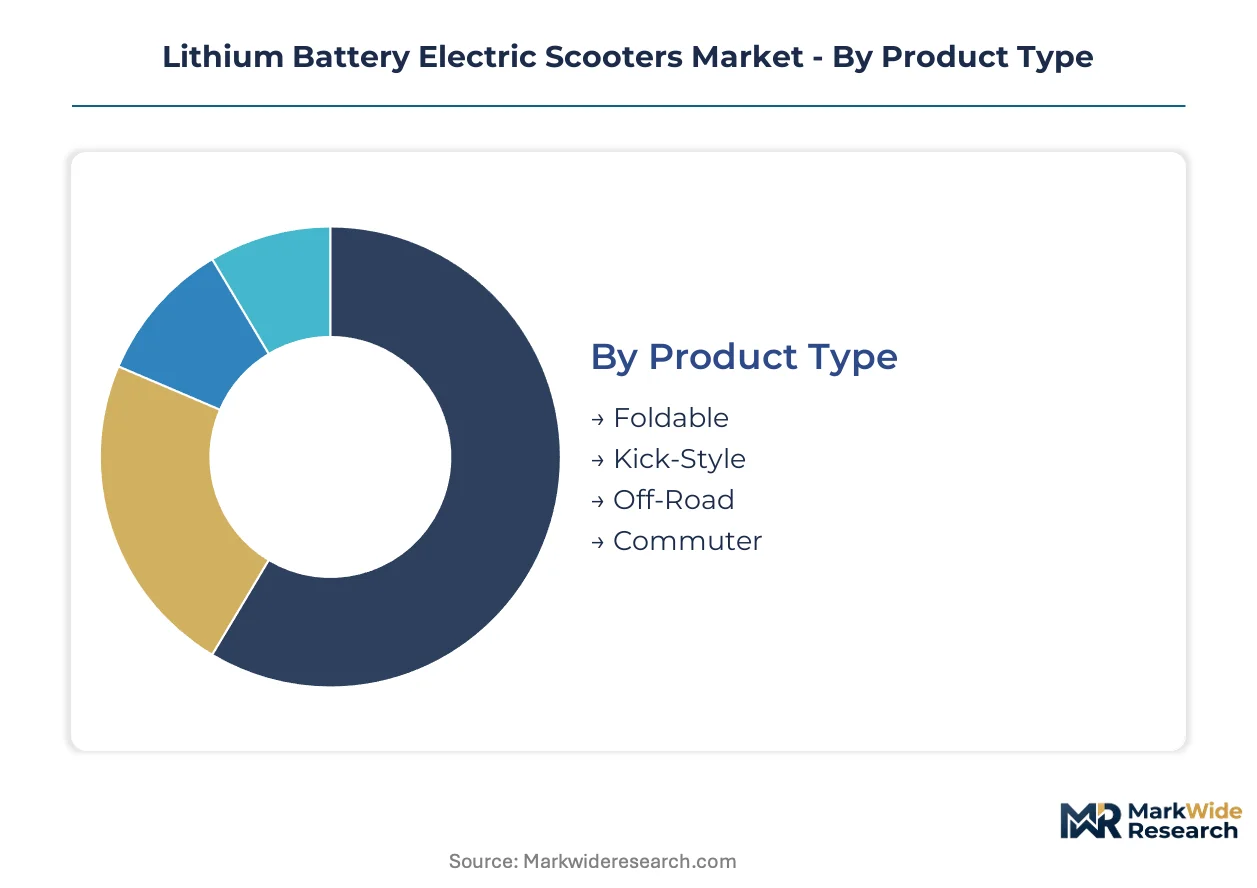
Segment boundaries in this market trace manufacturing capability clusters rather than consumer preference alone. Battery pack form factors and motor controller specifications create natural technical partitions that align with distinct pricing tiers and regulatory thresholds.
Product Type:
Frame architecture and wheel diameter specifications concentrate production in Dongguan and Wuxi manufacturing corridors, where tooling investments favor particular chassis formats.
- Commuter:Step-through frames with 10-inch pneumatic tires and integrated lighting systems dominate absolute volume. Demand clusters in Chinese megacities and European capitals where daily trips under 15 kilometers displace public transit segments. GB/T 36672 certification requirements filter out non-compliant imports, consolidating homologated supplier lists around Shenzhen and Changzhou producers.
- Foldable:Hinge mechanisms and reduced wheelbases sacrifice ride stability for trunk compatibility and office storage. Adoption concentrates among multimodal commuters in Singapore and Berlin who combine scooter segments with rail connections. Weight targets below 14 kilograms constrain battery capacity, forcing trade-offs between range and portability that favor 36V LFP configurations.
- Kick-Style:Standing-deck designs with minimal suspension target price-sensitive youth segments in Indian and Southeast Asian markets.
- Off-Road:Dual-motor configurations and knobby tires address recreational trails and rural terrain in Australia and the western United States.
Commuter absorbs the bulk of installed capacity; Foldable is expanding most quickly.
Power Rating:
Regulatory velocity caps in the EU, China, and India create discrete power tiers that manufacturers align with controller firmware limits rather than hardware differentiation alone.
- 500W:Single-hub motors at this rating balance hill-climbing torque with regulatory compliance across European markets. Production concentrates in Ningbo and Suzhou facilities supplying both domestic Chinese consumption and export assembly. The tier captures fleet procurement volumes from Barcelona and Milan shared-mobility operators who prioritize reliability over acceleration.
- 250W:Pedal-assist compatibility and 25 km/h speed limits satisfy EU L1e-A classification without type-approval costs. German and Dutch insurers mandate this rating for sidewalk-accessible policies, concentrating demand in Benelux and Scandinavian markets. Controller firmware restrictions rather than motor winding differences typically distinguish 250W from higher-rated hardware.
- 750W:North American markets permit higher power without motorcycle licensing, attracting recreational users in California and Texas.
- 1000W:Dual-motor configurations target performance enthusiasts and delivery fleets requiring loaded hill performance.
500W captures the dominant share of production value; 250W shows the steepest expansion trajectory in regulatory-aligned European markets.
End User:
Purchase authority and total cost of ownership calculations fragment demand across institutional procurement, individual ownership, and gig-economy platform subsidies.
- Urban Commuters:Daily travel patterns under 15 kilometers drive replacement of car ownership and public transit subscriptions. Demand concentrates in London, Paris, and Tokyo where congestion pricing and parking scarcity elevate scooter economics. Fleet-as-a-service models from Berlin and Amsterdam operators now capture this segment through monthly subscriptions rather than outright purchase.
- Delivery Personnel:Last-mile logistics platforms in Jakarta, Ho Chi Minh City, and São Paulo deploy scooters with hot-swappable battery configurations. High daily mileage and rough usage patterns prioritize durability over aesthetics, favoring steel-frame designs from Indian and Indonesian assemblers. Platform subsidies and leasing arrangements concentrate procurement authority with fleet managers rather than individual riders.
- Students:Campus mobility programs at North American and Australian universities favor shared fleets over individual ownership.
- Tourists:Rental kiosks in Barcelona, Rome, and Kyoto serve short-duration visitors with simplified interfaces and deposit-free payment.
Urban Commuters represent the largest addressable base; Delivery Personnel demonstrates the most rapid volume scaling through platform-mediated procurement.
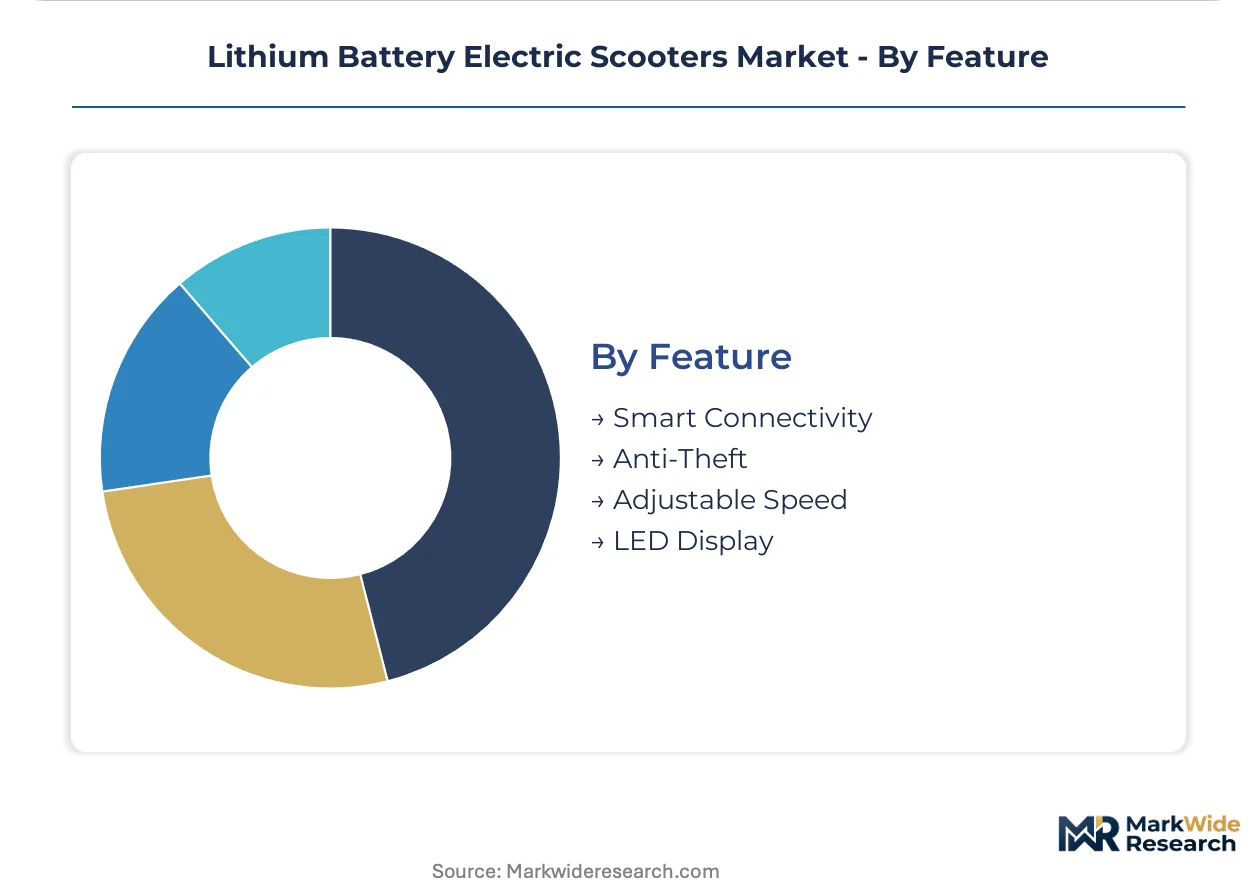
Feature:
Software-enabled differentiation commands margin premiums that hardware commoditization cannot sustain, redirecting R&D investment toward IoT stacks and predictive maintenance algorithms.
- Smart Connectivity:GPS tracking, over-the-air firmware updates, and ride-data analytics transform scooters into connected assets. Premium commuter segments in Germany and the Netherlands respond earliest, using passport-compliant traceability as retail differentiation. Subscription revenue from fleet management tools sustains recurring margins that resist hardware price erosion.
- Anti-Theft:Geofencing, remote immobilization, and biometric locking address urban theft rates that erode total cost of ownership calculations. Integration with municipal parking infrastructure in Singapore and Dubai requires certified communication protocols that filter out uncertified hardware.
- Adjustable Speed:Firmware-limited profiles satisfy multi-jurisdictional regulatory compliance without hardware variation.
- LED Display:Battery state-of-charge precision and navigation integration address range anxiety in markets with sparse charging infrastructure.
Smart Connectivity commands the highest attach rates in premium tiers; Anti-Theft is climbing fastest as urban theft rates reshape ownership economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the lithium battery electric scooter ecosystem, with the Guangdong manufacturing corridor housing the densest concentration of cell assembly lines and vehicle integration facilities worldwide.
China
Domestic consumption absorbs over half of global production volume, with Changzhou and Wuxi tooling corridors specializing in commuter-grade chassis assembly. MIIT enforces GB/T 36672 battery safety standards that filter non-compliant imports and consolidate homologated supplier lists around Shenzhen and Dongguan producers. The Yangtze River Delta cluster is retooling for solid-state cell pilot production by 2026.
Germany
Congestion pricing in Berlin and Munich redirects commuter spend toward electric two-wheelers, with fleet-as-a-service operators capturing urban mobility budgets through monthly subscriptions. The EU Machinery Directive and F-Gas Regulation shape import compliance costs and technical file requirements for scooters entering European distribution. Baden-Württemberg engineering firms supply motor controller firmware to Ningbo assemblers.
India
Last-mile logistics platforms in Bengaluru and Mumbai deploy scooters with hot-swappable battery configurations, prioritizing durability over aesthetics for high daily mileage operations. The PLI scheme for advanced chemistry cells redirects cathode and electrolyte investment toward Gujarat and Tamil Nadu manufacturing corridors. BIS certification requirements extend product launch timelines for imported packs.
United States
Recreational demand in California and Texas favors 750W configurations that North American regulations permit without motorcycle licensing. NHTSA guidelines and state-level helmet mandates fragment compliance requirements across jurisdictions. Austin and Los Angeles host pilot programs for battery-swapping infrastructure targeting delivery fleet operators.
Indonesia
Platform-mediated procurement by Jakarta and Ho Chi Minh City logistics operators drives rapid volume scaling through leasing arrangements that concentrate authority with fleet managers. The country's national standards body mandates thermal-runaway containment testing that filters low-cost competitors. Jababeka industrial estate outside Jakarta is attracting cell assembly joint ventures with Chinese partners.
Lithium Battery Electric Scooters Market Competitive Landscape
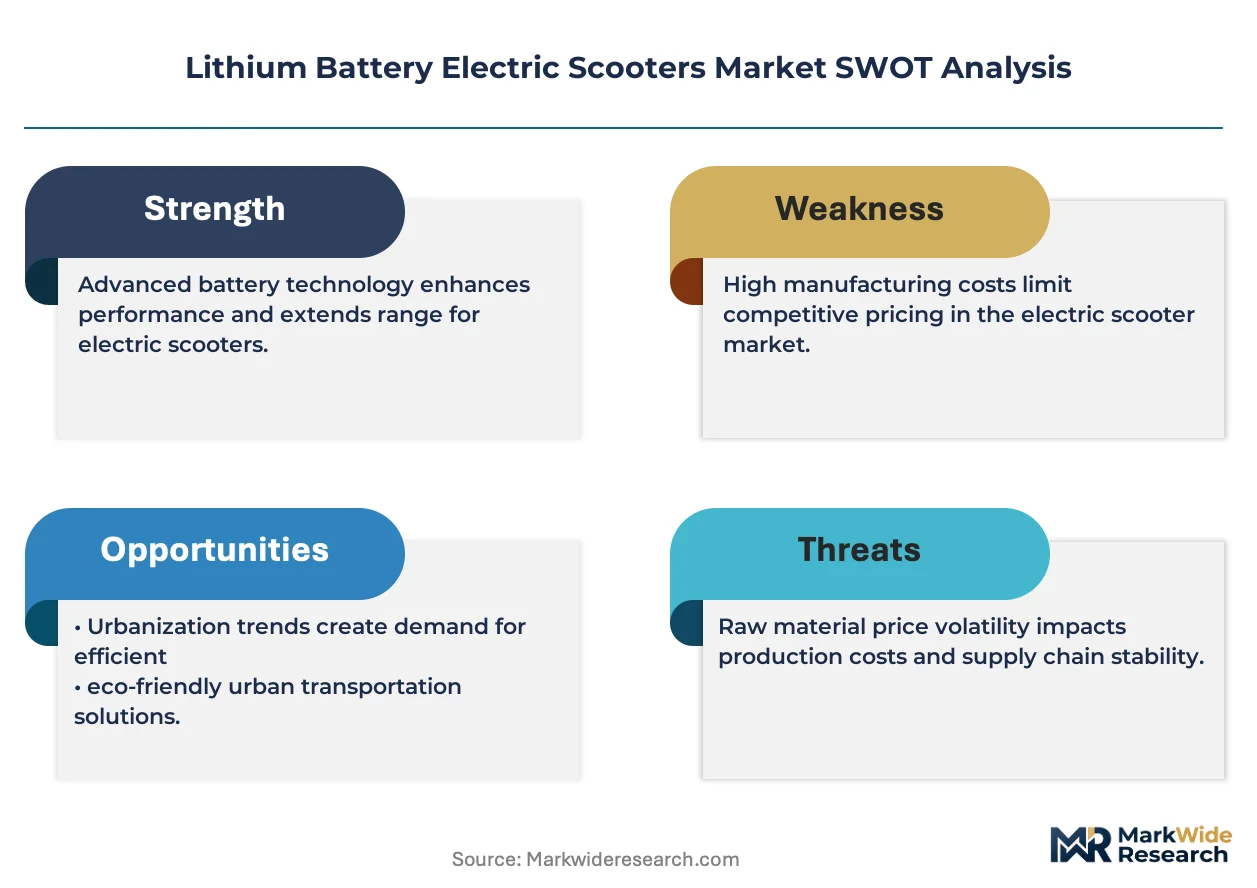
Premium-margin players sit above commodity-margin players across battery chemistry sophistication and connected feature depth rather than motor power alone. The vendor base arranges into three tiers: integrated battery producers commanding mass-market pricing, IoT-enabled specialists capturing recurring software revenue, and modular platform architects anchoring B2B shared mobility contracts. Consolidation pressures concentrate among chemistry-first entrants retooling for solid-state production and incumbent assemblers defending range benchmarks. Competitive moves center on backward integration into cathode material processing and strategic partnerships for fleet management software licensing.
Within the integrated supply chain tier, Yadea Group Holdings Ltd. and NIU Technologies occupy positions that exemplify divergent margin strategies—one leveraging captive battery production for cost compression, the other monetizing connected asset data through subscription tools. Segway-Ninebot sits within the modular platform archetype, with architectures designed for interchangeability that reduce full-vehicle obsolescence. Among India-based specialists, Ather Energy and Ola Electric represent the domestic challenger model targeting fleet procurement authority through localized manufacturing incentives.
| Leading Market Players |
|---|
| Yadea Group Holdings Ltd. |
| NIU Technologies |
| Segway-Ninebot |
| Gogoro Inc. |
| Ola Electric |
| Ather Energy |
| Bajaj Auto Ltd. |
| TVS Motor Company |
| BMW Motorrad International |
| Others |
Pricing and Supply Chain Analysis
Solid-state battery pilot production retooling across Shenzhen and Dongguan facilities is compressing unit economics for premium-tier packs while simultaneously concentrating cathode material processing authority within Yangtze River Delta refining clusters. This dual transformation is fragmenting pricing power between chemistry-first entrants and incumbent assemblers locked into legacy lithium-ion contract structures.
Pricing Analysis
Subscription-based fleet management pricing anchors value capture for premium commuter segments, with monthly per-vehicle fees tied to uptime guarantees and predictive maintenance throughput. Price differentiation rests on GB/T 36672 certification tier and connected feature depth rather than motor wattage alone. Cost compression in mass-market 48V LFP configurations is intensifying because Hunan cathode refiners are expanding capacity. Delivery fleet operators exhibit highest price sensitivity; German urban commuters with congestion pricing exposure show lowest sensitivity.
Supply Chain Analysis
Electrochemical engineering talent scarcity in Shenzhen and Seoul research clusters is constraining solid-state electrolyte interface optimization throughput for tier-one suppliers. Cell assembly draws from cylindrical 21700 capacity concentrated in Fujian and Jiangsu provinces, plus emerging Tamil Nadu corridors under India's PLI scheme. Raw material dependencies center on DRC cobalt, Indonesian nickel, and Chilean lithium carbonate. Single-source vulnerability runs through Chinese cylindrical cell concentration. Distribution runs through OEM direct sales to fleet operators and third-party e-commerce platforms for individual consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around battery chemistry sophistication and connected platform scale, with GB/T 36672 certification mandates and solid-state R&D capital requirements forcing sub-scale assemblers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into cathode material processing at Hunan and Hubei refining clusters to defend margin position against chemistry-first entrants. Prioritize captive 21700 cell capacity expansion in Jiangsu to reduce exposure to single-province supply concentration. Lock fleet management software licensing agreements with Barcelona and Milan shared-mobility operators to secure recurring revenue streams that resist hardware commoditization.
For New Entrants and Emerging Players: The 250W-500W price-point gap in European regulatory-aligned markets offers white-space entry with firmware-limited hardware differentiation. Target India's last-mile logistics procurement authority through hot-swappable battery configurations that eliminate delivery dwell-time penalties. Pursue Gujarat manufacturing corridor localization to capture PLI scheme incentives and BIS certification speed-to-market advantages.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier assemblers with GB/T 36672 homologation but lacking solid-state R&D pipelines, as consolidation pressure intensifies. Long-term viability favors integrated battery producers with captive cathode supply or IoT-enabled specialists with recurring software revenue. Watch EU Battery Regulation carbon footprint disclosure compliance as the inflection indicator for premium-tier margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Platform Development | Retooling Shenzhen pilot lines compresses recharge cycles and extends thermal stability windows for premium commuter tiers. |
| Fleet Management Software Licensing | Subscription revenue from Barcelona and Milan operators sustains margins that resist hardware price erosion. |
| GB/T 36672 Certification Investment | MIIT homologation filters non-compliant imports and consolidates supplier lists around Dongguan producers. |
| Cathode Material Backward Integration | Hunan and Hubei refining cluster control reduces exposure to DRC cobalt and Indonesian nickel price volatility. |
| Hot-Swappable Battery Infrastructure | Jakarta and Ho Chi Minh City pilot programs eliminate delivery fleet dwell-time penalties and concentrate procurement authority. |
Research Methodology
Independent corroboration across cell assembly line managers, fleet procurement directors at shared-mobility operators, and MIIT regulatory affairs specialists underwrites the qualitative findings in this study. Primary interviews with OEM platform engineers, aftermarket service heads, and cathode material procurement leads combined with secondary validation from MIIT GB/T standard filings, EU Machinery Directive technical documentation, and India BIS AIS-156 certification records. Bottom-up unit shipment estimates and top-down market value triangulation anchored the analytical framework.
Comparable-period anchoring to historical commuter adoption curves and fleet deployment cycles structured the forecast window across the analysis window. Segmentation dimensions modeled include product type, power rating, end-user archetype, and battery chemistry configuration. CAGRs derived from regression analysis against urban congestion pricing expansion and subsidy phase-out timelines. Solid-state cell pilot production schedules and PLI scheme investment flows served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; commuter-grade volume estimates carry tighter precision than emerging foldable category projections. Forecasts reflect assumptions around GB/T 36672 enforcement consistency, EU Battery Regulation timeline adherence, and cobalt supply stability from DRC mining operations. Material deviation in solid-state electrolyte interface yield rates or India's PLI scheme disbursement velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market