
 Colombia Automotive Engine Oils Market | 2026-2036
Colombia Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Automotive Engine Oils Market Outlook
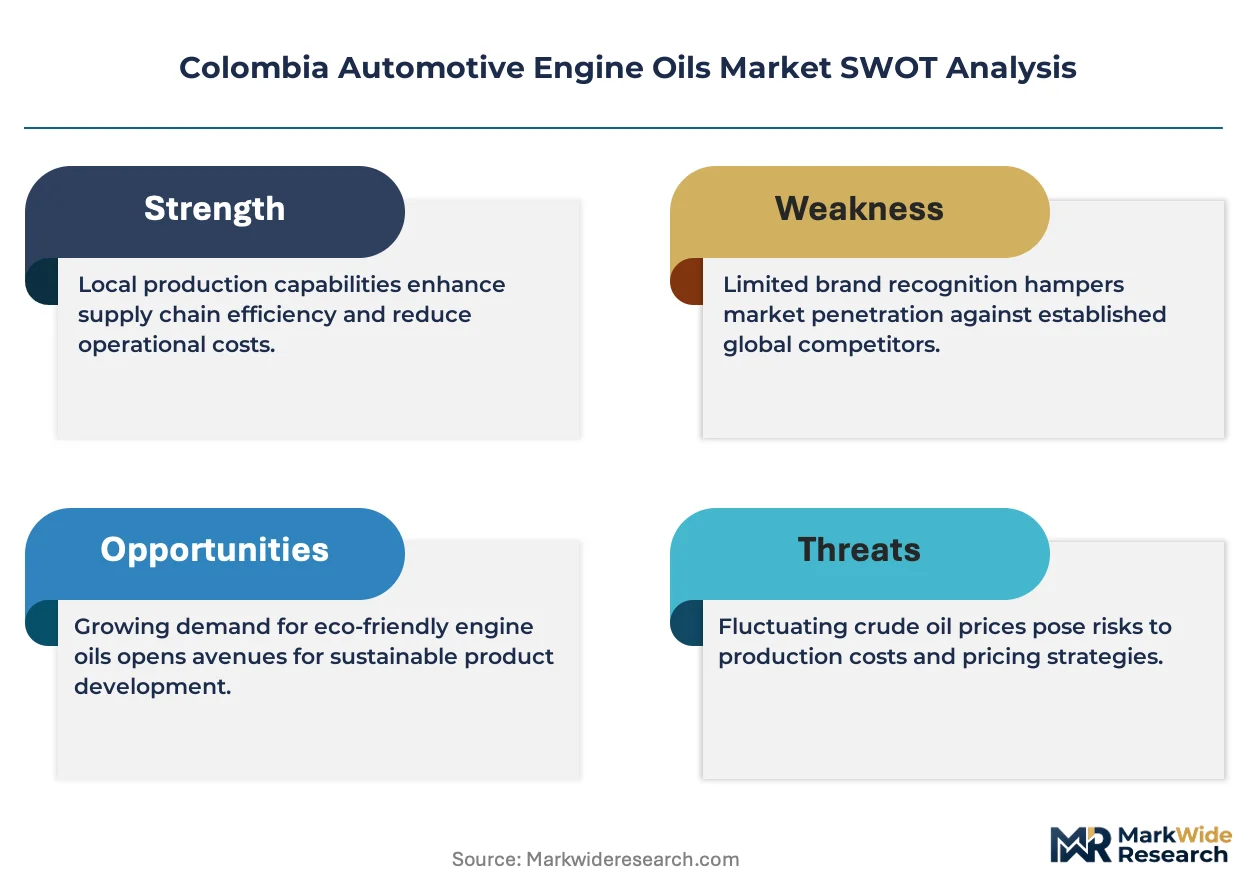
The price-performance gap between premium synthetic formulations and mineral-based commodity lubricants is hardening across Colombian distribution channels. BP Plc (Castrol) leverages its technical service partnerships with authorized dealerships to sustain premium positioning in major urban centers. Terpel anchors downstream volume through its integrated fuel-and-lube retail network spanning Andean highway corridors. Royal Dutch Shell PLC competes on brand recognition among fleet operators managing heavy truck maintenance cycles.
Automotive engine oils are formulated lubricants comprising base oils combined with detergent, dispersant, anti-wear, and viscosity-index improver additives, engineered to reduce friction between moving engine components while dissipating thermal loads and suspending combustion byproducts. Their primary commercial purpose is to extend engine operational life and maintain fuel efficiency across varying temperature and load conditions. Synthetic grades command margin concentration as OEM fill specifications tighten, while mineral oils retain volume dominance in informal service channels serving older vehicle parcs. Semi-synthetic blends capture growth in the passenger car segment where owners seek warranty compliance without full synthetic cost. The heavy truck end user category drives bulk packaging demand through direct procurement relationships with logistics contractors operating along Colombia's primary freight corridors.
Colombia's Ministry of Mines and Energy sets fuel quality benchmarks that cascade into lubricant performance requirements, while the National Institute of Metrology enforces packaging and labeling standards for petroleum-derived products sold through retail and wholesale channels. The Superintendency of Industry and Commerce monitors anti-competitive practices in concentrated distribution networks. Stakeholders must track regulatory alignment between domestic fuel specifications and API/ACEA oil service categories to anticipate reformulation investments and avoid stranded inventory in evolving compliance environments.
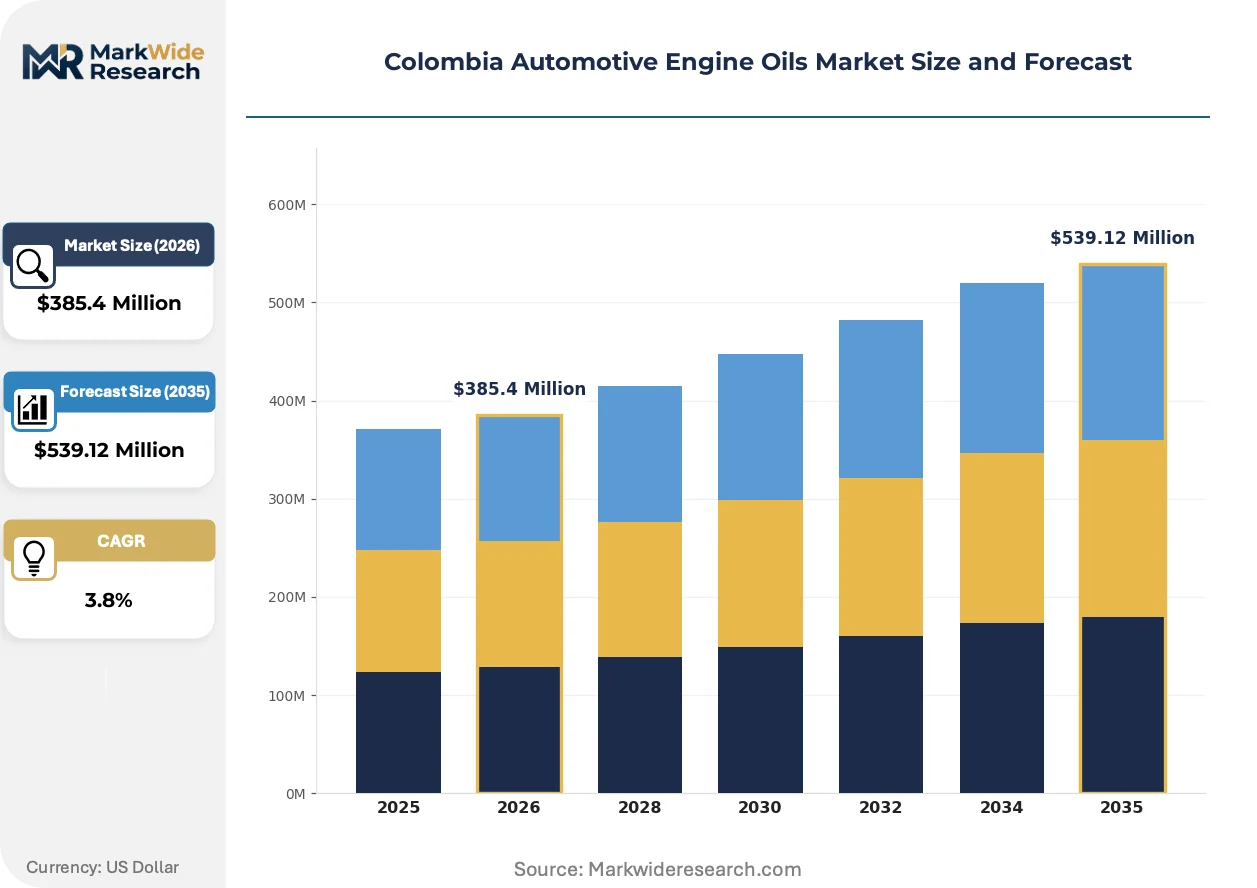
Market Dynamics
Fuel quality mandates from Colombia's Ministry of Mines and Energy are cascading into stricter lubricant performance specifications, forcing reformulation investments across the Andean corridor's supply base.
Growth Catalysts
- API SP/ILSAC GF-6 adoption:Tighter OEM fill specifications are pulling synthetic and semi-synthetic grades into the passenger car segment as owners seek warranty compliance.
- Freight corridor densification:Heavy truck fleets operating between Bogotá and Cali are compressing oil drain intervals, expanding bulk lubricant procurement from logistics contractors.
- Preventive maintenance protocols:Commercial vehicle operators are institutionalizing scheduled service programs that specify branded lubricant procurement over informal channel alternatives.
Market Restraints
- Base oil import dependency:Colombia lacks domestic Group II/III base oil production, exposing blenders to freight cost volatility from US Gulf Coast and Asian supply origins.
- Informal service channel persistence:Unlicensed mechanics in peripheral urban zones continue dispensing unbranded mineral oils, eroding formal market volume capture.
- Extended drain interval technology:Advanced additive packages enabling 15,000+ kilometer service cycles are compressing per-vehicle lubricant consumption volumes.
Strategic Opportunities
- Amazon basin logistics expansion:Emerging freight routes connecting Leticia and Puerto Carreño lack established lube distribution infrastructure, creating first-mover positioning potential.
- Integrated fuel-lube retail:Highway service stations along the Andean corridor can capture incremental margin through co-located oil change bays with captive lubricant sales.
- Used oil collection mandates:Anticipated environmental regulations will require reverse logistics infrastructure, favoring operators with existing collection network capabilities.
Industry Challenges
- Additive chemist scarcity:Formulation expertise for tropical climate viscosity stability remains concentrated among a limited pool of technical specialists in Bogotá and Medellín.
- API certification timeline compression:Accelerated specification cycles are straining testing laboratory capacity, delaying product launches and stranding development investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Automotive Engine Oils Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $539.12 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Semi-synthetic, Bio-based End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy Trucks Distribution Channel: Online, Retail, Wholesalers, Service Stations Packaging Type: Bottles, Drums, Bulk Containers, Pouches |
| Companies Covered | Biomax, BP Plc (Castrol), Terpel, Motul, TotalEnergies, Royal Dutch Shell PLC, Petromil SA, Petrobras, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Automotive Engine Oils Market Strategic Shifts
Synthetic formulation technology is absorbing regulatory pressure and operational stress simultaneously, reshaping how lubricant value is captured across Colombia's divergent service channels.
Low-viscosity synthetic grades engineered for turbocharged direct-injection gasoline engines are absorbing thermal load requirements that mineral bases cannot sustain. Passenger car owners in Bogotá's metropolitan zone are adopting these formulations at pace as OEM warranty terms harden against non-compliant oil use. The technology is absorbing margin compression in the premium segment while compressing mineral oil viability in urban formal channels.
Colombia's Ministry of Mines and Energy is tightening sulfur content ceilings in diesel and gasoline specifications, which indirectly elevates required detergent and dispersant loadings in crankcase lubricants. Blenders must reformulate additive packages to manage elevated combustion acid neutralization demands without exceeding existing viscosity grades. Heavy truck operators along the Cali-Buenaventura corridor face the steepest compliance cost adjustments as their equipment cycles between high-altitude and coastal humidity extremes.
Fleet procurement managers are consolidating lubricant specification authority away from individual driver discretion into centralized maintenance departments. Direct contracting between logistics contractors and blender technical service teams is displacing distributor-mediated purchasing in the heavy commercial segment. This concentration is most visible among refrigerated freight operators serving Bogotá's perishable export consolidation points, where unified oil analysis programs now dictate brand selection across entire vehicle pools.
Colombia Automotive Engine Oils Market Segmentation
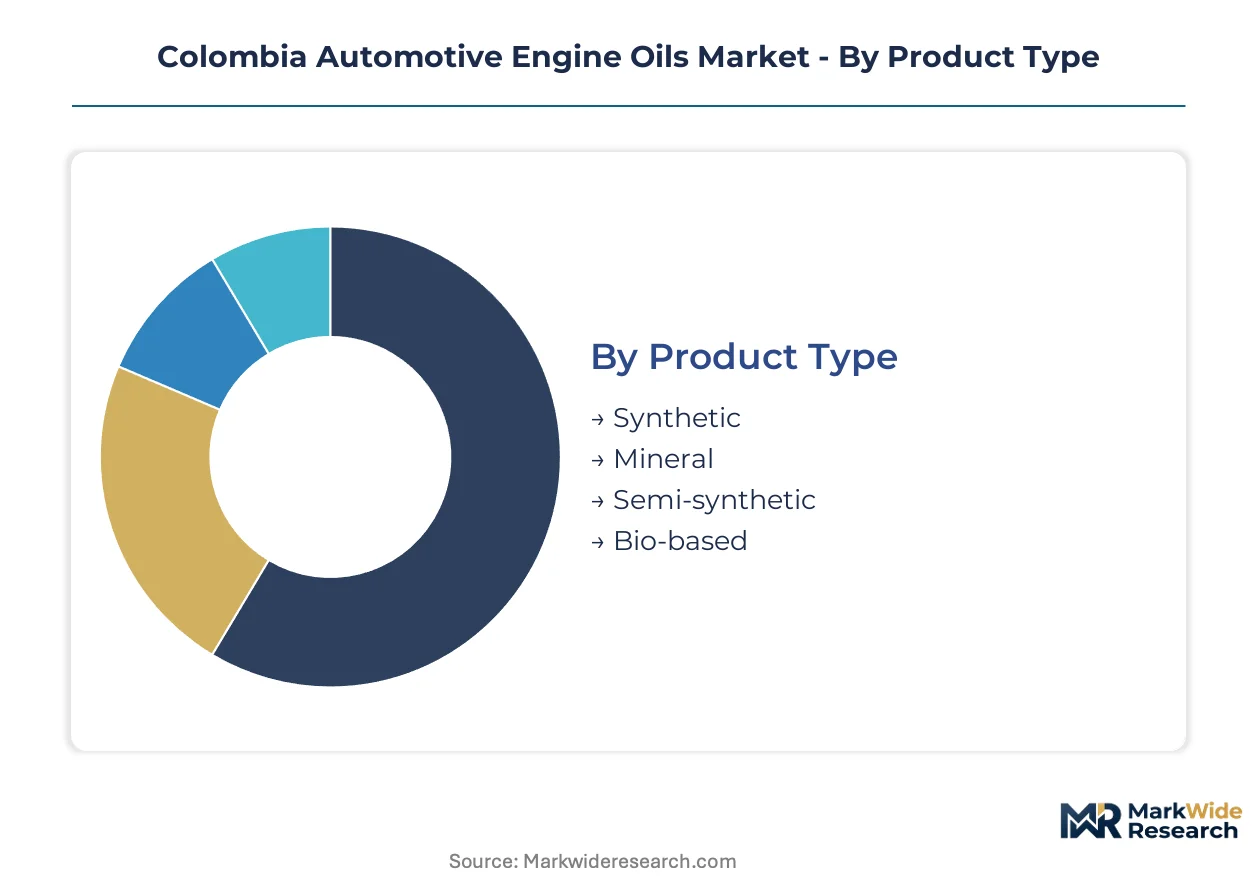
Colombia's automotive engine oils market fragments across formulation chemistry, vehicle duty cycles, and procurement channels. Each segmentation axis reveals distinct margin structures and capital deployment requirements for blenders and distributors operating in the Andean corridor.
Product Type:
Capital intensity varies sharply across base oil categories, with synthetic production requiring specialized blending equipment and additive dosing systems that mineral operations avoid.
- Synthetic:Group III and PAO base stocks combined with high-performance additive packages deliver thermal stability for turbocharged gasoline direct-injection engines. Demand concentrates in Bogotá's metropolitan service network where OEM warranty compliance drives specification authority. The Ministry of Mines and Energy's fuel quality mandates are accelerating reformulation investments toward these grades.
- Mineral:Solvent-refined Group I bases with conventional additive treat rates serve price-sensitive vehicle owners in informal service channels. Volume concentrates in peripheral urban zones and aging vehicle parcs where drain interval extension carries less economic weight.
- Semi-synthetic:Blended formulations capture passenger car owners seeking warranty protection without full synthetic cost.
- Bio-based:Vegetable oil derivatives and ester formulations target environmental compliance positioning in fleet procurement specifications.
Most installed capacity flows through Mineral. Expansion is steepest in Synthetic.
End User:
Vehicle duty cycles determine lubricant stress profiles and procurement decision structures across Colombian operating environments.
- Passenger Cars:Light-duty gasoline engines in urban stop-start traffic drive demand for low-viscosity formulations with thermal management capabilities. Bogotá's altitude and temperature swings stress viscosity stability requirements.
- Commercial Vehicles:Medium-duty diesel fleets operating regional distribution routes specify branded lubricants through centralized maintenance programs.
- Two-Wheelers:Motorcycle parcs in secondary cities and rural corridors sustain mineral oil volume through low-cost service channels.
- Heavy Trucks:Long-haul freight operators along the Cali-Buenaventura and Bogotá-Medellín corridors compress drain intervals and procure bulk lubricants through direct blender contracts. Thermal loading from high-altitude descents and coastal humidity exposure drives additive package sophistication.
Volume concentrates in Passenger Cars. Margin expansion is strongest in Heavy Trucks.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics for lubricant marketers.
- Online:E-commerce platforms capture DIY maintenance segments in metropolitan zones with delivery logistics for packaged lubricants.
- Retail:Auto parts stores and hypermarkets serve owner-operators with immediate availability requirements.
- Wholesalers:Distributor networks extend reach into secondary cities and independent service garages with credit terms and technical support.
- Service Stations:Integrated fuel-and-lube retail along Andean highway corridors captures fleet traffic with co-located oil change infrastructure. Terpel's network exemplifies this channel's volume concentration.
Service Stations capture the highest throughput velocity. Online is gaining share fastest in urban DIY segments.
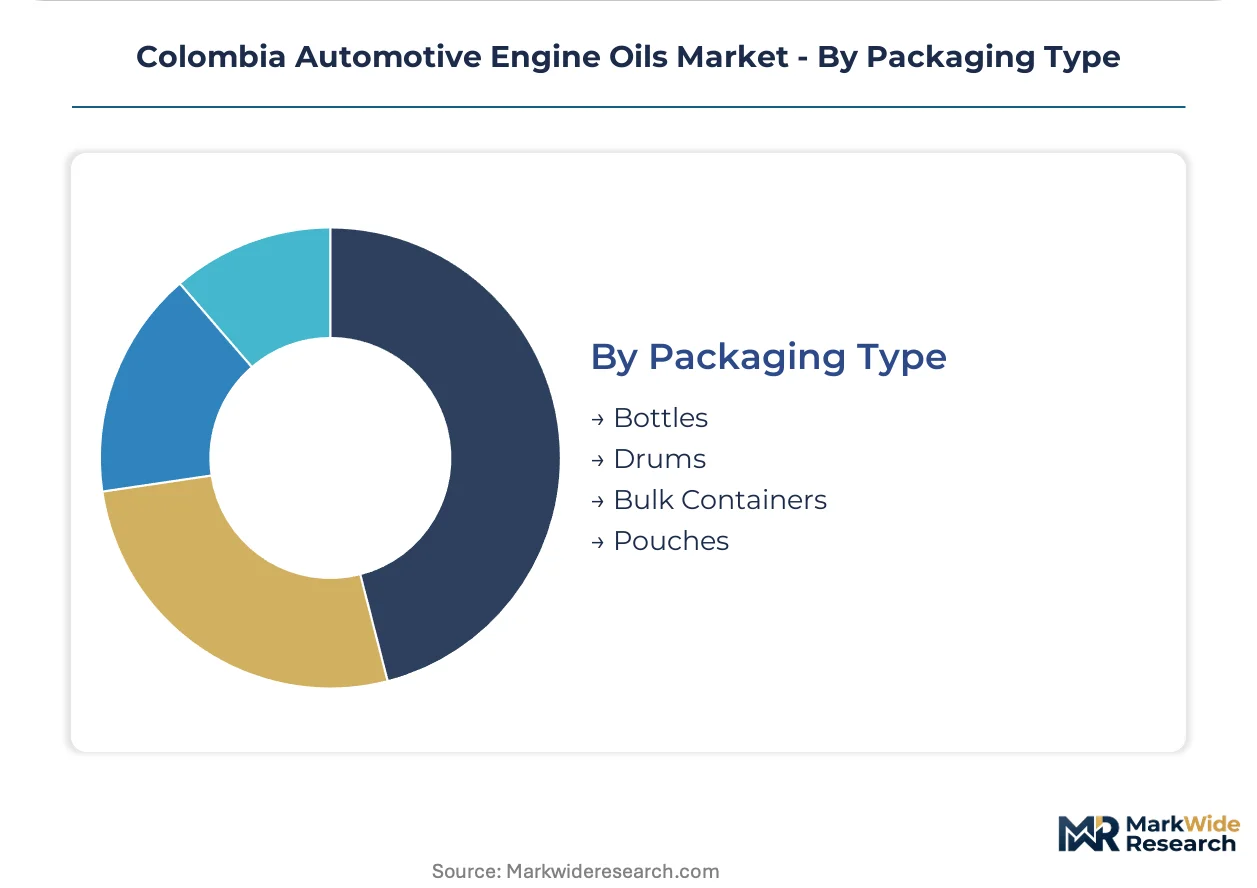
Packaging Type:
Packaging format aligns with procurement scale and inventory turnover requirements across customer segments.
- Bottles:One-liter and four-liter containers serve passenger car owners in retail and service station channels with manageable handling weights.
- Drums:Two-hundred-liter steel and plastic drums supply fleet maintenance bays and independent garages with intermediate volume requirements.
- Bulk Containers:Intermediate bulk containers and tanker deliveries serve heavy truck operators and logistics contractors with direct-to-facility supply arrangements.
- Pouches:Flexible packaging targets two-wheeler service channels and price-sensitive rural markets with minimal material cost.
Drums represent the most widely deployed format. Bulk Containers are climbing the fastest in fleet direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's lubricant formulation specialists cluster in Bogotá and Medellín, anchoring technical service capacity for the Andean corridor's commercial vehicle fleets.
Bogotá Metropolitan Zone
Passenger car density and OEM dealership concentration drive synthetic grade specification authority. Colombia's Ministry of Mines and Energy enforces fuel quality benchmarks that cascade into lubricant performance requirements. The capital's altitude stress on engine thermal management pulls low-viscosity formulations into warranty-compliant service channels.
Cali Logistics Corridor
Heavy truck fleets operating the Cali-Buenaventura freight route compress oil drain intervals and procure bulk lubricants through direct blender contracts. The Pacific port connection exposes equipment to humidity extremes that stress additive package sophistication. Refrigerated freight operators serving perishable export consolidation points now centralize lubricant procurement authority.
Medellín Industrial Cluster
Antioquia's manufacturing base sustains medium-duty diesel fleet operations with branded lubricant specifications through centralized maintenance programs. The National Institute of Metrology enforces packaging and labeling standards for petroleum-derived products sold through regional distribution networks. Independent service garages in the Aburrá Valley intermediate between formal wholesale channels and price-sensitive owner-operators.
Barranquilla Caribbean Hub
Port logistics and coastal commercial vehicle operations sustain mineral oil volume through informal service channels. The Superintendency of Industry and Commerce monitors anti-competitive practices in concentrated distribution networks. Caribbean climate conditions accelerate oxidation stress on crankcase lubricants, creating reformulation requirements distinct from Andean high-altitude specifications.
Amazon Basin Frontier
Emerging freight routes connecting Leticia and Puerto Carreño lack established lube distribution infrastructure. Anticipated environmental regulations will require reverse logistics infrastructure for used oil collection. First-mover positioning potential exists for operators with existing collection network capabilities extending into isolated riverine transport corridors.
Colombia Automotive Engine Oils Market Competitive Environment
Top-tier vendors anchor premium synthetic formulations, while commodity mineral blenders compete on volume throughput through informal channels. The market exhibits tiered concentration with multinational lubricant majors controlling OEM fill specifications and authorized dealership networks. Two strategic archetypes dominate: integrated fuel-lube retailers leveraging highway corridor presence, and technical service specialists capturing fleet procurement through oil analysis programs. Competitive moves center on co-located oil change infrastructure investment and direct contracting relationships with logistics contractors.
Within the multinational lubricant tier, BP Plc (Castrol) and Royal Dutch Shell PLC represent archetypes of brand-recognition competition for fleet operators. Terpel exemplifies integrated fuel-lube retail dominance through Andean highway corridor networks. Among regional energy conglomerates, Petrobras occupies a position reflecting South American downstream integration. These named entities anchor industry-level commentary on distribution channel strategy without implying specific market share claims.
| Leading Market Players |
|---|
| Biomax |
| BP Plc (Castrol) |
| Terpel |
| Motul |
| TotalEnergies |
| Royal Dutch Shell PLC |
| Petromil SA |
| Petrobras |
| Chevron Corporation |
| Others |
Value Chain & Pricing Dynamics
Colombia's anticipated used oil collection mandates gate both qualified supply and premium-tier pricing access, forcing blenders to embed reverse logistics costs into service bundles while mineral-grade competitors without collection infrastructure face margin compression in formal channels.
Pricing Analysis
The bundled-vs-unbundled service split separates synthetic-grade suppliers offering oil analysis and collection programs from commodity blenders selling unbranded mineral products. Price differentiation hinges on API certification tier and volume procurement scale, with fleet direct contracts commanding standardization premiums over retail single-unit sales. Pricing pressure stems from extended drain interval technology compressing per-vehicle consumption volumes. Owner-operators in informal channels exhibit highest price sensitivity, while refrigerated freight operators centralizing procurement authority show lowest.
Supply Chain Analysis
Local-content-rule absence in base oil production reshapes sourcing, as Colombia's blenders draw from US Gulf Coast Group II/III supply and Asian additive package origins without domestic alternatives. Raw material dependencies center on Group III base stocks, viscosity-index improvers, and detergent-dispersant chemistries. Supply chain risk concentrates in freight cost volatility from distant supply origins. Distribution runs through Terpel's integrated fuel-lube highway network and independent wholesale channels serving secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's automotive engine oils market functions as a regulatory compounder, where the Ministry of Mines and Energy's cascading fuel quality mandates continuously elevate formulation investment requirements and compress non-compliant inventory viability.
For Market Incumbents: Anchor synthetic-grade positioning through API SP certification investments that warranty-compliant OEM dealerships demand, while consolidating informal channel volume through co-located oil change infrastructure at Andean highway service stations. Threat substitution from extended drain interval technology demands additive package R&D concentration in Bogotá's technical cluster. Backward integration into used oil collection networks secures regulatory alignment ahead of anticipated mandates. For New Entrants and Emerging Players: Begin with Amazon basin logistics corridors connecting Leticia and Puerto Carreño, where established distribution infrastructure gaps create first-mover positioning potential for bulk-container fleet supply. The penetrable segment sits among riverine freight operators lacking technical service partnerships. A direct-contracting go-to-market angle with oil analysis program bundling displaces distributor-mediated purchasing. For Investors and Strategic Acquirers: Roll-up economics work for regional blending assets with existing collection network capabilities because environmental compliance layering favors operators with reverse logistics infrastructure already deployed. Long-term viability centers on synthetic-grade transition exposure over mineral-volume dependence. Watch fleet procurement centralization rates at Bogotá perishable export consolidation points as inflection signal for direct-contracting market structure maturity.| Strategic Initiative | Industry Significance |
|---|---|
| API SP Certification Investment | Secures OEM warranty compliance authority in Bogotá's metropolitan dealership network. |
| Used Oil Collection Network Buildout | Positions operators ahead of Ministry of Mines and Energy anticipated environmental mandates. |
| Direct Fleet Contracting Expansion | Displaces distributor mediation among Cali-Buenaventura refrigerated freight operators. |
| Amazon Basin Distribution Infrastructure | Captures emerging Leticia-Puerto Carreño freight routes lacking established lube supply. |
| Co-located Oil Change Bay Investment | Integrates lubricant sales with Terpel's highway service station throughput velocity. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant blending plant managers, fleet procurement directors at logistics contractors, Terpel network operations heads, and API certification laboratory technical leads with secondary validation against Colombian customs trade data, Ministry of Mines and Energy fuel specification bulletins, Superintendency of Industry and Commerce distribution monitoring reports, and National Institute of Metrology packaging standard enforcement records. Bottom-up volume builds across formulation grades and vehicle segments triangulated against top-down market sizing from supply-side capacity assessments.
Comparable-period anchoring tied projection models to historical reference intervals across the analysis window, with segmentation dimensions spanning base oil chemistry tier, vehicle duty cycle classification, procurement channel structure, and regional climate stress profile. CAGRs derived from elasticity-adjusted demand curves incorporating OEM fill specification evolution rates and fleet centralization trends. Industry-specific forecast inputs included API specification adoption timelines and Andean corridor freight density projections.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals by Colombia's Ministry of Mines and Energy, sustained base oil freight cost spikes exceeding historical volatility bands, and accelerated electric vehicle penetration compressing internal combustion engine lubricant demand. Forecasts reflect documented assumptions regarding specification alignment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Camshaft Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Car Active Purge Pump Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Powertrain Testing Market
Powertrain
Automotive Power Steering Pump Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Small Gas Engine Market
Powertrain
Gear Reduction Starter Market
Powertrain
Iridium Spark Plug Market
Powertrain
Yaw Damper Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
Continuously Variable Transmission (CVT) Market