
 Automotive Battery Powered Propulsion System Market | 2026-2036
Automotive Battery Powered Propulsion System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Powered Propulsion System Market Outlook
Battery-as-a-service and subscription-based energy capacity models is recalibrating how automotive customers procure propulsion power. Tesla leverages its proprietary supercharging network and over-the-air software updates to lock in recurring revenue streams alongside hardware sales. BYD Company Ltd. anchors its position through in-house production of lithium iron phosphate cells and integrated power electronics. Contemporary Amperex Technology Co., Limited dominates cylindrical and prismatic cell supply to multiple OEM platforms across three continents.
An automotive battery powered propulsion system integrates electrochemical cells, thermal management hardware, power electronics, and motor drives to convert stored chemical energy into mechanical torque for vehicle traction, typically operating at 400-800 volts in current passenger platforms. The assembly demands precision joining of pouch or prismatic cells into modules, followed by pack-level battery management system integration and validation against UN 38.3 transport safety protocols. Li-ion chemistry currently occupies the majority of installed capacity, though solid-state configurations are attracting development capital as manufacturers target higher energy density with reduced thermal runaway risk. Passenger vehicles sustain the largest revenue pool, while heavy-duty trucks represent the fastest-expanding application segment as fleet operators validate total cost of ownership against diesel equivalents.
The EPA tailpipe emission standards and NHTSA corporate average fuel economy rules in the United States mandate fleet-wide CO2 reductions that effectively require battery-electric powertrain penetration. China's MIIT new energy vehicle credit system and dual carbon goals enforce minimum zero-emission sales ratios for domestic manufacturers. The EU Green Deal and REACH chemical restrictions additionally shape cell material sourcing and end-of-life recycling obligations across European supply chains. Stakeholders must monitor how regulatory credit trading values and raw material qualification requirements alter make-versus-buy decisions for cell manufacturing capacity.
Market Dynamics
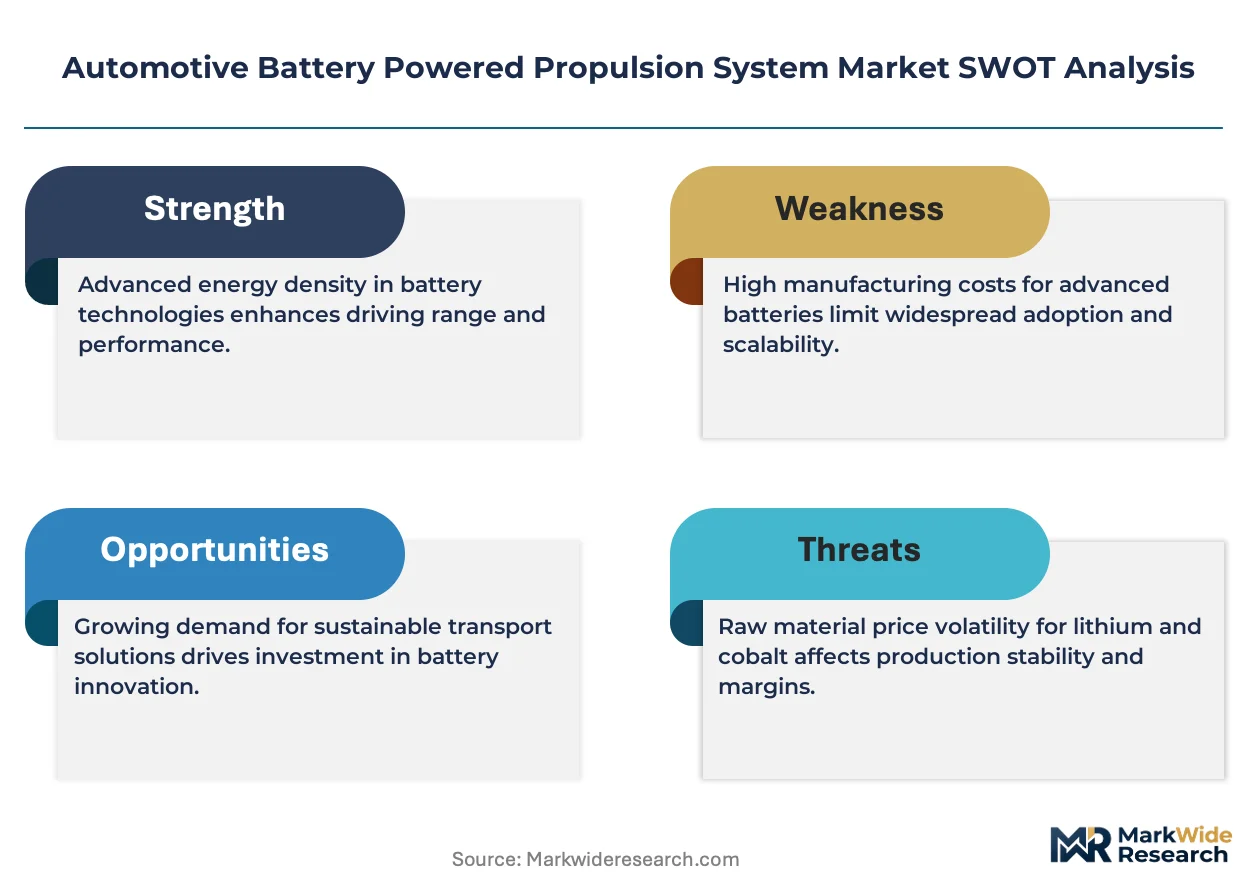
Fleet electrification mandates and solid-state battery maturation are compressing development timelines across automotive propulsion supply chains. Cell chemistry transitions and thermal management standardization are forcing simultaneous capital deployment into manufacturing capacity and recycling infrastructure.
Growth Catalysts
- EPA Fleet Emissions Mandates:US tailpipe regulations enforce CO2 reductions that effectively require battery-electric powertrain penetration across light-duty and medium-duty vehicle categories.
- Commercial Fleet TCO Validation:Heavy-duty trucking operators in North America and Europe are expanding electrified procurement as battery-electric platforms achieve operational parity with diesel equivalents on total cost metrics.
- Jiangsu-Guangdong Cluster Density:China's concentrated cell gigafactory and integrated pack assembly ecosystems supply domestic OEMs and export channels with unmatched manufacturing scale.
Market Restraints
- Lithium Carbonate Volatility:Raw material input costs for cathode active materials fluctuate with mining capacity constraints and processing bottlenecks in South American and Australian supply zones.
- Prismatic Cell Supply Concentration:Cylindrical and prismatic cell output concentrates among a limited set of Asian manufacturers, creating procurement risk for European and North American pack assemblers.
- Solid-State Manufacturing Complexity:Ceramic electrolyte processing and dry electrode coating techniques remain unproven at automotive scale, delaying energy density gains promised by next-generation architectures.
Strategic Opportunities
- Battery-as-a-Service Models:Subscription-based energy capacity procurement is recalibrating how fleet operators and retail customers finance propulsion assets, decoupling hardware from energy access.
- EU F-Gas Thermal Management Tailwind:Refrigerant phase-down regulations are accelerating demand for CO2-based cooling systems and advanced heat pump integration in battery thermal circuits.
- Second-Life Stationary Storage Convergence:Retired automotive packs are finding application in grid-scale energy storage, creating circular revenue streams from end-of-life mobility assets.
Industry Challenges
- UN 38.3 Certification Timelines:Transport safety validation protocols for lithium-ion cell configurations create extended approval cycles that compress product launch windows.
- Power Electronics Integration Complexity:SiC inverter and onboard charger packaging demands specialized thermal interface materials and electromagnetic compatibility engineering that outpaces available talent pools.
- Pack Disassembly Automation:End-of-life recycling obligations under EU REACH and emerging extended producer responsibility frameworks require capital-intensive robotic disassembly lines not yet deployed at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Powered Propulsion System Market |
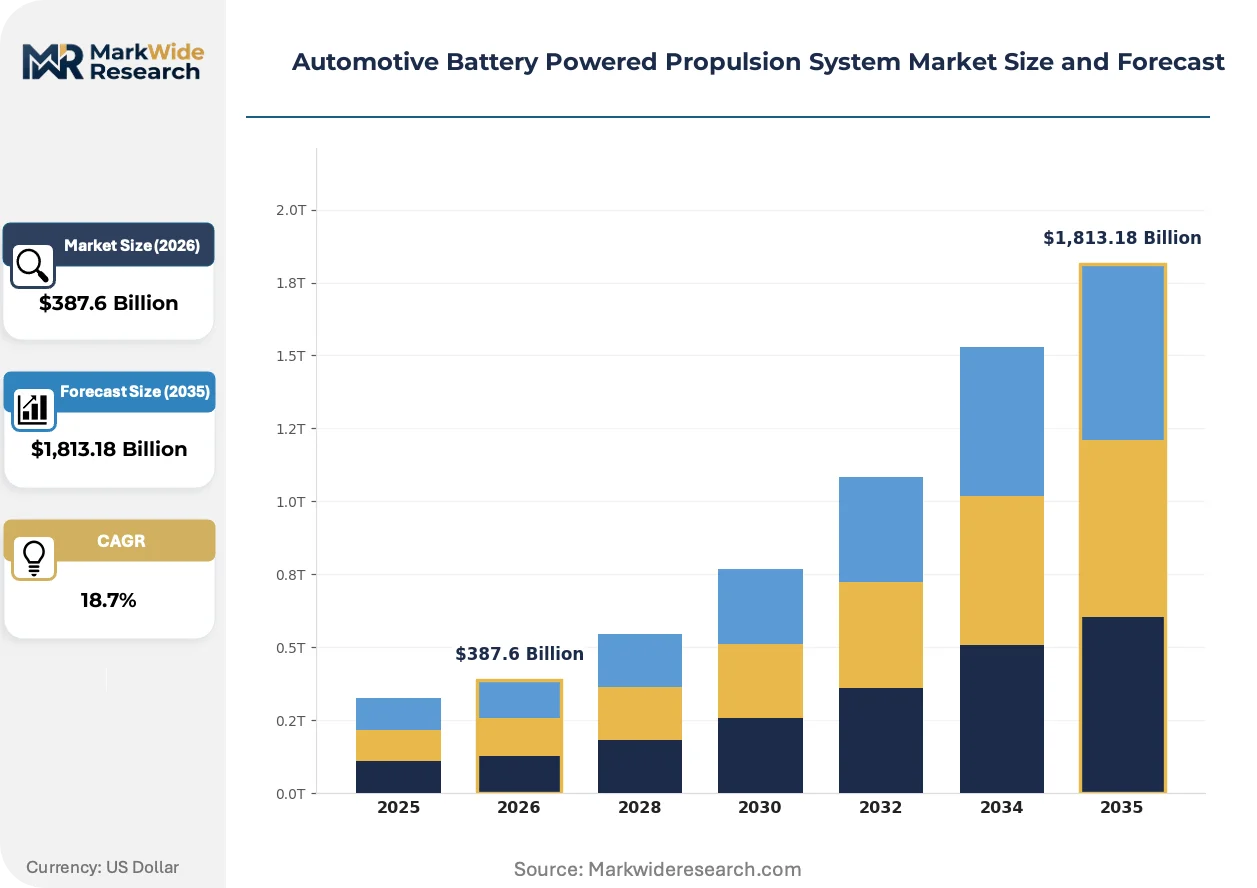
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,813.18 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion, NiMH, Lead-Acid, Solid-State Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Technology: Regenerative Braking, Fast Charging, Wireless Charging, Battery Management System End User: OEMs, Aftermarket Providers, Fleet Operators, Tier-1 Suppliers |
| Companies Covered | Tesla, BYD Company Ltd., Robert Bosch GmbH, Contemporary Amperex Technology Co., Limited, LG Energy Solution, Panasonic Corporation, SAMSUNG SDI, Toyota Motor Corporation, Volkswagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Powered Propulsion System Market Strategic Shifts
Solid-state cell architectures and thermal management refrigerant transitions are restructuring competitive requirements for automotive propulsion suppliers. These shifts demand simultaneous investment in materials science, manufacturing automation, and circular supply chain infrastructure.
Solid-state batteries replace liquid electrolytes with ceramic or sulfide conductors to enable higher energy density and reduced thermal runaway risk. Automotive OEMs are pilot-testing these configurations in premium passenger platforms ahead of mass-market deployment. This technology is electrifying the competitive landscape by rewarding manufacturers with captive solid-state development programs and compressing margins for conventional lithium-ion specialists.
The European Union's F-Gas Regulation mandates phased reduction of hydrofluorocarbon refrigerants in vehicle thermal management systems. This policy is accelerating engineering investment into CO2 heat pumps and dielectric fluid immersion cooling for high-voltage battery packs. Heavy-duty electric trucks operating in Germany and France face the most immediate compliance pressure, driving supplier partnerships with industrial refrigeration specialists.
Fleet operators are unbundling battery asset ownership from vehicle procurement through energy subscription contracts. Commercial buyers in North America are adopting mileage-based battery service agreements that transfer degradation risk to cell suppliers or third-party financiers. This pattern is most visible among last-mile delivery operators validating total cost of ownership models before scaling to long-haul electrification.
Automotive Battery Powered Propulsion System Market Segmentation
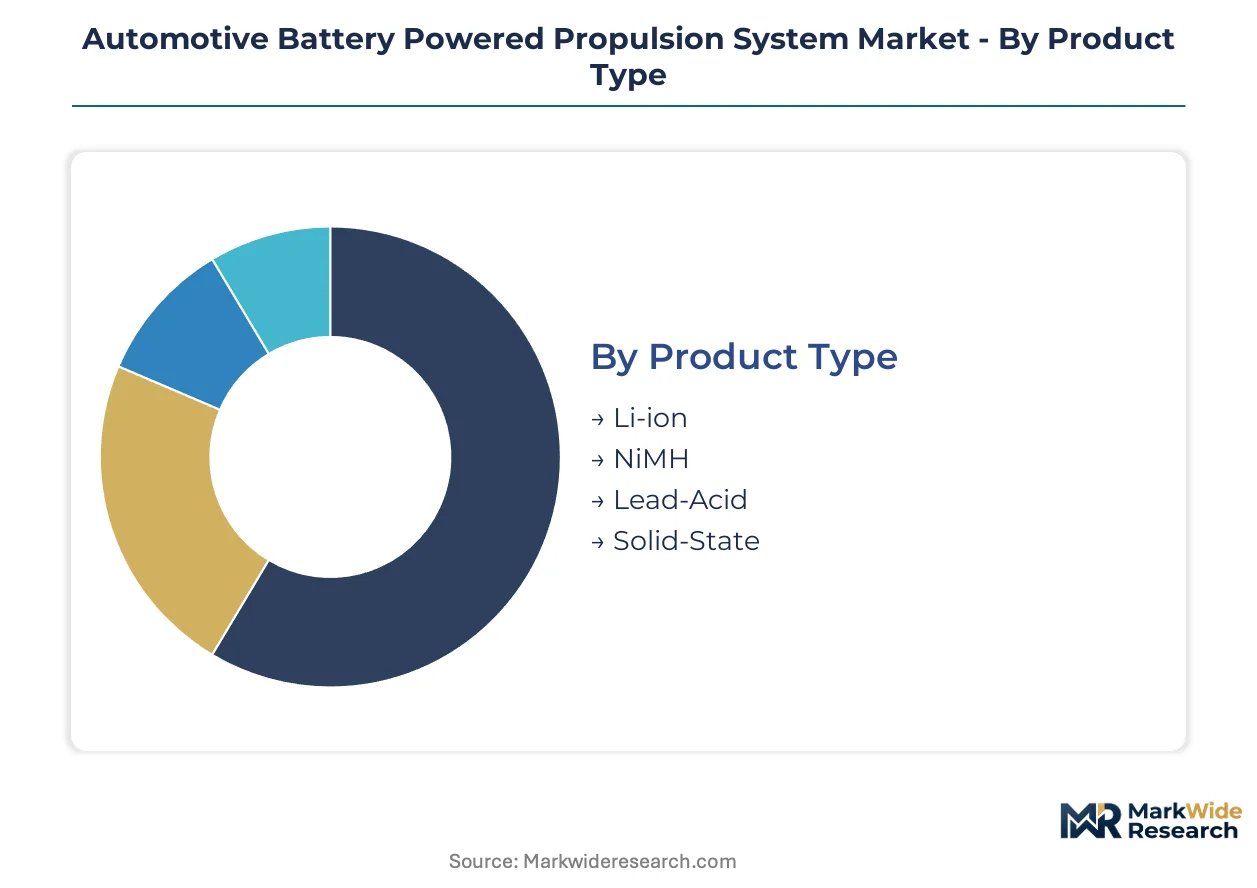
Automotive battery powered propulsion systems fragment across chemistry, vehicle class, and value chain position. Each dimension carries distinct margin profiles and regulatory exposure that shape procurement and investment decisions.
Product Type:
Cell chemistry selection hinges on energy density requirements, thermal stability tolerance, and total cost thresholds across vehicle platforms.
- Li-ion:Lithium-ion configurations dominate current production with nickel-manganese-cobalt and lithium iron phosphate variants offering 250-300 Wh/kg energy density. Demand concentrates in China's Jiangsu province cell gigafactories supplying domestic OEMs and export channels under MIIT new energy vehicle credit pressure.
- Solid-State:Ceramic and sulfide electrolyte architectures promise 400+ Wh/kg density with reduced thermal runaway risk. Pilot production lines in Japan and South Korea target premium passenger platforms as dry electrode coating techniques mature.
- NiMH:Nickel-metal hydride retains position in hybrid-electric transitional applications requiring proven cycle life without complex thermal management.
- Lead-Acid:Lead-acid chemistry persists in auxiliary power and starter functions where cost minimization outweighs energy density priorities.
Volume sits with Li-ion; growth tilts toward Solid-State.
Application:
Vehicle class determines pack sizing, duty cycle intensity, and charging infrastructure integration requirements.
- Passenger Vehicles:Light-duty platforms sustain the largest revenue pool with 400-800 volt architectures becoming standard. European OEMs face EU Green Deal fleet emission mandates that compress diesel phase-out timelines.
- Heavy-Duty Trucks:Battery-electric long-haul configurations are expanding most quickly as North American fleet operators validate total cost of ownership parity with diesel equivalents on dedicated freight corridors.
- Commercial Vehicles:Last-mile delivery vans and urban buses drive medium-format pack demand with depot charging infrastructure.
- Two-Wheelers:Moped and motorcycle electrification concentrates in Indian and Southeast Asian markets with swappable battery networks addressing range constraints.
Revenue concentrates in Passenger Vehicles; steepest expansion trajectory belongs to Heavy-Duty Trucks.
Technology:
System-level feature integration differentiates platform performance and unlocks recurring service revenue streams.
- Battery Management System:Cell balancing algorithms and state-of-charge estimation software protect asset longevity and enable warranty risk transfer in battery-as-a-service contracts. Tesla leverages over-the-air BMS updates to lock in recurring revenue alongside hardware sales.
- Fast Charging:800-volt architectures and silicon carbide power electronics enable 10-80% charge cycles under 20 minutes. Highway corridor deployment in Germany and France accelerates under EU Alternative Fuels Infrastructure Regulation pressure.
- Regenerative Braking:Kinetic energy recovery systems extend urban driving range and reduce brake wear maintenance costs.
- Wireless Charging:Inductive pad systems target fleet depot automation and premium residential installations where connector durability concerns persist.
Adoption runs through Battery Management System; infrastructure investment favors Fast Charging.
End User:
Procurement authority and financing structure vary sharply across direct manufacturing, fleet aggregation, and post-warranty service channels.
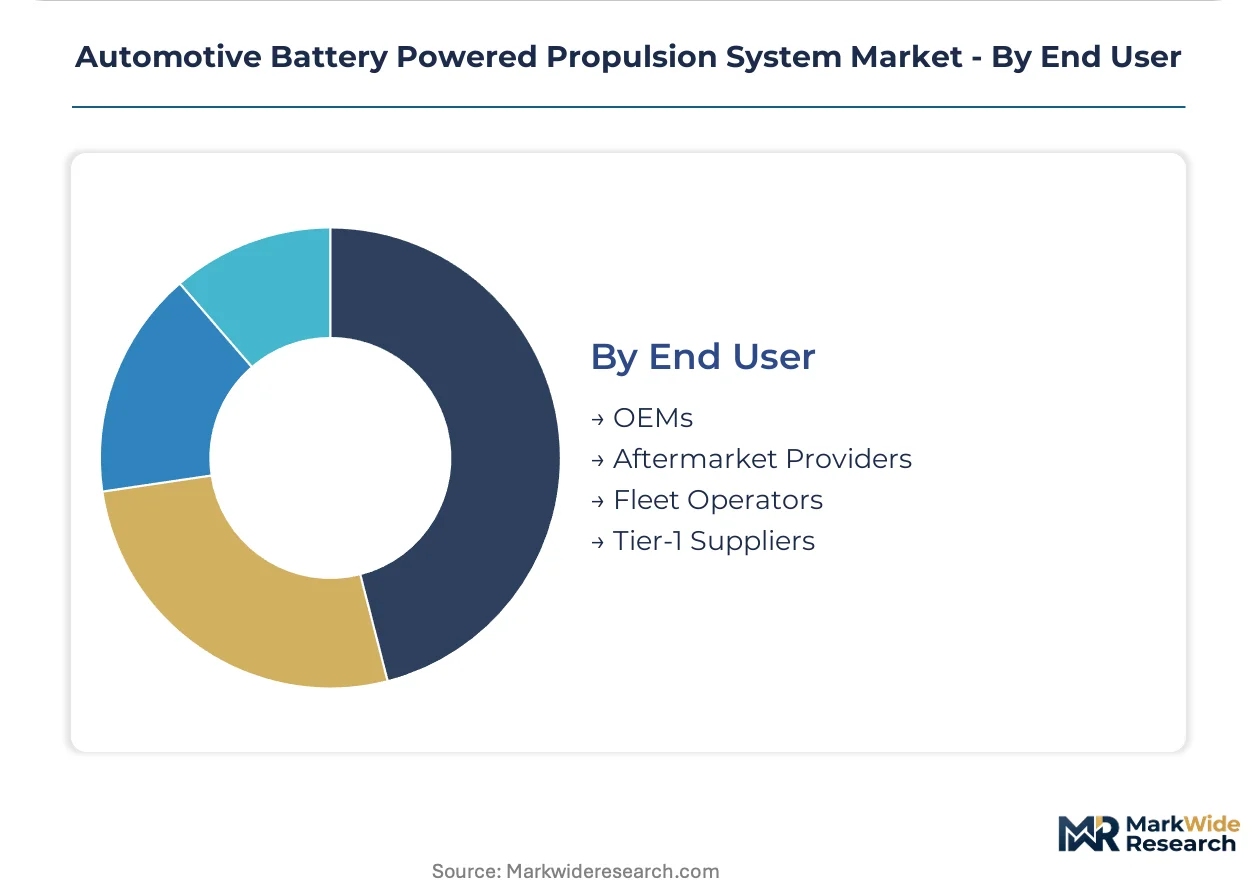
- OEMs:Vehicle manufacturers exercise design authority over pack form factor and cell supplier selection. BYD anchors position through in-house lithium iron phosphate production and integrated power electronics.
- Fleet Operators:Commercial buyers are unbundling battery asset ownership through mileage-based service agreements that transfer degradation risk to financiers. North American last-mile delivery operators validate these models before long-haul scaling.
- Tier-1 Suppliers:Pack assemblers and subsystem integrators serve multiple OEM platforms from concentrated manufacturing clusters in Guangdong province.
- Aftermarket Providers:Independent service channels address second-life stationary storage conversion and end-of-life recycling under emerging extended producer responsibility frameworks.
Design control rests with OEMs; financing innovation emerges through Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's cell gigafactory corridor anchors global manufacturing capacity for automotive battery powered propulsion systems. The report maps five national markets where regulatory pressure and industrial clustering are reshaping competitive positioning.
China
Guangdong province pack assembly clusters supply domestic OEMs and export channels under MIIT new energy vehicle credit pressure. The country's dual carbon goals enforce minimum zero-emission sales ratios for manufacturers. Shenzhen and Shanghai metropolitan areas concentrate BMS software development and power electronics integration talent.
United States
EPA tailpipe emission standards and NHTSA corporate average fuel economy rules mandate fleet-wide CO2 reductions across light-duty and medium-duty categories. The Inflation Reduction Act domestic content provisions are reshoring cell manufacturing investments. Michigan and Texas industrial corridors host expanding pack assembly operations serving Detroit Three electrification programs.
Germany
EU Green Deal fleet emission mandates compress diesel phase-out timelines for premium passenger platforms. The F-Gas Regulation refrigerant phase-down accelerates CO2 heat pump engineering partnerships with industrial refrigeration specialists. Bavaria and Baden-Württemberg automotive clusters integrate solid-state pilot lines with existing powertrain engineering centers.
South Korea
Pilot production lines for ceramic electrolyte architectures target premium platforms as dry electrode coating techniques mature. METI-aligned industrial policy supports cathode active material processing investments. Gyeonggi-do and Ulsan metropolitan areas concentrate cylindrical cell output for export to European and North American pack assemblers.
Japan
Solid-state development programs attract capital targeting higher energy density with reduced thermal runaway risk. METI technology roadmaps coordinate automotive OEM and chemical supplier R&D alignment. Nagoya and Tokyo metropolitan areas host integrated motor drive and SiC inverter packaging operations.
Automotive Battery Powered Propulsion System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the automotive battery powered propulsion system landscape. Cell manufacturing concentrates among Asian conglomerates with captive mining and refining operations, while European and North American pack assemblers rely on procurement contracts for cylindrical and prismatic supply. Three archetypes dominate: vertically integrated OEMs controlling cell-to-vehicle value chains; pure-play cell specialists scaling gigafactory output; and Tier-1 subsystem integrators bundling thermal management with power electronics. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with second-life stationary storage alliances emerging as a secondary vector.
Among Asian cell producers, Contemporary Amperex Technology Co., Limited and LG Energy Solution exemplify the scale-driven specialist archetype, supplying multiple OEM platforms across three continents. BYD Company Ltd. represents the vertically integrated OEM model, anchoring position through in-house lithium iron phosphate production and integrated power electronics. These three entities occupy positions that illustrate the structural tension between captive supply security and open-market procurement flexibility.
| Leading Market Players |
|---|
| Tesla |
| BYD Company Ltd. |
| Robert Bosch GmbH |
| Contemporary Amperex Technology Co., Limited |
| LG Energy Solution |
| Panasonic Corporation |
| SAMSUNG SDI |
| Toyota Motor Corporation |
| Volkswagen |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate spot price volatility cascades through cathode active material costs into tiered pack pricing, compressing margins for European and North American assemblers while Chinese integrated producers maintain cost advantage through captive refining operations.
Pricing Analysis
Energy throughput guarantees anchor value-based contracts for battery-as-a-service subscriptions, decoupling hardware ownership from mileage-based energy access. Three-tier pricing structure across premium solid-state, standard high-nickel, and economy LFP configurations reflects certification grade and thermal management complexity. Cost compression in cylindrical cell procurement is intensifying because South Korean suppliers are expanding 4680 output. Fleet operators exhibit highest price sensitivity due to total cost of ownership scrutiny, while premium passenger OEMs prioritize energy density over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium hydroxide processing capacity feeding cathode precursor production. Manufacturing gravity centers on China, South Korea, and Japan for cell output, with Germany and the United States expanding pack assembly. Supply chains draw from Australian spodumene, Chilean brine, and Indonesian nickel for critical mineral feedstock. Tariff exposure on Chinese cell imports creates procurement risk for European and North American OEMs. Distribution runs through Tier-1 subsystem integrators clustered in Guangdong province serving multiple OEM platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell manufacturing capacity constraints prop pricing power for incumbent producers with operational gigafactories, while raw material processing bottlenecks extend lead times for new entrants.
For Market Incumbents: Anchor market position through backward integration into lithium refining and cathode precursor production, securing feedstock against spot price volatility. Expand 4680 cylindrical output in South Korea and China to defend share against prismatic alternatives. Solid-state pilot line maturation by Japanese competitors threatens premium segment margins. For New Entrants and Emerging Players: Enter via second-life stationary storage conversion services, where retired automotive packs face limited competition from established recyclers. Target North American aftermarket providers underserved by OEM-controlled channels. Deploy robotic disassembly automation to meet EU REACH compliance obligations ahead of scaled competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-pack assemblers in Michigan and Texas industrial corridors with IRA-aligned domestic content positioning. Long-term viability hinges on securing offtake agreements with OEMs executing fleet electrification mandates. Watch EPA tailpipe standard stringency revisions as inflection indicator for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Line Deployment | CATL and Toyota ceramic electrolyte programs target 400+ Wh/kg density for premium platforms. |
| CO2 Heat Pump Integration | EU F-Gas Regulation compliance accelerates supplier partnerships with industrial refrigeration specialists. |
| Battery-as-a-Service Platform Launch | Tesla and emerging financiers unbundle asset ownership through mileage-based subscription contracts. |
| Gigafactory Capacity Expansion | BYD and LG Energy Solution scale cylindrical output across Jiangsu and Gyeonggi-do corridors. |
| Second-Life Storage Alliance | Retired automotive packs convert to grid-scale assets under extended producer responsibility frameworks. |
Study Parameters
Document review covered SEC 10-K filings, MIIT production databases, and EU regulatory filings, complemented by interviews with OEM platform engineers, Tier-1 procurement leads, and aftermarket service operators. Secondary sources included IHS Markit vehicle registration data, customs trade records, and cathode material pricing indices. Bottom-up cell production estimates triangulated against top-down OEM electrification targets.
Installed capacity and revenue outputs were generated through segmented modeling across vehicle class, cell chemistry, and regional production cluster dimensions throughout the forecast period. CAGRs were derived from production ramp schedules and fleet penetration curves. Key inputs included lithium carbonate spot trajectories, EPA regulatory stringency scenarios, and solid-state manufacturing yield assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material export restriction scenarios or accelerated solid-state commercialization. Projections reflect assumptions regarding mining capacity expansion and thermal management standardization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Coolants Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Two-Wheeler Market