
 Electric Vehicle Air Conditioning Market | 2026-2036
Electric Vehicle Air Conditioning Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Air Conditioning Market Insights
Software-defined thermal calibration is consolidating around recurring revenue models for cabin preconditioning and battery conditioning services. Denso Corporation leverages its semiconductor-integrated compressor platforms to anchor high-margin thermal contracts with Japanese OEMs. Valeo SA competes through European production scale in CO2 heat pump modules, while Hanon Systems specializes in integrated coolant valve assemblies that extend battery range in cold climates.
Electric vehicle air conditioning encompasses refrigerant circuits, heat exchangers, and electromechanical compressors engineered to maintain cabin comfort while managing battery thermal loads across temperatures from minus thirty to plus fifty degrees Celsius. The system serves the dual purpose of passenger climate control and powertrain temperature regulation, with coefficient of performance targets exceeding three hundred percent for heat pump configurations. Compressor electrification dominates value capture as OEMs shift from belt-driven to high-voltage scroll and swashplate designs. CO2 technology represents the fastest-expanding refrigerant pathway, driven by GWP compliance deadlines, while thermal management units concentrate margin pools through integration of chiller, valve, and sensor functions into single assemblies.
FEPA refrigerant phase-down timelines, EPA Section 608 enforcement, and EU F-Gas Regulation revisions are tightening allowable global warming potential thresholds and compelling supplier retooling toward CO2 and R-1234YF platforms. China's MIIT dual carbon goals and NMPA vehicle-type approval standards add parallel compliance layers for exporters serving domestic OEMs. Stakeholders must monitor refrigerant patent thickets, thermal system integration complexity, and the pace of OEM in-sourcing versus outsourced module procurement to align capacity investments with actual contract award trajectories.
Market Dynamics
CO2 refrigerant migration is compressing supplier margins while forcing simultaneous retooling of compressor foundries, heat exchanger lines, and system integration capabilities across the value chain. The shift from R-134A architectures demands capital deployment years ahead of volume ramp, stranding legacy equipment and concentrating procurement power among OEMs with thermal system design competency.
Growth Catalysts
- EPA AIM Act phase-down mandates:The US Environmental Protection Agency's refrigerant phase-down schedule under the American Innovation and Manufacturing Act is compelling fleet operators to accelerate heat pump retrofits and new vehicle specifications.
- Fleet electrification:Commercial vehicle operators are specifying integrated thermal management systems that precondition battery packs and cabin spaces simultaneously, expanding addressable system value per vehicle.
- German engineering corridor concentration:OEM and Tier-1 clustering around Stuttgart and Munich creates localized supplier ecosystems that compress development cycles and reduce qualification timelines for new thermal architectures.
Market Restraints
- CO2 system cost premiums:Transcritical CO2 heat pump modules require high-pressure-rated aluminum heat exchangers and reinforced compressor housings that add material cost versus conventional R-134A systems.
- Semiconductor supply concentration:Compressor inverter chips and thermal management controllers depend on fabrication capacity concentrated in East Asian foundries, exposing module assemblers to allocation volatility.
- Refrigerant patent thickets:Proprietary valve designs and CO2 cycle control algorithms held by incumbent suppliers create licensing friction for new entrants developing competitive thermal units.
Strategic Opportunities
- India PLI scheme alignment:The Production Linked Incentive scheme for automotive components offers cost offsets for domestic manufacturing of electric compressor assemblies serving export-oriented OEMs.
- Software-defined thermal services:Over-the-air calibration of cabin preconditioning and battery conditioning algorithms enables recurring revenue streams separate from hardware shipment economics.
- Retrofit aftermarket:Existing electric commercial vehicle fleets require thermal system upgrades to meet evolving refrigerant compliance deadlines, creating a secondary equipment demand channel parallel to OEM supply.
Industry Challenges
- Cross-functional thermal engineering scarcity:System integration requires simultaneous competency in refrigerant thermodynamics, high-voltage electrical safety, and battery electrochemistry, with limited talent pools spanning all three domains.
- Validation timeline compression:OEM platform cycles are compressing while CO2 system durability testing requires extended thermal cycling protocols, squeezing supplier development schedules.
- Multi-regulatory certification burden:Suppliers must simultaneously satisfy EPA Section 608 technician certification, EU F-Gas Regulation equipment standards, and China MIIT vehicle-type approval documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Air Conditioning Market |
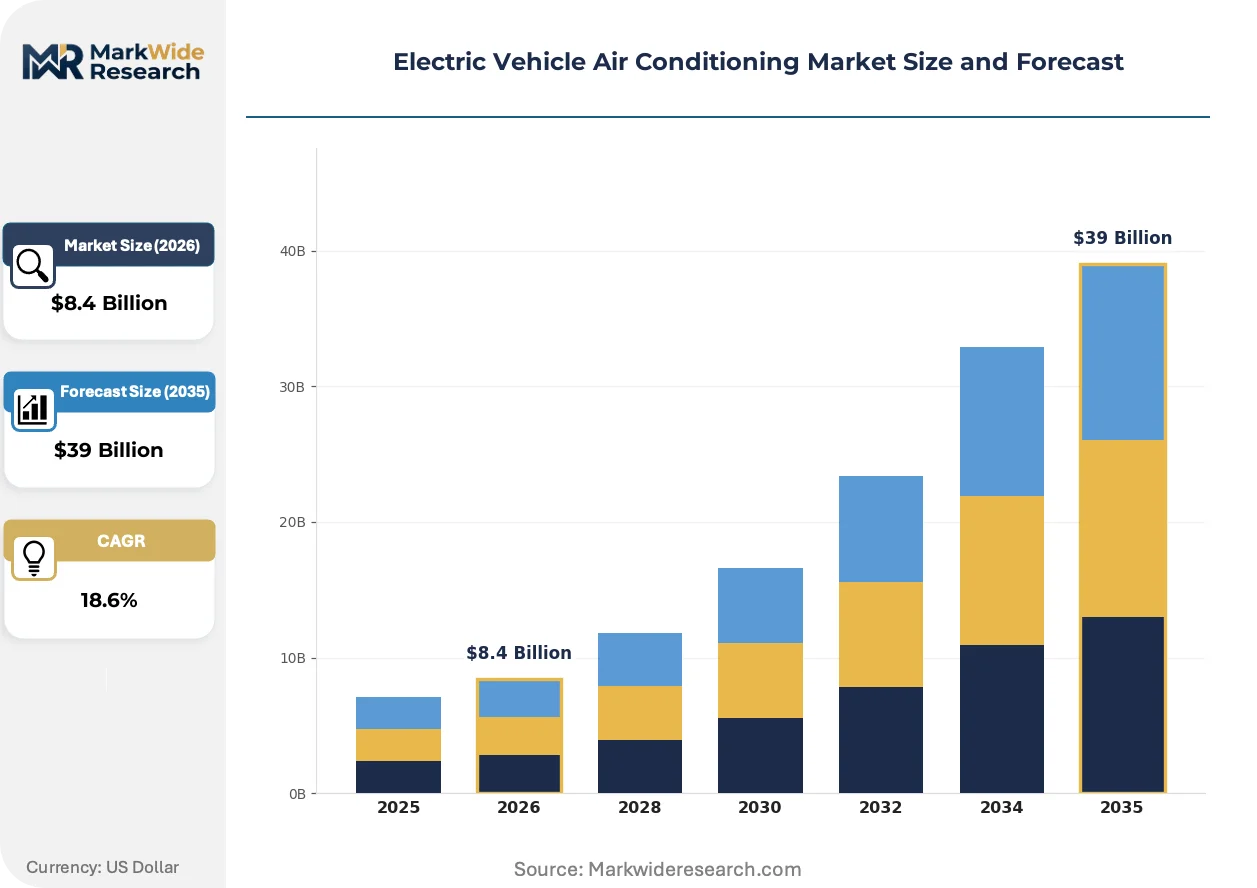
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressors, Evaporators, Condensers, Thermal Management Units Technology: R-134A, R-1234YF, CO2, Air-Cooled End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Installation: Integrated Systems, Retrofit Solutions, Modular Installations, Custom Builds |
| Companies Covered | Denso Corporation, Valeo SA, Hanon Systems, Sanden Corporation, Mahle GmbH, Toyota Industries Corporation, Panasonic Holdings Corporation, Marelli Holdings Co., Ltd., Brose Fahrzeugteile SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Air Conditioning Market Trends and Innovations
Thermal system architecture is fragmenting from centralized units toward distributed node configurations that place heating and cooling capacity closer to battery cell arrays and cabin zones. This decomposition is enabling new supplier entry points while complicating system integration responsibility.
Transcritical CO2 heat pump technology is decentralizing thermal capacity deployment across vehicle architectures. The refrigerant operates at pressure multiples above conventional systems, enabling compact heat exchanger packaging and extended temperature range performance. European commercial vehicle OEMs are specifying CO2 architectures for new platform launches scheduled across the mid-2020s. The technology is decentralizing margin capture from traditional compressor specialists toward integrated module assemblers that control valve, sensor, and controller integration.
The EU F-Gas Regulation revision is tightening global warming potential thresholds for mobile air conditioning systems sold in member states. The regulation is forcing refrigerant pathway decisions years ahead of US federal alignment, creating divergent regional product configurations. Suppliers serving European OEMs are prioritizing CO2 and R-1234YF platform development over R-134A derivative architectures, while maintaining legacy capacity for export markets with slower regulatory clocks.
Fleet procurement patterns are consolidating thermal system specification authority at the corporate level rather than delegating to individual depot managers. Large commercial vehicle operators are mandating standardized heat pump configurations across mixed OEM fleets to simplify maintenance training and parts inventory. This consolidation is visible most acutely in German logistics corridors where electrified last-mile delivery density is highest, compressing supplier negotiation leverage and favoring thermal system providers with multi-OEM validation histories.
Electric Vehicle Air Conditioning Market Segmentation
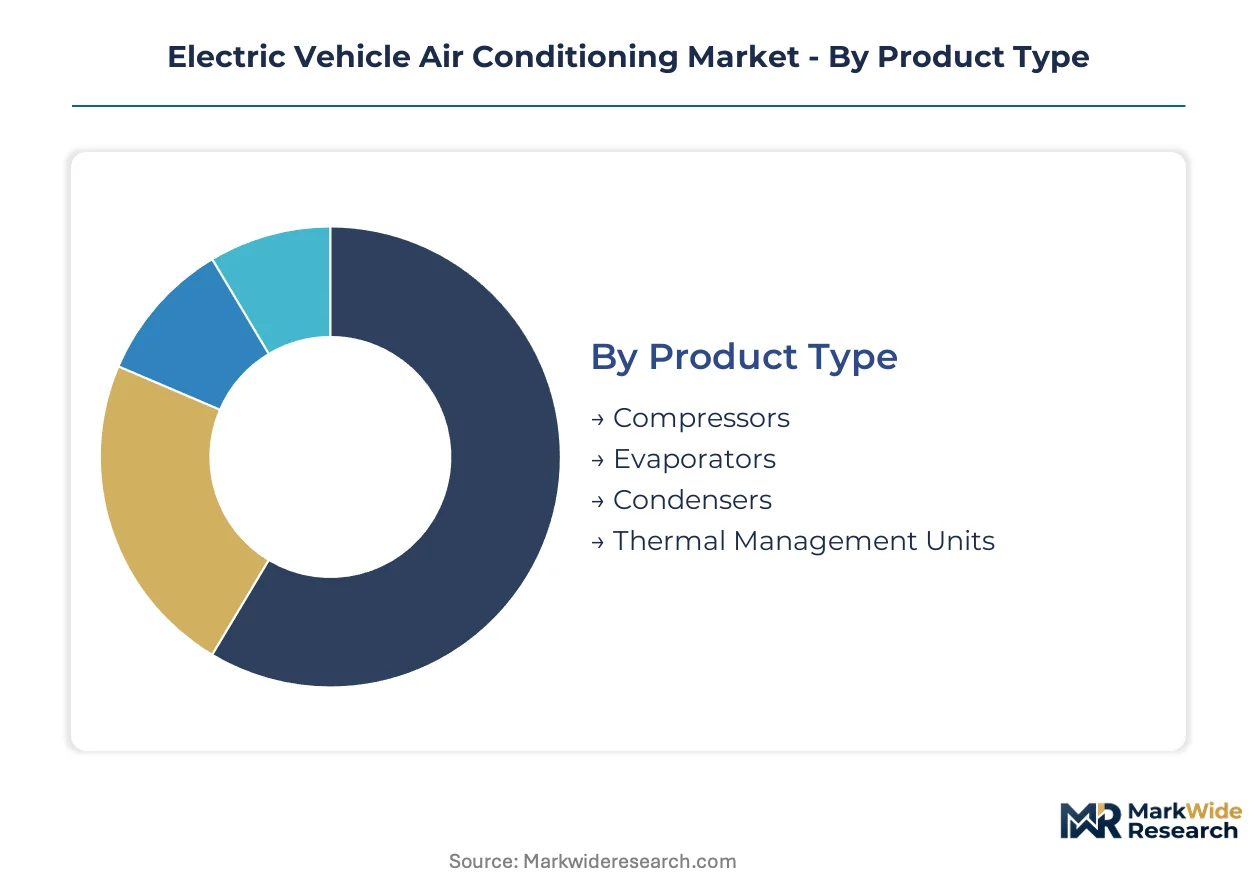
Thermal system procurement patterns diverge sharply across customer types and refrigerant pathways. Compressor electrification and CO2 migration are fragmenting supplier margins while creating distinct performance tiers that reshape contract structures.
Product Type:
Component selection tracks directly with vehicle platform voltage architecture and thermal load requirements.
- Compressors:High-voltage scroll and swashplate designs dominate value capture as OEMs abandon belt-driven legacy architectures. Japanese and German automakers specify semiconductor-integrated inverter compressors for battery conditioning precision. Compressor electrification concentrates procurement power among suppliers with captive power electronics capabilities.
- Thermal Management Units:Integrated assemblies combining chiller, valve, and sensor functions command premium positioning through reduced packaging complexity. Fleet operators in German logistics corridors specify these modules for simultaneous cabin and battery preconditioning. Integration depth determines supplier margin retention versus OEM in-sourcing pressure.
- Evaporators:Aluminum microchannel designs optimize heat transfer density for compact vehicle packaging.
- Condensers:Multi-flow configurations balance refrigerant pressure drop against thermal rejection capacity.
Compressors lead volumes today; thermal management units are gaining share fastest.
Technology:
Refrigerant pathway selection locks suppliers into decade-long capital commitments shaped by regulatory phase-down calendars.
- CO2:Transcritical heat pump architectures operate at pressure multiples above conventional systems, enabling extended temperature range performance from minus thirty to plus fifty degrees Celsius. European OEMs specify CO2 for commercial vehicle platforms launching across the mid-2020s, compelled by EU F-Gas Regulation GWP thresholds. The technology demands high-pressure-rated aluminum heat exchangers that strain legacy supplier tooling.
- R-134A:Dominant incumbent refrigerant facing stranded asset risk as EPA AIM Act phase-down mandates compress allowable deployment windows. Fleet operators in slower-regulatory-clock export markets sustain residual demand for R-134A service parts and retrofit components.
- R-1234YF:Low-GWP transitional refrigerant bridging R-134A phase-out and CO2 scale-up.
- Air-Cooled:Simplified thermal architectures for entry-segment electric vehicles with limited battery thermal conditioning requirements.
R-134A leads volumes today; CO2 is climbing the fastest.
End User:
Procurement authority concentration varies dramatically by customer scale and vehicle deployment model.
- OEMs:Original equipment manufacturers specify thermal systems during platform development cycles, locking suppliers into multi-year contracts with stringent durability validation protocols. German engineering corridors around Stuttgart and Munich concentrate OEM procurement activity, compressing supplier qualification timelines for new CO2 architectures.
- Fleet Operators:Large commercial vehicle operators mandate standardized heat pump configurations across mixed OEM fleets to simplify maintenance training and parts inventory. Corporate-level specification authority is consolidating in German last-mile delivery networks with highest electrified vehicle density.
- Aftermarket Providers:Independent service channels address refrigerant compliance retrofits and thermal system upgrades for existing electric commercial vehicle fleets.
- Individual Consumers:Retail replacement demand concentrates in cabin comfort components with shorter replacement cycles than powertrain thermal elements.
OEMs lead volumes today; fleet operators are expanding procurement most quickly.
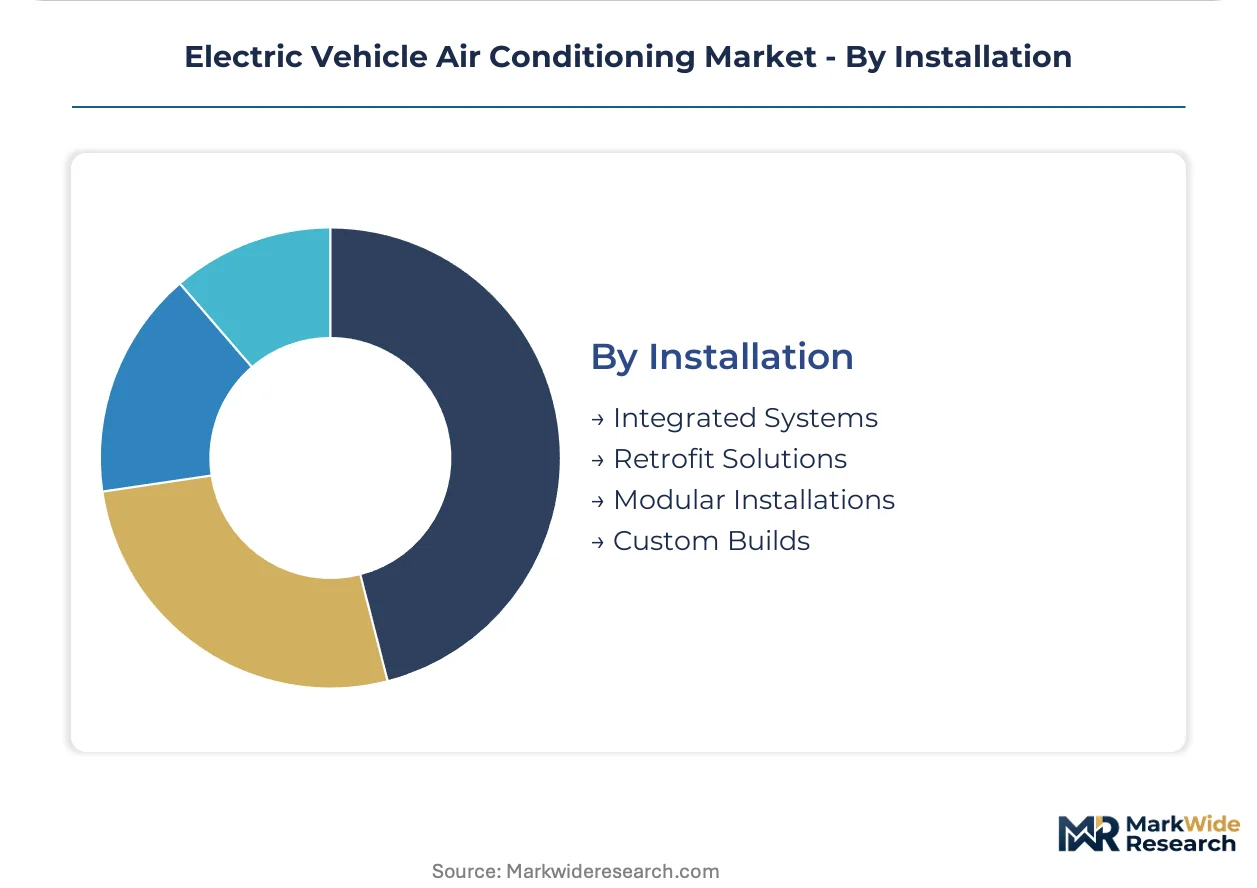
Installation:
System architecture choices reflect trade-offs between integration depth and field serviceability.
- Integrated Systems:Factory-installed thermal architectures with embedded compressor, heat exchanger, and controller assemblies optimized for specific vehicle platforms. OEMs favor these configurations for warranty control and performance optimization.
- Retrofit Solutions:Secondary equipment demand channel serving existing electric commercial vehicle fleets requiring thermal system upgrades to meet evolving refrigerant compliance deadlines. Aftermarket providers develop modular retrofit kits for R-134A to CO2 conversions.
- Modular Installations:Discrete component assemblies enabling field replacement of individual thermal elements without full system replacement.
- Custom Builds:Bespoke thermal configurations for specialized commercial vehicle applications with non-standard battery pack geometries or extreme climate operating requirements.
Integrated systems lead volumes today; retrofit solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates engineering talent for CO2 heat pump development, while China scales manufacturing capacity for electrified compressor assemblies serving domestic OEM export programs.
United States
EPA AIM Act phase-down mandates compel fleet operators to accelerate heat pump retrofits for commercial vehicle compliance. The agency's Section 608 enforcement tightens technician certification requirements for refrigerant handling. Detroit-area automotive engineering clusters coordinate thermal system validation with Michigan-based battery manufacturers.
Germany
EU F-Gas Regulation revisions force refrigerant pathway decisions ahead of federal alignment timelines in other markets. Stuttgart and Munich engineering corridors compress supplier qualification cycles for new CO2 architectures through concentrated OEM-Tier-1 proximity. KBA vehicle-type approval standards add documentation layers for thermal system exporters.
China
MIIT dual carbon goals and NMPA vehicle-type approval standards impose parallel compliance requirements on thermal system suppliers serving domestic OEMs. Yangtze River Delta manufacturing bases scale high-voltage compressor production for European and Asian export markets. Shanghai-based engineering centers develop integrated thermal management units for battery conditioning precision.
Japan
METI energy efficiency standards drive heat pump coefficient-of-performance targets above three hundred percent for domestic vehicle platforms. Nagoya-area automotive suppliers cluster around Toyota and Honda thermal engineering specifications. JIS standards govern refrigerant circuit durability testing protocols that exceed baseline international requirements.
India
PLI scheme cost offsets attract domestic manufacturing investment for electric compressor assemblies serving export-oriented OEMs. BIS certification requirements add qualification timelines for thermal system components entering the domestic market. Tamil Nadu and Gujarat automotive corridors concentrate supplier tooling for integrated coolant valve production.
Electric Vehicle Air Conditioning Market Competitive Landscape
Top-tier vendors anchor multi-year OEM platform contracts, while mid-scale specialists occupy retrofit aftermarket and regional fleet procurement channels. The vendor base stratifies across semiconductor-integrated compressor platforms, CO2 heat pump module assemblers, and integrated coolant valve specialists. Strategic archetypes include captive power electronics integrators, high-pressure aluminum heat exchanger fabricators, and software-defined thermal calibration providers. Competitive moves concentrate on capacity expansion for CO2-rated foundries and strategic partnerships bridging refrigerant thermodynamics with battery electrochemistry expertise.
Within the integrated module tier, Denso Corporation and Valeo SA exemplify divergent geographic anchoring strategies for thermal system procurement. Denso represents Japanese OEM captive supply relationships through semiconductor-integrated platform development. Valeo occupies European production scale positioning for CO2 heat pump architectures. Hanon Systems anchors Korean-based integrated valve assembly specialization for cold-climate battery range extension. These three entities illustrate how supplier archetypes map to distinct refrigerant pathway competencies and regional regulatory compliance priorities.
| Leading Market Players |
|---|
| Denso Corporation |
| Valeo SA |
| Hanon Systems |
| Sanden Corporation |
| Mahle GmbH |
| Toyota Industries Corporation |
| Panasonic Holdings Corporation |
| Marelli Holdings Co., Ltd. |
| Brose Fahrzeugteile SE & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up compressor specialists anchor supply discipline across German and Japanese manufacturing corridors, translating concentrated ownership into pricing power that resists cost pass-through from raw aluminum and semiconductor inputs. Their portfolio-scale procurement contracts with Denso and Valeo lock in multi-year price floors for high-voltage scroll platforms while fleet operators absorb CO2 system premiums through total-cost-of-ownership calculations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electrified compressor assemblies serving export-oriented OEMs. Contract-based long-term offtake dominates, with pricing stratifying across premium semiconductor-integrated tiers, standard inverter-driven configurations, and economy belt-driven legacy units. Cost compression in standard tiers intensifies because foundry competition from Yangtze Delta producers erodes margin buffers. Fleet operators exhibit highest price sensitivity on per-unit hardware, while OEM platform engineers prioritize performance certification over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated thermal management units, bypassing aftermarket distributors for factory-installed configurations. Supply concentrates in Germany, China, and Japan, with aluminum microchannel heat exchangers and silicon carbide inverter chips drawing from East Asian foundry capacity. Single-source vulnerability in semiconductor fabrication exposes module assemblers to allocation volatility during demand spikes. Distribution runs through Tier-1 system integrators that consolidate valve, sensor, and controller sourcing for OEM platform qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle air conditioning functions as a late-cycle quality story where fleet procurement authority shifts toward CO2 heat pump specifications that command sustained margin premiums over R-134A legacy architectures.
For Market Incumbents: Lock in captive power electronics capacity through backward integration into inverter chip sourcing, defending against emerging Chinese compressor specialists with state-backed foundry access. Prioritize certification investment for EPA Section 608 technician training programs to entrench service-channel control as refrigerant phase-down mandates accelerate retrofit demand.
For New Entrants and Emerging Players: Launch via aftermarket retrofit channels serving existing electric commercial vehicle fleets facing compliance deadlines, where incumbent OEM qualification timelines create temporary supply gaps. Target India's PLI scheme cost offsets for domestic compressor assembly production, penetrating export-oriented OEM supply chains with lower landed cost than European manufacturing.
For Investors and Strategic Acquirers: Valuations sit cheapest among integrated coolant valve specialists with cold-climate battery conditioning patents, where capability scarcity in cross-functional thermal engineering creates acquisition premiums. Watch for inflection when fleet operators consolidate procurement authority at corporate level, signaling shift from fragmented depot-level purchasing toward standardized multi-OEM contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Heat Pump Platform Standardization | European OEMs mandate transcritical architectures ahead of EU F-Gas Regulation GWP deadlines. |
| Semiconductor-Integrated Compressor Development | Japanese suppliers anchor high-margin thermal contracts through captive inverter chip design. |
| Software-Defined Thermal Service Launch | Over-the-air calibration enables recurring revenue separate from hardware shipment economics. |
| Retrofit Aftermarket Channel Expansion | Existing electric commercial fleets require R-134A to CO2 conversion kits for compliance. |
| India Manufacturing Footprint Establishment | PLI scheme offsets attract capacity for export-oriented OEM compressor supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier-1 thermal system procurement leads, fleet operations managers, and aftermarket service technicians alongside secondary validation. Trade data from customs filings, EPA refrigerant compliance databases, EU F-Gas Regulation equipment registries, and vehicle production statistics anchored supply-side modeling. Bottom-up component shipment tracking and top-down OEM platform content analysis triangulated market sizing.
Historical reference periods spanning the transition from belt-driven to electrified compressor architectures anchored projection parameters across the modeling period. Segmentation dimensions included refrigerant pathway, vehicle voltage architecture, integration depth, and regional regulatory cluster. CAGRs derived from curve-fitting against adoption S-cycles for prior automotive technology transitions, with battery thermal load requirements and fleet electrification pace as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA phase-down timelines or semiconductor supply disruptions. Outputs reflect documented assumptions around OEM in-sourcing propensity and refrigerant patent licensing friction. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Folding E-Scooter Market