
 Middle East Wireless EV Charging Market | 2026-2036
Middle East Wireless EV Charging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Wireless EV Charging Market Intelligence
A shift from outsourced pilot projects to in-house technology integration by large infrastructure developers is recalibrating the market's competitive dynamics. Technology providers like Siemens AG are embedding their systems within broader smart city contracts in the region. Concurrently, specialists such as Electreon Wireless focus on dynamic charging for public transport routes, differentiating through specialized application expertise in key Gulf Cooperation Council (GCC) countries.
Middle East wireless EV charging technology transfers electrical energy to a vehicle's battery without physical cables, typically using inductive pads that generate a magnetic field. These systems, with efficiencies often over 90%, provide automated charging solutions. Inductive charging is the dominant technology segment due to its maturity and standardization. While the private owners segment is large, demand from public transport and fleet operators represents the fastest-growing end-user category, driven by municipal tenders.
Regulatory compliance is shaped by national standards bodies like the Saudi Standards, Metrology and Quality Organization (SASO) and utility authorities in the UAE. These entities establish safety and interoperability requirements, often referencing IEC standards, which governs market access for technology vendors. The key strategic decision for infrastructure developers now centers on balancing proprietary system deployment against the adoption of open, interoperable charging standards to ensure future scalability.
Market Dynamics
The central dynamic in the Middle East wireless EV charging market is the strategic tension between deploying proprietary, closed-loop charging systems for specific fleets and adopting open, interoperable standards to support broader public and private vehicle ecosystems across smart cities.
Growth Catalysts
- Government Sustainability Mandates:National frameworks, including the UAE Net Zero 2050 initiative and Saudi Vision 2030, create direct policy support and funding mechanisms for the development of public EV charging infrastructure.
- Fleet Operator Demand:Public transport authorities and commercial logistics operators in urban centers like Dubai and Riyadh are seeking automated charging solutions to improve operational efficiency and reduce emissions from their vehicle fleets.
- Smart City Integration:The development of large-scale smart city projects provides a platform for integrating wireless EV charging as a core component of future urban mobility, attracting significant infrastructure investment.
Market Restraints
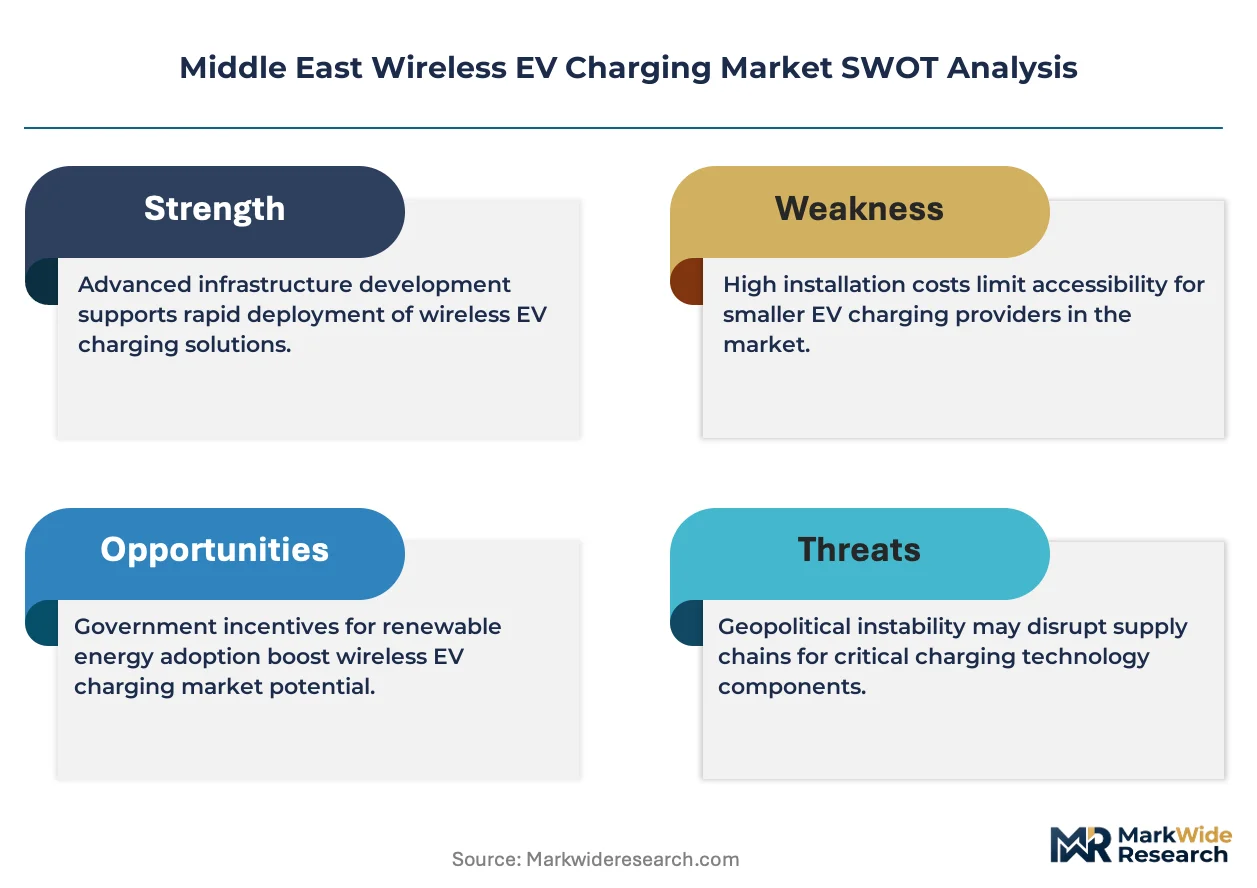
- High Initial Capital Costs:The significant upfront investment required for civil works and the installation of inductive charging pads in roads and depots acts as a barrier to widespread, rapid deployment.
- Interoperability Deficiencies:A lack of full interoperability between different vendors' charging pads and vehicle-side receivers creates technology lock-in risks for fleet operators and municipalities.
- Grid Capacity Limitations:Localized constraints on electrical grid capacity in certain districts can limit the deployment of multiple high-power wireless charging stations without substantial and costly grid upgrades.
Strategic Opportunities
- Expansion into Logistics Hubs:Developing wireless charging corridors for electric trucks and commercial vehicles connecting major ports, airports, and industrial zones in countries like Oman and Qatar presents a significant opportunity.
- Dynamic Charging for Highways:Deploying in-road dynamic wireless charging technology on key inter-city highways could enable long-range electric travel for passenger cars and commercial transport, creating a new service model.
- Vehicle-to-Grid (V2G) Services:Integrating wireless charging systems with V2G technology allows parked EV fleets, such as public buses, to function as distributed energy storage, providing grid stabilization services to utility providers.
Industry Challenges
- Specialized Talent Scarcity:A shortage of technicians and engineers with expertise in high-power electronics, magnetic field engineering, and the specific safety protocols required for wireless charging systems hinders project execution.
- Complex System Integration:Integrating wireless charging hardware with diverse legacy systems, including municipal utility billing platforms and fleet management software, poses a significant technical challenge for vendors.
- Protracted Certification Cycles:Aligning new technologies with the safety and performance requirements of national bodies like SASO and various UAE utility authorities can involve lengthy and costly testing and validation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Wireless EV Charging Market |
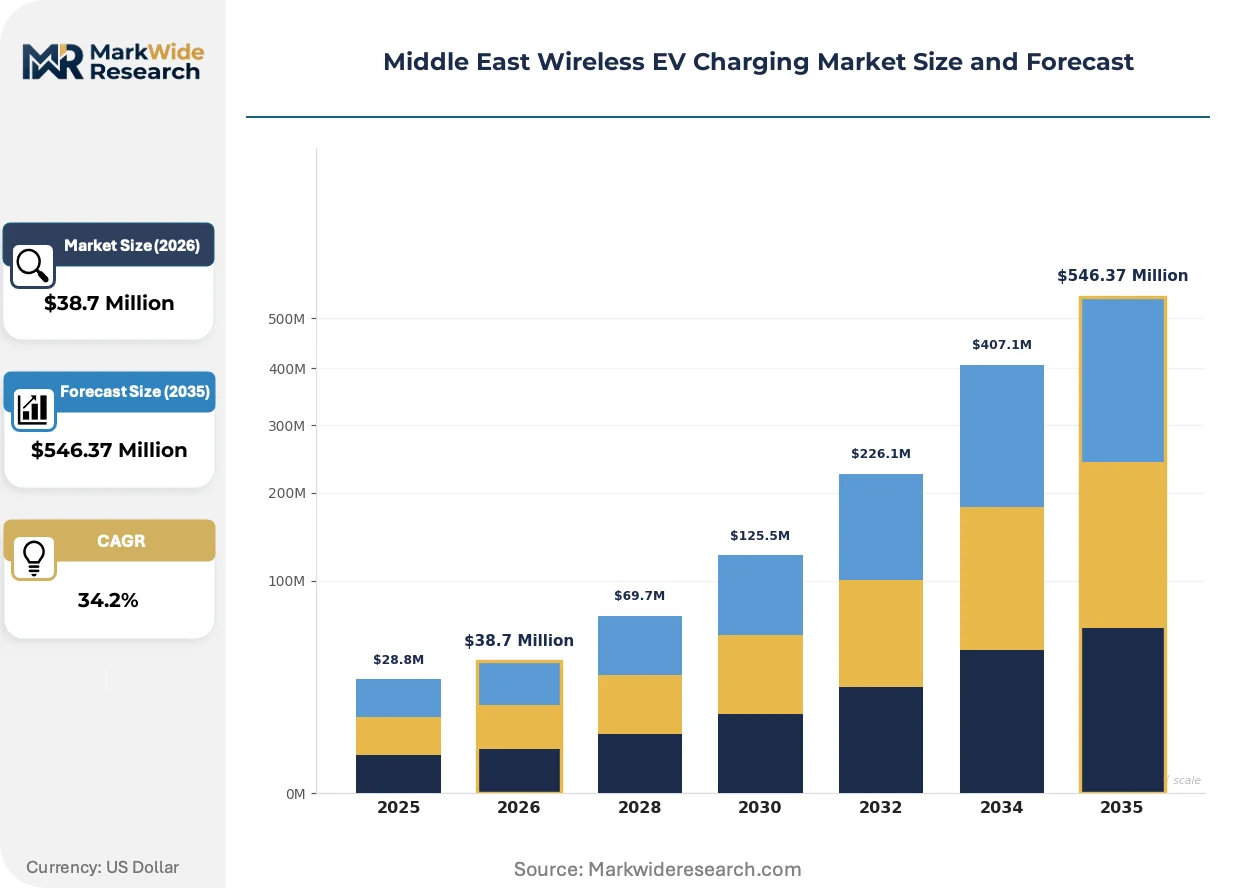
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $546.37 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Inductive Charging, Magnetic Resonance, RF Charging, Capacitive Charging End User: Public Transport, Private Owners, Fleet Operators, Charging Infrastructure Providers Application: Commercial Vehicles, Passenger Cars, Two-Wheelers, Stationary Equipment Installation Type: On-Street Charging, Parking Lots, Residential Areas, Commercial Spaces |
| Companies Covered | WiTricity Corporation, Qualcomm Incorporated, Electreon Wireless, Momentum Dynamics Corporation, Siemens AG, ABB Ltd., Schneider Electric, Tesla, Inc., Hyundai Motor Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Wireless EV Charging Market Strategic Shifts & Innovations
The market is transitioning from isolated, proof-of-concept projects to the strategic deployment of standardized wireless charging networks. This evolution is driven by a convergence of maturing technology, clearer regulatory pathways, and new procurement models tied to large-scale infrastructure development.
High-efficiency resonant inductive charging provides automated power transfer through ground-based pads. Public transport authorities and commercial fleet operators are accelerating adoption for depot and in-route charging. This technology is consolidating the market around inductive solutions as the default standard for automated commercial EV applications, pushing aside less mature alternatives.
Regulatory frameworks from national bodies like the Saudi Standards, Metrology and Quality Organization (SASO) and specific UAE utility authorities are now explicitly referencing IEC technical standards. This harmonization establishes clear safety and interoperability requirements for market access. Vendors targeting public tenders in Riyadh and Dubai are most affected, designing their systems to comply with these specific mandates from the outset.
A notable behavioral shift involves embedding wireless charging procurement within broader smart city or real estate development contracts. This model disrupts the sales cycle for specialized charging vendors, favoring large system integrators who can bundle charging into a wider infrastructure package. This pattern is most pronounced in large-scale urban projects across Saudi Arabia and the UAE.
Middle East Wireless EV Charging Market Segmentation
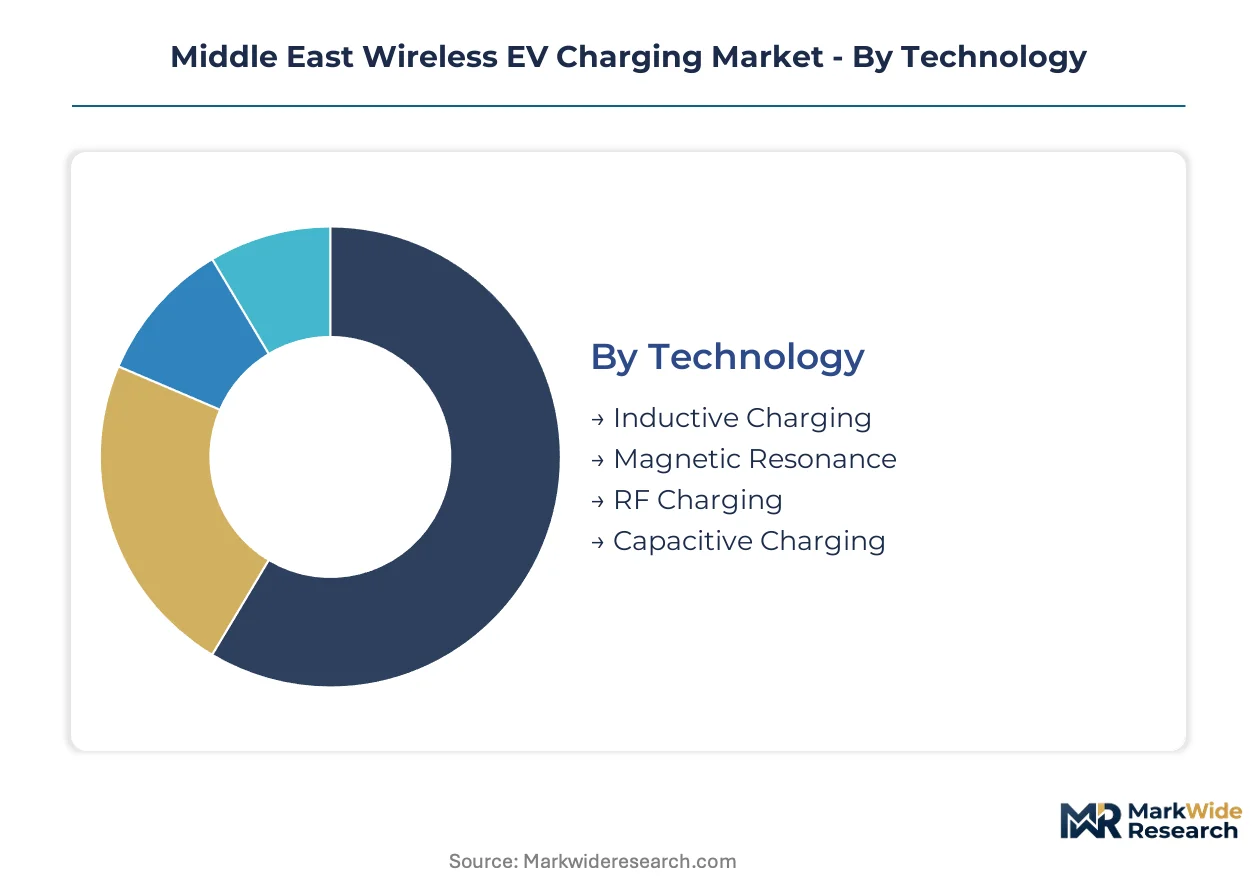
Understanding the distinct segments within the Middle East wireless EV charging market is crucial for infrastructure developers and technology providers. Each segment presents unique deployment challenges and opportunities, influencing investment strategies and product development. Analyzing these categories helps identify areas of concentrated demand and emerging growth trajectories across the region.
Technology:
Segments within technology for wireless EV charging often reflect varying capital expenditure requirements for infrastructure deployment.
- Inductive Charging:This dominant technology transfers electrical energy via magnetic fields between ground-based pads and vehicle receivers, offering high efficiency and automated operation. Demand concentrates in public transport depots and commercial fleet hubs in urban centers like Dubai, driven by the need for consistent, hands-free charging.
- Magnetic Resonance:This advanced method allows for greater misalignment tolerance and potentially higher power transfer over larger air gaps, enhancing flexibility for dynamic charging applications. Deployment is being explored for specialized public transport routes in GCC countries, aiming to support continuous operation.
- RF Charging:Radio frequency charging uses electromagnetic waves to transfer power, suitable for low-power applications.
- Capacitive Charging:This technology employs electric fields to transfer energy, offering an alternative for specific industrial or smaller vehicle applications.
Inductive Charging absorbs the bulk of installed capacity; Magnetic Resonance is expanding most quickly.
End User:
The end-user composition for wireless EV charging systems highlights distinct operational needs and procurement scales.
- Public Transport:Municipal transport authorities integrate wireless charging into bus depots and along urban routes to ensure continuous operation and reduce emissions from public fleets. Major tenders in Riyadh and Dubai prioritize these automated solutions for their operational efficiency.
- Fleet Operators:Commercial logistics and last-mile delivery companies deploy wireless charging in their private depots for automated, high-uptime vehicle charging. This segment seeks solutions that minimize vehicle downtime and optimize route efficiency.
- Private Owners:Individual EV owners represent a large potential market, primarily for residential and public parking solutions.
- Charging Infrastructure Providers:These entities develop and manage public and semi-public charging networks, often in partnership with municipalities.
Public Transport operators dominate current procurement volumes; Fleet Operators are demonstrating the steepest expansion trajectory.
Application:
Wireless EV charging applications vary significantly in their power demands and deployment environments across the region.
- Commercial Vehicles:This segment includes electric buses, trucks, and delivery vans requiring high-power, robust wireless charging solutions for depot and in-route applications. Demand is particularly strong from government-backed transport initiatives and logistics companies in the UAE.
- Passenger Cars:Wireless charging for private electric vehicles focuses on convenience and seamless integration into urban parking and residential settings. Smart city projects in Saudi Arabia are exploring this for future urban mobility.
- Two-Wheelers:Electric motorcycles and scooters can utilize lower-power wireless charging solutions for urban mobility.
- Stationary Equipment:This includes applications like automated guided vehicles (AGVs) or industrial robots within controlled environments.
Commercial Vehicles represent a substantial portion of current deployments; Passenger Cars are gaining share fastest as public infrastructure grows.
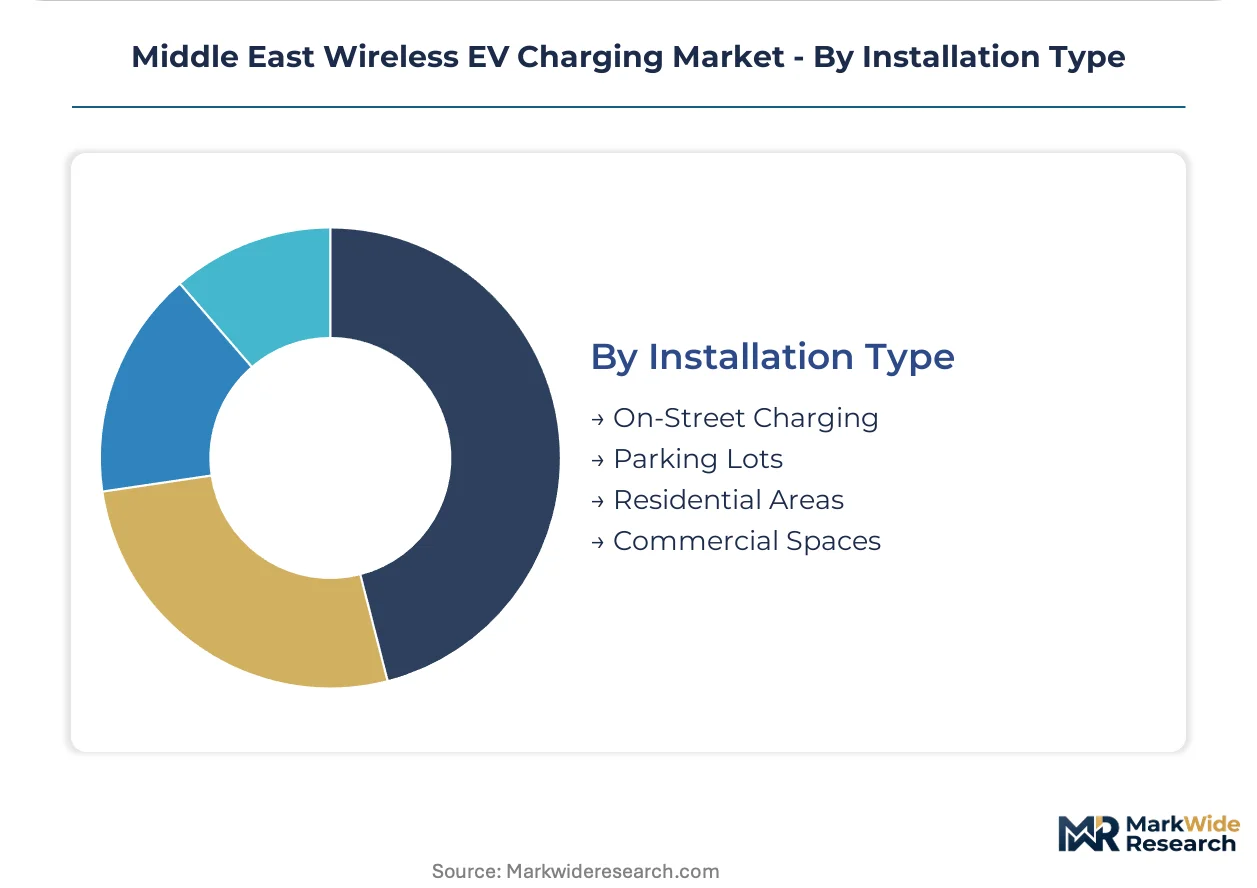
Installation Type:
The installation types for wireless EV charging infrastructure dictate site preparation complexities and integration into urban planning.
- On-Street Charging:Integrating charging pads directly into public roads or designated street parking areas requires significant civil works and utility coordination. Urban planners in Dubai are considering this for convenient public access.
- Parking Lots:Wireless charging solutions for both public and private parking facilities offer convenience for fleet depots and commercial establishments. This type of installation is common for municipal bus depots in Riyadh.
- Residential Areas:Wireless charging solutions for homes and residential complexes offer convenience for private EV owners.
- Commercial Spaces:This includes charging solutions deployed in shopping malls, office complexes, and other business premises.
Parking Lots currently account for the largest share of deployments; Commercial Spaces are climbing the fastest due to smart city initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East's substantial energy resources and ambitious diversification strategies anchor significant investment in advanced infrastructure. Governments across the region prioritize sustainable development and smart city initiatives. This focus provides a robust foundation for wireless EV charging deployment, particularly in urban centers and for public fleets.
United Arab Emirates
Dubai and Abu Dhabi drive demand for wireless EV charging through smart city projects and public transport electrification efforts. UAE utility authorities establish safety and interoperability requirements for new installations. These urban centers attract significant infrastructure investment for automated charging solutions for buses and commercial fleets.
Saudi Arabia
Saudi Arabia's Vision 2030 initiatives stimulate demand for electric vehicle infrastructure, particularly in emerging mega-cities. The Saudi Standards, Metrology and Quality Organization (SASO) provides regulatory oversight for charging systems. Riyadh and NEOM are concentrating on large-scale deployments for commercial fleets and future urban mobility concepts.
Qatar
Qatar's focus on sustainable transport for major events and urban development fuels demand for efficient EV charging technologies. National authorities implement policies supporting green mobility and infrastructure upgrades. Doha is witnessing the integration of wireless charging into public transport networks and smart parking solutions to enhance operational efficiency.
Oman
Oman's economic diversification plans include developing electric vehicle ecosystems and associated charging infrastructure across key sectors. The country's regulatory bodies are aligning with international standards for EV technology and deployment. Logistics hubs around Muscat are exploring wireless charging corridors for commercial vehicles to optimize freight movement.
Middle East Wireless EV Charging Market Key Industry Players
Strategic partnerships dominate the current landscape, as technology providers collaborate with infrastructure developers to deliver integrated solutions. The market structure remains somewhat fragmented, with a mix of specialized wireless charging firms and larger diversified technology conglomerates. Archetypes include pure-play wireless charging innovators and established industrial automation giants. Dominant competitive moves involve technology licensing and geographic expansion into key urban markets.
Specialists in advanced wireless power transfer technology include Electreon Wireless, an Israeli company focusing on dynamic charging solutions for public transport routes in GCC countries. Siemens AG, a German multinational conglomerate, occupies a position as a major system integrator, embedding charging capabilities within broader smart city contracts across the region. Qualcomm Incorporated, a US-based semiconductor and telecommunications equipment company, exemplifies a technology licensor, contributing core intellectual property for inductive charging systems to various manufacturers. These entities collectively anchor the market's technological evolution and deployment strategies.
| Leading Market Players |
|---|
| WiTricity Corporation |
| Qualcomm Incorporated |
| Electreon Wireless |
| Momentum Dynamics Corporation |
| Siemens AG |
| ABB Ltd. |
| Schneider Electric |
| Tesla, Inc. |
| Hyundai Motor Company |
| Others |
Cost & Logistics Intelligence
Public transport authorities in the Middle East drive project-based pricing models for wireless EV charging. Their large-scale infrastructure needs define procurement structures across the region.
Pricing Analysis
Warranty and long-term service agreements form a critical component of wireless EV charging system pricing. Project-based procurement dominates, with technology licensing fees often integrated into broader smart city contracts. Price differentiation stems from system customization and integration complexity. Pricing softness stems from municipal budget constraints and competitive tenders, while private owners exhibit high price sensitivity compared to public transport operators who prioritize operational efficiency.
Supply Chain Analysis
Direct-to-infrastructure developer channels manage large-scale project requirements for wireless charging systems. Component supply concentrates in Germany, the USA, and Israel, reflecting the origins of core technology providers. The supply chain sources high-power electronics, magnetic core materials, and specialized semiconductors. Single-source vulnerability for niche components poses a structural risk, with distribution often running through large system integrators for smart city projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East wireless EV charging market represents a technology-transition phase, with inductive charging displacing traditional wired solutions for commercial applications. This shift reconfigures urban mobility infrastructure across the region.
For Market Incumbents: Lock in long-term contracts with municipal transport authorities to secure recurring revenue streams. Expand proprietary system integration capabilities to counter the threat of interoperability deficiencies. Invest in regional talent development for high-power electronics to address specialized talent scarcity. Leverage existing smart city partnerships to bundle wireless charging into broader infrastructure offerings.
For New Entrants and Emerging Players: Logistics hub operators represent an underserved buyer archetype for specialized wireless charging solutions. Target commercial vehicle fleets in emerging logistics corridors across Oman and Qatar. Focus on developing modular, easily deployable systems for rapid integration into existing industrial zones. A go-to-market angle emphasizing rapid ROI through operational efficiency gains will attract these operators.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term infrastructure plays in the Middle East. Wireless EV charging offers significant viability over the next decade, driven by national sustainability mandates. Target specialized technology providers with strong intellectual property in dynamic charging or V2G integration. A critical signal to watch is the formalization of region-wide interoperability standards, which will unlock broader market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Establish regional R&D centers | Accelerates technology localization for specific Middle East climate and infrastructure requirements. |
| Form joint ventures with local infrastructure developers | Ensures regulatory compliance and streamlines project execution in Saudi Arabia and the UAE. |
| Develop V2G-enabled wireless charging platforms | Unlocks new revenue streams by providing grid stabilization services to utility providers. |
| Standardize charging protocols | Reduces technology lock-in risks for fleet operators and encourages broader market adoption. |
| Expand dynamic charging pilot projects | Validates continuous charging solutions for public transport routes in GCC urban centers. |
Research Approach
Multi-period observation of EV fleet growth rates and smart city project timelines anchored the trend analysis, supplemented by primary interviews. Discussions included municipal transport officials, infrastructure developers, and technology vendors. Secondary validation drew from SASO, UAE utility authority reports, and smart city project documentation. Bottom-up data collection combined with top-down market sizing ensured comprehensive coverage.
An input-output matrix model projected market trajectory across the analysis window, integrating various data points. Segmentation dimensions modeled included technology type, end-user category, application, and installation type. Compound annual growth rates were derived from historical trends and projected infrastructure investment patterns. Key forecast inputs included government EV adoption targets and smart city development budgets.
Revisions become necessary when significant shifts in national EV mandates or grid infrastructure development materialize. Forecasts reflect underlying assumptions regarding technological standardization and regulatory harmonization, with geopolitical instability posing a risk. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market