
 GCC Electric Vehicle Market | 2026-2036
GCC Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Electric Vehicle Market Insights
Software-defined battery management is shifting how OEMs monetize vehicle ownership in the GCC. Tesla leverages over-the-air performance upgrades to sustain recurring revenue streams beyond initial vehicle sales. Lucid Group anchors its regional strategy on luxury positioning and extended-range specifications tailored to Gulf climate conditions. Ceer Motors competes through sovereign-backed manufacturing scale and domestic supply chain development in Saudi Arabia.
Electric vehicles for GCC markets integrate thermal management systems engineered for ambient temperatures exceeding 50°C, with battery cooling loops and cabin preconditioning as mandatory design parameters. The primary commercial purpose spans passenger transportation, logistics electrification, and public transit decarbonization across oil-producing economies diversifying beyond hydrocarbons. Passenger cars dominate current volume, while commercial vehicles represent the fastest-expanding segment as last-mile delivery operators electrify. Lithium-ion battery technology leads installed capacity, though solid-state chemistries attract R&D investment for density and safety gains in extreme-heat deployment.
SFDA and SASO frameworks in Saudi Arabia, alongside UAE's ESMA standards and MOHAP technical regulations, establish product safety and energy efficiency benchmarks for regional EV certification. These bodies shape demand through import compliance requirements and domestic assembly incentives tied to localization thresholds. Stakeholders must monitor how Gulf standardization bodies harmonize charging protocols and battery recycling mandates across member states.
Market Dynamics
Sovereign capital deployment is compressing EV infrastructure timelines across Gulf economies, with state-backed charging networks and domestic manufacturing mandates restructuring competitive entry requirements faster than private capital could achieve independently.
Growth Catalysts
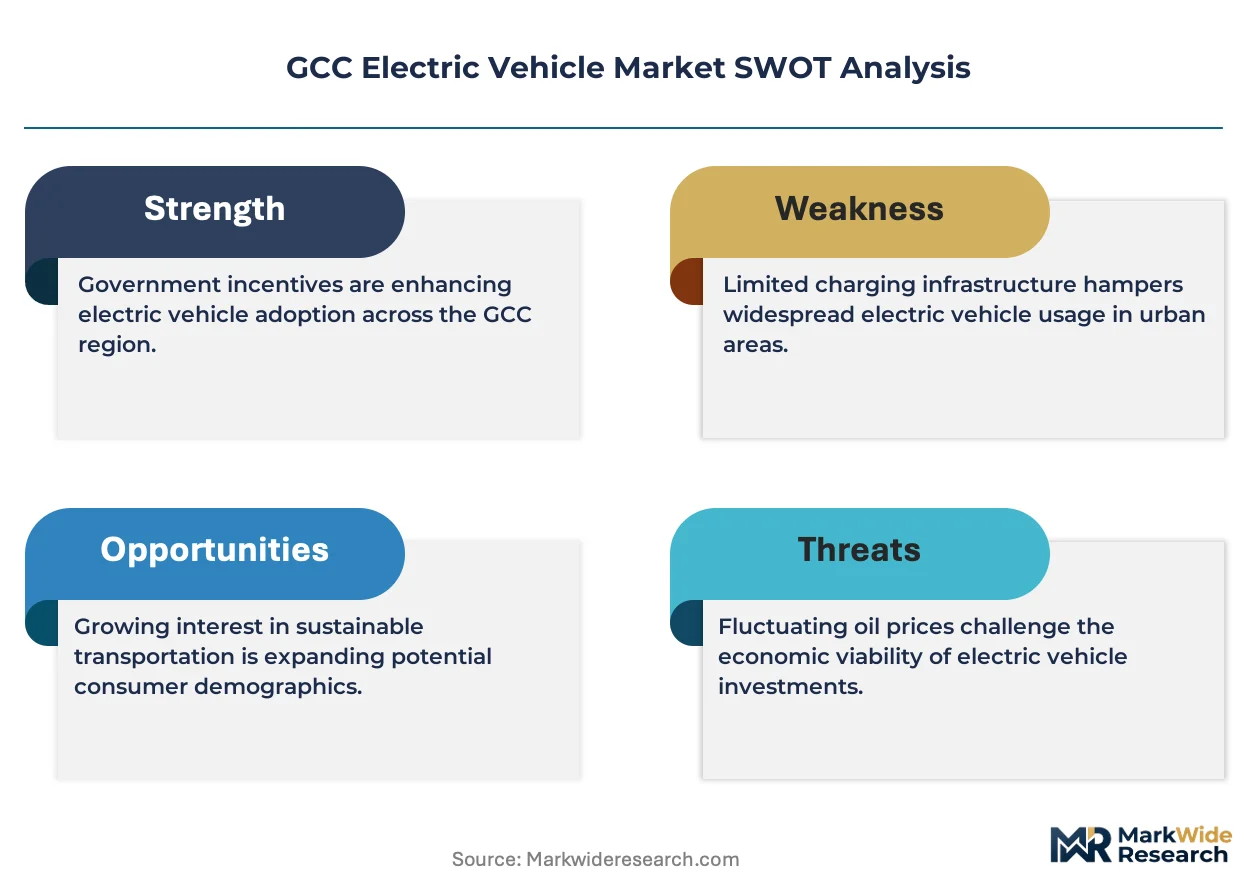
- EV30@30 Initiative:Saudi Arabia's binding target of 30% electric vehicle share by 2030 mandates fleet procurement quotas for government agencies and ride-hailing operators, creating guaranteed offtake channels.
- Green Mobility Regulatory Framework:UAE's ESMA technical regulations and MOHAP safety standards establish certification fast-tracks for vehicles meeting extreme-heat performance benchmarks, reducing import friction.
- Lithium-Ion Supply Localization:Battery cell assembly investments in Saudi Arabia's industrial zones are reducing import dependency and qualifying domestic producers for preferential fleet procurement contracts.
Market Restraints
- Charging Infrastructure Capital Intensity:Ultra-fast DC charging deployment across desert corridors requires grid reinforcement investments that strain utility capex cycles and delay network completion.
- Extreme-Temperature Battery Degradation:Ambient conditions exceeding 50°C accelerate lithium-ion capacity fade, compressing warranty exposure for OEMs and elevating total cost of ownership calculations.
- Petroleum Subsidy Persistence:Artificially suppressed gasoline prices in Kuwait and Qatar sustain internal combustion operating cost advantages that disincentivize consumer switching.
Strategic Opportunities
- Commercial Vehicle Electrification:Last-mile logistics operators in Dubai and Riyadh face municipal diesel restrictions, creating fleet replacement demand that outpaces passenger vehicle conversion rates.
- Solid-State Battery Convergence:Higher energy density chemistries combined with ceramic electrolyte thermal stability are attracting sovereign wealth deployment for pilot manufacturing lines targeting Gulf deployment.
- Integrated Solar-Charging Networks:MOHAP and ESMA are co-developing technical standards for photovoltaic-DC charging stations that qualify for green building certification credits.
Industry Challenges
- Specialized Thermal Engineering Talent Scarcity:Battery cooling system design and high-temperature power electronics expertise remains concentrated in East Asian and European supplier bases, constraining local R&D capabilities.
- Cross-Border Standardization Delays:Divergent charging connector protocols between Saudi Arabia's SASO framework and UAE's ESMA specifications fragment procurement for fleet operators with multi-territory routes.
- Recycling Infrastructure Gap:End-of-life battery processing capacity is undeveloped across GCC states, creating compliance exposure as early EV fleets reach retirement thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Electric Vehicle Market |
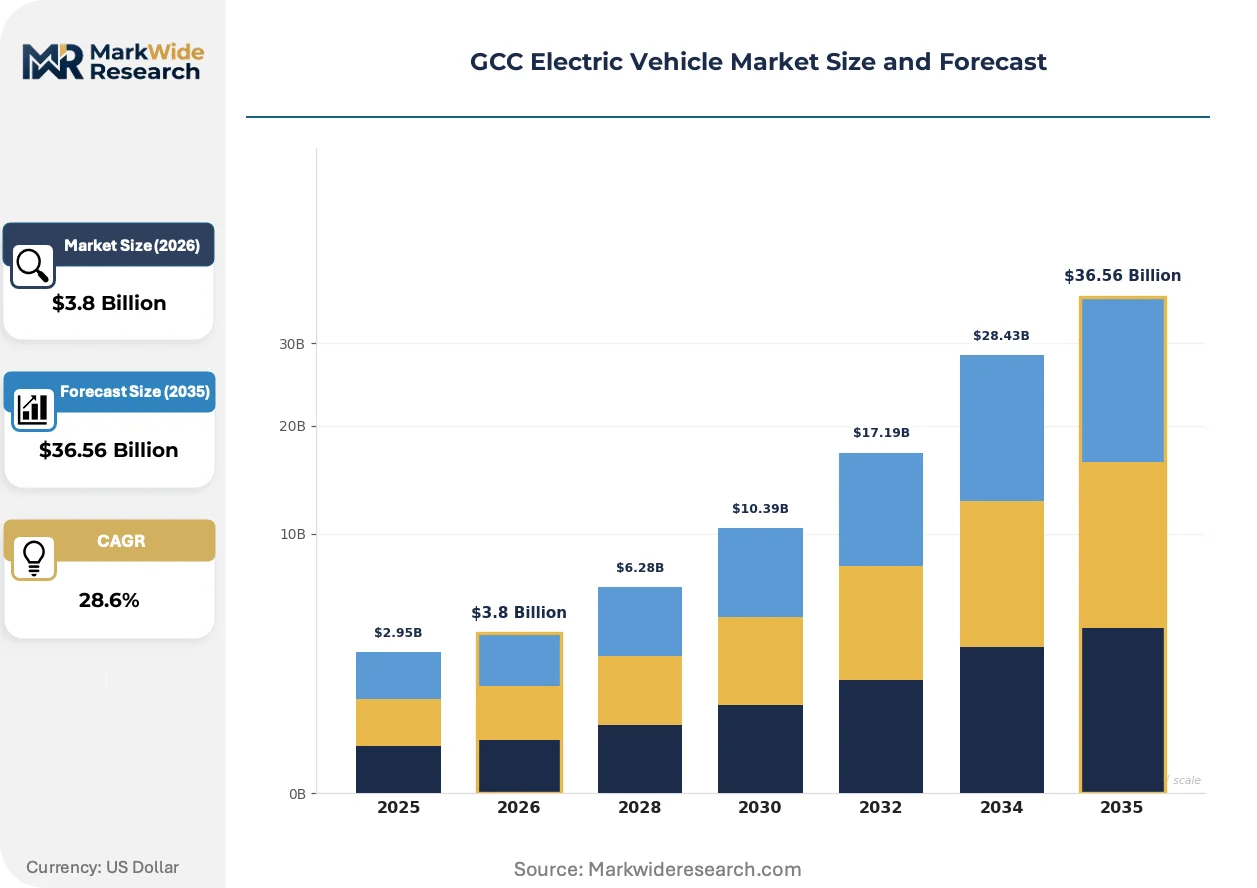
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid Charging Infrastructure: Fast Charging, Level 2 Charging, Wireless Charging, Ultra-Fast Charging End User: Government Fleets, Ride-Hailing Services, Private Owners, Corporate Fleets |
| Companies Covered | Nissan Motor Co., Ltd., Ceer Motors, Hyundai Motor Company, Volkswagen AG, Lucid Group, Inc., Tesla, Inc., BYD Company Limited, General Motors Company, BMW AG, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Electric Vehicle Market Trends and Innovations
Software-defined architectures and thermal engineering advances are repositioning vehicle value capture from hardware sales to recurring service monetization, while regulatory pressure on public fleet decarbonization accelerates technology deployment timelines.
Immersion cooling systems for battery packs are integrating dielectric fluid circulation directly against cell surfaces, replacing air-gap and cold-plate designs. Commercial fleet operators in Abu Dhabi and Jeddah are specifying this architecture in procurement tenders to sustain discharge rates during summer peak loads. The technology is integrating thermal stability guarantees into lease pricing structures, compressing total cost of ownership calculations against conventional cooling.
SASO's updated energy efficiency labeling requirements and SFDA's battery safety certification protocols now mandate thermal runaway propagation testing for all imported electric vehicles. These frameworks disqualify legacy platforms engineered for temperate climates, filtering the importable product set. Saudi fleet operators are responding by pre-qualifying only vehicles with Gulf-specific thermal validation, narrowing supplier shortlists before competitive bidding begins.
Corporate fleet managers are consolidating procurement decisions under centralized sustainability officers who negotiate multi-year electrification roadmaps with charging infrastructure bundled into vehicle supply contracts. Traditional dealer networks are losing transaction control as direct OEM-fleet relationships displace retail intermediation. This pattern concentrates most visibly in Dubai's logistics sector, where Emirates Post and Aramex have established dedicated electrification procurement functions with technical evaluation authority.
GCC Electric Vehicle Market Segmentation
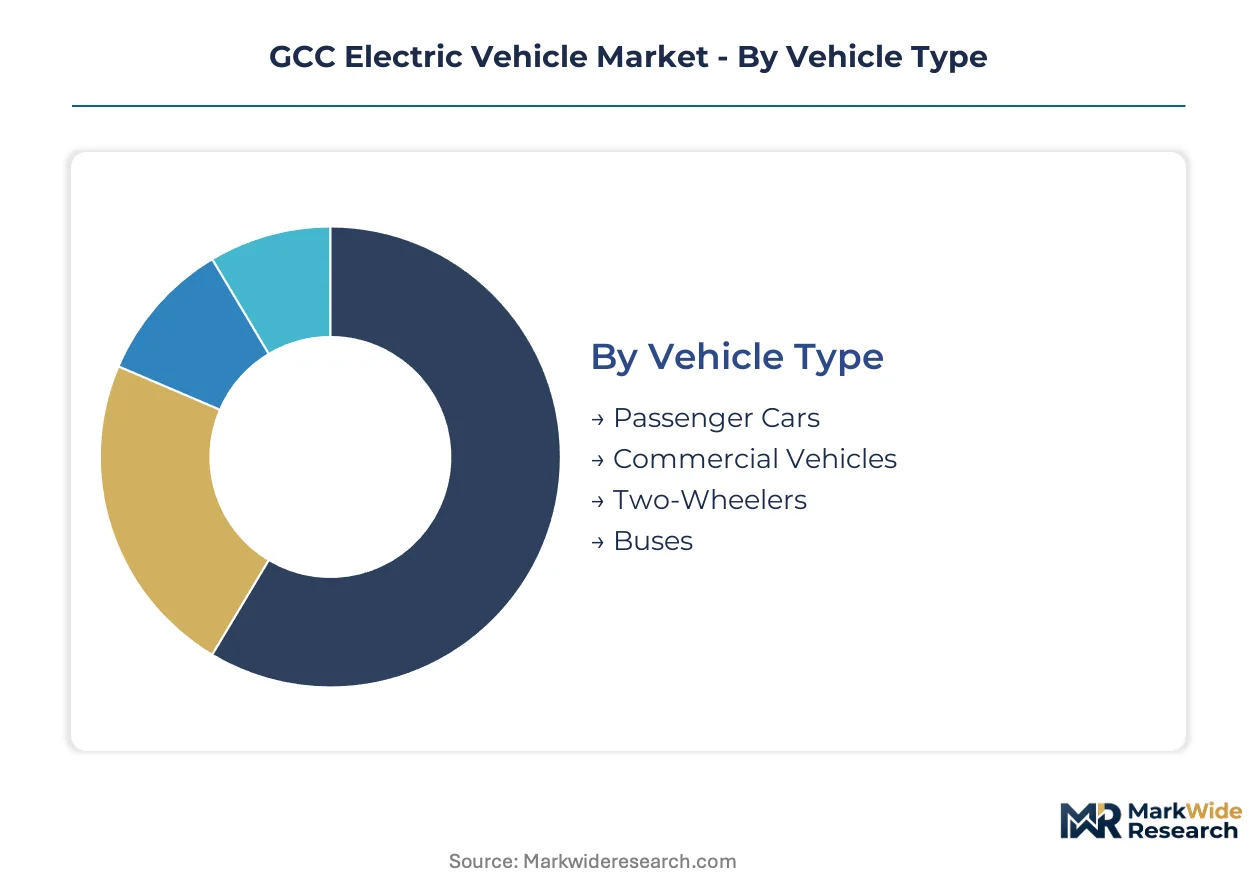
Segmentation reveals how sovereign procurement mandates and climate engineering requirements reshape competitive entry points across vehicle categories, battery chemistries, and charging architectures in Gulf markets.
Vehicle Type:
Standardized platforms dominate high-volume categories while bespoke thermal configurations capture premium positioning in this segment.
- Passenger Cars:Battery electric sedans and SUVs engineered with enhanced cooling loops for ambient temperatures exceeding 50°C. Demand concentrates in the UAE and Saudi Arabia where ESMA certification and SASO energy efficiency labeling filter importable models. Government fleet quotas and ride-hailing electrification mandates sustain guaranteed offtake channels.
- Commercial Vehicles:Light-duty vans and medium-duty trucks specified for last-mile logistics electrification in Dubai and Riyadh. Municipal diesel restrictions in these cities accelerate fleet replacement timelines beyond passenger vehicle conversion rates. Procurement bundles charging infrastructure into vehicle supply contracts.
- Two-Wheelers:Electric motorcycles and scooters for urban delivery fleets in Jeddah and Doha.
- Buses:Battery electric and fuel-cell transit vehicles for municipal operators in Abu Dhabi and Manama.
Leading the category by volume: Passenger Cars. Growing fastest: Commercial Vehicles.
Battery Technology:
Cost tiers separate mature chemistries with established supply chains from emerging alternatives attracting sovereign R&D capital.
- Lithium-Ion:NMC and LFP cell architectures with liquid electrolyte systems and active thermal management. Installed capacity leads across GCC markets though extreme-heat degradation accelerates warranty exposure for OEMs deploying in Saudi Arabia's interior regions.
- Solid-State:Ceramic electrolyte designs with higher energy density and thermal stability for extreme-heat deployment. Sovereign wealth funds in Saudi Arabia are deploying capital toward pilot manufacturing lines targeting regional qualification.
- Nickel-Metal Hydride:Legacy hybrid vehicle applications with limited new platform adoption.
- Lead-Acid:Auxiliary power units and low-speed electric vehicle applications in cost-sensitive segments.
Dominant by installed base: Lithium-Ion. Steepest expansion trajectory: Solid-State.
Charging Infrastructure:
Application requirements dictate power level selection, with fleet operators driving standardization toward high-speed DC architectures.
- Fast Charging:DC stations delivering 50-150kW across highway corridors and urban hubs. Grid reinforcement requirements in desert regions strain utility capex cycles and delay network completion timelines.
- Ultra-Fast Charging:350kW+ systems for commercial fleet depot charging and intercity transit. Abu Dhabi and Riyadh operators are specifying this architecture in procurement tenders to sustain discharge rates during summer peak loads.
- Level 2 Charging:AC residential and workplace installations with overnight dwell times.
- Wireless Charging:Inductive pad systems for premium residential and commercial parking applications.
Highest deployment volume: Fast Charging. Gaining share fastest: Ultra-Fast Charging.
End User:
Customer type determines procurement control points, with centralized sustainability functions displacing traditional dealer intermediation.
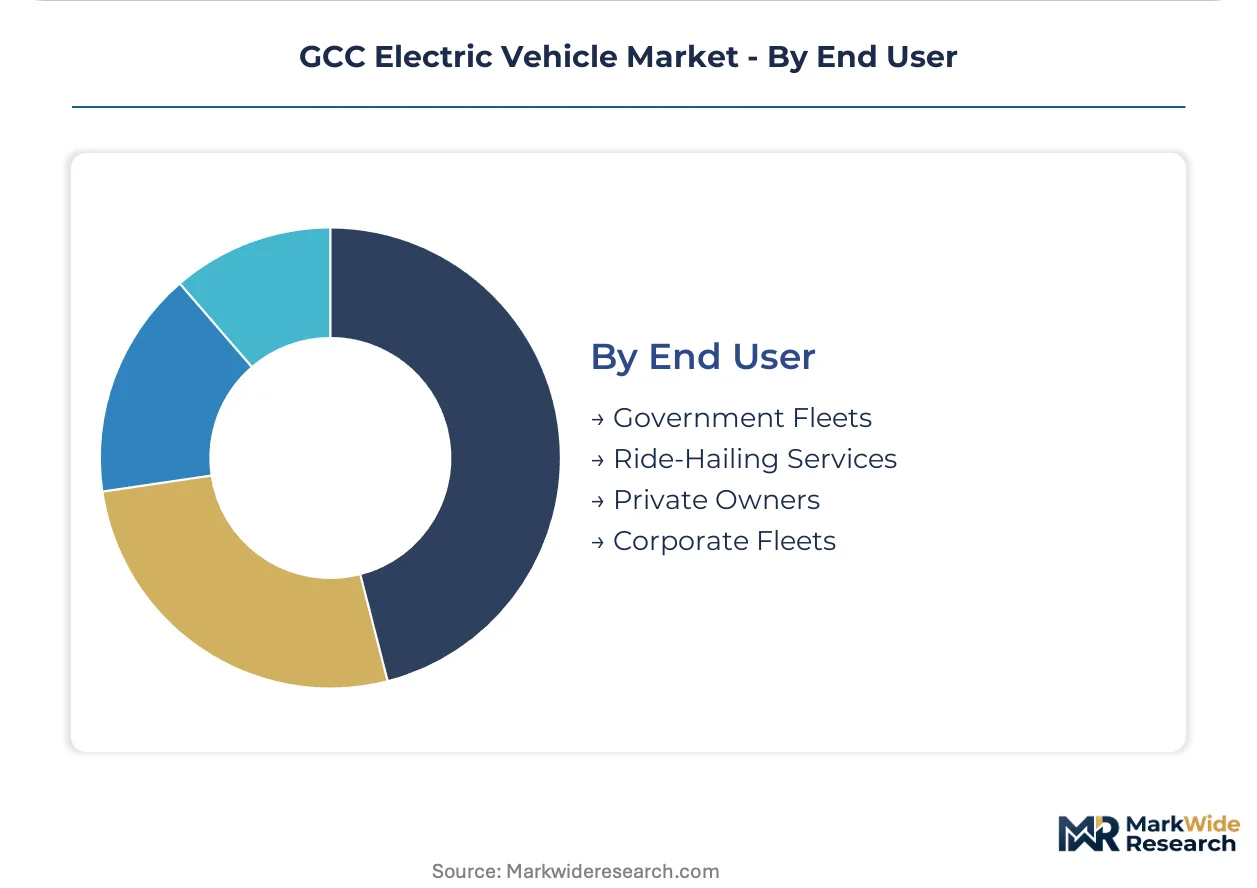
- Government Fleets:Centralized procurement by federal and municipal agencies under binding electrification quotas. Saudi Arabia's EV30@30 initiative mandates 30% electric vehicle share by 2030 with fleet procurement quotas creating guaranteed offtake.
- Corporate Fleets:Logistics operators and energy companies negotiating multi-year electrification roadmaps. Emirates Post and Aramex in Dubai have established dedicated procurement functions with technical evaluation authority over bundled vehicle-charging contracts.
- Ride-Hailing Services:Platform operators facing regulatory mandates for fleet electrification in Riyadh and Dubai.
- Private Owners:Individual purchasers responding to petroleum subsidy persistence in Kuwait and Qatar that sustains internal combustion operating cost advantages.
Controlling procurement volume: Government Fleets. Expanding most quickly: Corporate Fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf EV consumption outpaces domestic manufacturing capacity, with Saudi Arabia and the UAE absorbing imported vehicles while Ceer Motors builds sovereign production capability. State-backed charging networks and fleet procurement quotas concentrate demand in these two markets.
Saudi Arabia
Government fleet mandates and ride-hailing operator quotas drive procurement volume under the EV30@30 initiative. SASO energy efficiency labeling and SFDA battery safety protocols filter importable models to Gulf-validated platforms. Riyadh and Jeddah host concentrated charging infrastructure deployment with ultra-fast DC corridors linking the Red Sea coast.
United Arab Emirates
Corporate logistics electrification and municipal transit decarbonization sustain fleet replacement demand in Dubai and Abu Dhabi. ESMA technical regulations and MOHAP safety standards establish certification fast-tracks for extreme-heat performance benchmarks. Dubai's last-mile delivery operators specify bundled vehicle-charging contracts in procurement tenders.
Qatar
Petroleum subsidy persistence sustains internal combustion operating cost advantages that suppress consumer switching. The national petroleum regulator maintains artificial price floors that disadvantage EV total cost of ownership calculations. Doha municipal operators pilot electric bus procurement with limited fleet scale.
Kuwait
Fuel price controls and grid infrastructure constraints delay charging network completion timelines. The national electricity utility struggles with capex cycles for desert corridor reinforcement. Kuwait City commercial fleets show minimal electrification activity compared to Saudi and UAE counterparts.
Bahrain
Manama municipal transit operators test battery electric bus platforms with small-scale procurement. The national standards body awaits harmonization with Saudi SASO and UAE ESMA charging protocols. Limited domestic market size constrains infrastructure investment urgency relative to larger GCC economies.
GCC Electric Vehicle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the GCC electric vehicle landscape, with sovereign-backed manufacturing ventures facing established global OEMs. Market structure shows tiered concentration: premium positioning anchored by range-extended luxury sedans, mass-market volume driven by fleet procurement, and emerging domestic assembly qualifying for preferential government contracts. Strategic archetypes include software-defined monetization platforms, sovereign manufacturing champions, and thermal engineering specialists. Dominant competitive moves involve direct fleet relationship cultivation and charging infrastructure bundling.
Among established global OEMs, Nissan Motor Co., Ltd. and Hyundai Motor Company occupy positions exemplifying mass-market fleet penetration strategies. Tesla, Inc. and Lucid Group, Inc. represent the software-defined and luxury-range archetypes respectively, with Ceer Motors anchoring the sovereign-backed domestic manufacturing tier. These named entities illustrate how competitive positioning fragments across technology monetization models, climate engineering specialization, and state-supported industrial policy vectors.
| Leading Market Players |
|---|
| Nissan Motor Co., Ltd. |
| Ceer Motors |
| Hyundai Motor Company |
| Volkswagen AG |
| Lucid Group, Inc. |
| Tesla, Inc. |
| BYD Company Limited |
| General Motors Company |
| BMW AG |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between Gulf-validated thermal platforms and temperate-climate imports manifests in contract-based long-term offtake pricing for fleet procurement, while commodity spot dynamics govern private retail transactions. Saudi SASO energy efficiency labeling and UAE ESMA extreme-heat benchmarks create a two-tier supply qualification system that concentrates pricing power with OEMs holding regional validation.
Pricing Analysis
Cost-down pressure on mass-market fleet tiers accelerates because government procurement quotas consolidate buyer leverage and compress margins for non-validated suppliers. Pricing stratifies across premium extended-range sedans, standard fleet SUVs, and economy-grade last-mile delivery vans. Brand premium and certification level—specifically SASO thermal runaway propagation clearance—drive differentiation. Private owners in Kuwait and Qatar exhibit highest price sensitivity due to petroleum subsidy persistence, while corporate fleet managers in Dubai show lowest sensitivity when charging infrastructure bundling reduces total cost of ownership calculations.
Supply Chain Analysis
Returns and end-of-life battery flows remain undeveloped across GCC states, creating compliance exposure as early EV fleets approach retirement thresholds without regional recycling infrastructure. Cell manufacturing concentrates in China, South Korea, and Japan, with Saudi Arabia's industrial zones attracting pilot assembly investments to reduce import dependency. Raw material dependencies span lithium carbonate, nickel sulfate, and cobalt hydroxide. Single-source vulnerability in ceramic electrolyte supply for solid-state development poses structural risk. Distribution runs through direct OEM-fleet relationships that displace traditional dealer networks in high-volume government and corporate procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic battery cell capacity scarcity props pricing power for qualified suppliers, as sovereign-backed manufacturing timelines lag fleet electrification mandates by several years.
For Market Incumbents: Anchor market position through backward integration into thermal management component supply and captive qualification testing facilities in Saudi Arabia's industrial zones. Defend against sovereign-backed entrants like Ceer Motors by locking multi-year fleet offtake contracts with Emirates Post and Aramex before domestic assembly scales. Certification investment in SASO and ESMA dual compliance represents the critical lever for procurement shortlist retention. For New Entrants and Emerging Players: Capture white-space in commercial vehicle electrification where last-mile logistics operators in Dubai and Riyadh face municipal diesel restrictions with limited validated supplier options. Target light-duty van segments with bundled charging infrastructure propositions, as corporate sustainability officers consolidate procurement authority and displace dealer intermediation. Go-to-market angle should emphasize thermal engineering specialization for ambient temperatures exceeding 50°C with warranty terms that compress total cost of ownership against conventional cooling. For Investors and Strategic Acquirers: Re-rating potential sits with solid-state battery developers given sovereign wealth deployment toward pilot manufacturing lines targeting Gulf deployment. Long-term viability favors archetypes with ceramic electrolyte thermal stability and regional qualification pathways. Acquisition target archetype: thermal engineering specialists with battery cooling system design capabilities. Signal to watch: harmonization progress between Saudi SASO and UAE ESMA charging protocols as indicator of cross-border fleet operator procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from South Korean suppliers for Saudi fleet quotas. |
| Software-Defined Vehicle Investment | Enables Tesla-style over-the-air monetization beyond initial hardware sales in UAE. |
| Charging Infrastructure Partnership | Bundles ultra-fast DC deployment with vehicle procurement for Dubai logistics operators. |
| Geographic Manufacturing Footprint | Qualifies Ceer Motors for preferential government contracts under EV30@30 localization thresholds. |
| Thermal Engineering Specialization | Supports immersion cooling system specifications in Abu Dhabi and Jeddah fleet tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet sustainability officers, and charging infrastructure developers. Saudi SASO certification databases, UAE ESMA technical bulletins, and vehicle registration statistics from IHS Markit provided demand-side validation. Bottom-up unit economics modeling triangulated against top-down market sizing from hydrocarbon diversification policy documents.
Data-stream reconciliation across vehicle class, propulsion architecture, battery chemistry, and regional regulatory cluster dimensions produced volume and value outputs over the projection horizon. CAGRs derived from fleet procurement quota trajectories under EV30@30 and municipal diesel restriction timelines, cross-referenced with charging infrastructure deployment schedules from utility capex disclosures. Extreme-temperature battery degradation curves and thermal management cost premiums informed segment-specific pricing assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state manufacturing scale-up and cross-border protocol harmonization. Forecasts reflect documented assumptions regarding sovereign capital deployment continuity and petroleum subsidy reform pace. Practitioners should monitor SASO-ESMA standardization committee progress and early EV fleet retirement thresholds for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Folding E-Scooter Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market